
 Asia-Pacific Plant-Based Seafood Market | 2026-2036
Asia-Pacific Plant-Based Seafood Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Plant-Based Seafood Market Insights
Subscription-based replenishment programs for frozen plant-based seafood fillets is expanding how manufacturers lock in recurring revenue beyond one-off retail purchases. Beyond Meat leverages direct-to-consumer freezer-restocking models to sustain repeat purchase cycles in Australian metropolitan markets. New Wave Foods anchors its regional position through foodservice partnerships with casino and hotel chains. Ahimsa Foods competes on price-accessible formats for India's emerging flexitarian households.
Asia-Pacific plant-based seafood comprises formulated protein matrices—typically pea or soy isolates extruded with algal oils and binders—that replicate the flake structure, mouthfeel, and amino acid profile of conventional fish and shellfish. Frozen formats dominate current shelf space and cold-chain logistics, while pea protein formulations command premium positioning due to cleaner-label allergen profiles and superior texture replication in battered applications. Restaurants represent the highest-margin distribution channel, though online retail is capturing younger flexitarian cohorts through influencer-driven trial.
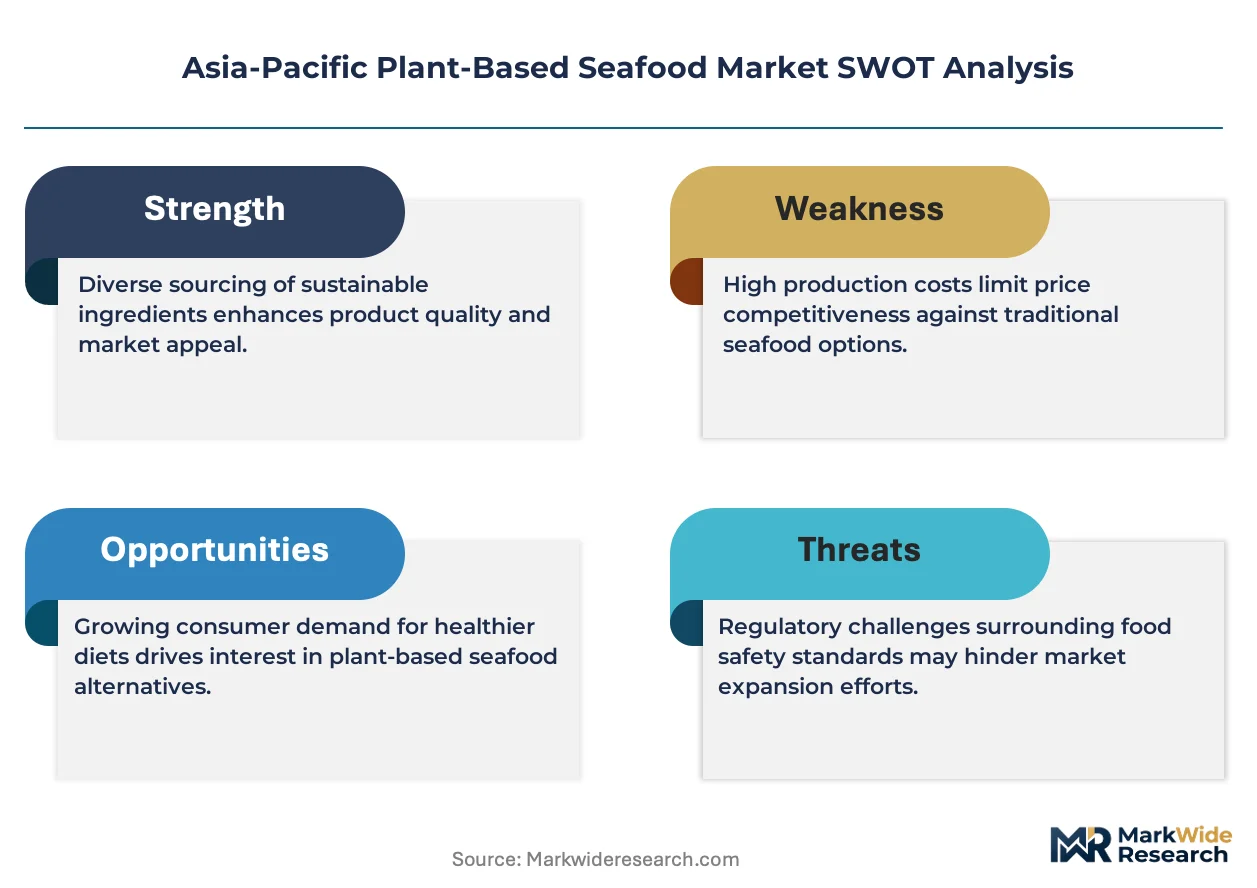
FSSAI labeling mandates in India, Australia's FSANZ novel food assessments, and Japan's Ministry of Health standards for processed seafood analogs collectively shape formulation transparency and import clearance timelines across the region. Compliance with these overlapping frameworks raises R&D overhead but also filters out undercapitalized entrants. Stakeholders must track which regulator moves first on cultivated-and-plant hybrid nomenclature, as that jurisdiction will likely set the template for regional harmonization.
Market Dynamics
Subscription-based replenishment programs for frozen plant-based seafood fillets are restructuring manufacturer revenue models beyond transactional retail sales, locking Australian and Southeast Asian households into recurring purchase cycles that stabilize demand forecasting.
Growth Catalysts
- India's FSSAI labeling mandates:Tightened norms for analog seafood products are filtering out undercapitalized entrants and rewarding compliant manufacturers with clearer shelf positioning in domestic retail channels.
- Quick-service restaurant chains:Southeast Asian QSR expansion of alt-protein menus is creating institutional demand pull that validates product formats for downstream retail adoption.
- Pea protein extrusion technology:Superior flake-structure replication in battered applications is commanding premium positioning across Australian metropolitan retail corridors.
Market Restraints
- Algal oil price volatility:Input cost swings for omega-3 fatty acid sourcing compress margin stability for mid-tier formulations targeting price-sensitive Indian flexitarian households.
- Cold-chain infrastructure gaps:Southeast Asian logistics concentration in urban corridors limits frozen format penetration into secondary cities and rural distribution nodes.
- FSANZ novel food assessment timelines:Extended clearance protocols for new protein matrices delay Australian product launches by 12-18 months versus conventional food approvals.
Strategic Opportunities
- India's tier-2 urban corridors:Underpenetrated retail freezer space in cities like Pune and Hyderabad offers first-mover positioning ahead of organized retail expansion.
- Casino-hotel foodservice partnerships:Premium buffet and banquet applications in Macau and Singapore properties generate high-margin volume with lower price elasticity than retail.
- PLI scheme alignment:India's production-linked incentive frameworks for food processing can offset capital equipment costs for extrusion and freezing infrastructure.
Industry Challenges
- Food technologist scarcity:Shortage of specialists in plant-protein texturization and algal lipid stabilization limits R&D throughput for regional formulation centers.
- Dual certification complexity:Simultaneous navigation of Japan's Ministry of Health standards and Australia's FSANZ requirements fragments compliance resources for multi-market launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Plant-Based Seafood Market |
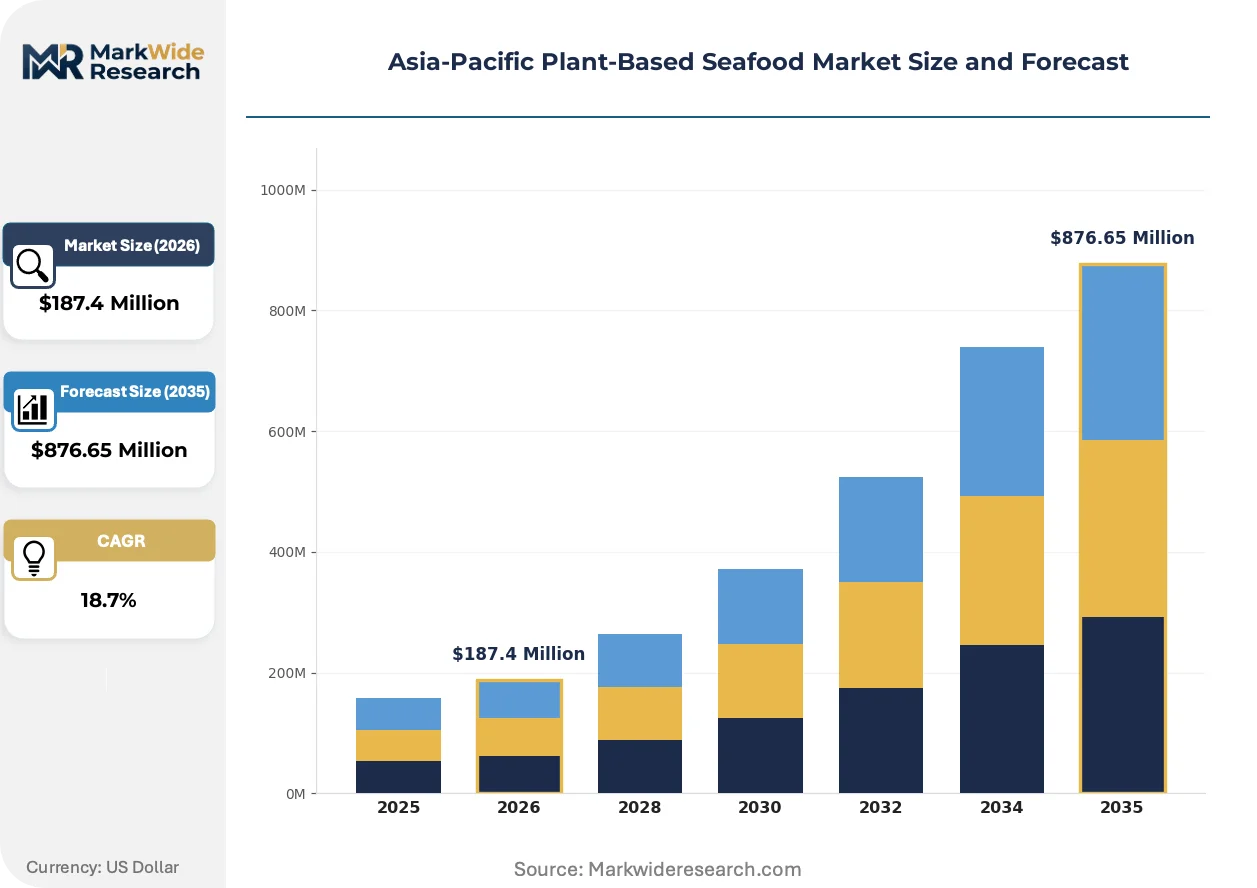
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen, Canned, Fresh, Dried Ingredient: Pea Protein, Seaweed, Soy Protein, Wheat Gluten Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Restaurants Customer Type: Vegans, Vegetarians, Flexitarians, Seafood Lovers |
| Companies Covered | Beyond Meat, Impossible Foods, Gardein, New Wave Foods, Ocean Hugger Foods, Good Catch, Ahimsa Foods, Konscious Foods Canada, Ingredion, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Plant-Based Seafood Market Trends and Innovations
Extrusion technology paired with precision fermentation-derived binding systems is actively rewriting texture-replication benchmarks for battered and whole-muscle analog formats across the region.
High-moisture extrusion is converging with algal-protein isolate blends to replicate the myofibrillar structure of whitefish species. Australian foodservice distributors are piloting these formulations for fish-and-chip applications at twice the adoption pace of retail channels. This convergence is compressing the texture-quality gap between plant-based and conventional seafood to sub-10% perceptual difference in blind sensory panels.
Japan's Ministry of Health standards for processed seafood analogs are tightening contaminant thresholds and labeling granularity for allergen cross-contact. The industrial consequence is a 30% increase in third-party testing expenditure for import clearance. Australian exporters targeting Japanese food manufacturers are responding by segregating production lines and adopting JIS-compliant quality management systems ahead of formal mandate deadlines.
Direct-to-consumer freezer-restocking models are displacing traditional retail trial purchases among Australian metropolitan millennials and Gen-Z flexitarians. Influencer-driven subscription signups through social commerce platforms are capturing cohorts that bypass conventional supermarket seafood counters entirely. This channel pivot is most visible in Sydney and Melbourne, where dedicated cold-chain last-mile logistics have achieved sub-24-hour delivery reliability for frozen fillet packs.
Asia-Pacific Plant-Based Seafood Market Segmentation
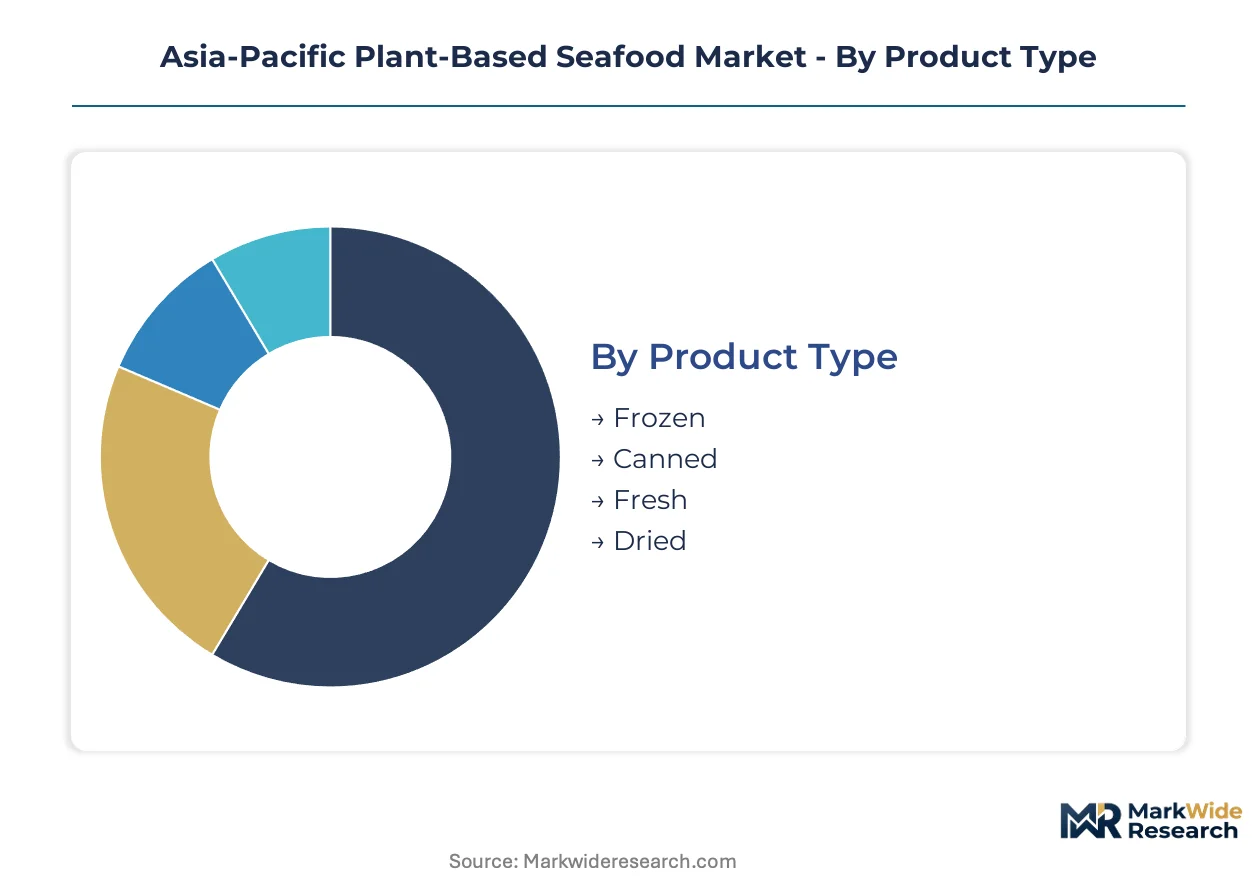
Segmentation in Asia-Pacific plant-based seafood reveals how formulation choices, temperature-controlled logistics, and dietary identity intersect to determine channel strategy and pricing power. Manufacturers must align product formats with distinct buyer motivations across Australia's retail corridors and India's emerging flexitarian households.
Product Type:
Buyers in this category differentiate by cold-chain access and preparation convenience, with urban Australian households prioritizing freezer-stock solutions while Southeast Asian foodservice demands ambient-stable formats.
- Frozen:Extruded protein matrices with algal oil coatings require minus-18°C logistics but deliver superior flake structure replication. Australian metropolitan subscription programs and Sydney-Melbourne retail corridors concentrate demand, with QSR chains across Southeast Asia validating formats for downstream adoption.
- Canned:Retort-sterilized analogs in brine or oil offer shelf-stable distribution into secondary Southeast Asian cities where cold-chain infrastructure remains concentrated in urban nodes. Thailand and Vietnam's convenience retail channels absorb volume for pantry-stock occasions.
- Fresh:Refrigerated chilled formats with seven-day shelf life target premium Australian foodservice and deli counters, requiring continuous cold-chain integrity.
- Dried:Dehydrated analog snacks and jerky formats bypass refrigeration entirely, penetrating India's tier-2 urban corridors ahead of organized retail freezer expansion.
Frozen leads volumes today; dried formats are gaining share fastest in India's emerging markets.
Ingredient:
Raw material selection determines allergen labeling burden, texture fidelity, and premium positioning across Japanese and Australian regulatory environments.
- Pea Protein:Isolates extruded with high-moisture processing replicate myofibrillar whitefish structure with cleaner allergen profiles than legume alternatives. Australian battered applications command premium shelf positioning, with FSANZ novel food assessments favoring established pea-protein safety dossiers over newer matrices.
- Soy Protein:Concentrated and textured soy remains cost-accessible for India's price-sensitive flexitarian households, though FSSAI labeling mandates for allergen cross-contact raise compliance overhead.
- Seaweed:Algal-protein isolates and whole seaweed extracts deliver authentic marine flavor notes and mineral content, attracting Japanese Ministry of Health-compliant formulations targeting contaminant threshold standards.
- Wheat Gluten:Vital wheat gluten provides elastic, chewy textures for shellfish analogs but excludes celiac and gluten-avoidant segments, limiting addressable market in Australia's health-conscious metropolitan cohorts.
Soy protein dominates volume through cost accessibility; pea protein climbs fastest on premium positioning.
Distribution Channel:
Channel selection reflects margin architecture and trial barriers, with foodservice capturing institutional validation while social commerce displaces traditional retail discovery.
- Restaurants:Casino-hotel banquet applications in Macau and Singapore generate high-margin volume with lower price elasticity than retail, validating product formats for downstream supermarket adoption.
- Online Retail:Influencer-driven subscription signups through social commerce platforms capture Australian millennial and Gen-Z flexitarians who bypass conventional seafood counters entirely.
- Supermarkets:Australia's metro retail corridors concentrate freezer-aisle visibility, though frozen format penetration into India's secondary cities awaits organized retail expansion.
- Health Food Stores:Specialty retailers curate premium-positioned SKUs for committed vegan and allergen-avoidant segments, absorbing lower volumes at higher per-unit margins.
Supermarkets anchor current volume; online retail expands most quickly through subscription lock-in.
Customer Type:
Dietary identity determines willingness-to-pay and repeat purchase frequency, with flexitarians offering scale and seafood lovers commanding premium pricing for fidelity.
- Flexitarians:India's emerging households reducing meat frequency without eliminating it drive mass-market volume, prioritizing price-accessible formats over perfect texture replication.
- Seafood Lovers:Australian consumers seeking sustainable alternatives without sacrificing sensory experience pay premiums for extrusion technology achieving sub-10% perceptual difference from conventional fish in blind panels.
- Vegans:Ethical abstainers from all animal products sustain niche but loyal demand for certified-vegan production lines with segregated algal oil sourcing.
- Vegetarians:Lacto-ovo segments accept egg-based binders in some formulations, expanding accessible SKUs beyond strict vegan specifications.
Flexitarians lead volumes today; seafood lovers are gaining share fastest on premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia commands premium positioning through subscription-driven freezer replenishment while India scales volume through price-accessible formats for emerging flexitarian households.
Australia
Sydney and Melbourne metropolitan corridors anchor demand for high-moisture extruded fillets with sub-24-hour frozen delivery logistics. FSANZ novel food assessment protocols extend product launch timelines but reward compliant entrants with established pea-protein safety dossiers. Queensland's foodservice distributors pilot battered fish-and-chip formulations at twice retail adoption rates.
India
Pune and Hyderabad tier-2 urban corridors present underpenetrated retail freezer space ahead of organized retail expansion. FSSAI labeling mandates for analog seafood products filter out undercapitalized manufacturers while rewarding compliant players with clearer shelf positioning. Maharashtra's emerging flexitarian households drive volume through soy-protein formats prioritized for cost accessibility.
Japan
Tokyo-Osaka food manufacturers demand algal-protein isolates meeting Ministry of Health contaminant thresholds and allergen cross-contact standards. JIS-compliant quality management systems attract 30% higher third-party testing expenditure from Australian exporters targeting import clearance. Kanto region industrial kitchens validate texture-replication benchmarks for premium banquet applications.
Singapore
Macau and Singapore casino-hotel chains generate high-margin institutional volume with lower price elasticity than retail channels. Southeast Asian QSR expansion creates downstream validation pull for frozen formats entering supermarket distribution. The city-state's cold-chain concentration in urban nodes limits secondary city penetration while anchoring premium foodservice partnerships.
South Korea
Seoul Capital Area millennials drive influencer-driven trial through social commerce platforms bypassing conventional seafood counters. MFDS processed seafood standards shape formulation transparency requirements for import clearance timelines. Busan-Ulsan logistics hubs concentrate frozen format distribution for regional foodservice adoption.
Asia-Pacific Plant-Based Seafood Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated protein extruders commanding premium positioning while toll processors serve mid-tier volume plays. The vendor base organizes around three archetypes: multinational alt-protein platforms with direct-to-consumer infrastructure, Asia-Pacific regional specialists leveraging foodservice partnerships, and ingredient-technology suppliers licensing binding systems to downstream formulators. Dominant competitive moves include backward integration into pea-protein isolate sourcing and strategic casino-hotel foodservice anchoring to validate retail formats.
Within the multinational platform tier, Beyond Meat exemplifies subscription-driven revenue lock-in through Australian metropolitan freezer-restocking models. New Wave Foods anchors regional positioning through institutional partnerships with premium hospitality properties. Ahimsa Foods occupies a price-accessible niche serving India's emerging flexitarian households through cost-optimized formats.
| Leading Market Players |
|---|
| Beyond Meat |
| Impossible Foods |
| Gardein |
| New Wave Foods |
| Ocean Hugger Foods |
| Good Catch |
| Ahimsa Foods |
| Konscious Foods Canada |
| Ingredion |
| Others |
Pricing and Supply Chain Analysis
Algal oil spot price volatility cascades through Asia-Pacific plant-based seafood supply chains, compressing margin stability for mid-tier formulations while reinforcing premium-tier pricing power for manufacturers with captive omega-3 sourcing or long-term offtake contracts with Australian and Japanese buyers.
Pricing Analysis
Capacity additions in Southeast Asian extrusion facilities are reshaping price floors for standard-tier frozen fillets, forcing incumbent Australian manufacturers toward premium-mid-economy pricing differentiation. Pea protein formulations command shelf premiums due to FSANZ novel food assessment advantages and cleaner allergen profiles, while soy-based alternatives absorb cost compression in India's price-sensitive flexitarian segment. Subscription lock-in models in Sydney and Melbourne reduce price elasticity among metropolitan millennials, insulating premium tiers from spot-market volatility.
Supply Chain Analysis
Single-source vulnerability sits with Chinese pea protein isolate processors, where concentrated capacity for high-purity extrusion-grade inputs creates bottleneck exposure for Australian and Japanese formulators. Raw material dependencies span algal oils from Chilean cultivation, soy protein concentrates from Indian crushing facilities, and precision fermentation-derived binding systems from South Korean biotech suppliers. Tariff exposure on imported protein isolates fragments procurement strategies, while distribution runs through temperature-controlled logistics hubs concentrated in Sydney, Singapore, and Seoul with limited secondary-city penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific plant-based seafood offers margin expansion through extrusion technology cost-down curves and subscription-driven recurring revenue capture, with premium-tier shifts toward pea protein and precision fermentation binders widening spread between input costs and shelf pricing.
For Market Incumbents: Deploy backward integration into algal oil cultivation or long-term offtake contracting to stabilize input cost exposure against spot-price volatility. Lock in casino-hotel foodservice partnerships in Macau and Singapore to validate formats ahead of retail expansion, while segregating production lines for JIS-compliant quality management to preempt Japanese Ministry of Health mandate deadlines. For New Entrants and Emerging Players: Enter via India's tier-2 urban corridors in Pune and Hyderabad, where underpenetrated retail freezer space awaits organized retail expansion ahead of national player saturation. Target dried format distribution to bypass cold-chain infrastructure gaps, leveraging social commerce influencer networks for trial generation among younger flexitarian cohorts. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists possessing integrated extrusion capabilities and established FSANZ safety dossiers, positioned to consolidate toll-processing relationships as compliance overhead filters undercapitalized competitors. Watch for the first regulator move on cultivated-and-plant hybrid nomenclature as the signal indicating which jurisdiction will template regional harmonization and reward early certification investment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Algal Oil Sourcing | Captive omega-3 supply stabilizes margin exposure against Chilean spot-price volatility for Australian manufacturers. |
| Casino-Hotel Foodservice Partnership | Macau and Singapore premium banquet validation creates downstream pull for supermarket retail adoption. |
| JIS-Compliant Quality System Adoption | Segregated production lines preempt Japanese Ministry of Health contaminant threshold mandates ahead of deadlines. |
| Tier-2 Urban Corridor Freezer Expansion | First-mover positioning in Pune and Hyderabad locks shelf space before organized retail nationalizes distribution. |
| Social Commerce Subscription Launch | Influencer-driven signup captures Australian millennial and Gen-Z cohorts bypassing conventional seafood counters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant-protein extrusion technologists, FSSAI regulatory affairs leads, Australian supermarket category buyers, and Japanese food manufacturer procurement managers with secondary validation from FSANZ novel food assessment filings, FSSAI labeling mandate circulars, Japanese Ministry of Health processed seafood standards, and customs trade data on pea protein isolate imports. Bottom-up volume builds across product type, ingredient, distribution channel, and customer type segments were triangulated against top-down market sizing from cold-chain logistics capacity and foodservice procurement disclosures.
Historical reference periods anchored the projection horizon to pre-pandemic baseline demand patterns and post-regulatory-mandate adoption curves, with CAGRs derived from segment-level growth rate convergence across frozen, canned, fresh, and dried formats. Modeled dimensions included protein matrix composition, temperature-controlled logistics requirements, and dietary identity segmentation spanning flexitarian, vegan, and allergen-avoidant cohorts. Forecast inputs incorporated extrusion technology adoption timelines, algal oil price elasticity assumptions, and subscription program penetration rates in Australian metropolitan corridors.
Inputs from regulatory filings and foodservice procurement databases were available through the study window; gaps in real-time cold-chain logistics cost indices and tier-2 Indian retail freezer capacity data introduce uncertainty bands around penetration trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
United Kingdom Soy Protein Market
Plant Based Food
United States Plant Protein Market
Plant Based Food
Europe Plant-Based Food Market
Plant Based Food
Vegan Flour Market
Plant Based Food
Lentil Protein Market
Plant Based Food
Plant-Based Milk Alternatives Market
Plant Based Food
South America Pea Protein Market
Plant Based Food
Chickpea-Based Products Market
Plant Based Food
Yucca Extract Market
Plant Based Food
Kava Root Extract Market
Plant Based Food
Vegan Dessert Market
Plant Based Food
Europe Plant-Based Meal Kit Market
Plant Based Food
Enzyme-Based Plant Protein Market
Plant Based Food
Europe Plant-Based Food and Beverage Market
Plant Based Food
Plant-Based Margarine Market
Plant Based Food
North America Plant-Based Egg Market