
 Plant-Based Burger Market | 2026-2036
Plant-Based Burger Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Burger Market Analytics
Modular meal-kit bundling is expanding consumer trial by pairing patties with branded sauces and side components in single-purchase formats. Beyond Meat leverages direct-to-consumer channel control to sustain repeat purchase rates in North American households. Impossible Foods Inc. anchors its position through R&D intensity in heme-protein fermentation, while Tyson Foods Inc. competes by extending conventional meat distribution networks into plant-based placement.
A plant-based burger is a formulated patty comprising isolated proteins, lipids, and binders extruded or sheared to replicate the texture, juiciness, and Maillard browning of ground beef, designed for grilling, pan-searing, or flame-broiling in foodservice and home kitchens. Frozen Burgers dominate retail velocity due to extended shelf stability and broad distribution reach, while Fresh Patties command higher margin pools in premium grocery delis and fast-casual kitchens. Pea Protein formulations lead ingredient-source growth as soy-allergen concerns and non-GMO positioning displace legacy soy-dominant recipes in Western markets.
FDA oversees allergen disclosure and GRAS self-affirmation pathways for novel proteins like soy leghemoglobin, while USDA sets school-meal protein-equivalency standards that determine institutional eligibility. EFSA and national regulators across Europe enforce novel-food authorization under retained EU frameworks, slowing launch timelines for fermented-ingredient entrants. Stakeholders must monitor evolving protein-equivalency rulings and clean-label threshold definitions as these determine which formulations qualify for public-procurement contracts and premium retail positioning.
Market Dynamics
Protein-equivalency rulings from USDA and EFSA are fragmenting formulation standards, forcing manufacturers to maintain parallel recipes for institutional eligibility versus retail premium positioning.
Growth Catalysts
- USDA School Meal Guidelines:Protein-equivalency standards in U.S. institutional cafeterias create locked-in procurement volumes for qualifying formulations, anchoring baseline demand.
- German Retail Density:Shelf-space allocation in German supermarkets exceeds European peers, normalizing plant-based patties as default protein options for mainstream consumers.
- Pea Protein Extraction:Wet-fractionation advances reduce off-flavor carryover, enabling cleaner taste profiles that satisfy Western clean-label preferences.
Market Restraints
- Input Cost Volatility:Yellow pea protein concentrate prices fluctuate with Canadian prairie harvest yields, compressing margin predictability for formulation-dependent processors.
- Novel Food Authorization Delays:EFSA's retained EU framework for fermented-ingredient assessment extends launch timelines by eighteen to thirty-six months versus GRAS self-affirmation pathways.
- Refrigerated Distribution Concentration:Cold-chain infrastructure for fresh patties clusters around urban coastal corridors, excluding interior markets from premium-margin product access.
Strategic Opportunities
- Meal-Kit Modular Bundling:Branded sauce and side-component pairings in single-purchase formats expand trial conversion among convenience-seeking households.
- Direct-to-Consumer Channel Control:Subscription models bypass retail slotting fees and capture repeat-purchase data for formulation iteration.
- Clean-Label Threshold Arbitrage:Formulations achieving sub-five-ingredient counts qualify for premium positioning in Nordic markets where ingredient-list length drives purchase decisions.
Industry Challenges
- Heme-Protein Fermentation Scale-Up:Bioreactor capacity constraints limit batch consistency for precision-fermentation entrants seeking taste parity with ground beef.
- Allergen Cross-Contamination Protocols:Shared extrusion equipment between legacy soy-dominant and emerging pea-protein lines triggers FDA disclosure requirements that complicate co-manufacturing arrangements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Burger Market |
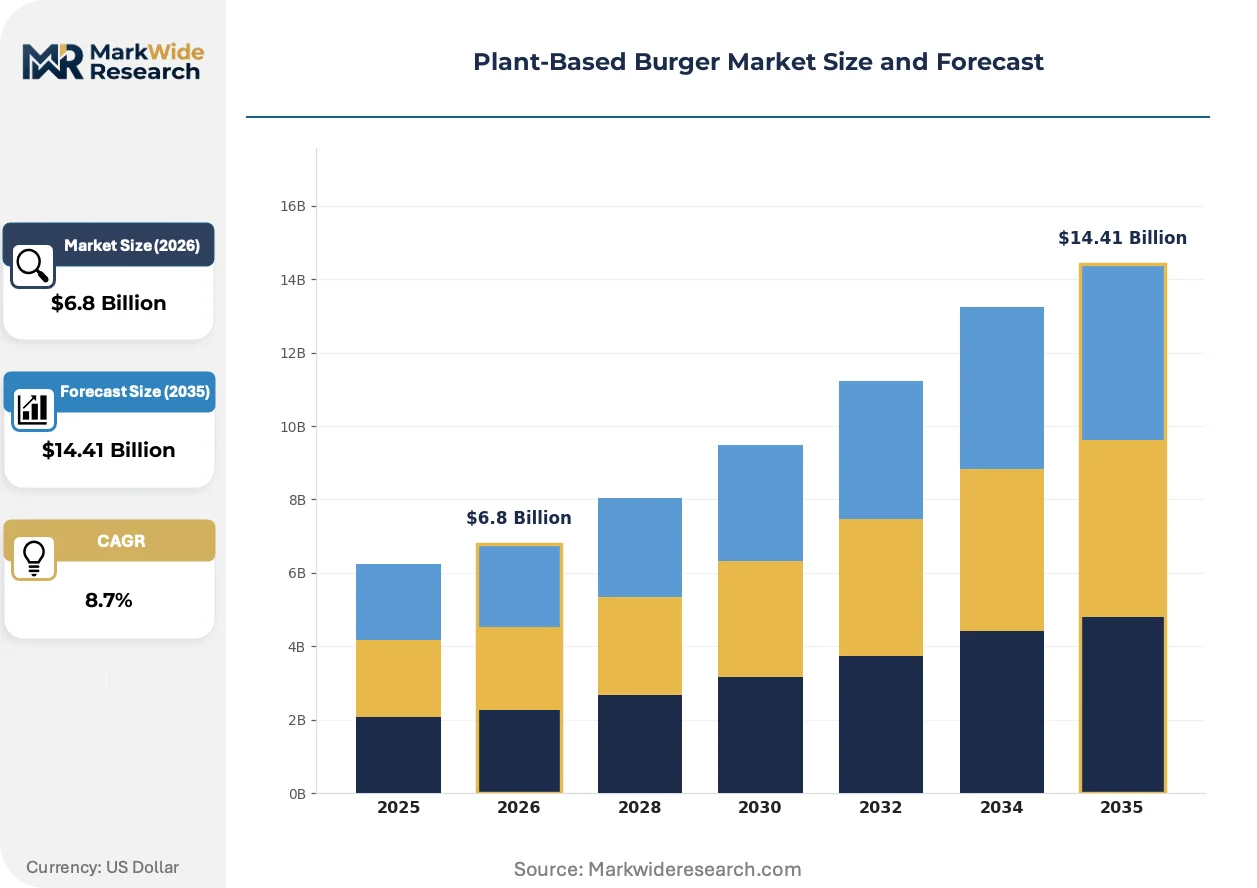
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Burgers, Fresh Patties, Ready-to-Cook, Meal Kits Ingredient Source: Pea Protein, Soy Protein, Wheat Protein, Lentils End User: Restaurants, Fast Food Chains, Grocery Stores, Consumers Pricing Tier: Premium, Mid-Range, Budget, Bulk |
| Companies Covered | Maple Leaf Foods, Conagra Foods, Beyond Meat, Atlantic Natural Foods LLC, Tofurky, Impossible Foods Inc., Quorn Foods, Tyson Foods Inc., Amy's Kitchen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Burger Market Evolving Landscape
High-moisture extrusion and precision fermentation are converging to compress the texture-performance gap between plant-based and animal-derived patties, reshaping competitive benchmarks across retail and foodservice channels.
High-moisture extrusion technology is rewriting textural fidelity standards by aligning protein fibrillation with fat-mimetic lipid encapsulation. Fast-casual chains in the United States are adopting these next-generation patties for flame-broiling applications previously restricted to animal protein. The structural consequence is collapsing the premium-price justification for conventional ground beef in quick-service formats.
EFSA's retained novel-food authorization framework under EU regulation 2015/2283 is extending assessment timelines for fermented-ingredient submissions. Manufacturers are responding by front-loading toxicology dossiers and establishing regulatory affairs subsidiaries in member states with streamlined rapporteur procedures. Fermented heme-protein entrants face the steepest compliance burden, delaying market entry relative to GRAS-affirmed U.S. competitors.
Meal-kit bundling is compressing consumer trial cycles by collapsing sauce-selection and side-pairing decisions into single-transaction formats. German and Dutch subscription services are displacing standalone patty purchases with curated protein-plus-accompaniment boxes. This pattern concentrates in urban households where cooking-confidence gaps and time scarcity intersect.
Plant-Based Burger Market Segmentation
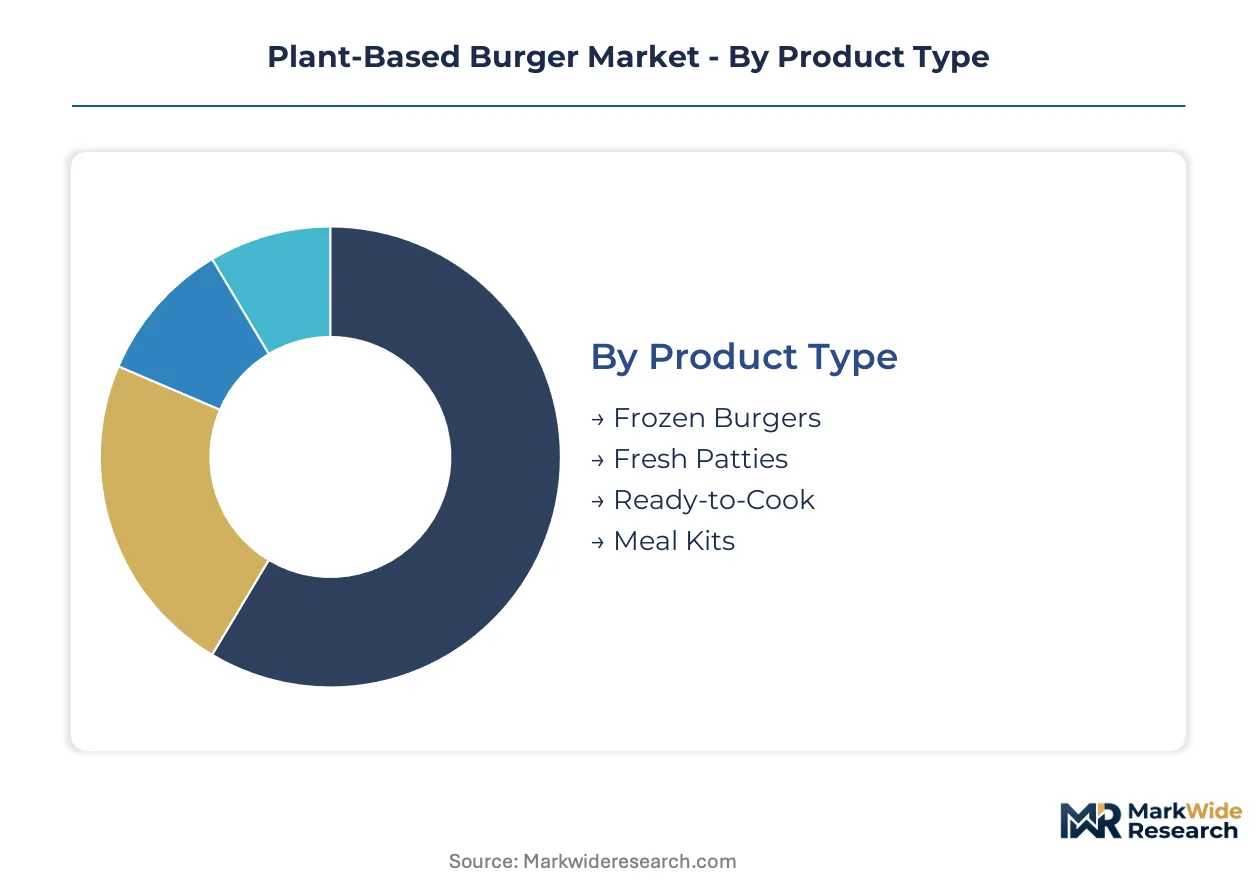
Segmentation in plant-based burgers reveals how formulation choices, distribution temperature, and procurement channel determine margin capture and regulatory exposure. Manufacturers must align protein source and product format with specific end-user operational constraints.
Product Type:
Standardization dominates at the frozen end of this spectrum, while fresh and modular formats demand customized logistics and shorter production runs.
- Frozen Burgers:Blast-frozen patties formulated for six-month shelf stability under standard retail freezer conditions. Quick-service chains in Germany and institutional cafeterias under USDA guidelines concentrate procurement here, driven by inventory flexibility and protein-equivalency compliance requirements.
- Fresh Patties:Refrigerated products with 14-21 day shelf life requiring continuous cold-chain integrity. Premium grocery delis in coastal US cities and fast-casual kitchens absorb volume, constrained by refrigerated distribution clustering around urban corridors.
- Ready-to-Cook:Pre-seasoned or marinated patties targeting convenience-oriented households.
- Meal Kits:Modular bundles pairing patties with sauces and side components in single-transaction formats.
Most installed capacity flows through Frozen Burgers. Expansion is steepest in Meal Kits.
Ingredient Source:
Cost tiers separate commodity legume proteins from precision-fermented alternatives, with allergen and non-GMO positioning driving substitution patterns.
- Pea Protein:Wet-fractionated isolate with reduced off-flavor carryover enabling clean-label positioning. Western retail markets and German supermarkets lead adoption, displacing soy-dominant recipes as non-GMO preferences harden.
- Soy Protein:Legacy isolate and concentrate formulations with established supply infrastructure. Budget-tier retail and Asian markets sustain volume, facing displacement pressure from allergen-labeling requirements.
- Wheat Protein:Gluten-based texturizing protein common in European formulations.
- Lentils:Whole-pulse and flour-based options targeting minimal-processing claims.
Pea Protein commands the steepest expansion trajectory. Soy Protein retains the largest installed extraction base.
End User:
Volume concentration sits with foodservice operators, while direct-to-consumer channels offer margin premiums and data capture.
- Restaurants:Independent and small-chain full-service operators sourcing through broadline distributors. US fast-casual kitchens adopting high-moisture extrusion patties for flame-broiling applications drive specification upgrades.
- Fast Food Chains:National quick-service brands with standardized menu boards and procurement contracts. German and Dutch chains normalize plant-based as default protein options, locking in volume commitments.
- Grocery Stores:Retailers ranging from mass-market supermarkets to premium natural channels.
- Consumers:Direct-to-consumer subscription and e-commerce purchasers.
Fast Food Chains absorb the largest production volumes. Direct-to-consumer channels are climbing the fastest.
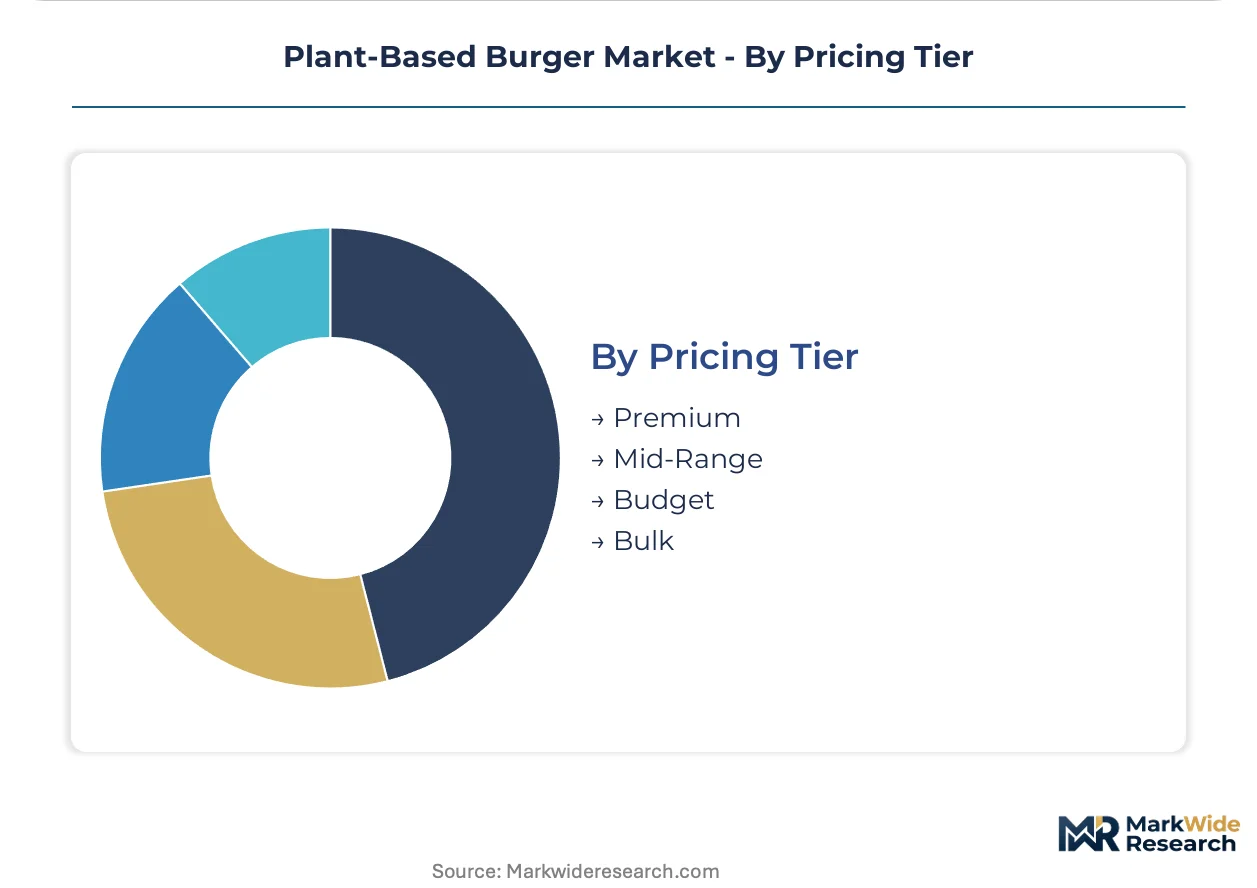
Pricing Tier:
Margin pools stratify across certification requirements, ingredient complexity, and channel slotting fee structures.
- Premium:Sub-five-ingredient formulations with organic or regenerative certification. Nordic markets and specialty retailers in Germany concentrate demand, where ingredient-list length directly influences purchase decisions.
- Mid-Range:Mainstream retail positioning balancing clean-label claims with cost accessibility.
- Budget:Price-competitive options targeting mass-market trial conversion.
- Bulk:Institutional and foodservice formats optimized for per-unit cost.
Mid-Range captures the widest distribution footprint. Premium is gaining share fastest in regulated European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The plant-based burger industry traces its commercial origins to North American food-tech ventures, with early scale achieved through Silicon Valley fermentation startups and Midwestern meat-industry incumbents repurposing extrusion infrastructure.
United States
Fast-casual chains and institutional cafeterias drive procurement volumes, with USDA protein-equivalency standards locking in baseline demand for qualifying formulations. FDA GRAS self-affirmation pathways accelerate novel-protein approvals relative to European counterparts. Chicago and Los Angeles anchor foodservice adoption, while Austin and San Francisco clusters concentrate precision-fermentation R&D facilities.
Germany
Retail shelf-space allocation exceeds European peers, normalizing plant-based patties as default protein options in mainstream supermarkets. EFSA novel-food authorization under retained EU frameworks governs ingredient eligibility, though Germany's streamlined rapporteur procedures offer faster assessment timelines than southern member states. Berlin and Hamburg dominate branded product distribution, with Bavarian processors specializing in clean-label extrusion.
United Kingdom
Meal-kit subscription services displace standalone patty purchases in urban households where cooking-confidence gaps intersect with time scarcity. FSA enforcement of post-Brexit retained EU novel-food rules maintains alignment with EFSA standards. London and Manchester concentrate direct-to-consumer channel control, while Scottish processors leverage pulse-crop proximity for pea-protein formulations.
Netherlands
Foodservice operators in quick-service chains normalize plant-based as standard menu items, with procurement contracts locking in volume commitments. EFSA retained frameworks apply, though Dutch rapporteur efficiency reduces assessment delays versus Mediterranean regulators. Rotterdam and Eindhoven anchor high-moisture extrusion manufacturing, with Wageningen University clusters feeding ingredient innovation pipelines.
Canada
Yellow pea protein concentrate supply chains concentrate in prairie provinces, with harvest yield fluctuations transmitting directly to processor input costs. Health Canada novel-food regulations parallel FDA pathways but require distinct dossier submissions. Saskatchewan and Manitoba dominate raw-material production, while Toronto and Vancouver clusters handle branded product formulation and coastal distribution.
Plant-Based Burger Market Competitive Landscape
The competitive structure tilts toward diversified protein conglomerates with legacy meat distribution networks. Tiered positioning separates precision-fermentation specialists, plant-protein pure-plays, and conventional meat processors extending into analog categories. Dominant competitive moves include backward integration into pea-protein extraction and strategic partnerships with foodservice distributors for institutional placement.
Among North American pure-plays, Beyond Meat and Impossible Foods Inc. occupy positions at the technology-intensive end of the spectrum, while Tyson Foods Inc. exemplifies the incumbent-extension archetype leveraging existing cold-chain infrastructure. Maple Leaf Foods and Conagra Foods represent mid-tier diversified processors balancing conventional and plant-based portfolios. Atlantic Natural Foods LLC, Tofurky, Quorn Foods, and Amy's Kitchen Inc. sit within specialized niche positions targeting allergen-conscious or organic-certification segments.
| Leading Market Players |
|---|
| Maple Leaf Foods |
| Conagra Foods |
| Beyond Meat |
| Atlantic Natural Foods LLC |
| Tofurky |
| Impossible Foods Inc. |
| Quorn Foods |
| Tyson Foods Inc. |
| Amy's Kitchen Inc. |
| Others |
Value Network & Pricing Analysis
EU Green Deal compliance thresholds gate both qualified pea-protein supply and premium-tier pricing access, as formulations failing clean-label benchmarks face exclusion from German retail shelves and Nordic procurement contracts while certified alternatives command ingredient-list premiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates organic-certified sub-five-ingredient formulations from mid-range clean-label patties and budget-tier soy-dominant alternatives. Price differentiation hinges on certification grade and volume scale, with USDA organic and EU organic labels adding substantial shelf-price separation. Pricing pressure stems from yellow pea protein concentrate cost compression as Canadian harvest volatility transmits to processor margins. Institutional buyers under USDA school-meal guidelines exhibit highest price sensitivity, while direct-to-consumer subscribers show lowest sensitivity due to convenience bundling.
Supply Chain Analysis
Regional distribution centers in Chicago, Hamburg, and Toronto anchor hub-and-spoke cold-chain patterns for fresh patty delivery to coastal urban corridors. Raw material supply concentrates in Canadian prairie provinces for yellow pea protein, Midwestern US for soy isolate, and Dutch processing clusters for high-moisture extrusion equipment. Supply chain risk centers on single-source vulnerability for precision-fermentation heme protein as bioreactor capacity constraints limit batch consistency. Downstream distribution runs through broadline foodservice distributors for institutional placement and direct-to-consumer subscription platforms for premium-margin capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories rest on wet-fractionation cost-down curves in pea-protein extraction and the accelerating premium-tier shift toward sub-five-ingredient formulations in Nordic and German markets.
For Market Incumbents: Deepen backward integration into Canadian prairie pea-protein extraction to insulate margin predictability from harvest yield volatility. Fortify co-manufacturing protocols to address FDA allergen cross-contamination disclosure requirements that complicate shared extrusion lines between legacy soy and emerging pea formulations. Prioritize certification investment in USDA organic and EU organic tiers to defend shelf-position against clean-label entrants. For New Entrants and Emerging Players: Enter via meal-kit modular bundling in German and Dutch urban households where cooking-confidence gaps intersect with time scarcity and subscription penetration remains underdeveloped. Target fast-casual flame-broiling specifications in US coastal cities as high-moisture extrusion technology collapses texture-performance gaps. Pursue direct-to-consumer channel control to bypass retail slotting fees and capture repeat-purchase data for rapid formulation iteration. For Investors and Strategic Acquirers: Valuations sit cheapest among diversified meat processors with underutilized extrusion infrastructure and legacy cold-chain networks extensible into plant-based placement. Long-term viability across the projection horizon favors precision-fermentation specialists with locked-in bioreactor capacity and GRAS-affirmed novel protein pathways. Watch EFSA novel-food authorization timeline compression as the inflection signal for European market entry acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pea Protein Extraction | Captive supply of yellow pea isolate insulates margin predictability from Canadian prairie harvest volatility. |
| Direct-to-Consumer Subscription Launch | Bypasses retail slotting fees while capturing repeat-purchase behavioral data for formulation iteration. |
| Clean-Label Certification Investment | USDA organic and EU organic tiers unlock premium positioning in Nordic markets where ingredient-list length drives purchase decisions. |
| High-Moisture Extrusion Capacity Expansion | Next-generation textural fidelity enables flame-broiling applications previously restricted to animal protein in US fast-casual chains. |
| Regulatory Affairs Subsidiary Establishment | German and Dutch rapporteur procedures offer faster EFSA novel-food assessment timelines than Mediterranean regulators. |
Research Methodology
Direct dialogue with plant-based protein R&D directors, foodservice procurement managers at broadline distributors, regulatory affairs leads at novel-food entrants, and category buyers at German and US retailers grounded qualitative findings. Secondary validation drew from FDA GRAS notification databases, EFSA novel-food authorization registers, USDA school-meal procurement records, and Nielsen retail audit data. Bottom-up and top-down triangulation reconciled volume estimates across ingredient-source extraction capacity and end-user procurement contracts.
Bottom-up modeling traced pea-protein concentrate supply from Canadian prairie harvest yields through wet-fractionation processing costs to finished patty pricing tiers. Top-down analysis anchored total addressable market sizing on protein-equivalency qualification rates under USDA guidelines and EFSA retained frameworks. Segmentation dimensions spanned product type, ingredient source, end-user channel, and pricing tier. CAGRs derived from elasticity-adjusted demand curves for institutional versus retail channels across the analysis window. Forecast inputs incorporated cold-chain infrastructure expansion rates and precision-fermentation bioreactor capacity buildout timelines.
The model holds under stable regulatory equivalence rulings and intact cold-chain infrastructure; deviation in EFSA authorization delays or Canadian harvest shocks would shift volume and value trajectories. Forecasts reflect documented assumptions around protein-source substitution rates and channel-mix evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
China Plant Protein Market
Plant Based Food
Plant-Based Wellness Foods Market
Plant Based Food
Canada Plant Protein Market
Plant Based Food
Africa Soy Beverages Market
Plant Based Food
Europe Plant-Based Food Market
Plant Based Food
USA Plant-Based Creamers Market
Plant Based Food
United Kingdom Soy Protein Market
Plant Based Food
Pea Protein Market
Plant Based Food
Fermented Plant Extracts Market
Plant Based Food
Flax-Based Protein Market
Plant Based Food
Plant-Based Vegan Eggs Market
Plant Based Food
Vegan Chocolate Market
Plant Based Food
Plant Based Pork Market
Plant Based Food
Plant-Based Ham Market
Plant Based Food
South America Pea Protein Market
Plant Based Food
Vegan Flour Market