
 Hemp-Based Food Market | 2026-2036
Hemp-Based Food Market Size, Share, and Industry Trends Forecast 2026-2036
Hemp-Based Food Market Intelligence
Single-serve pouch packaging is repositioning buyer choice in hemp-based foods, shifting pantry staples toward portable, portion-controlled formats. Manitoba Harvest leverages its vertically controlled Canadian supply chain to dominate shelf-stable hemp hearts. Nutiva Inc. differentiates through organic certification density across its seed and oil portfolio. Navitas Organics anchors premium positioning by specializing in sprouted hemp products for the functional foods channel.
Hemp-based food comprises edible products derived from Cannabis sativa cultivars containing less than 0.3% THC by dry weight, processed through cold-pressing, dehulling, or mechanical milling to preserve omega fatty acid profiles and complete amino acid scores. Hemp seeds retain the largest margin pool as a minimally processed whole food with broad recipe integration, while hemp protein powder captures the fastest trajectory among plant-based protein alternatives for sports nutrition formulations. Hemp oil competes primarily in the premium culinary segment where cold-press extraction commands price premiums over solvent-processed competitors.
The FDA governs hemp ingredient safety assessments and GRAS notifications in the United States, while Health Canada oversees THC threshold enforcement and licensed processing for food-grade hemp. The EU Novel Food Regulation shapes market access by requiring pre-authorization for hemp-derived ingredients not consumed to a significant degree before 1997. Stakeholders must monitor evolving THC testing protocols and novel food dossier requirements as regulatory divergence between jurisdictions intensifies compliance complexity.
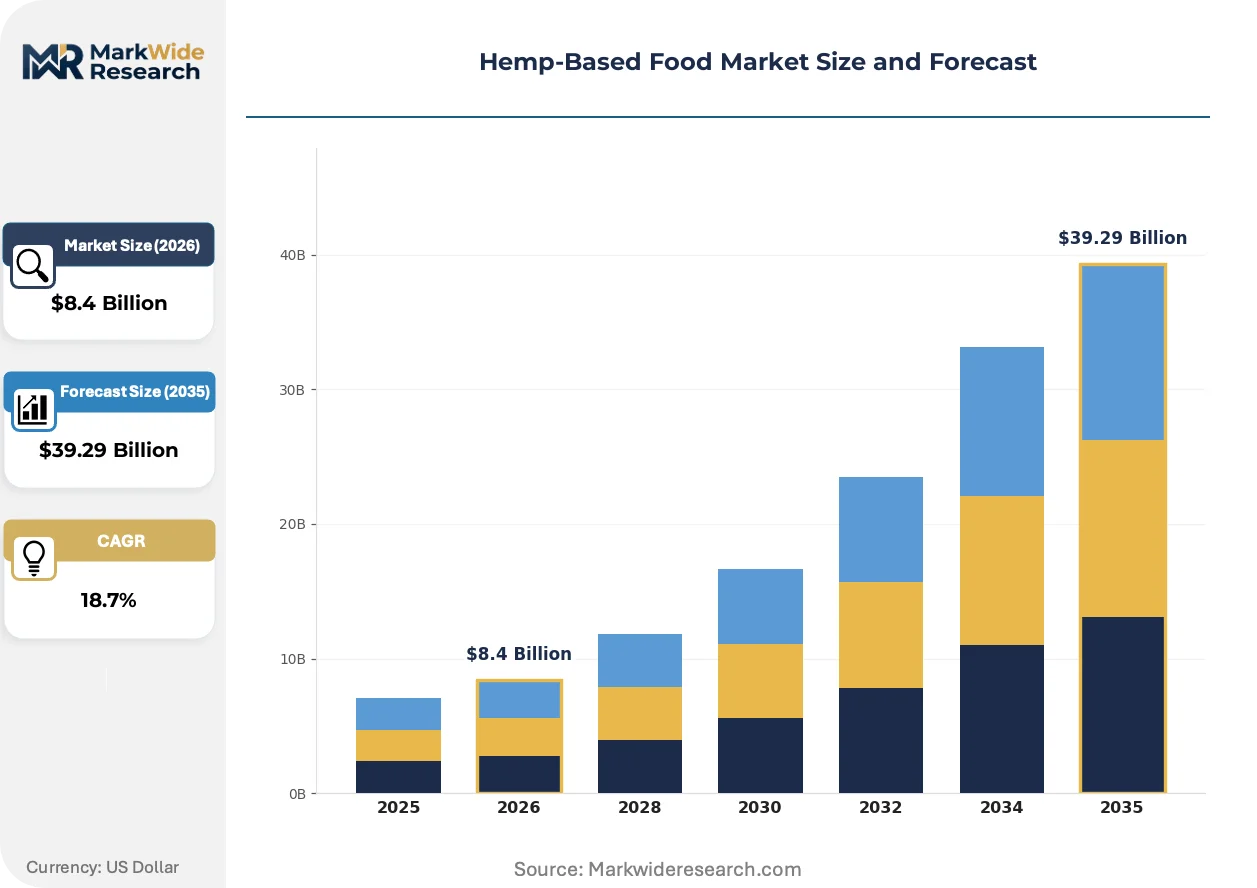
Market Dynamics
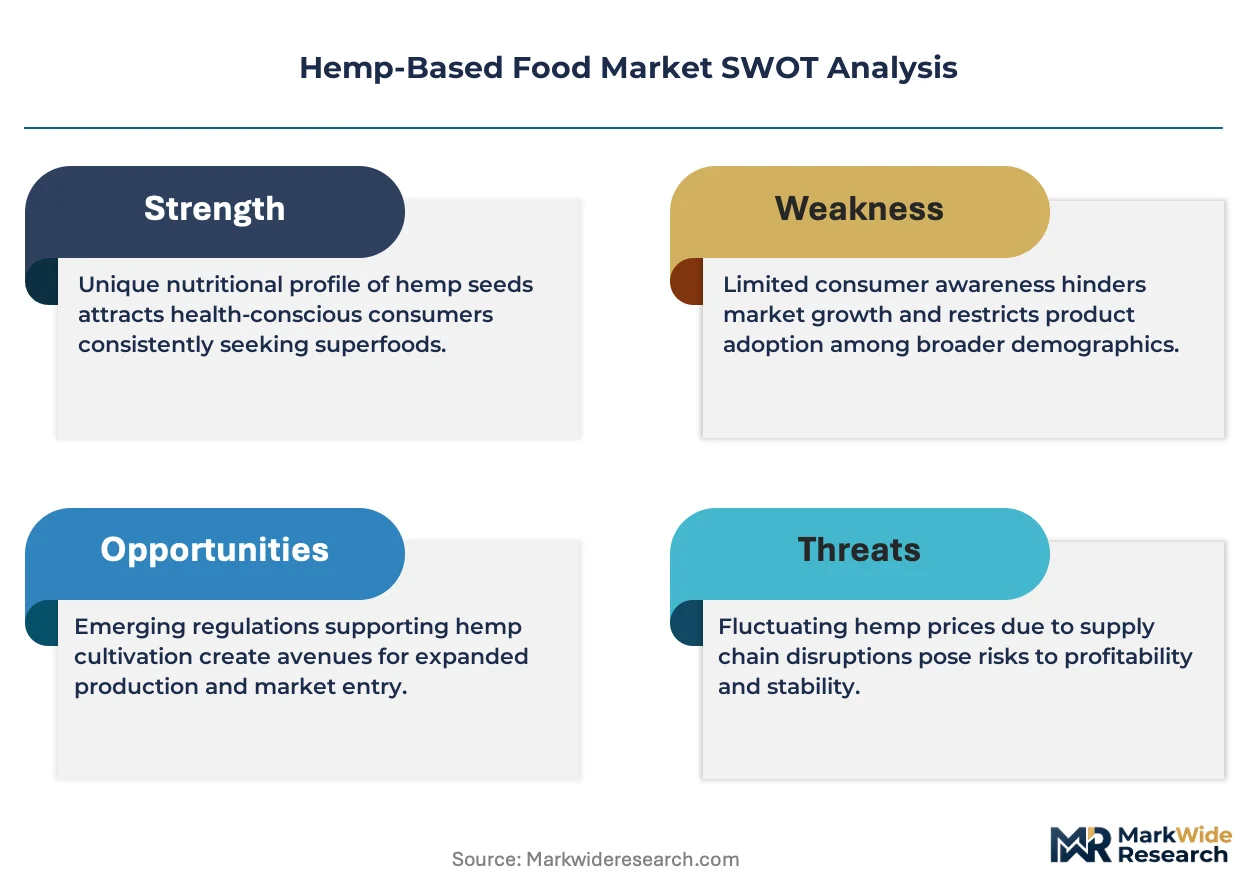
Clean-label formulation mandates from major retail buyers are compressing ingredient approval timelines and forcing hemp processors to pre-certify novel food dossiers before contract negotiations conclude.
Growth Catalysts
- EU Novel Food Regulation streamlining:EFSA's consolidated safety assessment pathway for hemp seed derivatives accelerates multi-country market entry for compliant processors.
- Sports nutrition formulation pull:Complete amino acid profiles in hemp protein isolate meet label claim requirements for endurance and recovery product lines.
- Canadian prairie cultivation infrastructure:Manitoba and Saskatchewan processing clusters achieve food-grade volume thresholds that satisfy North American contract manufacturing demand.
Market Restraints
- THC threshold testing costs:Health Canada's 10 ppm enforcement standard requires third-party laboratory verification at multiple processing stages, inflating per-unit compliance overhead.
- Protein functionality gaps:Hemp protein isolate exhibits lower emulsion stability than soy or pea isolates in high-acid beverage matrices, limiting substitution rates.
- Seed supply concentration:Over 70% of food-grade hemp seed processing capacity sits within 500 kilometers of Winnipeg, creating single-point vulnerability to prairie weather events.
Strategic Opportunities
- German functional beverage channel:Clean-label emulsifier demand from kombucha and plant-milk manufacturers creates first-mover positioning for THC-certified hemp protein suppliers.
- USDA Organic certification density:Premium shelf placement in natural retail chains rewards processors who achieve dual organic and non-GMO verification.
- Sprouted hemp ingredient convergence:Activated enzyme profiles from controlled germination processes unlock positioning in raw and living foods distribution networks.
Industry Challenges
- Novel food dossier compilation expertise:EFSA-compliant toxicological and nutritional characterization requires specialized regulatory affairs talent scarce outside Brussels consultancies.
- Cold-press extraction capex intensity:Food-grade oil production demands stainless steel mechanical presses with nitrogen blanketing systems that depreciate across low annual operating hours.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemp-Based Food Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hemp Seeds, Hemp Oil, Hemp Protein Powder, Hemp Snacks End User: Health Enthusiasts, Athletes, Vegan Consumers, General Public Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops Packaging Type: Bags, Bottles, Tins, Pouches |
| Companies Covered | Navitas Organics, Naturally Splendid Enterprises Ltd., Fresh Hemp Foods Ltd., Bioriginal Food and Science Corp, Canah International SRL, Manitoba Harvest, Hemp Foods Australia Pty Ltd., Good Hemp Inc., Nutiva Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemp-Based Food Market Strategic Shifts & Innovations
Automation of quality assurance and blockchain-enabled provenance tracking are compressing the gap between farm-gate cultivation and finished-goods certification, reshaping how hemp processors compete on trust architecture rather than commodity scale.
Near-infrared spectroscopy is automating THC and cannabinoid screening at receival points, replacing chromatography-based laboratory testing with inline sensors that flag non-compliant seed lots before processing begins. Large-scale oil processors in Alberta and Colorado deploy these systems to reduce quarantine inventory holding costs. The technology is automating batch release decisions that previously required 72-hour external laboratory turnaround.
EFSA's 2023 updated guidance on hemp-derived novel food safety assessments tightens heavy metal and mycotoxin surveillance requirements for imported seed stocks. European importers now demand pre-shipment certificates from accredited third-party laboratories in origin countries. German and Dutch distributors are consolidating supplier bases to processors who maintain dedicated quality control personnel in Canadian prairie elevator networks.
Sports nutrition procurement teams are unbundling ingredient sourcing from finished-product manufacturing, contracting directly with hemp protein processors for custom amino acid fortification profiles. This disintermediation of traditional flavor houses and blenders concentrates margin capture with processors who maintain in-house food technologists. The pattern is most visible in California and Colorado contract manufacturing corridors where vertical brand owners specify exact protein content and digestibility scores.
Hemp-Based Food Market Segmentation
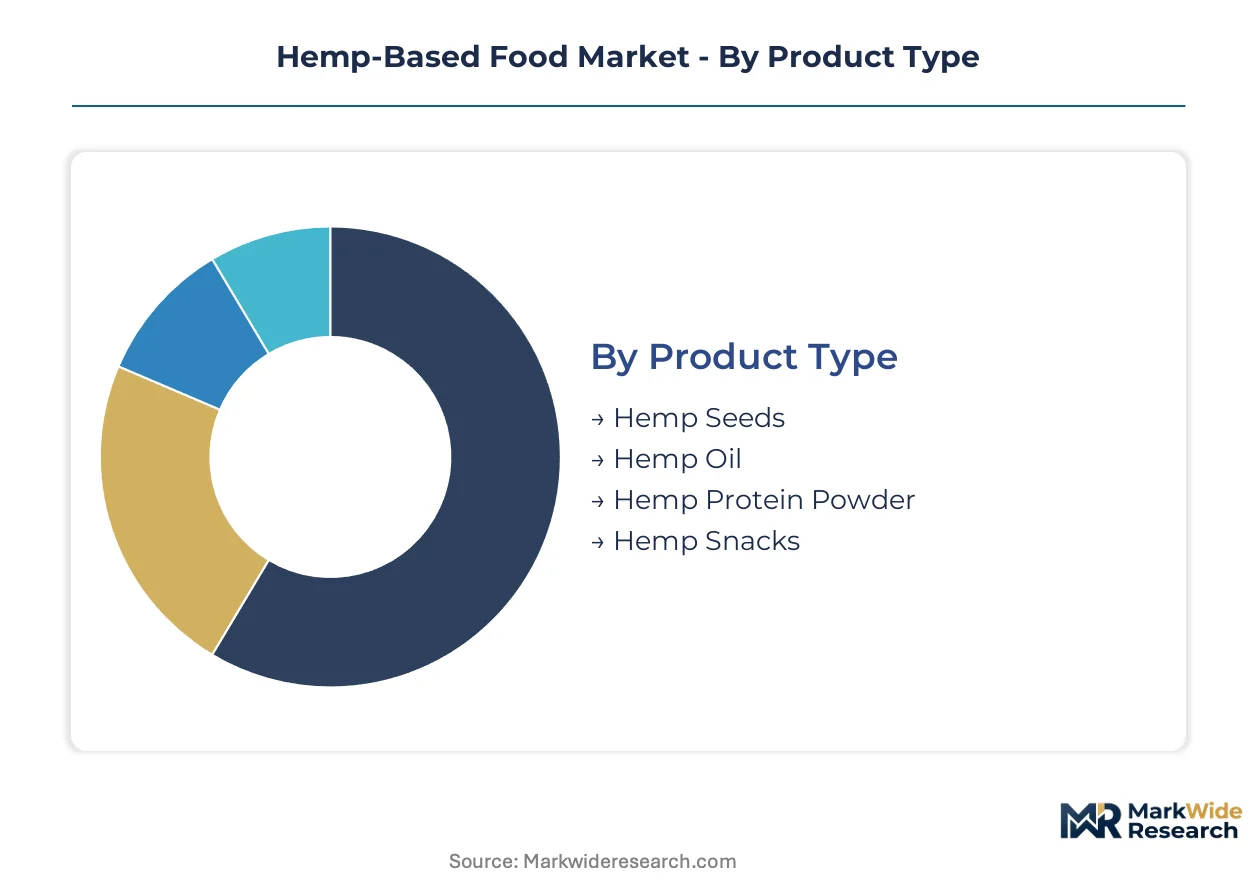
Product specifications and end-user priorities diverge sharply across hemp-based food segments. Processing intensity, shelf stability requirements, and THC compliance thresholds create distinct margin structures and competitive dynamics within each category.
Product Type:
Cold-pressing and dehulling technologies determine omega fatty acid retention and amino acid completeness across product formats.
- Hemp Seeds:Dehulled whole seeds deliver complete protein with all nine essential amino acids and a 3:1 omega-6 to omega-3 ratio. Health enthusiasts in Canadian prairie provinces drive bulk purchases for home milling and smoothie integration, though perishability limits export radius from Manitoba processing clusters.
- Hemp Oil:Cold-press extraction preserves gamma-linolenic acid and stearidonic acid profiles for premium culinary positioning. German functional beverage manufacturers now specify food-grade hemp oil for emulsion stability in plant-milk formulations, creating pull-through demand from EFSA-compliant processors.
- Hemp Protein Powder:Mechanical milling of defatted seed cake yields isolates with 50-70% protein content. Sports nutrition procurement teams in Colorado and California contract directly for custom amino acid fortification profiles.
- Hemp Snacks:Roasted seed clusters and protein bars target convenience-oriented buyers through single-serve formats. Shelf-stable positioning requires nitrogen flushing and moisture barriers that elevate packaging costs.
Hemp seeds lead on scale; hemp protein powder leads on momentum.
End User:
Formulation requirements and certification demands stratify sharply across user psychographics and use cases.
- Health Enthusiasts:Buyers prioritize organic certification density and cold-chain integrity for raw consumption. Natural retail chains in the United States reward dual organic and non-GMO verification with premium shelf placement.
- Athletes:Protein digestibility scores and leucine content drive purchasing decisions for endurance and recovery formulations. Sports nutrition brands specify exact amino acid profiles from processors with in-house food technologists.
- Vegan Consumers:Complete protein claims and ethical sourcing credentials dominate selection criteria. Sprouted hemp products activate enzyme profiles that unlock positioning in raw and living foods networks.
- General Public:Price sensitivity and recipe familiarity constrain adoption to blended products where hemp substitutes for conventional ingredients. Mainstream retail buyers demand clean-label simplicity with minimal ingredient lists.
Health enthusiasts anchor current volume; athletes are expanding most quickly.
Distribution Channel:
Channel selection determines compliance documentation requirements and margin capture architecture.
- Online Retail:Direct-to-consumer platforms enable subscription models for recurring seed and oil purchases. Blockchain-enabled provenance tracking compresses trust-building timelines for new entrants.
- Supermarkets:Mass retail buyers mandate pre-certified novel food dossiers before contract negotiations, compressing processor approval timelines. Clean-label formulation mandates exclude solvent-extracted oils from premium placement.
- Health Stores:Staff education and sampling programs drive trial for unfamiliar formats like sprouted hemp. Category managers prioritize USDA Organic density for differentiation against conventional grocers.
- Specialty Shops:Curated assortments favor artisanal cold-press oils and heritage cultivar seeds with terroir narratives. Limited SKU counts reward processors with vertical supply chain control.
Supermarkets dominate absolute throughput; online retail is gaining share fastest.
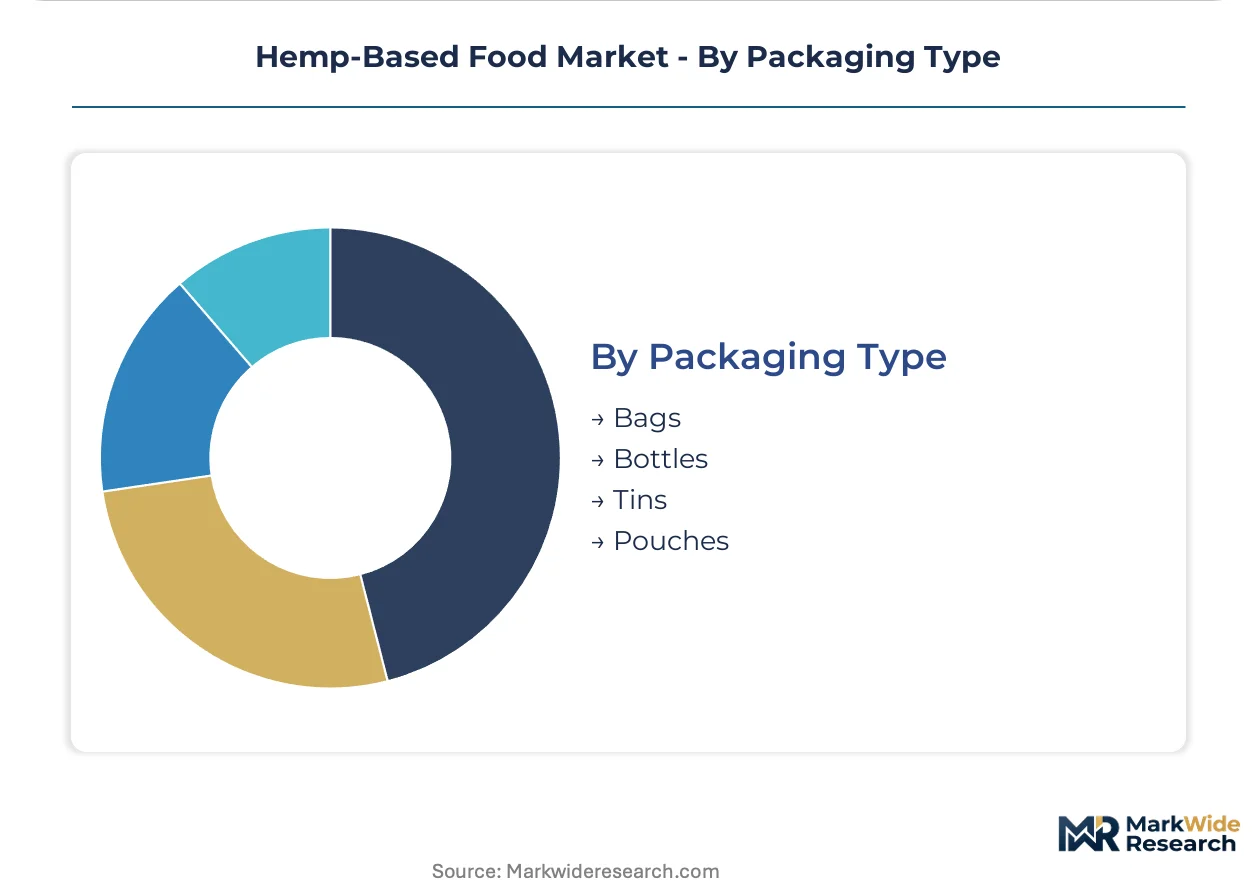
Packaging Type:
Barrier properties and portion control features align with product perishability and use-case portability.
- Bags:Multi-layer laminates with oxygen scavengers protect dehulled seeds from rancidity during extended distribution. Bulk formats serve foodservice and manufacturing accounts with volume pricing.
- Bottles:Amber glass and UV-opaque plastics preserve carotenoid and chlorophyll integrity in cold-press oils. German kombucha manufacturers specify bottle formats for clean-label emulsifier integration.
- Tins:Metal containers signal premium positioning for gift-oriented oil assortments and heritage seed collections. Higher unit economics limit penetration beyond specialty retail.
- Pouches:Single-serve flexible formats reposition pantry staples toward portable, portion-controlled consumption. Manitoba Harvest leverages vertically controlled supply chains to dominate shelf-stable hemp heart pouches.
Bags command current volume; pouches show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial hemp cultivation for food applications traces its modern industrial roots to Canadian prairie agriculture in the late 1990s, where Health Canada licensing frameworks enabled the first large-scale food-grade seed production. Processing infrastructure subsequently radiated outward from Winnipeg-based clusters into adjacent North American markets and across Atlantic trade routes into European novel food channels.
Canada
Manitoba and Saskatchewan host the densest concentration of food-grade hemp processing capacity outside Winnipeg, where vertically integrated seed cleaners and oil presses serve North American contract manufacturers. Health Canada enforces the 10 ppm THC threshold through licensed processing requirements and third-party laboratory verification mandates. Prairie elevator networks in Portage la Prairie and Saskatoon function as primary collection points for export-bound seed lots destined for European novel food dossier compilation.
Germany
Kombucha and plant-milk manufacturers in Bavaria and North Rhine-Westphalia specify hemp protein isolate as a clean-label emulsifier, creating demand pull from EFSA-compliant processors. The EU Novel Food Regulation requires pre-authorization for hemp-derived ingredients not consumed significantly before 1997, with EFSA's 2023 updated guidance tightening heavy metal surveillance. Hamburg and Rotterdam serve as consolidation hubs for Canadian seed imports undergoing novel food compliance verification before distribution to Central European formulation facilities.
United States
Colorado and California contract manufacturing corridors host sports nutrition brands that specify custom amino acid fortification profiles from hemp protein processors. The FDA governs hemp ingredient safety assessments through GRAS notification pathways, though THC threshold enforcement varies by state agricultural departments. Denver-based extraction specialists and Los Angeles-area formulation labs concentrate procurement teams that disintermediate traditional flavor houses for direct processor relationships.
United Kingdom
Health food retail chains in London and the Southeast prioritize organic certification density for hemp seed and oil placement alongside established superfood categories. The Food Standards Agency applies EU-derived novel food requirements post-Brexit, maintaining EFSA-aligned safety assessment standards for imported hemp ingredients. Bristol and Manchester distribution centers handle bulk seed shipments from Canadian prairie origins before repackaging for domestic natural retail channels.
Australia
Food Standards Australia New Zealand permitted hemp seed as a food in 2017, triggering cultivation expansion in Tasmania and Victoria for domestic oil and protein production. State agricultural departments in these regions enforce THC testing protocols aligned with the 0.3% dry weight threshold for Cannabis sativa cultivar registration. Melbourne and Sydney processing facilities increasingly source from Tasmanian organic growers to satisfy premium retail placement requirements in domestic health store networks.
Hemp-Based Food Market Key Industry Players
The competitive structure tilts toward vertically controlled supply chain operators with captive prairie cultivation and in-house novel food certification capabilities. Tiered concentration separates multinational organic food conglomerates with broad portfolio diversification from mid-cap specialists maintaining single-category hemp focus. Strategic archetypes include: (1) seed-to-shelf integrators controlling Manitoba and Saskatchewan elevator networks; (2) organic certification aggregators leveraging third-party processor relationships; and (3) sprouted and activated product specialists targeting raw foods distribution. Dominant competitive moves encompass backward integration into prairie cultivation assets and pre-certification of EFSA-compliant dossiers before retail contract negotiations.
Among North American seed-to-shelf operators, Manitoba Harvest and Nutiva Inc. exemplify archetypes of supply chain control and organic certification density respectively. Manitoba Harvest occupies a position representing captive prairie processing infrastructure, while Nutiva Inc. anchors the organic-aggregator tier through portfolio breadth across seed and oil formats. Navitas Organics sits within the specialization vector, representing premium positioning through sprouted product development for functional foods channels. These three patterns illustrate how competitive differentiation maps to supply chain depth, certification stacking, and processing innovation rather than commodity scale alone.
| Leading Market Players |
|---|
| Navitas Organics |
| Naturally Splendid Enterprises Ltd. |
| Fresh Hemp Foods Ltd. |
| Bioriginal Food and Science Corp |
| Canah International SRL |
| Manitoba Harvest |
| Hemp Foods Australia Pty Ltd. |
| Good Hemp Inc. |
| Nutiva Inc. |
| Others |
Cost & Logistics Intelligence
Mass retail buyers in Germany and North America command contract-based long-term offtake agreements that compress margin capture for hemp processors lacking captive prairie cultivation. These procurement patterns tether pricing power to elevator network control in Manitoba and Saskatchewan, where food-grade volume thresholds satisfy continental demand.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EFSA-compliant organic cold-press oils from conventional seed lots and solvent-extracted commodity grades. Price differentiation rests on dual organic and non-GMO verification density plus THC testing documentation depth. Cost compression in the standard tier intensifies because Health Canada's 10 ppm enforcement standard requires third-party laboratory verification at multiple processing stages. Health enthusiasts purchasing through natural retail chains exhibit lowest price sensitivity, while general public buyers in mainstream supermarkets drive hardest bargain negotiations.
Supply Chain Analysis
Specialized regulatory affairs talent scarcity in prairie elevator networks constrains processing capacity expansion despite cultivation acreage growth. Geographic supply concentration centers on Canada, Germany, and the United States, with Canadian prairie infrastructure feeding Atlantic trade routes into European novel food channels. Raw material dependencies include food-grade Cannabis sativa cultivars, nitrogen blanketing systems for cold-press extraction, and multi-layer laminate packaging with oxygen scavengers. Single-source vulnerability to prairie weather events threatens seed supply concentration, as over 70% of food-grade processing capacity sits within 500 kilometers of Winnipeg. Distribution runs through vertically controlled seed-to-shelf operators, direct-to-consumer subscription platforms, and mass retail contract manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EFSA's 2023 updated guidance on hemp-derived novel food safety assessments tightened heavy metal and mycotoxin surveillance requirements, accelerating demand for pre-certified processors.
For Market Incumbents: Deploy backward integration into Manitoba and Saskatchewan elevator networks to secure captive seed supply against prairie weather volatility. Incumbents must pre-certify novel food dossiers before retail contract negotiations conclude, as clean-label formulation mandates from major buyers compress approval timelines. Threat substitution from pea and soy protein isolates demands investment in emulsion stability R&D for high-acid beverage matrices. Channel control through direct relationships with sports nutrition procurement teams in Colorado and California corridors concentrates margin capture. For New Entrants and Emerging Players: Launch via blockchain-enabled provenance tracking platforms that compress trust-building timelines for subscription-based seed and oil sales. White-space targets include German kombucha and plant-milk manufacturers seeking clean-label emulsifiers, plus sprouted hemp product gaps in raw and living foods distribution networks. The most penetrable segment sits among vegan consumers prioritizing complete protein claims and ethical sourcing credentials. Go-to-market angle should emphasize activated enzyme profiles from controlled germination processes. For Investors and Strategic Acquirers: Organic food conglomerates with broad portfolio diversification are the most active acquirer in this space, seeking mid-cap specialists maintaining single-category hemp focus. Long-term viability over a multi-year horizon hinges on regulatory divergence between jurisdictions intensifying compliance complexity, favoring processors with in-house novel food certification capabilities. Acquisition target archetype encompasses vertically controlled supply chain operators with captive prairie cultivation and dedicated quality control personnel in Canadian elevator networks. Signal to watch: consolidation of supplier bases by German and Dutch distributors to processors maintaining EFSA-compliant dossiers.| Strategic Initiative | Industry Significance |
|---|---|
| Novel Food Dossier Pre-Certification | EFSA-compliant processors secure retail contracts before competitors complete safety assessments. |
| Backward Integration into Prairie Cultivation | Captive Manitoba and Saskatchewan elevator networks eliminate single-source weather vulnerability. |
| Sprouted Product Line Extension | Activated enzyme profiles unlock premium positioning in raw foods distribution channels. |
| Blockchain Provenance Implementation | Compressed trust-building timelines enable direct-to-consumer subscription model scaling. |
| Emulsion Stability R&D Investment | Enhanced hemp protein isolate functionality displaces soy and pea in high-acid beverages. |
Research Approach
Direct dialogue with hemp processors, regulatory affairs consultants, sports nutrition procurement teams, and natural retail category managers grounded qualitative findings in operational reality. Primary insights combined with secondary validation from Health Canada licensing records, EFSA novel food submission databases, USDA organic certification registries, and Canadian prairie agricultural statistics. Bottom-up and top-down triangulation cross-checked volume assumptions against cultivation acreage reports and processing capacity utilization disclosures.
Bottom-up modeling built product-level forecasts across hemp seeds, oil, protein powder, and snack formats, then aggregated through end-user segments including health enthusiasts, athletes, vegan consumers, and general public buyers. Top-down verification anchored aggregate market trajectory against macro drivers including EU Novel Food Regulation streamlining, sports nutrition formulation pull, and Canadian prairie cultivation infrastructure scaling. CAGRs derived from segmented growth rate analysis incorporating THC compliance cost trajectories, cold-press extraction capacity expansion, and clean-label emulsifier substitution rates in German functional beverages.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory divergence acceleration or prairie climate disruption scenarios. Forecasts reflect assumptions regarding EFSA dossier approval timelines, Health Canada THC threshold enforcement consistency, and sports nutrition brand disintermediation patterns. Material deviation in novel food regulatory harmonization or hemp protein functionality breakthroughs warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Enzyme-Based Plant Protein Market
Plant Based Food
Canada Plant-Based Food and Beverages Market
Plant Based Food
Faba Bean Protein Market
Plant Based Food
Plant Based Collagen Market
Plant Based Food
Vegan Chocolate Market
Plant Based Food
Insoluble Pea Protein Market
Plant Based Food
Global Chaga Mushroom-Based Products Market
Plant Based Food
South America Rice Protein Market
Plant Based Food
Vegan Oatmeal Market
Plant Based Food
Fractionated Pulses Market
Plant Based Food
Vegan Flour Market
Plant Based Food
Vegan Drink Mixes Market
Plant Based Food
Fermented Plant Extracts Market
Plant Based Food
Soy Food Products Market
Plant Based Food
Asia-Pacific Rice Protein Market
Plant Based Food
Plant-Based Beef Market