
 Plant-Based Wellness Foods Market | 2026-2036
Plant-Based Wellness Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Wellness Foods Market Analytics
Asset-light co-manufacturing partnerships is reconfiguring competitive entry barriers, allowing emerging brands to scale without capital-intensive production facilities. Beyond Meat leverages captive production capacity to sustain quality consistency across North American and European retail channels. Danone anchors its position through backward integration into oat and almond supply chains, securing ingredient traceability. Oatly Group competes through direct-store-delivery logistics that control shelf placement in premium grocery formats.
Plant-based wellness foods comprise formulated products derived from non-animal proteins, botanical extracts, and functional ingredients, manufactured through extrusion, fermentation, or high-pressure processing to achieve specific amino acid profiles, bioactive compound retention, and sensory parity with conventional foods; their primary purpose is to deliver targeted health outcomes including cardiovascular support, digestive health, and athletic recovery. Dairy substitutes occupy the largest revenue pool due to established consumer familiarity and coffee-shop distribution density, while meat alternatives represent the fastest-growing category as extrusion technology improves fibrous texture replication. Pea protein dominates ingredient sourcing for its allergen-friendly profile and complete amino acid composition, whereas ready-to-eat formats capture expanding convenience-oriented demand.
FDA nutrition labeling requirements and the USDA Organic certification framework shape product formulation and marketing claims in the United States, while EFSA novel food assessments govern ingredient approvals across European markets. The EU Green Deal's sustainability reporting mandates, including CSRD-aligned disclosures, are forcing reformulation investments and supply chain carbon accounting. Stakeholders must monitor evolving protein-quality scoring methodologies and emerging fermentation-derived ingredient regulatory classifications to anticipate compliance costs and first-mover positioning.
Market Dynamics
Asset-light co-manufacturing partnerships are dissolving traditional capital barriers for plant-based wellness entrants, while the EU Green Deal's Farm to Fork Strategy forces simultaneous reformulation and carbon-accounting investments across European supply chains.
Growth Catalysts
- EFSA Novel Food Assessments:Streamlined approval pathways for fermentation-derived proteins accelerate ingredient innovation timelines across European markets.
- Sports Nutrition End-Use:Athletic recovery applications drive pea protein demand due to complete amino acid composition and allergen-friendly positioning.
- German Retail Density:Exceptional shelf penetration for plant-based wellness lines creates template distribution models replicable in adjacent Western European markets.
Market Restraints
- Pea Protein Supply Concentration:Ingredient sourcing clusters in limited North American and Baltic processing facilities, exposing buyers to harvest volatility.
- Extrusion Equipment Capex:High-pressure processing and fibrous texture replication machinery require seven-figure capital commitments, favoring scaled incumbents.
- CSRD Reporting Burden:EU sustainability disclosure mandates impose compliance costs that compress margins for mid-tier producers lacking dedicated ESG infrastructure.
Strategic Opportunities
- Clinical Dietetics Channel:Hospital and therapeutic nutrition procurement opens institutional volume contracts with multi-year tenors and formulation stability.
- Fermentation-Extrusion Convergence:Precision biomass cultivation combined with mechanical texturizing enables whole-muscle structure replication previously unattainable.
- Direct-Store-Delivery Logistics:Controlled shelf placement in premium grocery formats bypasses traditional distributor markups and secures prime positioning.
Industry Challenges
- Fermentation Scale-Up Talent:Industrial bioprocessing expertise remains concentrated in pharmaceutical sectors, creating recruitment competition for food-tech ventures.
- Protein-Quality Scoring Uncertainty:Evolving DIAAS and PDCAAS methodologies complicate label claim substantiation and cross-border marketing consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Wellness Foods Market |
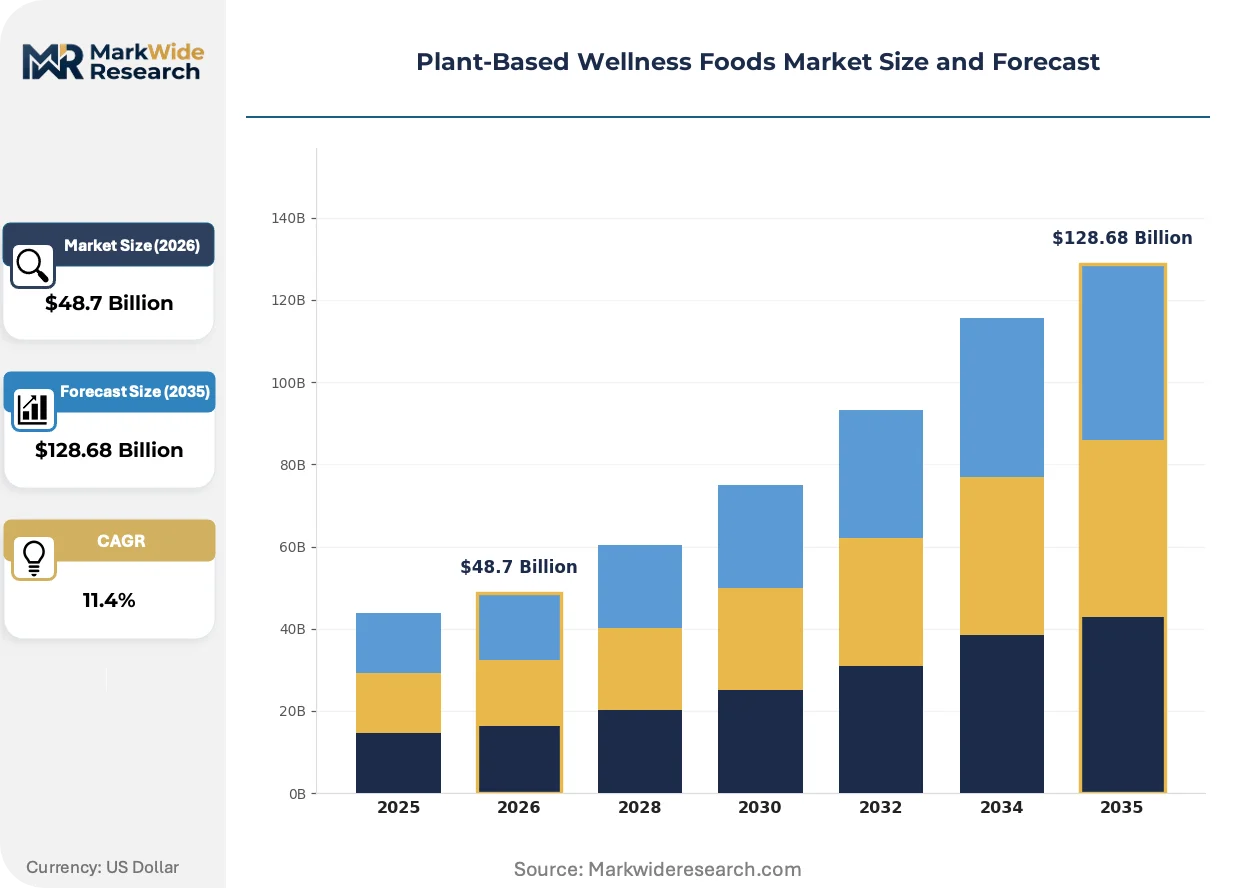
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $128.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat Alternatives, Dairy Substitutes, Snacks, Beverages Ingredient: Pea Protein, Almond Milk, Coconut Oil, Quinoa Form: Frozen, Dry, Liquid, Ready-to-Eat End User: Health-Conscious Consumers, Vegans, Vegetarians, Flexitarians |
| Companies Covered | Nestlé, Danone, Beyond Meat, Impossible Foods, Glanbia, Abbott, Herbalife, Oatly Group, The Hain Celestial Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Wellness Foods Market Evolving Landscape
Bioprocess engineering and precision fermentation are compressing the cost-performance gap between plant-derived and animal-derived proteins, reshaping competitive economics across formulated food categories.
Precision fermentation of whey-identical proteins is rendering obsolete traditional dairy-dependent supply chains for sports nutrition applications. Athletic supplement brands in North America and Western Europe are reformulating protein isolates around microbial-derived casein and lactoferrin analogs. This biotechnology is rendering obsolete the acreage-intensive, water-heavy grazing systems that previously anchored premium positioning in recovery nutrition.
The EU Green Deal's CSRD-aligned sustainability reporting mandates are forcing ingredient traceability investments throughout European supply chains. Food producers must now document Scope 3 emissions from oat cultivation through retail distribution, accelerating blockchain and satellite-verification adoption. German and Dutch plant-based manufacturers face the steepest compliance curves due to early enforcement timelines and stringent national interpretations.
Coffee-shop channel density is compressing consumer trial cycles for dairy substitutes beyond traditional grocery velocity patterns. Barista-format oat and almond milks now function as category entry points, with on-premise consumption driving at-home purchase conversion. This channel dynamic concentrates demand generation in urban clusters with specialty coffee penetration above fifteen percent, particularly in Melbourne, Berlin, and Los Angeles metropolitan corridors.
Plant-Based Wellness Foods Market Segmentation
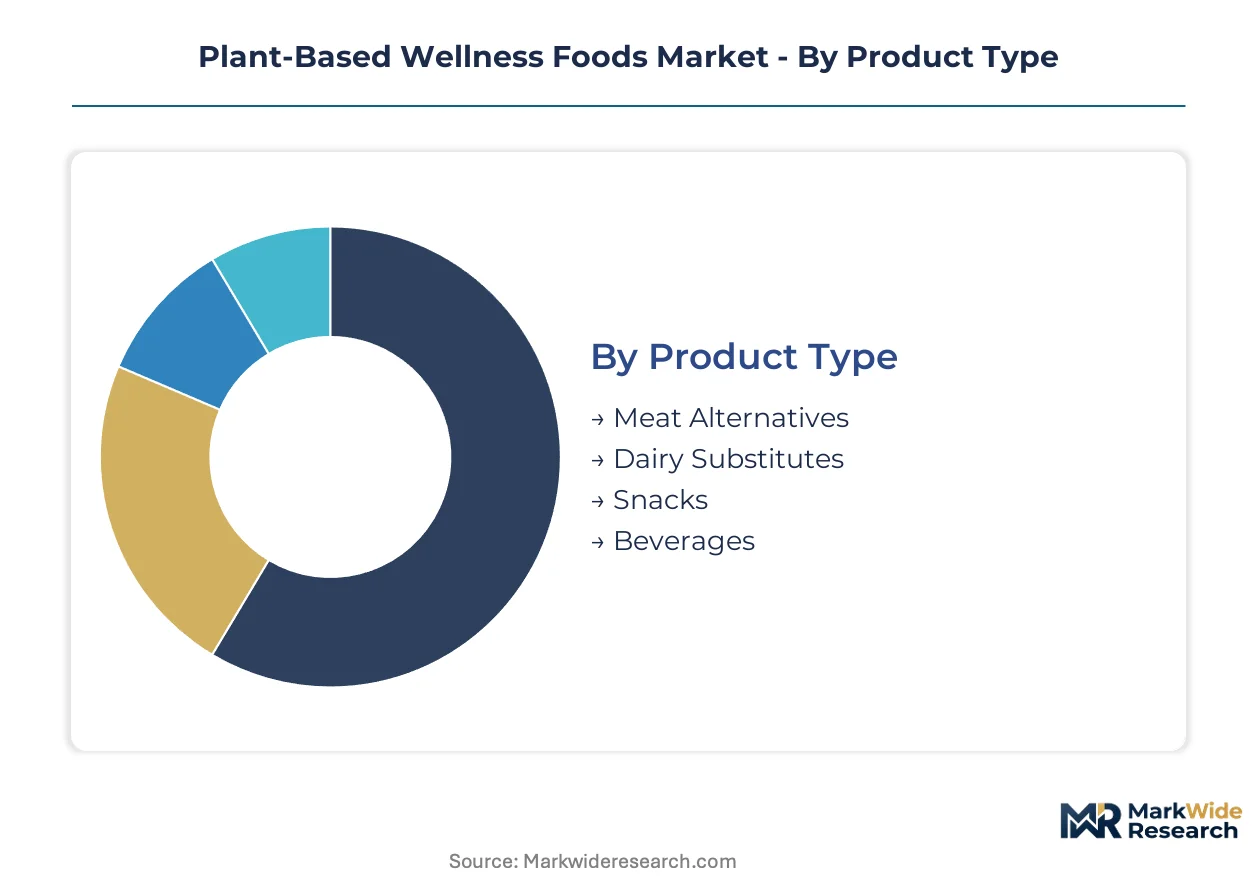
Plant-based wellness foods fragment across four distinct taxonomies that determine formulation priorities, supply chain configuration, and channel strategy. Product type dictates manufacturing capital intensity, while ingredient selection governs allergen positioning and protein quality claims. Form factor shapes cold-chain requirements and retail placement economics. End-user segmentation separates premium positioning from mass-market penetration.
Product Type:
Use-case spectrum spans athletic recovery applications through everyday meal replacement, with texture fidelity requirements varying dramatically across consumption contexts.
- Dairy Substitutes:Formulated oat, almond, and soy-based beverages engineered for foaming stability and neutral flavor profiles. Demand concentrates in urban coffee-shop corridors where barista-format products drive trial conversion; EFSA novel food assessments govern fermentation-derived dairy analog approvals.
- Meat Alternatives:Extruded or fermented protein matrices replicating fibrous muscle structure through high-pressure processing and shear-cell technology. German retail density creates template distribution models for whole-cut replication products; sports nutrition procurement opens institutional volume contracts.
- Snacks:Protein-fortified bars, puffs, and crisps leveraging pea protein isolates for complete amino acid composition.
- Beverages:Functional shots and ready-to-drink formulations incorporating botanical extracts for targeted health outcomes.
Established volume favors Dairy Substitutes; emerging adoption favors Meat Alternatives.
Ingredient:
Cost tier stratification separates commodity-scale inputs from precision-cultivated specialty proteins with traceability premiums.
- Pea Protein:Isolated yellow pea fractions with complete essential amino acid profiles and low allergen cross-reactivity. Sports nutrition brands in North America and Western Europe prioritize pea isolates for recovery formulations; supply concentration in Baltic and Canadian processing facilities exposes buyers to harvest volatility.
- Almond Milk:Blended and strained almond bases with vitamin fortification for calcium and vitamin D parity with dairy.
- Coconut Oil:Cold-pressed or refined medium-chain triglyceride sources providing texture and shelf-stability in frozen desserts.
- Quinoa:Pseudocereal grain valued for complete protein composition and gluten-free positioning in snack applications.
Ingredient sourcing clusters around Pea Protein for scale; Quinoa commands premium positioning for nutritional density.
Form:
Supply concentration varies with cold-chain infrastructure requirements and packaging technology maturity.
- Ready-to-Eat:Shelf-stable or refrigerated prepared meals requiring minimal consumer preparation. Convenience-oriented demand in metropolitan clusters with specialty grocery penetration above fifteen percent drives velocity; direct-store-delivery logistics secure prime shelf positioning.
- Frozen:Blast-chilled meat alternatives and prepared meals preserving texture through ice-crystal control.
- Dry:Dehydrated protein powders, grains, and mixes with extended shelf life and reduced shipping weight.
- Liquid:Pourable dairy substitutes and functional beverages demanding aseptic packaging investment.
Margin structure favors Ready-to-Eat for premium positioning; volume scale favors Frozen for retail distribution depth.
End User:
Customer type determines marketing claim substantiation requirements and channel selection intensity.
- Flexitarians:Consumers reducing animal protein without eliminating it, driving sensory parity demands. This segment captures expanding convenience-oriented demand across Berlin, Los Angeles, and Melbourne metropolitan corridors; coffee-shop channel density compresses trial cycles for dairy substitutes.
- Health-Conscious Consumers:Buyers prioritizing cardiovascular support, digestive health, and clean-label ingredient transparency.
- Vegans:Strict plant-based adherents requiring complete nutritional adequacy including B12 and iron fortification.
- Vegetarians:Lacto-ovo consumers seeking protein diversification without meat reintroduction.
Commercial momentum concentrates with Flexitarians; formulation rigor concentrates with Vegans.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's Farm to Fork Strategy is accelerating sustainability investments across European food supply chains. Germany's retail density for plant-based wellness lines creates template distribution models replicable in adjacent markets. Coffee-shop channel concentration in specific metropolitan corridors is compressing consumer trial cycles beyond traditional grocery velocity patterns.
Germany
Barista-format oat milk penetration in Berlin and Hamburg coffee-shop corridors drives at-home purchase conversion for dairy substitutes. The country's national food safety regulator enforces stringent novel food assessments under EU harmonized standards. Bavaria's food-tech cluster hosts precision fermentation scale-up facilities serving sports nutrition brands.
United States
FDA nutrition labeling requirements and USDA Organic certification frameworks shape formulation decisions for cardiovascular and digestive health claims. The Inflation Reduction Act's bioeconomy provisions support domestic fermentation infrastructure investments. Los Angeles and Austin metropolitan areas concentrate direct-store-delivery logistics for premium grocery placement.
United Kingdom
Post-Brexit regulatory divergence from EFSA novel food pathways creates parallel approval timelines for fermentation-derived ingredients. The Competition and Markets Authority monitors sustainability claim substantiation under consumer protection frameworks. London's specialty coffee density exceeds fifteen percent penetration, establishing template trial-to-purchase conversion mechanics.
Netherlands
Oat cultivation and processing integration in the Randstad region secures ingredient traceability for ESG-aligned procurement. The country's national environmental agency enforces CSRD-aligned sustainability reporting ahead of broader EU timelines. Eindhoven's food-tech corridor hosts extrusion equipment engineering specialists serving meat alternative manufacturers.
China
Dual carbon goals and provincial clean production mandates accelerate plant protein facility investments in Yangtze River Delta manufacturing zones. The national market regulator implements GB standards for novel food safety assessments distinct from Western frameworks. Shanghai's specialty coffee expansion creates channel density comparable to Melbourne and Berlin corridors.
Plant-Based Wellness Foods Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. Asset-light co-manufacturing partnerships allow emerging brands to bypass capital-intensive production facilities. Three archetypes dominate: integrated multinationals with captive supply chains, pure-play plant-based specialists, and ingredient-technology licensors. M&A activity concentrates on fermentation scale-up capabilities and direct-store-delivery logistics networks.
Within the integrated multinational tier, Nestlé and Danone occupy positions exemplifying backward integration into oat and almond supply chains for ingredient traceability. Among pure-play specialists, Beyond Meat and Oatly Group represent contrasting scale strategies: captive production capacity versus controlled shelf placement in premium formats. The Hain Celestial Group anchors the natural-foods channel specialist archetype with portfolio breadth spanning multiple plant-based categories.
| Leading Market Players |
|---|
| Nestlé |
| Danone |
| Beyond Meat |
| Impossible Foods |
| Glanbia |
| Abbott |
| Herbalife |
| Oatly Group |
| The Hain Celestial Group |
| Others |
Value Network & Pricing Analysis
Baltic and Canadian pea protein processing concentration funnels margin capture toward ingredient-technology licensors and away from finished-goods brands lacking backward integration into supply chains.
Pricing Analysis
Certification level creates the primary spread, with USDA Organic and EFSA novel food approvals commanding tiered premiums over conventional formulations. Three-tier pricing structure across premium, standard, and economy levels reflects protein-quality scoring methodology alignment and clean-label positioning intensity. Cost compression in mid-tier extruded meat alternatives is intensifying because extrusion equipment capex favors scaled incumbents with depreciated machinery. Health-conscious consumers in specialty coffee corridors show least price sensitivity, while mass-market flexitarians in conventional grocery drive volume at compressed margins.
Supply Chain Analysis
Export-control regimes on precision fermentation bioreactor technology limit equipment flows from German and Dutch engineering specialists to aspiring Asian producers. Ingredient sourcing clusters in Canada, the Baltic states, and the Netherlands for pea protein isolates and oat bases. Raw material dependencies center on yellow pea cultivation cycles, almond harvests from California, and coconut oil from Southeast Asian processors. Single-source vulnerability runs through limited North American extrusion equipment manufacturers. Distribution feeds from direct-store-delivery logistics networks in premium grocery formats and coffee-shop channel intermediaries in metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-based wellness foods are approaching a platform-economics inflection where fermentation-derived ingredient interoperability will determine which formulation ecosystems capture compounding returns.
For Market Incumbents: Entrench backward integration into oat and almond supply chains to defend against precision fermentation disruptors eroding traditional plant-protein positioning. Secure captive extrusion capacity in Germany and the Netherlands before equipment lead times extend. CSRD-aligned sustainability reporting investments function as a regulatory moat against mid-tier competitors lacking ESG infrastructure. For New Entrants and Emerging Players: Pursue clinical dietetics procurement channels where institutional volume contracts offer formulation stability and multi-year tenors absent from retail velocity competition. White-space concentration sits with therapeutic nutrition applications in hospital systems and sports nutrition procurement for athletic recovery formulations. Asset-light co-manufacturing partnerships bypass seven-figure extrusion capex requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision fermentation scale-ups possessing pharmaceutical-sector bioprocessing talent but lacking food-commercialization expertise. Long-term viability hinges on fermentation-extrusion convergence capabilities and direct-store-delivery logistics network control. Watch for EFSA novel food approval acceleration as signal of ingredient-innovation timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Scale-Up Investment | Precision biomass cultivation compresses cost-performance gaps with animal-derived proteins. |
| Direct-Store-Delivery Expansion | Controlled shelf placement in premium formats bypasses traditional distributor markups. |
| Clinical Dietetics Channel Entry | Hospital procurement opens institutional contracts with multi-year formulation stability. |
| Backward Integration into Oat Supply | Ingredient traceability secures ESG-aligned positioning under EU Green Deal mandates. |
| Co-Manufacturing Partnership Network | Asset-light models allow emerging brands to scale without capital-intensive production facilities. |
Research Methodology
Desk research of EFSA novel food assessment databases, USDA Organic certification records, and EU CSRD sustainability disclosure filings preceded structured interviews with plant-based food brand managers, extrusion equipment engineers, and hospital procurement directors. Primary fieldwork with specialty coffee channel buyers and sports nutrition formulators cross-validated velocity patterns and ingredient sourcing decisions. Secondary triangulation drew from customs trade data on pea protein isolates, Nielsen retail audit information, and SEC filings from publicly traded manufacturers. Bottom-up volume modeling and top-down category sizing converged through iterative calibration.
Assumptions held fixed include EFSA novel food approval timelines, EU Green Deal enforcement trajectories, and protein-quality scoring methodology stability; variables tested encompassed fermentation scale-up cost curves and coffee-shop channel expansion rates. Segmentation dimensions spanned product type, ingredient source, form factor, and end-user archetype across the projection horizon. CAGRs derived from logistic adoption curves fitted to historical analogs in functional food categories. Forecast inputs incorporated extrusion technology maturity, precision fermentation yield improvements, and retail distribution density metrics.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity price volatility or energy cost trajectories would shift the trajectory. Forecasts reflect these documented assumptions. Material shifts in EFSA regulatory posture or EU CSRD implementation timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Protein Foods Market
Plant Based Food
Smart Plant Based Food Packaging Market
Plant Based Food
Hemp-Based Food Market
Plant Based Food
United Kingdom Tofu Market
Plant Based Food
Vegan Meat Alternatives Market
Plant Based Food
Plant-Based Natural Flavor Market
Plant Based Food
Canada Plant Protein Market
Plant Based Food
Packed Vegan Foods Market
Plant Based Food
United States Pea Protein Market
Plant Based Food
Vegan Dessert Market
Plant Based Food
Insoluble Pea Protein Market
Plant Based Food
Pea Protein Market
Plant Based Food
Faba Bean Protein Market
Plant Based Food
Global Chaga Mushroom-Based Products Market
Plant Based Food
United Kingdom Soy Protein Market
Plant Based Food
United Kingdom Plant Protein Market