
 Global Calciphylaxis Treatment Market | 2026-2036
Global Calciphylaxis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Calciphylaxis Treatment Market Foresight
Specialty-grade sodium thiosulfate formulations is bifurcating the competitive landscape between commoditized generics and high-purity hospital-grade supply. Fresenius Medical Care anchors its position through captive dialysis center networks that internalize patient flow. Amgen Inc. differentiates via biologic R&D intensity targeting parathyroid hormone modulation pathways. Smith & Nephew plc specializes in advanced wound care adjacencies that complement pharmaceutical intervention.
Calciphylaxis treatment encompasses pharmacological and wound management interventions targeting calcific uremic arteriolopathy, a rare vascular calcification disorder characterized by painful skin necrosis in patients with renal dysfunction. Sodium thiosulfate chelates calcium deposits through thiosulfate-calcium complex formation, while hyperbaric oxygen and debridement address tissue hypoxia. The therapy area dimension shows End-Stage Renal Disease commanding the largest patient pool due to uremia-driven mineral dysregulation, with Diabetes-Associated calciphylaxis representing the fastest-growing subsegment as diabetic nephropathy prevalence rises. Product type dynamics favor phosphate binders as the mature revenue base, while parathyroid hormone modulators capture expanding margin pools from novel mechanism-of-action premiums.
FDA orphan drug incentives and EMA's rare disease framework jointly shape clinical trial design and market exclusivity timelines for calciphylaxis developers. The EU MDR and FDA 510(k) pathways impose divergent evidentiary standards on wound care devices versus pharmaceutical interventions, fragmenting go-to-market strategies. Stakeholders must monitor reimbursement parity between dialysis bundled payments and standalone calciphylaxis therapy codes to assess commercial viability.
Market Dynamics
The calciphylaxis treatment market is undergoing structural pressure from the FDA's orphan drug designation pathway, which compresses development timelines and concentrates sponsor investment around sodium thiosulfate formulations and parathyroid hormone modulators. This regulatory acceleration is reshaping competitive positioning between commoditized generics and high-purity hospital-grade supply chains.
Growth Catalysts
- Orphan Drug Incentives:The FDA's designation framework grants market exclusivity and tax credits to calciphylaxis therapy developers, accelerating clinical trial enrollment and reducing regulatory friction for novel mechanisms targeting vascular calcification.
- Dialysis Center Expansion:Fresenius Medical Care and DaVita are expanding captive nephrology networks across the United States, internalizing patient flow and creating dedicated channels for advanced wound care pharmaceutical intervention.
- Biologic R&D Intensity:Amgen Inc.'s investment in parathyroid hormone modulation pathways is generating novel calcimimetic candidates that address uremia-driven mineral dysregulation with improved specificity over phosphate binders.
Market Restraints
- Supply Concentration Risk:High-purity sodium thiosulfate production concentrates among a limited base of specialty chemical manufacturers in Germany and Switzerland, creating vulnerability to input cost volatility and batch consistency constraints.
- Reimbursement Fragmentation:The divergence between dialysis bundled payments and standalone calciphylaxis therapy codes in the United States creates pricing uncertainty that compresses commercial viability for novel entrants.
- Technical Limitation:Current hyperbaric oxygen protocols demonstrate inconsistent efficacy in tissue hypoxia resolution for deep vascular calcification cases, limiting addressable patient populations.
Strategic Opportunities
- Diabetes-Associated Subsegment:Diabetic nephropathy prevalence is expanding the fastest-growing calciphylaxis patient pool, creating white space for targeted therapy development in the United States and Western Europe.
- EMA Rare Disease Framework:The European Medicines Agency's accelerated assessment pathway offers 150-day review timelines for calciphylaxis therapies, enabling faster market access across Germany, France, and Italy.
- Advanced Wound Care Convergence:Smith & Nephew plc's integration of negative pressure wound therapy with pharmaceutical chelation protocols is opening new reimbursement categories in hospital outpatient settings.
Industry Challenges
- Specialist Workforce Scarcity:Certified wound care nurses and nephrology pharmacists are in short supply across dialysis networks, constraining protocol adherence and therapy administration capacity.
- EU MDR Compliance Timeline:The Medical Device Regulation's strengthened evidentiary requirements for wound care devices are extending certification cycles and increasing clinical data generation costs.
- Integration Complexity:Electronic health record systems in dialysis centers require custom configuration to track calciphylaxis-specific quality metrics, delaying protocol standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Calciphylaxis Treatment Market |
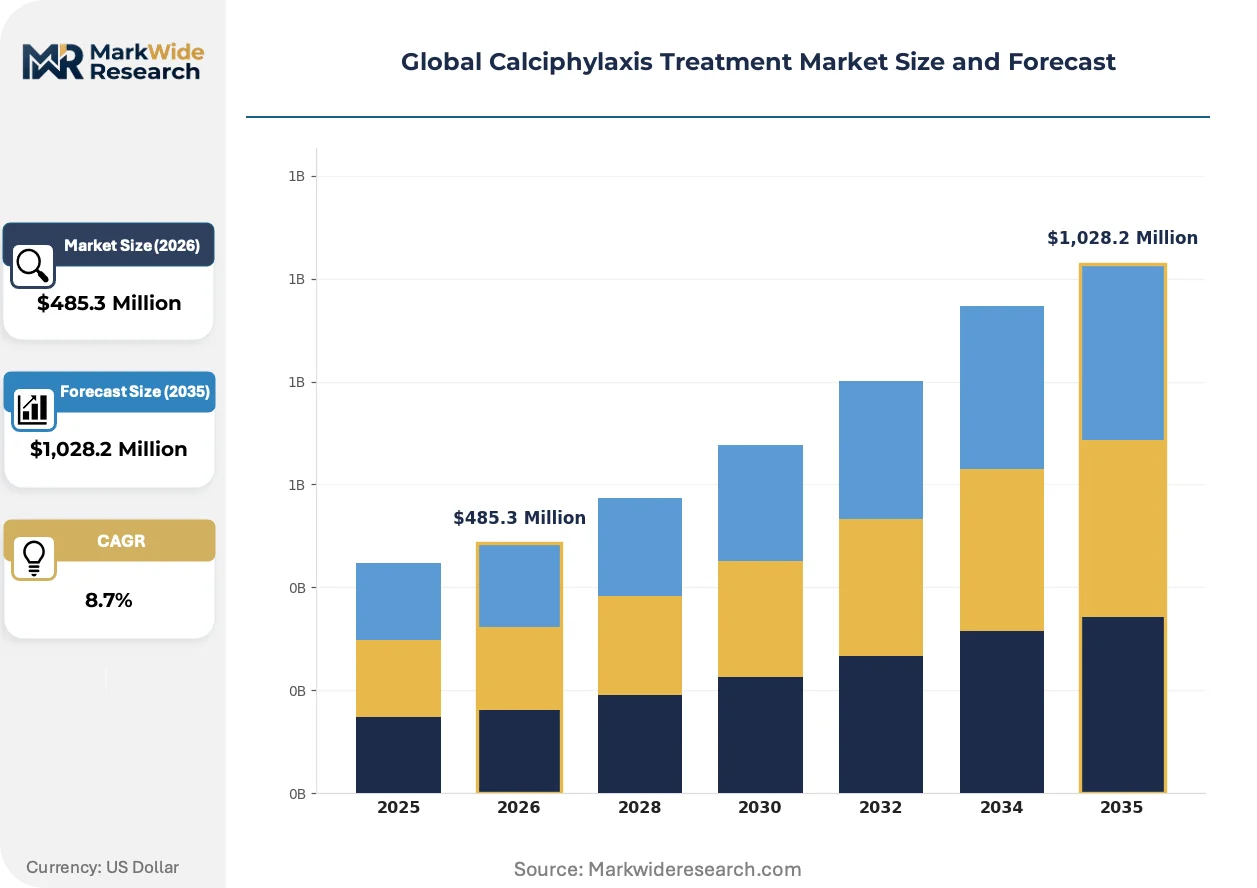
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $1,028.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phosphate Binders, Sodium Thiosulfate, Bisphosphonates, Parathyroid Hormone Modulators, Pain Management Agents Therapy Area: Chronic Kidney Disease, End-Stage Renal Disease, Diabetes-Associated, Surgical Wound Care End User: Dialysis Centers, Nephrology Clinics, Dermatology Hospitals, Pain Management Facilities Delivery Mode: Intravenous, Oral, Topical, Subcutaneous |
| Companies Covered | Amgen Inc., Smith & Nephew plc, Medtronic, 3M, Fresenius Medical Care, Bristol-Myers Squibb, Inozyme Pharma, Merck KGaA, Sun Pharmaceutical Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Calciphylaxis Treatment Market Shifts & Advancements
Novel formulation technologies and regulatory pathway optimization are actively compressing development cycles and fragmenting competitive positioning between commodity and premium supply tiers. These shifts are reconfiguring how therapies reach end-stage renal disease patients.
Specialty-grade sodium thiosulfate is bifurcating the competitive landscape between commoditized generics and high-purity hospital-grade supply. Academic medical centers and tertiary nephrology units are adopting chromatography-purified formulations at twice the rate of community dialysis centers. This technology is enabling margin capture for manufacturers with captive purification capabilities while compressing pricing power for standard-grade suppliers.
The FDA's orphan drug designation pathway is accelerating calciphylaxis therapy development through tax credits and waived user fees. This regulatory framework is concentrating sponsor investment around biologic mechanisms targeting parathyroid hormone modulation. Nephrology-focused biotechnology firms are responding by prioritizing calcimimetic candidates over phosphate binder line extensions.
Hospital purchasing coalitions are consolidating procurement authority for advanced wound care pharmaceuticals across integrated delivery networks. Group Purchasing Organizations are displacing standalone dialysis center contracting in the United States, concentrating volume among three national intermediaries. This concentration is most visible in the Southeast and Midwest regions where health system consolidation has advanced furthest.
Global Calciphylaxis Treatment Market Segmentation
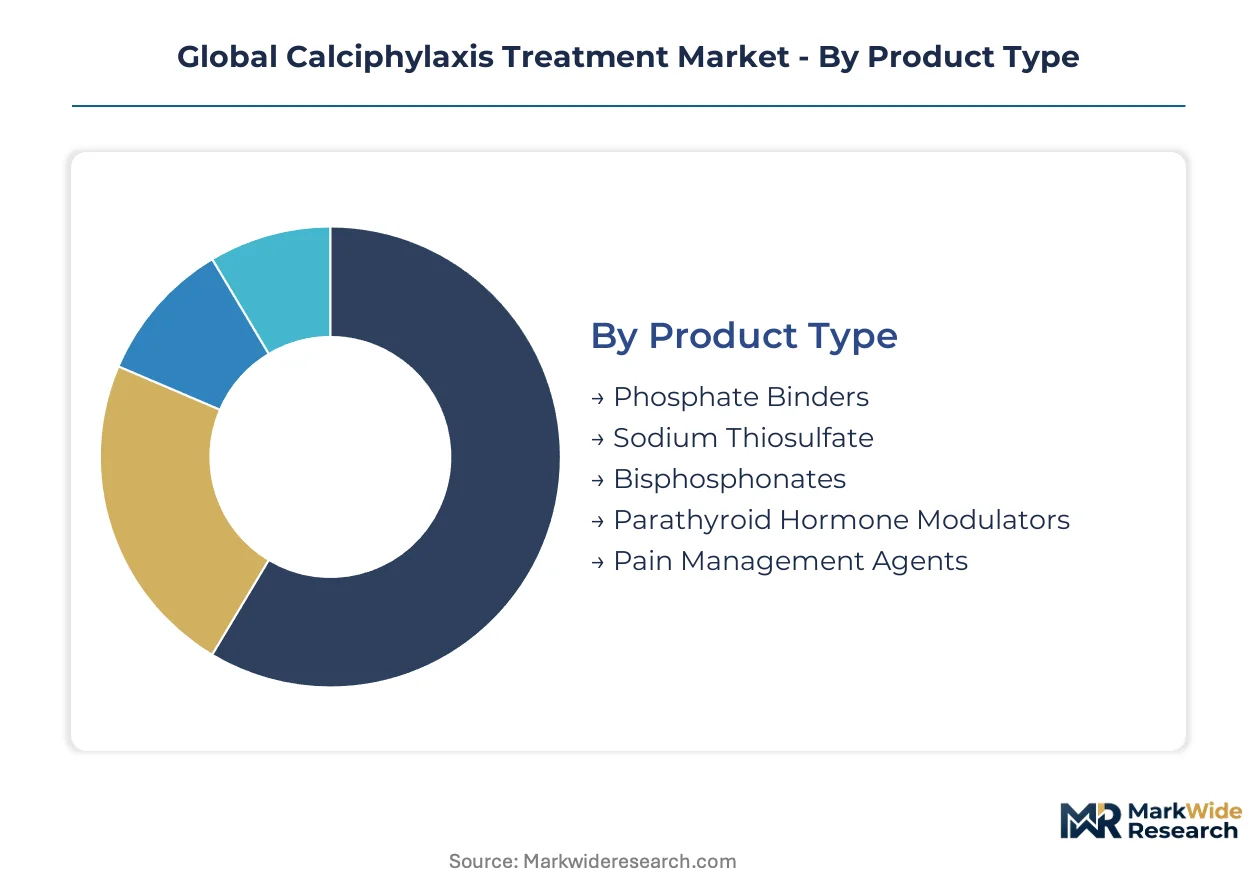
Calciphylaxis treatment segmentation reveals distinct regulatory pathways and reimbursement logics across pharmaceutical and device categories. Product type differentiation separates mature generic markets from orphan-designated biologics, while therapy area stratification isolates uremia-driven populations from emerging diabetic nephropathy cohorts.
Product Type:
FDA orphan drug incentives and EMA accelerated assessment pathways create divergent commercialization timelines across mechanism classes, privileging novel biologics over reformulated small molecules.
- Phosphate Binders:Sevelamer carbonate and lanthanum carbonate formulations constitute the established revenue base in dialysis-dependent calciphylaxis. Demand concentrates in United States integrated delivery networks where bundled reimbursement favors cost-controlled mineral management protocols.
- Sodium Thiosulfate:Chelating agent forming soluble calcium thiosulfate complexes to dissolve vascular calcifications. Academic medical centers in Germany and Switzerland are adopting chromatography-purified hospital-grade supply at twice the rate of community dialysis facilities, driven by batch consistency requirements for severe necrotic cases.
- Bisphosphonates:Off-label etidronate and pamidronate use persists in tertiary wound care units despite limited vascular calcification specificity.
- Parathyroid Hormone Modulators:Calcimimetic candidates targeting calcium-sensing receptor modulation address uremia-driven secondary hyperparathyroidism with improved specificity over phosphate binders.
- Pain Management Agents:Opioid-sparing multimodal protocols incorporating gabapentinoids and ketamine infusions manage calciphylaxis-associated neuropathic pain in specialized wound care units.
Established volume favors phosphate binders; emerging adoption favors parathyroid hormone modulators.
Therapy Area:
Patient pool stratification follows renal dysfunction severity and comorbidity profiles, with mineral dysregulation mechanisms determining therapy selection and dosing intensity.
- Chronic Kidney Disease:Pre-dialysis calciphylaxis cases in Stages 4-5 CKD require proactive mineral management before uremic crisis. United States nephrology clinics are expanding screening protocols in diabetic populations, where early vascular calcification detection drives preventive sodium thiosulfate initiation.
- End-Stage Renal Disease:Dialysis-dependent patients represent the largest addressable population with highest lesion burden and mortality risk. Demand concentrates in Fresenius Medical Care and DaVita captive networks across the United States, where internalized pharmaceutical procurement creates dedicated distribution channels.
- Diabetes-Associated:Diabetic nephropathy prevalence is expanding the fastest-growing calciphylaxis subsegment as prolonged hyperglycemia accelerates vascular calcification independent of uremic status.
- Surgical Wound Care:Post-operative calciphylaxis in cardiac and vascular surgery patients requires coordinated debridement and chelation protocols in tertiary hospital settings.
Revenue concentration sits with end-stage renal disease; steepest expansion trajectory belongs to diabetes-associated presentations.
End User:
Site-of-care economics and specialist workforce availability determine protocol adoption, with dialysis network integration creating captive pharmaceutical demand.
- Dialysis Centers:Fresenius Medical Care anchors calciphylaxis treatment volume through captive center networks spanning the United States, Germany, and Spain. Bundled reimbursement structures internalize pharmaceutical procurement decisions within network formularies.
- Nephrology Clinics:Independent specialist practices in the United States and France manage pre-dialysis mineral dysregulation with phosphate binder-first protocols.
- Dermatology Hospitals:Tertiary wound care units in academic medical centers handle necrotic lesion debridement and hyperbaric oxygen coordination.
- Pain Management Facilities:Specialized units in the United States and United Kingdom address refractory neuropathic pain through multimodal opioid-sparing protocols.
Procurement authority concentrates in dialysis centers; case complexity concentrates in dermatology hospitals.
Delivery Mode:
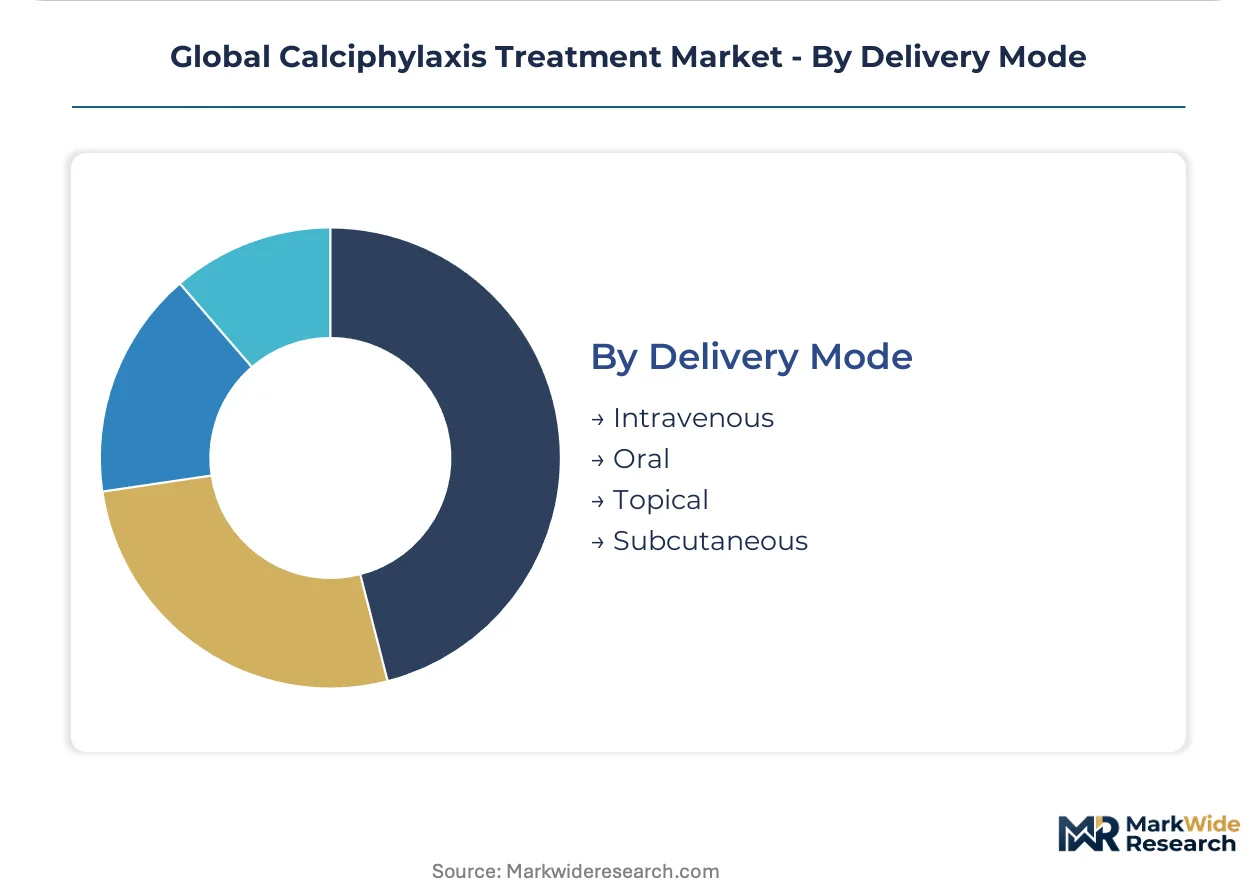
Route selection balances bioavailability requirements against site-of-care administration constraints, with intravenous formulations dominating acute intervention.
- Intravenous:Sodium thiosulfate and bisphosphonate administration requires infusion center capacity, concentrating demand in hospital outpatient departments and dialysis facilities with nursing infrastructure.
- Oral:Phosphate binders and calcimimetics enable patient self-administration, supporting adherence in pre-dialysis chronic kidney disease populations.
- Topical:Wound bed preparation agents and analgesic formulations address localized lesion management in home care settings.
- Subcutaneous:Emerging calcimimetic delivery systems target outpatient administration convenience for parathyroid hormone modulation therapy.
Administration burden favors intravenous in acute settings; patient convenience favors oral in chronic management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for high-purity sodium thiosulfate concentrates in Germany and Switzerland, while the United States runs a structural deficit in parathyroid hormone modulators. Dialysis network expansion and orphan drug incentives reshape regional competitive positioning.
United States
Fresenius Medical Care and DaVita captive networks internalize pharmaceutical procurement across 7,000-plus dialysis facilities. The FDA's orphan drug designation grants seven-year market exclusivity and tax credits for calciphylaxis therapy developers. The Southeast and Midwest regions show fastest dialysis center densification, concentrating demand for advanced wound care protocols in Atlanta and Chicago metropolitan clusters.
Germany
Specialty chemical manufacturers in Bavaria and North Rhine-Westphalia anchor European supply for chromatography-purified sodium thiosulfate. The EMA's accelerated assessment pathway offers 150-day review timelines for rare disease therapies. Heidelberg and Berlin academic medical centers drive adoption of hospital-grade chelation formulations at twice the rate of community dialysis facilities.
Switzerland
Basel-based pharmaceutical R&D infrastructure supports calcimimetic development targeting calcium-sensing receptor modulation. Swissmedic maintains alignment with EMA centralized procedures while offering national scientific advice for orphan indications. The Zurich-Geneva corridor concentrates nephrology clinical trial sites evaluating novel parathyroid hormone modulators.
Japan
PMDA's sakigake designation system accelerates priority review for calciphylaxis therapies addressing unmet needs in dialysis populations. The Kanto region around Tokyo hosts the highest density of tertiary wound care units managing necrotic lesion debridement. Osaka-based dialysis chains are expanding pharmaceutical formulary autonomy through vertical integration with regional distributors.
United Kingdom
NHS England's specialized commissioning framework routes complex calciphylaxis cases to designated supraregional centers in London and Manchester. The MHRA operates post-Brexit recognition procedures for EMA-approved orphan therapies with streamlined national access timelines. Scotland's dialysis network maintains distinct procurement autonomy through NHS National Services Scotland, creating pricing variation against English benchmark tariffs.
Global Calciphylaxis Treatment Market Competitive Landscape
Listed leaders compete with private specialists across R&D intensity and captive distribution channels. The market structures around three tiers: integrated dialysis-pharmaceutical conglomerates, biologic-focused innovators, and wound care device specialists. Strategic archetypes include network-integrated pharmaceutical suppliers, calcimimetic developers, and advanced wound care convergers. Dominant competitive moves encompass captive center network expansion and biologic mechanism licensing.
Among network-integrated suppliers, Fresenius Medical Care anchors the dialysis-pharmaceutical convergence archetype through captive center ownership. Amgen Inc. and Smith & Nephew plc exemplify divergent specialization paths—biologic R&D intensity versus advanced wound care adjacencies—each representing distinct margin capture strategies in the calciphylaxis treatment ecosystem.
| Leading Market Players |
|---|
| Amgen Inc. |
| Smith & Nephew plc |
| Medtronic |
| 3M |
| Fresenius Medical Care |
| Bristol-Myers Squibb |
| Inozyme Pharma |
| Merck KGaA |
| Sun Pharmaceutical Industries Ltd |
| Others |
Supply & Pricing Matrix
Chromatography-purified sodium thiosulfate displacing standard-grade formulations in academic medical centers simultaneously concentrates supply geography in Bavaria and North Rhine-Westphalia while compressing pricing power for commodity manufacturers. This substitution dynamic bifurcates procurement tiers between dialysis bundled payment networks and tertiary hospital formularies.
Pricing Analysis
Hospital purchasing coalitions anchor three-tier pricing structure across premium, standard, and economy levels in the United States calciphylaxis market. Price differentiation rests on batch consistency certification and captive dialysis network volume scale. Pricing pressure stems from Group Purchasing Organization consolidation in the Southeast and Midwest regions. Dialysis center procurement managers demonstrate highest price sensitivity; academic medical center pharmacy directors show lowest sensitivity due to severity-driven formulary autonomy.
Supply Chain Analysis
Six-month safety stock requirements for high-purity sodium thiosulfate reflect German and Swiss specialty chemical concentration. Raw material dependencies center on pharmaceutical-grade sulfur derivatives, chromatography resins, and nitrogen-purged packaging. Single-source vulnerability concentrates among three Bavarian manufacturers serving EMA-regulated markets. Distribution runs through captive Fresenius Medical Care networks and hospital purchasing coalitions rather than open wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward Group Purchasing Organizations as three national intermediaries displace standalone dialysis center contracting across United States integrated delivery networks.
For Market Incumbents: Compound captive center network density in the Southeast and Midwest to defend against Smith & Nephew plc's advanced wound care convergence strategy. Invest in chromatography purification capacity to capture hospital-grade margin pools as academic medical centers adopt specialty-grade sodium thiosulfate at twice community dialysis rates. Prioritize EMA accelerated assessment pathway positioning for parathyroid hormone modulators. For New Entrants and Emerging Players: FDA orphan drug designation fast-track offers seven-year exclusivity and tax credit leverage for calcimimetic developers targeting diabetes-associated calciphylaxis. White space concentrates in diabetic nephropathy protocols across Western Europe and the United States Kanto-equivalent wound care corridors. Go-to-market through nephrology clinic specialist detailing rather than dialysis network formulary battles. For Investors and Strategic Acquirers: The market sits at a regulatory-incentive phase that favors biologic mechanism developers over phosphate binder line extensions. Long-term viability hinges on parathyroid hormone modulation specificity and wound care device-pharmaceutical protocol integration. Acquisition targets should demonstrate EMA scientific advice engagement or FDA Breakthrough Therapy designation progress. Monitor reimbursement parity between dialysis bundled payments and standalone calciphylaxis therapy codes as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA pathway grants seven-year exclusivity and tax credits for calciphylaxis mechanism developers. |
| Chromatography Purification Scale-Up | Bavarian and Swiss manufacturers capture hospital-grade margin pools from academic medical center adoption. |
| Dialysis Network Vertical Integration | Fresenius Medical Care internalizes patient flow and pharmaceutical procurement across captive centers. |
| Calcimimetic Clinical Advancement | Amgen Inc. R&D intensity targets calcium-sensing receptor modulation with improved specificity. |
| Advanced Wound Care Convergence | Smith & Nephew plc integrates negative pressure therapy with chelation protocols for new reimbursement categories. |
Research Methodology
A spread of perspectives from nephrology clinic directors, dialysis center procurement managers, formulary pharmacists, and wound care nurse specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA orphan drug designations, EMA accelerated assessment pathway records, ClinicalTrials.gov calciphylaxis protocol registries, and hospital GPO contract databases. Bottom-up patient pool modeling and top-down pharmaceutical revenue triangulation anchored volume and value estimates.
Segmentation dimensions modeled include product type mechanism class, therapy area renal dysfunction severity, end-user site-of-care economics, and delivery mode administration burden across the projection horizon. CAGRs derived from patient volume expansion in dialysis-dependent populations and novel therapy adoption curves in diabetes-associated subsegments. Forecast inputs incorporated EMA 150-day review timeline probabilities and Medicare reimbursement code parity assumptions.
The analysis sits within stated boundaries; outcomes outside FDA orphan drug incentive continuity or dialysis bundled payment structure stability would require recalibration. Forecasts reflect documented assumptions regarding nephrology workforce availability and specialty chemical manufacturing capacity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Mantle Cell Lymphoma Market
Specialty Medicine
Advance Renal Cell Carcinoma Therapeutics Market
Specialty Medicine
Pseudomonas Aeruginosa Treatment Market
Specialty Medicine
Atopic Dermatitis Market
Specialty Medicine
Chromoblastomycosis Treatment Market
Specialty Medicine
Neurometabolic Disorder Market
Specialty Medicine
Autoimmune Hemolytic Anemia Therapeutics Market
Specialty Medicine
APOL1 Mediated Kidney Disease Market
Specialty Medicine
Polycystic Kidney Disease Treatment Market
Specialty Medicine
Latin America Bladder Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Cholangiocarcinoma Market
Specialty Medicine
Synovial Sarcoma Market
Specialty Medicine
Molybdenum Cofactor Deficiency Type-A (Mocod-A) Treatment Market
Specialty Medicine
Cubital Tunnel Syndrome Market
Specialty Medicine
Aarskog Syndrome Treatment Market
Specialty Medicine
Vasomotor Symptoms Market