
 Pipeline Chemical Cleaners Market | 2026-2036
Pipeline Chemical Cleaners Market Size, Share, and Industry Trends Forecast 2026-2036
Pipeline Chemical Cleaners Market Analytics
Specialty chemical distribution channels serving upstream oilfield services is reshaping how pipeline cleaners reach end users. Baker Hughes leverages its integrated energy services platform to anchor direct supply relationships with major pipeline operators across North America. Ecolab competes through its water and process chemicals division, which sustains long-term service contracts with industrial facilities requiring continuous pigging and chemical maintenance programs. Solvay differentiates via its specialty surfactant portfolio, positioning biodegradable formulations that address rising environmental compliance thresholds.
Pipeline chemical cleaners comprise formulated surfactant blends, chelating agents, and corrosion inhibitors designed to dissolve hydrocarbon deposits, mineral scale, and biological fouling from internal pipe surfaces, typically applied at concentrations between 2% and 15% by volume depending on deposit severity. Acid cleaners dominate mature oil and gas transmission networks where carbonate scale removal demands periodic high-strength intervention, while biodegradable cleaners represent the fastest-expanding product category as food industry and municipal water treatment end users adopt surfactants meeting OECD 301B ready biodegradability standards. Liquid delivery mode occupies the largest volume share due to compatibility with existing injection skids and continuous dosing systems, though gel formulations command premium positioning in vertical or low-flow pipeline configurations where wall-contact time determines cleaning efficacy.
The EPA regulates discharge of cleaning effluents under the Clean Water Act National Pollutant Discharge Elimination System, forcing reformulation of phosphorus-heavy alkaline cleaners and driving substitution toward nitrogen-based surfactant builders. OSHA Process Safety Management standards and the DOT Pipeline and Hazardous Materials Safety Administration integrity management rules mandate documented chemical compatibility and corrosion testing before any cleaner enters service on regulated pipelines. Stakeholders must monitor evolving state-level restrictions on per- and polyfluoroalkyl substances, as these compounds appear in some legacy corrosion inhibitor packages and face accelerating phase-out timelines across multiple jurisdictions.
Market Dynamics
The pipeline chemical cleaners sector is being fundamentally restructured by the EPA's phasedown of phosphorus-based surfactants under Clean Water Act discharge limits, which is forcing wholesale reformulation of alkaline cleaner chemistries and reshaping supplier R&D priorities across North America.
Growth Catalysts
- Biodegradable surfactant mandates:OECD 301B ready biodegradability standards are now required for municipal water treatment procurement specifications, opening substitution opportunities for nitrogen-based builder chemistries.
- Pipeline integrity management rules:DOT Pipeline and Hazardous Materials Safety Administration regulations mandate documented chemical compatibility testing, creating recurring demand for certified cleaner formulations.
- United States Gulf Coast corridor:Concentrated pipeline density from Houston to New Orleans sustains continuous maintenance cycles and bulk chemical procurement volumes from regional terminals.
Market Restraints
- Feedstock volatility:Ethylene oxide and fatty alcohol prices fluctuate with crude oil indices, compressing margins on nonionic surfactant production.
- Specialty chemical supplier concentration:Three integrated producers control over 60 percent of North American chelating agent capacity, creating supply vulnerability during force majeure events.
- Per- and polyfluoroalkyl substance legacy liability:State-level restrictions on PFAS compounds in corrosion inhibitor packages force costly reformulation of established product lines.
Strategic Opportunities
- Food processing sanitation crossover:USDA-authorized cleaner chemistries can pivot from industrial pipelines to food-grade equipment, leveraging existing surfactant manufacturing assets.
- Carbon capture pipeline networks:CO2 transport infrastructure requires specialized scale inhibitors for supercritical fluid conditions, an emerging specification not served by incumbent product portfolios.
- Direct-to-operator digital platforms:E-procurement channels are bypassing traditional distribution layers, allowing formulators to capture margin previously allocated to chemical distributors.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in surfactant-polymer compatibility for high-salinity brine environments commands premium compensation and extends product development timelines.
- Corrosion test protocol standardization:Absence of unified ASTM methods for cleaner-pipeline material interaction forces redundant testing across each operator qualification process.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipeline Chemical Cleaners Market |
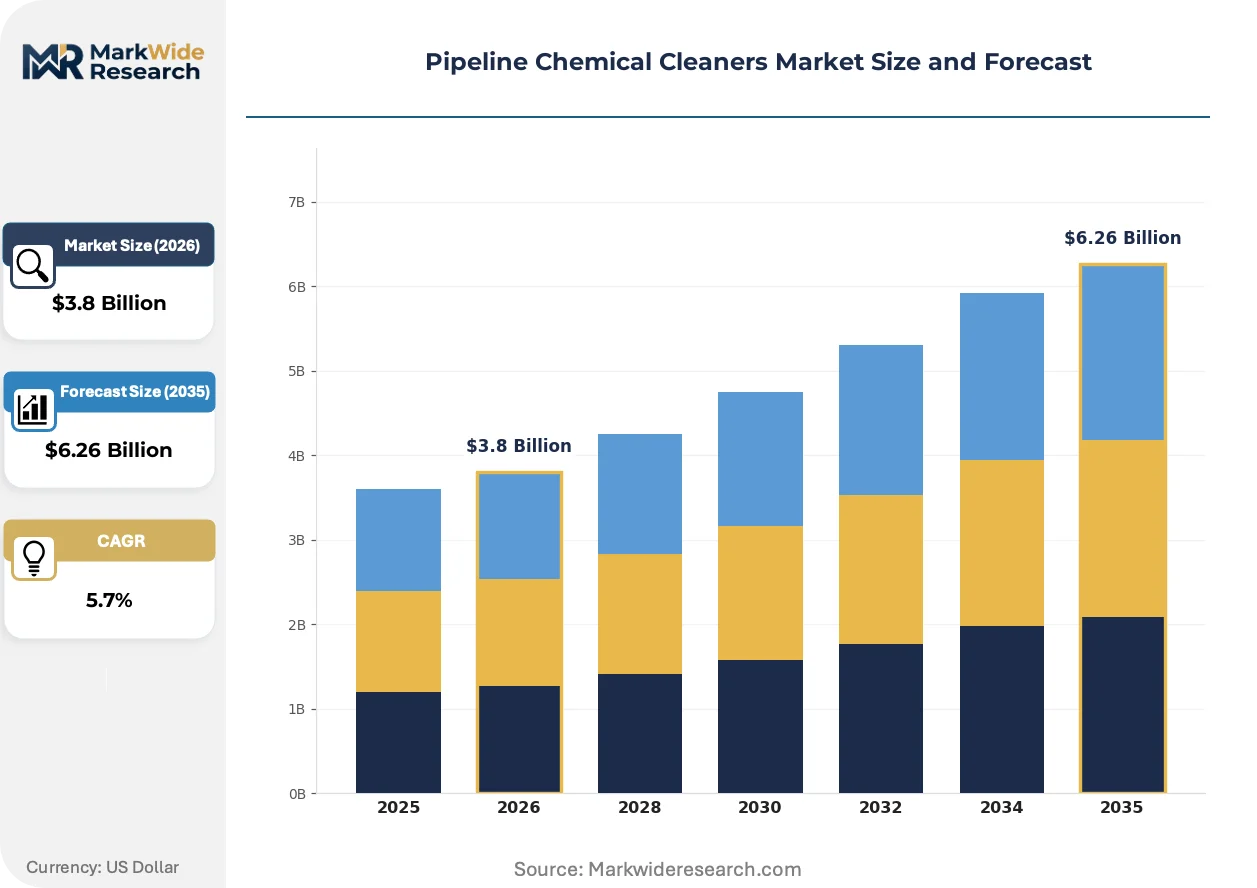
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvents, Acid Cleaners, Alkaline Cleaners, Biodegradable Cleaners Application: Oil & Gas, Water Treatment, Chemical Processing, Food Industry Delivery Mode: Liquid, Powder, Gel, Spray End User: Industrial Facilities, Municipalities, Manufacturing Plants, Oil Refineries |
| Companies Covered | Ecolab, Baker Hughes, BASF SE, Solvay, Henkel AG & Co. KGaA, Dow, Chemtex Speciality Limited, SUEZ Water Technologies & Solutions, Clariant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipeline Chemical Cleaners Market Evolving Landscape
Enzymatic cleaning technologies are disrupting conventional surfactant-dominated formulations, while regulatory pressure on aquatic toxicity is compressing acceptable chemistries and procurement digitization is collapsing traditional distribution hierarchies.
Enzyme-enhanced pipeline cleaners utilizing lipase and protease blends are rendering obsolete high-temperature caustic treatments for biological fouling removal. Food industry pipeline operators in the Midwest are piloting these formulations at 40°C below conventional operating temperatures, reducing energy costs and effluent neutralization requirements. The technology is rendering obsolete capital-intensive hot water circulation systems that previously defined cleaning economics for viscous organic deposits.
EPA's forthcoming effluent limitation guidelines for oil and gas extraction wastewater will impose numeric limits on chemical oxygen demand and toxicity to aquatic life. Refinery operators on the Texas Gulf Coast are pre-emptively reformulating alkaline cleaners to eliminate nonylphenol ethoxylates ahead of compliance deadlines. This regulatory compression is accelerating qualification of biosurfactant alternatives derived from rhamnolipid fermentation.
Integrated service contracts bundling chemical supply with pigging operations and waste disposal are displacing transactional chemical procurement. Midstream pipeline operators in Oklahoma and Kansas are consolidating vendors under five-year performance agreements with guaranteed throughput improvement metrics. This contracting evolution is most advanced among master limited partnerships seeking to outsource non-core maintenance functions.
Pipeline Chemical Cleaners Market Segmentation
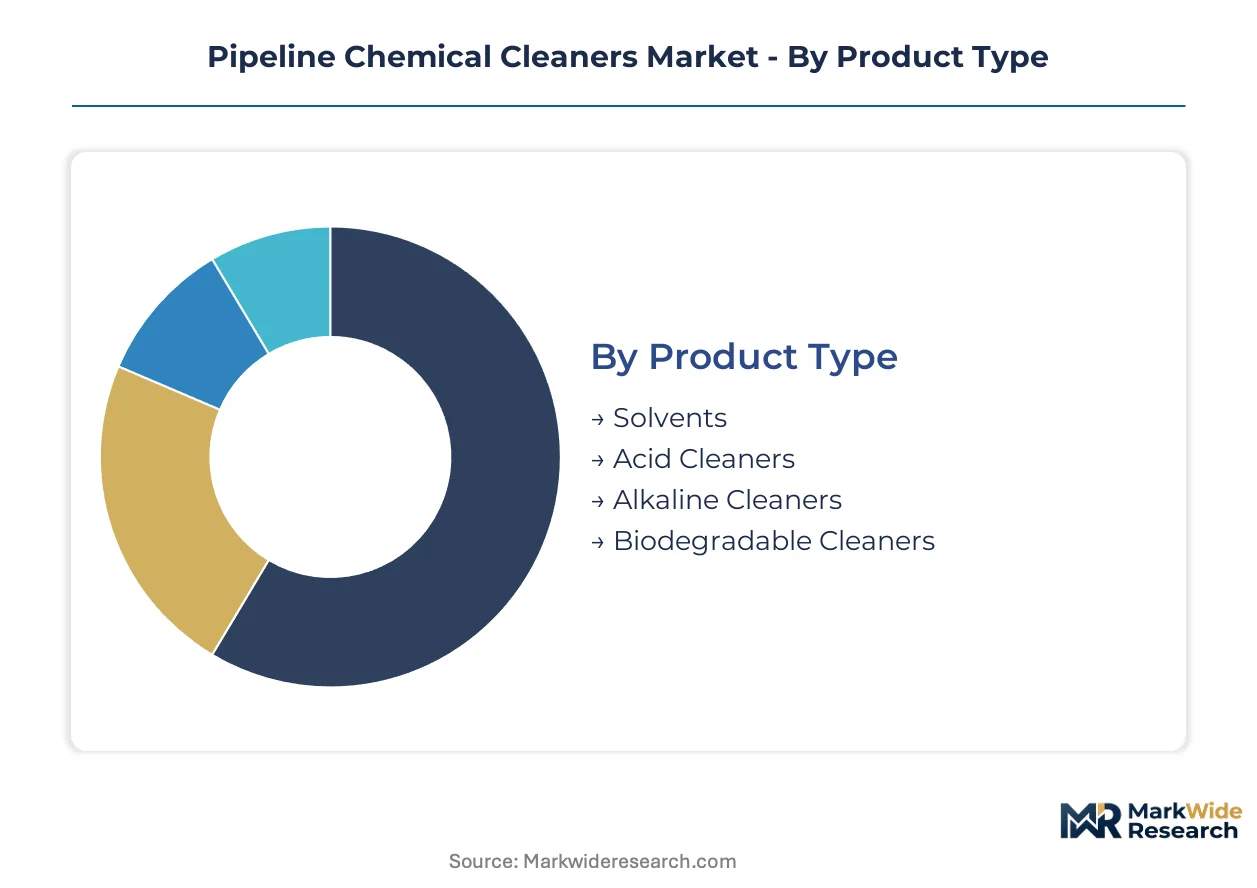
Pipeline chemical cleaners serve distinct operational regimes where product selection hinges on deposit chemistry, pipeline material compatibility, and effluent discharge constraints. Segmentation reveals how formulation requirements diverge across hydrocarbon extraction infrastructure versus food-grade sanitation networks.
Product Type:
Acid cleaners turn inventory fastest in carbonate-heavy transmission corridors, while biodegradable formulations sit longest on specification lists awaiting regulatory qualification.
- Acid Cleaners:Hydrochloric and sulfuric acid blends dissolve calcium carbonate and iron sulfide scale at concentrations reaching 15% by volume. Demand clusters along the United States Gulf Coast where mature oil and gas transmission networks require periodic high-strength intervention against mineral buildup.
- Biodegradable Cleaners:Surfactant formulations meeting OECD 301B ready biodegradability standards employ rhamnolipid biosurfactants and nitrogen-based builders. Municipal water treatment procurement in the Midwest and food industry sanitation programs are driving qualification timelines for these EPA-compliant alternatives.
- Solvents:Hydrocarbon-based and oxygenated formulations target paraffin wax and asphaltene deposits in crude oil pipelines.
- Alkaline Cleaners:Caustic soda and silicate blends remove organic fouling and grease accumulations from process piping.
Acid cleaners dominate installed base. Biodegradable cleaners are where expansion concentrates.
Application:
Cost tier separation runs deepest here, with oil and gas commanding premium formulation prices while municipal water treatment operates under strict procurement ceilings.
- Oil & Gas:Pipeline integrity management under DOT Pipeline and Hazardous Materials Safety Administration rules mandates documented chemical compatibility testing before deployment. Midstream operators from Houston to New Orleans sustain bulk procurement volumes for pigging and maintenance programs.
- Water Treatment:Municipal facilities face EPA Clean Water Act discharge limits that restrict phosphorus content and aquatic toxicity. Procurement specifications now require OECD 301B biodegradability certification, opening substitution opportunities for biosurfactant alternatives.
- Chemical Processing:Petrochemical and specialty chemical plants require cleaners compatible with exotic alloys and high-temperature process conditions.
- Food Industry:USDA-authorized formulations must pivot between industrial pipeline cleaning and equipment sanitation under FSIS oversight.
Oil and gas commands the highest revenue per gallon. Water treatment is climbing the fastest as biodegradability mandates spread.
Delivery Mode:
Volume economics favor liquid systems compatible with existing injection infrastructure, while gel and spray formats capture niche premiums.
- Liquid:Compatible with continuous dosing skids and batch treatment systems deployed across industrial facilities. The format occupies dominant volume share due to established supply chain infrastructure and operator familiarity.
- Gel:Thickened formulations adhere to vertical or low-flow pipeline walls, extending contact time for stubborn deposit removal. Premium positioning reflects specialized polymer thickener chemistry and confined-space application requirements.
- Powder:Concentrated alkalis and chelating agents ship dry for on-site reconstitution, reducing freight costs for remote locations.
- Spray:Aerosol and pump-spray formats serve external surface cleaning and localized maintenance access points.
Liquid delivery anchors procurement volumes. Gel formulations are gaining share fastest in offshore and directional drilling infrastructure.
End User:
Customer type determines contract structure, with oil refineries favoring long-term service agreements and municipalities bound by competitive bidding statutes.
- Oil Refineries:Complex fractionation unit networks and FCCU overhead systems demand cleaners tolerant of high temperatures and metallurgical diversity. EPA refinery effluent guidelines impose numeric limits on chemical oxygen demand, forcing pre-emptive reformulation of alkaline chemistries.
- Municipalities:Drinking water and wastewater treatment plants operate under state-level procurement rules and federal discharge permits. Budget constraints favor bulk concentrate purchasing with on-site dilution capabilities.
- Industrial Facilities:Manufacturing plants outside core process industries require general-purpose cleaners for utility piping and heat exchanger maintenance.
- Manufacturing Plants:Discrete manufacturing operations need periodic cleaning for cooling water and compressed air distribution systems.
Oil refineries dominate service contract value. Municipalities represent the steepest expansion trajectory as water infrastructure maintenance backlogs accumulate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Colonial Pipeline corridor from Houston to New Jersey anchors North American procurement volumes, while Rotterdam's chemical storage terminals and Singapore's bunkering hub shape Atlantic and Asia-Pacific distribution patterns respectively.
United States
DOT Pipeline and Hazardous Materials Safety Administration integrity management rules mandate documented chemical compatibility testing before cleaner deployment. EPA Clean Water Act discharge limits are forcing reformulation of phosphorus-heavy alkaline chemistries across the Gulf Coast refining cluster. The Houston-to-New Orleans corridor sustains continuous maintenance cycles and bulk chemical procurement from regional terminals.
Germany
Industrial pipeline networks serving the Rhine-Ruhr chemical complex require cleaners compatible with high-pressure process conditions. ECHA REACH regulations restrict hazardous substance content in formulations sold across the European Union. BASF's Ludwigshafen headquarters anchors regional surfactant R&D and qualification testing for adjacent industrial corridors.
China
West-East natural gas transmission pipelines and carbon capture demonstration projects create demand for scale inhibitors in supercritical CO2 conditions. MEE effluent discharge standards are tightening aquatic toxicity thresholds for cleaning effluents. The Yangtze River Delta petrochemical cluster concentrates procurement volumes for specialty surfactant formulations.
Saudi Arabia
Master Gas System expansion and associated pipeline infrastructure sustain maintenance chemical demand across the Eastern Province. The national oil company's procurement specifications increasingly require OECD 301B biodegradability certification for water treatment applications. Jubail Industrial City's integrated refining and petrochemical complexes generate concentrated demand for high-temperature compatible cleaners.
Brazil
Pre-salt oilfield pipeline networks require specialized paraffin and asphaltene deposit removal chemistries. ANVISA regulations govern cleaner formulations used in food industry applications, creating crossover qualification opportunities. The São Paulo state industrial corridor concentrates manufacturing plant demand for utility piping maintenance chemicals.
Pipeline Chemical Cleaners Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The sector exhibits moderate consolidation with integrated energy service providers and diversified chemical conglomerates occupying dominant positions alongside regional formulation specialists. Three strategic archetypes prevail: integrated energy platforms bundling chemical supply with field services, diversified chemical majors leveraging surfactant manufacturing scale, and regional specialists targeting niche application certifications. Competitive dynamics center on long-term service contract capture and biodegradability certification speed.
Within the integrated platform tier, Baker Hughes and Ecolab exemplify divergent approaches to operator relationships—one anchored in direct energy sector integration, the other in water and process chemicals service continuity. Solvay occupies a position representing specialty surfactant differentiation, particularly around biodegradable formulation portfolios. These three illustrate how competitive positioning increasingly separates on regulatory compliance velocity rather than baseline cleaning efficacy.
| Leading Market Players |
|---|
| Ecolab |
| Baker Hughes |
| BASF SE |
| Solvay |
| Henkel AG & Co. KGaA |
| Dow |
| Chemtex Speciality Limited |
| SUEZ Water Technologies & Solutions |
| Clariant |
| Others |
Value Network & Pricing Analysis
Ethylene oxide and fatty alcohol production clusters in the United States Gulf Coast and Northwestern Europe anchor surfactant input costs, concentrating margin capture with integrated chemical majors while fragmenting pricing power among regional formulation specialists serving midstream pipeline operators.
Pricing Analysis
Volume-discount tiering separates spot procurement for emergency maintenance from five-year performance contracts bundling chemical supply with pigging services. Price differentiation rests on OECD 301B biodegradability certification and guaranteed throughput improvement metrics. Pricing pressure stems from feedstock volatility tied to crude oil indices, compressing margins on nonionic surfactant production. Municipal water treatment facilities exhibit highest price sensitivity due to competitive bidding statutes, while oil refineries accept premium positioning for integrated service continuity.
Supply Chain Analysis
Supplier-financing facilities from integrated chemical majors extend payment terms to qualified distributors, tightening working capital constraints for independent formulators. Manufacturing concentrates in the United States, Germany, and China, with specialty surfactant R&D anchored by BASF's Ludwigshafen complex and Yangtze River Delta petrochemical clusters. The supply chain draws from ethylene oxide, fatty alcohols, and nitrogen-based builder chemistries. Single-source vulnerability runs through three integrated producers controlling North American chelating agent capacity. Distribution runs through direct-to-operator digital platforms and traditional chemical distribution channels serving upstream oilfield services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are restructuring competitive positioning as integrated service contracts displace transactional procurement, with interoperability between chemical dosing systems and pipeline integrity management software becoming the decisive ecosystem battleground.
For Market Incumbents: Build switching-cost moats through embedded sensor integration that ties cleaner performance data to operator predictive maintenance platforms. Deepen backward integration into biosurfactant fermentation capacity to secure rhamnolipid supply ahead of EPA effluent guideline deadlines. Accelerate qualification testing partnerships with DOT-certified laboratories to compress competitor entry timelines.
For New Entrants and Emerging Players: Build out carbon capture pipeline networks as white-space territory, where supercritical CO2 scale inhibitors represent unserved demand outside incumbent product portfolios. Target municipal water treatment procurement in the Midwest, where OECD 301B mandates are opening substitution windows for nitrogen-based builder chemistries. Pursue direct-to-operator digital platforms as the primary go-to-market angle, bypassing distributor margin capture.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional formulation specialists holding USDA-authorized certifications that pivot between industrial pipelines and food-grade equipment. Long-term viability favors platforms with demonstrated regulatory compliance velocity across multiple jurisdictions. Monitor state-level PFAS restriction timelines as the inflection signal for corrosion inhibitor package obsolescence and forced reformulation capex.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biosurfactant Production | Rhamnolipid fermentation capacity secures supply ahead of EPA effluent guideline enforcement. |
| Long-term Supply Agreement | Five-year performance contracts with guaranteed throughput metrics displace transactional procurement. |
| Joint Venture | Partnerships with DOT-certified laboratories compress qualification timelines for cleaner formulations. |
| Green Manufacturing Transition | Nitrogen-based builder chemistries replace phosphorus-heavy alkaline cleaners under Clean Water Act limits. |
| Geographic Expansion | Carbon capture pipeline networks in China and the United States require supercritical CO2 scale inhibitors. |
Research Methodology
A spread of perspectives from plant managers at Gulf Coast refineries, procurement leads at midstream pipeline operators, distribution channel partners, and technical R&D directors at surfactant manufacturers converged on the working assumptions. Primary interview insights were validated against secondary sources including EPA enforcement databases, DOT Pipeline and Hazardous Materials Safety Administration incident reports, customs and trade data from the American Chemistry Council, and SEC 10-K filings from integrated chemical majors. Bottom-up demand modeling across end-use segments was triangulated with top-down value chain analysis.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled by product type, application, delivery mode, and end-user contract structure. CAGRs were derived from weighted scenario analysis incorporating regulatory compliance timelines, feedstock price trajectories, and substitution elasticity between biodegradable and conventional formulations. Industry-specific inputs included pipeline integrity management rule implementation schedules and municipal procurement specification evolution.
Practitioners should monitor EPA effluent limitation guideline finalization, state-level PFAS restriction expansion, and enzymatic cleaning technology cost curves for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Instrument Detergents for Manual Cleaning Market
Cleaning Chemicals
Acid Coil Cleaner Market
Cleaning Chemicals
Latin America Detergent Market
Cleaning Chemicals
Green Floor Care Chemical Systems for Commercial Facilities Market
Cleaning Chemicals
Cleaning Nozzles Market
Cleaning Chemicals
Dry Cleaning Solvents Market
Cleaning Chemicals
Solar Component Cleaning Chemicals Market
Cleaning Chemicals
Purging Compound Market
Cleaning Chemicals
Eco-Label Certified Cleaning Chemicals for Professional Users Market
Cleaning Chemicals
Dust and Emission Control Chemicals for Ore Handling Market
Cleaning Chemicals
Brazil Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Industrial and Institutional (Iandi) Cleaning Chemicals Market
Cleaning Chemicals
Deck Brightener Market
Cleaning Chemicals
US Institutional Cleaning Detergents Market
Cleaning Chemicals
Global Metal Cleaning Chemicals Market
Cleaning Chemicals
Dust Suppressant Market