
 Brazil Industrial and Institutional Cleaning Chemicals Market | 2026-2036
Brazil Industrial and Institutional Cleaning Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Industrial and Institutional Cleaning Chemicals Market Outlook
The capability gap between integrated formulators and regional blenders is collapsing as concentrate technologies commoditize. Ecolab Brasil Ltda. leverages its captive service network to anchor hospital and food-processing accounts. Diversey Brasil competes through specialized hygiene programs for Brazilian meatpacking plants. 3M do Brasil Ltda. differentiates via aerosol delivery systems for precision manufacturing cleanrooms.
Brazil industrial and institutional cleaning chemicals encompass formulated surfactant systems, quaternary ammonium compounds, alkaline builders, and solvent blends designed for sanitization, degreasing, and surface preparation in commercial and industrial environments. These formulations typically operate within pH ranges of 2–13 depending on substrate compatibility and microbial target, with quat-based disinfectants requiring EPA-registered contact times for pathogen inactivation. Detergents occupy the largest product-type position due to universal deployment across food processing and hospitality settings, while disinfectants capture expanding margin pools as healthcare-associated infection protocols intensify. Concentrate formulations represent the fastest-growing form segment, driven by dilution-control dispensing systems that reduce freight costs and packaging waste for warehouse and school end users.
ANVISA governs biocidal efficacy claims and toxicological profiles for sanitizers deployed in Brazilian healthcare and food-contact applications, while the Ministry of Agriculture enforces residue limits for cleaning agents used in export-oriented protein processing. The country's national standards body aligns industrial chemical classifications with GHS hazard communication, compelling reformulation of legacy solvent degreasers. Stakeholders must monitor pending updates to Brazil's chemical substance inventory rules, as precursor registration requirements could restrict imported raw material flows and reshape local manufacturing economics.
Market Dynamics
ANVISA's tightened sanitization standards for food-contact surfaces are forcing wholesale reformulation across Brazil's cleaning chemicals sector, compressing legacy solvent-based portfolios while elevating quaternary ammonium and peracetic acid systems.
Growth Catalysts
- Healthcare procurement expansion:Brazilian hospital networks are expanding chemical procurement for infection control protocols, with surgical site prevention mandates driving bulk disinfectant adoption.
- ANVISA sanitization standards:Updated biocidal efficacy requirements for food-contact surfaces are compelling processors to upgrade from legacy chlorine-based systems to validated quat formulations.
- São Paulo manufacturing density:Concentrated industrial corridors in São Paulo state drive concentrate purchasing at scale, reducing per-unit freight costs for formulators serving meatpacking and beverage plants.
Market Restraints
- Petrochemical feedstock volatility:Surfactant and solvent input costs fluctuate with naphtha and ethylene pricing, squeezing blender margins on fixed-price municipal contracts.
- Import dependency for specialty quats:Brazil lacks domestic production of certain cationic biocides, exposing formulators to currency risk and extended lead times from Asian suppliers.
- GHS reclassification friction:The national standards body's alignment with GHS hazard communication is compelling reformulation of alkaline degreasers previously classified under legacy solvent categories.
Strategic Opportunities
- Northeast industrial corridor penetration:Pernambuco and Bahia manufacturing zones remain underpenetrated by integrated formulators, creating white space for concentrate distribution partnerships.
- Dual-chemistry dispensing systems:Convergence of IoT-enabled dilution control with electrochemical generation units allows on-site production of hypochlorous acid, reducing chemical transport costs for remote food processors.
- Export-oriented protein processor compliance:Ministry of Agriculture residue limit enforcement for EU and China-bound meat exports creates premium positioning for validated low-residue sanitizer programs.
Industry Challenges
- Formulation chemist scarcity:Brazil's technical institutes produce insufficient surfactant and biocide specialists, forcing formulators to recruit from Argentina or Portugal.
- ANVISA registration timelines:New active substance approvals require 18-24 month toxicological review cycles, delaying product launches for emerging pathogens.
- Legacy chlorine system integration:Food processors with sunk capital in bulk hypochlorite infrastructure resist retrofitting dispensing systems for quat compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Industrial and Institutional Cleaning Chemicals Market |
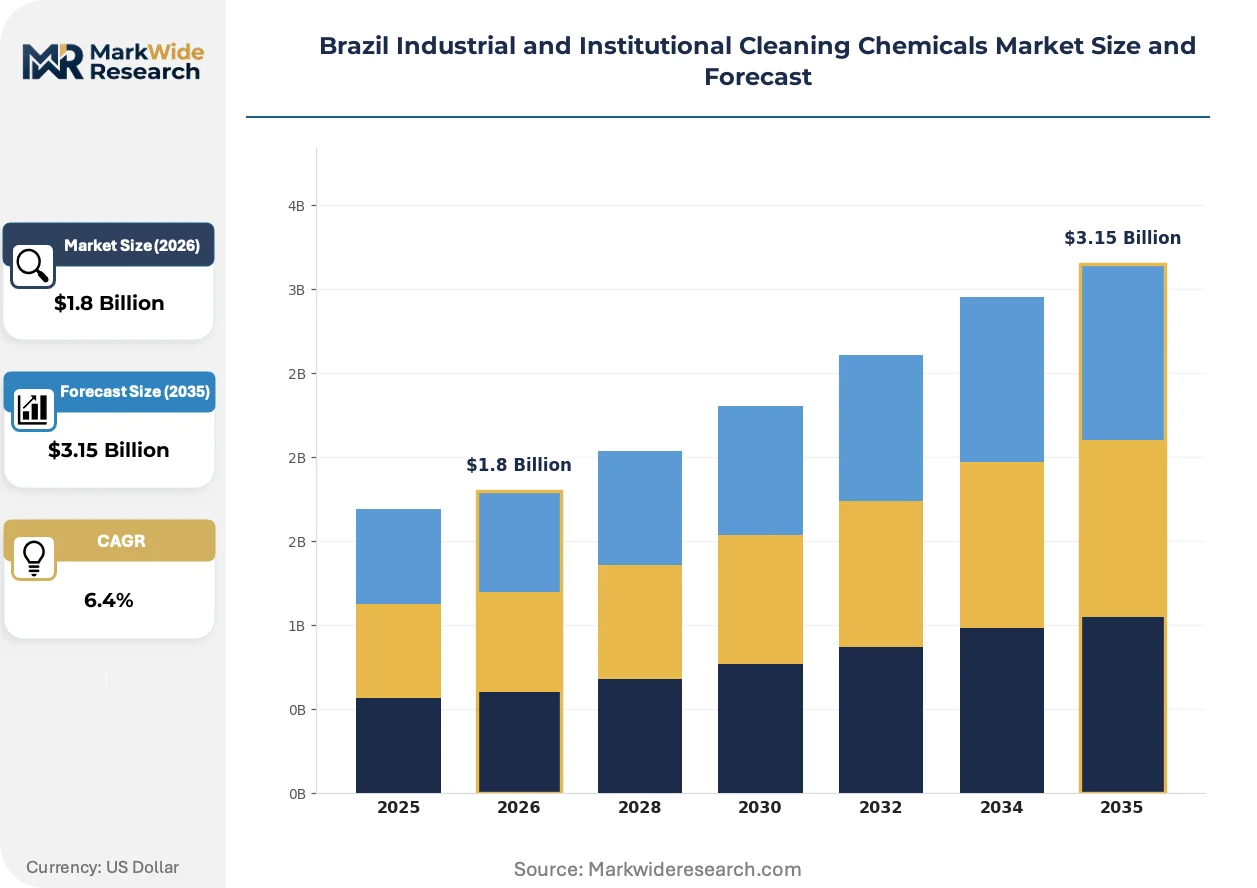
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Detergents, Disinfectants, Degreasers, Solvents Application: Food Processing, Healthcare Facilities, Hospitality, Manufacturing Form: Liquid, Powder, Aerosol, Concentrate End User: Restaurants, Hospitals, Warehouses, Schools |
| Companies Covered | Ecolab Brasil Ltda., Diversey Brasil, 3M do Brasil Ltda., Reckitt Benckiser Brasil Ltda., Procter & Gamble Professional Brasil, SC Johnson Professional Brasil, Unilever Brasil, Clorox Brasil Ltda., Bombril Professional, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Industrial and Institutional Cleaning Chemicals Market Strategic Shifts
Electrochemical generation and connected dispensing hardware are restructuring how Brazilian facilities source and consume cleaning chemistry, shifting value capture from product sales to equipment-anchored service models.
On-site electrochemical generation of hypochlorous acid and sodium hydroxide is decomposing traditional bulk chemical supply relationships. Protein processors in Mato Grosso are piloting these units to eliminate drum handling and reduce transport insurance costs. The technology is decomposing distributor margins on commodity sanitizers while transferring value to equipment manufacturers and maintenance service providers.
ANVISA's pending updates to biocidal product registration frameworks are extending compliance timelines for imported active substances. Foreign suppliers face additional toxicological data requirements for quaternary ammonium variants not previously marketed in Brazil. Food-contact surface sanitizers containing novel actives are most affected, with several multinational formulators establishing local toxicology testing partnerships to accelerate dossier preparation.
Facility managers are consolidating vendor relationships around full-service hygiene programs that bundle chemical supply with equipment maintenance and efficacy auditing. Large hospital networks in São Paulo and Rio de Janeiro are displacing transactional purchasing with multi-year contracts tying payment to infection rate metrics. This restructuring concentrates procurement authority within supply chain and infection control departments, marginalizing traditional distributor relationships in favor of direct manufacturer engagement.
Brazil Industrial and Institutional Cleaning Chemicals Market Segmentation
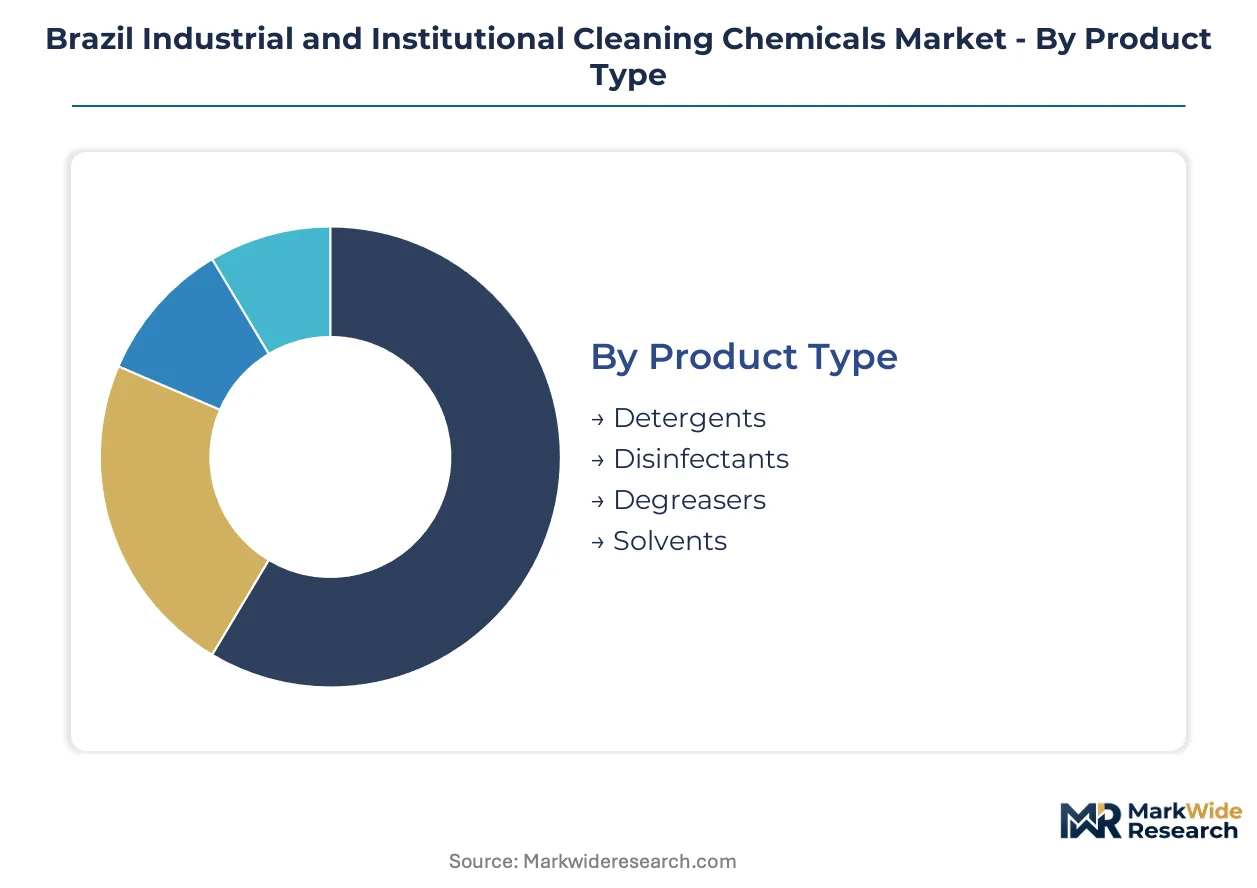
Segmentation in Brazil's industrial and institutional cleaning chemicals market reveals how procurement patterns diverge between export-oriented protein processors and domestic service establishments. Understanding these splits enables suppliers to align formulation portfolios with ANVISA compliance requirements and logistics constraints across São Paulo's industrial corridor and Northeast manufacturing zones.
Product Type:
Detergents dominate domestic consumption across food service and hospitality, while disinfectants concentrate in healthcare and export-protein channels where ANVISA biocidal validation carries premium pricing power.
- Detergents:Formulated surfactant systems with alkaline builders and chelating agents operate across pH 8–13 for substrate compatibility. São Paulo's meatpacking plants and beverage facilities deploy these universally for equipment cleaning, with bulk concentrate purchases reducing per-unit freight costs. Detergents hold the largest share; momentum sits with disinfectants.
- Disinfectants:Quaternary ammonium compounds and peracetic acid systems require EPA-registered contact times for pathogen inactivation. Brazilian hospital networks are expanding procurement for surgical site prevention mandates, while export-oriented processors upgrade from legacy chlorine to validated quat formulations for EU and China compliance.
- Degreasers:Solvent blends and alkaline builders designed for heavy soil removal in manufacturing environments face GHS reclassification pressure under Brazil's national standards body alignment.
- Solvents:Hydrocarbon and oxygenated solvent formulations for precision cleaning in electronics and aerospace applications confront toxicological profile scrutiny from ANVISA's updated biocidal frameworks.
Margin pools concentrate in disinfectants as healthcare-associated infection protocols intensify; detergents retain volume leadership through universal deployment.
Application:
Cost tier differentiation separates export-protein processors investing in validated low-residue programs from domestic establishments prioritizing operational expenditure control.
- Food Processing:Protein processors in Mato Grosso and São Paulo state drive demand for electrochemical generation-compatible chemistries and dual-chemistry dispensing systems. ANVISA's tightened food-contact surface standards compel upgrade from bulk hypochlorite infrastructure to quat-based validated systems, with Ministry of Agriculture residue limits creating premium positioning for compliant sanitizer programs.
- Healthcare Facilities:Surgical site prevention mandates and infection rate metric contracting are restructuring procurement around full-service hygiene programs. Large hospital networks in São Paulo and Rio de Janeiro displace transactional purchasing with multi-year contracts tying payment to clinical outcomes, concentrating authority within supply chain and infection control departments.
- Hospitality:Hotels and food service establishments in coastal tourism zones prioritize cost-efficient liquid detergents and surface sanitizers with rapid turnaround compatibility.
- Manufacturing:Precision manufacturing cleanrooms in automotive and electronics clusters demand aerosol delivery systems and solvent blends with defined evaporation profiles and substrate compatibility specifications.
Food processing commands the greatest chemical intensity per facility; healthcare exhibits the steepest expansion trajectory as infection control procurement professionalizes.
Form:
Volume economics favor concentrate formulations in industrial corridors where dilution-control dispensing reduces packaging waste and freight expenditure, while ready-to-use liquids dominate fragmented end-user bases lacking capital for installed equipment.
- Liquid:Ready-to-use formulations dominate restaurant and small warehouse procurement where capital constraints prevent dispensing system investment, with distribution running through traditional chemical distributors serving fragmented accounts.
- Powder:Alkaline builders and enzyme-containing formulations for heavy-duty laundry and floor cleaning in hospitality and institutional settings offer stability advantages in tropical storage conditions.
- Aerosol:Precision delivery systems for cleanroom and electronics manufacturing applications command technical specification requirements around particle generation and substrate compatibility, with 3M do Brasil Ltda. anchoring differentiation in this niche.
- Concentrate:Dilution-control dispensing systems are gaining share fastest as warehouse and school end users reduce freight costs and packaging waste. São Paulo's manufacturing density enables bulk concentrate purchasing at scale, while Northeast industrial corridors in Pernambuco and Bahia represent white space for distribution partnerships.
Liquid retains the broadest addressable base; concentrate climbs the fastest as IoT-enabled dispensing hardware penetrates mid-scale facilities.
End User:
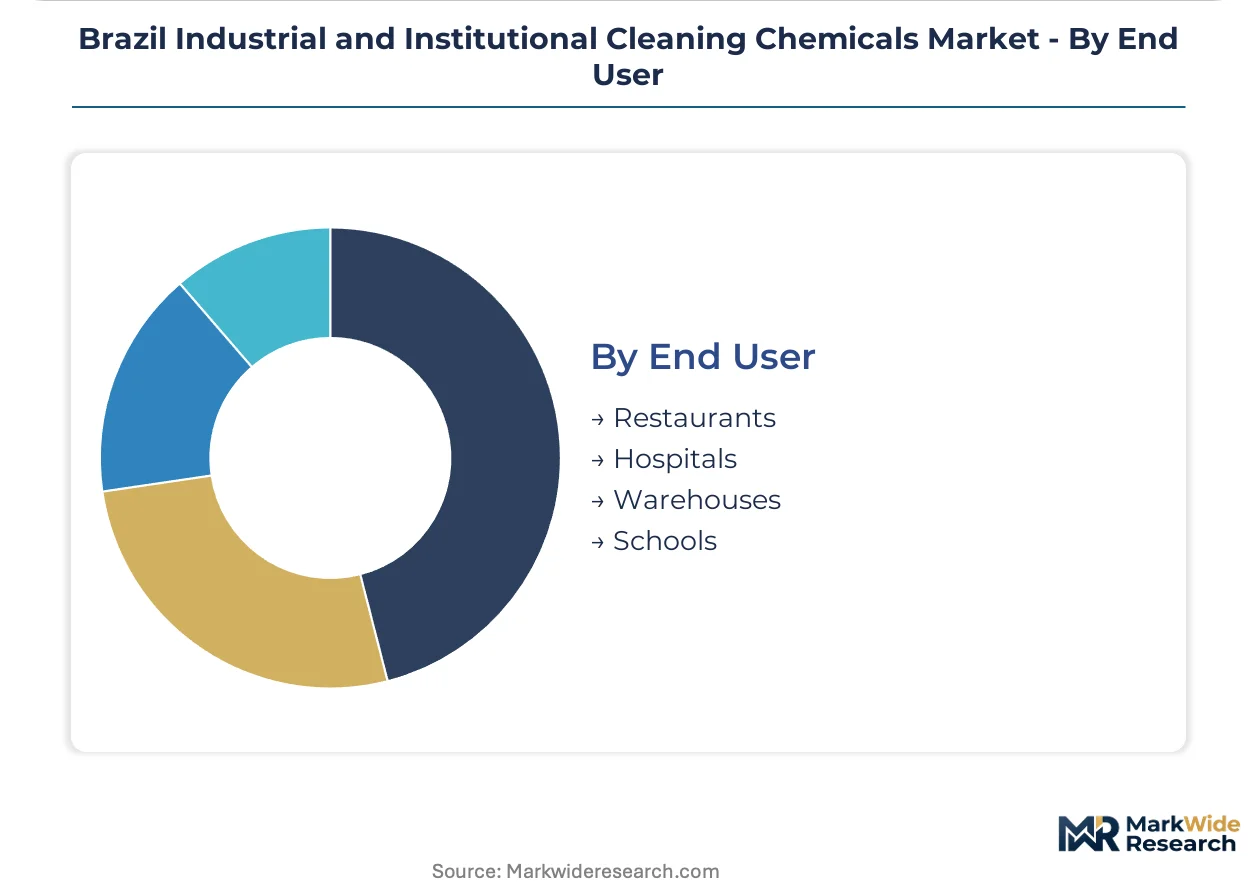
Customer type determines procurement sophistication, with hospitals and warehouses consolidating around equipment-anchored service models while restaurants and schools remain fragmented.
- Restaurants:Fragmented food service establishments prioritize cost-efficient liquid detergents and sanitizers through distributor relationships, with limited technical staff for dispensing system operation.
- Hospitals:Infection control departments are consolidating vendor relationships around full-service hygiene programs bundling chemical supply with equipment maintenance and efficacy auditing, displacing traditional distributor channels in favor of direct manufacturer engagement.
- Warehouses:Logistics facilities in São Paulo's industrial corridor are piloting electrochemical generation units to eliminate drum handling and reduce transport insurance costs, decomposing distributor margins on commodity sanitizers.
- Schools:Municipal procurement contracts for educational facilities favor concentrate formulations with dilution-control systems to manage operational expenditure within fixed budgets, though blender margins face pressure from petrochemical feedstock volatility.
Hospitals concentrate the highest value per account; warehouses are restructuring procurement most aggressively through on-site generation technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement elasticity varies sharply across Brazilian sub-regions. São Paulo's industrial buyers absorb premium pricing for validated quat systems, while Northeast municipal contracts prioritize cost control over technical specifications.
São Paulo
São Paulo state's manufacturing corridor generates the highest concentrate volumes. ANVISA's food-contact surface standards compel meatpacking and beverage plants to upgrade from bulk hypochlorite to quat-based validated systems. The state's industrial density enables bulk purchasing at scale, reducing per-unit freight costs for warehouse and school end users.
Minas Gerais
Minas Gerais dairy and coffee processing facilities drive demand for low-residue sanitizer programs. The Ministry of Agriculture enforces residue limits for EU-bound exports, creating premium positioning for compliant formulations. Belo Horizonte's food technology cluster anchors technical service relationships with integrated formulators.
Rio Grande do Sul
Rio Grande do Sul's protein export infrastructure demands electrochemical generation-compatible chemistries. Port facilities in Rio Grande pilot on-site hypochlorous acid production to eliminate drum handling and reduce transport insurance costs. The state's integration with Mercosur trade routes shapes procurement timing around seasonal export windows.
Bahia
Bahia's petrochemical complex near Camaçari supplies surfactant feedstocks to regional blenders. The state's manufacturing zones remain underpenetrated by integrated formulators, creating white space for concentrate distribution partnerships. Salvador's hospitality sector prioritizes cost-efficient liquid detergents through fragmented distributor channels.
Paraná
Paraná's soybean crushing and poultry processing facilities balance operational expenditure control with export compliance requirements. Curitiba's logistics hub consolidates chemical procurement for southern corridor warehouses. The state's municipal school contracts favor dilution-control systems to manage fixed-budget constraints.
Brazil Industrial and Institutional Cleaning Chemicals Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated multinational formulators anchor premium healthcare and food-processing accounts through captive service networks. Regional blenders compete on price for municipal and hospitality contracts with limited technical differentiation. Two dominant competitive moves define current positioning: equipment-anchored service model expansion and concentrate formulation partnerships for underpenetrated corridors.
Among multinational formulators, Ecolab Brasil Ltda., Diversey Brasil, and 3M do Brasil Ltda. represent the integrated service archetype. These entities occupy positions where direct manufacturer engagement displaces traditional distributor relationships. Ecolab Brasil Ltda. exemplifies the hospital and food-processing account anchor. Diversey Brasil sits within the specialized hygiene program tier for protein processing. 3M do Brasil Ltda. represents precision delivery system differentiation for manufacturing cleanrooms.
| Leading Market Players |
|---|
| Ecolab Brasil Ltda. |
| Diversey Brasil |
| 3M do Brasil Ltda. |
| Reckitt Benckiser Brasil Ltda. |
| Procter & Gamble Professional Brasil |
| SC Johnson Professional Brasil |
| Unilever Brasil |
| Clorox Brasil Ltda. |
| Bombril Professional |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between São Paulo meatpacking plants and integrated formulators lock in concentrate supply while fixing per-unit pricing against naphtha volatility. These arrangements transfer currency risk from processors to suppliers and establish volume commitments that justify dilution-control dispensing infrastructure.
Pricing Analysis
After-sales service revenue from equipment maintenance and efficacy auditing drives lifetime value for integrated formulators serving Brazilian hospital networks. Three-tier pricing structure across premium, standard, and economy levels separates validated quat formulations for export-protein processors from commodity chlorine blends for municipal schools. Price differentiation stems from ANVISA certification tier and geographic delivery cost to remote Mato Grosso facilities. Pricing pressure stems from petrochemical feedstock volatility squeezing blender margins on fixed-price educational contracts. Municipal procurement officers exhibit highest price sensitivity; infection control departments in tertiary hospitals least.
Supply Chain Analysis
China and India anchor global production of specialty quaternary ammonium compounds and surfactant intermediates that Brazilian formulators draw from. Domestic supply rests on petrochemical feedstocks from Bahia's Camaçari complex and imported naphtha derivatives. Single-source vulnerability concentrates in cationic biocides lacking Brazilian manufacturing. Distribution runs through regional blenders serving fragmented hospitality accounts and direct manufacturer engagement with consolidated healthcare networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA's pending biocidal registration framework extension constitutes a regulatory inflection that will compress launch timelines and reward pre-positioned toxicology capabilities.
For Market Incumbents: Shield hospital and food-processing accounts by deepening captive service networks before electrochemical generation units decompose distributor relationships. Invest in local toxicology testing partnerships to accelerate dossier preparation under ANVISA's extended review cycles. Prioritize backward integration into concentrate formulation to defend margin position against feedstock volatility.
For New Entrants and Emerging Players: Anchor in Pernambuco and Bahia manufacturing corridors where integrated formulators remain underpenetrated and concentrate distribution partnerships face limited competition. Target warehouse end users piloting IoT-enabled dilution-control systems with equipment-anchored service models that bypass traditional distributor channels. Lead with electrochemical generation compatibility to capture protein processors seeking transport cost elimination.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors formulators with captive toxicology capabilities and installed dispensing hardware bases. Long-term viability centers on service-model transitions that convert transactional chemical sales into recurring equipment-anchored revenue streams. Monitor ANVISA registration timeline announcements as the signal to watch for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Feedstocks | Captive supply from Bahia's petrochemical complex reduces currency exposure on imported naphtha derivatives. |
| Electrochemical Generation Partnership | Equipment-anchored service models transfer value from commodity sanitizer sales to maintenance revenue in Mato Grosso. |
| ANVISA Toxicology Testing Investment | Local dossier preparation accelerates product launches under extended biocidal registration frameworks. |
| Northeast Distribution Partnership | Concentrate supply agreements penetrate underpenetrated Pernambuco and Bahia manufacturing zones. |
| Dual-Chemistry Dispensing System Launch | IoT-enabled hardware captures warehouse and school end users seeking freight cost reduction. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant managers at São Paulo meatpacking facilities, procurement leads at hospital networks, distribution channel partners in Northeast corridors, and technical R&D directors at integrated formulators. Secondary validation drew from ANVISA registration databases, Ministry of Agriculture residue limit notifications, customs trade data on quaternary ammonium imports, and SEC filings of multinational parent companies. Bottom-up facility-level chemical consumption estimates triangulated against top-down market sizing from production capacity assessments.
Across the analysis window, volume and value outputs reflect segmentation modeling by product type, application sector, formulation form, and end-user procurement sophistication. CAGRs were derived from trend extrapolation of concentrate adoption rates and electrochemical generation penetration curves. Forecast inputs incorporated ANVISA compliance timeline scenarios and petrochemical feedstock price elasticity assumptions.
Material uncertainties — regulatory timeline delays, currency volatility on imported actives, and electrochemical generation technology adoption rates — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these drivers. Recalibration cycles align with material shifts in ANVISA registration frameworks and feedstock pricing regimes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Solar Component Cleaning Chemicals Market
Cleaning Chemicals
Adhesive Remover Market
Cleaning Chemicals
Document Cleaning Powder Market
Cleaning Chemicals
Surface Cleaning Products Market
Cleaning Chemicals
Chlorhexidine Gluconate (CHG) Cloth Market
Cleaning Chemicals
Europe Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Concentrated Laundry Powder Market
Cleaning Chemicals
High-Performance Descaling and Deliming Chemicals for HoReCa Equipment Market
Cleaning Chemicals
Cleaning Products Market
Cleaning Chemicals
North America Surface Treatment Chemicals Market
Cleaning Chemicals
Purging Compound Market
Cleaning Chemicals
Glass Cleaner Market
Cleaning Chemicals
Drain Opener Chemicals Market
Cleaning Chemicals
Mosquito Repellent Market
Cleaning Chemicals
Fragrance-Free Cleaning Chemicals for Sensitive Environments Market
Cleaning Chemicals
Low-VOC Cleaning Chemicals for Enclosed Workspaces Market