
 Dust and Emission Control Chemicals for Ore Handling Market | 2026-2036
Dust and Emission Control Chemicals for Ore Handling Market Size, Share, and Industry Trends Forecast 2026-2036
Dust and Emission Control Chemicals for Ore Handling Market Insights
Multi-source procurement among mineral processors is consolidating around integrated chemical suppliers with on-site technical service capabilities. Ecolab leverages its global water treatment infrastructure to bundle dust control with process chemistry programs. Solenis anchors its position through specialized polymer formulations for high-velocity ore transfer applications. Borregaard differentiates via lignin-based biopolymers that reduce synthetic surfactant loading in environmentally sensitive mine sites.
Dust and emission control chemicals for ore handling encompass surfactant blends, polymeric binders, and wetting agents formulated to suppress particulate matter during crushing, conveying, and stockpiling of metallic and non-metallic ores. These formulations typically operate at application rates of 0.5–2.0 liters per square meter, forming temporary crusts or reducing surface tension to immobilize fines. Liquid emulsions dominate volume shipments due to compatibility with existing spray infrastructure at mine sites, while polymer concentrates capture disproportionate margin pools through extended re-application intervals. Wetting agents lead adoption at transfer points where water-only suppression proves ineffective against hydrophobic ore surfaces.
EPA NAAQS particulate standards and MEE air quality regulations in China mandate continuous opacity monitoring at ore handling facilities, directly driving demand for certified chemical suppressants. REACH registration requirements in Europe restrict certain surfactant chemistries, pushing formulators toward biodegradable polymer alternatives. Mine operators and chemical suppliers must monitor evolving tailings dust regulations and carbon accounting frameworks that increasingly scope fugitive emissions into corporate disclosure obligations.
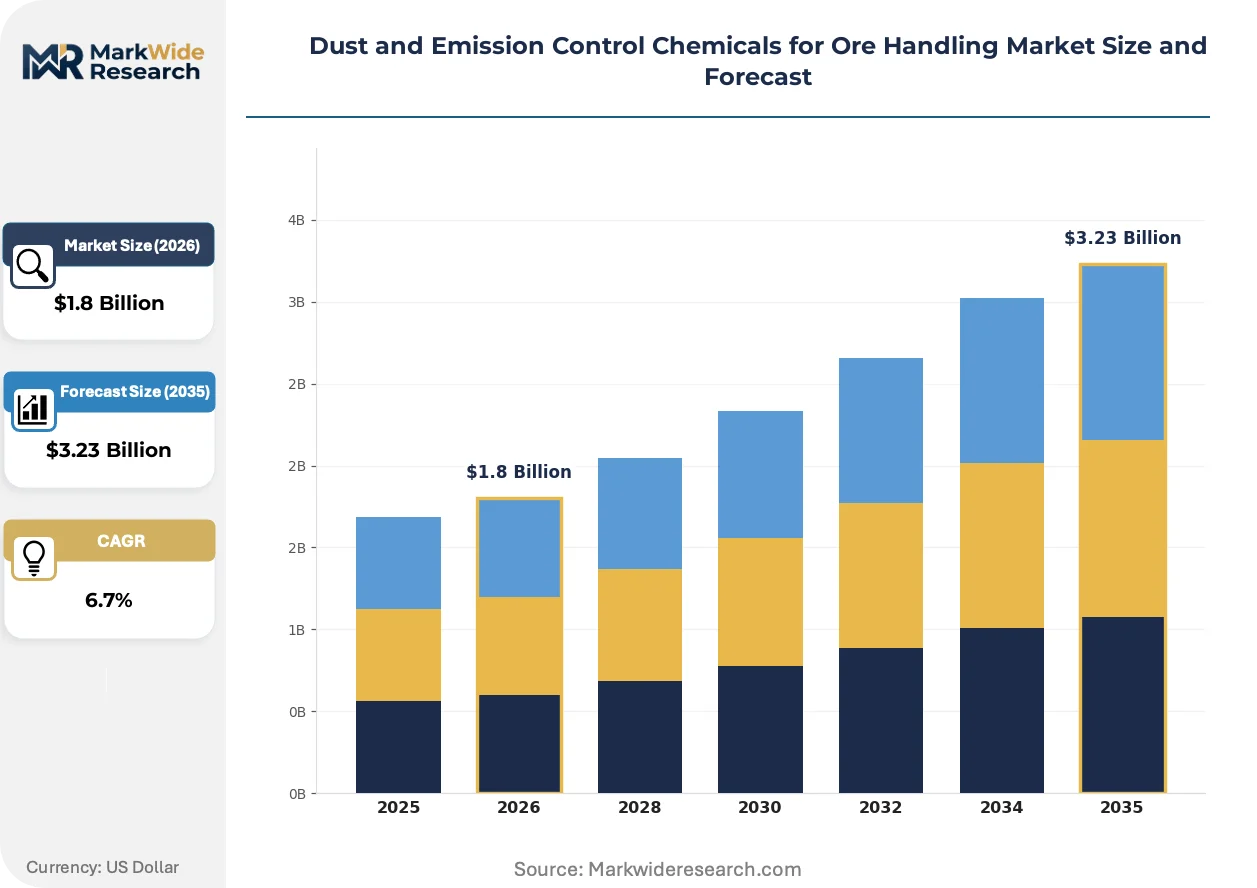
Market Dynamics
EPA NAAQS particulate standards and China's MEE air quality directives are compressing compliance timelines for fugitive dust at ore handling facilities, forcing procurement departments to requalify chemical suppressants against stricter opacity thresholds.
Growth Catalysts
- EPA NAAQS PM10/PM2.5 standards:Continuous opacity monitoring mandates at US iron ore facilities are expanding certified chemical suppressant procurement volumes.
- High-velocity ore transfer infrastructure:Polymeric binder formulations are displacing water-only suppression at crushing and conveying nodes where hydrophobic fines resist wetting.
- Chile's Atacama mining corridor:Copper extraction operations are standardizing dust control chemical programs across concentrator and smelter feedstock handling.
Market Restraints
- Petrochemical surfactant feedstock volatility:Ethylene oxide and propylene oxide price swings compress formulator margins and destabilize long-term supply contracts.
- REACH registration barriers:European chemical restrictions on nonylphenol ethoxylates and certain quaternary ammonium compounds force costly formulation reformulation.
- Water scarcity in arid mining jurisdictions:Western Australia's Pilbara and South Africa's Northern Cape face application rate constraints that limit suppressant effectiveness.
Strategic Opportunities
- Biopolymer wetting agents:Lignin-based formulations are opening procurement channels at environmentally sensitive mine sites seeking synthetic surfactant reduction.
- On-site technical service bundling:Integrated chemical suppliers are embedding dust control within broader process chemistry programs, displacing standalone product vendors.
- EU Green Deal carbon accounting:Fugitive emission disclosure requirements are scoping ore handling dust into corporate sustainability reporting, creating demand for verified suppressant performance data.
Industry Challenges
- Application equipment calibration:Mine maintenance crews lack training to optimize spray nozzle pressure and droplet sizing for varying ore moisture content and particle size distribution.
- Re-application interval variability:Climate conditions and ore chemistry create unpredictable crust degradation rates, complicating inventory planning and labor scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dust and Emission Control Chemicals for Ore Handling Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Chemical Type: Surfactants, Polymers, Wetting Agents, Flocculants, Biocides Application: Ore Crushing, Transfer Points, Storage Facilities, Conveyor Belts, Screening Units End User Industry: Mining Companies, Mineral Processing Plants, Smelting Units, Logistics Providers Form: Liquid, Powder, Granular, Emulsion, Gel |
| Companies Covered | Ecolab, Solenis, Quaker Houghton, Borregaard, Dust-A-Side, Global Road Technology, Soilworks, BASF, Clariant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dust and Emission Control Chemicals for Ore Handling Market Trends and Innovations
Formulation chemistry and service delivery models are converging around extended-performance suppressants and integrated site management, compressing the addressable market for commodity wetting agents.
Polymer concentrate emulsions with extended re-application intervals are consolidating procurement preferences among large-scale iron ore and copper operators. Major miners in Western Australia and Chile are standardizing these formulations across crushing, conveying, and stockpiling circuits. The technology is consolidating margin pools toward suppliers with on-site blending and technical service infrastructure.
China's MEE air quality directives now mandate real-time particulate monitoring at ore handling facilities with automatic suppression system activation. Industrial consequence includes forced capital expenditure on sensor networks and integrated chemical injection systems. Underground and open-pit copper mines in the Atacama Desert are responding with centralized procurement of certified suppressant formulations paired with monitoring hardware.
Buyer concentration among tier-one mining houses is compressing supplier negotiation leverage and extending payment terms. Integrated chemical service contracts are displacing transactional product sales at major Pilbara and Northern Cape operations. This pattern is most visible in iron ore, where BHP, Rio Tinto, and Fortescue Metals Group have consolidated dust control chemical procurement under multi-year framework agreements with technical performance guarantees.
Dust and Emission Control Chemicals for Ore Handling Market Segmentation
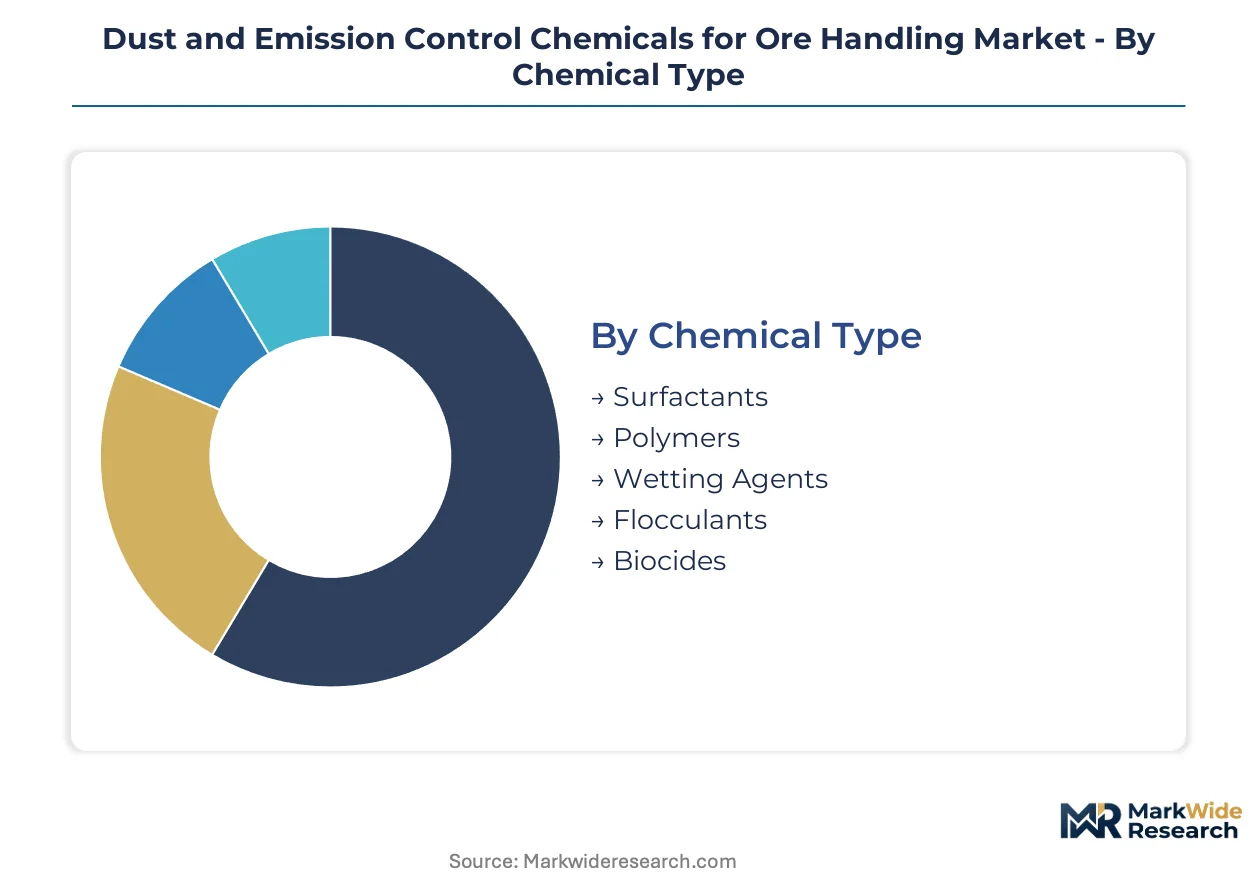
Dust and emission control chemicals for ore handling segment across formulation chemistry, application node, and physical form. Procurement patterns diverge sharply between standalone wetting agents for transfer points and integrated polymer programs spanning entire material handling circuits.
Chemical Type:
Surfactant formulations operate as standalone spray applications, while polymer and biopolymer chemistries embed within multi-service technical contracts.
- Surfactants:Synthetic and bio-based surface-active agents reduce water surface tension to penetrate hydrophobic ore fines. Demand concentrates at iron ore crushing nodes in Western Australia's Pilbara, where water-only suppression fails against silica-rich dust.
- Polymers:Acrylic and vinyl acetate copolymer emulsions form durable surface crusts with extended re-application intervals. Procurement is consolidating under framework agreements at Chilean copper concentrators, where high-velocity conveying demands crust integrity against wind erosion.
- Wetting Agents:Specialized formulations for extreme hydrophobicity in bituminous coal and graphite handling.
- Flocculants:Anionic and cationic polyelectrolytes for tailings dust stabilization in dry-stack facilities.
- Biocides:Algaecide and bactericide additives preventing biological degradation of organic-based suppressant formulations in tropical mining jurisdictions.
Volume placements concentrate in surfactants; the faster expansion belongs to polymers.
Application:
Application node determines spray infrastructure requirements, with crushing and transfer point installations commanding premium formulation specifications.
- Ore Crushing:Primary and secondary crushing generates the highest particulate velocities, demanding polymer binders with rapid film formation. Installations at South Africa's Northern Cape manganese operations specify certified suppressants meeting MEE opacity trigger thresholds.
- Transfer Points:Conveyor discharge and loading points require wetting agents compatible with automated spray bar systems. Procurement at Brazilian iron ore ports favors low-foaming surfactants that avoid sensor interference in real-time monitoring networks.
- Storage Facilities:Long-duration stockpile crusting applications favor slow-release polymer concentrates.
- Conveyor Belts:Continuous spray suppression along belt runs, typically water-augmented with minimal chemical loading.
- Screening Units:Vibration-agitated fines requiring misting systems with droplet size optimization.
Revenue gravity sits with ore crushing; transfer point applications are climbing the fastest as monitoring mandates spread.
End User Industry:
Customer scale determines contract structure, with tier-one mining houses consolidating procurement and mineral processors accepting transactional supply.
- Mining Companies:Integrated owners of extraction and handling infrastructure, standardizing suppressant programs across multiple ore types. BHP and Rio Tinto in Western Australia embed dust control within site-wide chemical service agreements with technical performance guarantees.
- Mineral Processing Plants:Standalone concentrator and beneficiation facilities with discrete procurement authority.
- Smelting Units:Pyrometallurgical facilities managing fugitive emissions from concentrate receiving and feed preparation.
- Logistics Providers:Third-party rail and port operators handling multiple commodity streams with variable suppressant requirements.
Contract value concentrates in mining companies; mineral processing plants show the steepest expansion trajectory as independent concentrator construction accelerates.
Form:
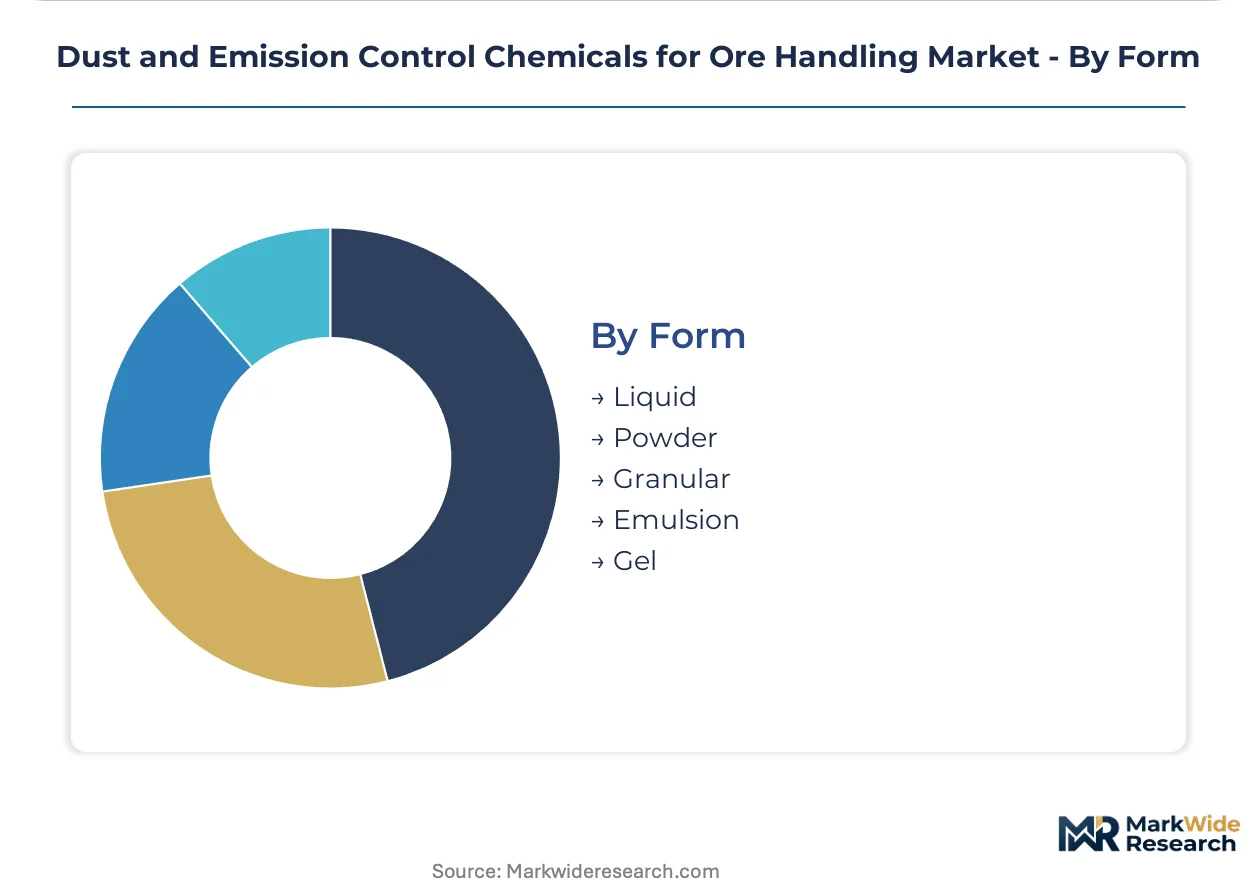
Physical form dictates logistics economics and on-site handling infrastructure, with liquid emulsions dominating volume and polymer concentrates capturing margin.
- Liquid:Ready-to-use aqueous solutions compatible with existing mine spray infrastructure. Shipments dominate volume in Western Australia's Pilbara due to compatibility with automated truck and rail car spray systems.
- Emulsion:Oil-in-water or water-in-oil concentrates requiring dilution, offering extended stability and re-application intervals. Adoption is accelerating at Chilean copper operations seeking reduced labor exposure in remote Atacama sites.
- Powder:Dry polymer requiring on-site dissolution systems, favored in water-scarce jurisdictions.
- Granular:Slow-release formulations for long-term stockpile stabilization.
- Gel:High-viscosity applications for extreme slope or vertical surface adhesion.
Shipment volumes concentrate in liquid form; emulsion formats are gaining share fastest through extended-interval performance claims.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pilbara iron ore deposits anchor Western Australia's dust suppressant procurement volumes. Chile's Atacama copper belt and South Africa's Northern Cape manganese corridor concentrate polymer emulsion demand.
Australia
BHP and Rio Tinto operate integrated dust control programs across Pilbara crushing and conveying infrastructure. EPA Western Australia mandates continuous opacity monitoring at ore handling facilities above specific throughput thresholds. Port Hedland and Newman mining clusters standardize polymer concentrate formulations under multi-year technical service agreements.
Chile
State-owned and private copper concentrators in the Atacama Desert face extreme aridity that degrades suppressant crust integrity. MEE-equivalent Chilean environmental standards require real-time particulate monitoring with automatic chemical injection activation. Calama and Antofagasta mining corridors drive emulsion format adoption to reduce labor exposure at remote sites.
South Africa
Northern Cape manganese and iron ore operations confront water scarcity constraints on suppressant application rates. South Africa's National Environmental Management Air Quality Act enforces fugitive dust limits at beneficiation facilities. Kathu and Hotazel mining towns concentrate demand for extended-interval polymer formulations compatible with limited water access.
United States
Mesabi Range iron ore taconite pellet plants deploy certified suppressants under EPA NAAQS PM2.5 compliance timelines. Minnesota Pollution Control Agency permits mandate opacity thresholds at crushing and transfer points. Hibbing and Virginia processing facilities represent the primary domestic demand concentration for wetting agent formulations.
China
Domestic iron ore concentrators in Hebei and Liaoning provinces expand chemical suppressant procurement under MEE air quality directives. GB standards for particulate emissions at mineral processing facilities tighten compliance windows. Tangshan and Anshan steel-feedstock handling clusters drive surfactant volume placements for high-silica ore dust suppression.
Dust and Emission Control Chemicals for Ore Handling Market Competitive Landscape
Integrated service bundling dominates the current landscape as chemical suppliers embed dust control within broader site-wide process chemistry programs. The supplier base organizes around three tiers: global water treatment conglomerates with mining-sector specialization, regional polymer formulators with technical service infrastructure, and standalone suppressant vendors serving transactional procurement channels. Capacity expansion in emulsion blending facilities and strategic partnerships with monitoring hardware providers constitute the primary competitive vectors reshaping vendor positioning.
Among global diversified suppliers, Ecolab anchors the integrated service tier through its water treatment infrastructure footprint, while Solenis occupies a specialized position in high-velocity ore transfer applications. Borregaard exemplifies the biopolymer differentiation archetype with lignin-based formulations targeting environmentally sensitive mine sites. These three companies represent distinct strategic postures: bundling, technical specialization, and sustainable chemistry substitution.
| Leading Market Players |
|---|
| Ecolab |
| Solenis |
| Quaker Houghton |
| Borregaard |
| Dust-A-Side |
| Global Road Technology |
| Soilworks |
| BASF |
| Clariant |
| Others |
Pricing and Supply Chain Analysis
Polymer concentrate emulsions with extended re-application intervals are compressing unit economics while simultaneously concentrating procurement power among integrated suppliers with on-site blending capabilities. This formulation shift rewards vendors possessing regional technical service infrastructure and penalizes standalone wetting agent merchants lacking application engineering support.
Pricing Analysis
Technical service bundling separates premium framework agreements from transactional product sales. Three-tier pricing structure across certified suppressants, standard polymer concentrates, and commodity surfactants reflects performance guarantee differentiation. Cost compression in commodity wetting agents is intensifying because buyer consolidation among Pilbara iron ore operators extends payment terms and demands volume rebates. Junior mining contractors and independent mineral processors exhibit the highest price sensitivity, while tier-one mining houses prioritize re-application interval performance over per-liter procurement costs.
Supply Chain Analysis
Regional distribution centers in Perth, Antofagasta, and Johannesburg anchor hub-and-spoke logistics for emulsion concentrates serving remote mining corridors. Manufacturing draws from ethylene oxide and propylene oxide feedstocks sourced from petrochemical complexes in the US Gulf Coast, Northwest Europe, and Northeast Asia. Single-source vulnerability for lignin-based biopolymers rests on Borregaard's Norwegian production facility. Distribution runs through integrated chemical service contracts that embed inventory management at mine sites, displacing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into polymer emulsion manufacturing represents the decisive competitive lever as formulators seek margin defense against petrochemical feedstock volatility.
For Market Incumbents: Deploy on-site technical service teams as a retention mechanism against emerging biopolymer specialists. Ecolab and Solenis should expand blending capacity in Western Australia and Chile to reduce logistics exposure. Certification investment in MEE-compliant opacity performance data protects against regional formulators undercutting on price. For New Entrants and Emerging Players: REACH registration barriers in Europe open a window for lignin-based formulations displacing synthetic surfactants in environmentally sensitive mine sites. White-space targets include South Africa's Northern Cape manganese corridor and Brazil's iron ore port handling facilities. A go-to-market angle pairing biopolymer suppressants with carbon accounting disclosure support addresses EU Green Deal procurement criteria. For Investors and Strategic Acquirers: Re-rating potential sits with regional polymer formulators possessing technical service infrastructure given consolidation pressure from global water treatment conglomerates. Long-term viability favors suppliers anchored in arid mining jurisdictions with water-scarcity-driven demand for extended-interval formulations. The signal to watch is framework agreement renewal rates at BHP and Rio Tinto operations as a proxy for incumbent lock-in effectiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Manufacturing | Captures margin pool from ethylene oxide feedstock volatility at Pilbara operations. |
| On-Site Blending Facility Expansion | Reduces logistics costs and enables real-time formulation adjustment for Atacama copper mines. |
| Biopolymer Certification Program | Opens procurement channels at EU Green Deal-compliant mine sites seeking synthetic surfactant reduction. |
| Integrated Monitoring Hardware Partnership | Links suppressant sales to MEE-mandated opacity sensor networks at Chinese concentrators. |
| Long-Term Technical Service Agreement | Locks in multi-year revenue visibility against transactional competitor pricing pressure. |
Research Methodology
Trade publications, mining sector procurement databases, and chemical industry association reports formed the secondary backbone for initial market sizing and competitive mapping. Primary interviews with mine site chemical program managers, procurement leads at tier-one mining houses, and technical sales directors at polymer formulators validated application rate assumptions and re-application interval performance claims. Bottom-up volume estimates derived from ore throughput projections across Pilbara, Atacama, and Northern Cape mining corridors were triangulated against top-down chemical spend data.
Historical trendline analysis of suppressant procurement volumes tracked against iron ore and copper production data established baseline growth coefficients. The analytical framework segmented the market by formulation chemistry, application node, and physical form across the projection horizon. CAGRs were derived from regression analysis of regulatory compliance timeline acceleration and mining capital expenditure patterns. Key forecast inputs included EPA NAAQS implementation schedules and MEE opacity monitoring mandate expansion trajectories.
The model assumes a particular technology adoption path; alternative pathways for lignin-based biopolymer substitution would alter the outlook if REACH restrictions tighten faster than anticipated. Forecasts reflect assumptions regarding mining production growth, regulatory enforcement intensity, and petrochemical feedstock price stability. Periodic stress-testing of base assumptions against actual framework agreement award data and site-level chemical consumption reports is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Global Metal Cleaning Chemicals Market
Cleaning Chemicals
Surface Cleaning Products Market
Cleaning Chemicals
Latin America Detergent Market
Cleaning Chemicals
North America Surface Treatment Chemicals Market
Cleaning Chemicals
South Africa Cleaning Products Market
Cleaning Chemicals
Global Cationic Reagent Market
Cleaning Chemicals
Green Floor Care Chemical Systems for Commercial Facilities Market
Cleaning Chemicals
Industrial Degreaser Market
Cleaning Chemicals
Home Care Chemicals Market
Cleaning Chemicals
Chlorhexidine Gluconate (CHG) Cloth Market
Cleaning Chemicals
US Institutional Cleaning Detergents Market
Cleaning Chemicals
Low-Foaming Detergent Market
Cleaning Chemicals
Cement Surface Treatment Chemicals Market
Cleaning Chemicals
Adhesive Remover Market
Cleaning Chemicals
Cleaning Chemicals for Airports and Transport Hubs Market
Cleaning Chemicals
Multifunctional Cleaner Market