
 Instrument Detergents for Manual Cleaning Market | 2026-2036
Instrument Detergents for Manual Cleaning Market Size, Share, and Industry Trends Forecast 2026-2036
Instrument Detergents for Manual Cleaning Market Foresight
Market Context
North American chemical formulators is expanding output of enzymatic and neutral detergent lines to serve surgical instrument reprocessing workflows. Ecolab leverages its healthcare division infrastructure to dominate hospital supply contracts across the United States. STERIS sustains technical leadership through integrated cleaning chemistries paired with sterilization hardware systems. Schülke & Mayr anchors European demand with specialized formulations compliant with EU medical device regulations.
Technical Definition and Segment Structure
Instrument detergents for manual cleaning comprise surfactant-based, enzyme-active, or pH-specific formulations engineered to remove bioburden, mineral deposits, and lubricants from reusable medical devices prior to sterilization, typically operating within temperature ranges of 20-45°C and specified contact times of 3-10 minutes. Enzymatic cleaners lead product type demand due to superior protein dissolution in surgical instrument pre-cleaning, while neutral detergents capture expanding share in delicate endoscope and robotic instrument workflows. Liquid form dominates hospital purchasing through dispenser-compatible packaging, though foam formulations gain traction in dental practices seeking reduced aerosol generation during manual scrubbing protocols.
Regulatory Framework and Outlook
FDA 510(k) clearance requirements for medical device reprocessing chemistries, EPA Safer Choice certification for environmental profile validation, and OSHA Bloodborne Pathogens Standard compliance collectively elevate barrier-to-entry for new detergent entrants while mandating documented efficacy against specified soil types. The EU Medical Device Regulation and REACH chemical restrictions add parallel compliance layers for multinational suppliers. Stakeholders must monitor evolving ISO 17664 guidance on cleaning validation parameters as health systems shift toward automated documentation and audit-ready compliance trails.
Market Dynamics
Consolidated health system procurement in the United States is compressing vendor margins while elevating performance validation requirements, forcing detergent formulators to embed automated documentation capabilities into their chemistry platforms.
Growth Catalysts
- FDA 510(k) reprocessing mandates:Heightened scrutiny of cleaning validation protocols compels hospitals to upgrade from commodity surfactants to enzymatic formulations with documented protein removal efficacy.
- Robotic surgery instrument proliferation:Delicate da Vinci and similar platforms require neutral pH detergents that prevent corrosion of aluminum and titanium components during manual pre-cleaning.
- EPA Safer Choice certification:Health systems pursuing sustainability targets specify chemistries meeting environmental profile standards, creating pull-through for reformulated product lines.
Market Restraints
- Enzyme raw material concentration:Protease and lipase supply chains cluster in Danish and Japanese fermentation facilities, exposing formulators to input volatility and single-source risk.
- REACH chemical restrictions:EU regulatory friction limits quaternary ammonium compound formulations, forcing European suppliers to maintain parallel product SKUs with reduced biocidal efficacy.
- Automated washer-disinfector substitution:Hospital capital investment in mechanical reprocessing systems displaces manual cleaning volumes in high-throughput surgical departments.
Strategic Opportunities
- India hospital accreditation expansion:NABH standards adoption in tier-2 and tier-3 cities creates demand for instrument detergents compliant with international reprocessing protocols.
- Point-of-use pre-cleaning foams:Novel aerosol-reduced foam formats enable dental and ambulatory surgical center workflows where sink infrastructure is limited or absent.
- ISO 17664 digital alignment:Smart dispenser systems that log contact time, temperature, and concentration automatically satisfy emerging audit-ready compliance requirements.
Industry Challenges
- Reprocessing technician certification gaps:Hospital staffing shortages in sterile processing departments elevate error rates in manual cleaning protocol execution.
- Legacy documentation system integration:Detergent tracking software must interface with hospital ERP and infection control databases, extending sales cycles and implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instrument Detergents for Manual Cleaning Market |
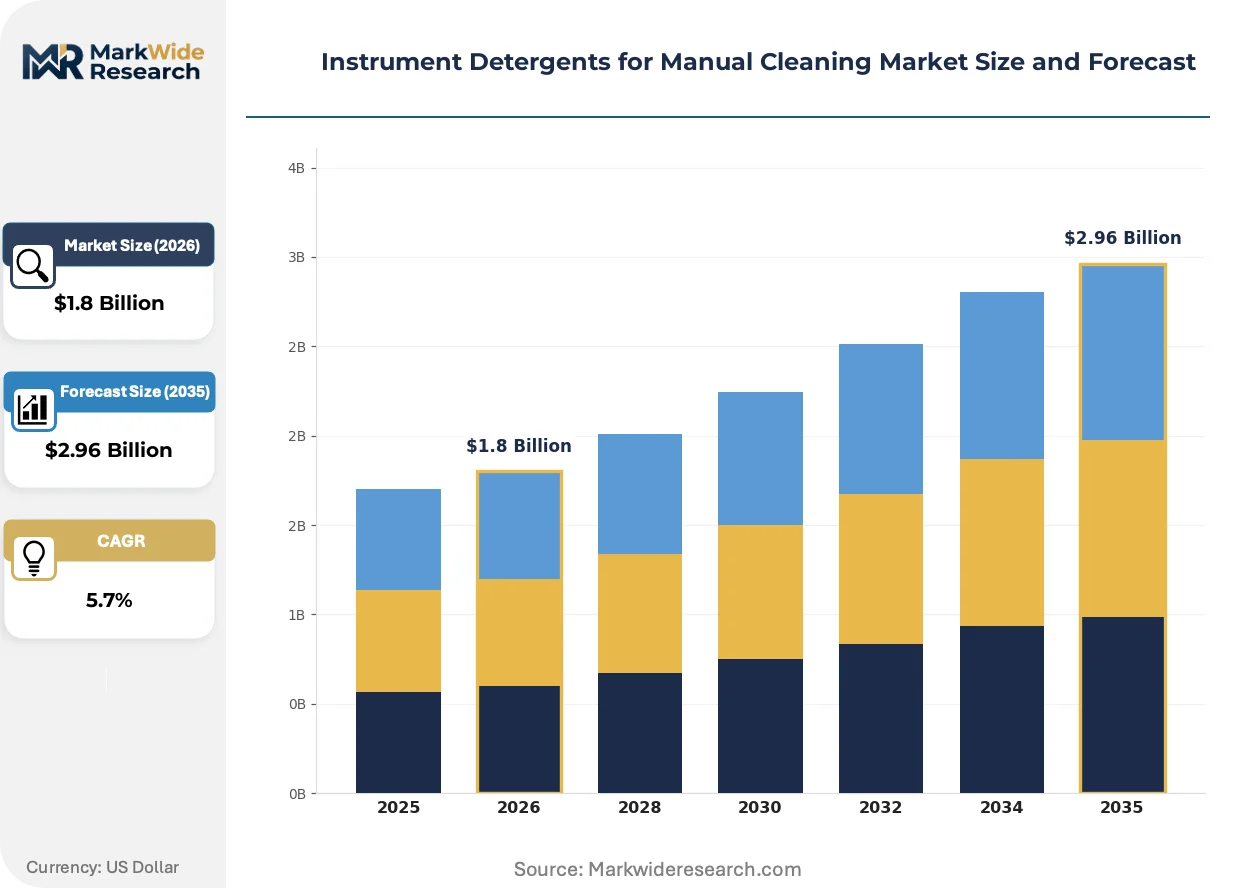
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkaline Detergents, Enzymatic Cleaners, Acidic Cleaners, Neutral Detergents End User: Hospitals, Clinics, Dental Practices, Laboratories Form: Liquid, Powder, Foam, Wipe Packaging Type: Bottles, Tubs, Sachets, Bulk Containers |
| Companies Covered | Ecolab, STERIS, Metrex Research, Ruhof, 3M, Getinge Group, Advanced Sterilization Products, Schülke & Mayr, Medline Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instrument Detergents for Manual Cleaning Market Shifts & Advancements
Enzymatic chemistry platforms are displacing conventional surfactant formulations across surgical instrument workflows, while regulatory pressure and procurement centralization reshape how cleaning efficacy is validated and purchased.
Multi-enzymatic detergent concentrates is overtaking single-enzyme products in hospital formulary decisions. These formulations combine protease, amylase, and lipase activity to address complex surgical soils in orthopedic and laparoscopic instrument sets. Academic medical centers in the United States are specifying these chemistries in 10,000-gallon bulk tank configurations. The shift is compressing demand for standalone surfactant pre-soaks and forcing commodity suppliers to reformulate or exit the acute care segment.
EPA Safer Choice and emerging state-level green procurement mandates are elevating environmental profile requirements above cost minimization in health system RFP evaluations. Formulators must now submit full chemical disclosure and aquatic toxicity data to qualify for contract tiers. Detergent manufacturers serving California and New York hospital systems are investing in surfactant biodegradability testing and packaging reduction to maintain preferred vendor status.
Consolidated procurement through group purchasing organizations is compressing supplier margins while extending contract durations. Health systems are bundling instrument detergents with sterilization wrap, biological indicators, and automated equipment into single-source agreements. This behavior is most visible in the United States, where three GPOs control purchasing for approximately 70 percent of acute care beds and are extracting performance guarantees on cleaning efficacy metrics.
Instrument Detergents for Manual Cleaning Market Segmentation
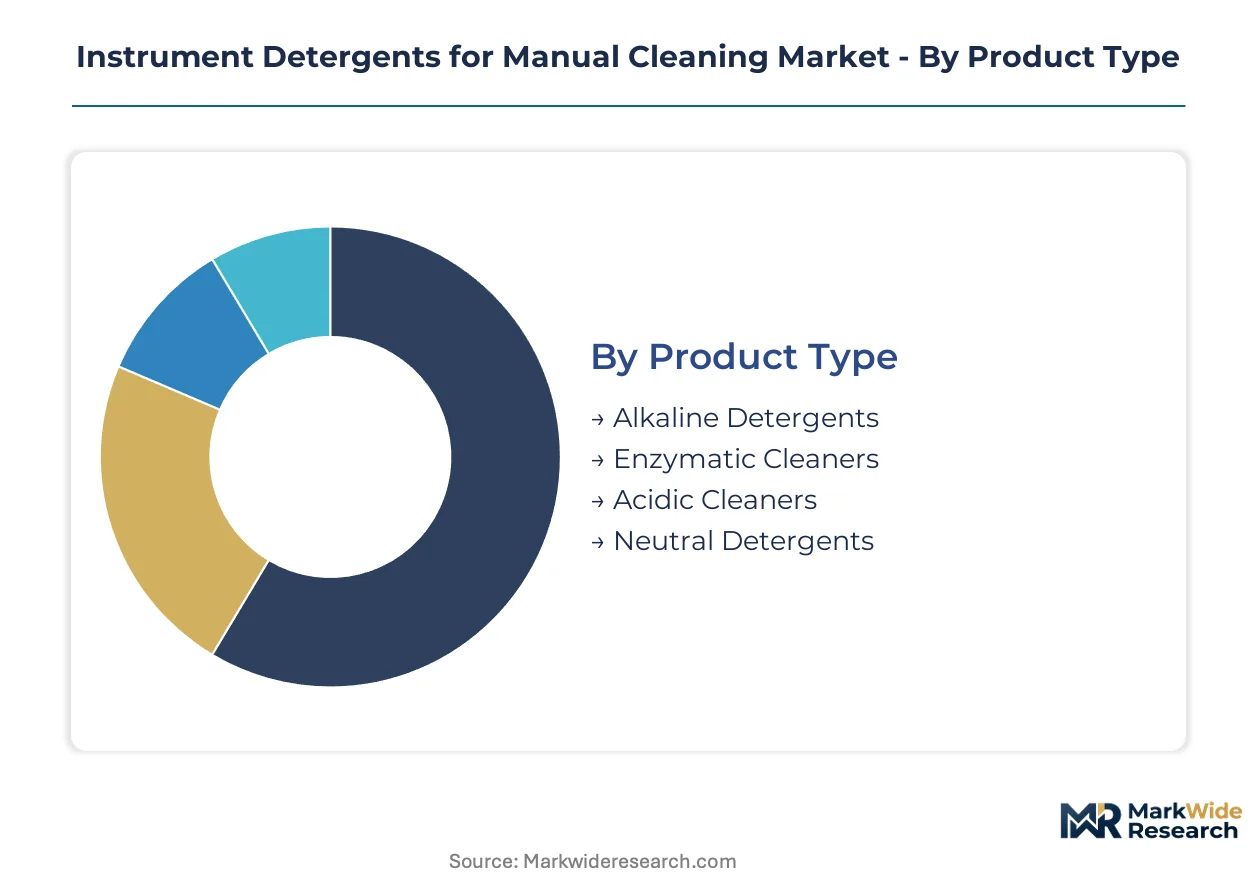
Segmentation in instrument detergents reveals how procurement priorities diverge across clinical settings. Hospital supply chains prioritize enzymatic efficacy and bulk logistics, while dental and ambulatory sites trade performance specifications for workflow convenience and space constraints.
Product Type:
Formulation chemistry determines reprocessing throughput, corrosion risk, and regulatory validation burden for sterile processing departments.
- Enzymatic Cleaners:Multi-enzyme blends containing protease, lipase, and amylase dissolve proteinaceous surgical soils at 20-45°C contact temperatures. United States academic medical centers specify these in 10,000-gallon bulk configurations for orthopedic and laparoscopic instrument sets, driven by FDA 510(k) documentation requirements for protein removal validation.
- Neutral Detergents:pH-balanced formulations between 6.5-7.5 prevent galvanic corrosion on aluminum robotic instrument components and delicate endoscope channels. Demand concentrates in da Vinci surgical system workflows where manufacturer warranties mandate neutral chemistry pre-cleaning protocols.
- Alkaline Detergents:High-pH surfactant systems excel at lipid emulsification and mineral deposit removal on stainless steel surgical trays.
- Acidic Cleaners:Low-pH formulations target calcium and rust deposits from autoclave steam systems and hard water regions.
Enzymatic Cleaners lead on scale; Neutral Detergents lead on momentum.
End User:
Facility infrastructure and patient volume shape detergent format preferences and purchasing contract structures.
- Hospitals:Central sterile processing departments with automated dispenser systems and bulk tank infrastructure drive concentrate procurement at volume tiers. United States health systems bundle detergents with sterilization equipment through GPO contracts exceeding five-year terms.
- Dental Practices:Sink-free operatories and aerosol reduction protocols favor pre-moistened wipe formats and compact foam dispensers. California and New York sustainability mandates elevate EPA Safer Choice specification rates in group dental chains.
- Clinics:Ambulatory surgical centers with mixed procedure volumes require flexible chemistry compatible across general surgery and ophthalmology instrument sets.
- Laboratories:Research and diagnostic facilities prioritize residue-free rinsing for analytical instrument compatibility.
Hospitals dominate procurement volume; Dental Practices expand most quickly.
Form:
Physical state determines dilution control, storage footprint, and occupational exposure profiles in clinical environments.
- Liquid:Pump-dispensed concentrates integrate with automated dosing systems and enable precise concentration monitoring for ISO 17664 documentation. United States hospital construction standards now specify in-wall liquid detergent plumbing for new sterile processing facilities.
- Foam:Reduced-aerosol formulations enable pre-cleaning at point-of-use where sink infrastructure is absent or restricted. Dental operatories and mobile surgical units specify foam for compliance with OSHA Bloodborne Pathogens Standard engineering controls.
- Powder:Lightweight shipping profiles reduce freight costs for international supply chains and remote facility replenishment.
- Wipe:Pre-saturated formats eliminate dilution error and support single-instrument workflows in satellite clinics.
Liquid commands installed base; Foam gains share fastest.
Packaging Type:
Container configuration influences inventory turns, waste stream composition, and dispenser compatibility in consolidated procurement environments.
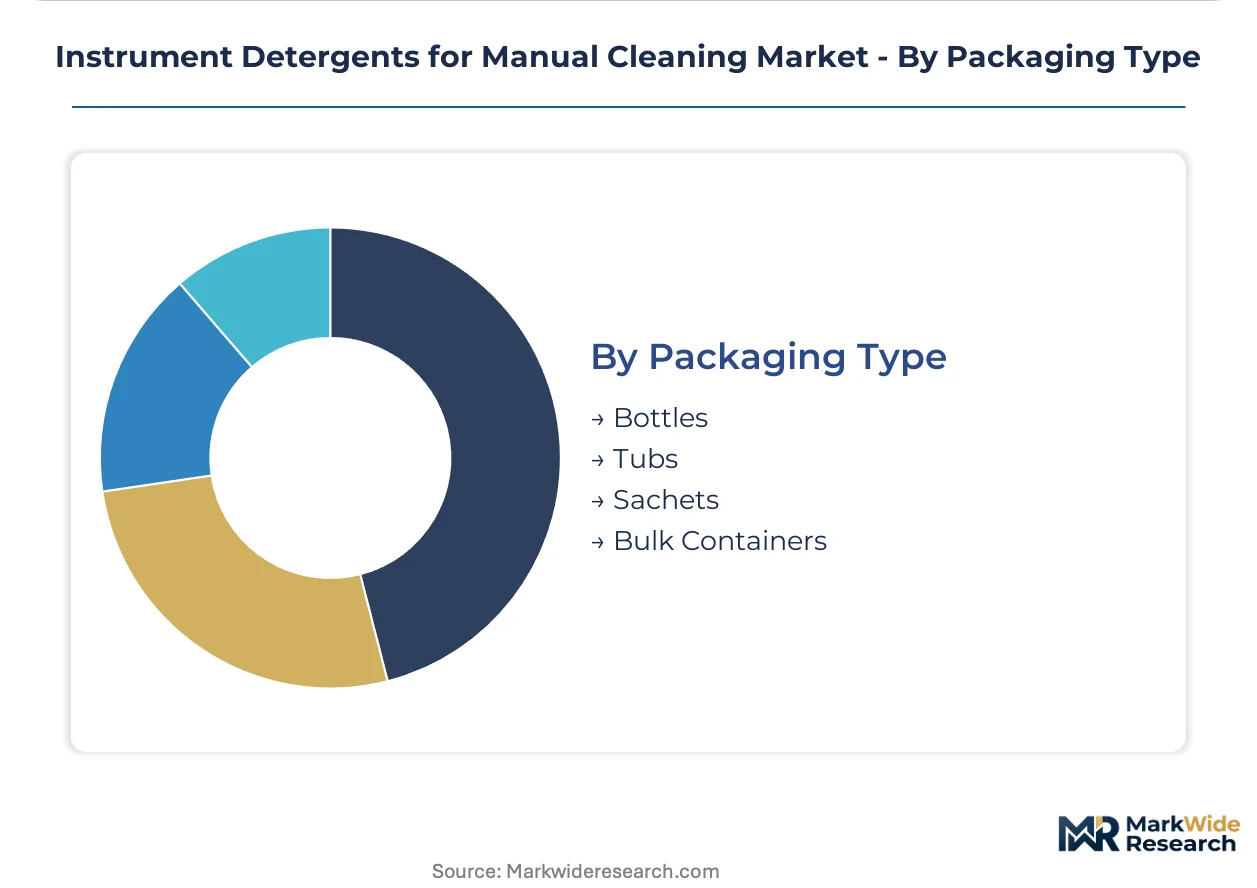
- Bulk Containers:Refillable 5-gallon carboys and 55-gallon drums minimize per-use packaging waste and support closed-loop dispenser systems. United States health systems with sustainability targets specify bulk formats for 80-plus percent of enzymatic chemistry procurement.
- Sachets:Single-dose foil packets eliminate dilution measurement error and support field deployment scenarios. Military and disaster response medical units specify sachet formats for forward surgical team resupply.
- Bottles:Standard 1-liter and 1-gallon containers serve small-to-mid volume facilities without bulk infrastructure.
- Tubs:Wide-mouth containers accommodate scoop-based powder dispensing in laboratory and research settings.
Bulk Containers anchor hospital procurement; Sachets climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in medical device reprocessing chemistries drives production migration toward jurisdictions with streamlined FDA equivalence pathways and lower EPA compliance costs. Formulators cluster where health system procurement centralization meets permissive environmental permitting regimes.
United States
Hospital GPO consolidation controls purchasing for approximately 70 percent of acute care beds, compressing vendor margins while extending contract durations beyond five years. EPA Safer Choice certification now gates preferred vendor status in California and New York health systems. Minneapolis-St. Paul anchors enzymatic detergent manufacturing, where Ecolab leverages healthcare division infrastructure to dominate supply contracts.
Germany
EU Medical Device Regulation and REACH chemical restrictions force parallel product SKUs with reduced biocidal efficacy for European markets. Schülke & Mayr anchors regional demand from its Hamburg base with specialized formulations compliant with MDR validation requirements. The Ruhr industrial corridor concentrates fermentation-derived enzyme sourcing for protease and lipase active ingredients.
China
NMPA medical device reprocessing guidelines are converging toward ISO 17664 validation parameters, elevating documentation requirements for imported chemistries. Domestic formulators in Jiangsu and Zhejiang provinces exploit cost advantages in surfactant synthesis to supply tier-2 hospital expansion. Shanghai's Pudong district hosts multinational technical centers supporting regional regulatory submissions.
India
NABH accreditation expansion in tier-2 and tier-3 cities creates demand for instrument detergents compliant with international reprocessing protocols. CDSCO import licensing requirements favor local manufacturing partnerships over direct chemical imports. Hyderabad's pharmaceutical corridor incubates contract manufacturing for enzymatic concentrates serving Southeast Asian export markets.
Japan
PMDA reprocessing validation requirements for robotic surgical instruments mandate neutral pH detergent specifications that prevent aluminum and titanium corrosion. METI industrial standards on chemical worker safety elevate packaging and dispenser system requirements. Osaka-Kobe manufacturing clusters supply concentrated enzymatic formulations to automated washer-disinfector OEMs.
Instrument Detergents for Manual Cleaning Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue EPA Safer Choice certification and point-of-use foam formats to bypass GPO contract lock-in. The vendor base stratifies across integrated healthcare chemical suppliers, standalone detergent specialists, and equipment OEMs bundling chemistries with sterilization hardware. Three archetypes dominate: multinational hygiene conglomerates with healthcare divisions, European medical device reprocessing specialists, and Asian contract manufacturers serving private-label hospital brands. Competitive moves concentrate on strategic partnerships with GPOs and portfolio diversification into pre-moistened wipe formats.
Within the integrated healthcare tier, Ecolab and STERIS exemplify contrasting approaches to market access. Ecolab, a St. Paul-based corporation, leverages its institutional and industrial divisions to cross-sell detergent contracts into existing health system relationships. STERIS represents the equipment-chemistry bundling archetype, pairing cleaning formulations with sterilization hardware systems to secure multi-year service agreements. Schülke & Mayr, a German GmbH, anchors European positioning through MDR-compliant specialization rather than scale.
| Leading Market Players |
|---|
| Ecolab |
| STERIS |
| Metrex Research |
| Ruhof |
| 3M |
| Getinge Group |
| Advanced Sterilization Products |
| Schülke & Mayr |
| Medline Industries |
| Others |
Supply & Pricing Matrix
Captive enzyme fermentation capacity in Denmark and Japan anchors both supply security and premium pricing power for multi-enzymatic concentrate suppliers serving United States hospital systems. Formulators with backward integration into protease and lipase production command contract tier advantages under consolidated GPO procurement, while outsourced surfactant blending operations face margin compression from bulk chemical spot markets.
Pricing Analysis
Distributor margins on enzymatic concentrates absorb 12-18 point spreads between bulk tank delivery and point-of-use dispensing in United States health systems. Three-tier pricing structure across FDA-validated premium, ISO-compliant standard, and private-label economy levels separates academic medical centers from ambulatory surgical centers and dental group purchasing. Cost compression in standard-tier surfactants is intensifying because Jiangsu province formulators are exporting neutral detergent bases at freight-parity rates. Dental practices exhibit highest price sensitivity due to sink-free workflow constraints, while robotic surgery service lines show lowest sensitivity given instrument warranty mandates.
Supply Chain Analysis
Reverse-logistics for bulk container refurbishment concentrates in Minneapolis-St. Paul, Hamburg, and Osaka-Kobe corridor facilities where closed-loop dispenser systems dominate hospital procurement. Enzyme active ingredient supply draws from Danish and Japanese fermentation clusters, with surfactant feedstocks sourcing from BASF Ludwigshafen and Zhejiang province petrochemical complexes. Single-source vulnerability in protease concentrate exposes formulators to batch contamination recalls. Distribution runs through healthcare-focused chemical distributors with cold-chain capabilities for temperature-sensitive enzymatic formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in instrument detergents rests on enzyme concentrate backward integration and premium-tier EPA Safer Choice certification pull-through in California and New York health systems.
For Market Incumbents: Acquire fermentation-derived enzyme capacity in Denmark or Japan to secure protease and lipase supply against batch contamination risks. Consolidate regional surfactant blending operations into Minneapolis-St. Paul and Ruhr corridor hubs to defend position against Jiangsu province cost competition. GPO contract bundling with sterilization hardware represents the critical lever for margin defense. For New Entrants and Emerging Players: Enter via point-of-use foam format specialization targeting dental operatories and mobile surgical units lacking sink infrastructure. White-space concentrates in tier-2 Indian cities pursuing NABH accreditation and California group dental chains facing aerosol reduction mandates. Direct-to-clinic subscription models bypass GPO lock-in. For Investors and Strategic Acquirers: Consolidation pressure builds where EPA Safer Choice certification gaps separate premium-tier incumbents from commodity surfactant suppliers. Long-term viability favors formulators with captive enzyme supply and automated dispenser integration capabilities. Monitor CDSCO import licensing rulings for early signals on India market access barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Fermentation | Captive protease capacity insulates Ecolab and STERIS from Danish supplier concentration risk. |
| EPA Safer Choice Certification Investment | Environmental profile validation gates preferred vendor status in California health system RFPs. |
| Point-of-Use Foam Format Development | Aerosol-reduced dispensers enable dental workflow compliance with OSHA Bloodborne Pathogens Standard. |
| Automated Dispenser System Partnership | Smart logging capabilities satisfy emerging ISO 17664 digital documentation requirements. |
| India Contract Manufacturing Establishment | Hyderabad-based production sidesteps CDSCO import licensing friction for Southeast Asian export. |
Research Methodology
Coverage spans the United States, Germany, China, India, and Japan, with primary inputs from each market cluster. Interviews with sterile processing department managers, GPO contracts directors, detergent formulator R&D heads, and EPA Safer Choice program officers combined with FDA 510(k) filing databases, REACH registration dossiers, and hospital procurement contract repositories. Bottom-up volume modeling triangulated against top-down health system expenditure analysis.
Granularity-level modeling operated at product type, end user, form, and packaging type dimensions, with additional chemistry-platform segmentation for enzymatic versus surfactant formulations. CAGR derivation applied instrument reprocessing volume projections against detergent consumption intensity ratios across the projection horizon. Forecast inputs incorporated NABH accreditation expansion timelines and robotic surgery instrument installed base growth.
Inputs from EPA Safer Choice certified product lists and FDA 510(k) clearance databases were available through the study window; gaps in private-label hospital contract pricing introduce uncertainty bands on margin structure estimates. Forecasts reflect documented assumptions on GPO consolidation trajectories and enzyme fermentation capacity expansion. Practitioners should monitor CDSCO manufacturing licensing rulings and California green procurement mandate enforcement for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Mosquito Repellent Market
Cleaning Chemicals
Efflorescence Remover Market
Cleaning Chemicals
Cleaning Fluids Market
Cleaning Chemicals
Multi-Residue Detoxifying Field Wash Aid Market
Cleaning Chemicals
Solar Component Cleaning Chemicals Market
Cleaning Chemicals
Fragrance-Free Cleaning Chemicals for Sensitive Environments Market
Cleaning Chemicals
Pipeline Chemical Cleaners Market
Cleaning Chemicals
Water-Saving Cleaning Chemical Systems for Professional Use Market
Cleaning Chemicals
Kitchen Vent Hood and Duct Cleaning Chemicals Market
Cleaning Chemicals
Cleaning Nozzles Market
Cleaning Chemicals
Firefighting Chemicals Market
Cleaning Chemicals
Cement Surface Treatment Chemicals Market
Cleaning Chemicals
Sponge and Scouring Pads Market
Cleaning Chemicals
Korea Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Low-VOC Cleaning Chemicals for Enclosed Workspaces Market
Cleaning Chemicals
US Specialty Cleaners Market