
 Industrial Cleaners Market | 2026-2036
Industrial Cleaners Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Cleaners Market Outlook
Preventive maintenance subscriptions and chemical-management programs are broadening how industrial cleaners get sold, shifting transactions from spot purchases to ongoing service relationships. Ecolab Inc. leverages its water-and-energy integration to bundle cleaning chemistry with utility optimization across food processing and hospitality accounts. BASF SE anchors its position through captive production of surfactant intermediates and specialty solvents that feed into customized blends for electronics and automotive clients. Diversey Holdings Ltd. differentiates through hygiene protocol certification and on-site training services that lock in multi-year facility contracts.
Industrial cleaners are formulated chemical systems—typically aqueous or solvent-based blends containing surfactants, chelating agents, pH modifiers, and corrosion inhibitors—engineered to remove oils, particulates, oxides, and biological residues from machinery, substrates, and process equipment without compromising material integrity. Solvent-based degreasers retain dominance in heavy manufacturing and aerospace where flash point and evaporation rate specifications govern process compatibility, while alkaline cleaners are gaining fastest in food processing and dairy applications where saponification of fats and compliance with USDA sanitation protocols drive specification. Application segmentation shows manufacturing facilities consuming the largest volume, though electronics cleaning commands the highest margin pool due to particulate thresholds below 0.1 micron and compatibility requirements with gallium arsenide and silicon carbide wafers.
EPA registration requirements under FIFRA and OSHA hazard communication standards shape product labeling, worker exposure limits, and permissible ingredient lists across the United States, while REACH authorization and restriction procedures in Europe block certain chlorinated and aromatic solvents from industrial use. The EU Green Deal's chemical sustainability targets and emerging state-level PFAS restrictions in Minnesota and Maine are forcing reformulation cycles that favor bio-based surfactants and closed-loop recovery systems. Stakeholders must monitor regulatory divergence between jurisdictions while building formulation flexibility that can pivot across compliance regimes without redundant R&D pipelines.
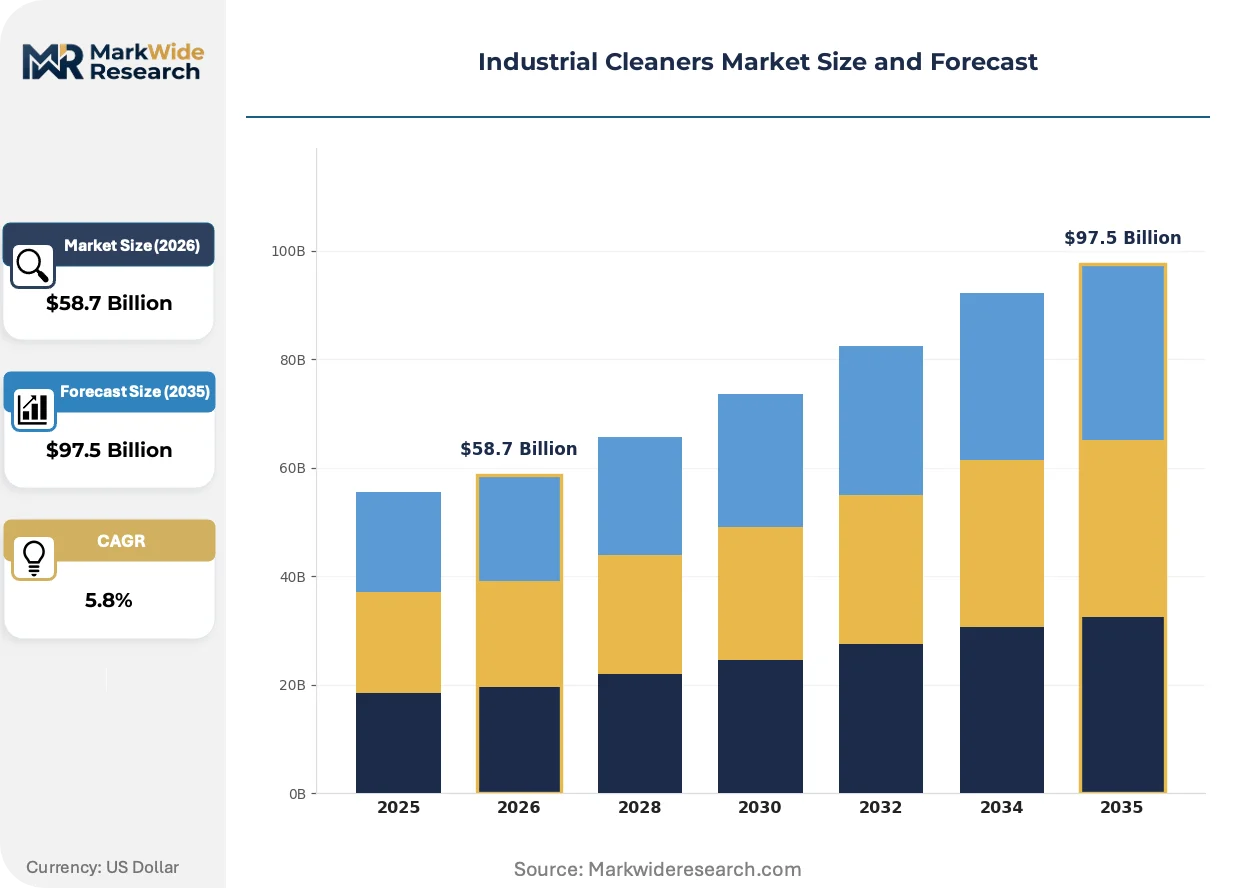
Market Dynamics
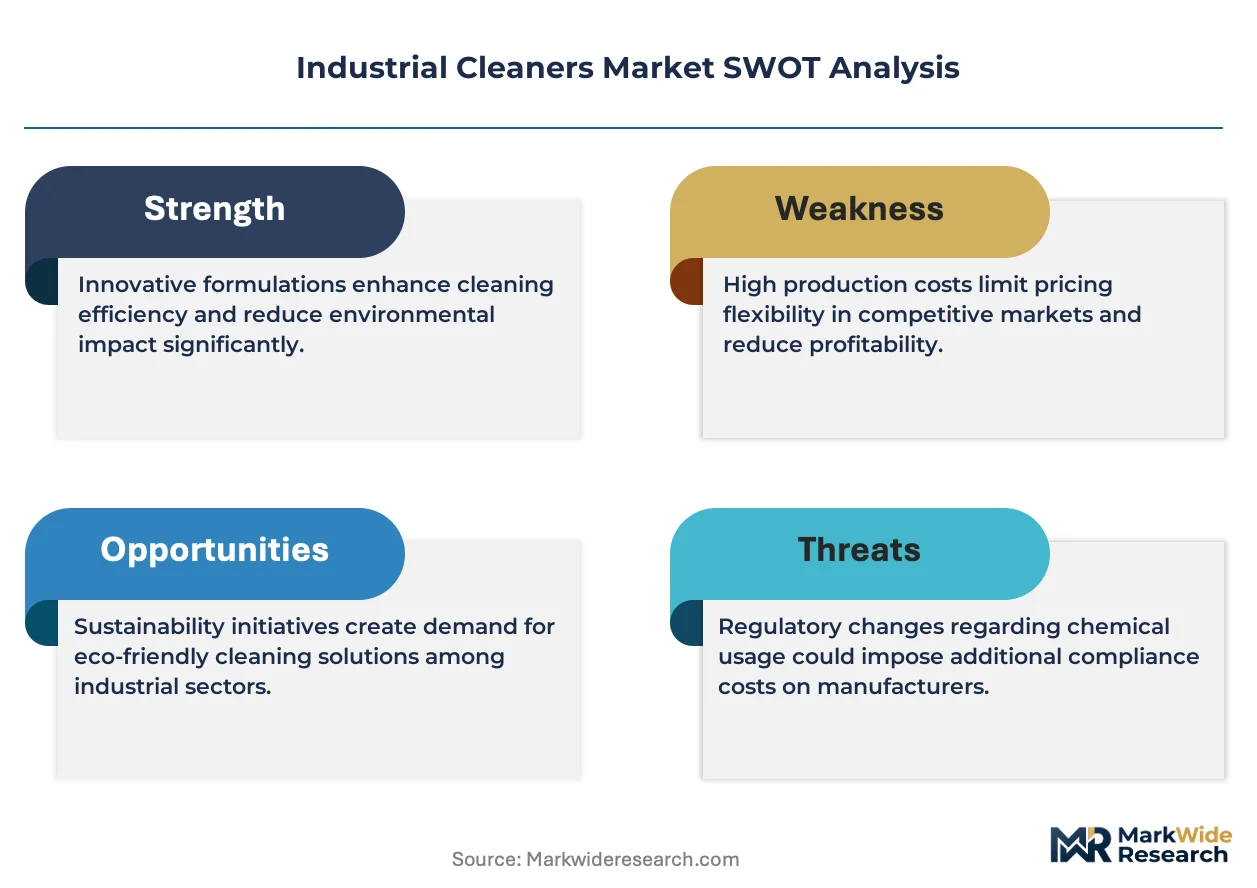
REACH authorization procedures and state-level PFAS restrictions in Minnesota and Maine are forcing simultaneous reformulation cycles across multiple compliance regimes, compressing product development timelines while expanding R&D overhead.
Growth Catalysts
- EU Green Deal chemical sustainability targets:The framework mandates bio-based feedstock ratios and closed-loop recovery systems, pulling demand toward surfactants derived from agricultural waste streams in German automotive supply chains.
- Precision cleaning thresholds in semiconductor fabrication:Particulate limits below 0.1 micron for gallium arsenide and silicon carbide wafers are expanding specification requirements for ultra-high-purity aqueous formulations.
- Food processing sanitation protocols:USDA compliance mandates for saponification-based fat removal are accelerating alkaline cleaner deployment across dairy and protein processing facilities.
Market Restraints
- Petrochemical feedstock volatility:Surfactant intermediates and specialty solvents remain tethered to naphtha and natural gas liquid pricing swings, compressing margin stability for blenders without captive oleochemical supply.
- Chlorinated solvent phase-out friction:REACH restrictions on trichloroethylene and perchloroethylene are stranding capital equipment in aerospace degreasing operations, slowing adoption of aqueous alternatives.
- Technical performance gaps in heavy manufacturing:Aqueous systems cannot yet match solvent-based flash point and evaporation rate specifications for certain precision metal cleaning applications.
Strategic Opportunities
- Closed-loop chemical recovery systems:Germany's automotive OEMs are piloting on-site solvent regeneration to reduce virgin chemical procurement and waste disposal costs.
- Preventive maintenance subscriptions:Chemical-management programs bundled with water-and-energy optimization are displacing spot purchases in food processing and hospitality accounts.
- Hygiene protocol certification services:On-site training and facility audit programs are locking in multi-year contracts with institutional buyers seeking operational risk transfer.
Industry Challenges
- Formulation chemist scarcity:Expertise in surfactant synergy design and regulatory compliance mapping is concentrating among a narrow cohort of specialists, inflating compensation and extending hiring timelines.
- Multi-jurisdiction registration complexity:Divergent EPA FIFRA requirements, OSHA hazard communication standards, and REACH authorization procedures demand parallel documentation streams, stretching regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Cleaners Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $97.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvents, Degreasers, Acid Cleaners, Alkaline Cleaners Application: Manufacturing Facilities, Automotive Industry, Food Processing, Electronics Cleaning End User: OEMs, Tier-1 Suppliers, Service Providers, Maintenance Contractors Packaging Type: Drums, Bottles, Pails, Sachets |
| Companies Covered | Ecolab Inc., BASF SE, Diversey Holdings Ltd., Henkel AG & Co. KGaA, Dow Chemical Co., Clariant AG, Evonik Industries AG, Solvay SA, 3M Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Cleaners Market Strategic Shifts
Reformulation pressures are converging with digital monitoring capabilities to reshape how cleaning chemistry is specified, delivered, and consumed across industrial facilities.
Supercritical CO2 cleaning is overtaking solvent-based degreasing in precision electronics and medical device manufacturing. Aerospace tier-1 suppliers in Germany and the United States are retrofitting production lines to accommodate this transition. The technology is overtaking incumbent vapor degreasing systems by eliminating hazardous air pollutant exposure and reducing wastewater treatment burdens.
REACH authorization procedures are tightening restrictions on per- and polyfluoroalkyl substances across industrial applications. The European Chemicals Agency is accelerating substance evaluation timelines, forcing manufacturers to submit substitution plans for fluorinated surfactants used in high-performance cleaners. Electronics cleaning segments in the Netherlands and Belgium are responding fastest, pivoting toward silicone-based and hydrocarbon alternatives ahead of formal sunset dates.
Subscription-based chemical stewardship is displacing transactional procurement in large-scale manufacturing accounts. Facility managers are consolidating vendor relationships to capture predictive maintenance analytics and regulatory documentation support. This pattern is most visible in German automotive OEM supply chains and United States food processing networks, where ESG reporting requirements favor documented chemical lifecycle tracking over lowest-unit-cost purchasing.
Industrial Cleaners Market Segmentation
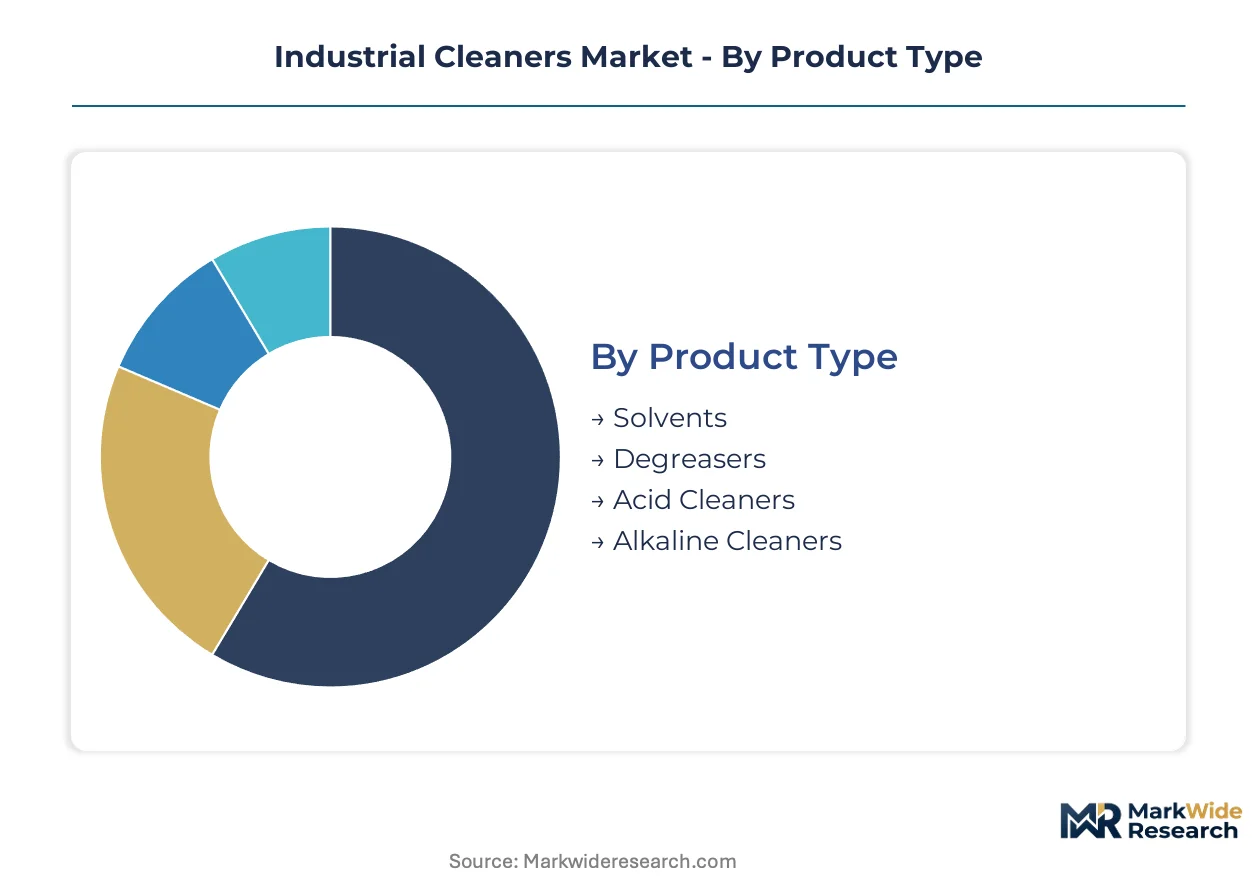
Industrial cleaners serve divergent contamination thresholds across substrate types, process temperatures, and regulatory exposure profiles. Segmentation reveals where formulation chemistry concentrates versus where service bundling commands premium positioning. Understanding these splits exposes margin architecture and R&D allocation priorities.
Product Type:
Supply concentration clusters around aqueous and solvent-based platforms, with specialty blends capturing disproportionate margin in precision applications.
- Solvents:Hydrocarbon and oxygenated formulations dominate heavy manufacturing degreasing where flash point specifications below 60°C govern process safety. Aerospace tier-1 suppliers in Germany specify these for aluminum alloy cleaning despite REACH authorization pressures forcing substitution planning.
- Degreasers:Emulsion-based and solvent-heavy variants remove petroleum-derived soils from machined components. Demand concentrates in automotive powertrain manufacturing where Ecolab and BASF supply captive formulations meeting OEM cleanliness standards.
- Acid Cleaners:Inorganic acid blends dissolve oxide scales and mineral deposits from heat exchangers and boiler systems.
- Alkaline Cleaners:Caustic and silicated formulations saponify organic fats in food processing environments.
Today's leader: Solvents. Tomorrow's challenger: Alkaline Cleaners.
Application:
Volume distribution tracks manufacturing intensity, while margin pools align with particulate tolerance thresholds and regulatory documentation burdens.
- Manufacturing Facilities:General machinery cleaning consumes the largest chemical volumes across metalworking, plastics molding, and assembly operations. Maintenance contractors in the United States specify these through MRO procurement channels with limited brand loyalty.
- Automotive Industry:Stamping, coating, and final assembly lines require residue-free substrates for paint adhesion and sealant bonding. German OEMs are driving closed-loop solvent recovery pilots to reduce virgin chemical procurement costs.
- Food Processing:USDA sanitation protocols mandate alkaline chemistry for fat removal and acid cycles for mineral deposit control.
- Electronics Cleaning:Ultra-high-purity aqueous and solvent systems remove sub-micron particulates from gallium arsenide and silicon carbide wafers.
Manufacturing Facilities anchor volume. Electronics Cleaning commands the steepest expansion trajectory.
End User:
Procurement authority fragments across technical specification, operational execution, and regulatory liability layers.
- OEMs:Original equipment manufacturers set formulation standards that cascade through supply chains. Automotive OEMs in Germany specify low-VOC and biodegradable requirements that tier-1 suppliers must match.
- Tier-1 Suppliers:Contract manufacturers and component suppliers execute cleaning protocols under OEM mandates. These accounts represent the fastest-growing service relationship segment as chemical stewardship programs displace spot purchasing.
- Service Providers:Third-party cleaning contractors operate on-site regeneration and waste minimization systems.
- Maintenance Contractors:Facilities management vendors procure through distributor networks with price-sensitive spot buying patterns.
OEMs dictate specifications. Tier-1 Suppliers are consolidating vendor relationships fastest.
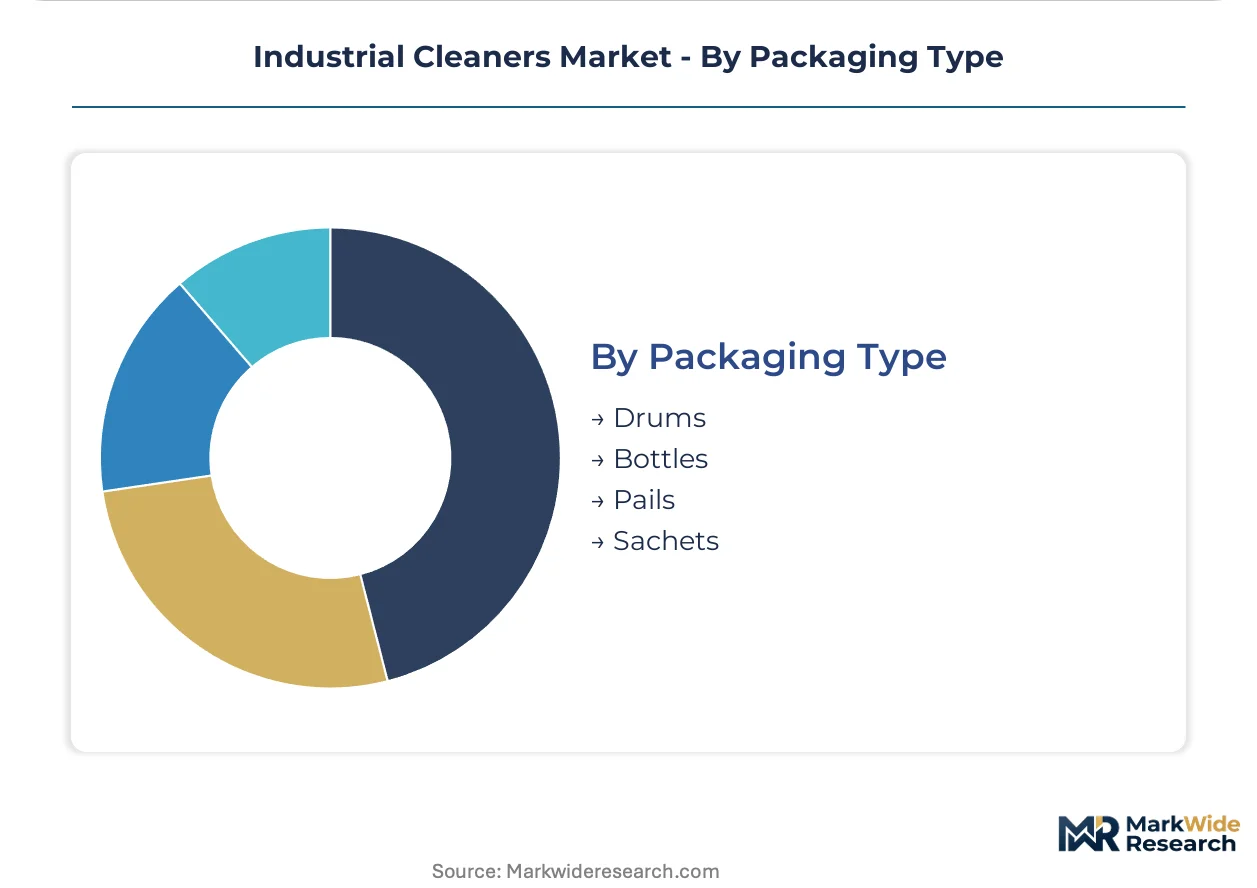
Packaging Type:
Container economics reflect order scale, chemical hazard classification, and closed-loop recovery infrastructure maturity.
- Drums:55-gallon steel and polyethylene containers serve high-volume manufacturing accounts with established chemical handling infrastructure. German automotive supply chains favor returnable drum programs to support ESG reporting requirements.
- Bottles:Trigger-spray and refill containers target precision application and laboratory environments.
- Pails:5-gallon open-head containers balance portability with volume for mid-scale maintenance operations.
- Sachets:Single-use water-soluble packets eliminate measuring errors and worker exposure in food processing sanitation protocols.
Drums dominate industrial scale. Sachets are gaining share in food safety-sensitive environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive supply chains impose stricter contamination thresholds than United States food processing networks, yet both jurisdictions face simultaneous pressure to eliminate chlorinated solvents under diverging regulatory timelines.
Germany
Automotive OEMs and tier-1 suppliers in Stuttgart and Wolfsburg specify low-VOC and biodegradable formulations for paint adhesion protocols. REACH authorization procedures accelerate substitution planning for perchloroethylene in aerospace degreasing operations. Munich-based chemical blenders pilot closed-loop solvent regeneration to reduce virgin procurement costs.
United States
EPA registration requirements under FIFRA reshape product labeling and worker exposure limits for metalworking facilities across the Midwest. State-level PFAS restrictions in Minnesota and Maine force reformulation cycles ahead of federal alignment. Houston petrochemical corridors supply surfactant intermediates to Gulf Coast blenders facing margin compression from feedstock volatility.
China
Semiconductor fabrication plants in Shanghai and Beijing demand ultra-high-purity aqueous systems for gallium arsenide wafer cleaning. MIIT standards for industrial chemical management tighten documentation requirements for imported formulations. Yangtze River Delta electronics clusters pivot toward silicone-based alternatives as fluorinated surfactant sunset dates approach.
Japan
Precision electronics manufacturers in Osaka and Nagoya specify sub-micron particulate thresholds below 0.1 micron for silicon carbide substrates. METI guidelines promote bio-based feedstock ratios in chemical procurement for automotive supply chains. Chubu region industrial cleaners blenders integrate water-and-energy optimization into preventive maintenance subscriptions.
India
Dairy and protein processing facilities in Maharashtra and Gujarat deploy alkaline cleaners for USDA-equivalent sanitation protocols. BIS certification requirements for industrial chemicals extend registration timelines for imported formulations. Gujarat chemical clusters develop captive surfactant production to reduce petrochemical import dependence.
Industrial Cleaners Market Competitive Environment
Top-tier vendors anchor formulation chemistry and service bundling, while mid-tier blenders compete on regional distributor relationships and spot purchasing channels. The market structure concentrates around multinational chemical conglomerates with captive intermediate production and specialized hygiene service providers. Strategic archetypes include water-and-energy integrators, surfactant intermediate producers, and protocol certification specialists. Dominant competitive moves encompass preventive maintenance subscription rollouts and closed-loop recovery system partnerships.
Within the chemical conglomerate tier, Ecolab Inc., BASF SE, and Diversey Holdings Ltd. occupy positions that exemplify divergent strategic anchors. Ecolab represents the water-and-energy integration archetype through bundled utility optimization. BASF exemplifies captive surfactant intermediate production feeding customized industrial blends. Diversey anchors the hygiene protocol certification model with on-site training and multi-year facility contracts.
| Leading Market Players |
|---|
| Ecolab Inc. |
| BASF SE |
| Diversey Holdings Ltd. |
| Henkel AG & Co. KGaA |
| Dow Chemical Co. |
| Clariant AG |
| Evonik Industries AG |
| Solvay SA |
| 3M Co. |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up specialty chemical distributors have consolidated regional blending capacity across the United States and Germany, tightening price discipline through volume aggregation while squeezing margin for non-integrated mid-caps without captive surfactant supply.
Pricing Analysis
Capacity additions in Germany's automotive supply belt are reshaping price floors for ultra-high-purity aqueous formulations. Pricing stratifies across premium, standard, and economy tiers based on particulate certification thresholds and closed-loop service bundling. Cost compression in standard-grade solvent degreasers is intensifying because petrochemical feedstock volatility feeds through naphtha-linked surfactant intermediates. Maintenance contractors in the United States exhibit the highest price sensitivity, while semiconductor fabs in Japan and China accept premium positioning for sub-0.1-micron particulate compliance.
Supply Chain Analysis
REACH authorization and EPA FIFRA registration gating concentrates qualified supply among blenders with dedicated regulatory affairs capacity, fragmenting tier-2 participation. Germany, the United States, and China anchor global production, with the Yangtze River Delta and Gulf Coast corridors feeding surfactant intermediates to downstream formulators. The chain draws from naphtha-derived oleochemicals, agricultural waste-stream bio-feedstocks, and fluorinated specialty solvents now facing substitution pressure. Single-source vulnerability runs through German automotive OEM specification control over tier-1 supplier chemistry choices. Distribution runs through direct mill-and-facility contracts for large accounts and industrial distributor networks for spot procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through closed-loop chemical recovery systems that collapse virgin procurement and waste disposal costs for large manufacturing accounts.
For Market Incumbents: Lock in multi-year chemical stewardship subscriptions with predictive maintenance analytics to forestall spot-purchase competitors. Deepen upstream control over surfactant intermediates through captive production or long-term offtake agreements with Gulf Coast and Yangtze River Delta petrochemical corridors. Counter aqueous substitution threats in aerospace degreasing by piloting supercritical CO2 retrofit partnerships before REACH sunset dates formalize. For New Entrants and Emerging Players: E-commerce procurement platforms targeting mid-scale maintenance contractors in India's Maharashtra and Gujarat dairy belt bypass entrenched distributor relationships. White-space concentrates in silicone-based fluorinated surfactant alternatives for Netherlands and Belgium electronics cleaning ahead of ECHA authorization timelines. Lead with hygiene protocol certification and on-site training to differentiate from commodity blenders. For Investors and Strategic Acquirers: Valuations sit cheapest among regional blenders lacking closed-loop infrastructure but holding EPA FIFRA and REACH registration assets. The five-to-ten-year viability window favors targets with formulation flexibility across compliance regimes rather than single-jurisdiction specialists. Watch for inflection when German automotive OEMs mandate documented chemical lifecycle tracking in supplier ESG scorecards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Intermediates | Captive supply of naphtha-derived oleochemicals insulates margin from petrochemical volatility in German automotive supply chains. |
| Closed-Loop Solvent Recovery Deployment | On-site regeneration at Stuttgart and Wolfsburg facilities collapses virgin chemical procurement costs under EU Green Deal targets. |
| Supercritical CO2 Retrofit Partnership | Aerospace tier-1 suppliers in Germany and the United States eliminate hazardous air pollutant exposure ahead of REACH restrictions. |
| Preventive Maintenance Subscription Rollout | Water-and-energy optimization bundling locks in multi-year contracts with ESG-reporting food processing accounts. |
| Hygiene Protocol Certification Program | USDA-equivalent sanitation training secures facility contracts with Maharashtra and Gujarat dairy processors seeking risk transfer. |
Study Parameters
Bottom-up end-use consumption modeling reconciled against top-down surfactant intermediate production tracking forms the analytical core of this study. Primary interviews with plant managers at automotive stamping facilities, procurement leads at tier-1 electronics suppliers, distribution channel partners in industrial chemical networks, and technical R&D directors at specialty blenders informed demand segmentation. Secondary validation drew from EPA FIFRA registration databases, ECHA REACH authorization filings, customs and trade flow records, and SEC 10-K disclosures from listed chemical conglomerates. Triangulation across these sources calibrated volume and value estimates.
Historical trendline analysis of aqueous versus solvent-based formulation shifts anchored growth trajectory assumptions across the projection horizon. The modeling framework disaggregated demand by product chemistry type, end-use industry vertical, packaging format, and regional production hub to isolate margin pool concentrations. CAGRs were derived from segment-level growth rates applied against base-year consumption intensities, with semiconductor fabrication capacity expansion and food processing sanitation protocol tightening as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for supercritical CO2 cleaning penetration would alter the outlook for solvent-based degreaser demand. Forecasts reflect assumptions regarding REACH authorization timelines and state-level PFAS restriction enforcement that could accelerate or delay reformulation cycles. A model refresh is warranted upon material change in German automotive OEM chemical specification mandates or EPA FIFRA registration requirement revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Cleanroom Consumables Market
Cleaning Chemicals
Electrostatic Liquid Cleaner Market
Cleaning Chemicals
South Africa Cleaning Products Market
Cleaning Chemicals
Firefighting Chemicals Market
Cleaning Chemicals
Water-Saving Cleaning Chemical Systems for Professional Use Market
Cleaning Chemicals
Bleaching Chemicals Market
Cleaning Chemicals
High-Performance Descaling and Deliming Chemicals for HoReCa Equipment Market
Cleaning Chemicals
Aviation Cabin Cleaning Chemical Market
Cleaning Chemicals
Acid Coil Cleaner Market
Cleaning Chemicals
Eco-Label Certified Cleaning Chemicals for Professional Users Market
Cleaning Chemicals
Sponge and Scouring Pads Market
Cleaning Chemicals
Dry Cleaning Solvents Market
Cleaning Chemicals
Deck Brightener Market
Cleaning Chemicals
US Institutional Cleaning Ingredients Market
Cleaning Chemicals
Global Dust Suppression and Control Chemicals Market
Cleaning Chemicals
Metal Polish Products Market