
 Solar Component Cleaning Chemicals Market | 2026-2036
Solar Component Cleaning Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Component Cleaning Chemicals Market Analytics
Chinese specialty chemical producers is expanding manufacturing footprints for photovoltaic-grade cleaning formulations to serve Asia-Pacific project pipelines. Ecolab leverages its institutional water-chemistry expertise to anchor service contracts with utility-scale operators across desert solar belts. Saint-Gobain sustains competitive positioning through integrated supply chains spanning glass substrate production and aftermarket surface treatment chemistry.
Solar component cleaning chemicals comprise formulated aqueous and solvent-based solutions engineered to remove particulate matter, organic residue, and mineral scaling from photovoltaic surfaces without compromising anti-reflective coatings or frame sealants; surfactant-dominant alkaline cleaners achieve sub-5% surface tension reduction to lift desert dust and pollen while maintaining <0.1% residue after rinse cycles, preserving module output efficiency. Solvent-based formulations occupy premium pricing tiers where hydrocarbon or silicone deposits from agricultural or industrial adjacencies require aggressive dissolution, though alkaline cleaners represent the fastest-growing product category as water-scarce sites adopt low-rinse-concentrate protocols. Ground-mounted installations generate the dominant application volume given accessibility for mechanized delivery systems, yet rooftop segments command margin premiums due to formulation constraints around drainage containment and residential safety thresholds.
EPA registration requirements under FIFRA govern antimicrobial claims in US solar cleaning products, while REACH substance restrictions in Europe constrain chlorinated solvent content and mandate biodegradability testing under OECD 301 protocols. India's BIS certification for chemical imports and state-level pollution control board discharge limits create layered compliance costs for foreign suppliers entering the market. Stakeholders must monitor evolving per- and polyfluoroalkyl substance regulations across multiple jurisdictions, as fluorosurfactant bans would force reformulation of high-performance anti-soiling coatings.
Market Dynamics
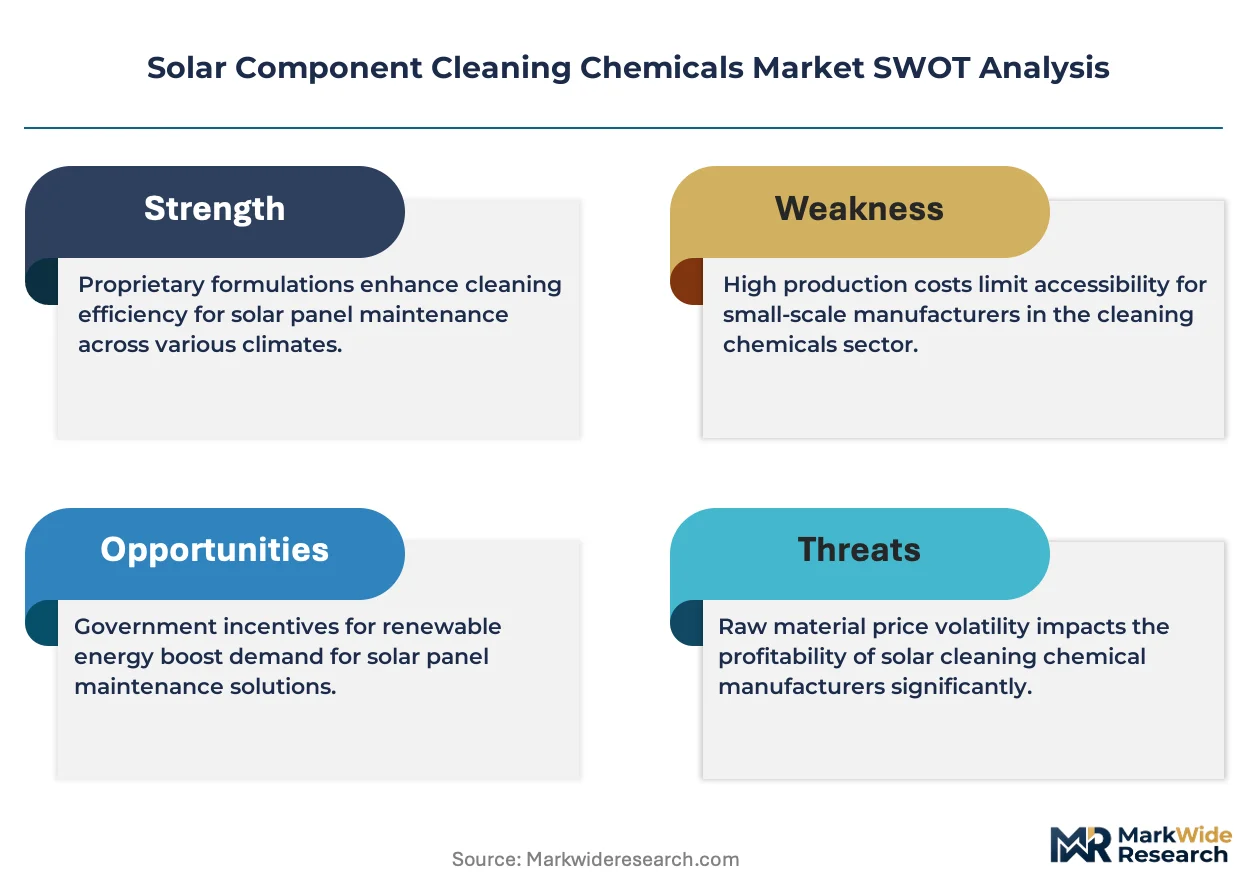
REACH substance restrictions and EU Green Deal chemical mandates are forcing formulators to abandon chlorinated solvents and fluorosurfactants, compressing incumbent product lifecycles while opening formulation white space for biodegradable surfactant systems.
Growth Catalysts
- India's solar capacity targets:The country's National Solar Mission and state-level renewable purchase obligations create chronic module soiling challenges across arid Rajasthan and Gujarat solar belts, driving recurring chemical consumption.
- Automated cleaning protocol adoption:Utility-scale operators in desert solar regions are integrating mechanized delivery systems that require low-foam, low-rinse concentrate chemistries compatible with robotic spray architectures.
- REACH biodegradability mandates:ECHA enforcement of OECD 301 testing protocols for surfactant systems is accelerating reformulation investments toward plant-derived alkyl polyglucosides and biosynthetic alternatives.
Market Restraints
- Petrochemical feedstock volatility:Ethylene oxide and fatty alcohol price swings squeeze margin structures for surfactant-dominant alkaline cleaner producers, particularly in Asia-Pacific contract manufacturing.
- Fluorosurfactant regulatory overhang:Anticipated PFAS restrictions across US EPA, EU ECHA, and multiple state jurisdictions threaten high-performance anti-soiling coating formulations with forced reformulation costs.
- Water-scarce site operational limits:Ground-mounted installations in Chile's Atacama and Saudi Arabia's NEOM face absolute rinse-water constraints that cap cleaning frequency and chemical application volumes.
Strategic Opportunities
- Indonesia's floating solar expansion:The archipelago's 3.6 GW floating PV pipeline creates unmet demand for marine-grade, low-toxicity cleaners compatible with reservoir ecosystems and polymer floatation systems.
- Service contract bundling:Chemical supply integrated with drone-based soiling monitoring and predictive cleaning scheduling offers margin expansion beyond commodity formulation sales.
- EU CSRD disclosure requirements:Corporate sustainability reporting mandates for Scope 3 emissions are pushing asset owners toward certified biodegradable cleaners with verified lifecycle carbon footprints.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in photovoltaic-grade surface chemistry—balancing anti-reflective coating compatibility with mineral scale dissolution—remains concentrated among legacy industrial cleaning compounders.
- BIS certification timelines:India's Bureau of Indian Standards import registration process for chemical formulations creates 8-14 month market entry delays, favoring domestic manufacturing investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Component Cleaning Chemicals Market |
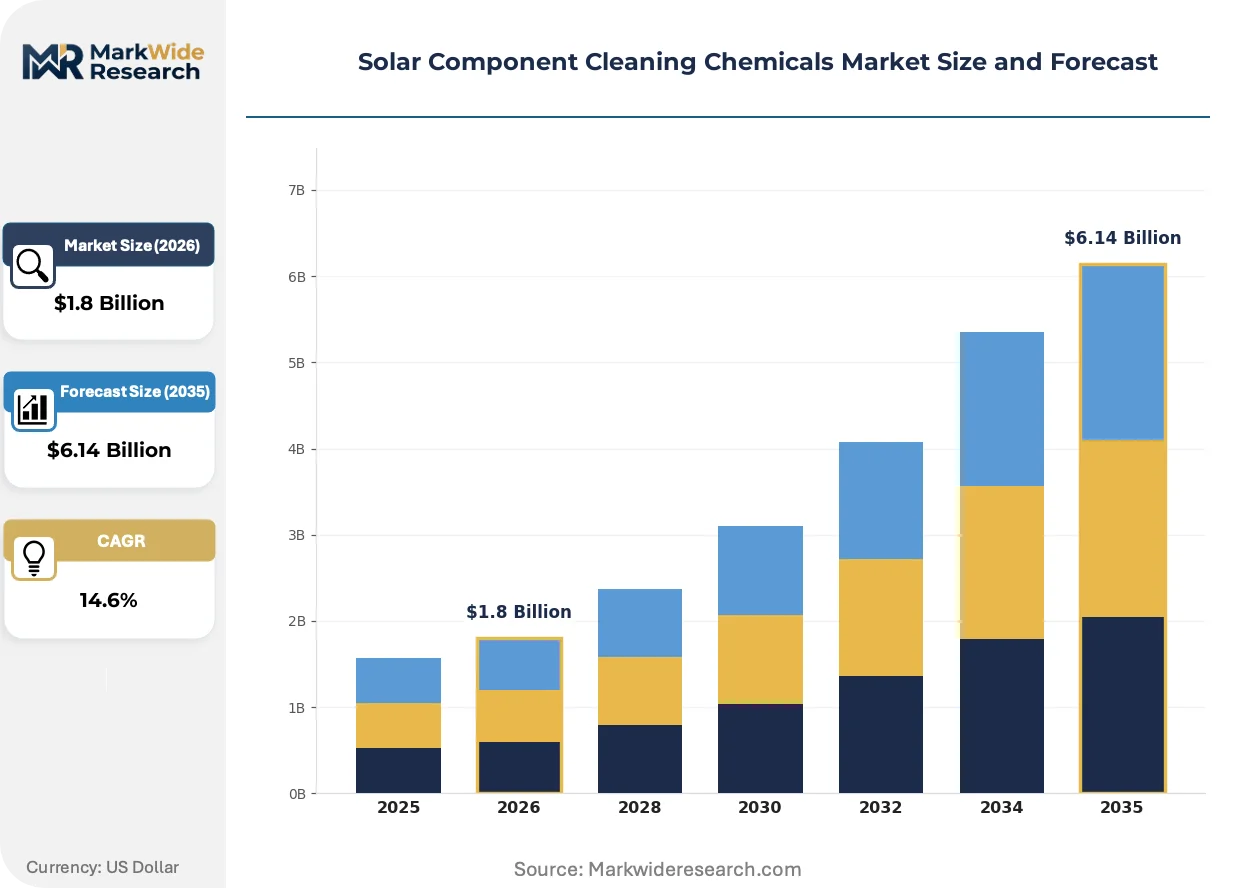
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surfactants, Solvents, Acids, Alkaline Cleaners Application: Ground-Mounted, Rooftop Installations, PV Modules, Solar Panels Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers End User: Utilities, Residential Users, Commercial Divers, Maintenance Providers |
| Companies Covered | IPC, Ecoppia, Ecolab, Saint-Gobain, Lavee, Emil Otto, WattUp, Alconox, Verteco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Component Cleaning Chemicals Market Evolving Landscape
Formulation science is pivoting from performance-maximizing chemistries to regulatory-compliant, site-specific solutions. Three developments are compressing product development cycles and reshaping competitive positioning.
Electrostatic dust-repelling nano-coatings is overtaking traditional wet-cleaning chemical regimes in high-soiling, water-constrained environments. Saudi Arabia's Red Sea Project and UAE's Al Dhafra Solar PV are piloting these treatments to extend cleaning intervals from monthly to quarterly cycles. The technology is compressing recurring chemical revenue pools while creating upfront coating application service opportunities.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluoroolefin solvent displacement in precision cleaning applications. Formulators serving agricultural-adjacent solar farms—where hydrocarbon pesticide residues require aggressive dissolution—are pivoting toward bio-based terpene and ester solvent blends. German and Spanish operators are absorbing 15-25% formulation cost premiums to maintain site access under tightening environmental permits.
Buyers are unbundling chemical supply from equipment procurement, rejecting historical bundled O&M contracts. Indian and Australian utility-scale operators now tender cleaning chemicals separately from robotic spray system leases, forcing pure-play chemical formulators to build direct sales and technical service capabilities. This disintermediation is visible most acutely in Rajasthan's 25 GW solar park cluster, where state nodal agencies mandate transparent chemical cost pass-throughs in power purchase agreements.
Solar Component Cleaning Chemicals Market Segmentation
Cleaning chemical specifications diverge sharply based on installation geometry and soiling chemistry. Product selection hinges on water availability constraints, coating compatibility requirements, and mechanized delivery system specifications.
Product Type:
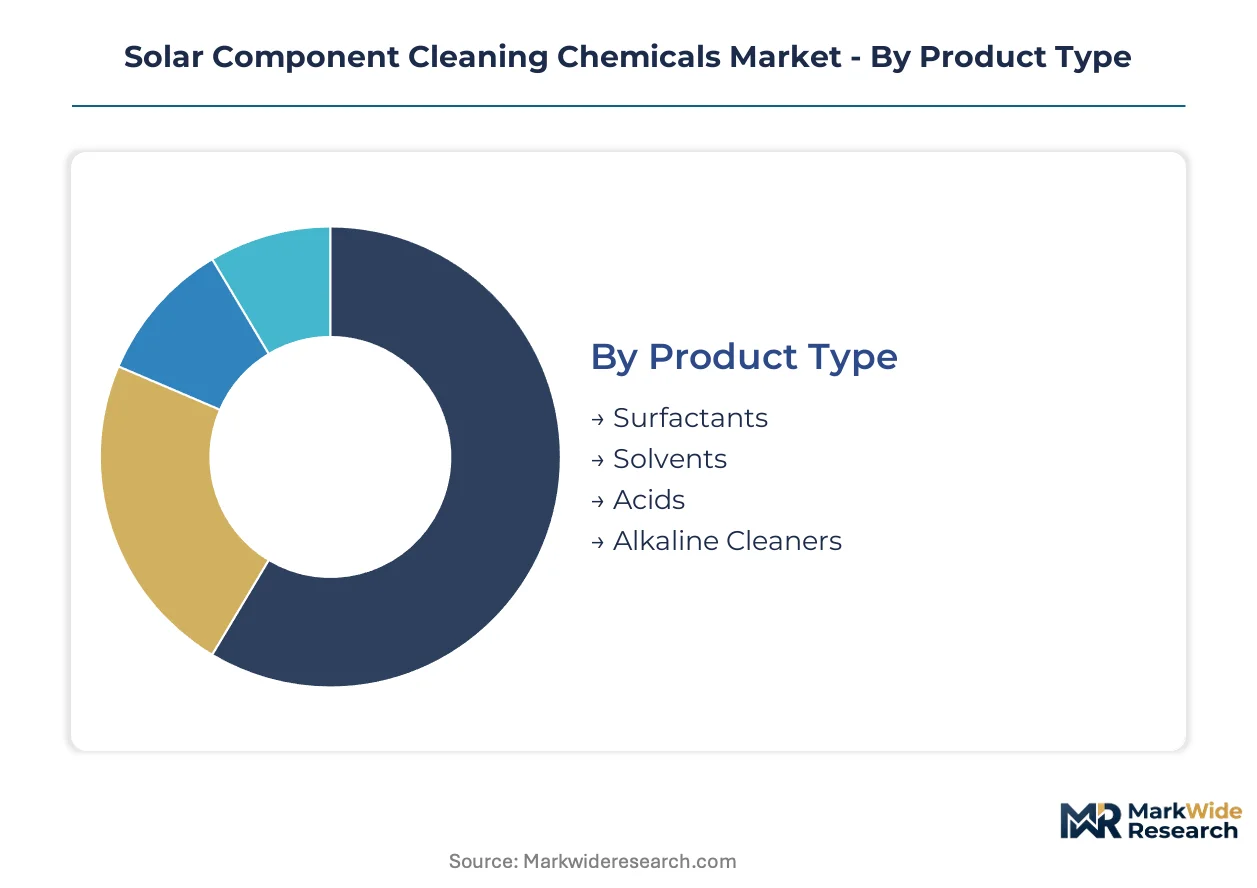
Alkaline cleaners operate as standalone concentrates requiring dilution at site, while solvent systems embed into pre-mixed aerosol or bulk delivery architectures.
- Alkaline Cleaners:Formulated around sodium hydroxide and potassium silicate bases with surfactant packages achieving sub-5% surface tension reduction. Demand concentrates in Rajasthan and Gujarat solar belts where desert dust accumulation mandates frequent low-rinse protocols compatible with water-scarce operations.
- Surfactants:Plant-derived alkyl polyglucosides and biosynthetic alternatives are displacing petroleum-based ethoxylates under REACH biodegradability mandates. German and Spanish operators absorb 15-25% cost premiums to maintain site access under tightening environmental permits.
- Solvents:Hydrocarbon and terpene blends for dissolving pesticide residues and industrial hydrocarbon deposits in agricultural-adjacent installations.
- Acids:Mineral acid formulations targeting calcium carbonate and silica scaling from hard water irrigation overspray.
Alkaline cleaners lead volumes today; surfactants are gaining share fastest.
Application:
Accessibility determines formulation constraints — ground-mounted systems accommodate bulk concentrate logistics while rooftop segments impose drainage containment and residential safety thresholds.
- Ground-Mounted:Mechanized spray architectures dominate utility-scale desert solar farms. Low-foam, low-rinse concentrate chemistries integrate with robotic delivery systems across Saudi Arabia's NEOM and Chile's Atacama installations where absolute water constraints cap cleaning frequency.
- Rooftop Installations:Polymer-safe, neutral-pH formulations with rapid biodegradation profiles serve residential and commercial distributed generation. BIS certification requirements and state pollution control board discharge limits in India create layered compliance costs favoring domestic formulation sourcing.
- PV Modules:Anti-reflective coating compatibility specifications drive surfactant selection to preserve surface transmission efficiency.
- Solar Panels:Frame sealant integrity requirements constrain solvent polarity and concentration thresholds.
Ground-mounted systems anchor current procurement volumes; rooftop installations command the steepest margin expansion trajectory.
Distribution Channel:
Channel selection tracks customer scale and technical service intensity requirements — large utilities favor direct supply relationships while fragmented maintenance providers rely on distributor networks.
- Direct Sales:Ecolab and integrated service providers anchor utility-scale contracts across desert solar belts with bundled water-chemistry expertise and predictive cleaning scheduling.
- Distributors:Regional chemical distributors serve mid-scale commercial operators in India's state nodal agency clusters with inventory proximity and local regulatory navigation support.
- Online Retail:Concentrate and ready-to-use formulations for residential rooftop maintenance in Australia and distributed generation markets.
- Wholesalers:Bulk concentrate logistics for O&M contractors managing multi-site solar park portfolios.
Direct sales channels capture the largest contract values; distributor networks are expanding most quickly into emerging solar markets.
End User:
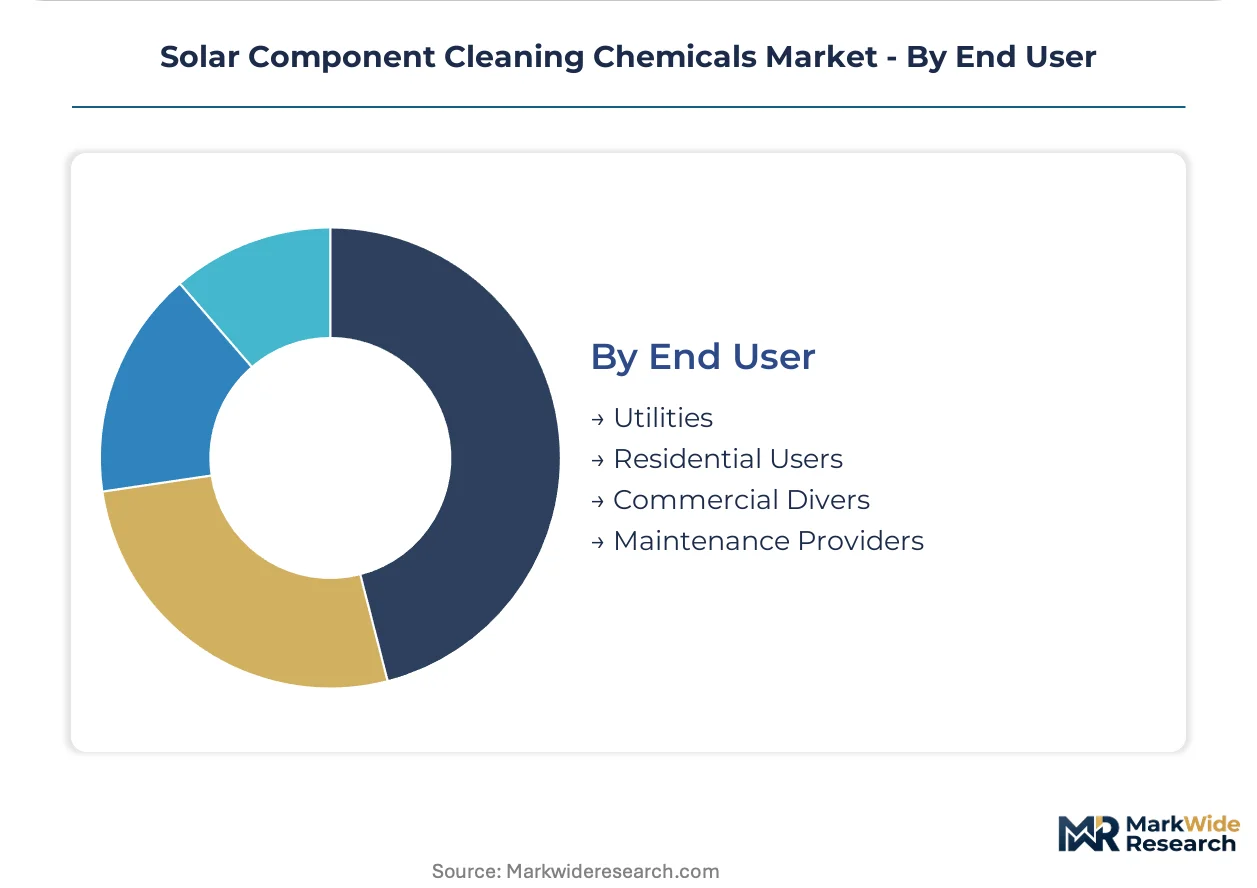
Procurement sophistication varies — utilities mandate certified lifecycle carbon footprints under EU CSRD disclosure requirements while residential users prioritize ease-of-application and safety labeling clarity.
- Utilities:State nodal agencies in Rajasthan's 25 GW solar park cluster mandate transparent chemical cost pass-throughs in power purchase agreements. Automated cleaning protocol adoption drives specification of low-foam concentrates compatible with robotic spray architectures.
- Maintenance Providers:Independent O&M contractors across India's National Solar Mission pipeline face BIS certification timelines of 8-14 months, favoring domestic manufacturing investments over import registration.
- Commercial:Corporate sustainability reporting mandates for Scope 3 emissions push asset owners toward certified biodegradable cleaners with verified lifecycle carbon footprints.
- Residential Users:Drainage containment requirements and polymer floatation system compatibility constrain formulation selection in Indonesia's 3.6 GW floating PV pipeline.
Utilities dominate absolute chemical consumption; maintenance providers are capturing procurement autonomy fastest as buyers unbundle chemical supply from equipment leases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's arid solar belts generate chronic soiling volumes that dwarf European consumption, while Saudi Arabia's NEOM installations impose absolute water constraints that reshape formulation chemistry entirely.
India
Rajasthan's 25 GW solar park cluster and Gujarat's Charanka Solar Park drive concentrated alkaline cleaner demand for desert dust removal. BIS certification timelines of 8-14 months for chemical imports favor domestic manufacturing investments by foreign suppliers. State nodal agencies now mandate transparent chemical cost pass-throughs in power purchase agreements across the National Solar Mission pipeline.
United States
Utility-scale desert installations in California's Mojave and Arizona's Sonoran regions adopt automated cleaning protocols requiring low-foam concentrates. EPA registration under FIFRA governs antimicrobial claims in cleaning products, adding compliance layers for imported formulations. The Imperial Valley solar cluster anchors procurement volumes for mechanized delivery system integration.
Germany
Agricultural-adjacent solar farms in Bavaria and Baden-Württemberg absorb 15-25% cost premiums for bio-based terpene solvents under tightening environmental permits. REACH biodegradability mandates through ECHA enforcement accelerate plant-derived alkyl polyglucoside adoption. The country's dual role as formulation hub and export platform shapes surfactant supply patterns across Europe.
Saudi Arabia
NEOM and Red Sea Project installations pilot electrostatic nano-coatings to extend cleaning intervals from monthly to quarterly cycles in water-scarce conditions. The kingdom's renewable targets concentrate demand in the northwestern region where absolute rinse-water constraints cap chemical application volumes. SFDA chemical import regulations add registration complexity for foreign suppliers.
Indonesia
The archipelago's 3.6 GW floating PV pipeline creates unmet demand for marine-grade, low-toxicity cleaners compatible with reservoir ecosystems. Java and Sumatra anchor project development where polymer floatation system compatibility constrains formulation selection. The country's national chemical regulator imposes discharge limits that favor rapid biodegradation profiles.
Solar Component Cleaning Chemicals Market Competitive Landscape
Chinese specialty chemical producers anchor one tier; European institutional water-chemistry specialists hold another. The market structures around formulation expertise concentration rather than manufacturing scale, with three archetypes dominating: integrated glass-chemical conglomerates, pure-play cleaning compounders, and water-treatment service bundlers. Competitive moves center on backward integration into surfactant raw materials and geographic expansion through domestic manufacturing investments to bypass import certification delays.
Within the service-bundler tier, Ecolab exemplifies institutional water-chemistry expertise applied to utility-scale desert contracts. Saint-Gobain occupies a position spanning glass substrate production and aftermarket surface treatment chemistry. Among pure-play specialists, Ecoppia represents automated cleaning system integration with formulated chemistry supply. These anchors illustrate how competitive positioning diverges between chemical-centric and equipment-centric revenue models.
| Leading Market Players |
|---|
| IPC |
| Ecoppia |
| Ecolab |
| Saint-Gobain |
| Lavee |
| Emil Otto |
| WattUp |
| Alconox |
| Verteco |
| Others |
Value Network & Pricing Analysis
Formulation chemist concentration in Germany's Rhine-Ruhr chemical corridor widens pricing spreads between premium REACH-compliant surfactants and commodity alkaline concentrates sourced from Asia-Pacific contract manufacturers. Labor-cost differentials in surfactant synthesis translate directly into three-tier pricing structure across premium, standard, and economy levels.
Pricing Analysis
Capacity additions in China's Shandong province are reshaping price floors for alkaline cleaner concentrates, compressing margins for legacy producers. Pricing stratifies across premium, standard, and economy tiers based on biodegradability certification under OECD 301 protocols and volume-scale procurement commitments. Cost compression in the economy tier is intensifying because Indian state nodal agencies mandate transparent chemical cost pass-throughs in power purchase agreements. Utility-scale operators exhibit lowest price sensitivity due to bundled service contracts, while independent O&M contractors in fragmented maintenance markets drive hardest bargain.
Supply Chain Analysis
Ethylene oxide and fatty alcohol supply rests on petrochemical complexes in China, South Korea, and Saudi Arabia. Specialty surfactant producers draw from palm-derived feedstocks in Malaysia and Indonesia alongside biosynthetic fermentation capacity in Western Europe. Single-source vulnerability in fluorosurfactant precursors threatens high-performance anti-soiling coating formulations as PFAS restrictions multiply. Distribution runs through regional chemical distributors serving India's state nodal agency clusters with inventory proximity and BIS certification navigation support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through biodegradable surfactant premiumization and automated cleaning protocol bundling. Reformulation cost recovery in REACH-compliant tiers outpaces commodity concentrate erosion.
For Market Incumbents: To counter electrostatic nano-coating substitution in water-scarce installations, anchor utility-scale contracts with predictive cleaning scheduling and drone-based soiling monitoring. Backward integration into plant-derived alkyl polyglucoside feedstocks secures supply continuity under ECHA enforcement timelines. Direct sales capabilities must replace distributor dependency as Indian and Australian operators unbundle chemical supply from robotic system leases. For New Entrants and Emerging Players: Enter via Indonesia's 3.6 GW floating PV pipeline, where marine-grade formulation requirements and polymer floatation system compatibility create unmet demand. Indonesia's national chemical regulator discharge limits favor rapid biodegradation profiles that incumbent solvent specialists struggle to meet. Partner with reservoir ecosystem consultants to demonstrate low-toxicity credentials for archipelago project developers. For Investors and Strategic Acquirers: Water-treatment service bundlers are the most active acquirer in this space, seeking formulation expertise to complement institutional chemistry contracts. Five-to-ten-year viability hinges on PFAS regulatory trajectory and electrostatic coating adoption curves. Watch for BIS certification timeline compression in India as domestic manufacturing investments accelerate.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Feedstocks | Captive supply of alkyl polyglucosides insulates margin from ethylene oxide volatility. |
| Domestic Manufacturing Investment in India | Bypasses 8-14 month BIS import registration delays for National Solar Mission pipeline access. |
| Automated Cleaning Protocol Bundling | Ecolab's utility-scale desert contracts demonstrate margin expansion beyond commodity sales. |
| Marine-Grade Formulation Development | Indonesia's floating PV pipeline creates first-mover advantage in reservoir-compatible chemistry. |
| REACH Biodegradability Certification | German and Spanish operators absorb 15-25% premiums for OECD 301-compliant surfactant systems. |
Research Methodology
Multiple input streams — formulation chemist interviews, utility procurement officer surveys, and customs trade data — were reconciled to construct demand estimates. Primary fieldwork engaged plant managers at alkaline cleaner facilities, technical R&D directors at surfactant producers, EPC contractors in Rajasthan's solar park cluster, and state nodal agency procurement leads. Secondary validation drew from BIS certification registries, ECHA substance restriction updates, SEC filings by integrated service providers, and OECD 301 biodegradability test submissions. Bottom-up project pipeline analysis and top-down chemical consumption intensity modeling were cross-referenced for triangulation.
Historical capacity deployment patterns were cross-referenced against panel input from industry practitioners to anchor growth assumptions across the analysis window. Segmentation modeling incorporated product type, installation geometry, distribution channel, and end-user procurement sophistication. CAGRs were derived from slope analysis of year-over-year consumption intensity trends, adjusted for water-scarcity constraints in Atacama and NEOM installations and REACH reformulation investment cycles.
The model holds under stable petrochemical feedstock pricing and incremental regulatory tightening; deviation in abrupt PFAS bans or electrostatic coating breakthroughs would shift volume trajectories. Forecasts embed assumptions around BIS certification timeline stability and ECHA enforcement consistency. A small set of named triggers — fluorosurfactant prohibition scope, floating PV project ramp rates, and automated cleaning robot deployment curves — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Eco-Label Certified Cleaning Chemicals for Professional Users Market
Cleaning Chemicals
Fabric Softener Market
Cleaning Chemicals
Surface Cleaning Products Market
Cleaning Chemicals
Industrial Cleaners Market
Cleaning Chemicals
Glass Cleaner Market
Cleaning Chemicals
Fragrance-Free Cleaning Chemicals for Sensitive Environments Market
Cleaning Chemicals
Dry Cleaning Solvents Market
Cleaning Chemicals
Global Bleach Wipes Market
Cleaning Chemicals
Pipeline Chemical Cleaners Market
Cleaning Chemicals
Industrial and Institutional (Iandi) Cleaning Chemicals Market
Cleaning Chemicals
Aviation Cabin Cleaning Chemical Market
Cleaning Chemicals
Autonomous Floor Cleaning Machine Detergent and Care Chemicals Market
Cleaning Chemicals
Micellar Cleansing Water Market
Cleaning Chemicals
Home Care Chemicals Market
Cleaning Chemicals
Drain Opener Chemicals Market
Cleaning Chemicals
Kitchen Vent Hood and Duct Cleaning Chemicals Market