
 Green Floor Care Chemical Systems for Commercial Facilities Market | 2026-2036
Green Floor Care Chemical Systems for Commercial Facilities Market Size, Share, and Industry Trends Forecast 2026-2036
Green Floor Care Chemical Systems for Commercial Facilities Market Insights
LEED v4.1 and the WELL Building Standard are consolidating demand around third-party-certified formulations that eliminate quaternary ammonium compounds and synthetic fragrances from floor maintenance protocols. Diversey leverages its captive biotechnology R&D to develop bio-based polymer finishes with accelerated biodegradation profiles. Ecolab anchors North American distribution through integrated water-and-energy service contracts that bundle chemical dispensing with IoT-enabled dilution control. SC Johnson Professional differentiates through concentrated pre-measured packs that reduce packaging waste and shipping volumes for facility management companies operating multi-site portfolios.
Green floor care chemical systems for commercial facilities encompass neutral cleaners, strippers, sealers, polishes, and degreasers formulated with plant-derived surfactants, bio-based solvents, and pH-neutral buffering agents rather than petroleum-derived constituents, engineered to maintain vinyl composite tile, terrazzo, polished concrete, and rubber flooring without compromising indoor air quality metrics. Neutral cleaners and automated dispensing systems occupy the largest revenue pools due to daily maintenance frequencies in high-traffic office buildings and hospitality venues, while sealers and pre-measured packs represent the fastest-expanding segments as healthcare centers and educational institutions prioritize infection-control consistency and custodial staff safety.
EPA Safer Choice, EU Ecolabel, and state-level green procurement statutes in California and New York shape product registration requirements and restrict volatile organic compound thresholds for commercial floor care formulations sold through institutional channels. Facility management companies and cleaning contractors must now verify full material disclosure through platforms such as Health Product Declarations to qualify for public-sector contracts. Stakeholders should monitor emerging per- and polyfluoroalkyl substance restrictions and biobased content verification protocols, as these standards will determine which formulation chemistries retain market access across regulated procurement environments.
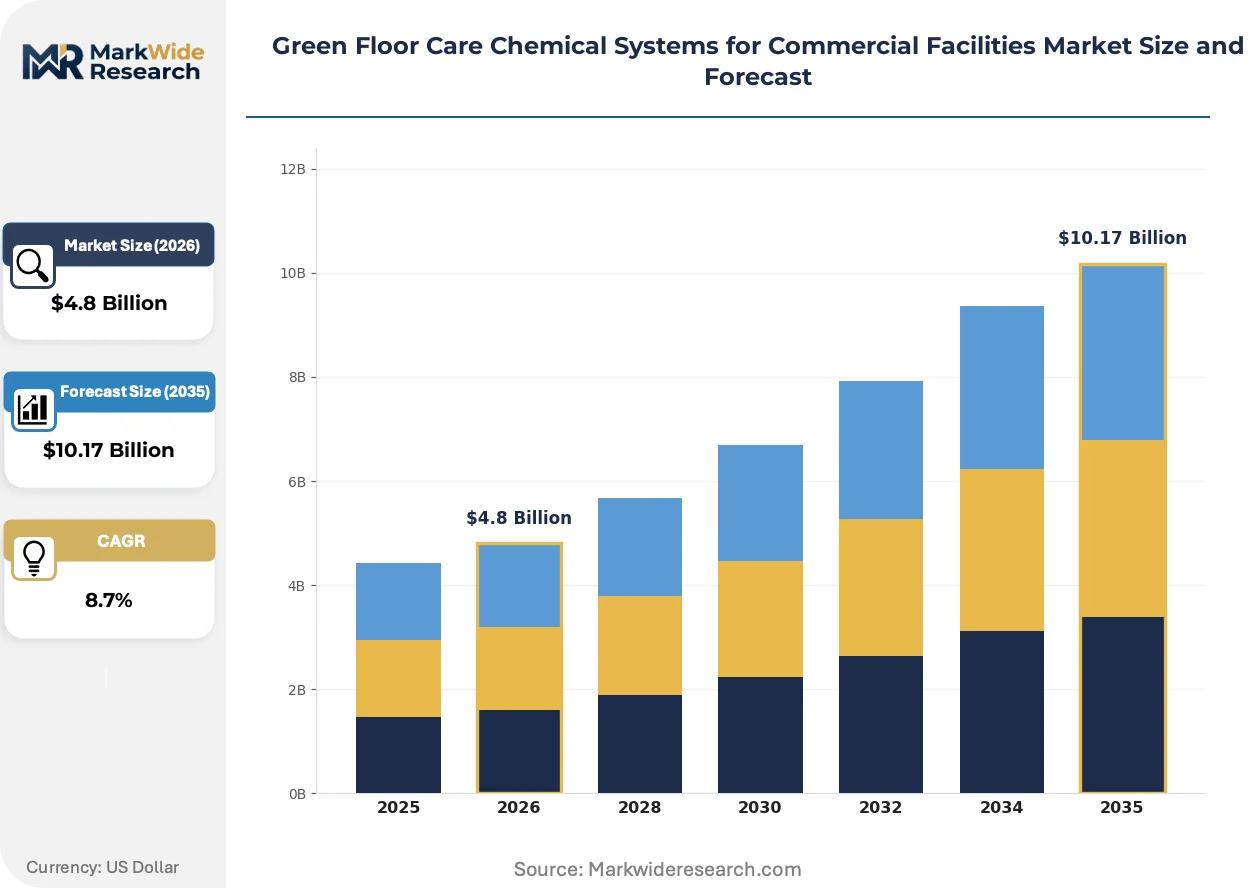
Market Dynamics
Third-party certification mandates from LEED v4.1 and the WELL Building Standard are compressing formulation choices toward bio-based chemistries that eliminate quaternary ammonium compounds and synthetic fragrances from commercial floor maintenance protocols.
Growth Catalysts
- EPA Safer Choice specifications:Federal procurement guidelines in the United States now require certified formulations for all federal facility maintenance contracts, pulling demand toward plant-derived surfactants and pH-neutral buffering agents.
- Healthcare infection-control protocols:Hospitals and long-term care facilities across Germany, France, and the United Kingdom are replacing petroleum-derived floor finishes with bio-based polymer alternatives that meet EU Ecolabel disclosure requirements.
- Automated dispensing integration:IoT-enabled dilution control systems in high-traffic office buildings and hospitality venues are bundling chemical delivery with real-time usage monitoring, locking in recurring neutral cleaner volumes.
Market Restraints
- Plant-derived surfactant supply concentration:Coconut and palm kernel oil feedstock processing clusters in Southeast Asia create input cost volatility and geographic concentration risk for bio-based formulation manufacturers.
- Performance parity gaps:Bio-based polymer finishes exhibit slower cure times and reduced durability on high-traffic rubber flooring compared to petroleum-derived acrylic alternatives, limiting adoption in airport and transit applications.
- EU Ecolabel registration friction:The European Commission's multi-stage dossier review process extends time-to-market by 12-18 months for novel bio-solvent formulations, compressing first-mover advantages.
Strategic Opportunities
- Pre-measured concentrated packs:Single-use water-soluble pods reduce packaging waste and shipping volumes for facility management companies operating multi-site portfolios across dispersed geographies.
- Educational institution green procurement:K-12 districts and university systems in California and New York are mandating Health Product Declaration verification for all custodial chemicals, creating tender advantages for full-disclosure suppliers.
- Per- and polyfluoroalkyl substance restrictions:Emerging state-level prohibitions on PFAS in commercial cleaning products are forcing reformulation of legacy stain-resistant floor sealers, opening substitution windows for bio-based alternatives.
Industry Challenges
- Green chemistry talent scarcity:Formulation chemists with expertise in bio-based polymer synthesis and accelerated biodegradation testing command premium compensation, constraining R&D expansion at mid-size manufacturers.
- Legacy dispensing system incompatibility:Existing dilution control infrastructure in aged commercial buildings requires retrofitting to handle concentrated bio-based chemistries with different viscosity profiles and shelf-stability characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Floor Care Chemical Systems for Commercial Facilities Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neutral Cleaners, Strippers, Sealers, Polishes, Degreasers, Conditioners Application: Office Buildings, Educational Institutions, Hospitality Venues, Healthcare Centers, Government Facilities, Airports End User: Facility Management Companies, Commercial Property Owners, Janitorial Services, Cleaning Contractors, Maintenance Teams Deployment: Manual Usage, Automated Dispensing, Bulk Supply, Pre-measured Packs, On-site Mixing |
| Companies Covered | Diversey, Ecolab, 3M, SC Johnson Professional, Betco, Spartan Chemical, Zep, P&G Professional, Unilever Professional, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Floor Care Chemical Systems for Commercial Facilities Market Trends and Innovations
Formulation science and delivery mechanisms are converging around modularity, certification transparency, and service bundling that redefines how commercial facilities procure and consume floor care chemistry.
Enzyme-based neutral cleaners are modularizing floor maintenance protocols by embedding targeted biocatalytic activity into daily cleaning regimens. Healthcare centers in the Netherlands and Denmark are piloting these formulations to reduce quaternary ammonium residue while maintaining infection-control standards. The technology is modularizing product portfolios, enabling suppliers to offer tiered performance levels through enzyme concentration adjustment rather than separate SKU proliferation.
REACH restrictions on persistent organic pollutants are forcing reformulation of floor strippers and degreasers across EU member states. The European Chemicals Agency's 2023-2024 substance evaluation roadmap specifically targets solvent alternatives with high volatility profiles used in commercial maintenance. German and French formulators are responding by accelerating bio-based solvent R&D partnerships with agricultural biotechnology suppliers.
Facility management companies are consolidating chemical purchasing through integrated service contracts that bundle product supply with equipment maintenance and staff training. This model displaces transactional distributor relationships in multi-site hospitality and corporate real estate portfolios. The shift is most visible in the United Kingdom, where ISS and Sodexo have established preferred supplier frameworks with full material disclosure requirements.
Green Floor Care Chemical Systems for Commercial Facilities Market Segmentation
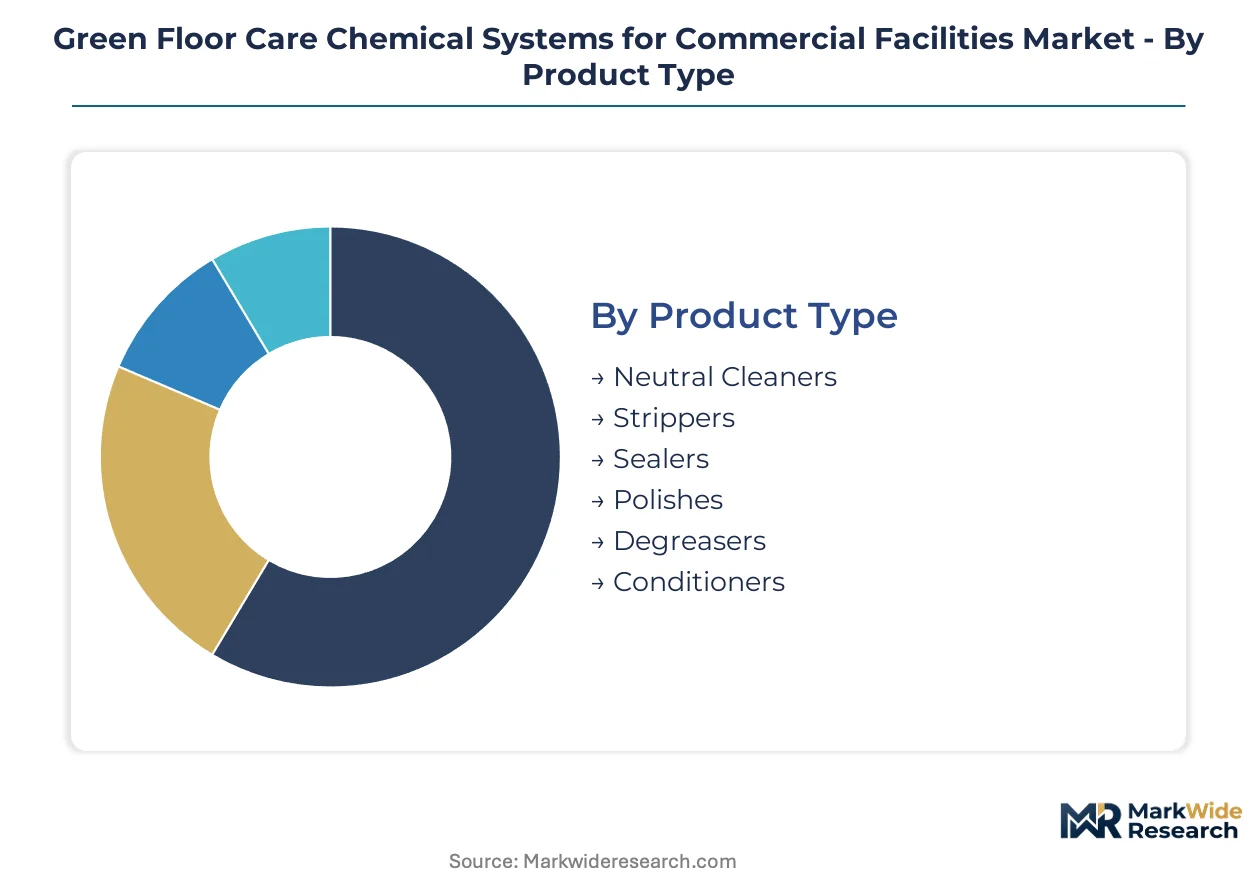
Segmentation in green floor care chemical systems reveals how procurement authority, usage intensity, and certification requirements reshape supplier strategies across commercial facility types. Understanding these divides exposes where bio-based formulations command price premiums versus where petroleum-derived alternatives retain residual share.
Product Type:
Buyers differentiate primarily by maintenance frequency and regulatory exposure—daily-use products face stricter indoor air quality scrutiny than periodic restoration chemicals.
- Neutral Cleaners:pH-balanced formulations with plant-derived surfactants and bio-based buffering agents maintain vinyl composite tile and polished concrete without quaternary ammonium residues. Daily deployment in high-traffic office buildings and hospitality venues across Germany and France concentrates procurement volumes around EPA Safer Choice and EU Ecolabel-certified variants.
- Sealers:Bio-based polymer finishes with accelerated biodegradation profiles protect terrazzo and rubber flooring substrates while meeting emerging per- and polyfluoroalkyl substance restrictions. Healthcare centers in the United Kingdom and the Netherlands are accelerating substitution of legacy stain-resistant formulations as Health Product Declaration verification becomes mandatory for public-sector tenders.
- Strippers:Solvent-based formulations remove accumulated finish layers from commercial flooring.
- Polishes:Restorative coatings restore gloss metrics on aged vinyl and linoleum surfaces.
- Degreasers:Heavy-duty formulations target petroleum and food-service residue in commercial kitchens.
- Conditioners:Maintenance additives extend polymer finish lifecycles between stripping cycles.
Neutral cleaners lead volumes today; sealers are gaining share fastest as PFAS prohibitions force reformulation across regulated procurement channels.
Application:
Facility type determines certification tier required—healthcare and education face mandatory disclosure rules that offices and hospitality have not yet adopted.
- Healthcare Centers:Hospitals and long-term care facilities demand bio-based polymer finishes with full material transparency through Health Product Declaration platforms. Infection-control protocols in France, Germany, and the United Kingdom now exclude quaternary ammonium compounds from floor maintenance regimens, consolidating procurement around enzyme-based neutral cleaners with biocatalytic residue reduction.
- Educational Institutions:K-12 districts and university systems in California and New York mandate EPA Safer Choice certification and full chemical disclosure for all custodial products. Pre-measured concentrated packs reduce packaging waste while ensuring dilution consistency across dispersed campus portfolios.
- Office Buildings:Corporate real estate prioritizes automated dispensing integration with IoT-enabled usage monitoring.
- Hospitality Venues:Hotels and conference centers balance guest-facing aesthetics with operational cost control.
- Government Facilities:Federal procurement guidelines in the United States require certified formulations for maintenance contracts.
- Airports:Transit hubs with rubber flooring and extreme traffic volumes prioritize durability over bio-content.
Healthcare centers anchor premium-tier demand; educational institutions show the steepest expansion trajectory as green procurement statutes proliferate.
End User:
Purchasing scale and technical capability separate integrated facility managers from fragmented contractor networks.
- Facility Management Companies:ISS, Sodexo, and similar multi-site operators consolidate chemical purchasing through integrated service contracts bundling product supply with equipment maintenance and staff training. These frameworks demand full material disclosure and prefer pre-measured packs that standardize outcomes across dispersed geographies.
- Janitorial Services:Regional cleaning contractors compete on price and face compressed margins that limit uptake of certified premium formulations.
- Commercial Property Owners:Single-asset or small-portfolio landlords prioritize first-cost minimization over lifecycle certification benefits.
- Cleaning Contractors:Transactional relationships with distributors dominate procurement for non-recurring restoration projects.
- Maintenance Teams:In-house custodial staff at universities and hospitals possess technical capacity for on-site dilution and equipment calibration.
Facility management companies command the largest contract values; janitorial services represent the most price-sensitive channel with slowest certified-product penetration.
Deployment:
Delivery mechanism determines concentration economics, packaging waste profiles, and compatibility with legacy infrastructure.
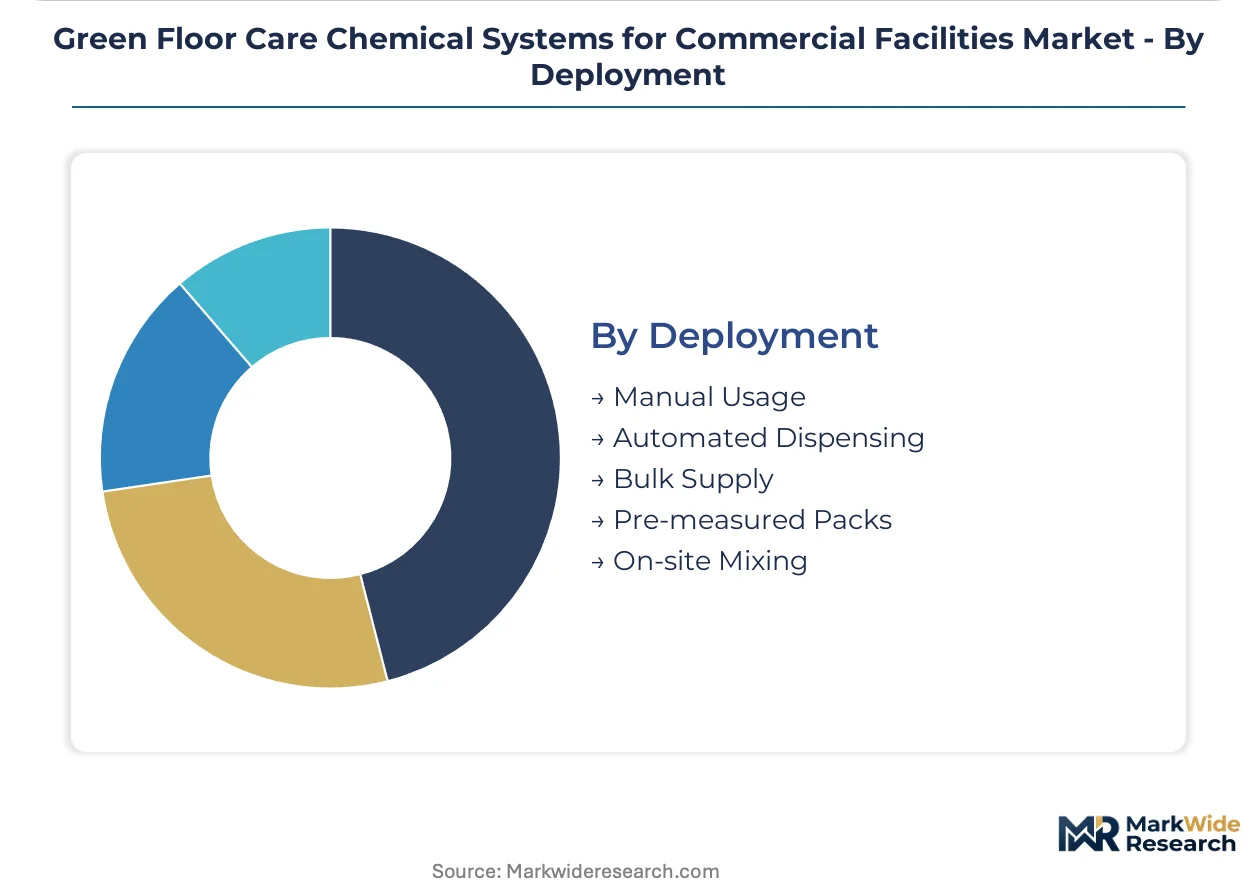
- Automated Dispensing:IoT-enabled dilution control systems in high-traffic office buildings and hospitality venues bundle chemical delivery with real-time usage monitoring, locking in recurring neutral cleaner volumes and reducing over-consumption. Ecolab anchors North American distribution through integrated water-and-energy service contracts leveraging this technology.
- Pre-measured Packs:Single-use water-soluble pods eliminate manual dilution errors and reduce shipping volumes for facility management companies operating multi-site portfolios. SC Johnson Professional differentiates through concentrated formats that cut packaging waste by substantial margins versus conventional ready-to-use alternatives.
- Manual Usage:Traditional dilution and application methods persist in aged commercial buildings with incompatible legacy infrastructure.
- Bulk Supply:Large-volume containers serve centralized custodial operations with dedicated storage and handling capabilities.
- On-site Mixing:Custom formulation blending for specialized restoration projects requiring variable solvent concentrations.
Automated dispensing dominates value capture today; pre-measured packs are climbing the fastest as sustainability metrics enter supplier scorecards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The commercial floor care chemical industry traces its modern regulatory foundations to post-war industrial hygiene movements in Germany and the United States, where occupational safety standards first linked cleaning product composition to indoor air quality metrics in institutional settings.
United States
Federal facility procurement through EPA Safer Choice specifications drives formulation demand toward plant-derived surfactants. California and New York state-level green procurement statutes mandate Health Product Declaration verification for public-sector custodial contracts. The Northeast Corridor corridor concentrates facility management company headquarters where integrated service contracts bundle chemical supply with IoT-enabled dispensing infrastructure.
Germany
Healthcare centers in Bavaria and North Rhine-Westphalia accelerate substitution of petroleum-derived floor finishes with bio-based polymer alternatives. REACH restrictions on persistent organic pollutants force reformulation of commercial strippers and degreasers through ECHA substance evaluation protocols. The Eindhoven-Ruhr industrial cluster hosts biotechnology R&D partnerships between agricultural feedstock processors and specialty chemical formulators.
France
Hospital infection-control protocols in Île-de-France and Auvergne-Rhône-Alpes exclude quaternary ammonium compounds from floor maintenance regimens. ANSM chemical disclosure requirements tighten procurement specifications for long-term care facilities under national healthcare modernization programs. The Lyon-Grenoble corridor anchors enzyme-based neutral cleaner pilot programs targeting biocatalytic residue reduction.
United Kingdom
NHS estates mandate EU Ecolabel-certified formulations for all new facility maintenance tenders across England and Scotland. ISS and Sodexo preferred supplier frameworks require full material disclosure through Health Product Declaration platforms. The Greater London area concentrates hospitality venue procurement where automated dispensing integration locks in recurring neutral cleaner volumes.
Netherlands
Healthcare centers in Amsterdam-Rotterdam-The Hague metropolitan zone pilot enzyme-based formulations to reduce quaternary ammonium residue while maintaining infection-control standards. National sustainable procurement guidelines align public-sector building maintenance with EU Green Deal chemical transparency objectives. The Port of Rotterdam cluster processes coconut and palm kernel oil feedstocks for bio-based surfactant manufacturing serving northwest European formulators.
Green Floor Care Chemical Systems for Commercial Facilities Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and service integration intensity. The market structures around three tiers: multinational chemical conglomerates with captive biotechnology R&D, mid-size specialty formulators with regional certification expertise, and private-label distributors competing on price. Consolidation pressures concentrate procurement volume through facility management company frameworks. Dominant competitive moves include strategic partnerships with agricultural biotechnology feedstock suppliers and backward integration into bio-based polymer synthesis capabilities.
Within the multinational tier, Diversey Holdings Ltd. and Ecolab Inc. exemplify divergent strategic positioning around service bundling versus product-centric distribution. Diversey anchors European healthcare sector penetration through biotechnology R&D investment. Ecolab occupies North American market presence through integrated water-and-energy service contract structures. SC Johnson Professional Inc. represents the concentrated-format specialist archetype, with pre-measured pack configurations targeting multi-site facility management standardization requirements.
| Leading Market Players |
|---|
| Diversey |
| Ecolab |
| 3M |
| SC Johnson Professional |
| Betco |
| Spartan Chemical |
| Zep |
| P&G Professional |
| Unilever Professional |
| Others |
Pricing and Supply Chain Analysis
Formulation chemists with bio-based polymer expertise cluster in the Eindhoven-Ruhr corridor, where labor-cost differentials between Dutch R&D hubs and German manufacturing zones widen pricing-tier spreads across premium-certified and commodity-grade floor care portfolios.
Pricing Analysis
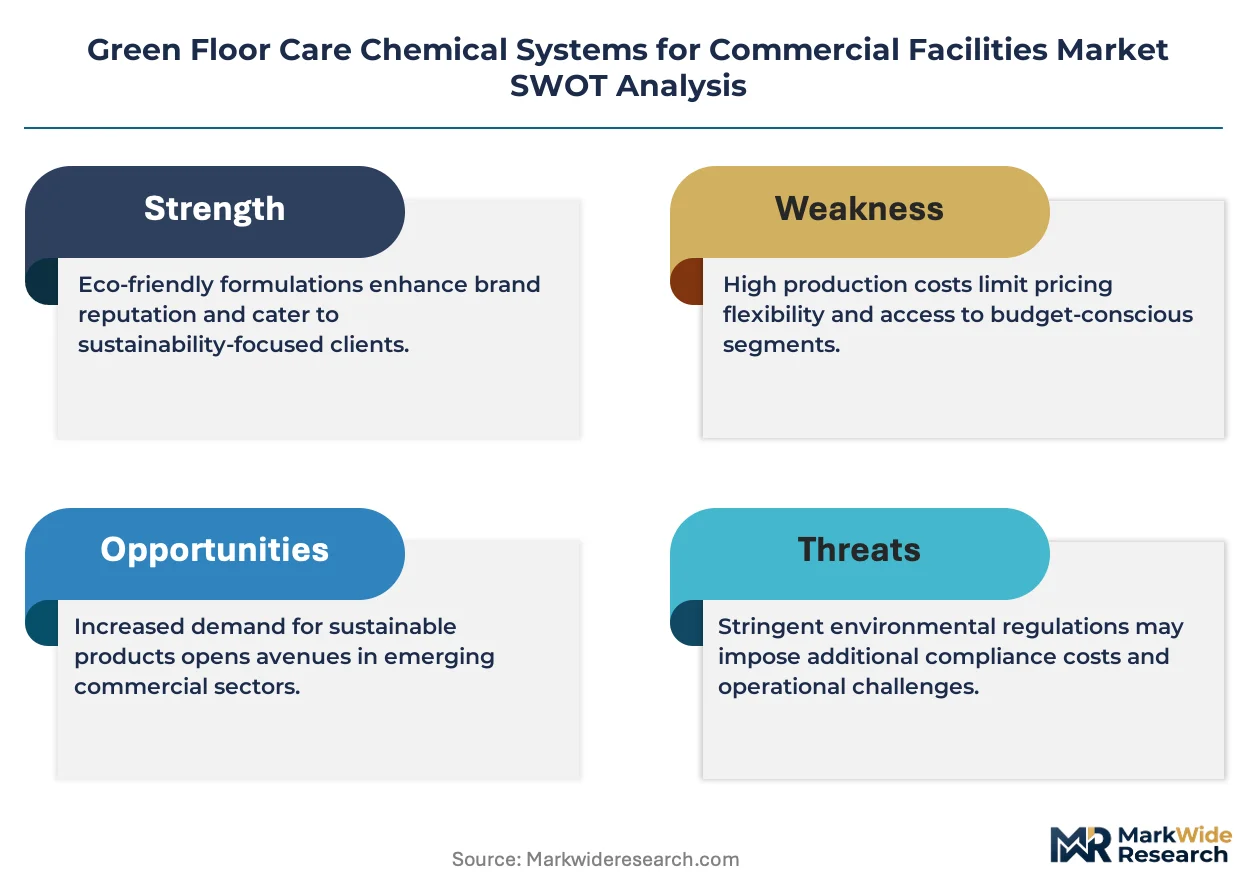
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification depth and service bundling intensity. Price differentiation hinges on EPA Safer Choice or EU Ecolabel verification and the inclusion of IoT-enabled dispensing infrastructure in contract terms. Cost compression in the economy tier is intensifying because janitorial services face margin pressure from facility management company consolidation. Healthcare centers demonstrate the lowest price sensitivity due to mandatory Health Product Declaration requirements, while regional cleaning contractors exhibit acute cost consciousness.
Supply Chain Analysis
Direct-to-facility management company channels handle multi-site contract demand through integrated service agreements bundling chemical supply with equipment maintenance. Feedstock supply concentrates in Indonesia, Malaysia, and the Philippines for coconut and palm kernel oil derivatives essential to plant-derived surfactant production. Raw material sourcing rests on agricultural biotechnology partnerships, bio-based solvent R&D pipelines, and concentrated pre-measured pack manufacturing. Single-source vulnerability in Southeast Asian oleochemical processing creates exposure to climate-induced harvest volatility and export restriction risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in certification-premium capture and concentrated-format logistics savings as bio-based feedstock costs stabilize relative to petroleum-derived alternatives.
For Market Incumbents: Deploy captive biotechnology R&D partnerships to accelerate bio-based polymer finish development ahead of emerging PFAS restrictions. Secure preferred supplier status with ISS, Sodexo, and similar facility management companies through full Health Product Declaration transparency. Defend against mid-size specialty formulators by locking in multi-year service contracts with IoT-enabled dispensing integration. For New Entrants and Emerging Players: REACH restrictions on persistent organic pollutants in EU member states open a window for bio-solvent stripper and degreaser formulations that bypass legacy petroleum chemistry. Target educational institutions in California and New York where green procurement statutes mandate EPA Safer Choice certification yet incumbent penetration remains incomplete. Pursue white-label partnerships with agricultural biotechnology feedstock suppliers to shortcut R&D timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-size specialty formulators with regional certification expertise but limited backward integration into bio-based polymer synthesis. Long-term viability favors suppliers with demonstrated EU Ecolabel registration success and established facility management company relationships. Monitor per- and polyfluoroalkyl substance prohibition timelines across U.S. states as the primary inflection indicator for substitution demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Polymer Synthesis | Captive production of accelerated biodegradation finishes reduces feedstock cost volatility for Ecolab and Diversey. |
| Pre-Measured Concentrated Pack Manufacturing Scale-Up | SC Johnson Professional's water-soluble pod expansion cuts shipping volumes for Sodexo multi-site portfolios. |
| EU Ecolabel Registration Acceleration | Compressed 12-18 month dossier timelines in Germany and France lock out slower competitors from healthcare tenders. |
| IoT-Enabled Dispensing Infrastructure Partnerships | Ecolab's integrated water-and-energy contracts anchor recurring neutral cleaner volumes in North American office buildings. |
| Agricultural Biotechnology Feedstock Alliance | Strategic partnerships with Indonesian and Malaysian oleochemical processors secure surfactant supply for bio-based formulation expansion. |
Research Methodology
Multiple input streams — primary interviews with formulation R&D directors, facility management company procurement leads, and janitorial services operators; secondary validation through EPA Safer Choice product registries, EU Ecolabel certified products databases, and SEC 10-K filings of listed chemical conglomerates — were reconciled through bottom-up volume modeling and top-down market sizing triangulation.
Data-stream reconciliation across product type, application, end user, and deployment mode dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectory analysis incorporating healthcare infection-control protocol shifts, educational institution green procurement mandate proliferation, and automated dispensing integration adoption curves as industry-specific forecast inputs.
Revisions become necessary when biobased feedstock supply disruptions, accelerated PFAS prohibition timelines, or facility management company consolidation waves materialize beyond base-case assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Surface Cleaning Products Market
Cleaning Chemicals
Mastic Remover Market
Cleaning Chemicals
Industrial Degreaser Market
Cleaning Chemicals
Fragrance-Free Cleaning Chemicals for Sensitive Environments Market
Cleaning Chemicals
Solar Component Cleaning Chemicals Market
Cleaning Chemicals
Instrument Detergents for Manual Cleaning Market
Cleaning Chemicals
Global Bleach Wipes Market
Cleaning Chemicals
Biodegradable Spray Tank Line-Cleaning Chemistry Market
Cleaning Chemicals
Dust Control Systems and Suppression Chemicals Market
Cleaning Chemicals
Commercial Cleaning Products Market
Cleaning Chemicals
Cleaning Products Market
Cleaning Chemicals
Cleaning Chemicals for Airports and Transport Hubs Market
Cleaning Chemicals
Global Antiseptic Products Market
Cleaning Chemicals
Lens Cleaning Product Market
Cleaning Chemicals
Eco-Label Certified Cleaning Chemicals for Professional Users Market
Cleaning Chemicals
Chlorinating Agents Market