

Acid Coil Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
Acid Coil Cleaner Market Insights
The acid coil cleaner category is decoupling into two distinct supply tiers: concentrated professional-grade formulations with corrosion inhibitors and pH buffering systems versus diluted retail-ready products with simplified labeling. Nu-Calgon leverages its HVAC-specialized distribution network to dominate the contractor channel. RectorSeal differentiates through foaming delivery systems that extend contact time on vertical coil surfaces. ComStar International anchors its position with phosphate-free formulations targeting regions with strict wastewater discharge rules.
Acid coil cleaners are low-pH chemical formulations, typically incorporating phosphoric, hydrochloric, or hydrofluoric acid blends with surfactants and corrosion inhibitors, designed to dissolve mineral scale, oxide deposits, and biological fouling from aluminum and copper heat transfer surfaces. Their primary purpose is restoring thermal efficiency in fin-and-tube heat exchangers without requiring mechanical disassembly. Liquid concentrates lead the product type landscape due to freight economics and dilution flexibility at point of use, while foaming spray forms represent the fastest-growing format as technicians prioritize vertical surface cling and reduced runoff. Data centers emerge as the highest-margin end user segment, driven by precision cooling uptime requirements and sensitivity to particulate contamination.
The US EPA regulates acid coil cleaner formulations under FIFRA pesticide device provisions and TSCA chemical reporting, while OSHA mandates hazard communication standards for contractor handling and storage. The EU REACH framework restricts certain acid blends and corrosion inhibitor chemistries, forcing reformulation for European market access. Buyers and suppliers must monitor the trajectory of state-level refrigerant phase-down schedules, as GWP-driven equipment replacement cycles will alter installed base ages and corresponding coil maintenance chemistries.
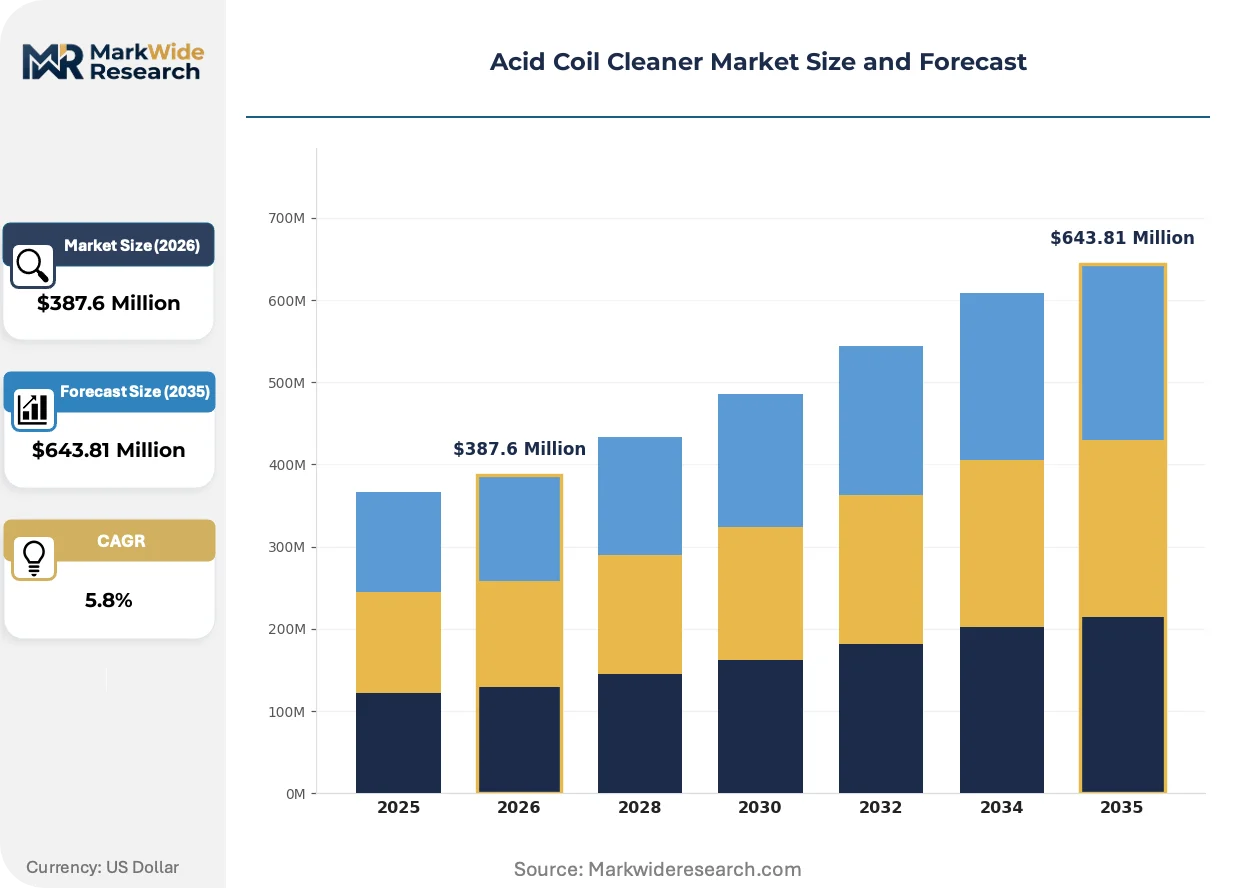
Market Dynamics
EPA refrigerant phase-down schedules are compressing equipment replacement cycles across commercial HVAC fleets, forcing recalibration of coil maintenance protocols and chemistry selection for aging versus new heat exchanger materials.
Growth Catalysts
- REACH chemical restrictions:European corrosion inhibitor bans are accelerating phosphate-free formulation development, opening export channels for compliant suppliers.
- Data center precision cooling:Hyperscale facilities demand zero-downtime coil maintenance, creating premium service contracts requiring specialized low-residue acid blends.
- Southeastern US humidity loads:Commercial cooling intensity in Florida, Georgia, and Texas generates concentrated coil fouling incidents requiring aggressive chemical remediation.
Market Restraints
- Aluminum price volatility:Raw material swings for fin stock compress margins on coil replacement versus cleaning decisions, limiting chemical attach rates.
- Hydrofluoric acid supply concentration:Three domestic producers control semiconductor-grade HF feedstock, creating bottleneck risk for high-performance cleaner formulations.
- OSHA hazard communication:Revised GHS labeling requirements increase compliance costs for diluted retail formats without contractor training infrastructure.
Strategic Opportunities
- India BIS certification expansion:Mandatory quality marks for HVAC chemicals create first-mover advantage for compliant international suppliers entering subcontinent distribution.
- IoT-enabled predictive maintenance:Sensor networks flag coil performance degradation before catastrophic fouling, scheduling preventive acid treatment rather than emergency response.
- EU F-Gas Regulation:High-GWP refrigerant bans accelerate natural refrigerant adoption, altering coil metallurgy and compatible cleaner chemistries.
Industry Challenges
- EPA FIFRA registration timelines:New active ingredient approvals stretch 18-36 months, delaying product pipeline commercialization against faster-moving competitors.
- Cross-contamination protocols:Facilities handling both food-grade and industrial HVAC systems require segregated chemical storage and technician certification tracks.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acid Coil Cleaner Market Trends and Innovations
Formulation chemistry and application methods are diverging sharply between contractor-grade concentrates and retail-ready formats, while regulatory pressure on refrigerants cascades into coil maintenance specifications.
Foaming delivery systems with extended vertical cling are automating technician labor allocation on rooftop and elevated coil arrays. Commercial service fleets adopt pressurized foam applicators to reduce repeat treatments on heavily fouled surfaces. The format shift is compressing per-job labor hours while elevating chemical consumption rates per maintenance event.
EPA Significant New Alternatives Policy reviews are tightening acceptable cleaner chemistries for systems transitioning to low-GWP refrigerants. Equipment manufacturers specify compatible maintenance chemicals to preserve warranty coverage on new installations. The policy friction most affects contractors servicing mixed-age building portfolios across refrigerant generations.
Facility managers bundle coil maintenance into comprehensive HVAC service agreements rather than standalone chemical purchases. National property management groups consolidate vendor relationships, displacing regional chemical distributors with direct manufacturer contracts. The procurement consolidation concentrates most visibly in Class A office portfolios and healthcare systems seeking standardized documentation for Joint Commission audits.
Acid Coil Cleaner Market Segmentation
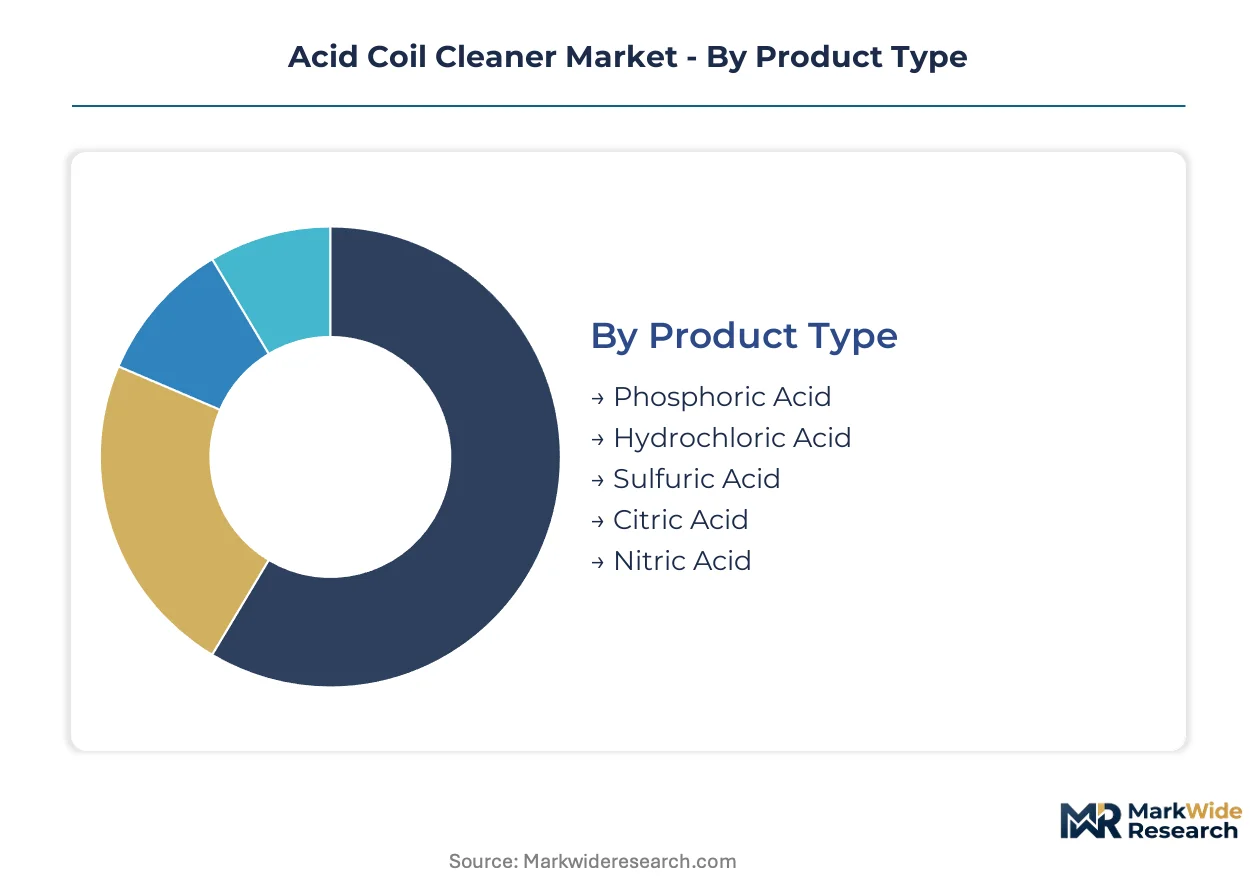
Equipment replacement cycles and refrigerant transitions are fragmenting demand across incompatible coil metallurgies and maintenance protocols. Segmentation clarity enables suppliers to match formulation chemistry with specific fouling profiles and regulatory constraints.
Product Type:
Upgrade cycles on aging HVAC fleets versus new low-GWP installations are splitting demand between aggressive mineral-dissolving acids and gentler buffered formulations compatible with advanced alloys.
- Phosphoric Acid:Buffered formulations with corrosion inhibitors dominate professional contractor channels for aluminum-copper fin-and-tube arrays. Demand concentrates in southeastern US commercial cooling infrastructure, where humidity-driven calcium scale accumulation requires repeated seasonal treatment.
- Hydrochloric Acid:High-strength formulations dissolve heavy oxide deposits on aged equipment, though supply concentration among three domestic semiconductor-grade feedstock producers creates formulation bottlenecks. Industrial plants with legacy carbon steel heat exchangers represent the core demand cluster.
- Sulfuric Acid:Cost-effective descaling for large-volume cooling tower applications where material compatibility permits aggressive chemistry.
- Citric Acid:Biodegradable option gaining traction in food-processing facilities with strict wastewater discharge monitoring.
- Nitric Acid:Specialized passivation treatments for stainless steel coil surfaces in pharmaceutical and semiconductor cleanroom environments.
Phosphoric acid sits at the top of the volume ranking, with citric acid climbing the fastest as phosphate-free mandates spread across watershed districts.
Form:
Cost tier differentiation separates bulk concentrate purchases by national service fleets from premium single-use formats for emergency response scenarios.
- Liquid:Freight economics and dilution flexibility at point of use anchor this format's dominance among HVAC maintenance contractors managing variable job scales. National property management groups specify liquid concentrates for standardized procurement across distributed building portfolios.
- Foam:Extended vertical cling reduces runoff on rooftop and elevated coil arrays, compressing per-job labor hours while elevating chemical consumption per treatment event. Foaming delivery systems are expanding most quickly in data center precision cooling contracts where downtime minimization justifies premium chemistry.
- Gel:Controlled contact time for delicate fin structures in heritage buildings and museums with irreplaceable equipment.
- Powder:Shelf-stable format for remote industrial sites with limited chemical storage infrastructure.
- Spray:Retail-ready packaging for facility manager self-service on minor fouling incidents between professional maintenance intervals.
Liquid commands the greatest shipment volumes, with foam gaining share fastest as labor rates outpace material costs in contractor economics.
Application:
Customer type specialization is driving formulation divergence between scheduled preventive maintenance programs and emergency restorative interventions.
- HVAC Systems:Seasonal cooling load intensity in Florida, Georgia, and Texas generates concentrated coil fouling incidents requiring aggressive chemical remediation on commercial rooftop units. EPA refrigerant phase-down schedules are forcing recalibration of maintenance protocols across mixed-age building portfolios.
- Data Centers:Hyperscale facilities demand zero-downtime coil maintenance with specialized low-residue acid blends, creating premium service contracts with documentation requirements for uptime guarantees. Precision cooling sensitivity to particulate contamination elevates chemistry specifications above standard commercial grades.
- Refrigeration Units:Cold chain infrastructure from food retail to pharmaceutical distribution requires compatible cleaners that won't compromise refrigerant purity.
- Heat Exchangers:Industrial process applications with heavy mineral scaling from hard water circulation loops.
- Air Handling Units:Healthcare and laboratory environments with combined particulate and biological fouling profiles.
HVAC systems anchor volume demand, with data center applications showing the steepest margin expansion trajectory.
End User:
Geography and maturity factors cluster demand in humid subtropical zones with intensive cooling loads and aging installed bases.
- Commercial Buildings:Class A office portfolios and retail chains consolidate vendor relationships, displacing regional chemical distributors with direct manufacturer contracts. Joint Commission audit documentation requirements in healthcare-adjacent properties standardize procurement specifications.
- Industrial Plants:Process cooling intensity and hard water exposure create predictable maintenance intervals with volume purchasing leverage. OSHA hazard communication mandates drive contractor certification requirements that favor established supplier relationships.
- Educational Institutions:Deferred maintenance backlogs and public procurement rules favor lowest-bid concentrate formats over performance-optimized formulations.
- Hospitality Venues:Guest comfort uptime requirements in resort and casino properties justify premium preventive service contracts.
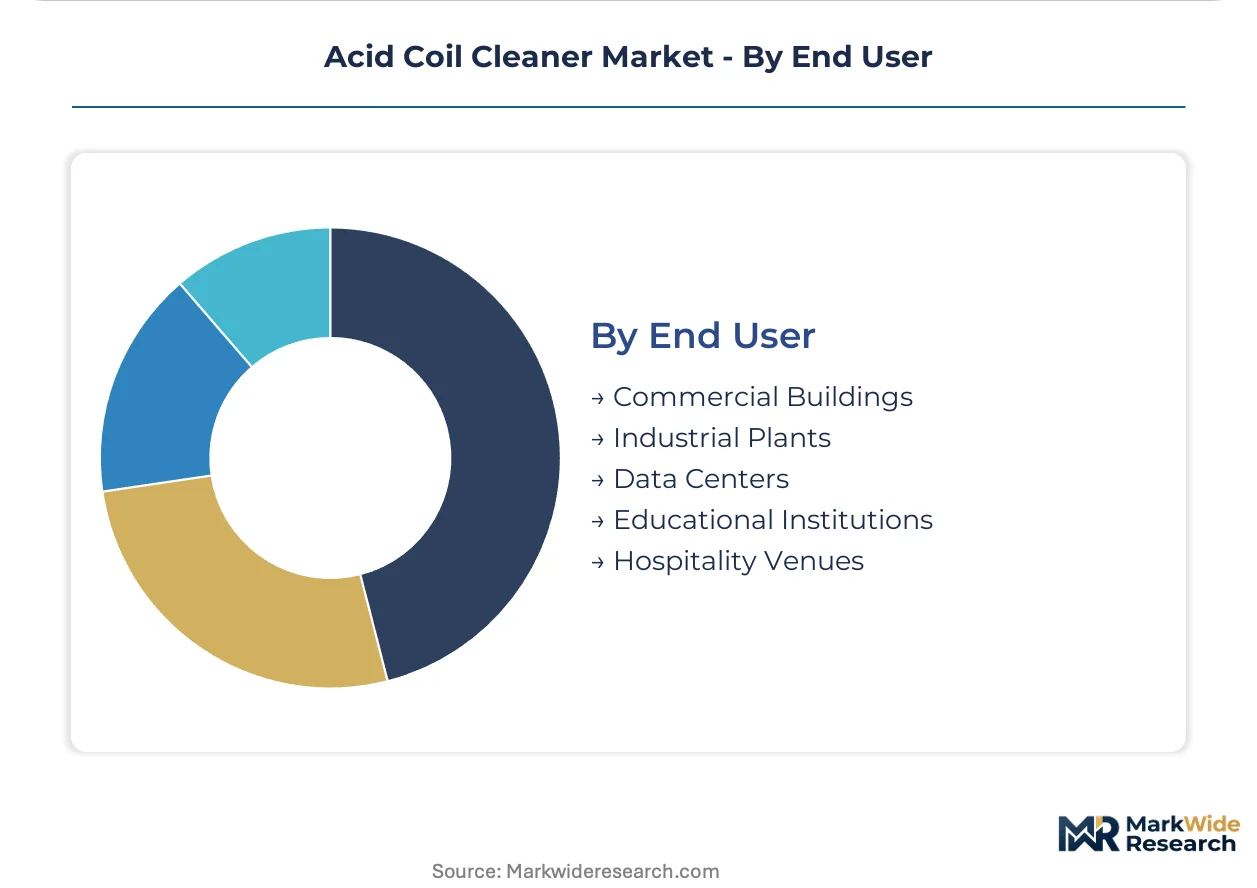
Commercial buildings generate the largest absolute demand, with data centers expanding most quickly as a distinct end-user category.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled HVAC technician pools concentrate in humid subtropical zones where cooling infrastructure density sustains year-round maintenance demand. These workforce clusters align with commercial building stock and data center development corridors.
United States
Southeastern commercial cooling intensity in Florida, Georgia, and Texas generates concentrated coil fouling incidents requiring aggressive chemical remediation. EPA refrigerant phase-down schedules under the Significant New Alternatives Policy force recalibration of maintenance protocols across mixed-age building portfolios. Houston and Atlanta anchor contractor service networks serving hyperscale data center clusters.
Germany
Industrial process cooling in the Rhine-Ruhr and Baden-Württemberg manufacturing belts sustains predictable maintenance intervals with volume purchasing leverage. EU F-Gas Regulation restrictions on high-GWP refrigerants accelerate natural refrigerant adoption, altering compatible cleaner chemistries. Munich and Frankfurt data center corridors demand specialized low-residue acid blends for precision cooling uptime.
India
Rapid commercial HVAC installation in Delhi-NCR and Maharashtra creates aftermarket service expansion as installed base ages. BIS mandatory quality marks for HVAC chemicals create first-mover advantage for compliant international suppliers entering subcontinent distribution. Bangalore and Hyderabad data center construction drives premium preventive maintenance contract growth.
China
Yangtze River Delta and Pearl River Delta manufacturing concentration generates industrial heat exchanger descaling demand at scale. NMPA and GB standards regulate chemical formulations for food-processing and pharmaceutical facilities with strict wastewater discharge monitoring. Shanghai and Shenzhen commercial building stock supports contractor-grade concentrate volumes.
Japan
Precision manufacturing in the Chubu region around Nagoya sustains demand for passivation treatments on stainless steel coil surfaces. METI energy-efficiency mandates tighten HVAC maintenance standards across commercial and industrial facilities. Tokyo-Osaka corridor data center density elevates chemistry specifications above standard commercial grades.
Acid Coil Cleaner Market Competitive Landscape
Capital-heavy producers compete with asset-light distributors across a bifurcated supply tier. The market structure consolidates around HVAC-specialized chemical formulators with captive distribution networks versus regional blenders serving price-sensitive maintenance contractors. Three strategic archetypes dominate: integrated formulator-distributors controlling contractor channels, foaming delivery system specialists, and phosphate-free formulation developers targeting watershed discharge restrictions. Competitive moves concentrate on distribution network expansion and formulation chemistry differentiation for emerging refrigerant compatibility requirements.
Within the integrated formulator-distributor tier, Nu-Calgon and RectorSeal exemplify channel control strategies. Nu-Calgon occupies a position representing HVAC-specialized distribution network dominance, while RectorSeal anchors the foaming delivery system specialization vector. ComStar International sits within the regulatory compliance tier, exemplifying phosphate-free formulation development for strict wastewater discharge markets.
| Leading Market Players |
|---|
| Nu-Calgon |
| Share Corporation |
| RectorSeal |
| ComStar International |
| Chemtex Speciality Limited |
| DiversiTech |
| Goodway Technologies |
| Vapco Products |
| Zep |
| Others |
Pricing and Supply Chain Analysis
Data center hyperscale procurement consolidation into direct manufacturer contracts forces supply chain reconfiguration toward bulk concentrate logistics and compresses margins on retail-diluted formats. National property management groups standardizing HVAC service specifications across distributed portfolios elevate freight economics and dilution flexibility as decisive cost variables.
Pricing Analysis
Bundled preventive maintenance contracts versus unbundled emergency chemical purchases split pricing structures across the contractor landscape. Three-tier pricing stratification separates premium low-residue formulations for precision cooling uptime guarantees from standard phosphoric acid concentrates and economy-grade hydrochloric blends for legacy equipment. Price differentiation hinges on corrosion inhibitor sophistication and EPA FIFRA registration tier, with data center operators showing lowest price sensitivity and educational institutions under public procurement rules exhibiting highest. Pricing pressure intensifies in retail-ready spray formats as OSHA GHS labeling compliance costs accumulate without contractor training infrastructure to absorb them.
Supply Chain Analysis
Freight economics favor concentrated liquid formulations shipped from domestic blending facilities in Texas, Georgia, and Ohio over diluted ready-to-use products with higher weight-to-active ratios. Hydrofluoric acid feedstock draws from three domestic semiconductor-grade producers, creating single-source vulnerability for high-performance cleaner formulations. Phosphoric acid and surfactant inputs rest on agricultural and petrochemical supply chains concentrated in the Gulf Coast and Midwest. Distribution runs through HVAC-specialized wholesalers with captive contractor relationships, displacing regional chemical distributors in national account procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acid coil cleaner market functions as a stable compounder anchored by irreversible HVAC installed base expansion and non-discretionary maintenance requirements driven by energy-efficiency mandates.
For Market Incumbents: Cement channel control through exclusive distribution agreements with national service fleets before property management procurement consolidation accelerates. Deepen backward integration into corrosion inhibitor chemistry to offset hydrofluoric acid feedstock concentration risk. Prioritize phosphate-free formulation R&D to capture export channels as EU REACH restrictions and US watershed discharge rules tighten. For New Entrants and Emerging Players: Capture India BIS certification first-mover advantage as mandatory quality marks reshape subcontinent distribution. Target data center precision cooling segments with specialized low-residue acid blends where incumbent HVAC-specialized players lack cleanroom chemistry expertise. Lead with IoT-enabled predictive maintenance partnerships to bypass entrenched wholesale channel relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with phosphate-free formulation developers holding compliant chemistry portfolios for watershed-restricted markets. Five-to-ten year viability favors suppliers with EPA FIFRA registration infrastructure and established contractor certification programs. Monitor state-level refrigerant phase-down acceleration as signal for equipment replacement cycle inflection and corresponding coil metallurgy shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corrosion Inhibitor Chemistry | Reduces dependence on concentrated HF feedstock suppliers and secures margin control. |
| Phosphate-Free Formulation Development | Opens EU REACH-compliant export channels and US watershed district access. |
| IoT-Enabled Predictive Maintenance Partnerships | Converts emergency chemical sales into recurring preventive service contracts. |
| India BIS Certification Acquisition | Creates regulatory moat for subcontinent distribution before competitor compliance. |
| Direct Manufacturer Contracts with National Property Managers | Displaces regional distributors in Class A office and healthcare consolidation. |
Research Methodology
Bottom-up HVAC maintenance contractor modeling reconciled against top-down chemical manufacturer shipment tracking forms the analytical core. Primary interviews with plant engineers, national service fleet procurement directors, wholesale distribution channel partners, and EPA regulatory affairs specialists combined with secondary validation from ACC chemical trade data, SEC 10-K filings of listed HVAC chemical suppliers, customs import records, and state-level refrigerant phase-down schedule documentation. Triangulation across these sources ensures segmentation integrity.
Input-output matrices connect end-use application demand with product-form supply capacity across the projection horizon. Segmentation dimensions modeled include acid type chemistry, concentrate versus ready-to-use format, application equipment category, and end-user vertical with regional regulatory cluster overlay. CAGRs derive from installed base aging curves, replacement cycle compression under EPA Significant New Alternatives Policy, and labor cost escalation driving foaming format adoption. Forecast inputs incorporate humidity-driven fouling intensity indices and data center construction permitting data.
Aluminum price volatility, hydrofluoric acid supply disruption, and refrigerant transition schedule acceleration are the dominant revision risks. Forecasts reflect assumptions about maintenance protocol continuity and regulatory enforcement consistency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.