
 Pinch Grip Jars Market | 2026-2036
Pinch Grip Jars Market Size, Share, and Industry Trends Forecast 2026-2036
Pinch Grip Jars Market Analytics
Food storage applications are pivoting toward ergonomic, reusable container solutions as meal-prep culture and bulk purchasing expand across consumer segments. Amcor Plc leverages its global manufacturing footprint to supply food-grade pinch grip formats at scale. Berry Global Group anchors North American distribution through extensive retail partnerships. Dongguan Fukang Plastic Products Co. Ltd competes on cost-efficient injection molding capacity serving export markets.
Pinch grip jars are cylindrical or rounded containers featuring indented side panels that enable secure finger grasping, typically manufactured through injection molding, blow molding, or glass-forming processes with wall thicknesses optimized for stackability and drop resistance. Their primary purpose centers on secure, user-friendly storage and transport of consumable and non-consumable goods across household and commercial settings. Plastic material formats dominate volume production due to lightweight properties and design flexibility, while glass variants command premium positioning in artisan food and cosmetic segments. Medium and large sizes capture the bulk of unit demand as consumers prioritize versatile capacity for pantry and refrigerator organization.
FDA food-contact regulations govern material safety and migration limits for plastic and glass containers distributed in the United States, while the EU Packaging and Packaging Waste Directive shapes recyclability mandates across European supply chains. ISO 9001 quality management standards influence manufacturing consistency for exporters serving multiple jurisdictions. Stakeholders must monitor evolving extended producer responsibility frameworks and recycled content thresholds that will determine which material technologies and regional production bases retain cost-competitive access to key consumer markets.
Market Dynamics
Post-consumer recycled content mandates across Germany, the United States, and Japan are forcing material requalification throughout pinch grip jar supply chains. FDA migration limits and EU Packaging and Packaging Waste Directive recyclability thresholds now determine which resin formulations retain commercial viability in major consumer markets.
Growth Catalysts
- Meal-prep culture expansion:Bulk purchasing behaviors in United States and Japanese households drive repeat procurement of stackable, refrigerator-optimized containers with ergonomic handling features.
- REACH-compliant rPET advances:European recyclability mandates accelerate adoption of food-grade recycled polyethylene terephthalate with certified migration performance for direct food contact.
- Artisan food segment premiumization:Small-batch producers in Germany and France command price premiums for glass pinch grip formats with tactile surface finishes and heritage aesthetic positioning.
Market Restraints
- Resin cost volatility:Polypropylene and PET feedstock prices fluctuate with crude oil derivatives, compressing margins for injection molders serving price-sensitive export markets.
- Single-source tooling concentration:Precision pinch grip mold fabrication concentrates among specialized toolmakers in Dongguan and Stuttgart, creating supply bottlenecks during capacity expansions.
- Glass weight penalty:Transportation cost differentials versus plastic alternatives limit glass format distribution radius to premium regional markets.
Strategic Opportunities
- Indian organized retail penetration:Reliance Retail and D-Mart expansion creates first-mover advantage for ergonomic storage formats in emerging middle-class household segments.
- Pharmaceutical compliance packaging:Child-resistant pinch grip closures meeting ISO 8317 standards open prescription and over-the-counter medication applications.
- Closed-loop retail takeback programs:Extended producer responsibility frameworks in California and France incentivize durable container leasing models with deposit-return infrastructure.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous FDA food-contact notification and EU 10/2011 compliance testing extends product launch cycles by eight to fourteen months.
- Legacy injection equipment retrofit costs:Converting standard cylindrical jar tooling to integrated pinch grip geometry requires substantial mold base modifications and hot runner reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pinch Grip Jars Market |
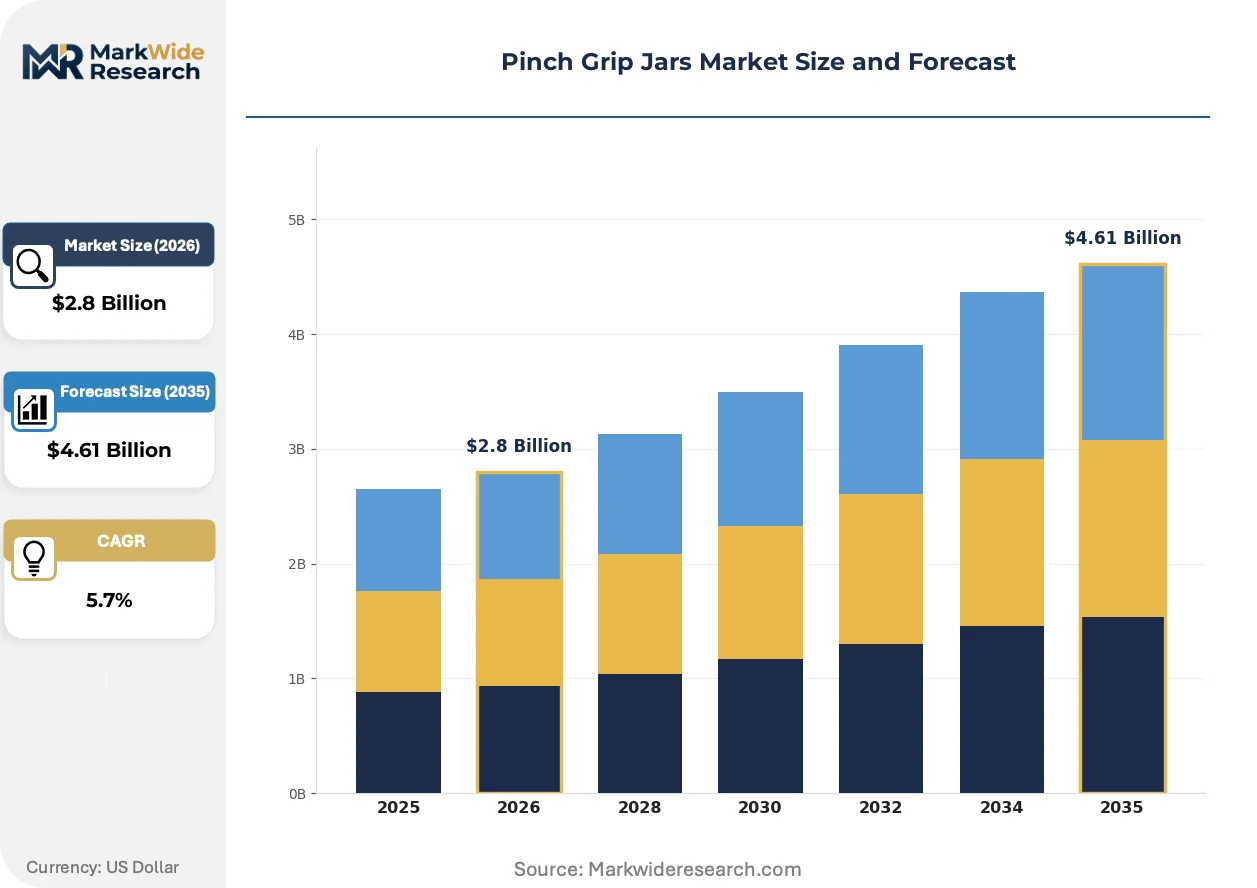
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Glass, Plastic, Metal, Ceramic Application: Food Storage, Kitchen Use, Crafting, Laboratory Size: Small, Medium, Large, Extra Large Closure Type: Screw Top, Snap Lid, Cork, Hinged Lid |
| Companies Covered | Priority Plastics, United States Plastic Corporation, Price Containers, MJS Packaging, Plascene, The Cary Company, Amcor Plc, Berry Global Group, Dongguan Fukang Plastic Products Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pinch Grip Jars Market Evolving Landscape
Material science advances and regulatory stringency are compressing the viable technology set for pinch grip jar production. Three converging developments determine competitive positioning.
Thin-wall injection molding with in-mold labeling is consolidating manufacturing economics for medium-volume food service applications. QSR chains and contract food manufacturers in the United States adopt these formats for sauce and condiment portion control. The technology is consolidating regional supplier bases by eliminating secondary decoration steps and reducing per-unit handling costs.
EU Packaging and Packaging Waste Directive recyclability performance grades are reshaping resin selection protocols. Minimum recycled content thresholds scheduled for implementation across France, Italy, and Spain force reformulation of opaque and tinted containers. German retailers now require third-party recyclability certification for private-label pantry storage lines, shifting procurement toward transparent, mono-material constructions.
Direct-to-consumer subscription pantry services are altering volume and mix requirements. Meal kit operators and bulk ingredient retailers in Japan and the United States specify uniform diameter ranges across multiple capacities to optimize warehouse rack density and last-mile packaging efficiency. This standardization pressure favors suppliers with modular mold programs and rapid changeover capabilities.
Pinch Grip Jars Market Segmentation
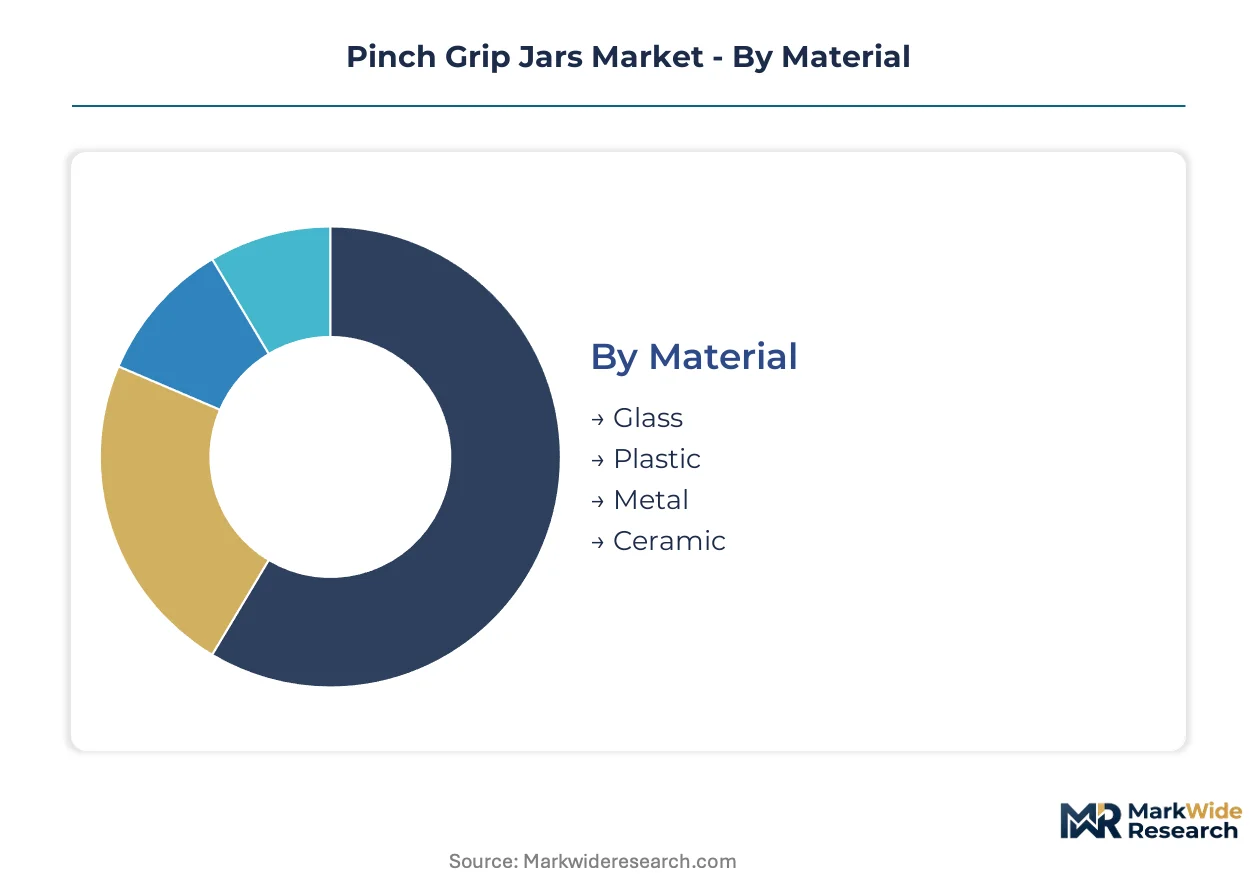
Pinch grip jar procurement patterns diverge sharply across material grades and functional specifications. Manufacturers align production configurations against distinct margin profiles and certification requirements within each segment cluster.
Material:
Standardization pressure from recyclability mandates compresses differentiation at the commodity end, while premium tiers retain customization latitude through surface engineering and heritage positioning.
- Glass:Soda-lime and borosilicate formulations with tactile surface finishes dominate artisan food and cosmetic applications in Germany and France. FDA migration testing and EU 10/2011 compliance extend qualification timelines, concentrating procurement among established European molders with in-house laboratory capacity.
- Plastic:Polypropylene and PET variants optimized for thin-wall injection molding capture bulk food service volume across United States QSR chains. REACH-compliant rPET advances from ECHA-registered recyclers are displacing virgin resin in private-label pantry lines bound for German and French retailers.
- Metal:Tinplate and aluminum formats with rolled-thread neck finishes serve specialty tea and spice segments requiring oxygen barrier performance.
- Ceramic:Glazed stoneware with silicone gasket interfaces occupies premium home organization niches in Japanese department store channels.
Most installed capacity flows through Plastic. Expansion is steepest in Glass.
Application:
Volume concentration tilts toward repeat-purchase household segments, while commercial applications impose stricter lot traceability and dimensional tolerance requirements.
- Food Storage:Refrigerator-optimized stackable formats with ergonomic handling features dominate United States and Japanese household procurement. Meal-prep culture expansion drives repeat orders for uniform-diameter ranges across multiple capacities.
- Kitchen Use:Countertop-accessible pinch grip profiles with wide-mouth apertures concentrate demand in German kitchenware specialty retailers emphasizing tactile ergonomics.
- Crafting:Opaque and tinted containers for bead and supply organization face reformulation pressure from EU Packaging and Packaging Waste Directive recyclability grades.
- Laboratory:Autoclavable borosilicate formats with graduated markings serve academic and industrial research institutions requiring ISO 9001-documented dimensional consistency.
Procurement volume concentrates in Food Storage. Kitchen Use is gaining share fastest.
Size:
Production economics favor mid-range capacities where mold utilization rates and material efficiency ratios optimize per-unit contribution margins.
- Medium:500ml to 1.5L capacities with standardized diameters capture the bulk of pantry and refrigerator organization demand across United States and German retail channels. Modular warehouse rack density requirements from direct-to-consumer subscription services reinforce specification convergence.
- Large:2L to 4L formats with reinforced pinch grip geometry serve bulk ingredient retailers and food service prep operations in Japan and the United States.
- Small:Sub-250ml portion control formats concentrate in condiment and sauce applications for United States QSR chains.
- Extra Large:Above-4L capacities with double-wall construction occupy commercial food storage and institutional kitchen niches with specialized logistics handling.
Mold utilization peaks in Medium. Steepest capacity additions target Large.
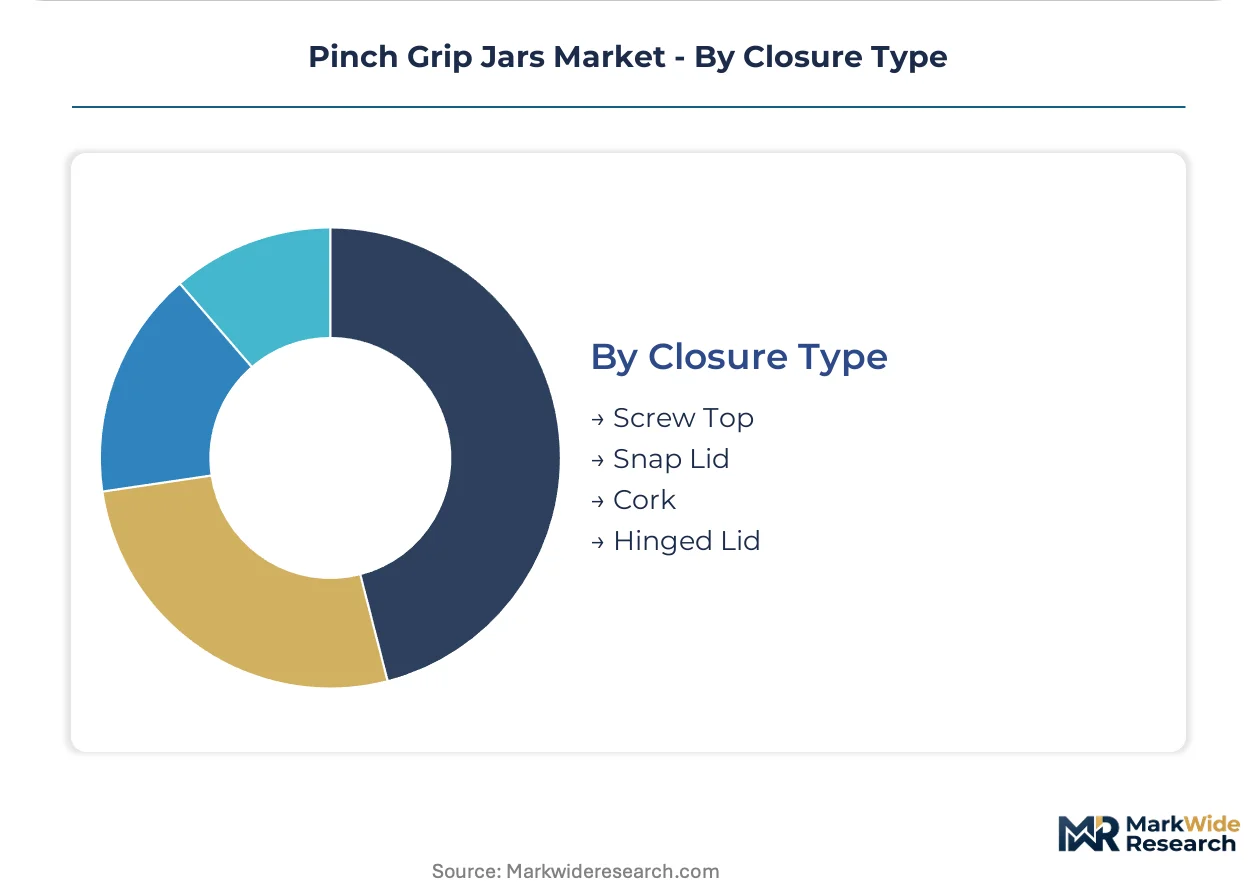
Closure Type:
Child-resistance and hermetic performance specifications are fragmenting procurement requirements across pharmaceutical, food, and cosmetic end-uses.
- Screw Top:Continuous-thread HDPE and PP closures with induction heat-seal liners dominate food storage applications requiring resealability. ISO 8317-compliant child-resistant variants open prescription medication packaging opportunities.
- Snap Lid:Polypropylene overmolded gasket designs with audible closure confirmation concentrate in meal-prep and refrigerator organization segments across United States and Japanese households.
- Cork:Natural and synthetic stopper formats with neck compression seals preserve artisan food and wine positioning in French and Italian specialty retail.
- Hinged Lid:Integral polypropylene living-hinge designs serve condiment portion control and food service dispensing applications with single-hand operation requirements.
Tooling concentration is tightest in Screw Top. Snap Lid is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing production maps as manufacturers relocate molding capacity to jurisdictions with lower compliance burdens while maintaining export access to premium consumer markets.
United States
Meal-prep subscription services and bulk ingredient retailers drive repeat procurement of stackable refrigerator formats. FDA food-contact notification requirements govern resin qualification timelines for direct food-contact applications. Michigan and Ohio tooling clusters host precision mold fabricators serving QSR condiment packaging contracts.
Germany
Private-label pantry storage lines from Aldi and REWE emphasize ergonomic handling features for organized kitchen segments. EU Packaging and Packaging Waste Directive recyclability grades mandate third-party certification for shelf placement. Stuttgart-area moldmakers concentrate fabrication of complex pinch grip geometries for artisan food glass formats.
Japan
Department store channels and specialty kitchenware retailers prioritize tactile surface finishes for countertop-accessible storage. METI circular economy guidelines shape post-consumer recycled content targets for domestic distribution. Osaka-based injection molders optimize thin-wall production for uniform-diameter subscription pantry specifications.
China
Export-oriented fabricators in Dongguan supply cost-optimized injection molding capacity for North American and European private-label programs. GB standards for food-contact plastics govern domestic market entry while export production follows customer-mandated certification protocols. Pearl River Delta logistics hubs enable containerized shipment of finished goods to trans-Pacific distribution centers.
India
Reliance Retail and D-Mart expansion into organized grocery creates first-mover opportunities for ergonomic storage formats in emerging middle-class households. FSSAI food-contact regulations establish baseline safety requirements for domestic plastic container distribution. Gujarat petrochemical corridors supply virgin polypropylene feedstock to injection molding operations serving export and domestic demand.
Pinch Grip Jars Market Competitive Landscape
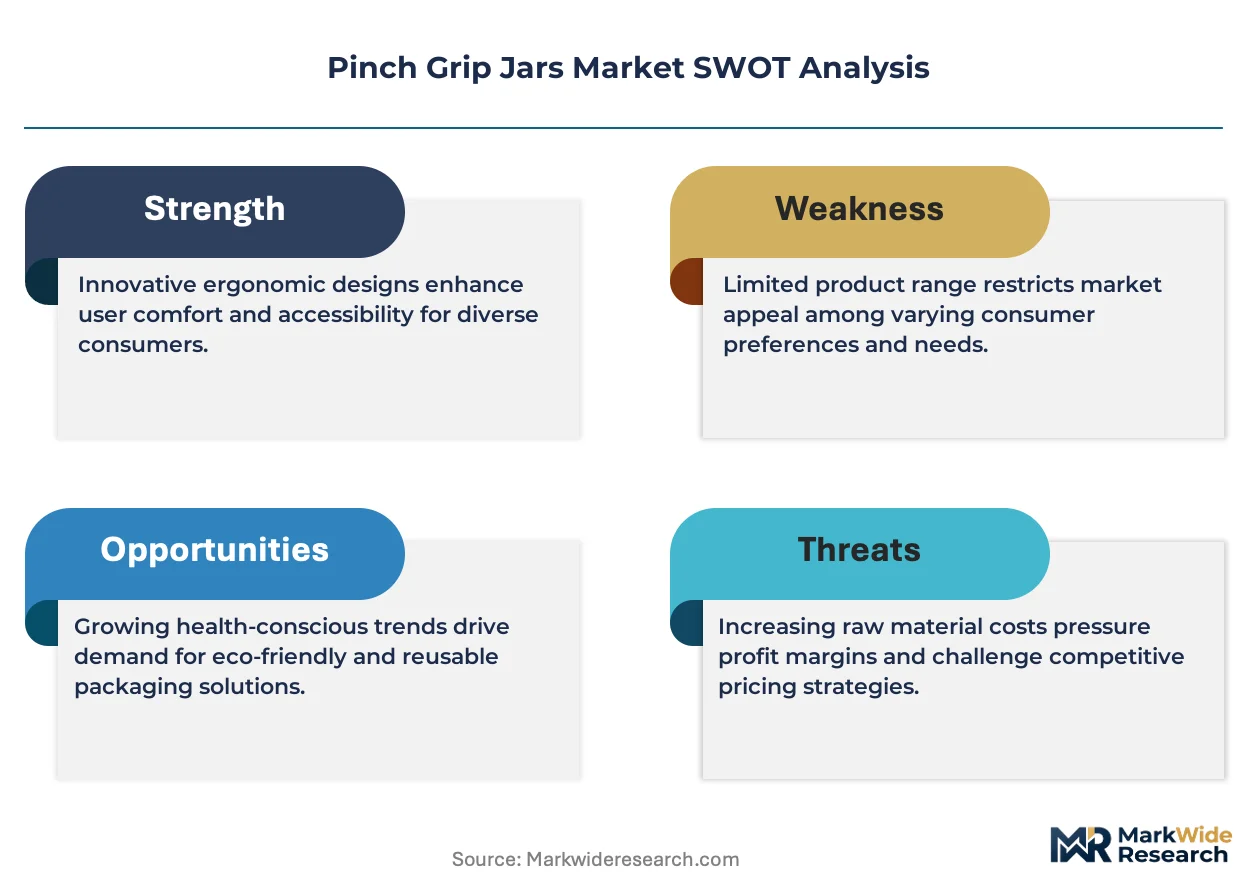
Capacity expansion dominates the current landscape as incumbent suppliers retrofit legacy cylindrical jar tooling to integrated pinch grip geometries. The vendor base separates into three discernible tiers: multinational packaging conglomerates with global manufacturing footprints, regional specialists with dedicated food-grade certification capabilities, and cost-focused export fabricators concentrated in Asian manufacturing clusters. Strategic archetypes include scale-driven resin integrators, compliance-focused certification specialists, and flexible molders serving private-label programs. Portfolio diversification into pharmaceutical-compliant closures and geographic expansion through distributor partnerships represent the two most visible competitive vectors.
Among North American-based suppliers, United States Plastic Corporation and The Cary Company occupy positions within the distribution-focused tier, leveraging extensive catalog breadth and rapid fulfillment infrastructure to serve contract food manufacturers and institutional buyers. Dongguan Fukang Plastic Products Co. Ltd exemplifies the export-specialist archetype, anchoring cost-efficient production capacity serving price-sensitive international procurement programs. Amcor Plc and Berry Global Group represent the multinational resin-integrator segment, maintaining food-grade manufacturing scale across multiple jurisdictions to meet divergent regional compliance requirements.
| Leading Market Players |
|---|
| Priority Plastics |
| United States Plastic Corporation |
| Price Containers |
| MJS Packaging |
| Plascene |
| The Cary Company |
| Amcor Plc |
| Berry Global Group |
| Dongguan Fukang Plastic Products Co. Ltd |
| Others |
Value Network & Pricing Analysis
QSR chain procurement concentration in the United States enforces contract-based long-term offtake pricing with volume-scaled discounts, while German private-label pantry buyers negotiate on recyclability certification tiers rather than unit cost alone.
Pricing Analysis
Distributor margins compress as much as 18-22 points between factory gate and retail shelf across North American food service channels. Three-tier pricing structure across premium, standard, and economy levels separates FDA food-contact certified glass formats from commodity polypropylene injection-molded units and unlabeled export-grade containers. Cost compression in virgin PET feedstock is intensifying because crude oil derivative volatility, squeezing margin contribution for molders without backward integration into resin supply. Price-sensitive export fabricators in Dongguan face the steepest margin pressure, while artisan food producers in France absorb premium glass pricing with minimal elasticity.
Supply Chain Analysis
Dual-sourcing requirements from United States meal-prep subscription services mandate parallel qualification of Dongguan injection molders and Stuttgart-area precision toolmakers to mitigate single-source vulnerability. Raw material dependencies rest on polypropylene feedstock from Gujarat petrochemical corridors, soda-lime glass batch from German industrial minerals processors, and REACH-compliant rPET from ECHA-registered European recyclers. Tariff exposure on Chinese-molded components entering North American distribution channels threatens cost structures for private-label programs. Distribution runs through Pearl River Delta container terminals for trans-Pacific shipment, with European artisan formats moving via Rotterdam consolidation hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where meal-prep culture and bulk purchasing behaviors in United States and Japanese households shift procurement toward ergonomic, refrigerator-optimized specifications with certified migration performance.
For Market Incumbents: Deploy modular mold program investments to capture direct-to-consumer subscription pantry standardization requirements. Retrofit legacy cylindrical jar tooling to integrated pinch grip geometries before REACH-compliant rPET mandates disqualify opaque virgin resin formulations. Capacity addition in Ohio and Michigan tooling clusters defends position against Dongguan cost competition for QSR condiment contracts. For New Entrants and Emerging Players: EU Packaging and Packaging Waste Directive recyclability grades in France and Germany open a window for transparent mono-material construction specialists with third-party certification capabilities. Target Indian organized retail expansion through Reliance Retail and D-Mart private-label programs as the most penetrable geography. Pursue pharmaceutical-compliant child-resistant closure development meeting ISO 8317 standards as the differentiated go-to-market angle. For Investors and Strategic Acquirers: Packaging conglomerates with food-grade manufacturing footprints across multiple jurisdictions are the most active acquirer in this space, consolidating regional specialists with dedicated certification capabilities. Acquisition target archetype centers on European molders with in-house FDA and EU 10/2011 testing laboratories and established artisan food channel relationships. Signal to monitor: California extended producer responsibility framework implementation triggering deposit-return infrastructure investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Recycling | ECHA-registered recyclers gain preferential access to German and French private-label procurement. |
| Modular Mold Program Investment | Osaka-based thin-wall specialists capture subscription pantry standardization requirements from Japanese meal-kit operators. |
| Pharmaceutical Compliance Certification | ISO 8317 child-resistant closure qualification opens prescription medication packaging applications. |
| Direct-to-Consumer Channel Expansion | United States meal-prep subscription services demand uniform-diameter ranges across multiple capacities. |
| Recyclability Repositioning | Transparent mono-material constructions displace opaque tinted containers under EU Packaging Directive grades. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured plant managers at Dongguan injection molding operations, procurement leads at United States QSR chains, category buyers at German Aldi and REWE, and technical R&D directors at European glass molders. Secondary validation drew from FDA food-contact notification databases, EU 10/2011 compliance registries, ECHA REACH substance registrations, and customs trade data for polypropylene container shipments. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates.
Segment-weighting across material grade, application function, capacity tier, closure specification, and regional regulatory cluster determined value distribution throughout the projection horizon. CAGRs derived from fitted growth curves against historical procurement patterns and policy implementation schedules. Industry-specific forecast inputs included meal-prep subscription service expansion rates and EU Packaging Directive recycled content threshold phase-ins.
Forecast precision tightens around the base case; tail outcomes carry wider variance under resin cost volatility and tariff regime shifts. Deviation in FDA migration limit enforcement stringency or ECHA rPET registration timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
EMEA Container Technology Market
Containers
Canning Jars Market
Containers
Global Flexitanks Market
Containers
Durable Insulated Containers Market
Containers
Hinged Lid Compostable Container Market
Containers
HDPE Containers Market
Containers
Child-Resistant Containers Market
Containers
North America Insulated Shipping Containers Market
Containers
Europe Plastic Bottles and Containers Market
Containers
Metal IBC Market
Containers
Shipping Container Liners Market
Containers
Flexible Water Tanks Market
Containers
Thermoformed Shallow Trays Market
Containers
Clear Hinged Container Market
Containers
Lever Lid Tinplate Containers Market
Containers
Conipack Pails Market