
 Smartphone Lenses Market | 2026-2036
Smartphone Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Smartphone Lenses Market Analytics
Multi-element aspheric glass specification tiers is bifurcating the competitive landscape into precision manufacturers and commodity assemblers. LG Innotek leverages its captive position within Samsung's supply chain to dominate high-resolution periscope modules. Largan Precision sustains manufacturing scale advantages across plastic-glass hybrid lens stacks for mid-tier handset OEMs. Sunny Optical Technology anchors the Chinese domestic market through backward integration into mold-core equipment and wafer-level optics.
Smartphone lenses are optomechanical assemblies comprising one or more curved refractive elements—typically borosilicate crown glass or polycarbonate substrates with anti-reflective dielectric coatings—engineered to focus electromagnetic radiation onto CMOS image sensors with focal lengths ranging from 2.8 mm to 125 mm equivalent. Their primary commercial purpose is to enable computational photography, video capture, and machine-vision functions in mobile devices. Wide angle configurations currently lead volume shipments as ultrawide secondary cameras become standard across flagship and mid-range devices, while telephoto modules capture disproportionate margin pools due to complex prism-folded optical paths and tighter yield requirements. Glass material segments face cost pressure from emerging composite substrates that replicate refractive indices at reduced weight.
FCC equipment authorization rules in the United States, EU RoHS substance restrictions on heavy metals in optical coatings, and China's GB standards for electromagnetic compatibility collectively shape product design cycles and market access timelines for lens vendors. REACH compliance in Europe adds testing burden for exotic coating chemistries, particularly fluoropolymer anti-smudge treatments. Stakeholders must monitor how computational photography software from handset OEMs commoditizes hardware differentiation, and whether module miniaturization demands will force consolidation among second-tier mold-core suppliers.
Market Dynamics
Computational photography software from Apple, Google, and Samsung is compressing hardware differentiation cycles, forcing lens vendors to integrate AI-optimized optical designs earlier in development pipelines while racing against shortening flagship refresh timelines.
Growth Catalysts
- Content creator economy expansion:TikTok, Instagram Reels, and YouTube Shorts monetization tools are pulling demand for cinematic bokeh and macro capabilities into mid-tier handsets, expanding addressable lens volumes beyond flagship tiers.
- India PLI scheme:Production-linked incentives for mobile device assembly are localizing optical component sourcing, pulling mold-core equipment and wafer-level optics suppliers into Gujarat and Tamil Nadu manufacturing corridors.
- Periscope prism modules:Folded optical paths enabling 5x-10x optical zoom are penetrating sub-$600 price bands, creating fresh demand for high-precision glass molding and actuator integration.
Market Restraints
- Borosilicate crown glass cost volatility:Energy-intensive melting furnaces face natural gas price spikes in Germany and Japan, compressing margins for precision glass element suppliers serving telephoto modules.
- Concentrated mold-core supply:Ultra-precision diamond-turning equipment for aspheric lens masters clusters in Osaka and Aachen, creating single-source vulnerability for second-tier module assemblers.
- REACH fluoropolymer restrictions:ECHA scrutiny of PFAS-based anti-smudge coatings is forcing reformulation of hydrophobic lens surface treatments, extending qualification timelines by 8-14 months.
Strategic Opportunities
- Underpenetrated African markets:Nigeria and Kenya smartphone penetration remains below 45%, creating first-time buyer demand for cost-optimized plastic-glass hybrid lens stacks with simplified supply chains.
- Automotive camera convergence:Surround-view and cabin-monitoring systems in electric vehicles are adopting smartphone-derived wafer-level optics, opening adjacent revenue streams for lens vendors with ISO 26262 certification pathways.
- China dual carbon mandates:MEE enforcement of carbon intensity targets is accelerating glass-to-composite substrate transitions, rewarding early movers with compliant low-refractive-index polymer formulations.
Industry Challenges
- Aspheric metrology talent scarcity:Interferometric measurement of sub-micron surface deviations requires specialized optomechanical engineers concentrated in Taiwan and Bavaria, constraining quality ramp rates for new manufacturing sites.
- Module miniaturization capex intensity:Sub-4mm z-height telephoto designs require bonded prism assemblies and folded actuator mechanisms, demanding $40-80 million cleanroom investments per production line.
- FCC equipment authorization timelines:SAR testing and modular approval processes for camera modules with integrated RF components are extending US market entry cycles, compressing revenue recognition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smartphone Lenses Market |
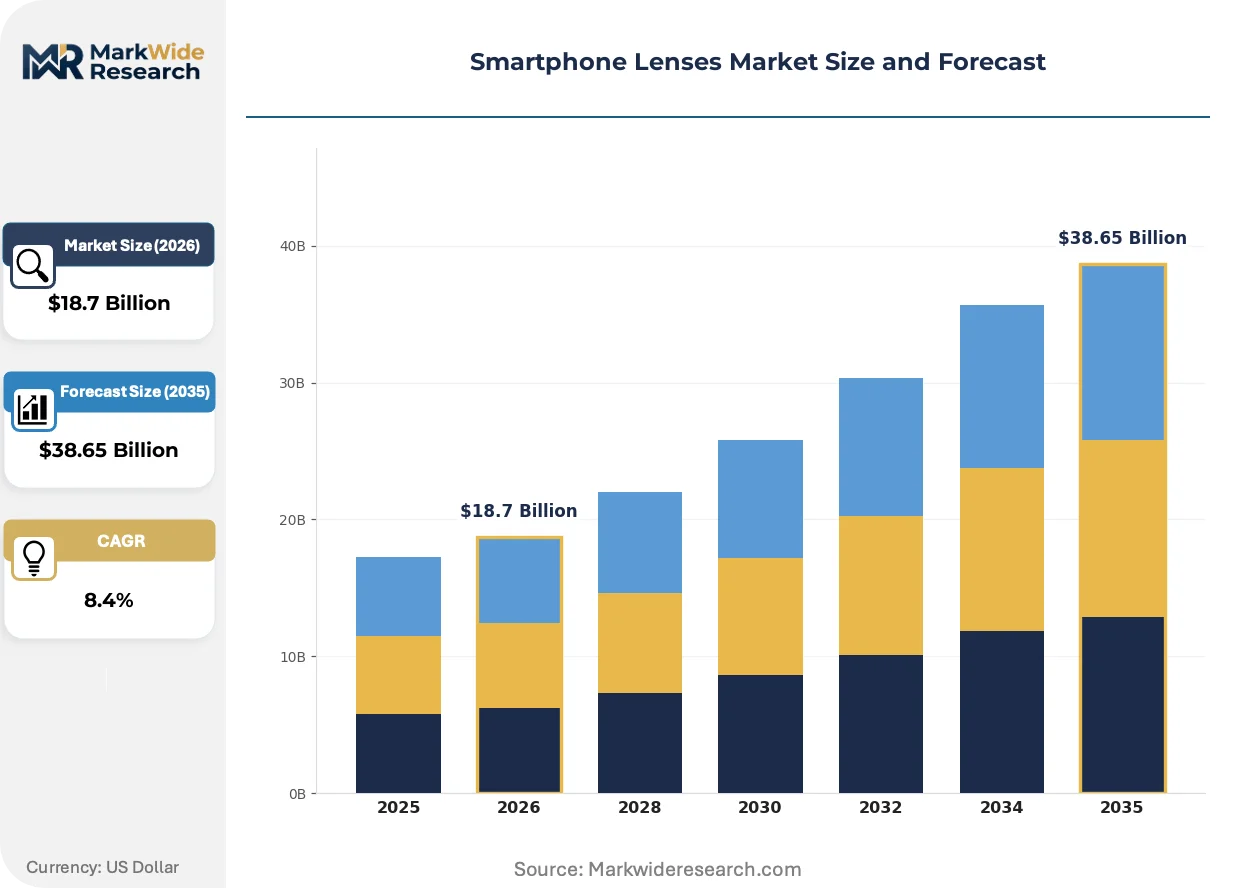
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wide Angle, Telephoto, Macro, Fish-eye Material: Glass, Plastic, Coated, Composite End User: Consumers, Professionals, Influencers, Content Creators Brand: Canon, Nikon, Sony, Moment |
| Companies Covered | Genius Electronic Optical Co. Ltd., LG Innotek, Largan Precision Co. Ltd., Asia Optical, Kantatsu Corporation, Sunny Optical Technology (Group) Co. Ltd., AAC Technologies Holdings Inc., Sekonix, Samsung Electro-Mechanics Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smartphone Lenses Market Evolving Landscape
Wafer-level optics and computational image processing are converging to redefine physical lens specifications, compressing traditional performance hierarchies while opening new design spaces for miniaturized multi-camera arrays.
Polymer-derived composite substrates with tunable refractive indices are fragmenting the historical glass-versus-plastic dichotomy in lens manufacturing. Chinese module suppliers are adopting these materials for ultrawide secondary cameras, achieving 30% weight reduction while maintaining MTF performance. The technology is fragmenting procurement patterns as OEMs qualify hybrid material stacks alongside conventional all-glass designs.
EU RoHS substance restrictions on cadmium and lead in optical coatings are forcing reformulation of high-index glass edge blackening treatments. German lens vendors are migrating to titanium dioxide-based alternatives, absorbing 12-18 month requalification costs. Mid-tier Asian suppliers serving European OEMs face disproportionate compliance burden relative to integrated captive manufacturers.
Direct-to-OEM component sourcing is displacing tiered distributor networks for high-volume lens stack procurement. Samsung and Apple procurement teams are negotiating mold-core equipment access and yield guarantees directly with Sunny Optical and LG Innotek, bypassing legacy module integrators. The pattern concentrates most visibly in Vietnam and India, where new assembly capacity lacks established distribution infrastructure.
Smartphone Lenses Market Segmentation
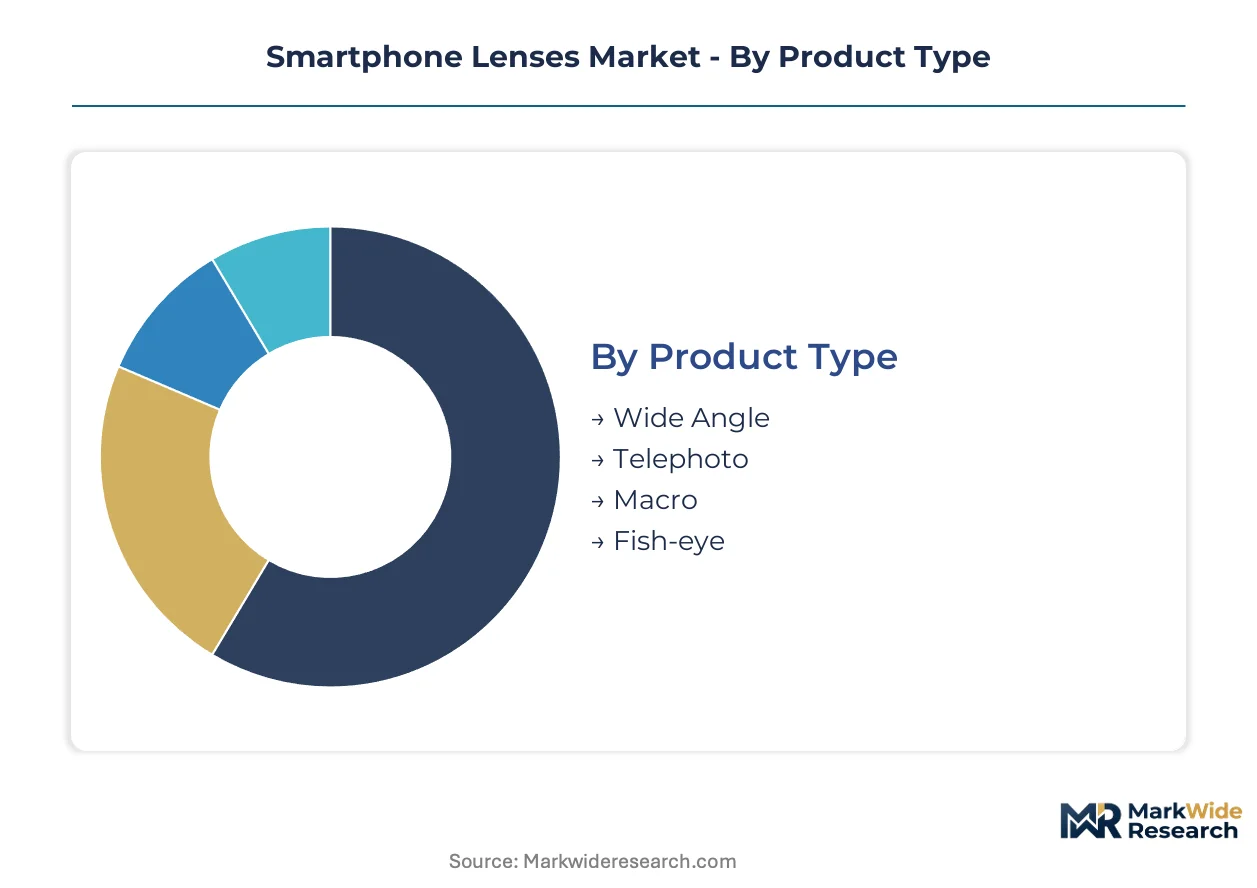
Smartphone lens procurement patterns diverge sharply across optical specifications, substrate chemistry, and user sophistication tiers. Each segmentation axis reveals distinct margin architectures and substitution vulnerabilities that reshape vendor positioning strategies.
Product Type:
Computational photography software is eroding hardware differentiation fastest among standard focal lengths, while folded optical paths and extreme magnifications retain stronger defensive moats against algorithmic substitution.
- Wide Angle:Ultrawide secondary cameras with sub-16mm equivalent focal lengths now ship as standard across flagship and mid-range handsets. India's PLI scheme is pulling volume concentration toward Gujarat assembly corridors where domestic OEMs specify simplified plastic-glass hybrid stacks.
- Telephoto:Prism-folded optical paths enabling 5x-10x optical zoom demand sub-micron surface precision and bonded actuator mechanisms. Periscope modules capture disproportionate margin pools due to yield complexity and concentrated mold-core supply in Osaka and Aachen.
- Macro:Close-focus capabilities require floating element groups with extended travel ranges. Content creator demand from TikTok and Instagram Reels is pushing macro specifications into sub-$400 handsets.
- Fish-eye:Extreme barrel distortion optics serve niche action-camera and automotive surround-view applications. Automotive camera convergence is opening adjacent revenue streams for vendors with ISO 26262 certification pathways.
Wide Angle retains volume leadership; Telephoto holds the steepest expansion curve.
Material:
Substrate selection now pivots on carbon intensity compliance and weight targets rather than pure optical performance hierarchies.
- Glass:Borosilicate crown glass dominates telephoto and periscope modules where thermal stability and refractive precision are non-negotiable. Germany and Japan face energy cost volatility in melting furnace operations.
- Plastic:Polycarbonate substrates enable cost-optimized ultrawide and front-facing camera stacks. Nigeria and Kenya first-time buyer demand favors simplified plastic-only designs.
- Coated:Anti-reflective dielectric stacks and hydrophobic surface treatments face REACH fluoropolymer scrutiny. ECHA PFAS restrictions are forcing 12-18 month reformulation timelines for anti-smudge chemistries.
- Composite:Polymer-derived substrates with tunable refractive indices are fragmenting historical material dichotomies. China's MEE dual carbon mandates are accelerating glass-to-composite transitions for environmental compliance.
Glass maintains premium positioning; Composite substrates are climbing the fastest.
End User:
Monetization infrastructure on short-form platforms is redistributing demand toward creator-class specifications previously confined to professional tiers.
- Consumers:Mass-market handset owners prioritize cost-optimized optics with computational photography compensation. Volume concentrates in India and Southeast Asia assembly corridors.
- Professionals:Photojournalists and commercial photographers demand manual control interfaces and raw output preservation. Specifications align with Sony and Canon camera division heritage.
- Influencers:Platform-native creators require cinematic bokeh and consistent skin-tone rendering for brand-sponsored content. YouTube Shorts monetization tools are pulling these specifications into mid-tier devices.
- Content Creators:The fastest-expanding category spans TikTok, Instagram Reels, and emerging platforms. Macro capabilities and portrait-mode fidelity now drive upgrade cycles for this segment.
Consumers retain volume leadership; Content Creators hold the steepest expansion curve.
Brand:
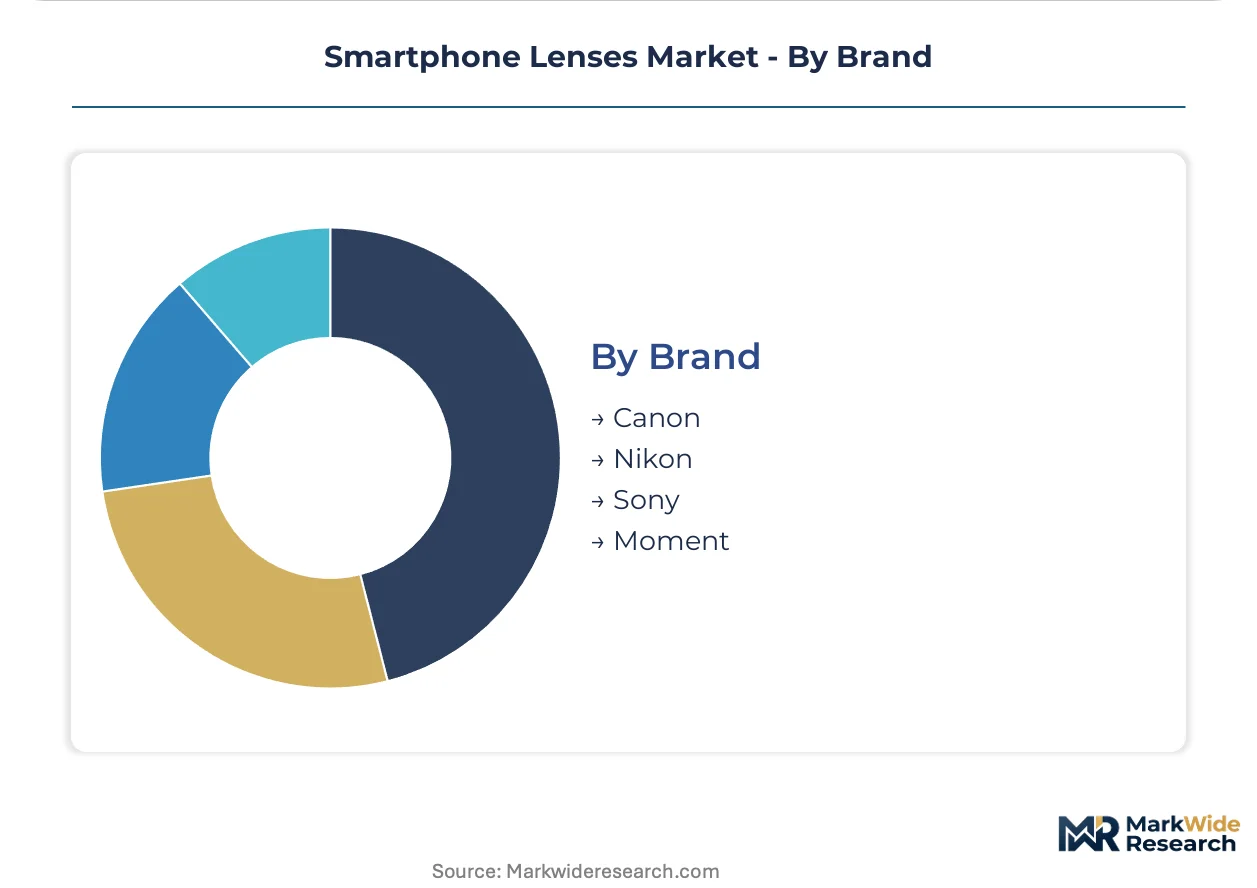
Optical heritage brands compete against mobile-native specialists on attachment mechanism ecosystems and software integration depth.
- Canon:EF-M and RF mount optical expertise translates to clip-on smartphone attachments with manual focus rings. Professional video workflows drive loyalty among documentary filmmakers.
- Nikon:Z-series lens design language informs compact smartphone attachment architectures. Nikkor coating technologies differentiate against commodity alternatives.
- Sony:Xperia smartphone integration creates captive demand for Sony optical attachments. Alpha camera division sensor expertise informs computational photography partnerships.
- Moment:Mobile-native brand built on MagSafe and universal clip mounting ecosystems. Direct-to-consumer distribution bypasses legacy retail markups.
Canon and Nikon retain heritage positioning; Moment is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances favor net exporters in East Asia while assembly gravity shifts toward South Asia and Southeast Asia. China maintains surplus positions in mold-core equipment and wafer-level optics. India and Vietnam run structural deficits in precision glass elements, importing from Japan and Germany.
China
Domestic OEM procurement and MEE carbon intensity enforcement drive demand concentration. The dual carbon goals accelerate glass-to-composite substrate transitions in lens manufacturing. Yangtze River Delta clusters around Suzhou and Ningbo anchor wafer-level optics capacity expansion.
India
PLI scheme incentives for mobile device assembly pull optical component supply chains into Gujarat and Tamil Nadu corridors. BIS standards for electromagnetic compatibility shape product qualification timelines. Domestic OEMs specify simplified plastic-glass hybrid stacks for cost-optimized handsets.
Japan
Precision glass melting and ultra-precision diamond-turning equipment sustain export competitiveness. METI industrial policy supports borosilicate crown glass production amid energy cost volatility. Osaka industrial clusters concentrate aspheric metrology talent and mold-core supply.
Germany
REACH fluoropolymer restrictions force reformulation of hydrophobic lens surface treatments for European OEM compliance. ECHA scrutiny of PFAS-based coatings extends qualification timelines. Aachen engineering corridors concentrate diamond-turning equipment for aspheric lens masters.
South Korea
Captive supply chain integration within Samsung's ecosystem dominates high-resolution periscope module demand. MFDS standards for electromagnetic compatibility align with global flagship specifications. Seoul metropolitan area anchors module assembly and actuator integration capacity.
Smartphone Lenses Market Competitive Landscape
Concentration sits with integrated module suppliers possessing captive OEM relationships and in-house mold-core capabilities. The vendor base separates into three tiers: precision manufacturers serving telephoto specifications, commodity assemblers for mid-range hybrid stacks, and automotive-certified specialists pursuing adjacent revenue. Strategic moves center on backward integration into wafer-level optics and geographic expansion into India PLI corridors.
Among East Asian precision specialists, LG Innotek and Largan Precision exemplify divergent archetypes. LG Innotek occupies a captive position within Samsung's supply chain, while Largan Precision sustains manufacturing scale advantages across plastic-glass hybrid configurations. Sunny Optical Technology anchors Chinese domestic positioning through upstream control over mold-core equipment supply.
| Leading Market Players |
|---|
| Genius Electronic Optical Co. Ltd. |
| LG Innotek |
| Largan Precision Co. Ltd. |
| Asia Optical |
| Kantatsu Corporation |
| Sunny Optical Technology (Group) Co. Ltd. |
| AAC Technologies Holdings Inc. |
| Sekonix |
| Samsung Electro-Mechanics Co. Ltd. |
| Others |
Value Network & Pricing Analysis
REACH fluoropolymer restrictions under ECHA scrutiny simultaneously gate supply qualification for European OEM access and force price differentiation between reformulation-compliant premium tiers and legacy-coated economy alternatives.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade for MEE carbon compliance and volume scale commitments from Gujarat assembly corridors. Cost compression in telephoto glass elements is intensifying because energy-intensive borosilicate melting faces natural gas volatility in Germany and Japan. Flagship handset OEMs exhibit lowest price sensitivity; mid-tier domestic assemblers in India show highest sensitivity.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for mold-core equipment shipments from Osaka and Aachen. Supply concentrates in China for wafer-level optics, Japan for precision glass melting, and Germany for diamond-turning equipment. Raw material dependencies draw from borosilicate crown glass, polycarbonate substrates, and fluoropolymer coating chemistries. Single-source vulnerability clusters in ultra-precision aspheric metrology talent. Distribution runs through direct-to-OEM procurement channels displacing legacy module integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computational photography software from Apple and Google is compressing hardware differentiation cycles, creating a high-growth disruption window for lens vendors who integrate AI-optimized optical designs ahead of flagship refresh timelines.
For Market Incumbents: Compound captive supply chain positions through backward integration into mold-core equipment production and yield guarantee negotiations with Samsung and Apple procurement teams. Defend against computational photography commoditization by accelerating periscope prism module development where folded optical paths retain hardware moats. Prioritize ISO 26262 certification pathways for automotive camera convergence revenue. For New Entrants and Emerging Players: Differentiate on low-carbon composite substrate formulations aligned with China's MEE dual carbon mandates. Target underpenetrated African markets in Nigeria and Kenya where first-time buyer demand favors cost-optimized plastic-glass hybrid stacks. Pursue direct-to-OEM component sourcing relationships in Vietnam and India PLI corridors where distribution infrastructure remains nascent. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sub-4mm z-height telephoto designs demanding bonded prism assemblies and folded actuator mechanisms. Long-term viability favors vendors with cleanroom scale and captive OEM relationships over pure-play mold-core suppliers. Monitor ECHA PFAS restriction enforcement timelines as inflection indicator for coating chemistry reformulation costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mold-Core Equipment | Sunny Optical's upstream control over equipment supply anchors Chinese domestic market positioning. |
| Automotive ISO 26262 Certification Pathway | Wafer-level optics vendors gain adjacent revenue from electric vehicle surround-view and cabin-monitoring systems. |
| Composite Substrate Formulation Development | Low-refractive-index polymer alternatives reward early movers under MEE carbon intensity enforcement. |
| Direct-to-OEM Procurement Negotiation | Samsung and Apple procurement teams bypass legacy module integrators in Vietnam and India corridors. |
| Periscope Prism Module Capacity Expansion | Folded optical paths penetrating sub-$600 price bands create fresh demand for high-precision glass molding. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with lens module procurement managers, optical design engineers, and supply chain directors at tier-1 handset OEMs; and secondary validation against customs records, SEC filings from listed component suppliers, and MEE environmental compliance disclosures. Bottom-up triangulation across wafer-level optics shipment data and top-down reconciliation against handset production forecasts anchored volume estimates.
Across the analysis window, the forecasting framework modeled demand by product type, material substrate, end-user sophistication tier, and regional assembly corridor. CAGRs were derived from segment-level growth rate reconciliation against macro smartphone penetration trajectories. Key inputs included PLI scheme incentive disbursement timelines, periscope module yield curves, and computational photography software roadmap disclosures from Google and Apple.
Decision-makers should treat outputs as directional under assumptions of sustained India PLI scheme enforcement and stable ECHA PFAS regulatory timelines; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Electro Optics Market
Optics
Fiber Optic Switch Market
Optics
Solid State Lasers Market
Optics
Fiber Optic Receiver Market
Optics
APAC Smart Glass Market
Optics
India Laser Market
Optics
Fiber Optic Amplifier Market
Optics
Excimer Lasers for DUV Lithography Market
Optics
Smartphone Camera Lenses Market
Optics
Fiber Optic Connectivity Market
Optics
Acrylic Lenses Market
Optics
Optical Lens for Mobile Phone Market
Optics
Picosecond Lasers Market
Optics
Digital Holographic Microscopy Market
Optics
Europe Laser Interferometer Market
Optics
Residential 1080P Laser Television Projector Market