
 Single-Mode Optical Fiber Market | 2026-2036
Single-Mode Optical Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Single-Mode Optical Fiber Market Outlook
Multi-source procurement is recalibrating how carriers secure optical fiber supply. Corning Incorporated leverages its vertically integrated silica-to-cable manufacturing to anchor North American supply security. YOFC competes on scale, operating the world's largest preform and draw facilities to dominate domestic Chinese procurement. Prysmian Group extends its European footprint through submarine and terrestrial cable integration.
Single-mode optical fiber transmits light through a small core diameter, typically 8-10 micrometers, enabling minimal signal dispersion across distances exceeding 100 kilometers without amplification. Its primary commercial purpose is high-capacity, long-reach data transmission for telecommunications infrastructure and inter-data-center connectivity. Low-loss fiber commands the dominant volume position in long-haul and submarine applications where attenuation below 0.17 dB/km directly reduces repeater costs. Bend-insensitive fiber represents the fastest-growing product category as fiber-to-the-home installers route cable through tight premises spaces without signal degradation.
Telecommunications deployment faces overlapping compliance requirements from the ITU-T G.652/G.654 standards series, the IEC 60793 fiber specification framework, and national telecom regulators including the FCC in the United States and MIIT in China. These bodies shape product qualification, interconnection rules, and subsidy eligibility that determine which fiber grades carriers specify. Stakeholders must monitor how AI workload growth reshapes metro versus long-haul capacity planning and whether submarine cable consortiums shift procurement toward ultra-low-loss designs.
Market Dynamics
AI workload concentration in hyperscale data centers is compressing upgrade cycles for metro and inter-facility fiber links, forcing carriers to pre-position capacity ahead of actual traffic ramp. This demand pull is restructuring supplier qualification timelines and capex allocation across terrestrial and submarine networks.
Growth Catalysts
- EU Green Deal fiber mandates:National broadband targets in Germany, France, and Spain are accelerating fiber-to-the-home deployment timelines and locking in multi-year procurement volumes.
- 5G backhaul densification:China's state-led rural connectivity programs sustain massive single-mode fiber procurement for macro cell and small cell aggregation networks.
- Submarine cable consortium expansion:Transoceanic bandwidth requirements for cloud region interconnection are driving ultra-low-loss fiber specifications for new cable systems.
Market Restraints
- High-purity silica supply concentration:Synthetic silica precursor production clusters in limited geographic zones, creating input cost volatility for preform manufacturers.
- ITU-T G.654 qualification timelines:Extended type-testing protocols for submarine-grade fiber delay revenue recognition and tie up working capital.
- Copper-to-fiber substitution ceiling in last-mile:Legacy coaxial infrastructure in aging urban buildings limits immediate fiber penetration in certain brownfield installations.
Strategic Opportunities
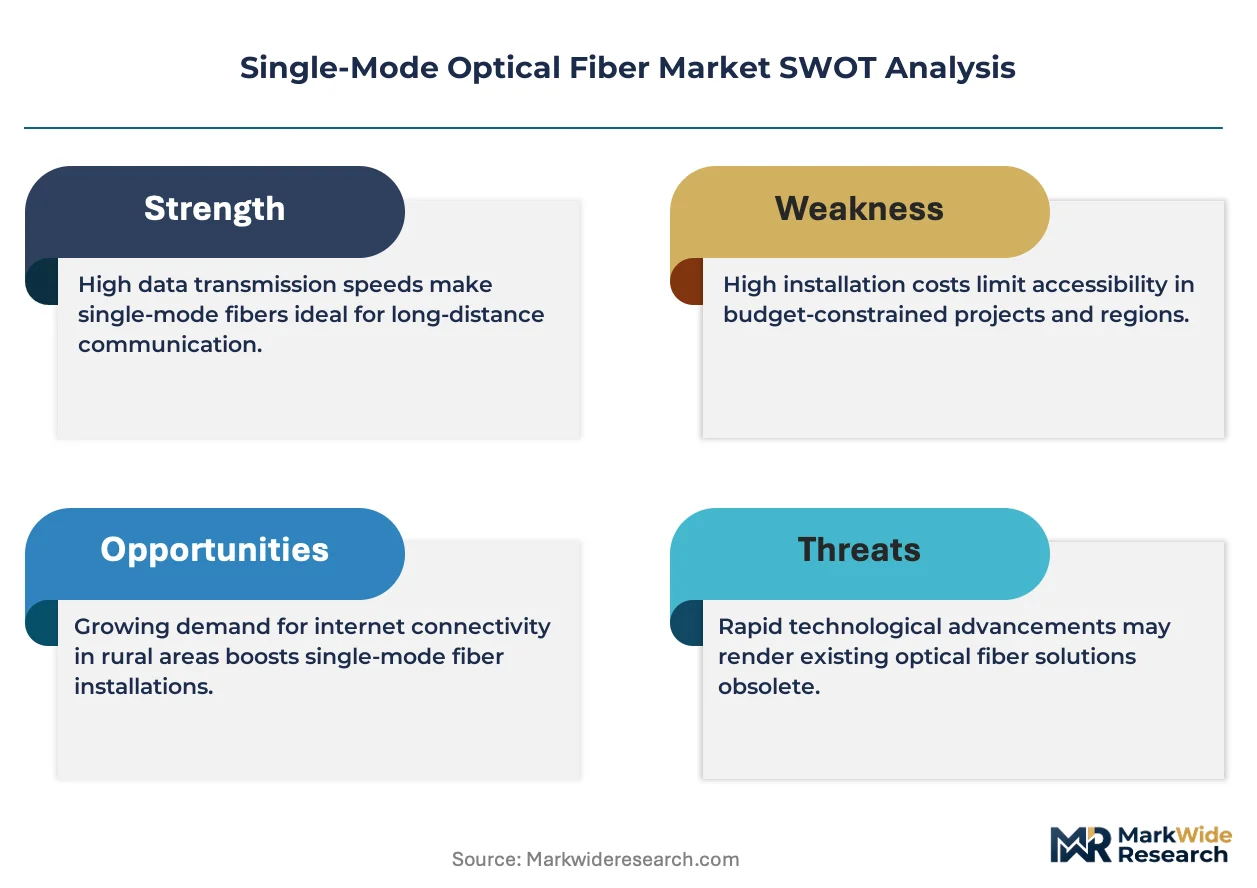
- Rural India broadband underpenetration:The country's BharatNet initiative and subsequent state-led extensions present greenfield fiber deployment scope outside urban corridors.
- Bend-insensitive fiber in multi-dwelling units:Tight-radius routing through apartment infrastructure enables installer productivity gains and reduced call-back rates.
- AI-driven coherent optical convergence:Integration of DSP-enabled transceivers with optimized fiber profiles is opening specification partnerships between cable and equipment vendors.
Industry Challenges
- Specialized fusion splicing technician scarcity:Precision alignment skills for low-loss field connections are concentrating in contractor workforces, constraining deployment velocity.
- Legacy SONET/SDH interoperability:Brownfield network segments require backward-compatible fiber grades, complicating inventory management and procurement standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single-Mode Optical Fiber Market |
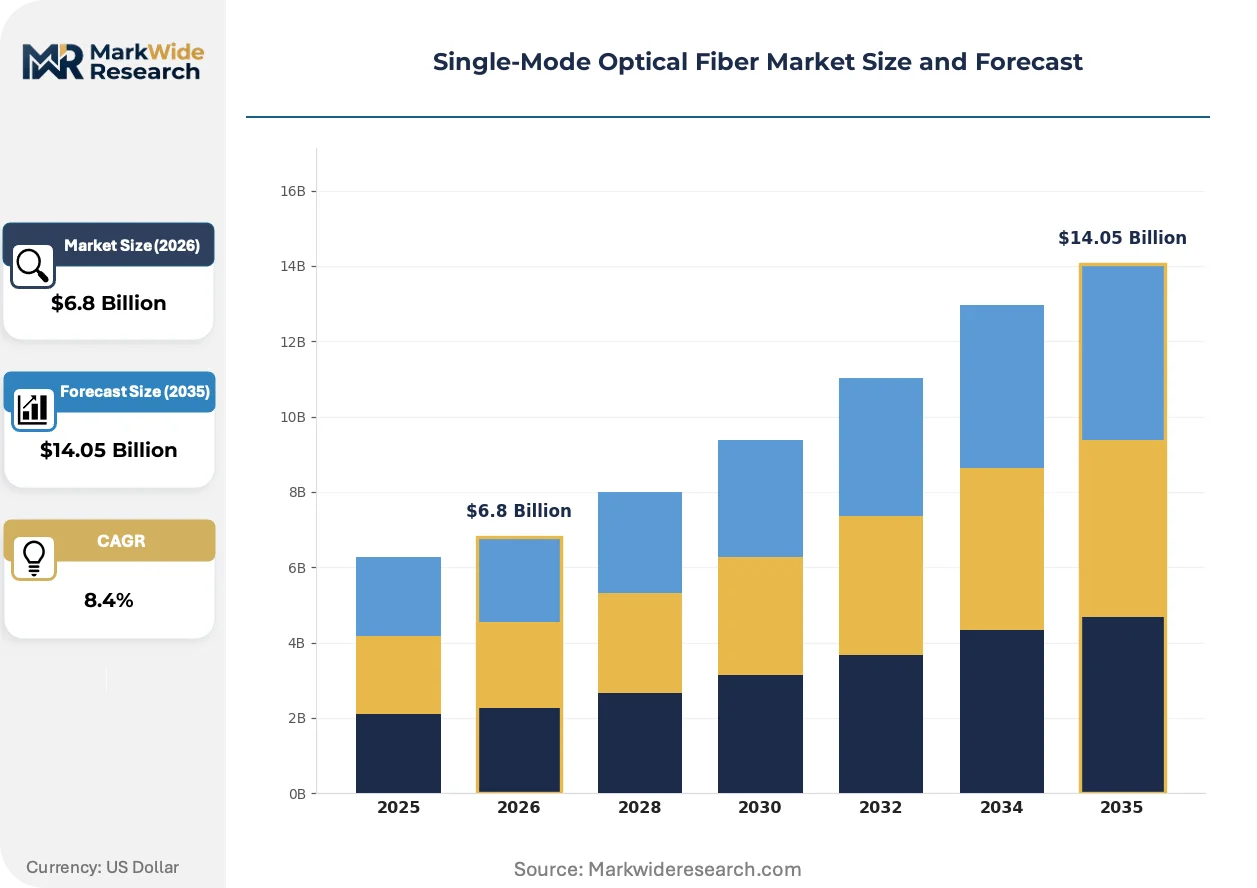
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Fiber, Specialty Fiber, Low-loss Fiber, Bend-Insensitive Fiber Installation: Indoor, Outdoor, Aerial, Underground End User: Telecommunications, Data Centers, Government, Enterprises Application: Long-haul Transmission, Metro Networks, CATV, Submarine Cable |
| Companies Covered | Sumitomo Electric Industries, Yangtze Optical Fibre and Cable (YOFC), Corning Incorporated, CommScope Inc., Sterlite Technologies Limited, Prysmian Group, Furukawa Electric Co., Ltd., OFS Fitel, Fujikura Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single-Mode Optical Fiber Market Strategic Shifts
Coherent optical transmission is compressing the economic case for signal regeneration, while regulatory carbon accounting and procurement consolidation are rewriting vendor selection criteria. These forces are converging to favor fiber designs that minimize both attenuation and installation labor.
Hollow-core fiber is integrating photonic bandgap structures to guide light through air rather than glass, slashing nonlinear impairments that limit capacity-distance products. Hyperscale operators are piloting this technology for data center interconnects where latency and power consumption dominate total cost. The structural consequence is that traditional solid-core suppliers are integrating hollow-core R&D into their roadmap acceleration programs.
The EU AI Act and parallel CSRD disclosure requirements are mandating supply chain carbon footprint documentation for telecommunications infrastructure. European carriers are now embedding lifecycle emissions criteria into fiber procurement specifications, favoring manufacturers with renewable-powered draw towers and recycled silica sourcing. Submarine cable consortiums are responding by pre-qualifying suppliers with verified Environmental Product Declarations ahead of tender issuance.
Consolidated procurement by hyperscale cloud operators is displacing the traditional carrier-led specification model for metro fiber. Amazon Web Services, Microsoft, and Google are issuing unified global fiber standards that override regional ITU-T variant preferences, compressing supplier SKU diversity. This concentration is most visible in Northern Virginia, Frankfurt, and Singapore, where data center cluster expansion is binding fiber procurement to cloud capex cycles rather than telecom operator budgets.
Single-Mode Optical Fiber Market Segmentation
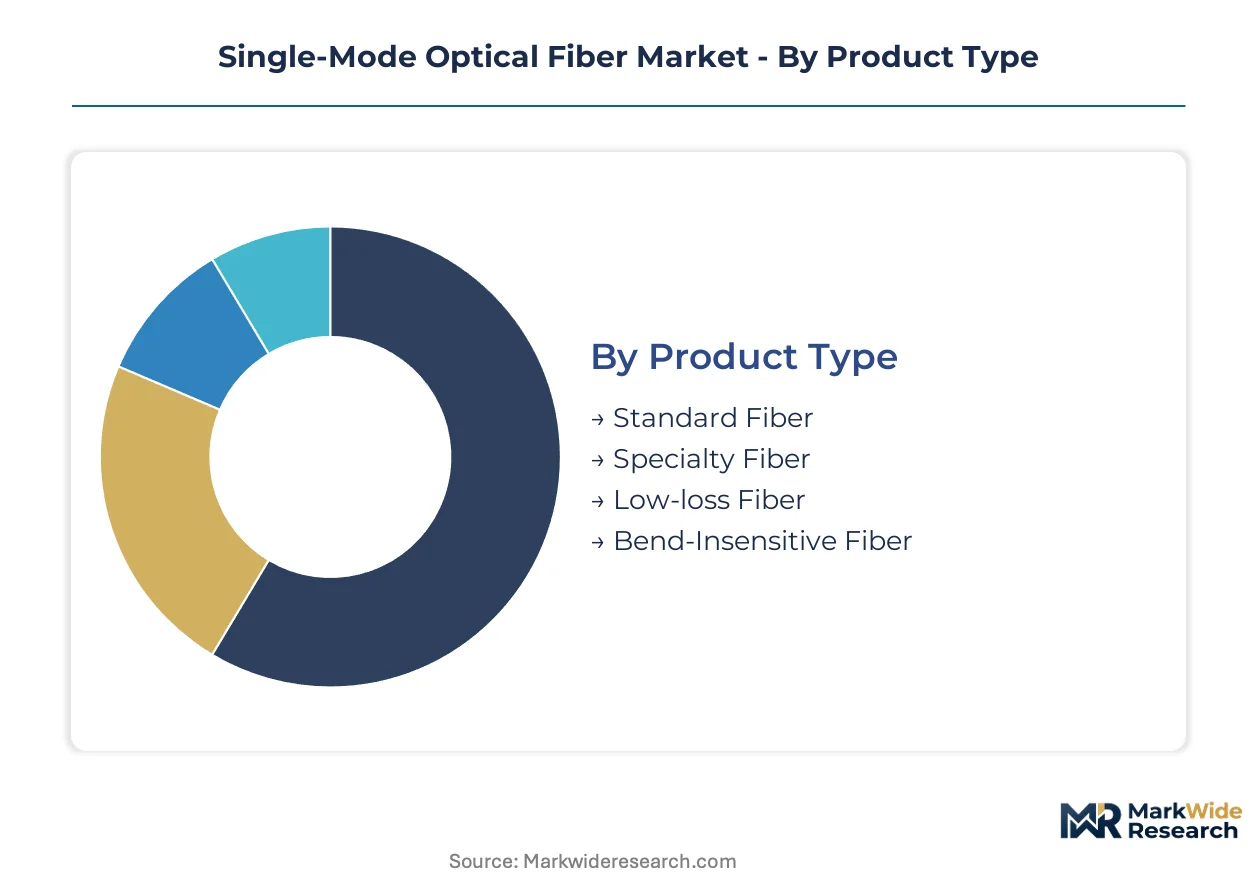
Single-mode optical fiber procurement splits across technical specifications, deployment environments, and customer archetypes. Each segmentation axis carries distinct qualification burdens from ITU-T, IEC, and national regulators that shape supplier margins and contract structures.
Product Type:
ITU-T G.652 and G.654 certifications dominate qualification timelines, with submarine-grade testing extending vendor revenue recognition cycles by months.
- Standard Fiber:ITU-T G.652.D compliant silica core with 0.20 dB/km typical attenuation. Telecom carriers in Germany and France specify this grade for mass FTTH deployment under EU Green Deal subsidy rules, locking in predictable procurement volumes through 2030.
- Low-loss Fiber:Enhanced purity reduces attenuation below 0.17 dB/km for repeater spacing economics. Transoceanic cable consortiums pre-qualify this grade for trans-Pacific and trans-Atlantic routes where amplifier spacing directly determines system capex.
- Specialty Fiber:Polarization-maintaining and photosensitive variants for sensor and laser applications. Medical device manufacturers and defense contractors drive niche demand with extended qualification protocols.
- Bend-insensitive Fiber:Trench-assisted refractive index profiles permit 7.5mm bend radii without macrobending loss. Apartment installers in Spain and Italy specify this grade for tight-radius routing through multi-dwelling unit infrastructure.
Standard fiber sits at the top of the volume ranking, with bend-insensitive fiber climbing the fastest.
Installation:
Deployment method selection hinges on right-of-way access, labor cost structures, and climate exposure across target geographies.
- Indoor:Tight-buffered cable designs for premises distribution. Data center operators in Northern Virginia and Frankfurt specify this grade for inter-facility links where fire safety codes mandate plenum-rated jacketing.
- Outdoor:Loose-tube gel-filled construction for moisture resistance. Chinese provincial broadband programs drive massive procurement for rural 5G backhaul where aerial and underground methods converge.
- Aerial:All-dielectric self-supporting designs eliminate metallic elements. Brazilian and Indian utilities favor this method where trenching costs exceed pole attachment fees in remote terrain.
- Underground:Direct-buried or duct-installed cables with armored protection. German and Dutch municipalities mandate this approach in urban cores to preserve streetscape aesthetics and enable future overbuild capacity.
Outdoor installation commands the dominant procurement volume, though underground methods are expanding most quickly in European urban renewal projects.
End User:
Customer type determines specification authority, with hyperscale cloud operators increasingly displacing traditional carrier-led standards.
- Telecommunications:Incumbent carriers and competitive local exchange carriers specifying ITU-T compliant grades. Verizon and Deutsche Telekom maintain qualified supplier lists with multi-year framework agreements.
- Data Centers:Hyperscale operators issuing unified global standards that override regional variants. AWS, Microsoft, and Google bind fiber procurement to cloud capex cycles rather than telecom operator budgets.
- Government:National broadband initiatives and defense networks with security-cleared supply chain requirements. India's BharatNet and China's rural connectivity programs sustain state-led procurement volumes.
- Enterprises:Campus and private network operators with shorter qualification timelines. Financial services firms in Singapore and London drive demand for low-latency dark fiber leases.
Telecommunications retains the largest installed base, while data center procurement is gaining share fastest.
Application:
Distance and capacity requirements split fiber specifications between amplification economics and terminal equipment compatibility.
- Long-haul Transmission:Ultra-low-loss G.654.E fiber for terrestrial routes exceeding 500km without electrical regeneration. Chinese state grid and Russian trunk operators specify this grade for transcontinental backbone capacity.
- Metro Networks:G.652 variants optimized for coherent 400G/800G transceiver compatibility. Dense urban corridors in Japan and South Korea drive upgrade cycles as AI workload concentration compresses refresh timelines.
- CATV:Hybrid fiber-coaxial plant extensions with backward-compatible specifications. US cable operators maintain legacy infrastructure while overlaying fiber deeper into access networks.
- Submarine Cable:G.654.D ultra-low-loss designs with 25-year reliability guarantees. Transoceanic consortiums pre-qualify suppliers with verified Environmental Product Declarations ahead of tender issuance under EU CSRD alignment.
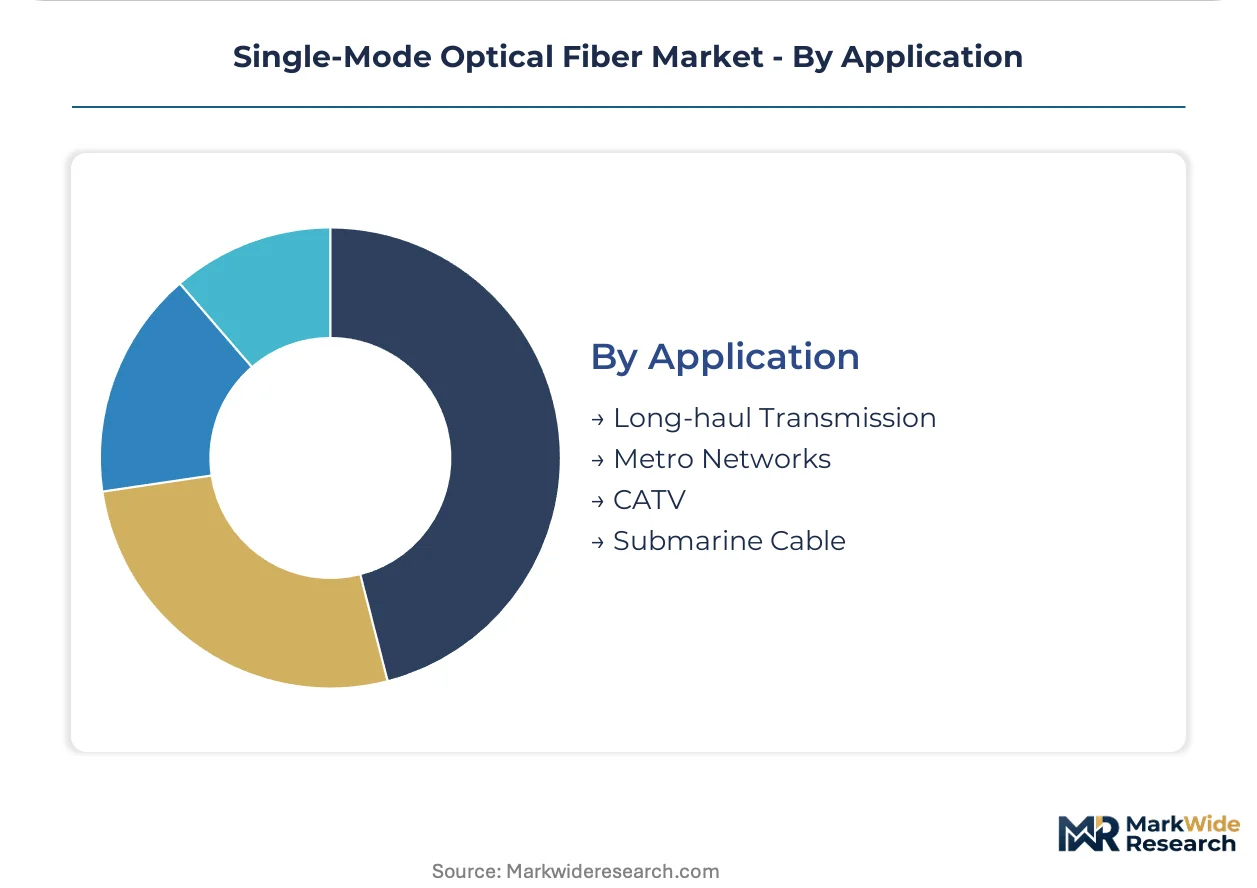
Metro networks generate the highest current procurement volume, with submarine cable applications showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate draw-tower operations to jurisdictions with streamlined environmental permitting and subsidized renewable energy access.
China
State-led 5G backhaul and rural connectivity programs sustain massive procurement volumes for single-mode fiber. MIIT mandates drive standardization across provincial broadband initiatives. Yangtze River Delta clusters host the world's largest preform and draw facilities, serving domestic carriers and export markets simultaneously.
United States
Hyperscale data center expansion in Northern Virginia and Dallas-Fort Worth compresses upgrade cycles for inter-facility fiber links. FCC broadband subsidy programs accelerate rural deployment timelines. Corning's vertically integrated silica-to-cable manufacturing anchors North American supply security.
Germany
National broadband targets under the EU Green Deal lock in multi-year FTTH procurement volumes through 2030. ECHA REACH compliance requirements shape preform manufacturing input sourcing. Rhine-Ruhr industrial corridors concentrate fusion splicing technician training programs to address field deployment bottlenecks.
India
BharatNet initiative extensions present greenfield fiber deployment scope across rural corridors outside urban centers. TRAI interconnection rules and BIS certification frameworks govern product qualification. Maharashtra and Gujarat host emerging cable manufacturing clusters serving domestic carrier qualification lists.
Japan
Metro network densification in Tokyo-Osaka corridors drives coherent 400G/800G transceiver compatibility requirements. METI carbon accounting guidelines influence supplier environmental product declarations. Kanto region data center clusters bind fiber procurement to cloud operator capex cycles.
Single-Mode Optical Fiber Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue hollow-core and specialty fiber adjacent spaces. The vendor base stratifies across scale-driven integrated manufacturers, regional cable assemblers, and technology licensors. Three archetypes dominate: vertically integrated silica-to-cable operators, draw-tower specialists with captive preform supply, and R&D-focused hollow-core pioneers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms pre-position for hyperscale qualification cycles.
Among Asia-Pacific-based fabricators, Sumitomo Electric Industries, Yangtze Optical Fibre and Cable (YOFC), and Furukawa Electric Co., Ltd. exemplify scale-driven archetypes. Corning Incorporated occupies a position within the North American integrated tier. Prysmian Group anchors European supply security through submarine and terrestrial cable integration. These named entities represent geographic production concentration rather than definitive market share claims.
| Leading Market Players |
|---|
| Sumitomo Electric Industries |
| Yangtze Optical Fibre and Cable (YOFC) |
| Corning Incorporated |
| CommScope Inc. |
| Sterlite Technologies Limited |
| Prysmian Group |
| Furukawa Electric Co., Ltd. |
| OFS Fitel |
| Fujikura Ltd. |
| Others |
Value Chain & Pricing Dynamics
Fusion splicing technician scarcity in the Rhine-Ruhr corridor compresses labor-cost differentials between premium submarine-grade fiber and standard FTTH deployments, widening pricing-tier spreads across European procurement.
Pricing Analysis
Distributor margins on standard ITU-T G.652.D fiber compress under direct-to-hyperscale contracting, while submarine cable consortiums negotiate multi-year offtake agreements with embedded volume discounts. Pricing stratifies across premium, standard, and economy tiers based on attenuation certification and bend-insensitivity specifications. Cost compression in the standard tier intensifies as Chinese state-led programs flood export markets with surplus draw-tower capacity. Data center operators exhibit the lowest price sensitivity, prioritizing latency guarantees and rapid qualification timelines over per-kilometer fiber costs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand in Northern Virginia and Frankfurt, bypassing traditional distribution layers. Preform manufacturing concentrates in China, the United States, and Japan, with synthetic silica precursor production anchored in limited geographic zones. The supply chain draws from high-purity silicon tetrachloride, germanium tetrachloride for refractive index profiling, and specialized coating resins. Single-source vulnerability in synthetic silica feedstock creates input cost volatility when energy prices spike. Distribution runs through qualified supplier lists maintained by major carriers, with submarine cable consortiums imposing additional environmental certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, with AI-driven bandwidth expansion in hyperscale data centers providing steady demand visibility across the analysis window.
For Market Incumbents: Lock in long-term preform supply agreements with synthetic silica producers to defend margins against feedstock volatility. Extend captive draw-tower capacity in renewable-powered jurisdictions to satisfy EU CSRD-aligned procurement criteria from European carriers and submarine cable consortiums. For New Entrants and Emerging Players: Enter via hollow-core fiber pilot programs with hyperscale operators seeking latency reduction for AI training cluster interconnects. Target data center interconnect applications in Singapore and Tokyo-Osaka corridors where incumbent qualification timelines create temporary specification gaps. For Investors and Strategic Acquirers: Hyperscale cloud operators are the most active acquirer in this space, pursuing vertical integration into preform manufacturing to secure supply for captive fiber consumption. The acquisition target archetype comprises draw-tower specialists with MIIT or FCC pre-qualification and stranded capacity in lower-cost manufacturing zones. Monitor submarine cable consortium tender issuance patterns as an inflection indicator for ultra-low-loss fiber demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Silica | Corning and YOFC secure feedstock autonomy against precursor supply volatility. |
| Renewable-Powered Draw Tower Expansion | Prysmian qualifies for EU CSRD-mandated Environmental Product Declarations. |
| Hollow-Core Fiber R&D Partnership | Hyperscale operators pilot air-guiding structures for latency-critical AI workloads. |
| Multi-Year Hyperscale Supply Agreement | AWS and Microsoft bind fiber procurement to cloud capex cycles outside carrier budgets. |
| Submarine Cable Consortium Pre-Qualification | Suppliers secure 25-year reliability guarantees with transoceanic route operators. |
Study Parameters
Coverage spans China, the United States, Germany, India, and Japan, with primary inputs from each. The research combines structured interviews with submarine cable procurement directors, hyperscale data center network architects, and MIIT regulatory affairs specialists with secondary validation from ITU-T standards documentation, IEC fiber specification frameworks, and carrier capex disclosure filings. Bottom-up and top-down triangulation reconciles preform manufacturing capacity data with end-user deployment schedules.
Rate-of-change decomposition separates volume expansion from specification mix shifts across the projection horizon. The analytical framework models fiber demand by product type, installation environment, end-user archetype, and application distance tier, with additional segmentation by coherent transceiver compatibility requirements. CAGRs derive from installed base depreciation schedules overlaid with AI workload concentration patterns in metro network corridors.
The model holds under stable silica precursor supply and continued hyperscale data center expansion; deviation in trade policy or energy cost spikes would shift preform manufacturing economics. Forecasts reflect assumptions about ITU-T G.654 qualification timeline stability and submarine cable consortium procurement consolidation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Sports Optics Market
Optics
EUV Pellicle Market
Optics
Tunable Laser Market
Optics
Fiber Optic Receiver Market
Optics
APAC Smart Glass Market
Optics
Latin America Optical Imaging Market
Optics
Interchangeable Lens Market
Optics
Anomaloscope Market
Optics
Smart Glass Market
Optics
Europe Laser Interferometer Market
Optics
Optical Microscope Market
Optics
Optical Wavelength Service Market
Optics
Middle East and Africa Tunable Laser Market
Optics
Middle East and Africa Optical Imaging Market
Optics
Optical Imaging Market
Optics
Optical Fiber Market