
 Methylene Diphenyl Di-Isocyanate (MDI) Market | 2026-2036
Methylene Diphenyl Di-Isocyanate (MDI) Market Size, Share, and Industry Trends Forecast 2026-2036
Methylene Diphenyl Di-Isocyanate (MDI) Market Foresight
China is fragmenting MDI supply concentration as Wanhua Chemical Group Co. extends its Ningbo complex into one of the world's largest integrated sites. Covestro AG leverages its European asset base to sustain premium polymeric MDI output for automotive and construction clients. BASF SE anchors German production with backward integration into aniline and nitrobenzene precursors.
Methylene Diphenyl Di-Isocyanate is an aromatic di-isocyanate synthesized from aniline and formaldehyde, typically containing 4,4'-MDI, 2,4'-MDI, and 2,2'-MDI isomers in varying ratios; it serves as the primary building block for rigid and flexible polyurethane foams, coatings, and elastomers. Polymeric MDI dominates volume flows into construction insulation boards where thermal performance standards drive specification intensity. Foams application growth outpaces coatings and adhesives as cold-chain logistics and refrigerated transport expand. Modified MDI variants command margin premiums in automotive seating where VOC emissions regulations tighten.
China's MEE enforces dual carbon goals that constrain coal-based aniline feedstock expansion, while the EU's REACH authorization list and F-Gas Regulation limit blowing-agent options in rigid foam formulations. The US EPA Toxic Substances Control Act Section 5 requirements add pre-manufacture notification burdens for novel MDI derivatives. Stakeholders must monitor feedstock decarbonization pathways and blowing-agent transition timelines to preserve formulation compliance across jurisdictions.
Market Dynamics
MDI demand trajectories hinge on building energy efficiency mandates that are tightening thermal performance specifications across residential and commercial construction codes. The regulatory compression on blowing-agent chemistries and feedstock carbon intensity is forcing reformulation investments throughout the value chain.
Growth Catalysts
- EU F-Gas Regulation phase-down:The scheduled reduction in hydrofluorocarbon blowing-agent availability is accelerating adoption of water-blown and hydrocarbon-blown rigid foam systems that rely on optimized MDI index formulations.
- Cold-chain infrastructure expansion:Refrigerated warehousing and transport fleet growth in emerging economies is pulling polymeric MDI volumes into insulated panel applications for temperature-controlled logistics.
- Construction retrofit mandates:Germany's Building Energy Act and similar national renovation frameworks are specifying polyurethane insulation boards for facade and roof upgrades in existing building stock.
Market Restraints
- Aniline feedstock volatility:Benzene and nitrobenzene price swings transmit directly into MDI production economics, compressing margin visibility for non-integrated producers.
- Supply concentration in China:Capacity expansion at Ningbo and Yantai complexes is creating regional oversupply conditions that depress export pricing into Southeast Asian and Middle Eastern markets.
- Substitution by mineral wool:Stone wool and glass wool insulation systems are capturing specification share in fire-critical commercial applications where polyurethane smoke toxicity concerns persist.
Strategic Opportunities
- India construction acceleration:The country's affordable housing and commercial real estate pipeline remains underpenetrated by rigid polyurethane insulation relative to extruded polystyrene alternatives.
- Modified MDI for automotive lightweighting:Interior trim and structural composite applications are specifying low-VOC, low-emission MDI variants for electric vehicle platforms.
- Bio-based aniline pathways:Pilot-scale production of aniline from renewable feedstocks is creating compliance hedges against EU carbon border adjustment mechanisms and Scope 3 disclosure requirements.
Industry Challenges
- Process safety expertise scarcity:Phosgenation chemistry operations require specialized occupational health protocols that exceed standard chemical engineering training curricula in multiple jurisdictions.
- REACH authorization timelines:Substance evaluation and restriction processes for isocyanate derivatives are extending product registration cycles and demanding expanded toxicological dossiers.
- Legacy asset retrofit costs:Existing naphtha-to-aniline production trains face stranded asset risk as dual carbon goals and carbon pricing mechanisms penalize coal-derived feedstock routes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methylene Diphenyl Di-Isocyanate (MDI) Market |
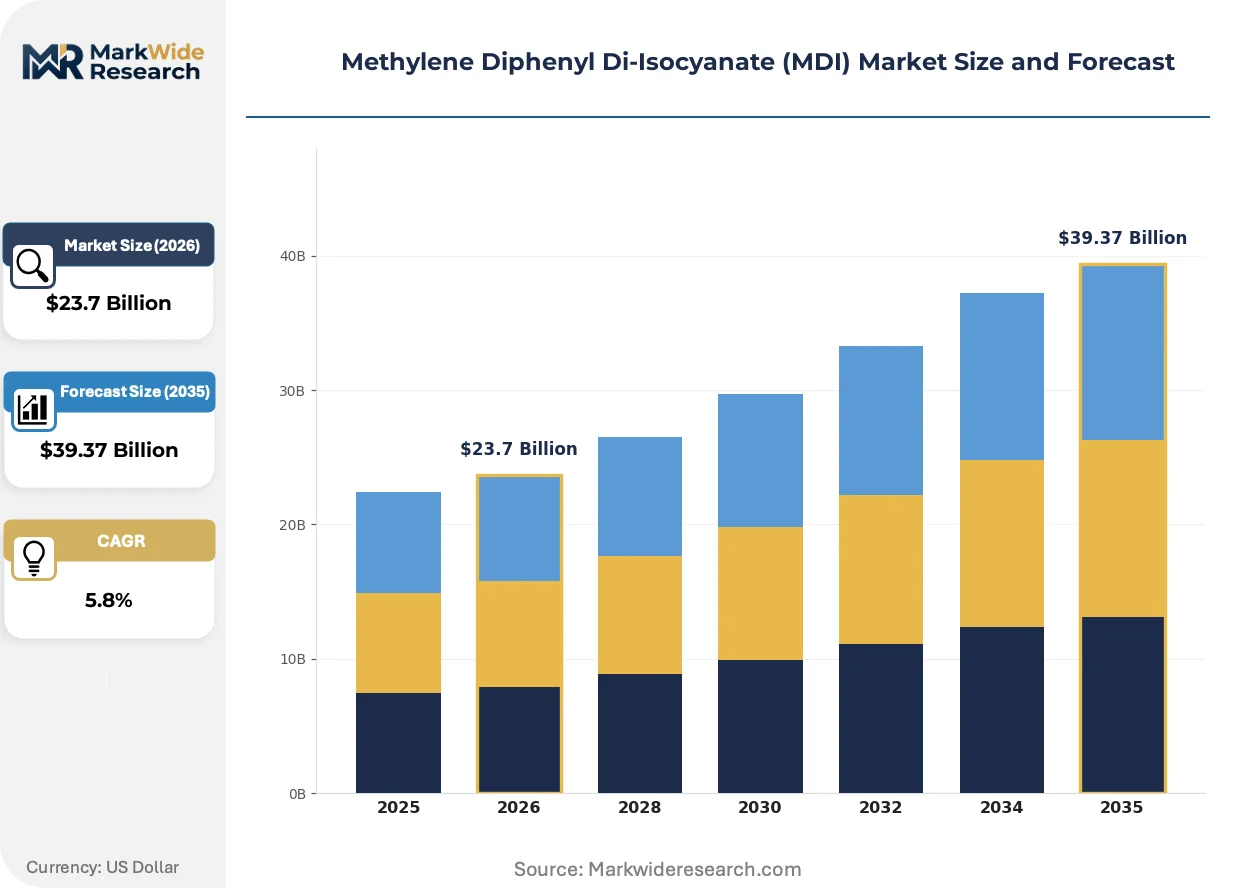
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $39.37 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymeric MDI, Monomeric MDI, Modified MDI, Liquid MDI End User: Construction, Automotive, Furniture, Footwear Application: Coatings, Adhesives, Sealants, Foams Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Wanhua Chemical Group Co., Covestro AG, BASF SE, Dow Chemical Company, Huntsman Corporation, Kumho Mitsui Chemicals, Tosoh Corporation, Hexion Inc., Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methylene Diphenyl Di-Isocyanate (MDI) Market Shifts & Advancements
Formulation science and digital manufacturing tools are compressing product development cycles while regulatory chemistry constraints are redirecting R&D investment toward sustainable feedstock integration and emission control.
Advanced process simulation software is virtualizing reactor design and distillation sequence optimization for MDI isomer separation. European and Asian producers are deploying these digital twins to debottleneck existing assets without physical pilot campaigns. The technology is virtualizing capital deployment decisions by reducing scale-up risk and accelerating time-to-market for modified MDI grades.
China's MEE enforcement of dual carbon goals is constraining coal-based aniline expansion permits and redirecting investment toward naphtha and light hydrocarbon feedstock routes. This policy pivot is elevating production costs for domestic MDI supply while creating competitive advantage for producers with backward integration into petrochemical complexes. The regulatory pressure is most acute in Shandong and Jiangsu provinces where legacy coal-chemical clusters face emissions intensity targets.
Buyers in construction and appliance manufacturing are consolidating procurement volumes and demanding vendor-managed inventory arrangements with real-time consumption tracking. Long-term offtake agreements with indexed pricing are displacing spot market transactions for standard polymeric MDI grades. This behavioral shift is most visible in Germany's industrial chemical corridor where BASF and Covestro maintain integrated supply relationships with major insulation panel producers.
Methylene Diphenyl Di-Isocyanate (MDI) Market Segmentation
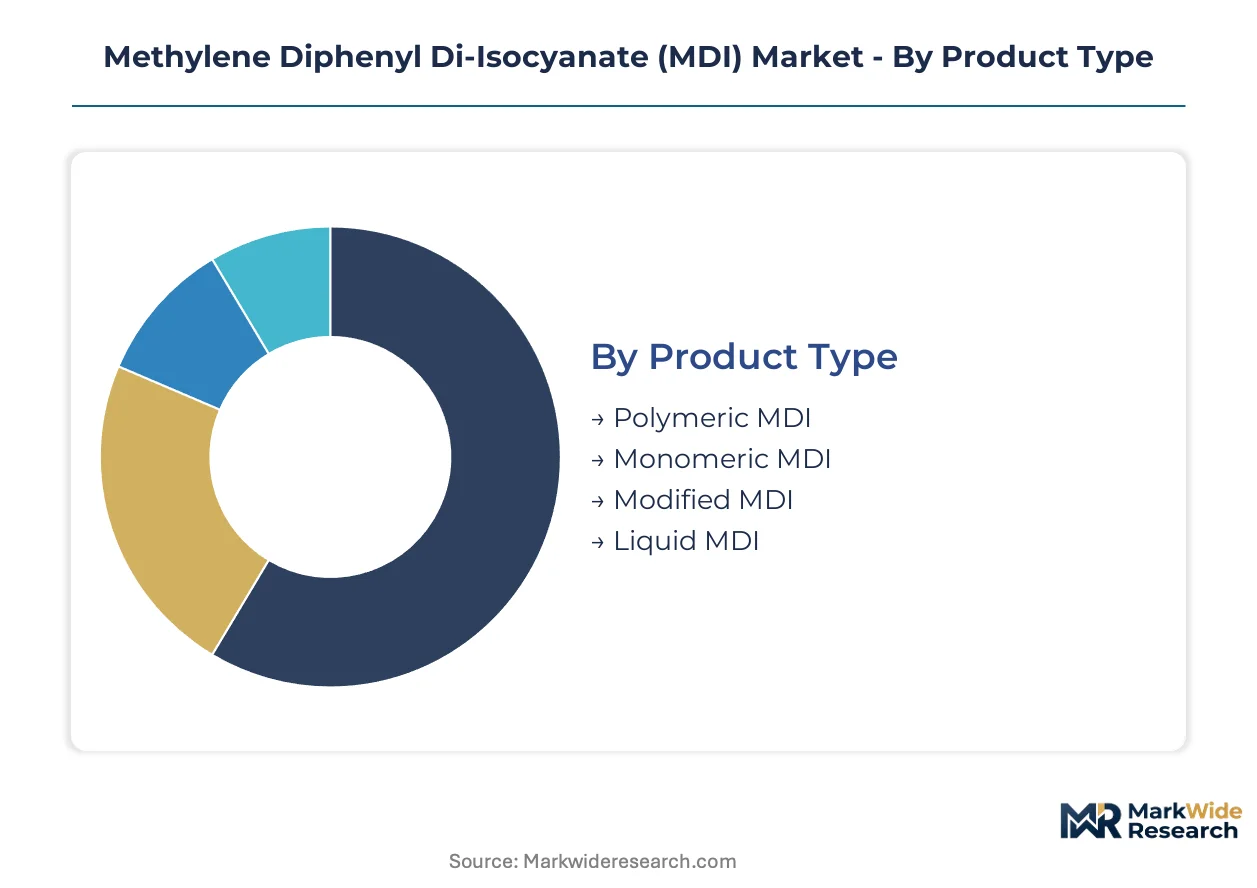
MDI segmentation reflects divergent margin profiles across product chemistries and end-use specifications. Construction insulation pulls polymeric MDI volumes while automotive seating drives modified MDI premiums. Distribution channel selection varies with customer scale and formulation complexity requirements.
Product Type:
Cost tier differentiation separates commodity polymeric grades from specification-driven modified variants.
- Polymeric MDI:A blend of MDI isomers with higher functionality oligomers, typically containing 40-60% di-isocyanate monomer content. Demand concentrates in Germany's industrial chemical corridor where BASF and Covestro supply rigid foam insulation panel producers facing EU F-Gas Regulation compliance deadlines.
- Modified MDI:Pre-reacted variants containing carbodiimide, uretonimine, or allophanate modifications to reduce reactivity and vapor pressure. Automotive seating specifications in electric vehicle platforms are pulling low-VOC formulations from European producers with REACH-registered toxicological dossiers.
- Monomeric MDI:Purified 4,4'-MDI isomer above 98% concentration for high-performance elastomers and coatings.
- Liquid MDI:Low-temperature storage variants with crystallization inhibitors for small-volume applicators lacking heated handling infrastructure.
Polymeric MDI holds installed capacity. Modified MDI is rotating up the share rankings.
End User:
Application intensity varies with thermal performance mandates and lightweighting imperatives across sectors.
- Construction:Rigid polyurethane foam insulation for facade, roof, and foundation systems. Germany's Building Energy Act renovation frameworks are specifying polyurethane boards for existing building stock retrofits.
- Automotive:Interior trim, seating, and structural composite applications. Electric vehicle platforms are specifying low-emission MDI variants as OEMs tighten interior air quality protocols.
- Furniture:Flexible foam cushioning for residential and contract seating.
- Footwear:Microcellular polyurethane soles and synthetic leather applications.
Construction maintains volume leadership. Automotive is gaining share fastest on lightweighting specifications.
Application:
Volume concentration tracks blowing-agent chemistry transitions and cold-chain infrastructure buildout.
- Foams:Rigid and flexible polyurethane cellular structures for insulation, cushioning, and packaging. Refrigerated warehousing expansion in emerging economies is pulling polymeric MDI into insulated panel applications for temperature-controlled logistics.
- Coatings:Two-component polyurethane protective and decorative finishes. Industrial maintenance specifications in marine and infrastructure sectors are driving solvent-free formulations.
- Adhesives:Structural bonding systems for construction and transportation assembly.
- Sealants:Elastomeric joint fillers for building envelope and transportation applications.
Foams command capacity allocation. Coatings are climbing the fastest on environmental compliance reformulation.
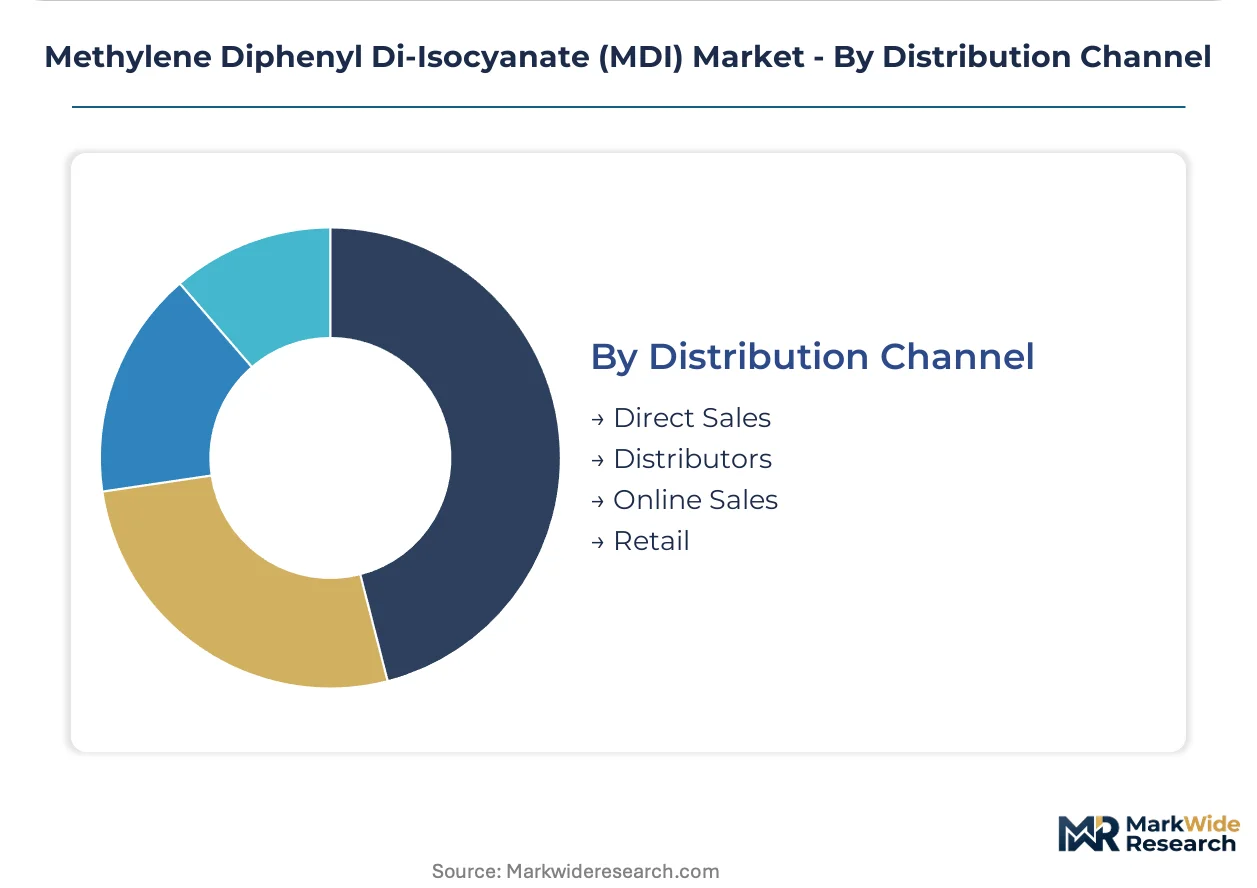
Distribution Channel:
Customer scale and technical service requirements determine channel selection across the value chain.
- Direct Sales:Long-term offtake agreements with indexed pricing for large insulation panel and appliance manufacturers. Germany's industrial chemical corridor exhibits consolidated procurement with vendor-managed inventory arrangements.
- Distributors:Regional stockholding for mid-volume formulators lacking storage infrastructure for isocyanate handling.
- Online Sales:Small-volume transactional purchasing for specialty coatings and adhesives compounding.
- Retail:Consumer-packaged quantities for minor repair and DIY applications.
Direct Sales anchors volume flows. Distributors are expanding coverage as regional formulator networks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE enforces dual carbon goals that constrain coal-based aniline feedstock expansion, while Germany's Building Energy Act and the US EPA Toxic Substances Control Act create divergent compliance pathways across major production centers.
China
Wanhua Chemical Group Co. extends its Ningbo complex into one of the world's largest integrated MDI-to-foam production sites. The MEE's dual carbon goals redirect investment away from coal-chemical clusters in Shandong and Jiangsu provinces toward naphtha-based routes. Yantai and Ningbo complexes now supply polymeric MDI into Southeast Asian construction markets facing oversupply pressure.
Germany
BASF SE and Covestro AG anchor production in the industrial chemical corridor between Ludwigshafen and Leverkusen. The EU F-Gas Regulation phase-down accelerates water-blown rigid foam adoption for Building Energy Act retrofit mandates. Backward integration into aniline and nitrobenzene precursors preserves margin visibility against feedstock volatility.
United States
Refrigerated warehousing expansion along Gulf Coast logistics corridors pulls polymeric MDI into insulated panel applications. EPA Toxic Substances Control Act Section 5 requirements add pre-manufacture notification burdens for novel MDI derivatives. Texas and Louisiana chemical complexes face stranded asset risk as carbon pricing mechanisms penalize high-intensity production routes.
India
Affordable housing and commercial real estate pipelines remain underpenetrated by rigid polyurethane insulation relative to extruded polystyrene alternatives. The Bureau of Indian Standards enforces building code compliance for thermal performance in new construction. Maharashtra and Gujarat industrial zones attract import substitution investment as domestic formulator networks proliferate.
Japan
Automotive seating specifications for electric vehicle platforms demand low-VOC modified MDI variants. METI guides industrial chemical producers toward carbon neutrality roadmaps with Scope 3 disclosure requirements. Chubu and Kansai manufacturing clusters specialize in high-purity monomeric grades for coatings and elastomer applications.
Methylene Diphenyl Di-Isocyanate (MDI) Market Competitive Landscape
Integrated petrochemical conglomerates and specialized isocyanate producers split the market between scale-driven commodity supply and specification-grade premium positioning. Concentration remains high at the polymeric MDI tier where backward integration into aniline precursors creates defensive moats. Three archetypes dominate: Asian state-linked champions with domestic market anchoring, European industrial incumbents with REACH-registered toxicological dossiers, and North American diversified chemical majors with Gulf Coast feedstock access. Competitive moves center on capacity expansion in low-carbon jurisdictions and portfolio diversification into modified grades for automotive lightweighting.
Among Asian producers, Wanhua Chemical Group Co. exemplifies the state-linked champion archetype with integrated Ningbo operations. Covestro AG and BASF SE occupy positions within the European incumbent tier, leveraging REACH compliance infrastructure and automotive specification relationships. These three anchors represent divergent strategic responses to feedstock decarbonization pressures and blowing-agent transition timelines.
| Leading Market Players |
|---|
| Wanhua Chemical Group Co. |
| Covestro AG |
| BASF SE |
| Dow Chemical Company |
| Huntsman Corporation |
| Kumho Mitsui Chemicals |
| Tosoh Corporation |
| Hexion Inc. |
| Merck KGaA |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp barge freight corridors transmit benzene and nitrobenzene cost volatility directly into MDI production economics, compressing margin visibility for non-integrated producers while amplifying price differentiation between backward-integrated majors and merchant-market suppliers. This logistics-cost dynamic concentrates pricing power with producers commanding captive aniline supply in Germany and China, forcing smaller formulators to absorb basis-risk exposure or surrender volume commitments.
Pricing Analysis
Regional price spreads between Ningbo export quotations and European domestic contract levels now exceed historical norms as Chinese oversupply conditions depress Asian spot markets while EU F-Gas Regulation compliance sustains premium rigid foam formulations. Contract-based long-term offtake agreements with indexed benzene pricing anchor volume flows for insulation panel manufacturers, whereas spot-market polymeric MDI trades at widening discounts to contract tiers. Price differentiation hinges on REACH-registered toxicological dossiers and ISO 9001 certification status for automotive specifications. Pricing pressure stems from Wanhua's Ningbo capacity additions flooding Southeast Asian markets. Construction formulators exhibit highest price sensitivity due to specification commoditization, while electric vehicle seating programs demonstrate lowest sensitivity given VOC compliance premiums.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities now structure working-capital relationships between integrated MDI producers and downstream insulation panel manufacturers, particularly in Germany's industrial chemical corridor. Supply concentrates in China, Germany, and the United States as Wanhua, BASF, and Covestro command two-thirds of installed nameplate capacity. Raw material dependencies center on benzene, nitrobenzene, and phosgene feedstocks with aniline synthesis representing the critical margin-determining step. Single-source vulnerability concentrates in Shandong province coal-chemical clusters facing MEE emissions intensity targets. Distribution runs through direct sales channels for large appliance OEMs and regional distributor networks for mid-volume formulators lacking heated storage infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MDI market fragmentation accelerates as blowing-agent chemistry transitions and dual carbon compliance requirements splinter formerly standardized specifications, creating defendable niches for specialized modified-grade producers and regional formulator networks.
For Market Incumbents: Entrench position through backward integration into bio-based aniline pilot production hedging EU carbon border adjustment exposure, while accelerating water-blown rigid foam formulation partnerships with German insulation panel producers facing Building Energy Act retrofit deadlines. Mineral wool substitution in fire-critical commercial applications and REACH authorization timeline extensions for isocyanate derivatives constitute immediate threats requiring toxicological dossier expansion and non-halogenated flame-retardant co-development with downstream partners. For New Entrants and Emerging Players: Build out regional compounding capabilities in Maharashtra and Gujarat industrial zones serving India's underpenetrated affordable housing insulation market, where Bureau of Indian Standards thermal performance enforcement is displacing extruded polystyrene specifications. Modified MDI supply for electric vehicle seating programs offers the most penetrable entry vector given low-VOC formulation scarcity and incumbent capacity allocation toward commodity polymeric grades. Go-to-market execution should leverage technical service partnerships with domestic automotive Tier 1 suppliers lacking REACH-registered formulation expertise. For Investors and Strategic Acquirers: European REACH-registered specialty isocyanate formulators with automotive specification relationships represent the priority acquisition archetype, offering compliance infrastructure and customer intimacy that capital-intensive commodity producers cannot replicate organically. Long-term viability across the analysis window rests on feedstock decarbonization pathway credibility and blowing-agent transition execution speed. The signal to watch is MEE permitting velocity for naphtha-based aniline expansions versus coal-chemical retrofit approvals, which would recalibrate Chinese export pricing dynamics and regional margin distribution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aniline Precursors | Captive nitrobenzene supply insulates BASF and Covestro from benzene volatility in Ludwigshafen-Leverkusen corridor. |
| Water-Blown Foam Formulation Partnerships | Collaborative R&D with German insulation panel producers accelerates F-Gas Regulation compliance without hydrocarbon blowing-agent capital. |
| Modified MDI Capacity Addition | Low-VOC variant investment captures electric vehicle seating premiums as OEMs tighten interior air quality protocols. |
| Bio-Based Aniline Pilot Scale-Up | Renewable feedstock demonstration plants create Scope 3 disclosure hedges against EU carbon border adjustment mechanisms. |
| Regional Compounding Joint Venture | Local production in Maharashtra industrial zones reduces import logistics costs for Indian construction formulator networks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with polyurethane foam plant managers, procurement leads at insulation panel OEMs, distribution channel partners in Germany's industrial chemical corridor, and technical R&D directors overseeing modified MDI formulation development. Secondary validation drew from customs and trade flow databases, Cefic and ACC chemical industry reports, SEC 10-K filings of listed isocyanate producers, and EU REACH substance evaluation dossiers. Bottom-up capacity and consumption estimates were triangulated against top-down macroeconomic drivers across the analysis window.
Calibration against historical capacity utilization rates and price realization data informed the analytical framework for segment-level projections. Segmentation dimensions modeled include product chemistry tier, end-use industry vertical, blowing-agent formulation type, and regional production hub classification. CAGRs were derived from regression analysis of demand drivers against observed consumption elasticities. Forecast inputs incorporated EU F-Gas Regulation phase-down schedules, MEE dual carbon permitting trajectories, and Building Energy Act renovation mandate implementation pacing.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-linked champions or accelerated REACH restriction listings for isocyanate derivatives would shift outcomes substantially from modeled trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Process Chromatography Market
Industrial Chemicals
Rust Preventive Oil Market
Industrial Chemicals
Global Refrigerants Market
Industrial Chemicals
Global Sponge Applicator Market
Industrial Chemicals
Drum Melters Market
Industrial Chemicals
Welding Electrodes Market
Industrial Chemicals
Shea Olein Market
Industrial Chemicals
Cobalt Acetate Solution Market
Industrial Chemicals
Dynamite Market
Industrial Chemicals
Acetylene Market
Industrial Chemicals
Machine Tool Oils Market
Industrial Chemicals
High Pressure Roll Compactor Market
Industrial Chemicals
Global Metalworking Fluids Market
Industrial Chemicals
Batch Reactors Market
Industrial Chemicals
Swimming Pool Salt Chlorinator Market
Industrial Chemicals
Global Low GWP Refrigerants Market