
 Diisononyl Phthalate (DINP) Market | 2026-2036
Diisononyl Phthalate (DINP) Market Size, Share, and Industry Trends Forecast 2026-2036
Diisononyl Phthalate (DINP) Market Analysis
High-purity DINP grades is rotating toward center stage as downstream buyers enforce stricter volatility and migration limits. BASF SE leverages integrated C4 value chains to sustain cost-competitive supply across European flexible PVC compounders. ExxonMobil anchors North American volume through captive oxo-alcohol feedstock positions. Mitsubishi Chemical Holdings Corporation specializes in low-odor, low-fogging variants tailored to Japanese automotive interior specifications.
Diisononyl phthalate is a C9-branched dialkyl phthalate ester produced via oxo-alcohol phthalation, characterized by a molecular weight near 419 g/mol and a viscosity range that delivers optimal processability in polyvinyl chloride formulations. Its primary commercial purpose centers on imparting flexibility, durability, and low-temperature resistance to PVC compounds used across automotive interiors, construction membranes, and coated textiles. The plasticizers segment dominates value capture due to entrenched flexible PVC demand, while the automotive end-use industry exhibits the steepest growth trajectory as lightweighting and interior comfort specifications intensify. Industrial grade DINP retains the largest volume share, though technical grade formulations are gaining traction in specialty cable and flooring applications where extraction resistance commands price premiums.
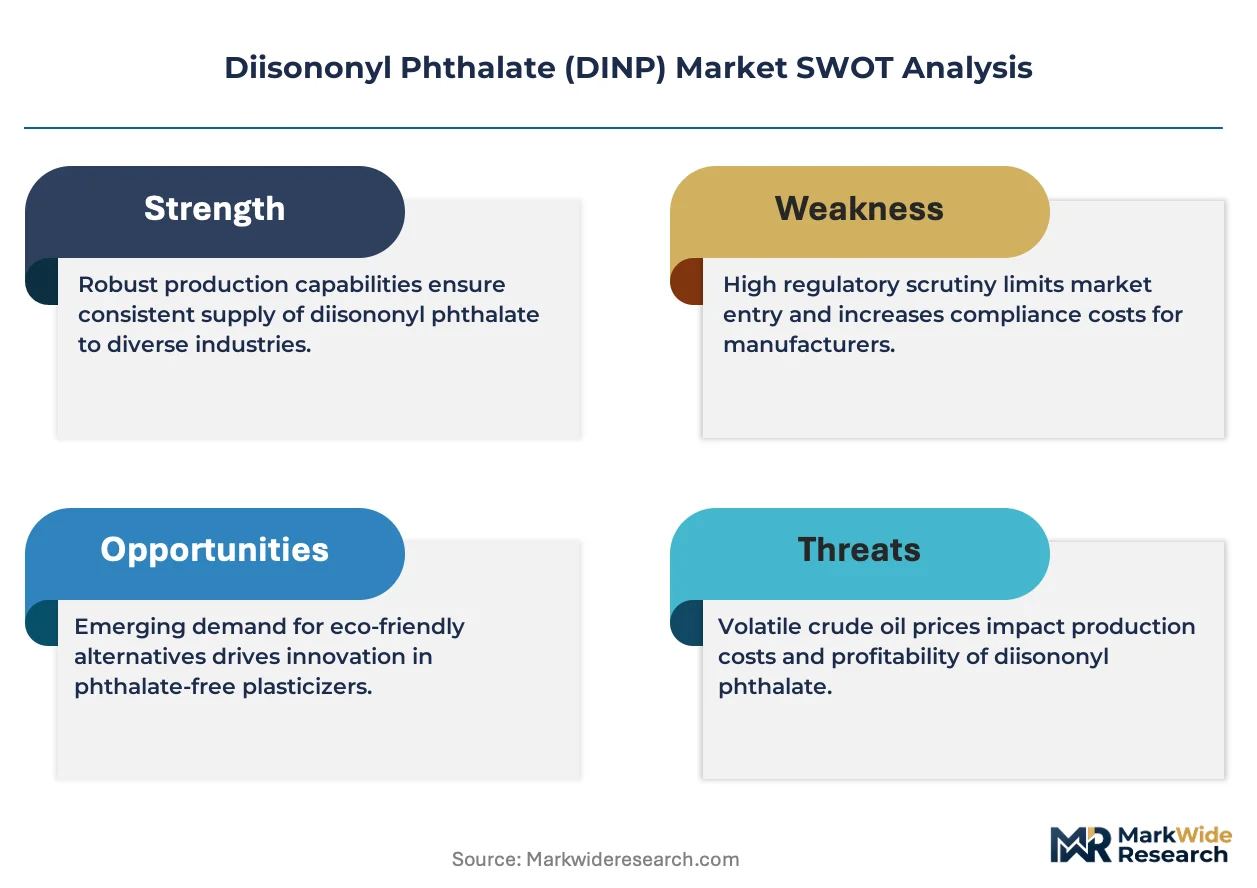
REACH registration requirements and the EU F-Gas Regulation indirectly tighten phthalate substitution economics, while the US EPA TSCA Section 6 risk evaluation framework shapes permissible exposure thresholds for DINP in consumer goods. China's GB standards and evolving MEE environmental compliance protocols are elevating production cost structures for domestic manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation mandates and secure uninterrupted market access across major consumption zones.
Market Dynamics
Flexible PVC compounders are pivoting toward high-purity DINP grades as downstream automotive OEMs enforce stricter volatility limits for cabin air quality, compressing margins for standard-grade producers while rewarding integrated oxo-alcohol suppliers.
Growth Catalysts
- REACH registration tiering:ECHA's differentiated data requirements for high-tonnage substances are accelerating consolidation among compliant European plasticizer manufacturers.
- Automotive interior lightweighting:Japanese and German OEMs specify low-fogging DINP variants for instrument panel skins and door panels, pulling volume from general-purpose alternatives.
- China construction membranes:GB standards for waterproofing materials in high-speed rail and commercial roofing are standardizing DINP-loaded PVC formulations.
Market Restraints
- Oxo-alcohol feedstock volatility:Propylene and n-butylene price swings directly transmit to DINP production economics, squeezing non-integrated compounders.
- Phthalate substitution chemistry:Bio-based adipates and trimellitates from specialty chemical suppliers are capturing niche cable and medical tubing applications.
- EU F-Gas Regulation spillover:Indirect pressure on PVC processing equipment emissions is raising compliance costs for flexible film extruders.
Strategic Opportunities
- Indian infrastructure buildout:BIS certification pathways for construction-grade plasticizers remain underdeveloped, creating first-mover positioning for compliant DINP suppliers.
- Recycled PVC integration:Mechanical recycling streams for post-consumer automotive trim require reformulated plasticizer packages with optimized migration resistance.
- MEE environmental protocols:China's tightened wastewater discharge standards are forcing domestic capacity rationalization, opening import substitution windows for compliant foreign producers.
Industry Challenges
- Migration testing talent scarcity:Analytical chemists capable of running EPA 8270 and ISO 16000 chamber methods command premium compensation, constraining quality control scaling.
- Legacy formulation requalification:Automotive Tier-1 suppliers face 18-24 month validation cycles to switch plasticizer grades, freezing procurement flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diisononyl Phthalate (DINP) Market |
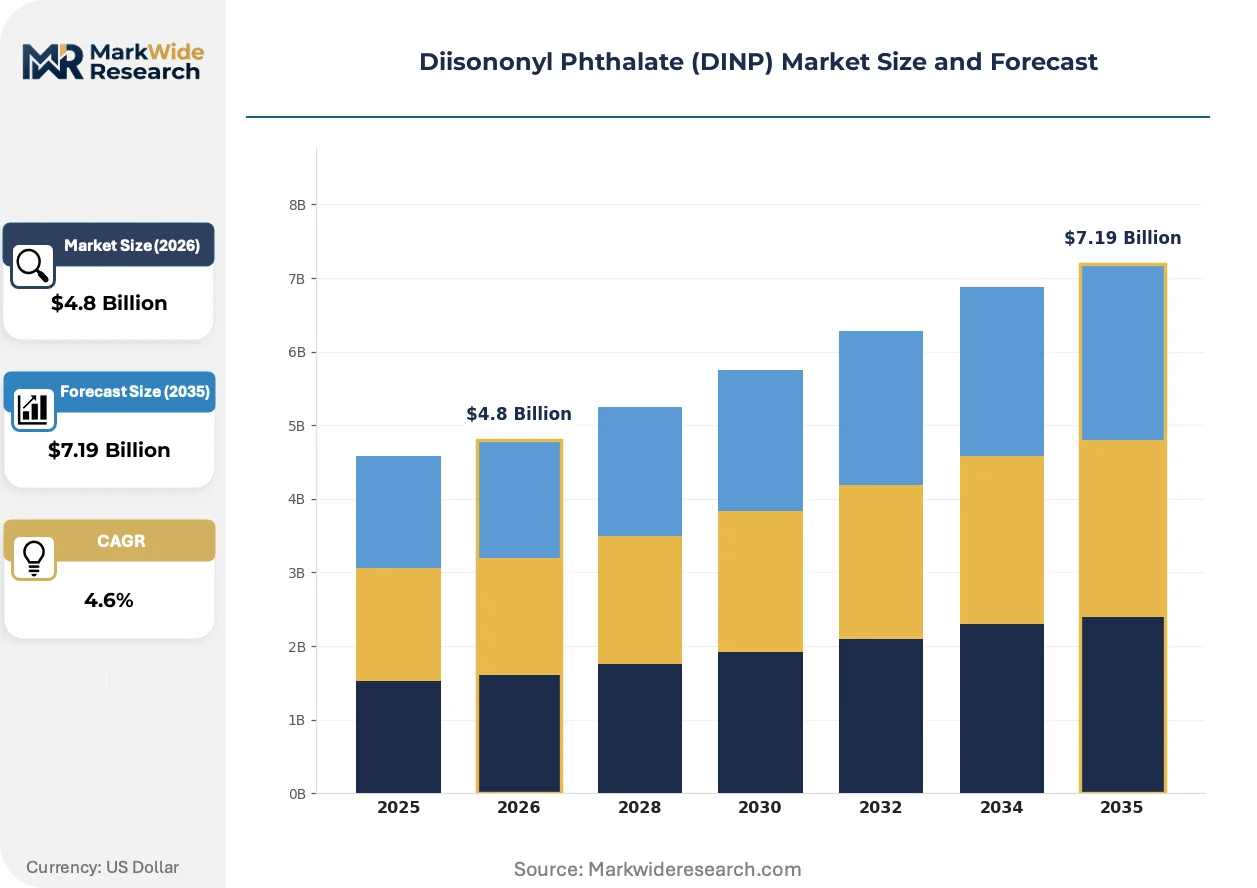
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasticizers, Adhesives, Coatings, Sealants End Use Industry: Automotive, Construction, Consumer Goods, Packaging Grade: Food Grade, Industrial Grade, Pharmaceutical Grade, Technical Grade Application: Flexible PVC, Non-Flexible PVC, Rubber, Textiles |
| Companies Covered | LG Chem, KLJ Group, BASF SE, AEKYUNG, Azelis Group, ExxonMobil, Mitsubishi Chemical Holdings Corporation, Nan Ya Plastics, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diisononyl Phthalate (DINP) Market Emerging Trajectories
DINP market evolution is splitting along purity-grade lines as regulatory thresholds tighten and end-use specifications diverge, with technology investment concentrating in migration-resistant molecular architectures.
Non-phthalate plasticizer technology is fragmenting the traditional DINP application map. Bio-based adipate esters and polymeric alternatives are capturing medical device and food-contact segments where FDA 21 CFR compliance costs have escalated. European cable compounders are trialing these substitutes in sheathing applications, compressing DINP's addressable market at the premium end while industrial-grade volumes hold steady.
EPA TSCA Section 6 risk evaluation frameworks are reshaping permissible exposure thresholds for DINP in consumer goods. The industrial consequence is a bifurcation between industrial compounds, which face moderate scrutiny, and children's product applications, where testing documentation requirements have intensified. US flooring and wallcovering manufacturers are responding by segregating supply chains and qualifying dedicated low-exposure grade streams.
Specification-driven procurement is consolidating buyer power among large automotive and construction compounders. Long-term offtake agreements with oxo-alcohol producers are displacing spot-market purchasing for volume-stable Tier-1 suppliers. This pattern is most visible in Germany and Japan, where OEMs have consolidated approved vendor lists to under ten qualified DINP sources per region.
Diisononyl Phthalate (DINP) Market Segmentation
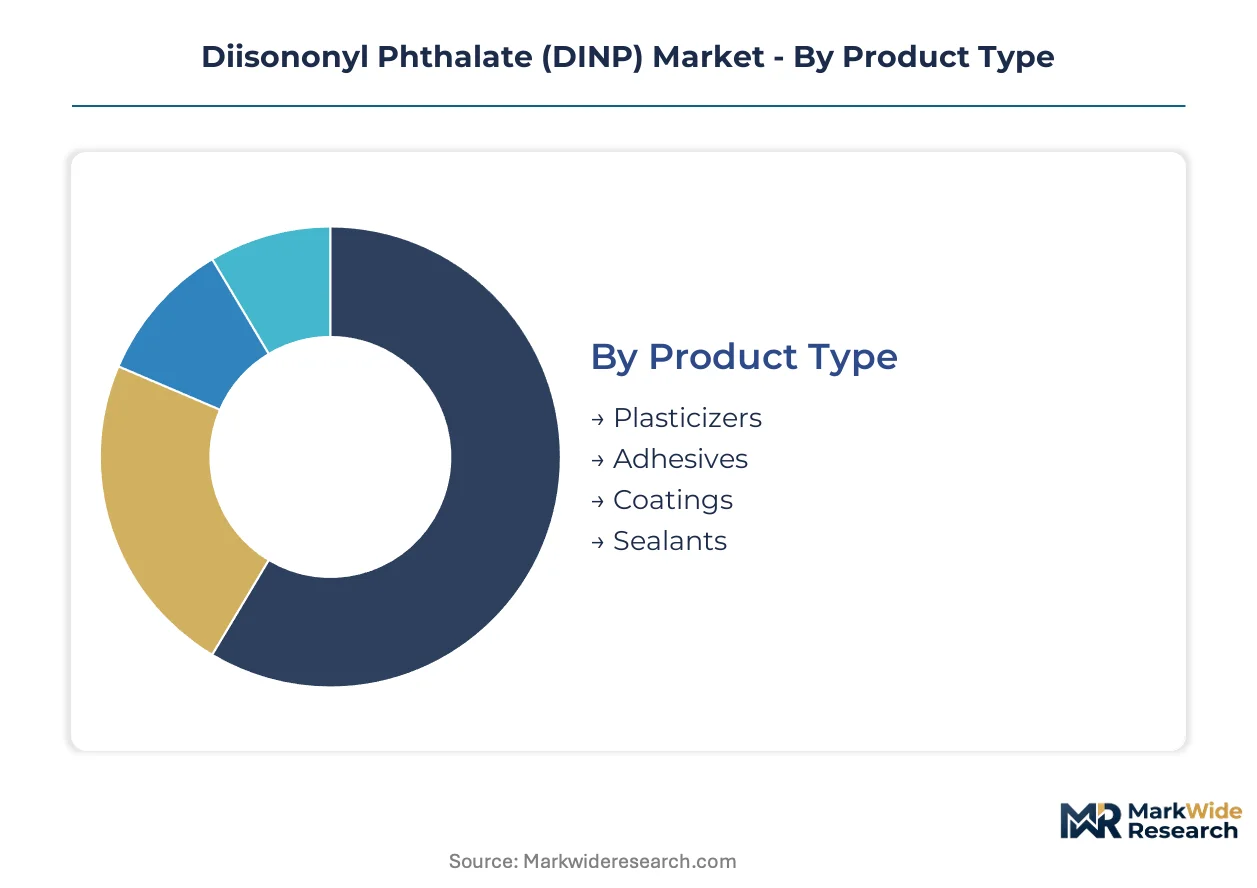
DINP demand fragments across purity thresholds and application durability requirements. Substitution pressure from bio-based alternatives intensifies competition in premium tiers while industrial volumes retain cost-driven loyalty.
Product Type:
Plasticizers face the most acute substitution threat as automotive OEMs and medical device manufacturers accelerate non-phthalate trials.
- Plasticizers:C9-branched dialkyl esters dominate flexible PVC compounding with viscosity optimized for extrusion and calendering. Automotive interior specifications in Germany and Japan are pulling volume toward low-fogging, low-odor variants as cabin air quality standards tighten.
- Adhesives:Pressure-sensitive and construction adhesive formulations exploit DINP's compatibility with acrylic and rubber-based polymers. Flooring installation adhesives in China's commercial real estate sector standardize DINP-loaded systems for peel strength consistency.
- Coatings:Protective and decorative film formers leverage plasticizer permanence for weathering resistance.
- Sealants:Caulk and gasket compounds depend on migration resistance for joint durability.
Plasticizers retain volume leadership; adhesives hold the steepest expansion curve.
End Use Industry:
Cost tier stratification separates specification-driven automotive procurement from price-sensitive construction buying.
- Automotive:Instrument panel skins, door panels, and seating upholstery demand low-fogging DINP grades meeting JIS and OEM-specific chamber tests. German and Japanese manufacturers enforce approved vendor lists under ten qualified sources per region.
- Construction:Waterproofing membranes, flooring, and wallcoverings consume industrial-grade volumes where GB standards in China and EN norms in Europe set migration limits. High-speed rail and commercial roofing projects in China concentrate demand for compliant formulations.
- Consumer Goods:Toys, childcare articles, and household products face EPA TSCA Section 6 and REACH restrictions on phthalate content.
- Packaging:Flexible films and containers encounter food-contact regulatory barriers limiting DINP adoption.
Construction commands volume leadership; automotive claims the steepest expansion trajectory.
Grade:
Application maturity determines margin capture, with technical grades defending premium positioning against specialty adipate incursions.
- Industrial Grade:Standard-purity formulations serve bulk flexible PVC compounding where cost minimization outweighs volatility specifications. Construction membranes and general-purpose flooring absorb the majority of this tier.
- Technical Grade:Enhanced purity and extraction-resistant molecular architectures target cable sheathing and specialty flooring where performance commands price premiums. European cable compounders trial these formulations against bio-based substitutes.
- Food Grade:Stringent FDA 21 CFR and EFSA compliance costs restrict addressable market scope.
- Pharmaceutical Grade:Medical tubing and device applications face intense non-phthalate substitution.
Industrial grade retains volume leadership; technical grade climbs the fastest.
Application:
Customer type concentration separates specification-captive automotive tiers from dispersed construction procurement.
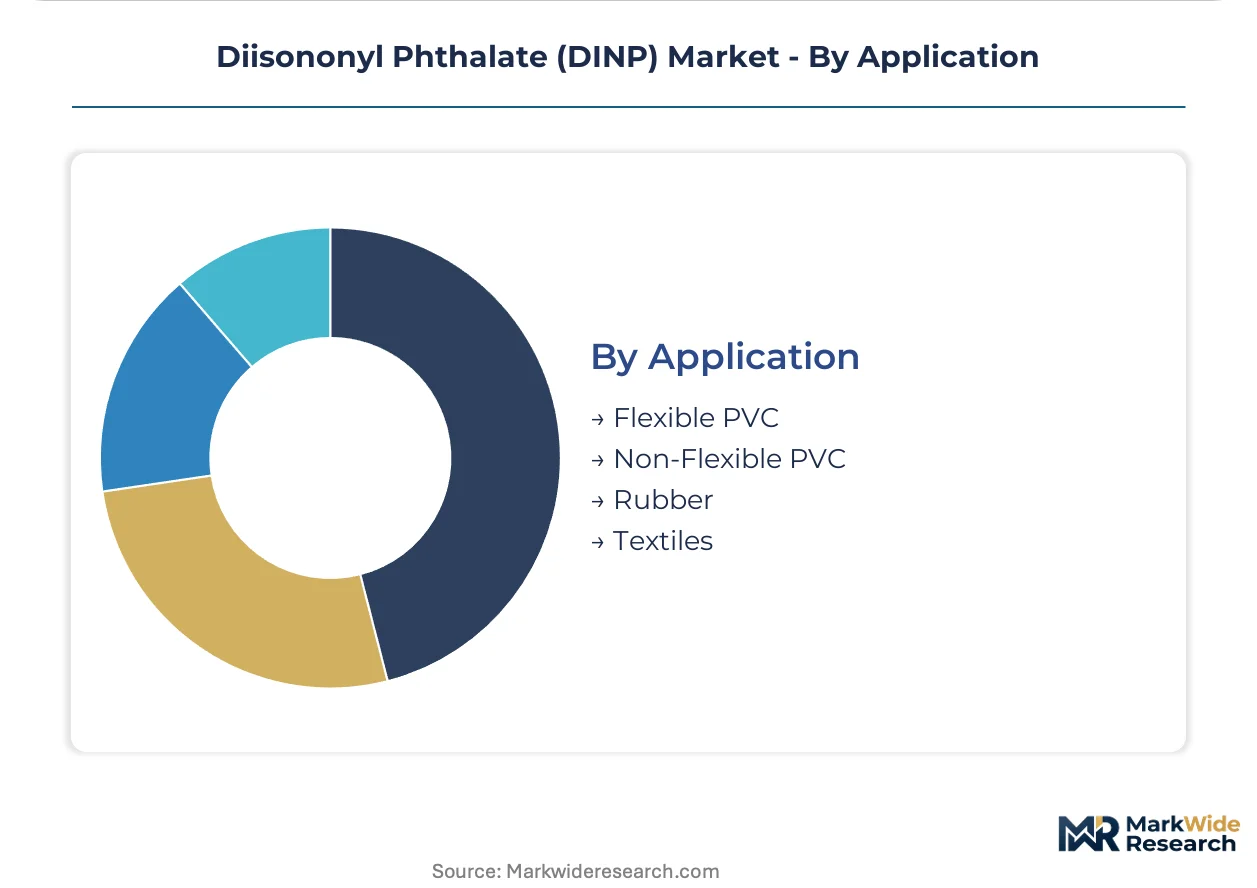
- Flexible PVC:Wire insulation, synthetic leather, and coated textiles constitute the core demand reservoir. Automotive OEMs in Germany, Japan, and the US consolidate long-term offtake agreements with integrated oxo-alcohol suppliers to secure volume stability.
- Non-Flexible PVC:Rigid pipe and profile applications employ DINP for limited flexibility modulation where impact resistance requirements apply.
- Rubber:Seal and gasket formulations exploit plasticizer compatibility with nitrile and EPDM elastomers.
- Textiles:Coated fabrics and artificial leather applications compete with water-based polyurethane alternatives.
Flexible PVC retains volume leadership; rubber holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oxo-alcohol production clusters in East Asia and the US Gulf Coast concentrate DINP supply capacity, while European REACH compliance costs and Chinese environmental enforcement reshape regional competitive positions. Demand dispersion follows automotive manufacturing footprints and construction investment cycles across four major consumption zones.
China
High-speed rail waterproofing membranes and commercial roofing drive DINP consumption in construction applications. MEE environmental protocols tighten wastewater discharge standards for domestic oxo-alcohol producers. The Yangtze River Delta plasticizer compounding cluster around Shanghai faces capacity rationalization as compliance costs escalate.
United States
Automotive interior lightweighting specifications from Detroit-based OEMs pull low-fogging DINP grades into instrument panel and door panel formulations. EPA TSCA Section 6 risk evaluations reshape permissible exposure thresholds for consumer goods applications. The US Gulf Coast petrochemical corridor anchors captive oxo-alcohol feedstock positions for integrated suppliers.
Germany
Flexible PVC compounders serving Volkswagen, BMW, and Mercedes-Benz enforce approved vendor lists under ten qualified DINP sources. REACH registration tiering accelerates consolidation among high-tonnage substance manufacturers. The Ruhr industrial basin concentrates legacy plasticizer production capacity facing margin compression from purity-grade bifurcation.
Japan
JIS standards for cabin air quality drive specification of low-odor, low-fogging DINP variants in automotive interiors. METI industrial standards coordinate with OEM-specific chamber test protocols. The Chubu region around Nagoya hosts specialized automotive compounders qualifying dedicated plasticizer supply streams.
Diisononyl Phthalate (DINP) Market Vendor Landscape
Concentration sits with integrated petrochemical majors controlling captive oxo-alcohol feedstock positions. Three to five suppliers capture majority volume in each major geography, with specialty compounders and regional distributors occupying fragmented downstream tiers. Strategic archetypes split between backward-integrated petrochemical giants, formulation-specialist compounders, and specification-focused automotive suppliers. Competitive moves center on long-term offtake agreements with automotive Tier-1s and selective capacity expansion in high-purity grade segments.
Within the integrated petrochemical tier, BASF SE and ExxonMobil exemplify archetypes leveraging captive C4 value chain control. BASF SE occupies a position representing European supply stability through Ludwigshafen-anchored production. ExxonMobil anchors North American volume security through Gulf Coast feedstock integration. Mitsubishi Chemical Holdings Corporation sits within the specialty-grade vector, exemplifying low-fogging formulation expertise aligned with Japanese automotive specifications.
| Leading Market Players |
|---|
| LG Chem |
| KLJ Group |
| BASF SE |
| AEKYUNG |
| Azelis Group |
| ExxonMobil |
| Mitsubishi Chemical Holdings Corporation |
| Nan Ya Plastics |
| Evonik Industries |
| Others |
Supply Flow & Price Mechanics
Bio-based adipate esters displacing DINP in medical tubing and food-contact applications simultaneously redraws supply geography toward renewable feedstock clusters and compresses pricing premiums in legacy phthalate tiers. This substitution dynamic forces integrated oxo-alcohol producers to defend position through captive C4 value chain control while specialty compounders absorb margin pressure from dual-sourcing requirements.
Pricing Analysis
REACH registration tiering dictates the pricing tier structure across European flexible PVC compounders, separating high-purity grades commandeering automotive OEM contracts from industrial formulations serving construction membranes. Three-tier pricing structure across premium low-fogging, standard technical, and economy industrial levels stratifies by extraction resistance and volatility specifications. Pricing pressure stems from propylene and n-butylene feedstock volatility transmitting directly to non-integrated producers. Construction sector buyers exhibit highest price sensitivity, while automotive Tier-1 suppliers prioritize specification compliance over unit cost.
Supply Chain Analysis
China and the United States anchor oxo-alcohol production capacity feeding DINP synthesis, with the Yangtze River Delta and US Gulf Coast petrochemical corridors concentrating upstream chemical manufacturing. Propylene and n-butylene feedstocks draw from regional steam cracker and refinery operations, while phthalic anhydride rests on ortho-xylene supply chains. Single-source vulnerability concentrates in C4 olefin availability for European compounders lacking backward integration. Distribution runs through qualified supplier lists maintained by automotive OEMs and bulk chemical distributors serving construction sector procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DINP procurement is consolidating around platform-standardized plasticizer packages, with automotive OEMs enforcing interoperability across instrument panel and seating specifications that lock compounders into approved vendor ecosystems.
For Market Incumbents: Secure long-term offtake agreements with automotive Tier-1 suppliers before legacy formulation requalification cycles freeze procurement flexibility. BASF SE and ExxonMobil exemplify defensive positioning through captive oxo-alcohol integration that insulates margin structures from feedstock volatility. Capacity rationalization in China's Yangtze River Delta under MEE environmental protocols creates acquisition opportunities for compliant foreign producers seeking import substitution windows. For New Entrants and Emerging Players: Anchor in India's underdeveloped BIS certification pathways for construction-grade plasticizers, where infrastructure buildout concentrates demand for waterproofing membranes. Specialty low-fogging formulations for Japanese automotive interiors represent a penetrable niche against consolidated incumbent lists in Germany. Technical grade DINP for cable sheathing applications offers a specification-captive entry point where extraction resistance commands sustainable premiums. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed specialty chemical distributors holding fragmented regional positions in European flexible PVC compounding. Long-term viability hinges on migration testing capabilities and EPA TSCA Section 6 compliance documentation rather than commodity volume scale. Watch for MEE enforcement actions triggering domestic Chinese capacity closures as the inflection signal for import substitution opportunity timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oxo-Alcohol Feedstocks | BASF SE's Ludwigshafen complex demonstrates margin protection against propylene volatility. |
| Low-Fogging Formulation Development | Mitsubishi Chemical Holdings Corporation's JIS-compliant variants capture Japanese automotive specification premiums. |
| Long-Term Supply Agreement with Automotive Tier-1s | Volkswagen and BMW consolidated vendor lists under ten qualified sources per region. |
| MEE Environmental Compliance Investment | Yangtze River Delta producers face wastewater discharge standard rationalization. |
| Recycled PVC Plasticizer Package Reformulation | Post-consumer automotive trim streams require optimized migration resistance architectures. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with oxo-alcohol plant managers, flexible PVC procurement leads at automotive Tier-1 suppliers, distribution channel partners, and technical R&D directors; and secondary validation through customs/trade data, ACC and Cefic industry reports, SEC 10-K filings, and REACH registration databases. Bottom-up volume modeling triangulated against top-down value chain estimates derived from petrochemical feedstock consumption patterns.
Across the analysis window, the forecast framework modeled segmentation dimensions including grade tier purity thresholds, end-use industry specification requirements, and regional production hub regulatory compliance clusters. CAGRs were derived from elasticity-adjusted demand projections and capacity utilization assumptions. Industry-specific inputs incorporated automotive lightweighting content per vehicle trajectories and Chinese high-speed rail waterproofing membrane deployment rates.
Underlying assumptions cover REACH tiering stability, MEE enforcement continuity, and oxo-alcohol feedstock price correlation persistence, with deviation risk concentrated in EPA TSCA Section 6 risk evaluation outcomes and bio-based plasticizer substitution acceleration. Recalibration cycles align with material shifts in automotive OEM approved vendor list revisions and major regulatory framework updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Reconditioned Drums Market
Industrial Chemicals
VOC Concentrator Market
Industrial Chemicals
Dewatering Aids Market
Industrial Chemicals
Modified Bitumen Market
Industrial Chemicals
Thermally Stable Antiscalant Market
Industrial Chemicals
Automotive Chemicals Market
Industrial Chemicals
Food Grade Grease Market
Industrial Chemicals
Quenching Fluids and Salts Market
Industrial Chemicals
Heat Shrink Tubes Market
Industrial Chemicals
Fluidized Bed Reactors Market
Industrial Chemicals
Cryolite Market
Industrial Chemicals
Continuous Reactors Market
Industrial Chemicals
Thermic Fluids Market
Industrial Chemicals
Pickling Chemicals Market
Industrial Chemicals
Anti-Corrosive Agents Market
Industrial Chemicals
Electroelutor Market