
 Phthalonitrile Resin Market | 2026-2036
Phthalonitrile Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Phthalonitrile Resin Market Analytics
REACH compliance in Europe is broadening the cost-of-entry calculus for phthalonitrile resin suppliers seeking CE-marked aerospace qualifications. Toray Industries leverages its carbon fiber prepreg integration to dominate high-temperature composite supply chains. Evonik Industries anchors European specialty chemical production with controlled phthalonitrile monomer synthesis. Huntsman Corporation competes through differentiated curing agent portfolios that extend processing windows for thick-section laminates.
Phthalonitrile resin denotes a high-performance thermoset polymer synthesized from dicyanobenzene precursors, exhibiting thermal stability exceeding 375°C in cured form and retaining mechanical integrity under prolonged oxidative exposure. The material primarily serves structural applications requiring fire-smoke-toxicity compliance and resistance to jet fuel, hydraulic fluid, and de-icing chemicals. Thermosetting formulations lead volume consumption due to established aerospace qualification protocols, while thermoplastic variants represent the fastest-growing category as out-of-autoclave processing gains traction among OEMs seeking cycle time reductions. Electrical insulation applications concentrate margin pools where IEC 60243 dielectric standards and UL 94 V-0 ratings command specification premiums.
EPA oversight governs volatile organic compound emissions during resin synthesis and solvent-based coating operations in the United States, while REACH registration requirements in Europe mandate full substance toxicity dossiers for phthalonitrile monomer import. EASA certification specifications for aircraft interior materials create parallel compliance pathways that shape product development roadmaps. Stakeholders must monitor pending amendments to FAA fireworthiness standards and corresponding EASA harmonization timelines, as these will determine which curing chemistry platforms retain qualification currency across transatlantic supply chains.
Market Dynamics
Aerospace OEMs are consolidating thermoset procurement around phthalonitrile platforms as next-generation engine programs demand fire-smoke-toxicity compliance beyond 375°C operational thresholds, compressing qualification timelines for incumbent epoxy-bismaleimide systems.
Growth Catalysts
- REACH substance registration:ECHA's phased dossier requirements for high-tonnage monomer import are accelerating supplier consolidation toward qualified European manufacturers with existing toxicity data packages.
- Out-of-autoclave processing:Thermoplastic phthalonitrile variants are gaining traction among airframe integrators seeking cycle time reductions for thick-section primary structures.
- China:Domestic COMAC C919 and CR929 programs are redirecting thermoset procurement toward local resin compounders with CAAC qualification pathways.
Market Restraints
- Dicyanobenzene feedstock volatility:Precursor concentration among Chinese specialty chemical producers exposes formulation costs to regional supply interruptions and export licensing delays.
- Epoxy-bismaleimide hybrid substitution:Lower-cost high-temperature thermosets retain incumbent status in secondary structural applications where full phthalonitrile thermal performance exceeds design requirements.
- FAA-EASA harmonization friction:Divergent fireworthiness certification timelines create duplicate testing burdens for suppliers seeking dual qualification for transatlantic OEM supply chains.
Strategic Opportunities
- Electrical insulation grade penetration:IEC 60243 dielectric certification and UL 94 V-0 ratings command specification premiums in power distribution and EV battery enclosure applications.
- India:BIS standardization for aerospace materials and PLI scheme incentives for advanced composites are opening qualification pathways for imported resin systems.
- Digital curing monitoring:Integration of in-situ dielectric sensors with automated fiber placement equipment is enabling real-time viscosity control for thick laminate consolidation.
Industry Challenges
- High-temperature autoclave capacity scarcity:Qualification runs for primary structure laminates require extended cure cycles that strain available oven infrastructure at tier-1 composite fabricators.
- Formulation-to-fiber interface optimization:Carbon fiber surface treatment protocols developed for epoxy matrices require recalibration to achieve interlaminar shear strength targets with phthalonitrile chemistry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phthalonitrile Resin Market |
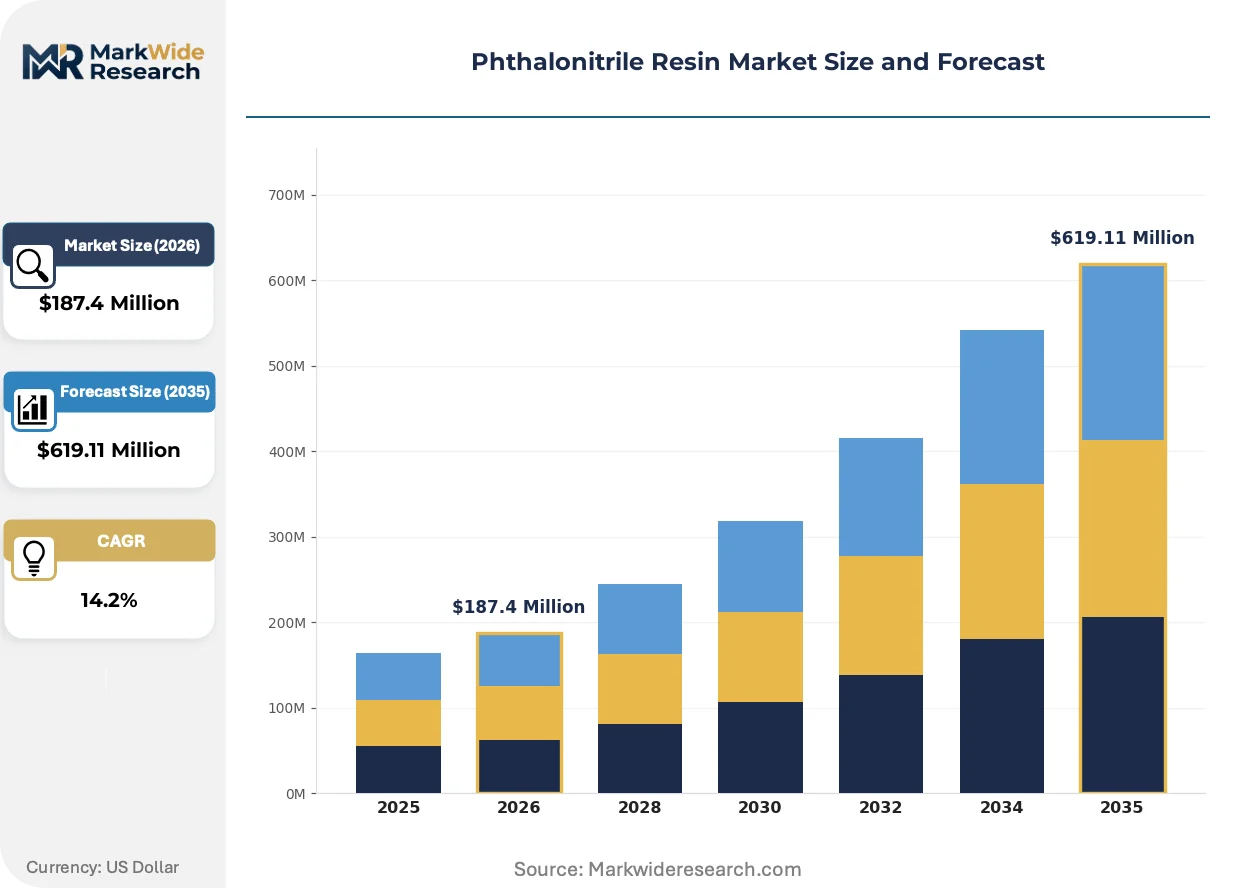
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermosetting, Thermoplastic, Solvent-Based, Water-Based Application: Aerospace, Electrical Insulation, Automotive, Coatings End User: Manufacturers, Contractors, Distributors, OEMs Technology: Polymerization, Injection Molding, Extrusion, Lay-Up |
| Companies Covered | Toray Industries, Evonik Industries, Lonza Group, BASF, DuPont de Nemours, Huntsman Corporation, Solvay, Mitsubishi Rayon, Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phthalonitrile Resin Market Evolving Landscape
Processing methodology and regulatory chemistry specifications are converging to reshape competitive positioning among thermoset suppliers serving aerospace and electrical insulation verticals.
Thermoplastic phthalonitrile formulations are expanding into primary airframe applications previously reserved for thermosetting systems. Boeing and Airbus tier suppliers are piloting these materials for wing spar caps and fuselage frames. The shift is compressing autoclave dependency and enabling welded joint configurations that eliminate mechanical fasteners.
EPA emissions standards governing volatile organic compound release during resin synthesis are tightening solvent recovery requirements at US manufacturing facilities. Formulators are responding with aqueous-based coating alternatives and closed-loop monomer purification systems. Small-batch specialty producers face disproportionate compliance costs relative to integrated chemical majors.
Buyer consolidation among tier-1 aerospace composite fabricators is compressing supplier qualification cycles and demanding extended performance warranties. Original equipment manufacturers are unbundling material certification from processing parameter validation, forcing resin suppliers to assume liability for out-of-specification cure outcomes. This pattern is most visible in US and French supply chains where Safran and Spirit AeroSystems have centralized thermoset procurement functions.
Phthalonitrile Resin Market Segmentation
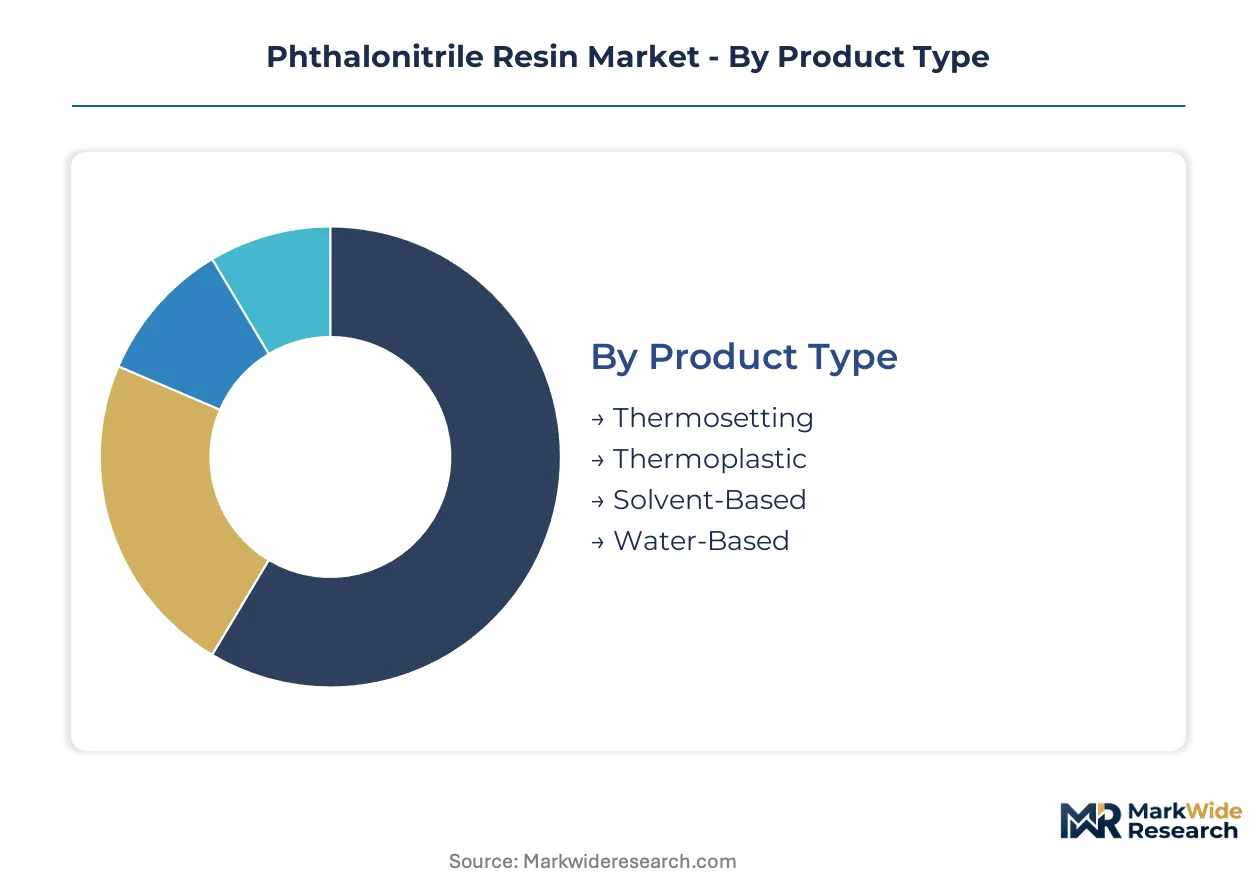
Phthalonitrile resin segmentation reveals divergent capital requirements across chemistry platforms and processing methodologies. Aerospace qualification protocols and electrical insulation certification standards create tiered barriers to entry that reshape supplier economics.
Product Type:
Thermosetting formulations demand substantial upfront investment in high-temperature autoclave infrastructure and extended cure cycle validation, while thermoplastic variants require precision extrusion and welding equipment for out-of-autoclave processing.
- Thermosetting:Cured through irreversible cross-linking reactions that deliver thermal stability exceeding 375°C, this chemistry dominates engine nacelle and exhaust fairing applications where FAA-EASA fireworthiness compliance is mandatory. Boeing and Airbus tier suppliers concentrate procurement around qualified thermosetting prepregs due to established aerospace certification pathways.
- Thermoplastic:Reversible melting behavior enables welded joint configurations and eliminates mechanical fasteners, compressing cycle times for thick-section primary structures. COMAC C919 program suppliers in China are accelerating adoption of thermoplastic phthalonitrile for wing spar caps as CAAC qualification timelines shorten.
- Solvent-Based:Conventional formulations rely on organic carrier systems that face tightening EPA volatile organic compound emission limits at US manufacturing facilities.
- Water-Based:Aqueous dispersion technologies reduce environmental compliance burdens but require reformulation to match solvent-based performance in chemical resistance applications.
Thermosetting absorbs the bulk of installed capacity; thermoplastic is expanding most quickly.
Application:
Application segmentation tracks directly to performance specification intensity, with aerospace and electrical insulation commanding premium pricing against automotive and coatings segments where cost thresholds constrain formulation selection.
- Aerospace:Structural composites for engine nacelles, exhaust fairings, and interior components must satisfy fire-smoke-toxicity standards beyond 375°C operational thresholds. Safran and Spirit AeroSystems have centralized thermoset procurement functions around phthalonitrile platforms for next-generation engine programs.
- Electrical Insulation:Power distribution equipment and EV battery enclosures require IEC 60243 dielectric certification and UL 94 V-0 ratings that command specification premiums through rigorous testing protocols.
- Automotive:Underhood thermal management components represent a cost-constrained segment where epoxy-bismaleimide hybrids retain incumbent status.
- Coatings:Protective surface treatments for chemical processing equipment face substitution pressure from ceramic and fluoropolymer alternatives.
Aerospace commands the dominant revenue share; electrical insulation demonstrates the steepest expansion trajectory.
End User:
End user structure reflects supply chain position and technical capability, with OEMs and tier-1 manufacturers driving specification development while distributors and contractors execute fulfillment and application services.
- Manufacturers:Composite fabricators and resin compounders with in-house formulation capabilities and direct aerospace qualification pathways capture margin pools through captive processing technology.
- OEMs:Boeing, Airbus, and COMAC airframe integrators unbundle material certification from processing parameter validation, forcing resin suppliers to assume liability for out-of-specification cure outcomes.
- Contractors:Field application specialists execute coating and repair operations under license from qualified material suppliers.
- Distributors:Inventory and logistics intermediaries serve secondary markets and smaller fabrication shops without direct supplier relationships.
Manufacturers retain the deepest value capture; OEMs are consolidating procurement influence fastest.
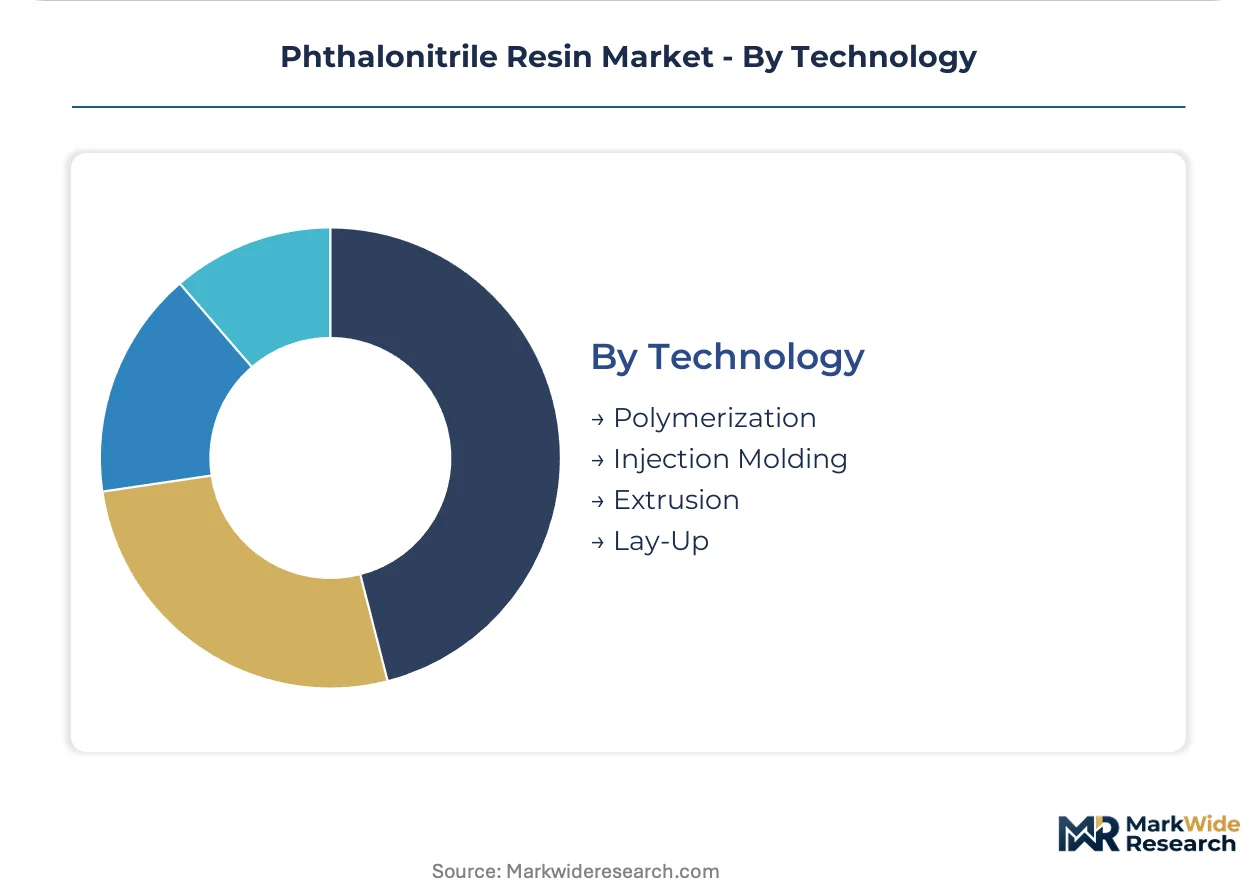
Technology:
Technology segmentation differentiates by processing sophistication and automation potential, with polymerization and automated fiber placement representing capital-intensive frontiers against conventional molding approaches.
- Polymerization:Controlled synthesis of phthalonitrile monomer from dicyanobenzene precursors requires closed-loop purification systems and REACH-compliant toxicity dossier maintenance for European market access.
- Lay-Up:Automated fiber placement with in-situ dielectric sensors enables real-time viscosity control for thick laminate consolidation, compressing qualification timelines for primary structures.
- Injection Molding:High-pressure processing of thermoplastic variants suits complex geometries in electrical insulation housings and automotive components.
- Extrusion:Continuous profile manufacturing supports welded joint configurations in airframe applications seeking fastener elimination.
Polymerization anchors the technology investment base; lay-up is climbing the fastest on automation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang Free Trade Zone tax incentives are concentrating phthalonitrile resin precursor capacity among specialty chemical producers serving COMAC supply chains.
United States
Spirit AeroSystems and Safran USA procurement consolidation drives specification standardization around thermosetting prepregs for engine nacelles. EPA volatile organic compound emission limits tighten solvent recovery requirements at Kansas and South Carolina manufacturing facilities. Wichita's aerospace cluster anchors qualification testing infrastructure for next-generation fireworthiness protocols.
China
COMAC C919 and CR929 programs redirect thermoset procurement toward local resin compounders with CAAC qualification pathways. MIIT dual carbon goals accelerate aqueous-based formulation development to reduce synthesis emissions. Yangtze River Delta chemical parks concentrate dicyanobenzene precursor production for captive phthalonitrile monomer supply.
Germany
ECHA REACH substance registration mandates full toxicity dossiers for phthalonitrile monomer import, accelerating supplier consolidation toward qualified European manufacturers. Evonik Industries anchors controlled monomer synthesis at Marl Chemical Park. Bavaria's aerospace tier-1 fabricators strain under high-temperature autoclave capacity scarcity for extended cure cycle validation.
France
Safran's centralized thermoset procurement function unbundles material certification from processing parameter validation, forcing resin suppliers to assume cure outcome liability. EASA fireworthiness certification timelines diverge from FAA harmonization, creating duplicate testing burdens. Toulouse-Blagnac aerospace cluster concentrates qualification runs for Airbus A320neo engine program composites.
India
BIS standardization for aerospace materials and PLI scheme incentives for advanced composites open qualification pathways for imported resin systems. CEA electrical insulation standards drive IEC 60243 dielectric certification demand for power distribution applications. Gujarat's specialty chemical corridor attracts formulation investments targeting EV battery enclosure specifications.
Phthalonitrile Resin Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across phthalonitrile resin supply chains. The vendor base stratifies into three tiers: integrated chemical majors with carbon fiber prepreg capabilities, specialty monomer producers with REACH-compliant synthesis infrastructure, and regional compounders serving localized aerospace qualification pathways. Consolidation pressures concentrate around curing agent portfolio differentiation and out-of-autoclave processing technology licensing. Strategic partnerships between resin suppliers and tier-1 composite fabricators compress qualification timelines while extending performance warranty obligations.
Among Japanese-based diversified materials groups, Toray Industries exemplifies the integrated archetype through carbon fiber prepreg dominance. German specialty chemical producers represented by Evonik Industries anchor European monomer synthesis with controlled production systems. US-based chemical manufacturers including Huntsman Corporation occupy positions defined by differentiated curing agent portfolios that extend processing windows for thick-section laminates.
| Leading Market Players |
|---|
| Toray Industries |
| Evonik Industries |
| Lonza Group |
| BASF |
| DuPont de Nemours |
| Huntsman Corporation |
| Solvay |
| Mitsubishi Rayon |
| Dow Chemical Company |
| Others |
Value Network & Pricing Analysis
Captive dicyanobenzene production in Yangtze River Delta chemical parks anchors both supply security and pricing power for Chinese resin compounders serving COMAC supply chains, while European REACH-compliant manufacturers leverage toxicity dossier control to sustain specification premiums.
Pricing Analysis
Short lead-time premiums for aerospace-qualified thermosetting prepregs compress margins at tier-1 fabricators facing autoclave capacity scarcity. Three-tier pricing structure across aerospace-certified, electrical insulation-grade, and industrial coating tiers reflects certification intensity and volume scale. Pricing pressure stems from epoxy-bismaleimide hybrid substitution in secondary structural applications. Automotive underhood components exhibit highest price sensitivity; aerospace engine nacelle programs show lowest.
Supply Chain Analysis
Certification gating through FAA-EASA fireworthiness protocols concentrates qualified supply among Toray Industries, Evonik Industries, and Huntsman Corporation with established aerospace pathways. Dicyanobenzene precursor supply draws from China, Germany, and Japan. Feedstock dependency rests on Chinese specialty chemical export licensing. Single-source vulnerability runs through Yangtze River Delta concentration. Distribution feeds from qualified prepreg manufacturers to tier-1 composite fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into dicyanobenzene precursor synthesis has become the decisive competitive lever as feedstock volatility and REACH registration costs reshape supplier economics.
For Market Incumbents: Lock in carbon fiber prepreg integration to defend against thermoplastic substitution threats. Extend performance warranty coverage to capture consolidated procurement functions at Spirit AeroSystems and Safran. Anchor backward integration into dicyanobenzene production to neutralize Chinese feedstock volatility. For New Entrants and Emerging Players: Digital curing monitoring partnerships with automated fiber placement equipment vendors open qualification pathway compression. Target electrical insulation grade penetration in India and EV battery enclosure specifications as the most penetrable white space. Pursue aqueous-based formulation licensing to bypass EPA emission compliance burdens. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty monomer producers with REACH-compliant synthesis infrastructure and established aerospace qualification dossiers. Long-term viability hinges on out-of-autoclave processing technology ownership. Watch FAA-EASA harmonization progress as the inflection signal for qualification cost normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dicyanobenzene | Captive precursor supply insulates formulation costs from Yangtze River Delta export licensing volatility. |
| Out-of-Autoclave Processing Technology | Thermoplastic variant licensing compresses cycle times for COMAC C919 wing spar cap applications. |
| REACH-Compliant Monomer Synthesis | Controlled production systems at Marl Chemical Park secure European aerospace qualification pathways. |
| Digital Curing Monitoring Integration | In-situ dielectric sensors enable real-time viscosity control for thick laminate consolidation. |
| Electrical Insulation Grade Certification | IEC 60243 and UL 94 V-0 ratings command specification premiums in EV battery enclosures. |
Research Methodology
Document review covered ECHA REACH registration databases, FAA fireworthiness certification filings, and COMAC supplier qualification records, complemented by interviews with aerospace composite procurement directors, resin formulation R&D leads, tier-1 fabricator plant managers, and carbon fiber prepreg technical directors. Secondary validation drew from SEC 10-K chemical segment disclosures, customs trade data for dicyanobenzene precursor flows, and ACC aerospace materials reports. Bottom-up resin consumption estimates triangulated against top-down OEM build rate projections.
Segmented volume and value trajectories across thermosetting, thermoplastic, solvent-based, and water-based chemistry platforms were modeled against aerospace build rates, electrical infrastructure investment cycles, and automotive thermal management content per vehicle. CAGRs were derived from regression analysis of historical qualification timelines and projected OEM procurement consolidation patterns. Forecast inputs incorporated CAAC pathway acceleration, EPA emission standard amendment timelines, and autoclave capacity expansion announcements.
The model holds under stable REACH registration enforcement and continued FAA-EASA harmonization progress; deviation in Chinese export licensing protocols or fireworthiness certification divergence would shift supply concentration and pricing power distributions. A model refresh is warranted upon material change in COMAC production ramp schedules or ECHA substance registration deadline amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
France Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Asia-Pacific Thermoplastics Market
Polymers & Resins
Synthetic and Bio Thermosets Market
Polymers & Resins
Europe Polypropylene Market
Polymers & Resins
Polyurethane (PU) Foam Market
Polymers & Resins
Solid-Grade Thermoplastic Acrylic (Beads) Resin Market
Polymers & Resins
Europe Geopolymer Market
Polymers & Resins
Polystyrene and Expandable Polystyrene (EPS) Market
Polymers & Resins
Thermoplastic Polyamide Elastomer (TPE) Market
Polymers & Resins
Canada Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Resin Cement for Luting Market
Polymers & Resins
Global Polybutene Market
Polymers & Resins
Europe Thermoplastics Market
Polymers & Resins
Extruded Polystyrene Market
Polymers & Resins
Photopolymers Market
Polymers & Resins
Polydicyclopentadiene (Pdcpd) Market