

Resin Cement for Luting Market Size, Share, and Industry Trends Forecast 2026-2036
Resin Cement for Luting Market Insights
Dental ceramist training capacity is bifurcating the market into clinics capable of complex adhesive protocols and those defaulting to simplified self-adhesive systems. 3M leverages its Scotchbond universal adhesive platform to sustain clinician loyalty across both workflow types. Kuraray Noritake Dental anchors the Asian premium segment through proprietary silane coupling technology integrated with its Panavia product line.
Resin cement for luting denotes a methacrylate-based or resin-modified glass ionomer material formulated for permanent fixation of indirect restorations, typically exhibiting film thickness below 25 micrometers and bond strengths exceeding 20 MPa to enamel and dentin. Its primary purpose is to create a durable, sealed interface between prepared tooth structure and ceramic, metal, or composite prostheses while accommodating thermal and mechanical stress. Self-adhesive formulations now dominate volume flows due to reduced technique sensitivity and chair-time compression, though total-etch systems retain margin premiums in specialized prosthodontist channels. Crown and bridge applications constitute the mature revenue core, while veneer luting represents the fastest-growing indication driven by aesthetic dentistry expansion.
FDA 510(k) premarket notifications govern resin cement biocompatibility and mechanical performance claims in the United States, while the EU Medical Device Regulation requires notified body oversight and clinical evidence documentation for permanent implantable dental materials. ISO 4049 sets international baseline standards for polymer-based restorative materials including luting cements, influencing harmonized testing protocols across multiple jurisdictions. Stakeholders must monitor evolving regulatory divergence between FDA's predicate-based clearance and EMA's escalating clinical data demands when prioritizing geographic launch sequences.
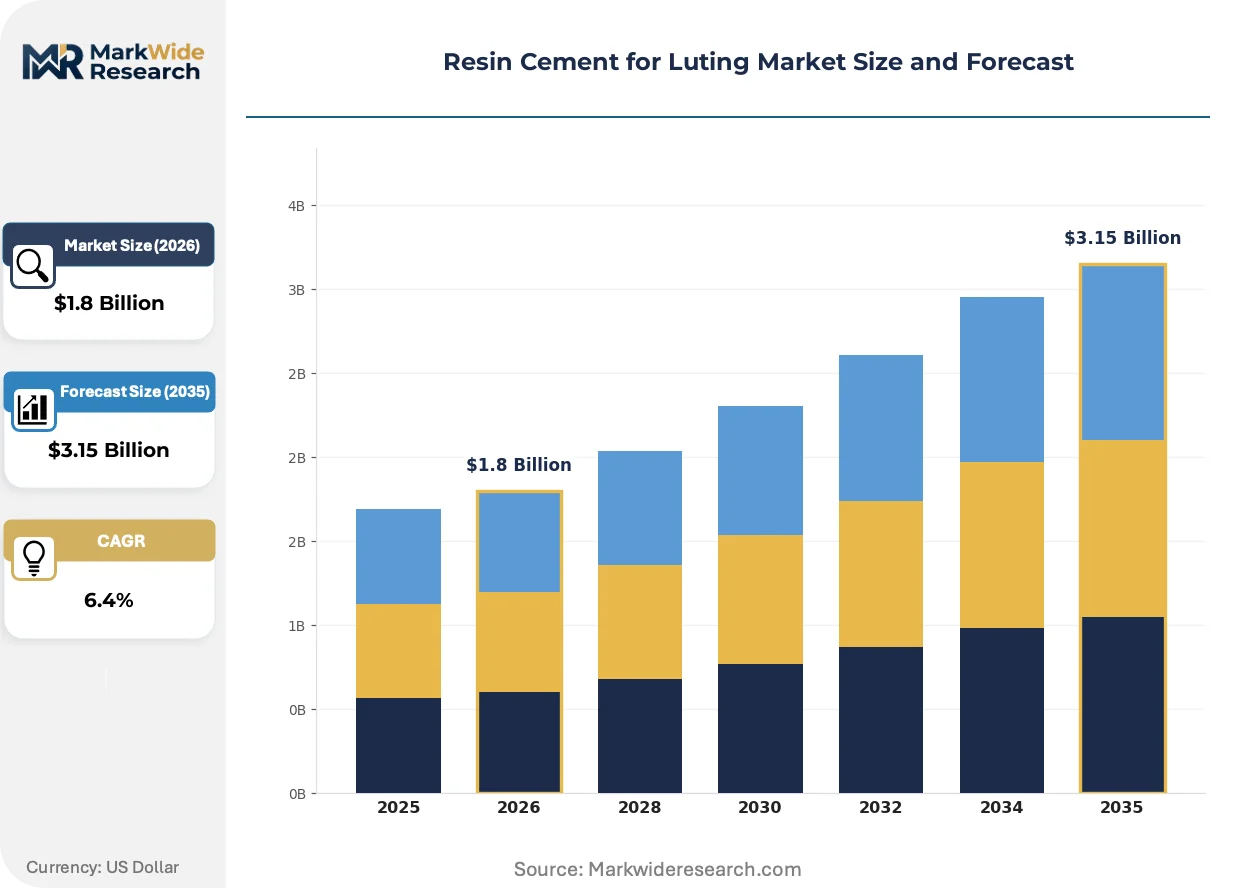
Market Dynamics
Dual-cure resin cement systems are compressing chair-time requirements while forcing clinicians to choose between simplified self-adhesive protocols and technique-sensitive total-etch methods. This bifurcation is reshaping manufacturer R&D priorities and distributor inventory strategies across dental supply chains.
Growth Catalysts
- EU Medical Device Regulation (MDR):Stricter biocompatibility documentation requirements are accelerating consolidation among notified body-certified manufacturers, privileging established European suppliers with existing clinical evidence portfolios.
- Aesthetic dentistry workflows:Ceramic veneer placements are expanding faster than crown and bridge volumes, pulling demand for translucent, color-stable resin cements with simplified cleanup characteristics.
- Japan's aging demographic:Prosthodontic service utilization among patients over 65 is elevating reimbursement-stable premium cement categories in the world's most aged major economy.
Market Restraints
- Methacrylate monomer cost volatility:Bisphenol A-glycidyl methacrylate (Bis-GMA) and urethane dimethacrylate (UDMA) feedstock prices fluctuate with petrochemical cycles, squeezing formulation margins unpredictably.
- Silane coupling agent supply concentration:Proprietary silane technology for ceramic priming concentrates among Japanese and German specialty chemical suppliers, creating single-source vulnerabilities.
- Total-etch technique sensitivity:Moisture control requirements and multi-step protocols limit adoption to specialized prosthodontist practices, capping addressable market for premium adhesive systems.
Strategic Opportunities
- India's dental infrastructure expansion:Private clinic chains in Mumbai, Delhi, and Bangalore are upgrading from conventional glass ionomer to resin-modified systems, creating first-mover positioning for mid-tier cement portfolios.
- Chairside CAD/CAM integration:Same-day ceramic milling workflows require rapid-setting dual-cure cements compatible with immediate light activation and self-cure completion.
- FDA 510(k) predicate pathway:Streamlined clearance for substantially equivalent formulations enables faster US market entry compared to EU MDR clinical evidence requirements.
Industry Challenges
- Adhesive protocol training deficits:General practitioners lack consistent education in selective enamel etching and dentin bonding, causing premature restoration failures and liability exposure.
- ISO 4049 harmonization gaps:Divergent national implementations of polymer-based restorative material standards complicate multi-jurisdiction product registration and testing cost allocation.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resin Cement for Luting Market Trends and Innovations
Material science convergence with digital dentistry workflows is redefining performance expectations for resin cements. Manufacturers now engineer products around scanner compatibility, millable block adhesion, and immediate functional loading rather than traditional laboratory bench metrics.
Universal adhesive systems with integrated silane functionality are supplanting separate primer-and-cement protocols in general practice settings. Clinicians in high-volume US dental service organizations are adopting these streamlined workflows to compress appointment slots. The consolidation is eroding market space for conventional multi-bottle adhesive systems requiring separate ceramic primers.
EMA's escalating clinical evidence demands under the EU Medical Device Regulation are extending product development timelines for permanent implantable dental materials. Manufacturers must now generate prospective clinical data rather than rely on predicate equivalence, favoring larger firms with dedicated regulatory affairs infrastructure. German and Swiss suppliers with established notified body relationships are capturing disproportionate share of new MDR certificates.
Buying committees at US dental service organizations are consolidating vendor relationships and demanding volume-based pricing guarantees for resin cement categories. Independent distributors lose shelf space as DSOs negotiate direct supply agreements with manufacturers. This concentration is most visible in Florida, Texas, and California where dental chain penetration exceeds national averages.
Resin Cement for Luting Market Segmentation
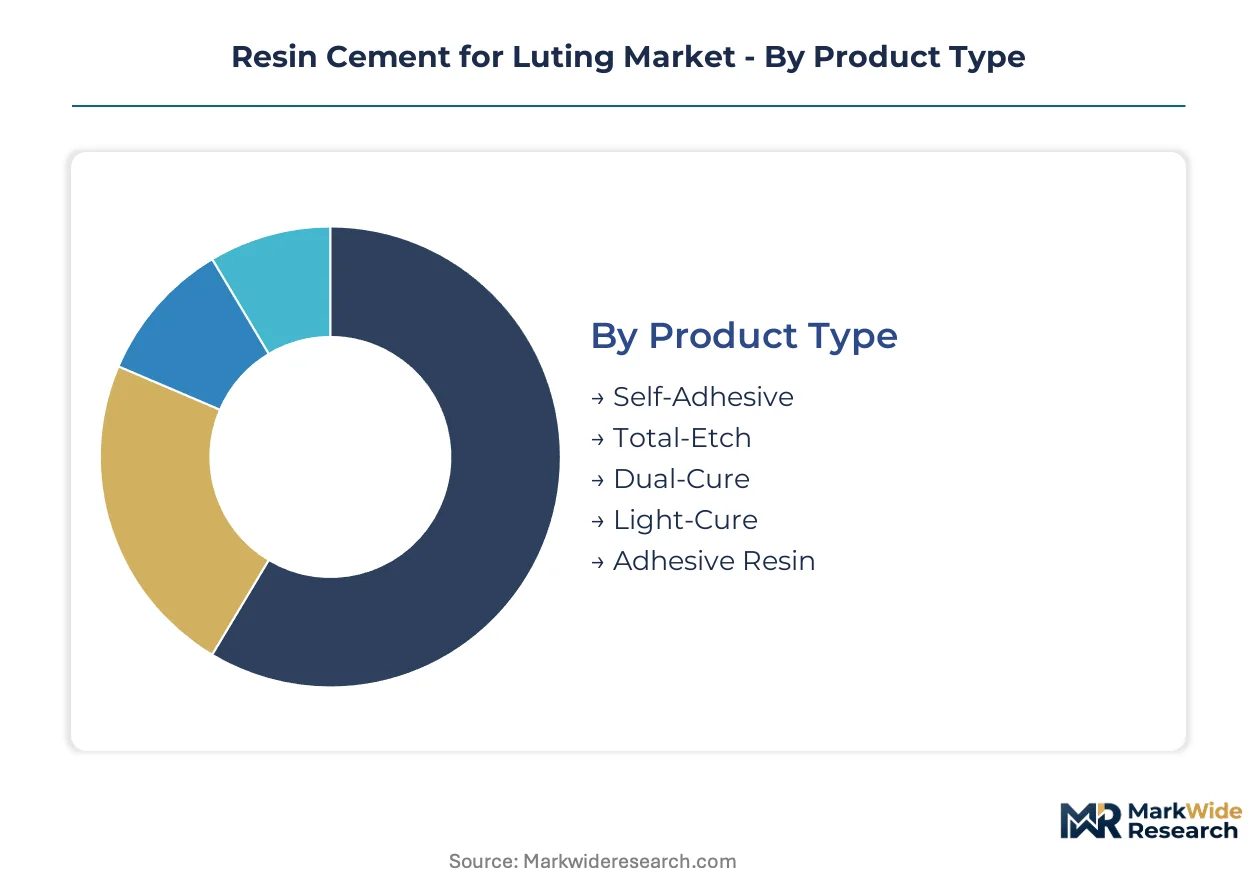
Resin cement for luting segments along workflow complexity, restoration type, and delivery format. Each dimension carries distinct regulatory footprints and margin structures that shape manufacturer portfolio strategy and distributor inventory allocation.
Product Type:
FDA 510(k) predicate pathways favor formulations with established biocompatibility profiles, while EU MDR clinical evidence requirements create divergent certification timelines across chemistry classes.
- Self-Adhesive:Methacrylate-functionalized acidic monomers eliminate separate priming steps. General practitioners in US dental service organizations favor these systems for crown seating efficiency, compressing appointment slots while reducing technique sensitivity liability.
- Total-Etch:Requires phosphoric acid enamel conditioning and separate dentin bonding agents. Specialized prosthodontists in Germany and Japan retain preference for these systems in high-stress posterior bridges where bond strength thresholds exceed 25 MPa.
- Dual-Cure:Combines light-activation with chemical polymerization for opaque or deep restorations. Oral surgery centers deploy these for post-endodontic crowns where light penetration is compromised.
- Light-Cure:Photoinitiator-dependent systems with rapid set characteristics. Veneer applications in aesthetic-focused Miami and Los Angeles practices favor these for color stability and immediate cleanup.
- Adhesive Resin:Conventional multi-bottle protocols requiring separate ceramic primers. Dental laboratories in Switzerland maintain these for complex multi-unit prostheses where protocol control outweighs chair-time costs.
Self-Adhesive handles the majority of throughput; Veneers is the fastest mover on share.
Application:
Restoration geometry dictates cement selection through film thickness tolerance, optical requirements, and functional load exposure.
- Indirect Restorations:All-ceramic and metal-ceramic crowns, bridges, and implant-supported prostheses. German prosthodontic practices drive premium cement specifications through statutory insurance reimbursement stability.
- Orthodontic Attachments:Bracket bonding and lingual retainer fixation. Japanese orthodontic clinics favor dual-cure systems for metal bracket bases where light access is restricted.
- Crown & Bridge:Conventional fixed prosthodontics representing mature volume concentration. US dental service organizations negotiate volume pricing on self-adhesive variants for this indication.
- Veneers:Thin ceramic laminate bonding demanding translucent, color-stable cements. Aesthetic dentistry expansion in São Paulo and Dubai elevates demand for light-cure systems with shade matching precision.
- Inlays & Onlays:Partial coverage indirect restorations. Italian dental clinics prefer dual-cure formulations for posterior onlays where occlusal load exceeds anterior veneer stress.
Crown & Bridge anchors volume flows; Veneers climbs the fastest on revenue contribution.
End User:
Clinical setting determines procurement authority, training infrastructure, and protocol standardization capacity.
- Dental Clinics:General practice settings with high patient throughput. Indian clinic chains in Mumbai and Delhi are upgrading from glass ionomer to resin-modified systems, creating mid-tier cement demand.
- Oral Surgery Centers:Hospital-affiliated or standalone surgical facilities. These centers in South Korea prioritize dual-cure systems for immediate implant provisionalization workflows.
- Specialized Prosthodontists:Fellowship-trained clinicians handling complex rehabilitations. Swiss and German prosthodontists sustain premium pricing for total-etch systems through referral network insulation.
- Dental Laboratories:Off-site fabrication facilities influencing cement specification through dentist-laboratory protocol agreements. Brazilian laboratories in São Paulo specify adhesive resin systems for full-mouth reconstructions.
Dental Clinics process the highest unit volumes; Oral Surgery Centers are expanding most quickly on cement spend per procedure.
Formulation Type:
Packaging format shapes shelf-life economics, dispensing precision, and chairside workflow integration.
- Paste:Two-paste automix systems in dual-barrel syringes. US dental service organizations standardize on these for dispensing consistency across multi-location practices.
- Syringe:Single-component or base-catalyst delivery in manual or automix configurations. Japanese clinics favor pre-loaded syringe tips for veneer seating efficiency.
- Capsule:Triturated powder-liquid systems for mechanical mixing. German dental laboratories specify capsules for high-viscosity build-up cements in crown cementation.
- Liquid:Primers, bonding agents, and ceramic coupling solutions. Silane liquid formulations concentrate among Japanese and German specialty chemical suppliers.
- Powder:Resin-modified glass ionomer components requiring chairside proportioning. Indian government dental colleges utilize powder-liquid systems for cost-controlled training programs.
Paste dominates commercial throughput; Capsule gains share fastest through laboratory channel consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for resin cement for luting diverge sharply by geography. The United States and Germany favor premium self-adhesive and dual-cure systems for high-throughput dental service organizations, while Japan and India exhibit starker bifurcation between simplified chairside protocols and specialized prosthodontic workflows.
United States
Dental service organizations in Florida, Texas, and California drive volume demand for paste-format self-adhesive cements that compress appointment slots. FDA 510(k) predicate pathways enable faster clearance for substantially equivalent formulations, privileging established suppliers with existing biocompatibility portfolios. Miami and Los Angeles aesthetic practices anchor premium light-cure veneer cement consumption.
Germany
Statutory insurance reimbursement stability sustains premium total-etch system demand among specialized prosthodontists in Berlin and Munich. EU MDR clinical evidence requirements extend development timelines, favoring domestic suppliers with notified body relationships and existing clinical data archives. Bavarian dental laboratories specify capsule-format high-viscosity build-up cements for complex crown cementation.
Japan
The world's most aged major economy elevates prosthodontic service utilization among patients over 65, stabilizing premium cement categories. METI oversight of medical device quality systems intersects with proprietary silane coupling technology concentration among domestic specialty chemical suppliers. Tokyo and Osaka orthodontic clinics favor dual-cure systems for metal bracket bases where light access is restricted.
India
Private clinic chains in Mumbai, Delhi, and Bangalore upgrade from conventional glass ionomer to resin-modified systems, creating first-mover positioning for mid-tier portfolios. BIS standards for polymer-based dental materials remain less stringent than FDA or EU MDR equivalents, accelerating product registration for foreign entrants. Government dental colleges in Maharashtra utilize powder-liquid systems for cost-controlled training programs.
Switzerland
Swissmedic oversight of permanent implantable dental materials demands rigorous clinical documentation, extending certification timelines beyond EU MDR baselines. Zurich and Geneva prosthodontists sustain premium pricing for adhesive resin systems through referral network insulation and full-mouth reconstruction specialization. Dental laboratories in Basel specify multi-bottle protocols where protocol control outweighs chair-time economics.
Resin Cement for Luting Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the resin cement for luting market. The upper tier commands formulation chemistry, regulatory affairs infrastructure, and direct supply relationships with dental service organizations. Mid-tier specialists compete on ceramic priming technology, automix delivery systems, or regional regulatory expertise. Competitive moves concentrate on M&A for silane technology access and capacity expansion for dual-cure production lines.
Among Japanese suppliers, Kuraray Noritake Dental and Tokuyama Dental exemplify the specialty chemical archetype with proprietary silane integration. 3M occupies a position as the integrated leader leveraging universal adhesive platform loyalty across workflow types. Within the European precision tier, Ivoclar represents Swiss-German regulatory sophistication with notified body-certified manufacturing.
| Leading Market Players |
|---|
| 3M |
| Kuraray Noritake Dental |
| Ivoclar |
| GC Corporation |
| Dentsply Sirona |
| Envista Holdings |
| BISCO |
| Shofu |
| Tokuyama Dental |
| Others |
Pricing and Supply Chain Analysis
Self-adhesive resin formulations displacing total-etch protocols in US dental service organizations are simultaneously shifting procurement geography toward paste-format automix suppliers and compressing per-unit margins through volume-based contracting.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between US dental service organizations and established manufacturers, with pricing stratifying across premium, standard, and economy tiers based on ISO 4049 certification grade and after-sales technical support bundling. Cost compression in the mid-tier segment is intensifying because Indian clinic chains negotiate aggressive entry pricing for resin-modified glass ionomer upgrades. General practitioners in high-volume settings exhibit the highest price sensitivity, while Swiss and German specialized prosthodontists show minimal elasticity due to referral network insulation.
Supply Chain Analysis
Proprietary silane coupling agent production concentrates among Japanese and German specialty chemical suppliers, creating single-source vulnerability for ceramic priming workflows. Bis-GMA and UDMA monomer feedstock draws from petrochemical complexes in the United States, Germany, and Japan, with formulation chemistry resting on urethane dimethacrylate consistency. Tariff exposure on methacrylate imports complicates multi-jurisdiction manufacturing footprints. Distribution runs through direct supply agreements with dental service organizations, bypassing independent distributors in concentrated markets like Florida and Texas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Resin cement for luting sits in early-cycle expansion as India's private clinic infrastructure upgrades from conventional glass ionomer, creating penetration tailwinds for mid-tier automix portfolios.
For Market Incumbents: Secure silane technology access through targeted acquisition of Japanese or German specialty chemical suppliers to defend against ceramic primer commoditization. Expand dual-cure production capacity in South Korea to capture oral surgery center demand for immediate implant provisionalization workflows. For New Entrants and Emerging Players: Differentiate on chairside CAD/CAM compatibility with rapid-setting formulations designed for same-day ceramic milling workflows. Target India's Mumbai and Bangalore clinic chains with cost-optimized resin-modified systems as the most penetrable geography. Pursue BIS registration pathways ahead of FDA or EU MDR timelines to accelerate market entry. For Investors and Strategic Acquirers: The market sits at a capacity-buildout phase that favors notified body-certified manufacturers with existing clinical evidence portfolios. Long-term viability hinges on regulatory affairs infrastructure scale rather than formulation innovation alone. Acquisition targets should display established EU MDR certificates and direct DSO supply relationships. Watch FDA 510(k) clearance velocity for dual-cure veneer cements as an inflection indicator for premium segment momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Silane Technology Acquisition | Captures proprietary ceramic priming capability concentrated among Japanese and German suppliers. |
| Dual-Cure Capacity Expansion | Addresses oral surgery center demand for immediate implant provisionalization in South Korea. |
| BIS Registration Acceleration | Exploits less stringent Indian standards to establish first-mover positioning in upgrading clinic chains. |
| DSO Direct Supply Agreement | Bypasses distributor margin capture in Florida, Texas, and California consolidation markets. |
| EU MDR Clinical Evidence Build | Secures notified body certification ahead of escalating EMA documentation requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) premarket notification databases, EU MDR notified body certificates, and ISO 4049 harmonized testing protocols. Clinical interviews with prosthodontists, dental laboratory technicians, and procurement managers at US dental service organizations informed workflow segmentation. Regulatory affairs directors at German and Swiss manufacturers provided perspective on certification timeline divergence. Trade data from Indian pharmaceutical and medical device import records validated regional demand trajectories. Bottom-up unit volume estimates triangulate against top-down category spending analysis.
Segmentation dimensions modeled span product type, application, end user, and formulation format across the analysis window. CAGRs derive from trend extrapolation of dual-cure adoption rates, veneer placement growth in aesthetic dentistry, and aging demographic prosthodontic utilization patterns. Forecast inputs incorporate dental service organization expansion rates, chairside CAD/CAM penetration, and reimbursement stability indices by geography.
Material uncertainties — methacrylate monomer cost volatility, silane supply concentration disruption, and EU MDR clinical evidence requirement escalation — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway efficiency and dental infrastructure investment continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.