
 Bipolar Junction Transistors Market | 2026-2036
Bipolar Junction Transistors Market Size, Share, and Industry Trends Forecast 2026-2036
Bipolar Junction Transistors Market Outlook
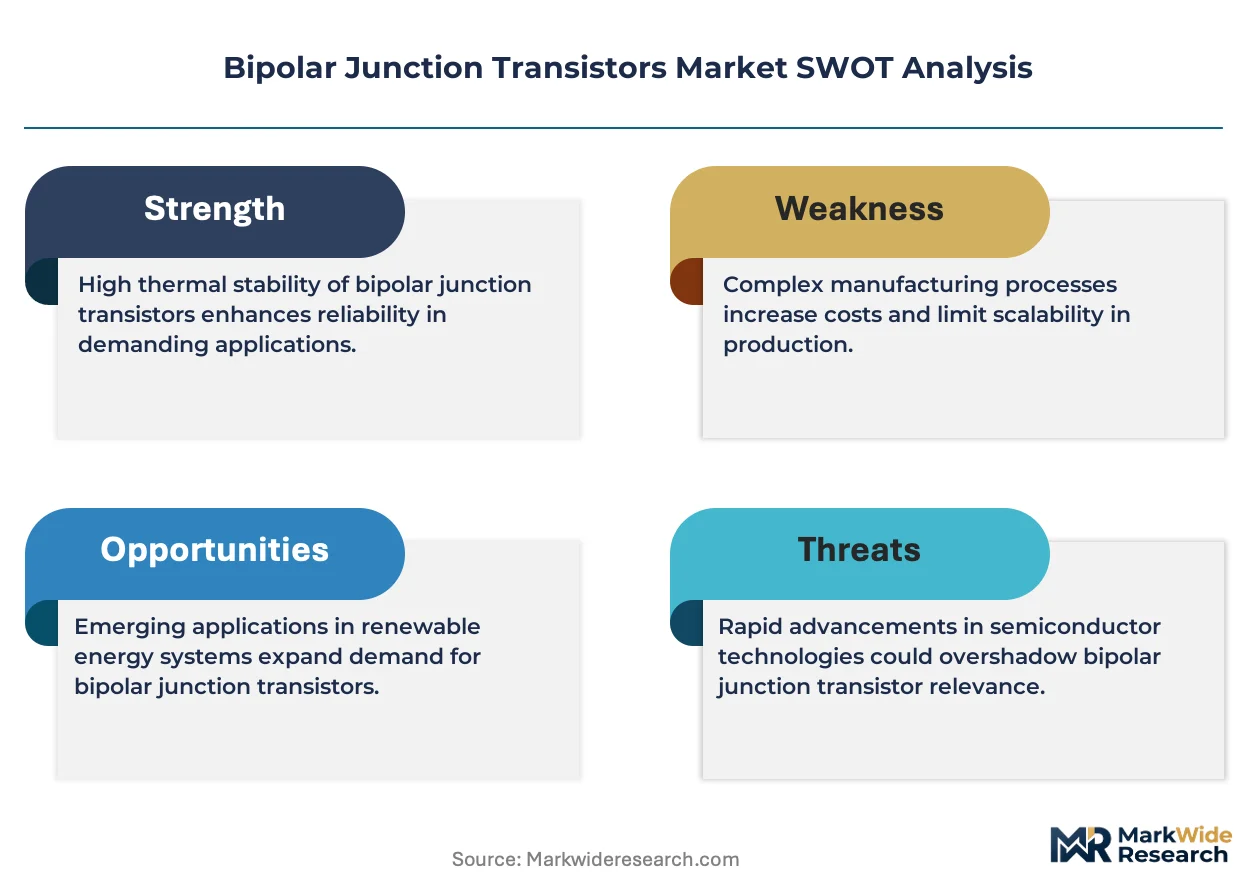
A capital-intensity divergence between foundry-dependent and IDM players is reorganizing competitive tiers in bipolar junction transistor supply. Texas Instruments sustains captive fabrication for power transistor lines, insulating margin pools from wafer allocation shocks. ON Semiconductor anchors its automotive-qualified BJT portfolio through in-house capacity at East Fishkill and Roznov. STMicroelectronics competes by extending its trench-isolated power transistor technology into 48V mild-hybrid architectures.
Bipolar junction transistors are three-terminal semiconductor devices constructed with alternating p-type and n-type doped silicon layers, operating via electron-hole pair injection across forward-biased base-emitter junctions to achieve current amplification with typical current gains (β) ranging from 10 to 300 depending on geometry and doping profile. Their primary industrial purpose spans power switching, linear amplification, and signal conditioning in circuits where cost sensitivity and ruggedness outweigh frequency performance demands. Power transistors command the largest revenue share within product type segmentation, driven by sustained replacement cycles in industrial motor drives and automotive load switching. RF transistors represent the fastest-expanding technology segment, as high-frequency bipolar architectures retain cost advantages over compound-semiconductor alternatives in sub-6GHz infrastructure applications. Gallium nitride technology is displacing silicon BJTs in RF power amplification above 2GHz, though silicon bipolar designs persist where thermal cycling reliability and supply chain maturity outweigh efficiency gains.
FDA device regulations for medical electronics, EPA energy-efficiency standards for industrial equipment, and EU RoHS substance restrictions collectively shape BJT material selections, qualification timelines, and market access conditions across major demand centers. China's GB standards for semiconductor reliability and MIIT domestic sourcing directives further constrain import-dependent supply chains serving the country's automotive and telecommunications sectors. Stakeholders must monitor compound-semiconductor cost curves and regional content requirements to calibrate technology roadmaps and capacity commitments.
Market Dynamics
Silicon carbide and gallium nitride process innovations are pressuring traditional silicon BJT architectures to demonstrate thermal efficiency advantages or cede position in power electronics applications.
Growth Catalysts
- Automotive Electrification:Electric vehicle motor control and power management modules are expanding BJT deployment as manufacturers seek cost-effective switching solutions for 48V mild-hybrid systems.
- China's MIIT Directives:Domestic semiconductor fabrication investments and electric vehicle production scale create sustained procurement pull for discrete power components in the world's largest automotive market.
- Trench-Isolated Architectures:Advanced isolation techniques are extending silicon BJT viability into higher-voltage automotive applications previously threatened by compound semiconductors.
Market Restraints
- Compound Semiconductor Substitution:Gallium nitride technology is displacing silicon BJTs in RF power amplification above 2GHz, compressing addressable market scope in telecommunications infrastructure.
- Wafer Allocation Volatility:Foundry-dependent players face margin erosion from semiconductor capacity constraints, while captive fabricators at Texas Instruments and ON Semiconductor insulate supply security.
- EU RoHS Substance Restrictions:Material selection constraints from hazardous substance directives extend qualification timelines and limit leadframe and die-attach compound options.
Strategic Opportunities
- Sub-6GHz Infrastructure:RF transistors represent expansion potential as high-frequency bipolar architectures retain cost advantages over compound-semiconductor alternatives in emerging telecommunications deployments.
- Industrial Motor Drive Replacement Cycles:Sustained equipment refresh demand in manufacturing automation creates stable revenue pools for power transistor suppliers with ruggedness certifications.
- India's PLI Scheme:Production-linked incentives for semiconductor and automotive component manufacturing are attracting fabrication investments that could reshape Asia-Pacific supply geography.
Industry Challenges
- Power Discrete Talent Scarcity:Specialized expertise in bipolar device physics and thermal management is concentrating among aging engineering cohorts at established IDMs, constraining new entrant capability building.
- Automotive Qualification Timelines:AEC-Q101 certification requirements extend product development cycles, delaying revenue recognition and tying up engineering resources across multiple design iterations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bipolar Junction Transistors Market |
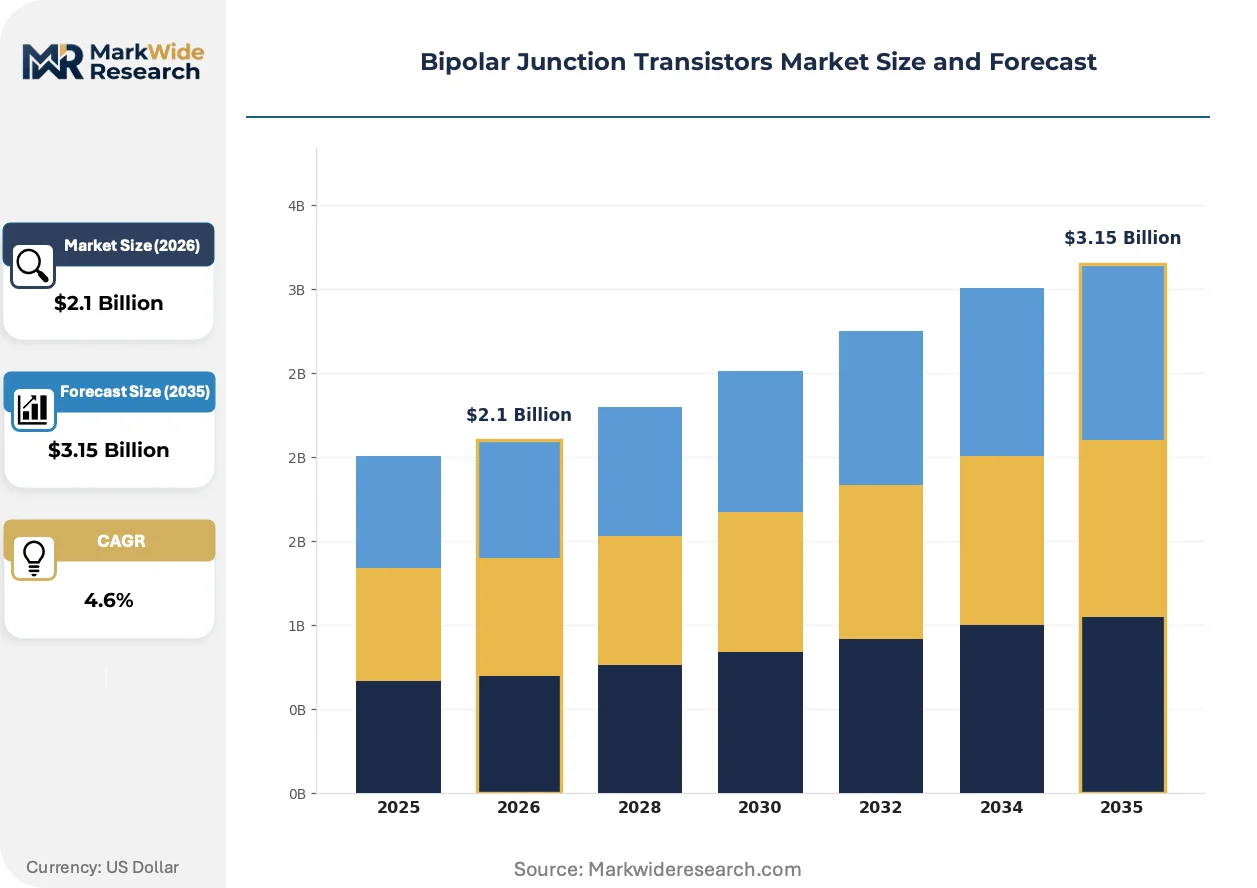
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Signal Transistors, Power Transistors, RF Transistors, High Voltage Transistors Technology: Bipolar Technology, Silicon Technology, Gallium Nitride Technology, High Frequency Technology End User: Consumer Electronics, Automotive, Telecommunications, Industrial Automation Application: Amplifiers, Switches, Oscillators, Signal Processing |
| Companies Covered | Texas Instruments, ON Semiconductor, STMicroelectronics, NXP Semiconductors, Infineon Technologies, Toshiba, Renesas Electronics, Diodes Incorporated, Vishay Intertechnology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bipolar Junction Transistors Market Strategic Shifts
Process technology divergence and end-use specification tightening are fragmenting competitive positioning between silicon legacy architectures and compound semiconductor insurgents.
Silicon germanium heterojunction bipolar transistor technology is decomposing the traditional frequency-performance tradeoff in RF applications. Base station OEMs are adopting SiGe BiCMOS processes for sub-6GHz massive MIMO arrays. This integration path is decomposing the discrete component market into process-node-dependent supply tiers.
EPA energy-efficiency standards for industrial equipment are mandating standby power reductions that favor advanced switching architectures. Motor drive manufacturers must demonstrate compliance with tightened loss metrics. Power transistor suppliers serving US industrial OEMs are responding with enhanced trench-isolated designs that minimize leakage current.
Buyer consolidation among tier-one automotive suppliers is compressing component sourcing decisions into centralized procurement functions. Direct OEM relationships are displacing traditional distribution channels for high-volume power discretes. This concentration is most visible in Germany, where KBA-type approval integration requires early supplier engagement in platform development cycles.
Bipolar Junction Transistors Market Segmentation
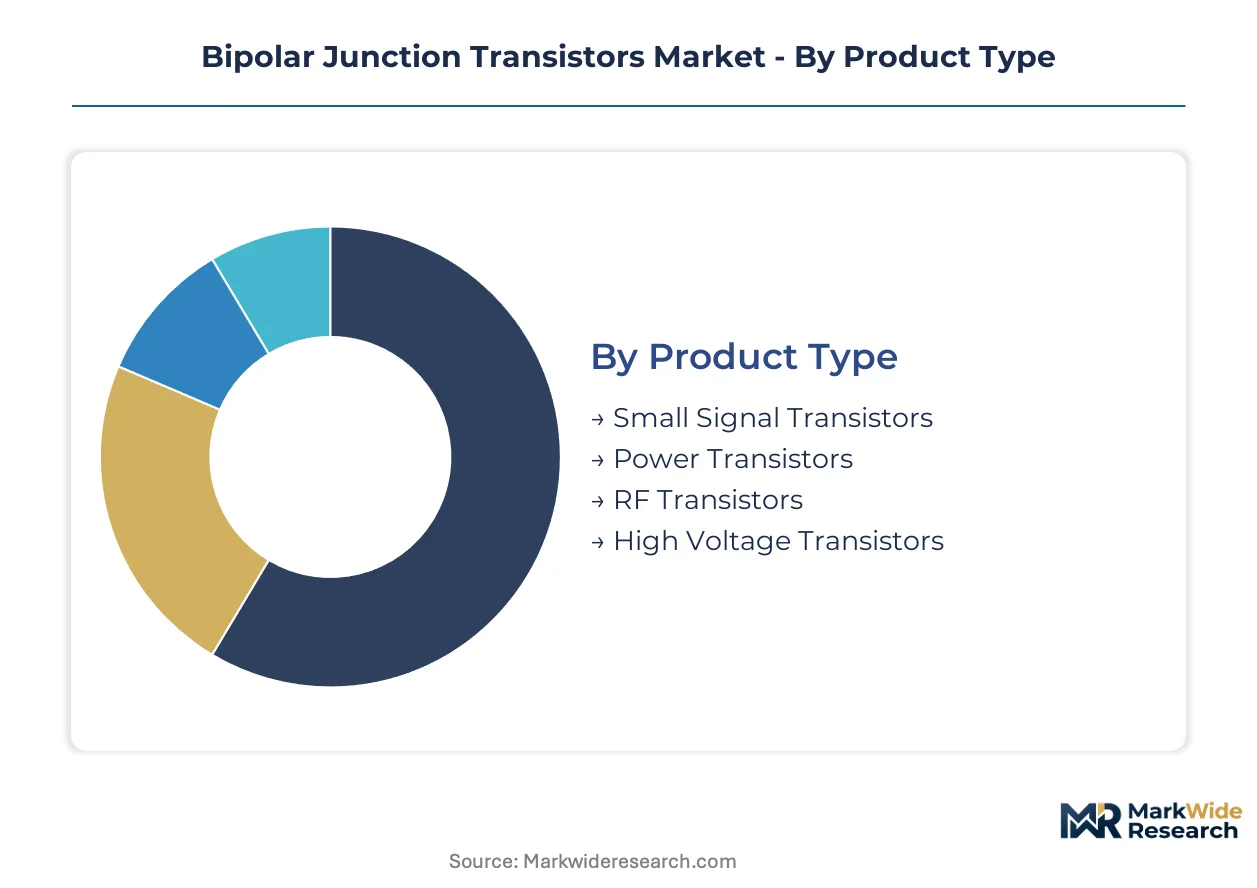
BJT market segmentation reveals how technology choices and end-use specifications fragment procurement patterns across discrete power electronics. Product architecture, process node, and application voltage requirements create distinct margin tiers that reshape supplier positioning.
Product Type:
Margin pools concentrate in power-handling segments where thermal ruggedness and voltage isolation command qualification premiums from automotive and industrial buyers.
- Power Transistors:These devices handle current loads above 1A with collector-emitter voltages spanning 40V to 1500V, employing epitaxial base structures and interdigitated emitter geometries to manage thermal dissipation. Demand clusters in China's electric vehicle motor drives and industrial motor control modules, where 48V mild-hybrid architectures extend silicon BJT viability against compound semiconductor encroachment.
- RF Transistors:Optimized for frequency performance above 100MHz through reduced base transit times and self-aligned polysilicon emitter technologies, these components achieve transition frequencies exceeding 10GHz. Sub-6GHz massive MIMO deployments in telecommunications infrastructure concentrate procurement, with SiGe heterojunction architectures gaining share against III-V alternatives on cost grounds.
- Small Signal Transistors:Low-current devices below 100mA dominate volume shipments in consumer electronics signal conditioning and general-purpose amplification.
- High Voltage Transistors:Specialized structures with thick epitaxial layers and field plate terminations serve traction inverter and grid-tied converter applications.
Power Transistors holds installed capacity. RF Transistors is rotating up the share rankings.
Technology:
Process differentiation separates captive-fabricated silicon legacy from foundry-dependent compound semiconductor alternatives with divergent cost structures.
- Bipolar Technology:Conventional junction-isolated and trench-isolated architectures fabricated on silicon substrates, leveraging established doping profiles and metallization schemes for current gains between 10 and 300. Automotive qualification timelines at AEC-Q101 grade concentrate demand among IDMs with in-house diffusion capacity.
- Silicon Technology:Standard CMOS-compatible bipolar modules and BiCMOS integration paths enable mixed-signal system-on-chip implementations. Base station OEMs in telecommunications drive adoption where digital control integration outweighs discrete performance.
- Gallium Nitride Technology:Wide-bandgap heterostructures displace silicon above 2GHz and 600V operating points, though thermal cycling reliability constraints limit automotive penetration.
- High Frequency Technology:Specialized epitaxial growth and self-aligned processing push transition frequencies for radar and satellite communication front-ends.
Bipolar Technology anchors current revenue. Gallium Nitride Technology is climbing the fastest as RF power amplification requirements intensify.
End User:
Customer concentration varies sharply, with automotive procurement centralization compressing supplier margins while industrial fragmentation sustains distributor channels.
- Automotive:Tier-one supplier consolidation around electrification platforms drives qualification-heavy procurement for motor control, DC-DC conversion, and load switching in 12V, 48V, and high-voltage domains. China's MIIT domestic sourcing directives and KBA-type approval integration in Germany shape regional supply requirements.
- Industrial Automation:Motor drive replacement cycles and manufacturing equipment refresh sustain demand for ruggedized power transistors with extended temperature ratings. EPA energy-efficiency standards mandate standby power reductions that favor advanced trench-isolated switching architectures.
- Consumer Electronics:Cost-optimized small signal and power devices serve audio amplification, power management, and display driver applications.
- Telecommunications:Base station and infrastructure deployments concentrate RF transistor procurement among OEMs with centralized component sourcing functions.
Automotive holds installed capacity. Industrial Automation is rotating up the share rankings.
Application:
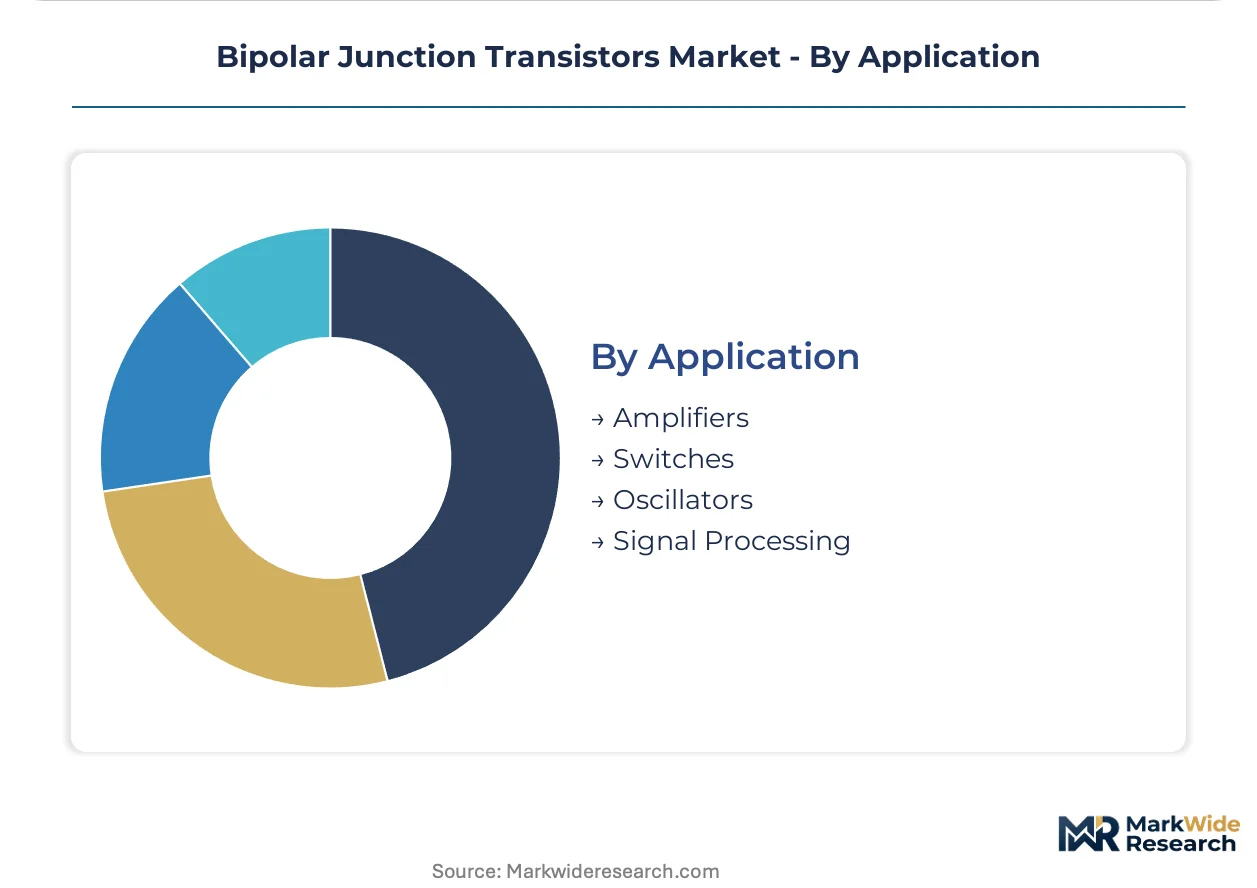
Functional use cases segment by linear versus switching operating modes, with thermal design requirements determining technology selection.
- Switches:Saturation-mode operation for power conversion and load control demands low collector-emitter saturation voltage and fast switching transitions. Electric vehicle power management modules and industrial motor drives concentrate procurement, with trench-isolated architectures extending silicon BJT viability in 48V architectures.
- Amplifiers:Linear-mode biasing for audio, RF, and instrumentation applications requires controlled gain flatness and low distortion. Sub-6GHz telecommunications infrastructure and consumer audio systems sustain demand for complementary bipolar pairs and Darlington configurations.
- Oscillators:Feedback network implementations in timing and frequency generation circuits.
- Signal Processing:Analog conditioning and interface circuits in mixed-signal systems.
Switches holds installed capacity. Amplifiers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany's automotive sector demonstrate the lowest price elasticity, accepting qualification premiums for AEC-Q101 certified devices, while Chinese procurement functions drive hard on unit costs for 48V mild-hybrid modules. India's emerging electronics manufacturing shows intermediate sensitivity, balancing PLI scheme incentives against landed cost considerations. Japan's industrial automation buyers prioritize thermal cycling reliability over upfront pricing.
China
MIIT domestic sourcing directives and electric vehicle production at scale create sustained procurement pull for discrete power components. GB standards for semiconductor reliability constrain import-dependent supply chains serving automotive and telecommunications sectors. Shanghai and Shenzhen clusters concentrate domestic fabrication investments and tier-one automotive supplier engineering centers.
Germany
KBA-type approval integration requires early supplier engagement in platform development cycles for motor control modules. EU RoHS substance restrictions extend qualification timelines and limit leadframe material options for power transistor suppliers. Stuttgart and Munich engineering corridors anchor tier-one automotive supplier consolidation around electrification platforms.
United States
EPA energy-efficiency standards for industrial equipment mandate standby power reductions favoring advanced switching architectures. FDA device regulations for medical electronics shape material selections and qualification timelines for BJT components. Texas and Arizona fabrication corridors concentrate captive capacity investments from established IDMs.
Japan
METI industrial policy supports domestic semiconductor fabrication for automotive and industrial automation applications. JIS standards for component reliability sustain demand for thermally rugged power transistors in manufacturing equipment refresh cycles. Nagoya and Osaka industrial clusters concentrate motor drive OEM procurement and precision manufacturing supply chains.
India
PLI scheme production-linked incentives attract semiconductor and automotive component manufacturing investments reshaping Asia-Pacific supply geography. Central Electricity Authority regulations for industrial equipment efficiency create compliance-driven replacement demand. Gujarat and Karnataka emerging electronics corridors concentrate contract manufacturing investments and automotive tier-two supplier development.
Bipolar Junction Transistors Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with IDMs sustaining captive fabrication for margin insulation while foundry-dependent competitors face wafer allocation volatility. The vendor base organizes around three strategic archetypes: integrated device manufacturers with in-house diffusion capacity, fabless specialists leveraging external foundries, and diversified conglomerates with cross-divisional technology leverage. Competitive moves concentrate on capacity expansion at automotive-qualified nodes and strategic partnerships for compound semiconductor process licensing.
Among diversified semiconductor conglomerates, Texas Instruments and ON Semiconductor occupy positions exemplifying captive-fabrication resilience against supply shocks. STMicroelectronics represents the European IDM archetype with trench-isolated power transistor technology extending into 48V mild-hybrid architectures. These three anchors demonstrate how in-house diffusion capacity insulates margin pools from foundry allocation constraints while sustaining AEC-Q101 qualification pipelines for automotive procurement centralization.
| Leading Market Players |
|---|
| Texas Instruments |
| ON Semiconductor |
| STMicroelectronics |
| NXP Semiconductors |
| Infineon Technologies |
| Toshiba |
| Renesas Electronics |
| Diodes Incorporated |
| Vishay Intertechnology |
| Others |
Value Chain & Pricing Dynamics
Automotive-qualified fabrication capacity utilization above 85% at East Fishkill and Roznov facilities anchors pricing power for AEC-Q101 certified BJTs, while foundry-dependent competitors absorb wafer allocation premiums that compress margins in unqualified consumer tiers.
Pricing Analysis
After-sales service contracts and extended qualification support drive lifetime value differentiation between captive-fabricated automotive lines and spot-market consumer devices. Three-tier pricing structure across AEC-Q101 certified, industrial-grade, and commercial-grade levels separates procurement pools, with China's MIIT domestic sourcing directives intensifying cost compression in unqualified segments. German tier-one suppliers demonstrate lowest price elasticity for KBA-integrated motor control modules, while Indian contract manufacturers under PLI schemes show highest sensitivity to landed unit costs.
Supply Chain Analysis
Die bank inventory cycles extending beyond 16 weeks signal constrained epoxy molding compound availability and gold wire bonding capacity at leadframe suppliers. Taiwan, China, and Japan concentrate front-end wafer fabrication for power discretes, drawing from silicon epitaxial wafers, copper leadframes, and silver-filled die-attach compounds. Single-source vulnerability in automotive-qualified molding compounds creates disruption risk for AEC-Q101 certification pipelines. Distribution runs through authorized franchised channels for automotive OEMs and open-market brokers for consumer replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical support contracts and qualification engineering services are expanding faster than discrete component hardware, creating service-attach margin pools that captive fabricators at Texas Instruments and ON Semiconductor already monetize through automotive platform partnerships.
For Market Incumbents: Compound trench-isolated power transistor investments with SiGe BiCMOS licensing partnerships to defend RF market share against gallium nitride displacement above 2GHz. Prioritize AEC-Q101 capacity expansion at automotive-qualified nodes before China's MIIT directives harden domestic sourcing requirements. Backward integration into epitaxial wafer supply insulates margin pools from silicon substrate volatility. For New Entrants and Emerging Players: Differentiate on India's PLI scheme incentives by targeting Gujarat and Karnataka contract manufacturing corridors for industrial motor drive replacement cycles. White-space exists in sub-6GHz massive MIMO RF transistors where SiGe cost advantages persist against compound semiconductors. Go-to-market through direct OEM relationships with base station manufacturers bypasses entrenched distribution channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among IDMs with captive automotive qualification pipelines and multi-year platform supply agreements. Long-term viability across the analysis window hinges on compound semiconductor process licensing flexibility and China domestic content compliance capability. Acquisition target archetype: mid-cap specialists with trench-isolated technology and AEC-Q101 certification infrastructure. Signal to watch: MIIT domestic sourcing directive enforcement intensity in Shanghai and Shenzhen automotive clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Trench-Isolated Power Transistor Capacity Expansion | Extends silicon BJT viability in 48V mild-hybrid architectures against GaN encroachment. |
| SiGe BiCMOS Process Licensing Partnership | Captures sub-6GHz massive MIMO procurement from base station OEMs seeking cost advantages. |
| AEC-Q101 Qualification Pipeline Investment | Secures KBA-type approval integration with German tier-one electrification platforms. |
| Epitaxial Wafer Backward Integration | Insulates margin pools from silicon substrate allocation shocks at foundry competitors. |
| India PLI Scheme Manufacturing Footprint | Reshapes Asia-Pacific supply geography for industrial motor drive replacement demand. |
Study Parameters
Cross-validation between primary interviews with power discrete engineering directors, automotive tier-one procurement managers, and foundry operations leads and secondary validation through SEC 10-K filings, MIIT domestic sourcing directive documentation, and AEC-Q101 certification databases anchors the qualitative findings. Bottom-up triangulation across product type, technology node, and end-user segmentation dimensions combines with top-down macroeconomic factor adjustment.
Sensitivity analysis across wafer allocation volatility scenarios, compound semiconductor cost curves, and regional content requirement enforcement intensity shapes the analytical framework over the projection horizon. Modeled dimensions span power transistor, RF transistor, and small signal product architectures; bipolar, silicon, and gallium nitride technology tiers; automotive, industrial automation, and telecommunications end-user categories; plus application voltage requirements and regional regulatory clusters. CAGRs derive from installed base replacement cycles, electric vehicle production ramp rates, and telecommunications infrastructure deployment schedules.
The analysis sits within stated boundaries; outcomes outside sustained automotive electrification investment, stable MIIT directive enforcement, and manageable gallium nitride cost compression would require recalibration. Forecasts reflect documented assumptions regarding silicon carbide thermal efficiency benchmarks and China domestic fabrication scale-up timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Global Precision Parts Market
Semiconductor Devices
Europe Touch Screen Controllers Market
Semiconductor Devices
Fin Field Effect Transistor (Finfet) Market
Semiconductor Devices
Japan CEP Market
Semiconductor Devices
DNA Chromatography Chip Market
Semiconductor Devices
Global 8 - Bit Microcontroller Market
Semiconductor Devices
Middle East Distribution Panel Market
Semiconductor Devices
APAC Semiconductor Device for Processing Applications Market
Semiconductor Devices
Ultra Low Power Microcontroller Market
Semiconductor Devices
Automotive Grade Emmc Market
Semiconductor Devices
Japan Power Transistor Market
Semiconductor Devices
Gan on Silicon Technology Market
Semiconductor Devices
Global Embedded FPGA Market
Semiconductor Devices
Digital Transistor Market
Semiconductor Devices
Ram BOP Market
Semiconductor Devices
Gan-On-Silicon Market