
 Hairpin Stator Market | 2026-2036
Hairpin Stator Market Size, Share, and Industry Trends Forecast 2026-2036
Hairpin Stator Market Insights
Buyer concentration among electric vehicle OEMs is consolidating as Volkswagen, Tesla, and BYD narrow their supplier panels for high-volume hairpin stator programs. Nidec leverages its vertical integration from lamination stamping to final assembly, sustaining cost advantages across Japanese and European supply chains. Denso anchors production capacity in Toyota's supplier ecosystem, while BorgWarner competes through technology leadership in multi-layer hairpin architectures for 800-volt platforms.
A hairpin stator is an electric motor component formed from rectangular copper conductors bent into U-shaped segments, inserted into stator slots, and welded at the ends to create continuous windings with fill factors exceeding 60 percent. Vacuum pressure impregnation technology dominates high-voltage EV applications where thermal cycling resistance determines motor lifespan. Multi-layer hairpin configurations capture the fastest growth segment as OEMs pursue power density targets above 4.5 kW per kilogram. Laser welding equipment suppliers occupy concentrated margin pools, since joint quality directly impacts motor efficiency and warranty exposure.
FDA oversight of electromagnetic compatibility in medical device motors and EPA fuel-economy standards for hybrid powertrains shape product certification requirements in the United States. The EU's F-Gas Regulation and REACH restrictions on insulation materials constrain coating chemistry choices for European-bound production. China's GB standards for NEV motor efficiency, enforced by MIIT, mandate minimum performance thresholds that filter supplier qualification. Stakeholders must monitor how regional efficiency thresholds diverge and decide whether to maintain separate product architectures or converge on a single global design.
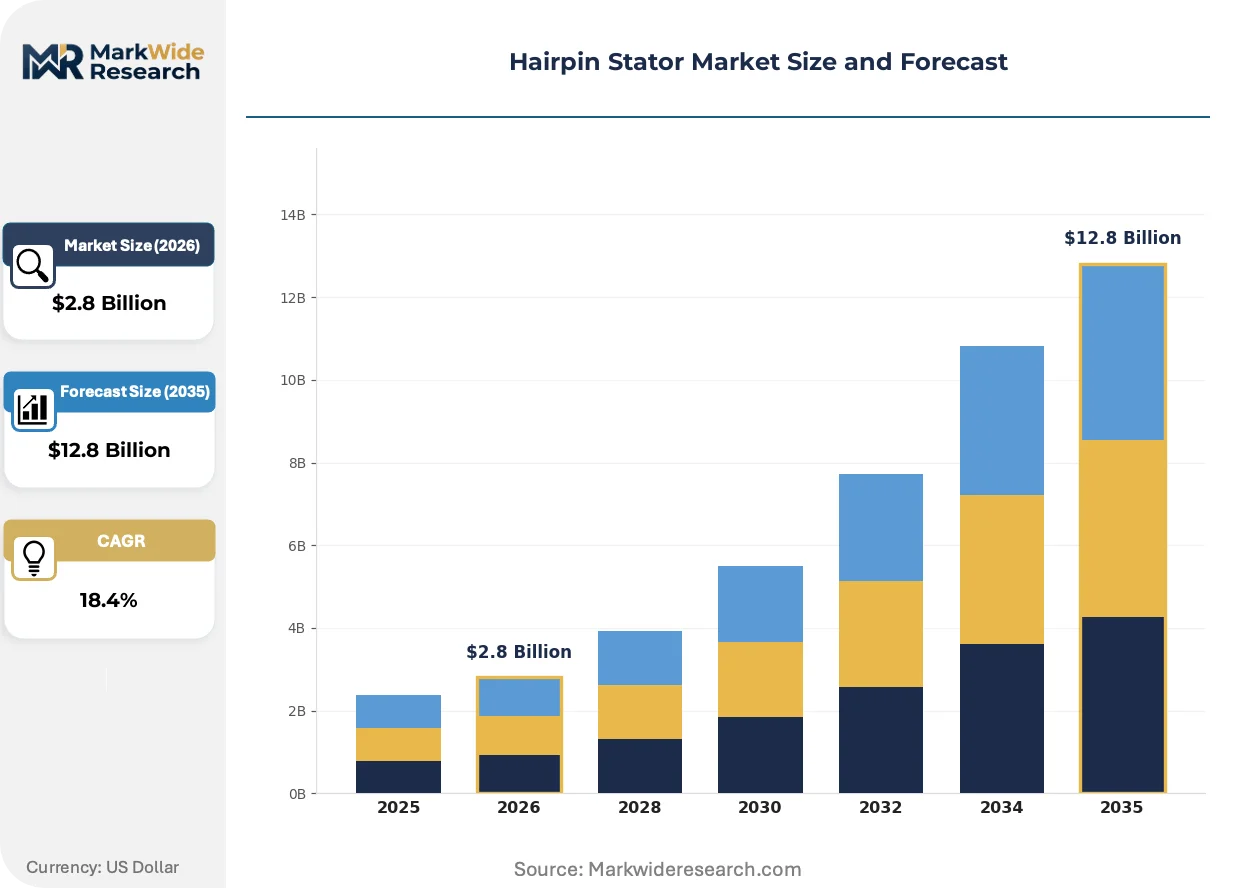
Market Dynamics
Automotive OEM consolidation around 800-volt powertrain architectures is compressing supplier qualification timelines and forcing hairpin stator manufacturers to absorb upfront tooling costs without guaranteed volume commitments.
Growth Catalysts
- China's GB Standards:MIIT-enforced NEV motor efficiency mandates filter supplier qualification and accelerate procurement of multi-layer hairpin designs by domestic EV manufacturers.
- Copper Forming Automation:Robotic hairpin bending and laser welding systems reduce cycle times and defect rates in high-volume European assembly plants.
- Germany's Supplier Corridor:Stuttgart-Munich production clusters concentrate lamination stamping and vacuum pressure impregnation expertise within 200-kilometer radii of Volkswagen and BMW engineering centers.
Market Restraints
- Copper Price Volatility:Raw material cost swings compress margin visibility for winding manufacturers locked into 12-month automotive supply agreements.
- Laser Welding Equipment Concentration:German and Japanese capital equipment suppliers control 90% of precision jointing systems, creating single-source vulnerability for tier-two stator assemblers.
- Round Wire Substitution:Continuous hairpin winding technology retains cost advantages in sub-50 kW auxiliary motors, limiting addressable market expansion.
Strategic Opportunities
- India's PLI Scheme:Production-linked incentives for automotive component manufacturing attract hairpin stator investment to serve emerging domestic EV and two-wheeler electrification demand.
- Aviation Thermal Management:Hybrid-electric propulsion programs at airframers require hairpin-derived motors with power density above 5 kW per kilogram for turbofan replacement applications.
- EU F-Gas Phase-Down:REACH-compliant insulation varnish formulations create first-mover advantages for coating chemistry suppliers requalifying European-bound production lines.
Industry Challenges
- Laser Optics Technician Scarcity:Joint quality verification requires specialized weld pool monitoring expertise that outpaces vocational training program output in manufacturing regions.
- 800-Volt Platform Validation:Dielectric testing protocols for multi-layer hairpin configurations extend motor certification cycles by 8-14 months versus 400-volt baseline designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hairpin Stator Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $12.8 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Layer Hairpin, Multi-Layer Hairpin, Double-Layer Hairpin, Wound Stator Technology: Vacuum Pressure Impregnation, Automated Winding, Laser Welding, Insulation Coating Application: Electric Vehicles, Industrial Automation, Renewable Energy Systems, Consumer Appliances End User: OEM Manufacturers, Tier-1 Suppliers, Electric Motor Assemblers, Aftermarket Providers |
| Companies Covered | Nidec, Denso, Aumann, Tecnomatic, AMADA WELD TECH, GROB, BorgWarner, Huayu Automotive Systems, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hairpin Stator Market Trends and Innovations
Hairpin winding technology is undergoing material and process convergence as copper alloy formulations, insulation systems, and joining methods advance in lockstep with automotive electrification roadmaps.
Continuous hairpin forming from rectangular copper strip is rewriting motor manufacturing economics by eliminating discrete segment cutting and individual insertion steps. Tier-one suppliers in Germany and Japan are adopting this approach for 2026-model-year powertrains. The technology is compressing capital intensity per unit of motor output and enabling same-line flexibility across 400-volt and 800-volt product variants.
REACH restrictions on phenolic resin precursors are forcing insulation coating reformulations across European-bound production. ECHA substance evaluations have disqualified two legacy varnish chemistries since 2023. High-voltage motor manufacturers are responding with vacuum pressure impregnation systems using epoxy-anhydride hybrids that meet thermal class 200 requirements while satisfying substance authorization timelines.
Direct sourcing contracts between EV OEMs and copper semi-fabricators are displacing traditional tiered supply structures for conductor procurement. BYD and Tesla have established annual volume agreements with Asian copper rod producers, bypassing legacy magnet wire distributors. This pattern is most visible in China, where integrated OEMs capture 15-20 percentage points of cost advantage through backward integration into raw material conversion.
Hairpin Stator Market Segmentation
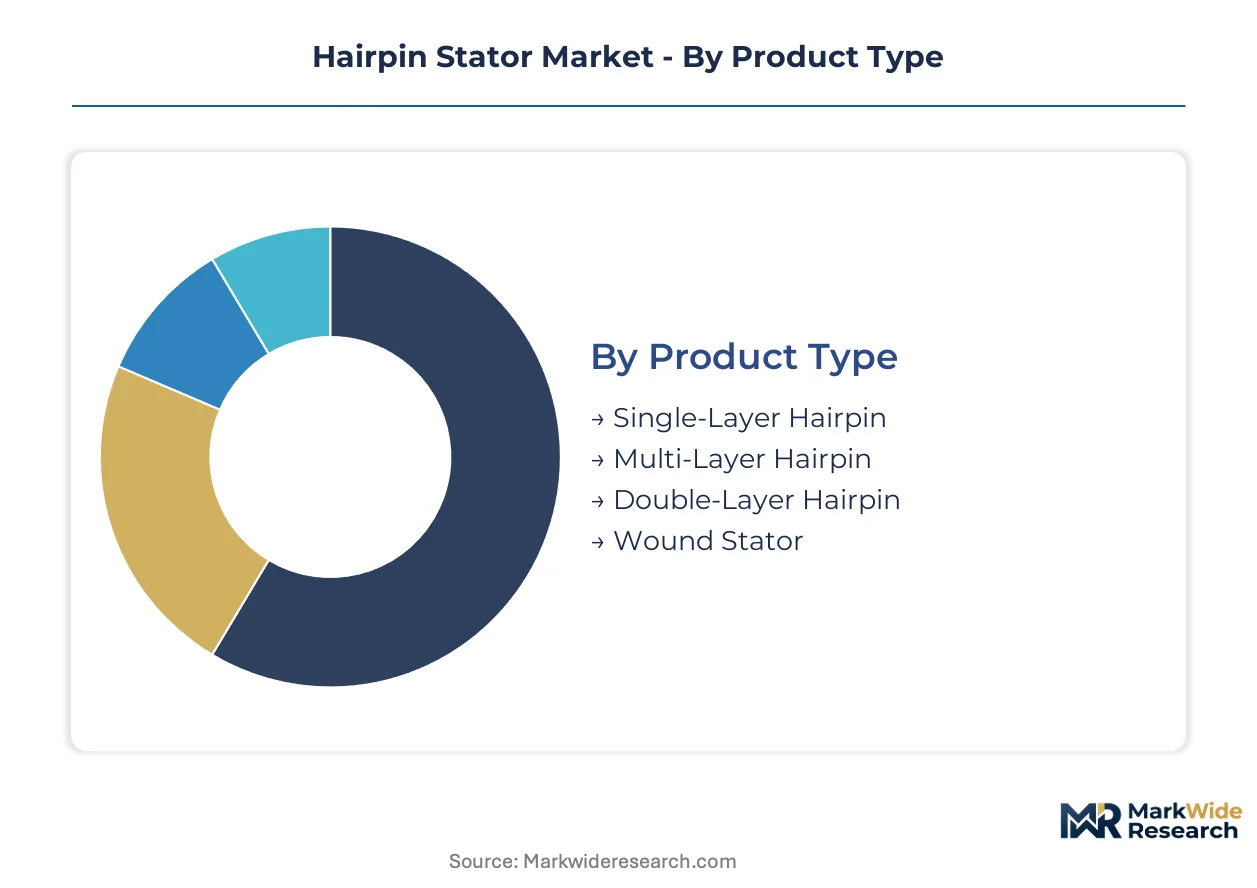
Hairpin stator procurement diverges sharply across powertrain architectures, manufacturing processes, and customer integration depth. Understanding these segment boundaries clarifies where capital equipment investments concentrate and which technical specifications filter supplier qualification.
Product Type:
Standardization dominates low-voltage auxiliary motors while customization intensity escalates with layer count and thermal class requirements.
- Multi-Layer Hairpin:Stacked rectangular conductors achieve fill factors above 60 percent in 800-volt traction motors. BYD and Volkswagen procurement programs in China and Germany specify these configurations for power density targets exceeding 4.5 kW per kilogram.
- Single-Layer Hairpin:Simpler U-shaped segments suit cost-sensitive 400-volt platforms with moderate thermal cycling demands. Nidec's Japanese production lines optimize automation economics for this architecture across compact EV segments.
- Double-Layer Hairpin:Intermediate complexity bridges standard and high-performance applications.
- Wound Stator:Legacy round-wire construction retains share in sub-50 kW auxiliary motors.
Most installed capacity flows through Single-Layer Hairpin. Expansion is steepest in Multi-Layer Hairpin.
Technology:
Process maturity separates high-volume automotive qualification from emerging industrial adoption.
- Laser Welding:Precision jointing of hairpin ends determines motor efficiency and warranty exposure. German and Japanese equipment suppliers control 90 percent of precision systems, creating qualification bottlenecks for tier-two assemblers.
- Vacuum Pressure Impregnation:Epoxy-anhydride resin systems under vacuum ensure dielectric integrity across thermal cycling. REACH-compliant formulations are requalifying European-bound production lines following ECHA substance evaluations.
- Automated Winding:Robotic bending and insertion reduce cycle times in Stuttgart-Munich supplier corridors.
- Insulation Coating:Varnish chemistry choices face F-Gas Regulation constraints in EU markets.
Capital deployment concentrates in Laser Welding. Fastest capability buildout is occurring in Vacuum Pressure Impregnation.
Application:
Volume scale and technical specification stringency create distinct procurement channels across end-use sectors.
- Electric Vehicles:Traction motors above 150 kW dominate hairpin stator procurement value. China's MIIT-enforced GB standards for NEV motor efficiency mandate minimum performance thresholds that filter supplier panels for domestic EV manufacturers.
- Industrial Automation:Servo and spindle motors require precision winding with tight inductance tolerances.
- Renewable Energy Systems:Wind turbine generators and solar tracking motors adopt hairpin designs for reliability in variable thermal environments.
- Consumer Appliances:High-efficiency washing machine and HVAC compressor motors represent emerging volume opportunities.
Revenue concentration sits with Electric Vehicles. Industrial Automation is gaining share fastest as robotics electrification accelerates.
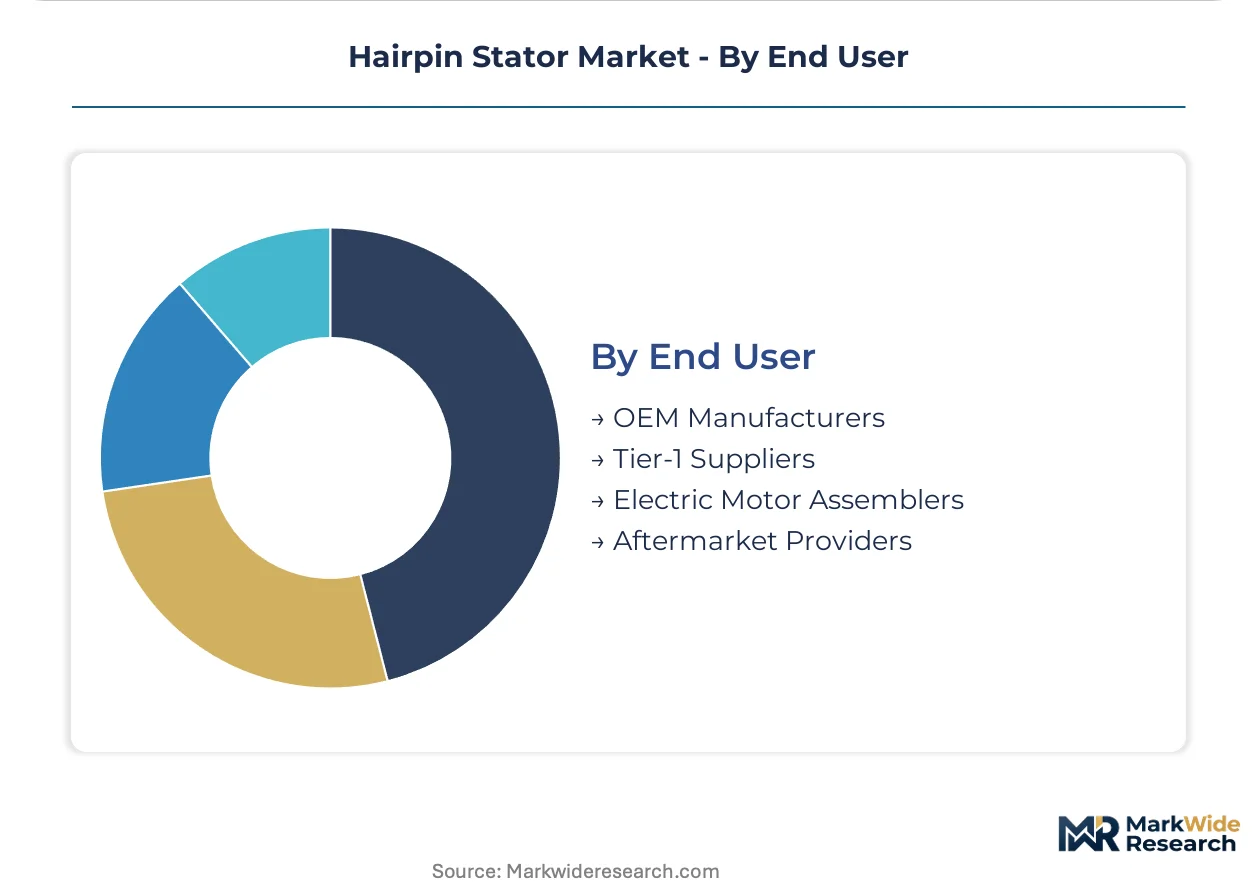
End User:
Integration depth and backward integration appetite segment the customer base.
- OEM Manufacturers:Tesla and BYD direct sourcing contracts with copper semi-fabricators bypass traditional tiered supply structures. Integrated OEMs capture cost advantages through captive raw material conversion.
- Tier-1 Suppliers:BorgWarner and Denso anchor production capacity within Toyota and Volkswagen ecosystems.
- Electric Motor Assemblers:Independent winding houses serve aftermarket and specialty industrial demand.
- Aftermarket Providers:Repair and replacement volumes concentrate in legacy vehicle parc regions.
Procurement volume flows predominantly through Tier-1 Suppliers. OEM direct engagement is expanding most quickly as vertical integration strategies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive supplier corridor concentrates hairpin stator expertise more densely than any comparable cluster in North America, while China's vertically integrated OEMs capture cost advantages through direct copper sourcing that European tier-one suppliers cannot replicate.
China
BYD and domestic EV manufacturers drive procurement volume for multi-layer hairpin configurations under MIIT-enforced GB standards for NEV motor efficiency. The country's dual carbon goals accelerate motor efficiency mandates that filter supplier qualification. Yangtze River Delta production clusters around Shanghai concentrate lamination stamping and automated winding capacity.
Germany
Volkswagen and BMW engineering centers in Stuttgart and Munich anchor demand for 800-volt traction motor assemblies with fill factors exceeding 60 percent. The EU's F-Gas Regulation and REACH restrictions on insulation materials constrain coating chemistry choices for European-bound production. Baden-Württemberg supplier corridors within 200-kilometer radii concentrate vacuum pressure impregnation expertise.
United States
Tesla's direct sourcing contracts with copper semi-fabricators displace traditional tiered supply structures for conductor procurement. EPA fuel-economy standards for hybrid powertrains and FDA oversight of electromagnetic compatibility in medical device motors shape product certification requirements. Midwest automotive manufacturing zones and California EV engineering centers split demand concentration.
Japan
Nidec and Denso anchor production capacity within Toyota's supplier ecosystem, optimizing automation economics for single-layer hairpin architectures. METI industrial policy supports motor efficiency advancement in compact EV segments. Chubu and Kanto manufacturing belts concentrate robotic bending and laser welding systems.
India
Production-linked incentives for automotive component manufacturing attract hairpin stator investment to serve emerging domestic EV and two-wheeler electrification demand. The country's PLI scheme offers cost competitiveness for export-oriented winding houses. Tamil Nadu and Maharashtra automotive clusters host initial capacity buildout.
Hairpin Stator Market Competitive Landscape
German and Japanese producers anchor one tier; Chinese specialists hold cost-driven positions through backward integration into raw material conversion. Supplier qualification timelines compress as automotive OEM consolidation around 800-volt architectures forces manufacturers to absorb upfront tooling costs without guaranteed volume commitments. Three strategic archetypes dominate: vertically integrated motor manufacturers, precision winding equipment suppliers, and copper semi-fabricators with direct OEM contracts. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms race to secure laser welding equipment and qualified technician pools.
Among Japanese motor manufacturers, Nidec and Denso exemplify the vertically integrated archetype, with geographic naming conventions signaling Kansai and Chubu regional anchoring respectively. BorgWarner represents technology leadership positioning within the tier-one supplier tier. These three occupy positions that illustrate how competitive advantage flows from either upstream control over lamination-to-assembly workflows or from multi-layer architecture specialization for high-voltage platforms.
| Leading Market Players |
|---|
| Nidec |
| Denso |
| Aumann |
| Tecnomatic |
| AMADA WELD TECH |
| GROB |
| BorgWarner |
| Huayu Automotive Systems |
| Siemens |
| Others |
Pricing and Supply Chain Analysis
EV OEM direct sourcing programs concentrate procurement power among vertically integrated manufacturers, forcing contract-based long-term offtake pricing with copper semi-fabricators rather than spot-market transactions. This buyer consolidation compresses margin buffers for tier-two stator assemblers locked into 12-month automotive supply agreements without volume guarantees.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for multi-layer hairpin configurations as Yangtze River Delta producers achieve scale economies. Contract-based long-term offtake dominates, with price differentiation driven by certification grade (MIIT GB standard compliance) and volume scale. Cost compression in single-layer architectures is intensifying because round-wire substitution retains cost advantages in sub-50 kW auxiliary motors. Tier-1 suppliers exhibit lowest price sensitivity due to captive OEM relationships; independent winding houses face highest price sensitivity.
Supply Chain Analysis
Freight cost escalation from German and Japanese laser welding equipment suppliers to tier-two assemblers in India and Southeast Asia amplifies working capital requirements. Supply concentrates in Germany, China, and Japan for precision jointing systems and lamination stamping. The chain draws from copper rod, epoxy-anhydride resin, and silicon steel inputs. Single-source vulnerability in laser optics equipment creates structural risk. Distribution runs through OEM direct contracts and tier-1 supplier networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hairpin stator market compounds steadily as automotive electrification mandates tighten motor efficiency thresholds across major economies. This regulatory ratchet sustains procurement volume growth independent of near-term vehicle sales cycles.
For Market Incumbents: Hedge against round-wire substitution in auxiliary motor segments by accelerating multi-layer architecture R&D for 800-volt platforms. Lock in laser welding equipment allocation through strategic partnerships with German and Japanese capital equipment suppliers before technician scarcity worsens. For New Entrants and Emerging Players: Capture India's PLI scheme incentives for automotive component manufacturing by establishing winding capacity in Tamil Nadu or Maharashtra clusters. Target two-wheeler electrification and emerging domestic EV demand as the most penetrable segment, with cost-competitive export positioning to Southeast Asia as the go-to-market angle. For Investors and Strategic Acquirers: Tier-1 automotive suppliers are the most active acquirer in this space, seeking laser welding capability and qualified technician pools. The market offers 5-10 year viability through sustained OEM electrification roadmaps. Acquisition target archetype: mid-cap winding houses with MIIT GB certification and existing relationships with copper semi-fabricators. Watch laser welding equipment lead times as the inflection indicator for supply-constrained pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Layer Architecture Scale-Up | BYD and Volkswagen procurement programs specify fill factors above 60 percent for 800-volt traction motors. |
| Laser Welding Equipment Partnership | German and Japanese suppliers control 90 percent of precision jointing systems, creating qualification bottlenecks. |
| REACH-Compliant Varnish Reformulation | ECHA substance evaluations disqualified two legacy chemistries, forcing epoxy-anhydride hybrid adoption. |
| India PLI Scheme Capacity Buildout | Tamil Nadu and Maharashtra clusters attract investment for domestic EV and two-wheeler electrification demand. |
| Copper Semi-Fabricator Direct Contract | Tesla and BYD bypass traditional tiered supply structures to capture 15-20 percentage point cost advantages. |
Research Methodology
Coverage spans China, Germany, United States, Japan, and India, with primary inputs from each region combining interviews with OEM platform engineers, tier-1 supplier procurement leads, laser welding equipment specialists, and copper semi-fabricator commercial directors. Secondary validation draws from MIIT GB standard filings, EU REACH substance evaluations, EPA fuel-economy compliance data, and automotive production databases. Bottom-up and top-down triangulation reconciles equipment installation counts with OEM procurement pipeline visibility.
Granularity extends to powertrain architecture (400-volt versus 800-volt), layer count configuration, and regional regulatory cluster across the projection horizon. CAGRs derive from segment-level volume buildups incorporating OEM electrification roadmap commitments and motor efficiency mandate enforcement timelines. Industry-specific inputs include laser welding equipment lead times and copper price volatility assumptions.
Copper price volatility, laser optics technician availability, and 800-volt platform certification delays are the dominant revision risks. Forecasts reflect documented assumptions about OEM sourcing strategy evolution and regulatory enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Leadframes Market
Semiconductor Devices
Middle East Distribution Panel Market
Semiconductor Devices
Digital Transistor Market
Semiconductor Devices
Embedded Multimedia Card Market
Semiconductor Devices
AIN DBC Ceramic Substrate Market
Semiconductor Devices
Chip Crusher Market
Semiconductor Devices
Amorphous-Semiconductor Devices Market
Semiconductor Devices
Global Power MOSFET Market
Semiconductor Devices
Epi Wafer Market
Semiconductor Devices
Underfill Market
Semiconductor Devices
IT & Telecom Discrete Semiconductor Market
Semiconductor Devices
Global Vacuum Capacitors Market
Semiconductor Devices
High Electron Mobility Transistor Market
Semiconductor Devices
Finfet Technology Market
Semiconductor Devices
Photosensitive Semiconductor Device Market
Semiconductor Devices
Middle East and Africa Ultra-Low-Power Microcontroller Market