
 Global Inp Wafer Market | 2026-2036
Global Inp Wafer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Inp Wafer Market Outlook
Capital-intensity divergence between vapor-phase epitaxy specialists and liquid-phase incumbents is unwinding competitive stability across the InP wafer supply base. Sumitomo Electric Semiconductor Materials leverages captive crystal-growth capacity to sustain pricing power in high-purity substrates. Freiberger Compound Materials anchors European supply through specialized hydride vapor phase epitaxy expertise. AXT competes on cost-optimized molecular beam epitaxy platforms for photonic device foundries.
Indium phosphide wafers are III-V compound semiconductor substrates with lattice-matched InGaAs and AlInAs layers, typically manufactured via liquid-encapsulated Czochralski pulling followed by chemomechanical polishing to epitaxy-ready surface specifications below 0.5 nm roughness. Photonic devices dominate current volume as datacenter transceivers and coherent optical modules replace legacy silicon photonics at 800G and beyond. Discrete devices represent the fastest-expanding margin pool, driven by defense radar and satellite communication procurement. Chemical vapor deposition retains technology leadership for integrated circuits requiring atomic-layer thickness control.
Japan's METI subsidizes domestic InP substrate capacity under semiconductor resilience frameworks, while China's SAMR enforces GB standards for compound semiconductor imports that elevate qualification barriers for non-Chinese suppliers. REACH and RoHS compliance in Europe restricts indium sourcing from conflict-affected zones, reshaping supplier audit requirements. Stakeholders must monitor divergence between Japan's export-control alignment with US CHIPS Act restrictions and China's push for alternative epitaxy equipment supply chains.
Market Dynamics
Telecommunications infrastructure buildout for 5G backhaul and fiber-optic networks is compressing substitution timelines for legacy silicon photonics, forcing substrate suppliers to align capacity with coherent optical module roadmaps.
Growth Catalysts
- 5G Infrastructure Deployment:Telecommunications carriers in Japan, China, and South Korea are expanding fiber-optic backhaul networks that require indium phosphide substrates for high-frequency photonic devices.
- MIIT Domestic Sourcing Mandates:China's Ministry of Industry and Information Technology is accelerating local qualification requirements for compound semiconductor materials under national self-sufficiency frameworks.
- Datacenter Transceiver Upgrades:Cloud infrastructure operators are migrating to 800G coherent optical modules, creating pull-through demand for lattice-matched III-V substrates with superior electron mobility.
Market Restraints
- Indium Supply Concentration:Primary indium refining concentrates in Chinese smelters, exposing substrate manufacturers to export quota volatility and price swings in the raw material layer.
- GB Standards Qualification Barriers:China's State Administration for Market Regulation enforces compound semiconductor import standards that extend certification timelines for non-domestic suppliers by 12-18 months.
- Silicon Photonics Cost Pressure:Mature silicon photonics platforms for sub-400G applications continue to capture volume in price-sensitive datacenter interconnects, capping InP substrate penetration in the mid-tier.
Strategic Opportunities
- Defense Radar Procurement:Satellite communication and electronic warfare programs in the United States and European NATO members are sourcing discrete indium phosphide devices for millimeter-wave applications.
- Japan METI Resilience Subsidies:Japan's Ministry of Economy, Trade and Industry is funding domestic substrate capacity expansion under semiconductor supply chain security frameworks.
- Photonic Integrated Circuit Convergence:Monolithic integration of lasers, modulators, and detectors on single InP chips is enabling transceiver footprint reduction for hyperscale datacenter operators.
Industry Challenges
- Epitaxy Equipment Lead Times:Hydride vapor phase epitaxy and molecular beam epitaxy tool availability from specialized equipment vendors stretches 14-20 months, constraining substrate qualification cycles.
- Atomic-Layer Thickness Control:Integrated circuit applications demand sub-nanometer uniformity across 150mm wafers, requiring process engineers with compound semiconductor metrology expertise that remains scarce outside East Asian manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Inp Wafer Market |
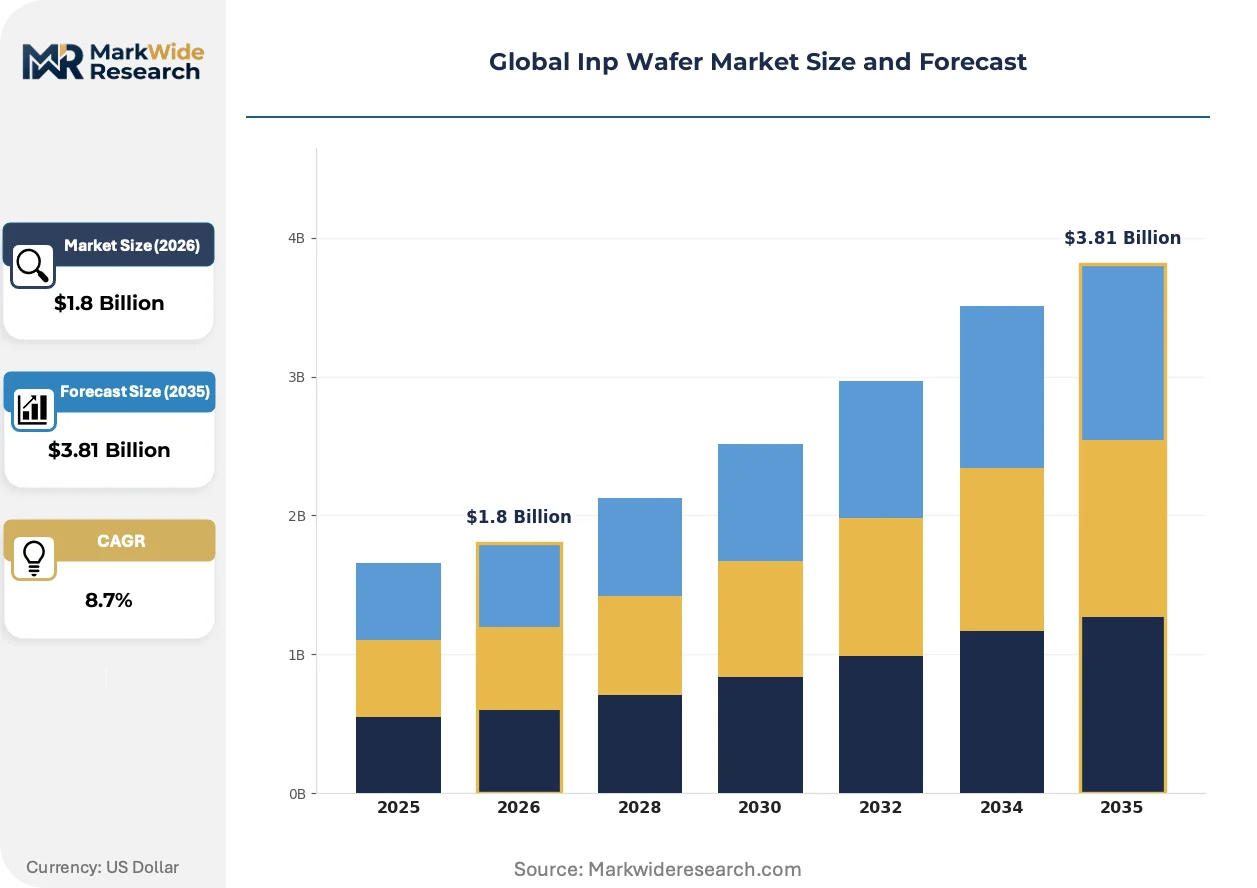
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Discrete Devices, Integrated Circuits, Photonic Devices, Sensors Technology: Molecular Beam Epitaxy, Chemical Vapor Deposition, Hydride Vapor Phase Epitaxy, Liquid Phase Epitaxy End User: Telecommunications, Consumer Electronics, Automotive, Aerospace Application: Data Communications, Optical Communication, Defense, Medical Devices |
| Companies Covered | Sumitomo Electric Semiconductor Materials Inc., AXT Inc., Freiberger Compound Materials GmbH, JX Nippon Mining & Metals Corporation, Wafer Technology Ltd., Xiamen Powerway Advanced Material Co. Ltd., DOWA Electronics Materials Co. Ltd., IQE plc, IntelliEPI Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Inp Wafer Market Strategic Shifts
Substrate manufacturing is bifurcating between high-purity vapor-phase epitaxy for photonic integrated circuits and cost-optimized liquid-phase platforms for discrete devices, with equipment choices locking in decade-long competitive positioning.
Hydride vapor phase epitaxy is displacing liquid-phase Czochralski methods for datacenter transceiver substrates. Cloud infrastructure operators are specifying HVPE-grown wafers for 800G coherent modules. This technology shift is compressing margins for incumbent crystal-pulling specialists while rewarding equipment-heavy entrants with atomic-layer control capabilities.
Japan's METI semiconductor resilience frameworks are redirecting subsidy flows toward domestic InP substrate capacity. The industrial consequence is a protected qualification pathway for Japanese suppliers in defense and telecommunications procurement. European REACH and RoHS compliance requirements are most affected, forcing supplier audit restructuring to exclude conflict-zone indium sourcing.
Hyperscale operators are consolidating photonic device procurement through captive foundry relationships rather than merchant substrate channels. Cloud infrastructure buyers in the United States and China are negotiating direct epitaxy-ready wafer supply agreements. This concentration is most visible in East Asian manufacturing clusters where substrate vendors co-locate with transceiver assembly facilities.
Global Inp Wafer Market Segmentation

Indium phosphide wafer procurement channels diverge sharply by device complexity. Photonic integrated circuits flow through captive foundry relationships, while discrete devices move through merchant distributors. Understanding these channel dynamics reveals where pricing power concentrates and qualification barriers bite hardest.
Product Type:
Channel concentration varies dramatically across device categories. Photonic devices and integrated circuits dominate direct OEM supply agreements, while discrete devices and sensors flow through broader distribution networks.
- Photonic Devices:These substrates carry lasers, modulators, and photodetectors monolithically integrated for coherent optical transceivers. Datacenter operators in Virginia, Frankfurt, and Singapore are specifying epitaxy-ready wafers for 800G module roadmaps, compressing substitution timelines for legacy silicon photonics.
- Integrated Circuits:Atomic-layer thickness control enables high-frequency amplifiers and mixed-signal processors. Defense procurement offices in the United States and Japan are sourcing these substrates under classified electronic warfare programs, creating insulated demand pockets with extended qualification cycles.
- Discrete Devices:Individual transistors and diodes for radar front-ends.
- Sensors:Photodetectors and thermal imaging arrays.
By volume, photonic devices leads. By growth pace, integrated circuits is ahead.
Technology:
Cost structures stratify by equipment intensity. Hydride vapor phase epitaxy and molecular beam epitaxy command premium pricing for photonic applications, while liquid-phase methods serve price-sensitive discrete device markets.
- Hydride Vapor Phase Epitaxy:Delivers atomic-layer uniformity across 150mm wafers for datacenter transceivers. Cloud infrastructure operators are mandating HVPE-grown substrates for 800G coherent modules, displacing legacy crystal-pulling methods.
- Chemical Vapor Deposition:Enables precise thickness control for integrated circuit applications. Japanese and South Korean foundries are expanding CVD capacity under METI resilience subsidies and domestic self-sufficiency frameworks.
- Molecular Beam Epitaxy:Ultra-high vacuum deposition for research-grade and defense-specified wafers.
- Liquid Phase Epitaxy:Cost-optimized growth for high-volume discrete device production.
Equipment lock-in spans decade-long depreciation cycles, freezing competitive positioning for each technology choice.
End User:
Customer concentration shapes contract structures. Telecommunications carriers negotiate multi-year supply agreements, while automotive and aerospace buyers impose stringent qualification protocols.
- Telecommunications:Fiber-optic backhaul and 5G infrastructure deployment in Japan, China, and South Korea drives substrate demand for high-frequency photonic devices. NTT, China Mobile, and SK Telecom are consolidating procurement through direct epitaxy-ready wafer agreements.
- Aerospace:Satellite communication and electronic warfare programs require radiation-hardened discrete devices. United States Space Force and European NATO members are sourcing millimeter-wave components under accelerated procurement timelines.
- Consumer Electronics:Optical interconnects for high-performance computing devices.
- Automotive:Lidar sensors and optical networking for autonomous driving systems.
Telecommunications commands the largest revenue share. Aerospace exhibits the steepest expansion trajectory.
Application:
Margin profiles diverge by performance requirements. Defense and medical applications tolerate premium pricing for qualified supply, while data communications faces relentless cost compression.
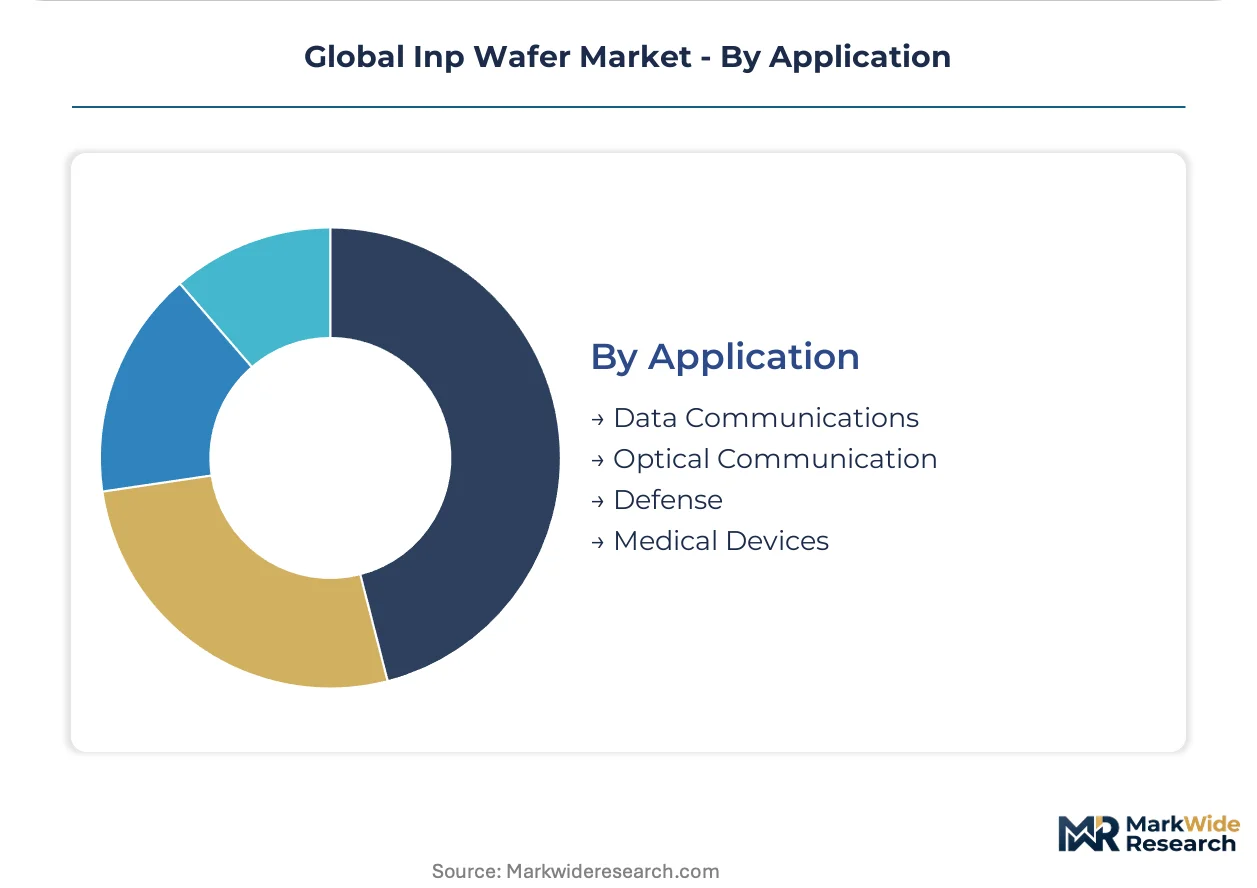
- Data Communications:Datacenter transceiver upgrades are pulling 800G coherent optical modules into mass deployment. Hyperscale operators in Ashburn, Dublin, and Singapore are consolidating photonic device procurement through captive foundry relationships rather than merchant channels.
- Defense:Radar and electronic warfare systems demand discrete indium phosphide devices with guaranteed supply chains. United States Department of Defense and Japan's Acquisition, Technology and Logistics Agency are screening suppliers for indium sourcing compliance outside conflict-affected zones.
- Optical Communication:Long-haul fiber networks and submarine cable systems.
- Medical Devices:Optical coherence tomography and laser surgical equipment.
Data communications generates the highest wafer volume. Defense applications capture the widest margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese and Chinese substrate corridors while European suppliers absorb REACH compliance premiums. Japanese METI resilience subsidies shield domestic manufacturers from raw material volatility. Chinese MIIT localization mandates compress qualification windows for non-domestic entrants.
Japan
Defense radar procurement and datacenter transceiver roadmaps drive substrate demand from NTT and Fujitsu. METI semiconductor resilience frameworks fund domestic InP capacity expansion under supply chain security mandates. Tokyo-Osaka manufacturing clusters host epitaxy-ready wafer production for 800G coherent optical modules.
China
MIIT domestic sourcing mandates accelerate local qualification for compound semiconductor materials under self-sufficiency targets. SAMR enforces GB standards that extend certification timelines for imported substrates by 12-18 months. Xiamen and Shanghai manufacturing corridors concentrate hydride vapor phase epitaxy capacity for photonic device foundries.
United States
Department of Defense electronic warfare programs and Space Force satellite communications create insulated demand for radiation-hardened discrete devices. Export control alignment with CHIPS Act restrictions limits Chinese substrate access to classified procurement channels. Virginia and Texas datacenter clusters pull 800G transceiver substrates through direct OEM agreements.
South Korea
SK Telecom and Korea Telecom 5G backhaul deployment drives high-frequency photonic device substrate procurement. Domestic self-sufficiency frameworks under the Ministry of Trade, Industry and Energy subsidize local epitaxy capacity. Seoul-Incheon manufacturing belts concentrate molecular beam epitaxy platforms for defense-specified wafers.
Germany
European NATO defense procurement and automotive lidar development create dual demand streams for indium phosphide substrates. REACH and RoHS compliance requirements force supplier audit restructuring to exclude conflict-zone indium sourcing. Freiburg compound materials corridor anchors continental supply through specialized hydride vapor phase epitaxy expertise.
Global Inp Wafer Market Competitive Environment
Concentration sits with integrated crystal-growth specialists who command pricing power through captive indium refining and epitaxy-ready wafer finishing. The supply base fragments across liquid-phase incumbents defending discrete device margins and vapor-phase entrants capturing photonic integrated circuit premiums. Two strategic archetypes dominate: equipment-heavy specialists with atomic-layer control capabilities and cost-optimized molecular beam epitaxy platforms. Competitive moves center on backward integration into indium refining and geographic co-location with transceiver assembly facilities.
Among Japanese integrated manufacturers, Sumitomo Electric Semiconductor Materials Inc. exemplifies the crystal-growth specialist archetype with METI-subsidized domestic capacity. Freiberger Compound Materials GmbH anchors European supply positioning through German REACH-compliant sourcing frameworks. AXT Inc. occupies the cost-optimized tier serving photonic device foundries with molecular beam epitaxy platforms. These three represent distinct competitive vectors: subsidy-protected domestic supply, regulation-compliant continental sourcing, and merchant foundry cost positioning.
| Leading Market Players |
|---|
| Sumitomo Electric Semiconductor Materials Inc. |
| AXT Inc. |
| Freiberger Compound Materials GmbH |
| JX Nippon Mining & Metals Corporation |
| Wafer Technology Ltd. |
| Xiamen Powerway Advanced Material Co. Ltd. |
| DOWA Electronics Materials Co. Ltd. |
| IQE plc |
| IntelliEPI Inc. |
| Others |
Value Chain & Pricing Dynamics
150mm wafer scale economies in Japanese and Chinese manufacturing corridors concentrate pricing power among crystal-growth specialists with captive indium refining. This scale concentration elevates price floors for epitaxy-ready substrates while compressing margins for equipment-light liquid-phase incumbents.
Pricing Analysis
The customization-premium spread separates epitaxy-ready wafer pricing from standard substrate tiers by a factor reflecting atomic-layer specification stringency. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with defense-specified wafers commanding the widest spreads. Cost compression in merchant foundry channels is intensifying because hyperscale datacenter operators are consolidating procurement through direct OEM agreements. Photonic device foundries exhibit the highest price sensitivity, while defense procurement offices tolerate premium pricing for qualified supply chains.
Supply Chain Analysis
Port congestion on transpacific trade lanes and container availability constraints on Asia-Europe routes are elevating inbound logistics costs for European and North American substrate consumers. Supply concentrates in Japan, China, and South Korea, with primary indium refining anchored in Chinese smelters. Raw material dependencies center on high-purity indium metal, specialty quartz crucibles, and pyrolytic boron nitride components. Single-source vulnerability in hydride vapor phase epitaxy equipment creates qualification bottlenecks stretching 14-20 months. Distribution runs through captive foundry relationships for photonic integrated circuits and merchant distributors for discrete devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Epitaxy-ready wafer qualification services and metrology calibration contracts are expanding faster than substrate hardware volumes, creating a service-attach opportunity for suppliers with compound semiconductor process expertise.
For Market Incumbents: Shield pricing power in high-purity substrates by deepening backward integration into indium refining and expanding METI-subsidized domestic capacity in Japan. Silicon photonics substitution threats in sub-400G applications demand accelerated HVPE platform deployment to maintain technology leadership in 800G coherent modules. Certification investment in China's GB standards qualification pathway is essential for defending access to MIIT-mandated procurement channels. For New Entrants and Emerging Players: After-sales metrology and epitaxy process optimization services represent a service-layer gap where incumbents under-serve photonic device foundries. European defense procurement corridors offer the most penetrable geography, with REACH-compliant indium sourcing creating qualification barriers that favor new entrants with audit-transparent supply chains. A go-to-market angle anchored in rapid GB standards certification support for Chinese market entry can accelerate customer acquisition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among equipment-heavy specialists with atomic-layer control capabilities and long-term foundry service agreements. Long-term viability over the projection horizon favors crystal-growth specialists with captive refining and geographic co-location with transceiver assembly clusters. The acquisition target archetype combines HVPE platform ownership with established defense qualification pathways. The signal to watch is divergence between Japanese export-control alignment with US CHIPS Act restrictions and China's alternative epitaxy equipment supply chain development.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Indium Refining | Captive high-purity metal supply insulates margin from Chinese export quota volatility. |
| HVPE Platform Capacity Expansion | Atomic-layer uniformity capabilities capture 800G coherent module specification premiums. |
| GB Standards Certification Investment | Accelerated qualification timelines unlock MIIT-mandated domestic sourcing procurement. |
| Defense Qualification Pathway Development | Insulated demand pockets with extended cycles reduce price sensitivity exposure. |
| Metrology Service Layer Expansion | Recurring calibration contracts attach to substrate hardware with superior retention economics. |
Study Parameters
Operator-level perspectives from epitaxy process engineers, photonic device foundry procurement managers, compound semiconductor equipment specialists, and defense program office technical directors anchored the qualitative base. These primary inputs combined with secondary validation from SEC filings of listed substrate manufacturers, METI semiconductor resilience framework disclosures, SAMR GB standards documentation, and customs trade data for indium metal flows. Bottom-up wafer demand modeling by device category triangulated against top-down market sizing from crystal-growth capacity announcements.
Sensitivity analysis tested forecast robustness across indium price volatility scenarios, equipment lead time variations, and regulatory qualification timeline shifts. Segmentation dimensions modeled include product type, epitaxy technology platform, end-user industry, and application performance tier across the analysis window. CAGRs derived from regression against historical substrate pricing and volume trends, with industry-specific inputs incorporating datacenter transceiver roadmap disclosures and defense procurement budget trajectories.
Underlying assumptions cover sustained 5G backhaul deployment, continued silicon photonics displacement at 800G and above, and stable indium supply from primary refining sources, with deviation risk concentrated in export control escalation and alternative compound semiconductor substrate substitution. Recalibration cycles align with material shifts in telecommunications infrastructure capex, defense procurement priority rebalancing, and epitaxy equipment availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
DNA Chip Market
Semiconductor Devices
Dynamic Electrograph Market
Semiconductor Devices
Asia-Pacific Semiconductor Device Market
Semiconductor Devices
Japan CEP Market
Semiconductor Devices
Global Transistor Market
Semiconductor Devices
Europe Room Cell Module Market
Semiconductor Devices
China Semiconductor Device Market
Semiconductor Devices
APAC Semiconductor Device for Processing Applications Market
Semiconductor Devices
Power Supply in Package (Psip) and Power Supply on Chip (Pwrsoc) Market
Semiconductor Devices
Bipolar Junction Transistors Market
Semiconductor Devices
Photosensitive Semiconductor Device Market
Semiconductor Devices
Nanowires Market
Semiconductor Devices
Chip Equalizers Market
Semiconductor Devices
CMP Pads Market
Semiconductor Devices
N-Topcon Solar Cells Market
Semiconductor Devices
Global Precision Parts Market