
 DNA Chromatography Chip Market | 2026-2036
DNA Chromatography Chip Market Size, Share, and Industry Trends Forecast 2026-2036
DNA Chromatography Chip Market Insights
A capital-intensity divergence between in-house foundry operators and fabless design specialists is redrawing competitive boundaries in DNA chromatography chips. Thermo Fisher Scientific leverages captive semiconductor fabrication to control substrate quality for silicon-based devices. Agilent Technologies anchors its position through deep vertical integration in glass microfluidics, from raw borosilicate to finished consumables. Illumina competes by extending its sequencing ecosystem into upstream sample-prep separation modules.
DNA chromatography chips integrate micro- or nano-scale fluidic channels with stationary-phase chemistries to separate nucleic acid fragments by size, charge, or binding affinity, typically operating at nanoliter flow rates with channel dimensions below 100 micrometers. These devices serve primarily to automate and miniaturize preparatory separation steps that previously required bench-scale liquid chromatography or gel electrophoresis. Microfluidic chips lead the product landscape due to their compatibility with existing sequencing workflows, while silicon chips represent the fastest-growing category as semiconductor fabrication techniques enable denser channel arrays. Among end users, pharmaceutical companies command the deepest procurement budgets, though academic research institutes sustain the highest shipment volumes for exploratory applications.
The FDA regulates these devices as in vitro diagnostic components or research-use-only instruments depending on intended application, creating a bifurcated compliance pathway that shapes R&D investment priorities. EPA and OSHA frameworks additionally govern manufacturing facilities handling solvent-based surface chemistries and nanoscale substrate materials. ISO 13485 certification has become a de facto market-access requirement for suppliers serving clinical laboratories. Stakeholders must monitor how evolving FDA guidance on next-generation sequencing quality controls reshapes validation requirements for integrated chip-based separation modules.
Market Dynamics
Semiconductor fabrication capacity scarcity is redrawing competitive boundaries in DNA chromatography chips, forcing design specialists into foundry partnerships while integrated operators deepen captive substrate control. This supply concentration dynamic amplifies pricing power for silicon-based device manufacturers and accelerates consolidation in glass microfluidics supply chains.
Growth Catalysts
- Liquid Biopsy Guidance:FDA's evolving companion diagnostic frameworks compress validation timelines for chip-based separation modules in oncology workflows.
- Pharmaceutical Procurement:Contract research organizations in the United States are building dedicated genomics pipelines around microfluidic separation platforms for high-throughput screening.
- Silicon Channel Density:Advanced lithography techniques enable nanoliter-scale flow control in denser array configurations, expanding throughput per device.
Market Restraints
- Foundry Bottlenecks:Limited 200mm and 300mm semiconductor fabrication capacity for MEMS-compatible processes concentrates production risk in Taiwan and South Korea.
- Surface Chemistry Volatility:Solvent-based functionalization reagents face EPA and OSHA reporting thresholds that inflate manufacturing compliance costs.
- Substitute Platforms:Magnetic bead-based nucleic acid purification systems compete for sample-prep automation budgets in clinical laboratories.
Strategic Opportunities
- Point-of-Care Expansion:Decentralized diagnostic networks in India present underpenetrated demand for cartridge-integrated separation chips.
- ISO 13485 Certification:Accelerated quality management system adoption creates first-mover access to clinical laboratory procurement channels.
- Sequencing Convergence:Integration of upstream separation modules with next-generation sequencing workflows reduces sample-handling steps.
Industry Challenges
- Microfluidic Engineering Talent:Scarcity of specialists combining semiconductor process knowledge with biochemistry surface functionalization extends product development cycles.
- Multi-Site Validation:ISO 13485 certification requires documented quality controls across distributed manufacturing locations, complicating supply chain scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DNA Chromatography Chip Market |
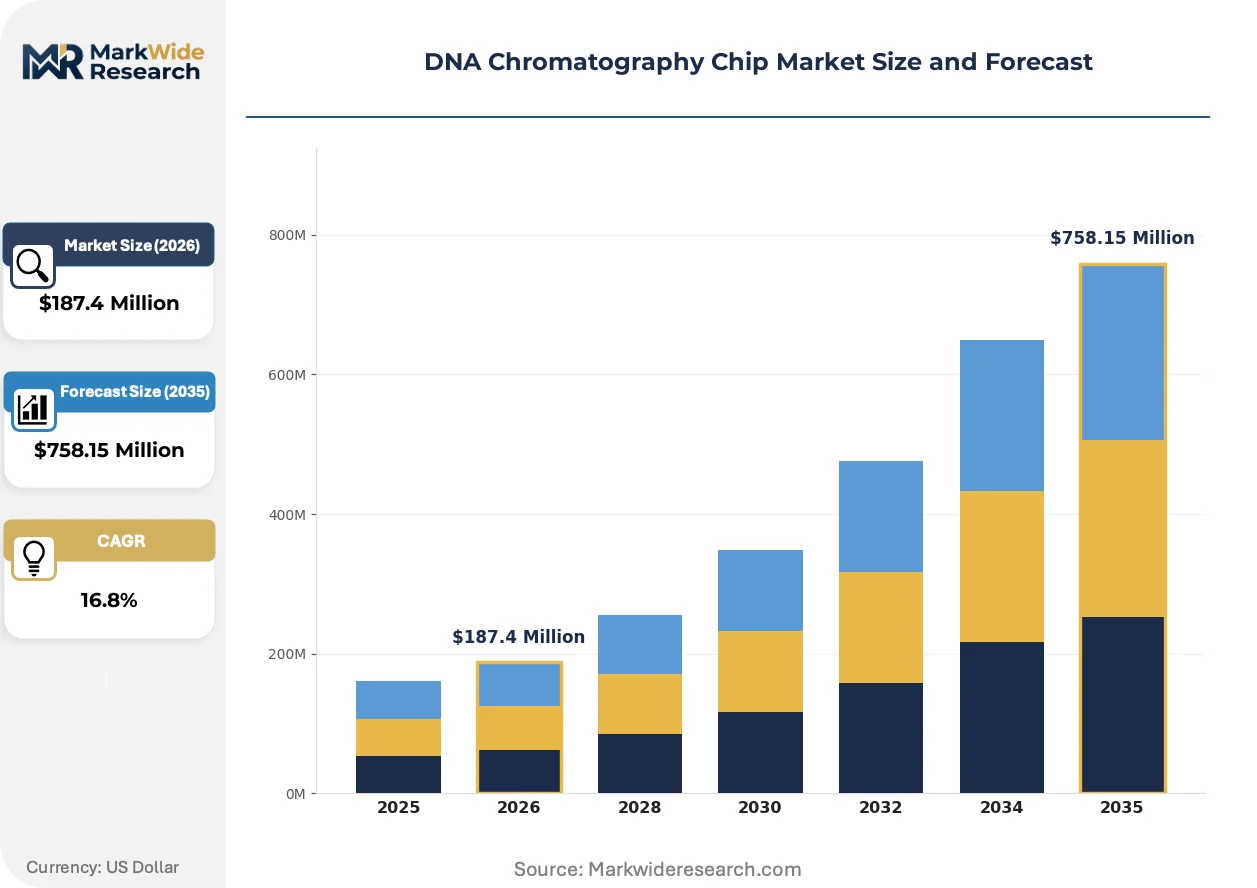
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $758.15 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfluidic Chips, Polymer-Based Chips, Glass Chips, Silicon Chips End User: Academic Research Institutes, Pharmaceutical Companies, Biotechnology Firms, Clinical Laboratories Technology: Affinity Chromatography, Ion-Exchange Chromatography, Size-Exclusion Chromatography, Reverse Phase Chromatography Application: Gene Sequencing, Protein Purification, Metabolomics, Drug Development |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, Illumina, Arrayit Corporation, PerkinElmer, Macrogen, CapitalBio Corporation, Revvity, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DNA Chromatography Chip Market Trends and Innovations
Active materials substitution and regulatory pathway evolution are compressing product lifecycles in DNA chromatography chips. Device architectures are pivoting toward modular integration with adjacent analytical platforms.
Polymer-based microfluidic substrates are displacing traditional borosilicate glass in mid-throughput applications. Academic medical centers in Germany and the United States are adopting these devices for exploratory genomics workflows. This material transition is displacing legacy glass fabrication specialists from price-sensitive procurement segments while enabling roll-to-roll manufacturing scale.
REACH restrictions on perfluorinated compounds are forcing reformulation of hydrophobic surface coatings used in nucleic acid separation channels. European manufacturers face accelerated substance authorization timelines that compress R&D planning horizons. Glass microfluidics suppliers with in-house coating capabilities are internalizing chemistry development to maintain formulation control.
Consolidated procurement by pharmaceutical central laboratories is compressing vendor qualification cycles and unbundling after-sales service contracts. Large CROs in the United States now demand dedicated field application scientist coverage as a standard contractual term. This service unbundling shifts margin pressure onto smaller device manufacturers lacking nationwide support infrastructure.
DNA Chromatography Chip Market Segmentation
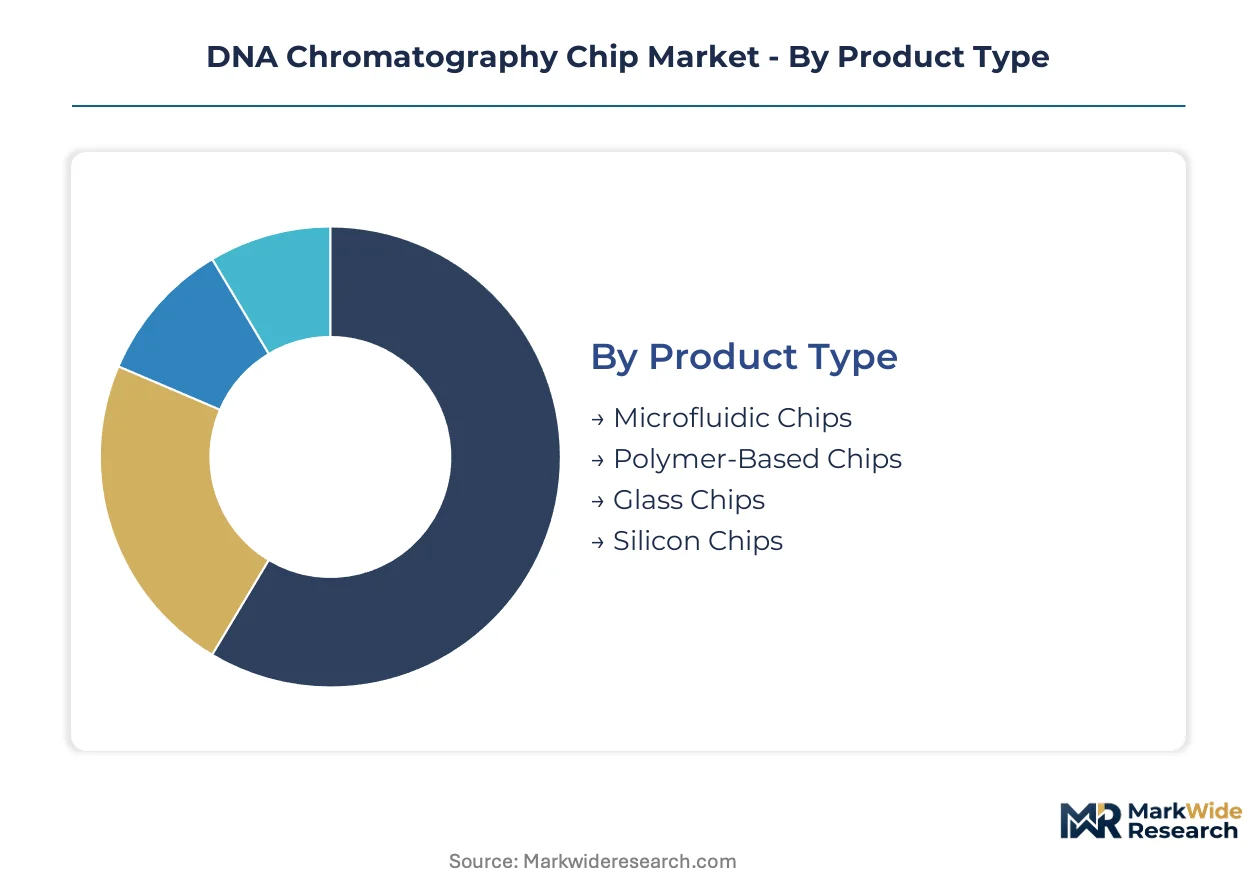
Segmentation in DNA chromatography chips reveals how regulatory pathways, material science trade-offs, and end-use workflows fragment procurement priorities across the value chain. Each dimension carries distinct compliance burdens and performance specifications that shape vendor positioning.
Product Type:
FDA classification diverges sharply by substrate material, with silicon devices facing stricter validation as IVD components while polymer chips navigate research-use-only pathways.
- Microfluidic Chips:These devices integrate etched channels with nanoliter-scale flow control, typically fabricated from PDMS or thermoplastics. Academic medical centers in the United States deploy them for exploratory genomics workflows where protocol flexibility outweighs regulatory burden. Their compatibility with existing liquid-handling robotics sustains volume leadership despite lower per-unit pricing.
- Silicon Chips:Semiconductor lithography produces sub-100-micrometer channel arrays with exceptional dimensional precision. Pharmaceutical central laboratories in Germany and the United States are qualifying these for high-throughput screening pipelines where batch-to-batch consistency is non-negotiable. MEMS-compatible foundry bottlenecks in Taiwan and South Korea constrain supply expansion.
- Polymer-Based Chips:Roll-to-roll manufacturing enables cost scaling for mid-throughput applications, displacing glass in price-sensitive procurement segments.
- Glass Chips:Borosilicate substrates retain dominance in analytical applications requiring optical transparency and solvent resistance.
Microfluidic chips handle the majority of throughput; silicon chips are expanding most quickly on share.
End User:
Procurement authority concentrates differently across customer types, with pharmaceutical buyers commanding dedicated field support while academic institutes drive exploratory specification development.
- Pharmaceutical Companies:These organizations operate centralized genomics facilities with validated workflows and ISO 13485-mandated supplier qualification. Contract research organizations in the United States are building dedicated separation pipelines around microfluidic platforms to compress compound screening timelines. Their procurement contracts increasingly unbundle after-sales service as a separate negotiable term.
- Academic Research Institutes:Exploratory applications dominate, with researchers prioritizing protocol adaptability over regulatory certification. Institutes in Germany and the United States sustain the highest shipment volumes despite fragmented purchasing authority across individual principal investigators. Surface chemistry customization requests extend vendor sales cycles but build long-term specification influence.
- Biotechnology Firms:Mid-scale operations balance throughput needs with capital constraints, often piloting silicon devices before pharmaceutical-scale deployment.
- Clinical Laboratories:ISO 13485 certification is a de facto market-access requirement, with FDA guidance on liquid biopsy quality controls reshaping validation priorities for integrated separation modules.
Academic institutes sustain the highest shipment volumes; clinical laboratories are gaining share fastest as companion diagnostic frameworks mature.
Technology:
Surface chemistry selection determines regulatory pathway complexity, with affinity methods facing stricter analytical validation than size-based separation.
- Affinity Chromatography:Biomolecular recognition enables highly selective nucleic acid capture, though ligand stability complicates shelf-life claims. Oncology workflows in the United States are driving qualification of chip-based affinity modules for circulating tumor DNA isolation. REACH restrictions on perfluorinated hydrophobic coatings are forcing European manufacturers into accelerated reformulation timelines.
- Size-Exclusion Chromatography:Passive separation by hydrodynamic radius eliminates binding chemistry variability, simplifying validation documentation. Quality control laboratories in pharmaceutical central facilities favor this approach for plasmid and mRNA fragment analysis. Channel fouling susceptibility limits reuse cycles in high-duty applications.
- Ion-Exchange Chromatography:Charge-based separation dominates nucleic acid purification from complex biological matrices.
- Reverse Phase Chromatography:Hydrophobic interaction methods serve metabolite and modified nucleotide applications where polarity differentiation is critical.
Affinity chromatography commands the deepest R&D investment; size-exclusion methods are climbing the fastest as regulatory validation burdens intensify.
Application:
Workflow integration requirements vary sharply, with gene sequencing demanding upstream compatibility while drug development emphasizes throughput scalability.
- Gene Sequencing:Sample preparation modules must interface with next-generation sequencing platforms from Illumina and Thermo Fisher. Integrated separation chips are reducing handling steps in clinical laboratories pursuing FDA-recognized test development. The convergence of upstream purification with sequencing workflows is compressing total turnaround time.
- Drug Development:High-throughput screening of nucleic acid therapeutics requires batch processing consistency across multi-well formats. Pharmaceutical central laboratories in the United States are standardizing on silicon-based devices for oligonucleotide purity verification. Compound library scale-out is driving demand for denser channel array configurations.
- Protein Purification:Chromatography chips for nucleic acid-contaminated protein samples serve bioprocess analytical development.
- Metabolomics:Small-molecule separation applications leverage reverse phase surface chemistries with distinct solvent compatibility requirements.
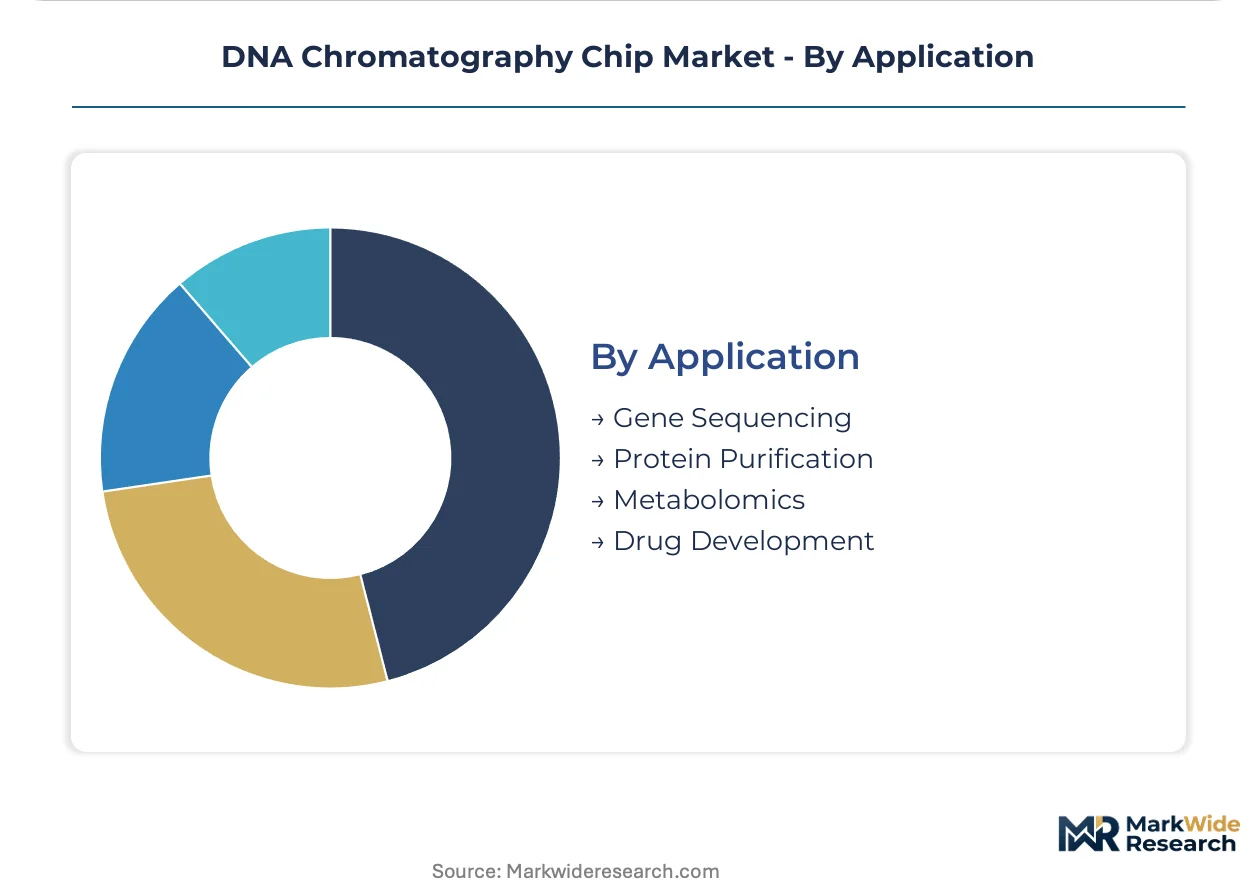
Gene sequencing anchors current procurement volume; drug development applications are expanding most rapidly as nucleic acid therapeutics pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while German buyers extract volume discounts through consolidated procurement. Taiwan and South Korea control foundry capacity for silicon devices. Academic demand in India and China reshapes mid-tier product specifications.
United States
FDA companion diagnostic guidance accelerates validation timelines for liquid biopsy applications. Academic medical centers in Boston and San Diego are building integrated genomics pipelines around microfluidic separation platforms. Pharmaceutical central laboratories in New Jersey and North Carolina command dedicated field application scientist coverage as standard contractual terms.
Germany
REACH restrictions on perfluorinated compounds force accelerated reformulation of hydrophobic surface coatings. ECHA substance authorization timelines compress R&D planning horizons for European manufacturers. Industrial clusters in Munich and Heidelberg anchor glass microfluidics development with in-house coating capabilities.
China
NMPA regulatory harmonization with international standards reshapes validation documentation for imported devices. Domestic biotechnology firms in Shanghai and Suzhou are piloting silicon-based devices before pharmaceutical-scale deployment. Yangtze River Delta manufacturing hubs are internalizing polymer substrate production to reduce import dependency.
India
CDSCO streamlined approval pathways for research-use-only instruments attract exploratory procurement from academic institutes. Decentralized diagnostic networks in Maharashtra and Karnataka present underpenetrated demand for cartridge-integrated separation chips. Bengaluru-based contract research organizations are building dedicated genomics pipelines for high-throughput screening.
South Korea
MFDS quality management system requirements align with ISO 13485 certification standards for clinical laboratory access. MEMS-compatible foundry capacity in Gyeonggi Province constrains supply expansion for silicon-based devices. Seoul Capital Area biotechnology firms balance throughput needs with capital constraints through mid-scale pilot programs.
DNA Chromatography Chip Market Competitive Landscape
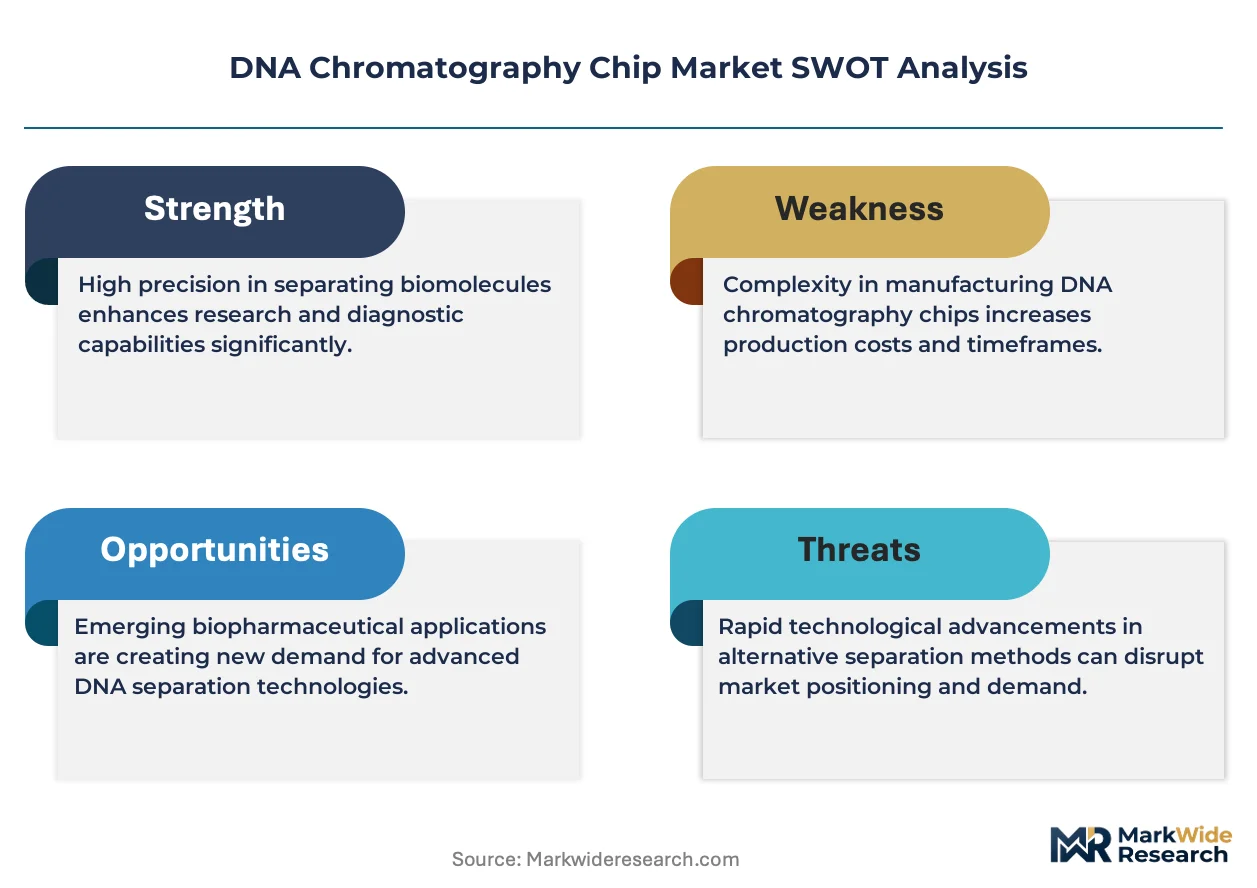
Concentration sits with vertically integrated life sciences conglomerates that control substrate fabrication and surface chemistry development. The vendor base separates into three strategic archetypes: captive foundry operators securing MEMS-compatible capacity, fabless design specialists partnering for semiconductor fabrication, and glass microfluidics fabricators with in-house borosilicate processing. Dominant competitive moves include foundry partnership negotiations to bypass capacity bottlenecks and accelerated ISO 13485 certification to access clinical laboratory procurement channels.
Among diversified life sciences conglomerates, Thermo Fisher Scientific and Agilent Technologies exemplify the integrated archetype through captive control of silicon and glass substrate production respectively. Illumina occupies a position extending sequencing ecosystems into upstream sample preparation. Arrayit Corporation and PerkinElmer sit within the specialist tier serving mid-throughput applications with modular device architectures.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| Illumina |
| Arrayit Corporation |
| PerkinElmer |
| Macrogen |
| CapitalBio Corporation |
| Revvity |
| Bio-Rad Laboratories |
| Others |
Pricing and Supply Chain Analysis
ISO 13485 certification gates both supplier qualification and price differentiation simultaneously, creating a bifurcated market where certified manufacturers command premium positioning in clinical laboratory procurement while uncertified competitors compete on unit economics in research-use-only segments. This regulatory threshold concentrates pricing power with vertically integrated incumbents who have absorbed compliance costs, while forcing price-sensitive buyers toward polymer-based alternatives that navigate simpler research pathways.
Pricing Analysis
The customization-premium spread separates standard microfluidic chips from configured-to-order silicon devices with application-specific surface chemistries. Pricing stratifies across premium, standard, and economy tiers, with pharmaceutical central laboratories showing lowest price sensitivity due to validated workflow dependencies, while academic institutes drive cost compression through fragmented purchasing authority and protocol flexibility demands. Cost compression in the mid-tier polymer segment is intensifying because roll-to-roll manufacturing scale is displacing legacy glass fabrication.
Supply Chain Analysis
MEMS-compatible foundry capacity in Taiwan and South Korea constitutes the critical chokepoint constraining silicon-based device expansion. Raw material dependencies center on high-purity borosilicate glass, photoresist polymers, and perfluorinated hydrophobic coatings facing REACH authorization pressures. Single-source vulnerability runs through concentrated semiconductor fabrication, while distribution feeds from captive production facilities through direct sales to pharmaceutical central laboratories and academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is positioned for cyclical recovery as FDA companion diagnostic guidance accelerates validation timelines and compresses product replacement cycles in oncology workflows.
For Market Incumbents: Fortify captive foundry relationships or secure long-term MEMS-compatible capacity allocations to defend against fabless design specialists facing fabrication bottlenecks. Deepen in-house surface chemistry development to maintain formulation control as REACH restrictions on perfluorinated compounds force competitor reformulation delays. For New Entrants and Emerging Players: ISO 13485 certification fast-track creates first-mover access to clinical laboratory procurement channels currently dominated by entrenched suppliers. Target decentralized diagnostic networks in India with cartridge-integrated separation chips, leveraging CDSCO streamlined approval pathways for research-use-only instruments to establish specification influence before pharmaceutical-scale deployment. For Investors and Strategic Acquirers: FDA liquid biopsy guidance reshapes the acquisition landscape by elevating chip-based separation module developers with validated oncology workflows. Long-term viability favors targets combining semiconductor process knowledge with biochemistry surface functionalization capabilities. Watch for MEMS foundry capacity expansion announcements as the inflection signal indicating supply constraint easing.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Fast-Track | Accelerated quality management adoption unlocks clinical laboratory procurement channels previously blocked to uncertified suppliers. |
| Foundry Partnership Negotiation | Secured MEMS-compatible fabrication capacity insulates against Taiwan and South Korea supply concentration risks. |
| Surface Chemistry Internalization | In-house coating capabilities preserve formulation control as REACH restrictions force competitor reformulation cycles. |
| Sequencing Workflow Integration | Upstream separation module convergence with Illumina and Thermo Fisher platforms reduces customer handling steps. |
| Point-of-Care Geographic Expansion | Cartridge-integrated chip deployment in Maharashtra and Karnataka diagnostic networks captures underpenetrated demand. |
Research Methodology
Initial hypotheses were tested against primary input from biomedical engineers at academic medical centers, regulatory affairs leads at device manufacturers, pharmaceutical procurement managers, and GPO contracts managers, then refined through secondary validation against FDA 510(k) filings, ECHA substance authorization databases, ISO 13485 certification registries, and hospital procurement databases. Bottom-up shipment estimates triangulated with top-down market sizing across product type, end user, technology, and application dimensions.
Variance decomposition anchored the analytical framework across the projection horizon, with segmentation modeling spanning substrate material tiers, regulatory pathway clusters, and workflow integration depth. CAGRs were derived from fitted growth curves calibrated to pharmaceutical R&D expenditure patterns, academic research funding trajectories, and companion diagnostic pipeline maturation timelines.
Decision-makers should treat outputs as directional under stable FDA guidance evolution and intact semiconductor fabrication capacity assumptions; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as REACH substance authorization timelines and MEMS foundry expansion announcements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Leadframes Market
Semiconductor Devices
Taiwan Discrete Semiconductor Market
Semiconductor Devices
Pcie Switches Market
Semiconductor Devices
Chip Crusher Market
Semiconductor Devices
Field Programmable Gate Array (FPGA) Market
Semiconductor Devices
Rad-Hard Mosfets Market
Semiconductor Devices
Fin Field Effect Transistor (Finfet) Market
Semiconductor Devices
Japan International CEP Market
Semiconductor Devices
Micro and Nano PLC Market
Semiconductor Devices
Global Through Silicon via (TSV) Technology Market
Semiconductor Devices
Global Semiconductor Device Market
Semiconductor Devices
Europe Printed Circuit Board (PCB) Market
Semiconductor Devices
Global Power MOSFET Market
Semiconductor Devices
Advanced HDI PCB Market
Semiconductor Devices
Reachers Market
Semiconductor Devices
Plastic Transistors Market