
 Printing Machinery Market | 2026-2036
Printing Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Printing Machinery Market Analysis
High-definition, servo-driven specification tiers is rotating demand away from mechanical legacy platforms toward electronically controlled presses. Heidelberger Druckmaschinen AG leverages its long-sheet perfecting expertise to anchor premium commercial installations across Central Europe. HP Inc. competes through continuous feed inkjet architectures that dominate high-volume transactional and direct-mail environments. Canon Inc. differentiates via integrated workflow software that extends hardware utility into color-managed production ecosystems.
Printing machinery comprises engineered systems that transfer ink or toner substrates through controlled impression, drying, and finishing sequences, typically operating at speeds from 3,000 to 20,000 sheets per hour depending on format and drying technology. These systems serve industrial and commercial purposes spanning replication of text, imagery, and functional coatings onto paper, film, textile, and rigid substrates. Offset printers retain the largest installed base and aftermarket revenue pool, though digital printers represent the fastest-expanding segment as run lengths contract and versioning requirements intensify. UV printing technology commands premium positioning due to instant polymerization capabilities that enable direct-to-substrate applications on non-porous materials.
The EPA regulates volatile organic compound emissions from heatset web offset operations, compelling dryer retrofits and thermal oxidizer investments that alter total cost of ownership calculations. CE marking under the EU Machinery Directive and REACH substance restrictions jointly shape equipment import eligibility and ink chemistry formulations for European deployments. FDA food-contact notification requirements for printed packaging materials influence press specification and ink selection for North American food and beverage converters. Stakeholders must monitor how dual regulatory pressure on emissions and material safety reshapes capital allocation between analog replacement and digital migration strategies.
Market Dynamics
The transition from mechanical to electronically controlled press architectures is compressing replacement cycles and rewiring supplier-buyer relationships across commercial and packaging print.
Growth Catalysts
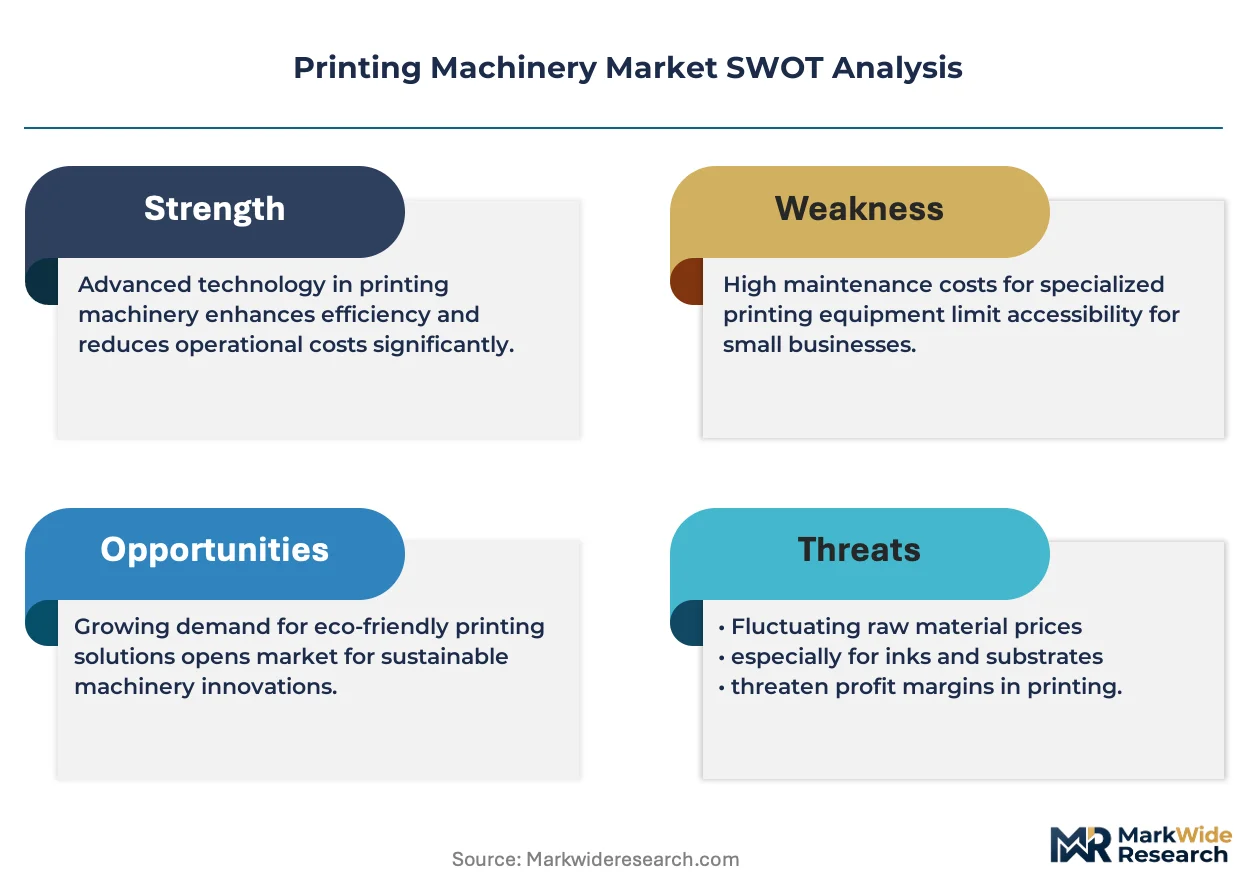
- Short-run packaging demand:E-commerce fulfillment centers and craft beverage brands in China are contracting run lengths below 5,000 impressions, pulling investment toward digital sheetfed configurations.
- REACH substance restrictions:ECHA mandates on photoinitiator migration are accelerating certified UV ink formulations and press ventilation upgrades across European food-contact converters.
- Servo-driven impression control:Closed-loop register systems are cutting makeready waste by eliminating mechanical gripper bars, justifying premium tier positioning in high-value security print.
Market Restraints
- Copper and rare-earth magnet costs:Servo motor assemblies depend on neodymium supply concentrated in Chinese refining operations, exposing OEMs to input price volatility.
- Heatset dryer retrofits:EPA volatile organic compound rules for web offset operations impose thermal oxidizer capital burdens that extend payback periods on legacy equipment.
- Substrate limitation:Electron beam curing remains incompatible with heat-sensitive films, constraining penetration in thin-gauge flexible packaging segments.
Strategic Opportunities
- Indian label conversion:Domestic pharmaceutical serialization mandates are creating installed base gaps that digital press vendors can fill ahead of local manufacturing scale-up.
- Industrial textile decoration:Direct-to-fabric inkjet is penetrating sportswear and home furnishing verticals previously served by rotary screen, opening equipment categories outside traditional print.
- CE marking and CSRD alignment:EU machinery directive compliance combined with corporate sustainability reporting requirements is creating bundled certification services that extend vendor relationships beyond hardware sale.
Industry Challenges
- Mechatronics technician scarcity:Convergence of mechanical, electronic, and color science competencies exceeds vocational training pipeline output in mature manufacturing regions.
- FDA food-contact notification timelines:Ink and coating approvals for direct food contact extend 18-24 months, compressing product launch windows for North American packaging converters.
- Legacy prepress integration:Proprietary digital front-end architectures resist standardization, forcing custom workflow engineering for hybrid offset-digital operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printing Machinery Market |
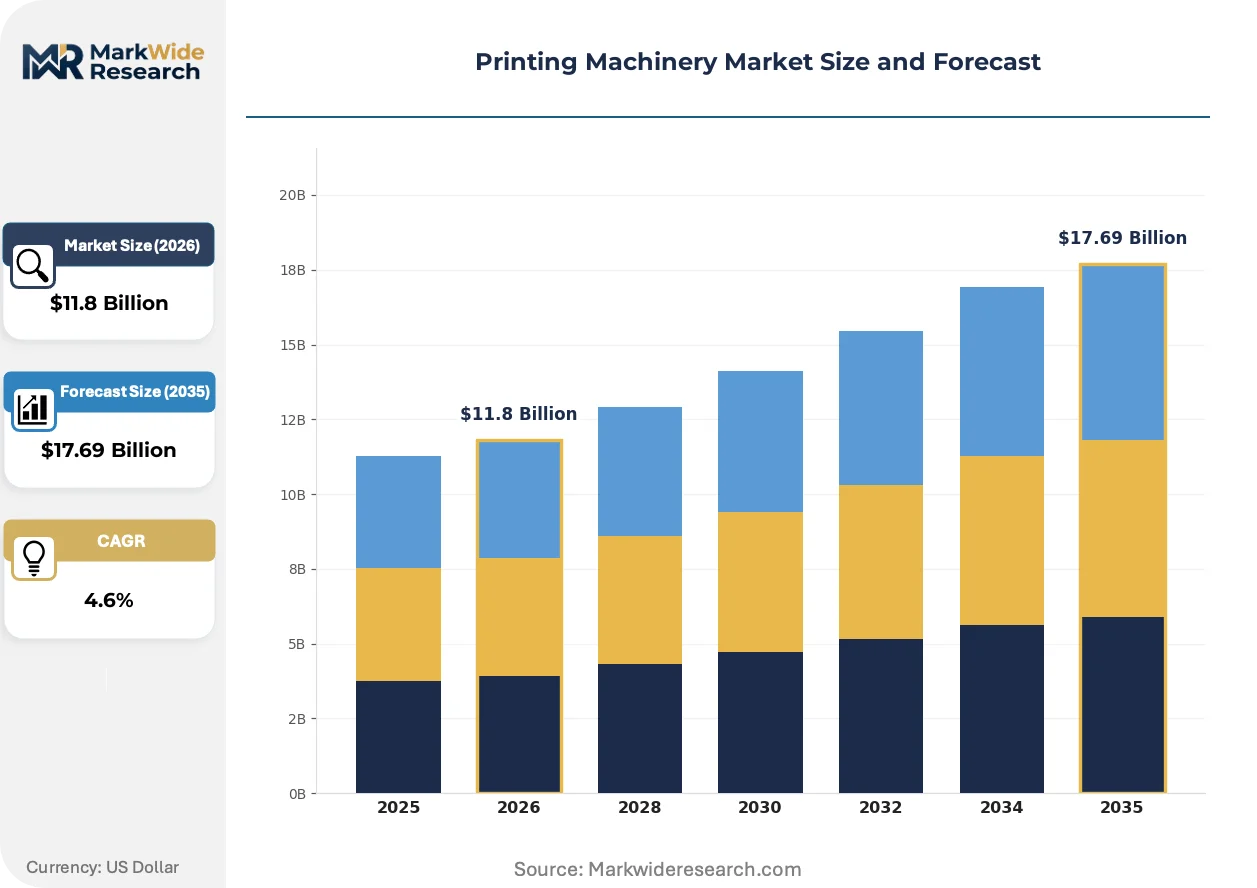
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Printers, Flexographic Printers,Offset Printers, Gravure Printers Application: Packaging, Commercial Printing, Labeling, Textile Printing Technology: Inkjet Technology, Toner Technology, Eco-Solvent Technology, UV Printing Technology End User: Manufacturers, Publishers, Retailers, Advertisers |
| Companies Covered | Heidelberger Druckmaschinen AG, Canon Inc., Xerox Holdings Corporation, HP Inc., Koenig & Bauer, Ricoh Company Ltd., Bobst Group SA, Seiko Epson Corporation, Komori Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printing Machinery Market Emerging Trajectories
Hardware differentiation is flattening as software-defined workflow control and ink chemistry certification become the primary axes of vendor competition.
Single-pass inkjet arrays are supplanting scanning-head architectures in corrugated post-print applications. Box plants serving grocery and appliance fulfillment networks are adopting these systems to match flexographic speeds without plate costs. The technology is supplanting traditional preprint models by enabling late-stage graphic versioning directly at the converting line.
EPA enforcement of Maximum Achievable Control Technology standards for heatset web offset dryers is tightening emission thresholds. Converter operations in California and Texas are installing regenerative thermal oxidizers ahead of inspection cycles. Mid-volume commercial printers in these states are accelerating digital migration to bypass compliance capital entirely.
Converters are unbundling maintenance contracts from equipment finance, treating service as a competitive procurement category rather than captive OEM revenue. Large packaging groups in Germany and Japan are awarding multi-vendor service agreements to independent technical service providers. This pattern is most visible in folded carton operations where uptime guarantees override brand loyalty in supplier selection.
Printing Machinery Market Segmentation
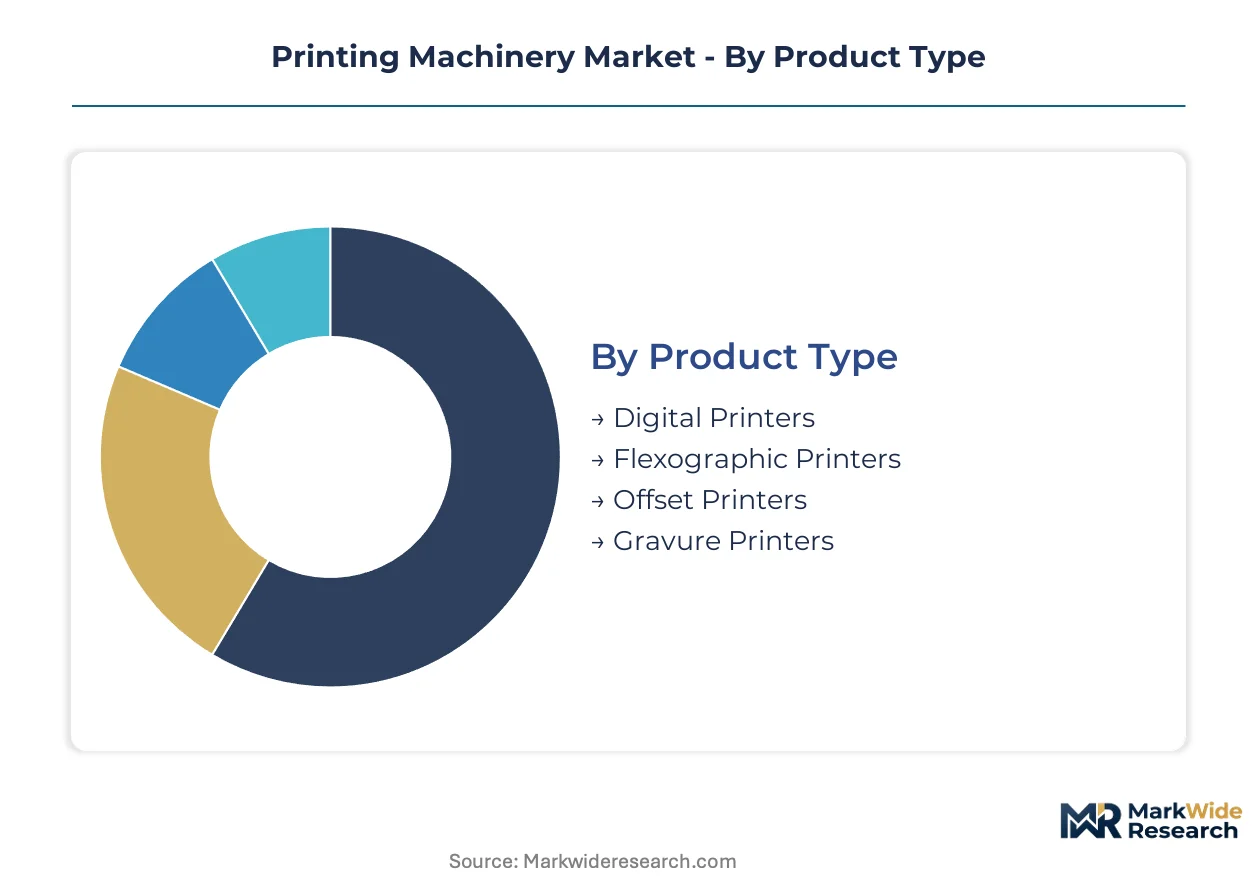
Segmentation in printing machinery reveals how regulatory pressure and substrate requirements split capital allocation across technology tiers. Buyers select equipment based on emission compliance, food-contact certification, and run-length economics rather than speed alone.
Product Type:
REACH substance restrictions and FDA food-contact rules create divergent equipment specifications across analog and digital platforms.
- Digital Printers:Electrophotographic and inkjet architectures enable impression-by-impression variable data without plate costs. Pharmaceutical serialization mandates in India and craft beverage versioning in China are pulling investment toward sheetfed configurations for runs below 5,000 impressions.
- Offset Printers:Lithographic transfer systems using aluminum plates and dampening solutions retain the largest installed base and aftermarket revenue pool. Heatset web operations face EPA volatile organic compound enforcement in California and Texas, forcing thermal oxidizer retrofits that extend payback periods.
- Flexographic Printers:Rotary relief plate systems dominate corrugated post-print and flexible packaging with fast-drying solvent or water-based inks.
- Gravure Printers:Intaglio cylinder engraving delivers high-volume, consistent reproduction for publication and decorative laminates.
Offset printers handle the majority of throughput; digital printers are expanding most quickly on share.
Application:
End-use concentration varies by regional manufacturing specialization and e-commerce fulfillment density.
- Packaging:Folding carton, corrugated, and flexible film converting equipment serves food, beverage, and appliance fulfillment networks. Single-pass inkjet arrays are supplanting flexographic preprint models by enabling late-stage graphic versioning directly at converting lines in China and Germany.
- Commercial Printing:Marketing collateral, direct mail, and transactional document production. HP Inc. and Canon Inc. compete through continuous feed inkjet and integrated workflow software that extends hardware utility into color-managed production ecosystems.
- Labeling:Pressure-sensitive and shrink-sleeve decoration for pharmaceuticals and consumer goods. Domestic pharmaceutical serialization mandates in India create installed base gaps that digital press vendors are filling.
- Textile Printing:Direct-to-fabric inkjet penetration in sportswear and home furnishing verticals previously served by rotary screen, opening equipment categories outside traditional print.
Packaging commands the largest equipment revenue pool; textile printing is climbing the fastest as ink chemistry advances.
Technology:
Curing mechanism and ink vehicle selection determine substrate compatibility and regulatory compliance pathway.
- UV Printing Technology:Photoinitiator-driven polymerization enables instant drying on non-porous films, metals, and rigid plastics. ECHA mandates on photoinitiator migration are accelerating certified low-migration formulations and press ventilation upgrades across European food-contact converters.
- Inkjet Technology:Piezoelectric or thermal drop-on-demand deposition of aqueous, solvent, or UV-curable fluids. Single-pass arrays in corrugated post-print are matching flexographic speeds without plate costs at box plants serving grocery networks.
- Toner Technology:Electrophotographic fusing of dry polymer particles onto paper and synthetic substrates.
- Eco-Solvent Technology:Mild-solvent ink vehicles for outdoor signage and vehicle wraps with reduced volatile organic compound profiles.
UV printing technology holds premium positioning; inkjet technology is gaining share fastest as run lengths contract.
End User:
Procurement authority and maintenance contract structures differ by buyer scale and vertical integration.
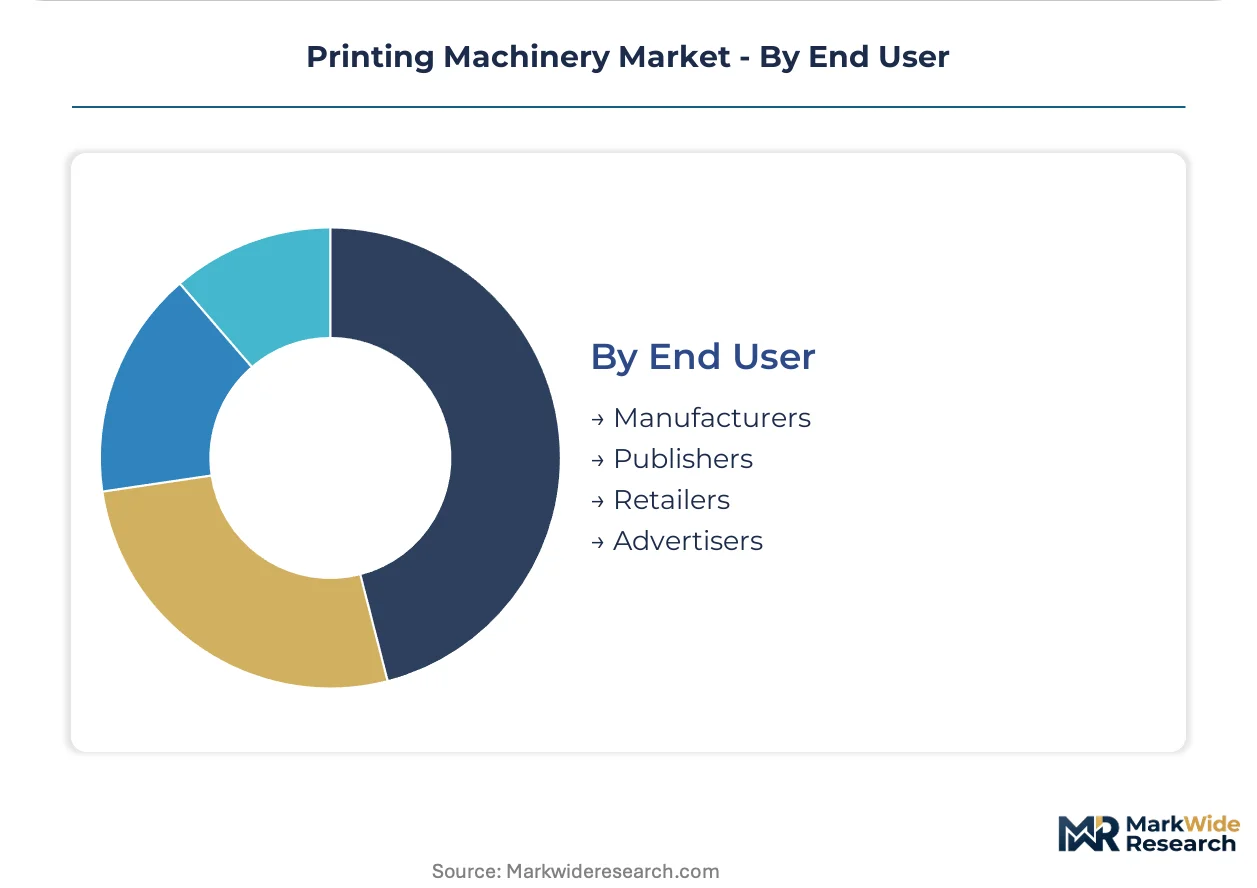
- Manufacturers:Packaging converters and industrial decorators operating captive print capacity. Large groups in Germany and Japan are unbundling maintenance contracts from equipment finance, awarding multi-vendor service agreements to independent technical service providers.
- Publishers:Book, magazine, and directory producers managing long-run web offset or short-run digital workflows. Heidelberger Druckmaschinen AG anchors premium commercial installations across Central Europe with long-sheet perfecting expertise.
- Retailers:Private label and promotional material production for in-store and e-commerce channels.
- Advertisers:Agencies and brand owners managing versioning for personalized direct mail and regional campaign customization.
Manufacturers represent the dominant equipment purchaser segment; advertisers are expanding fastest as versioning requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese equipment fabricators dominate servo motor assembly supply chains, concentrating neodymium refining and rare-earth magnet production in domestic operations. This concentration shapes cost structures for electronically controlled presses worldwide and influences OEM sourcing strategies across all major demand centers.
China
Domestic label and flexible packaging output expansion drives capital deployment toward high-speed digital configurations. MIIT industrial upgrading directives accelerate replacement of mechanical legacy platforms in coastal manufacturing zones. The Yangtze River Delta cluster around Shanghai hosts the densest concentration of packaging converter upgrades to servo-driven presses.
Germany
CE marking compliance under the EU Machinery Directive and REACH substance restrictions shape import specifications for food-contact converters. ECHA mandates on photoinitiator migration accelerate certified UV ink formulations and press ventilation upgrades. The Baden-Württemberg industrial corridor anchors premium commercial installations with long-sheet perfecting expertise.
United States
EPA Maximum Achievable Control Technology enforcement tightens emission thresholds for heatset web offset dryers in California and Texas. FDA food-contact notification requirements for printed packaging materials extend 18-24 month approval timelines. The Pacific Northwest and Midwest manufacturing belts see accelerating digital migration to bypass thermal oxidizer capital burdens.
India
Domestic pharmaceutical serialization mandates create installed base gaps that digital press vendors target ahead of local manufacturing scale-up. CDSCO regulatory alignment with international traceability standards pressures label converters toward compliant equipment. The Maharashtra and Gujarat industrial corridors concentrate pharmaceutical packaging demand and associated machinery procurement.
Japan
METI support for industrial automation integrates closed-loop register systems into security print and high-value commercial operations. JIS standards certification requirements influence equipment specification for export-oriented converters. The Kanto and Kansai manufacturing clusters host unbundled maintenance contract awards to independent technical service providers.
Printing Machinery Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the printing machinery sector. The market structures around a consolidated premium tier of long-tenured European and Japanese manufacturers alongside fragmented mid-market specialists. Strategic archetypes include heritage perfecting press builders, continuous feed inkjet architects, and integrated workflow software providers. Dominant competitive moves span geographic licensing partnerships and vertical integration into certified ink chemistry supply.
Within the heritage European tier, Heidelberger Druckmaschinen AG and Koenig & Bauer occupy positions anchored in long-sheet perfecting expertise and rotary relief plate systems respectively. Among diversified electronics conglomerates, Canon Inc. and HP Inc. exemplify contrasting pathways into production ecosystems through integrated software control versus continuous feed architectures. These named entities represent archetype poles rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Heidelberger Druckmaschinen AG |
| Canon Inc. |
| Xerox Holdings Corporation |
| HP Inc. |
| Koenig & Bauer |
| Ricoh Company Ltd. |
| Bobst Group SA |
| Seiko Epson Corporation |
| Komori Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements for neodymium magnet supply lock in servo motor cost visibility for OEMs while insulating against Chinese refining volatility. These contracts tie digital press pricing to rare-earth input floors, compressing margin flexibility for electronically controlled architectures.
Pricing Analysis
REACH substance restrictions dictate the pricing tier structure across European deployments, separating certified low-migration UV configurations from standard inkjet platforms. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking compliance depth, FDA food-contact certification status, and after-sales service bundling. Cost compression in mid-tier offset retrofits is intensifying because thermal oxidizer capital burdens extend payback periods. Mid-volume commercial printers exhibit highest price sensitivity, while security print and pharmaceutical serialization buyers prioritize uptime guarantees over acquisition cost.
Supply Chain Analysis
China anchors rare-earth magnet refining and servo motor assembly, with Germany and Japan hosting precision mechanical component fabrication. Neodymium, copper windings, and piezoelectric printhead ceramics feed from concentrated upstream nodes. Single-source vulnerability in Chinese rare-earth processing exposes OEMs to export restriction risk. Distribution runs through direct OEM channels for large packaging groups, while independent technical service providers capture unbundled maintenance procurement in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital inkjet substitution threatens legacy offset installed bases as run lengths contract below mechanical break-even thresholds. Incumbents must reposition around regulatory compliance bundling and workflow software retention to defend replacement revenue pools.
For Market Incumbents: Consolidate aftermarket service relationships through multi-year uptime guarantees that resist unbundling pressure from independent technical providers. Deepen backward integration into certified UV ink chemistry supply to capture recurring revenue streams as hardware differentiation flattens. Anchor positioning in pharmaceutical serialization and security print verticals where FDA and ECHA compliance requirements sustain premium pricing.
For New Entrants and Emerging Players: Differentiate on single-pass inkjet architectures for corrugated post-print applications where flexographic preprint models remain vulnerable to late-stage versioning demand. Target Indian label conversion ahead of domestic manufacturing scale-up, exploiting CDSCO regulatory alignment gaps. Pursue direct-to-fabric textile printing in sportswear verticals previously served by rotary screen, leveraging aqueous ink chemistry advances.
For Investors and Strategic Acquirers: Workflow-integrated software specialists with captive color management ecosystems present acquisition targets as hardware margins compress. Long-term viability hinges on vendor ability to extend relationships beyond equipment sale into recurring certification and maintenance revenue. Monitor EPA enforcement intensity in California and Texas as inflection indicator for digital migration velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Certified Ink Chemistry Backward Integration | Captures recurring revenue from ECHA-compliant UV formulation supply. |
| Single-Pass Inkjet Platform Launch | Matches flexographic speeds without plate costs at corrugated box plants. |
| Multi-Vendor Service Agreement Partnership | Responds to German and Japanese packaging group procurement unbundling. |
| Pharmaceutical Serialization Compliance Bundle | Addresses CDSCO mandates creating installed base gaps in India. |
| Direct-to-Fabric Textile Equipment Expansion | Penetrates sportswear verticals previously served by rotary screen. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with packaging converter procurement directors, OEM product managers, aftermarket service heads, and regulatory compliance officers at food-contact material producers. Secondary validation drew from EPA enforcement databases, ECHA substance restriction updates, FDA food-contact notification filings, and customs trade records for printing machinery imports. Bottom-up equipment shipment tracking and top-down macroeconomic absorption modeling were triangulated against regional manufacturing output indices.
Across the analysis window, projections integrate technology substitution curves, regulatory compliance cost burdens, and run-length economics by segment. Modeled dimensions span digital versus analog platform type, packaging versus commercial end-use, UV versus aqueous ink chemistry, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and net new capacity absorption rates, with servo motor cost trajectories and thermal oxidizer retrofit penetration serving as key forecast inputs.
Material uncertainties — rare-earth export restrictions, EPA MACT enforcement intensity, FDA notification timeline variability — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory stability and substitution elasticity. Recalibration cycles align with material shifts in emission compliance thresholds and photoinitiator migration standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Large Character Printers Market
Printing Technology
RFID Printer Market
Printing Technology
Automated Document Inserter (ADI) Market
Printing Technology
Commercial Printer Market
Printing Technology
Professional Printers Market
Printing Technology
Global Barcode Printer Market
Printing Technology
Oceania Digital Textile Printer Market
Printing Technology
Digital Printing Market
Printing Technology
Cloud Print Market
Printing Technology
Retail Printers Market
Printing Technology
Card Printers Market
Printing Technology
ID Card Printers Market
Printing Technology
Photo Printing Market
Printing Technology
Digital Pattern Generator Market
Printing Technology
Print on Demand Market
Printing Technology
Dye-Sublimation Printing Machines Market