
 Point of Sale (Pos) Printers Market | 2026-2036
Point of Sale (Pos) Printers Market Size, Share, and Industry Trends Forecast 2026-2036
Point of Sale (Pos) Printers Market Analytics
Quick-service restaurant chains is recalibrating deployment patterns for Point of Sale printers, shifting from front-counter units to kitchen automation and drive-thru order confirmation systems. Epson Corporation leverages its precision micro-piezo technology to sustain dominance in high-speed thermal receipt segments. Star Micronics Co., Ltd. anchors its competitive position through compact form-factor designs tailored for space-constrained hospitality environments. Zebra Technologies Corporation specializes in ruggedized mobile printing solutions that extend operational flexibility into warehouse-adjacent retail floors.
Point of Sale printers are electro-mechanical devices that generate physical transaction records through thermal, impact, inkjet, or dot matrix mechanisms, typically achieving print speeds of 150-350 millimeters per second in thermal configurations and operating across voltage ranges of 100-240V for universal deployment. Their primary commercial purpose centers on creating auditable, customer-facing documentation of financial exchanges while integrating with inventory management and customer relationship systems. Thermal technology occupies the dominant volume position due to silent operation and minimal moving parts, though impact mechanisms retain structural relevance in kitchen environments where heat and grease degrade thermal media. Bluetooth connectivity is gaining fastest traction among portable installation types, particularly in pop-up retail and curbside pickup workflows where cable infrastructure proves impractical.
FCC certification governs electromagnetic emissions for printers deployed across US retail networks, while CE marking mandates compliance with EU safety and interoperability standards for European installations. India's BIS certification requirements for electronic goods create procedural barriers that filter out uncertified imports, shaping competitive access patterns. Stakeholders must monitor evolving energy efficiency benchmarks from multiple regulators and assess whether in-house production of print mechanisms or continued reliance on specialized component suppliers offers superior cost control as connectivity integration deepens.
Market Dynamics
Quick-service restaurant chains are recalibrating deployment patterns, shifting from front-counter units to kitchen automation and drive-thru order confirmation systems as labor costs and throughput pressure intensify.
Growth Catalysts
- EU Green Deal ecodesign requirements:Manufacturers are accelerating development of lower-energy thermal mechanisms to meet tightening European efficiency benchmarks.
- India's tier-two cities:Modern trade formats penetrating beyond metros are generating concentrated demand for compact receipt printing infrastructure.
- Bluetooth connectivity protocols:Pop-up retail and curbside pickup workflows are driving fastest traction for portable installation types where cable infrastructure proves impractical.
Market Restraints
- Thermal paper cost volatility:Bisphenol-A coating regulations and specialty chemical supply constraints are compressing margins on consumables.
- Component supplier concentration:Precision thermal printhead manufacturing concentrates in East Asian specialist foundries, creating single-source vulnerability.
- Impact mechanism substitution ceiling:Kitchen environments with heat and grease degrade thermal media, locking in legacy dot-matrix demand without upgrade pathway.
Strategic Opportunities
- Cloud-native POS integration:API-first printer architectures are opening white space in software-defined retail ecosystems.
- India BIS certification barriers:Procedural filtering of uncertified imports creates protected runway for compliant domestic assembly operations.
- Warehouse-adjacent retail floors:Ruggedized mobile printing solutions extend operational flexibility into hybrid fulfillment environments.
Industry Challenges
- FCC and CE multi-jurisdiction certification:Parallel electromagnetic emissions and safety testing timelines extend product launch cycles by four to six months.
- Legacy ERP integration complexity:Older hospitality management systems lack native drivers for modern Ethernet-connected printers, forcing middleware development.
- Thermal printhead field replacement skill gaps:Technician certification for precision mechanism servicing lags behind installed base expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Point of Sale (Pos) Printers Market |
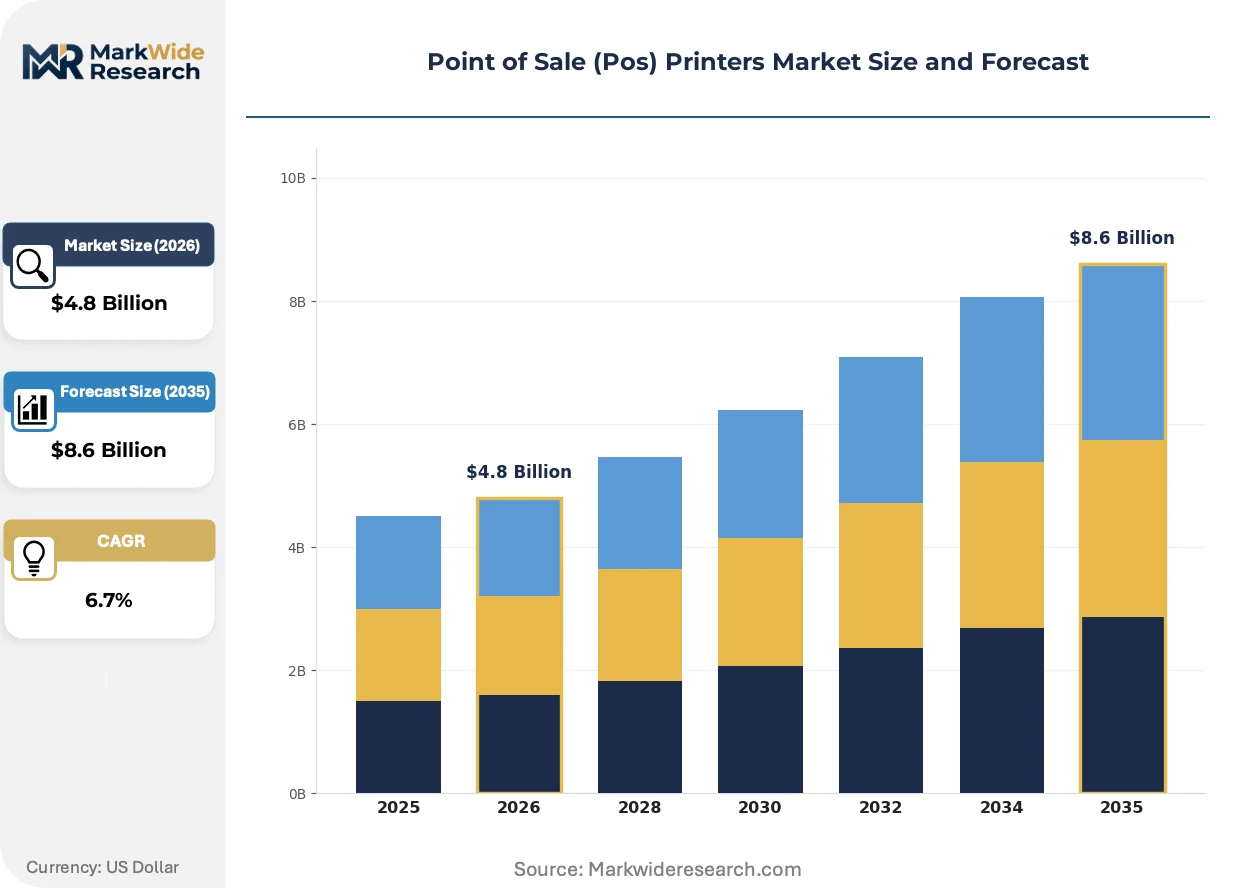
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal, Impact, Inkjet, Dot Matrix End User: Retail, Hospitality, Transportation, Healthcare Connectivity: USB, Bluetooth, Ethernet, Wi-Fi Installation Type: Tabletop, Wall-Mounted, Portable, Integrated |
| Companies Covered | Epson Corporation, Star Micronics Co., Ltd., Zebra Technologies Corporation, Bixolon Co., Ltd., Honeywell International Inc., Citizen Systems, HP Development Company, NCR Corporation, Toshiba Tec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Point of Sale (Pos) Printers Market Evolving Landscape
Connectivity architecture and energy efficiency mandates are rewriting procurement criteria, compressing the viable technology set toward cloud-integrated, low-power thermal platforms.
Cloud-native firmware architectures are integrating directly with SaaS POS platforms, enabling real-time diagnostics and remote configuration management. Mid-market hospitality chains are adopting these capabilities fastest, replacing on-premise server dependencies. This convergence is integrating printer hardware into recurring-revenue software ecosystems, compressing standalone equipment margins.
EU Green Deal ecodesign requirements are forcing redesign of thermal heating elements and standby power circuits. Manufacturers serving European quick-service restaurant chains must recertify entire product lines. Kitchen printer segments face particular pressure, as heat-resistant specifications conflict with efficiency targets.
Curbside and pop-up retail formats are compressing installation timelines from weeks to hours. Bluetooth-enabled portable units are displacing cabled infrastructure in temporary locations across North American and European urban cores. This behavioral shift is visible most acutely in seasonal hospitality operations and festival retail circuits.
Point of Sale (Pos) Printers Market Segmentation
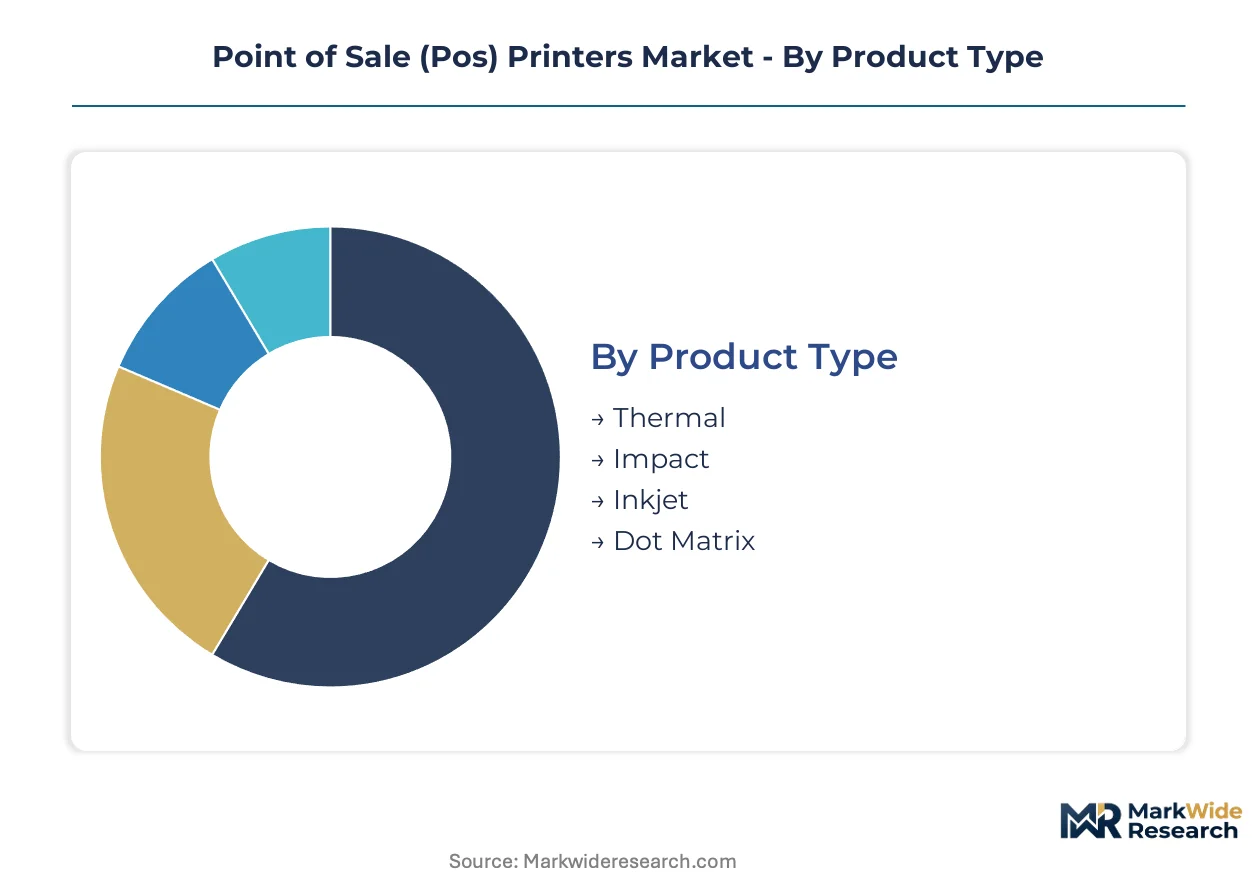
Point of Sale printer procurement decisions split sharply between cost-optimized volume plays and premium-positioned specialized configurations. Understanding where each segment concentrates demand reveals which technology investments will capture replacement cycles versus greenfield expansion.
Product Type:
Thermal mechanisms dominate unit economics through silent operation and minimal maintenance, while impact and dot matrix retain defensive positions in hostile environments where consumable durability outweighs efficiency gains.
- Thermal:Solid-state heating elements activate thermal-coated paper without ink cartridges or impact pins, achieving 150-350 millimeters per second print speeds. Quick-service restaurant chains across India and Southeast Asia are standardizing on thermal for front-counter deployments where customer noise sensitivity and maintenance minimization drive specifications. EU Green Deal ecodesign requirements are now forcing thermal redesigns to reduce standby power consumption below one watt.
- Impact:Physical pins strike inked ribbons against paper, producing multi-part carbon copies resistant to heat degradation. Full-service restaurant kitchens in the United States and Germany continue specifying impact mechanisms where grease-laden heat destroys thermal media within hours, though this segment faces structural decline as kitchen automation reduces hard-copy requirements.
- Inkjet:Piezoelectric nozzles deposit aqueous or solvent-based inks onto standard paper stocks, enabling color logo reproduction and coupon printing. Boutique retail segments in Japan and France specify inkjet for brand-differentiated receipts where color marketing offsets higher per-page costs.
- Dot Matrix:Electromagnetic pin arrays form characters through impact patterns, historically deployed for multi-part forms. Legacy banking and government installations in Brazil and Mexico maintain dot matrix fleets for check and document printing where regulatory audit trails require physical duplicates.
Today's leader: Thermal. Tomorrow's challenger: Inkjet.
End User:
Application environments dictate connectivity requirements, media durability specifications, and integration complexity with downstream software systems.
- Retail:High-volume transaction environments require 99.9% uptime reliability across extended operating hours. Supermarket chains in the United Kingdom and Australia are deploying Ethernet-connected thermal units with automatic cutter mechanisms to sustain throughput during peak trading periods.
- Hospitality:Table-service restaurants, bars, and hotels prioritize compact footprints and spill-resistant enclosures. Full-service chains in Italy and Spain specify wall-mounted thermal printers to reclaim counter space for customer-facing operations.
- Transportation:Ticket counters, baggage handling, and onboard sales demand ruggedized portable units with extended battery autonomy. Airport ground services across Germany and the Netherlands are standardizing on Bluetooth-enabled mobile printers for gate-side baggage tagging.
- Healthcare:Pharmacy dispensing and patient registration require antimicrobial housing materials and quiet operation near clinical areas. Hospital networks in France and Switzerland specify thermal units with ISO 22196-certified antibacterial surfaces for prescription printing at ward stations.
Retail captures current volume concentration. Healthcare offers the steepest expansion trajectory as patient safety regulations drive specification upgrades.
Connectivity:
Wired infrastructure investments versus wireless flexibility trade-offs are reshaping deployment patterns across temporary and permanent installations.
- USB:Direct host connection delivers deterministic latency for fixed-point-of-sale terminals. Small independent retailers across Poland and the Czech Republic continue specifying USB for single-terminal deployments where network infrastructure costs prove prohibitive.
- Bluetooth:Short-range wireless pairing enables rapid relocation without cable management. Pop-up retail operators and festival vendors across the United States and Canada are adopting Bluetooth portable units to compress installation timelines from days to hours.
- Ethernet:Wired network integration supports centralized device management and real-time status monitoring. Mid-market hospitality chains in the United Kingdom are standardizing on Ethernet-connected kitchen printers to enable remote diagnostic alerting.
- Wi-Fi:Infrastructure-independent wireless deployment suits heritage buildings and temporary structures where Ethernet cabling is impractical. Seasonal hospitality operations in coastal Spain and Greece specify Wi-Fi tabletop units for terrace service expansion.
Ethernet anchors enterprise-standard deployments. Bluetooth is gaining share fastest in experiential and temporary retail formats.
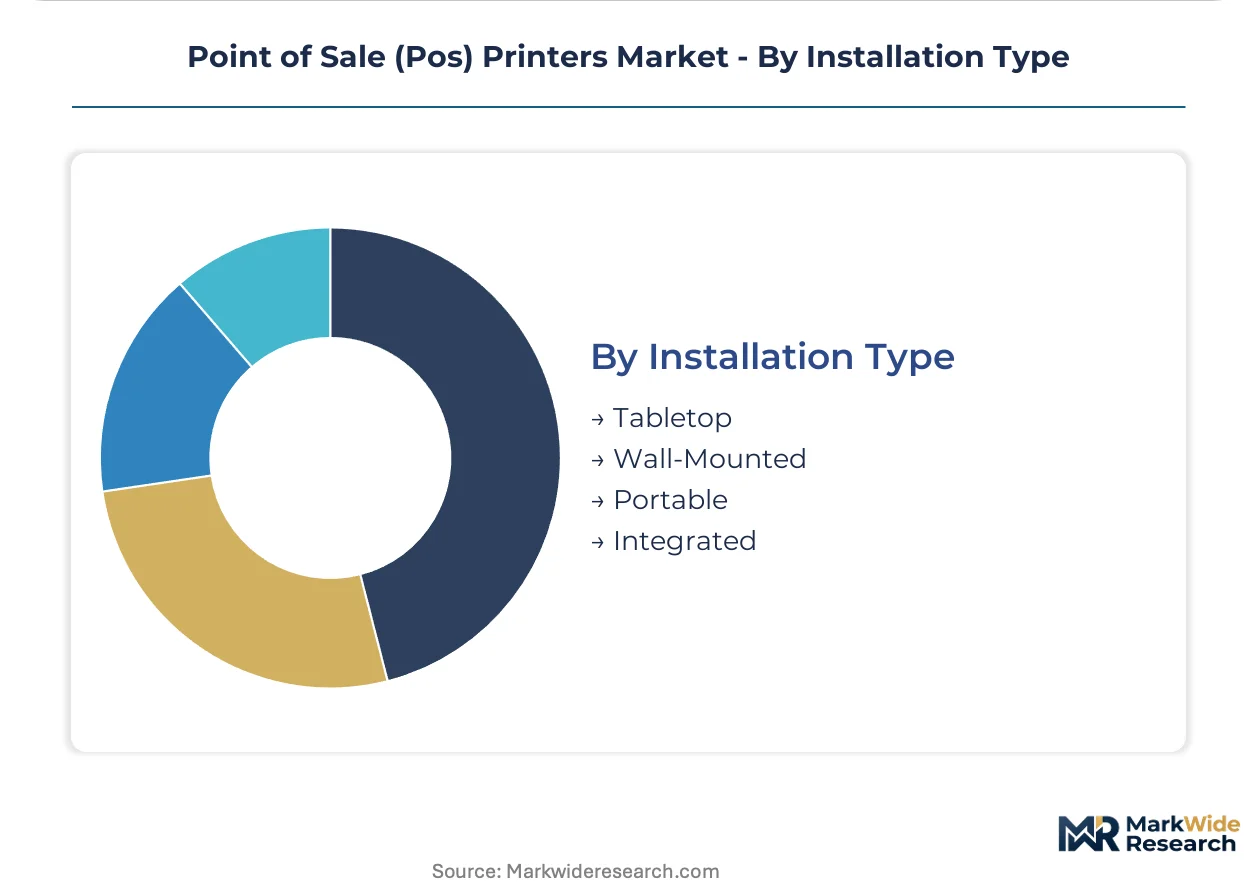
Installation Type:
Physical mounting constraints determine form factor optimization and environmental sealing requirements across deployment contexts.
- Tabletop:Self-contained units with integrated power supplies suit standard counter configurations. Convenience store chains across Japan and South Korea specify compact tabletop thermal printers with front paper loading to minimize operator reach.
- Wall-Mounted:Bracket-based vertical installation reclaims horizontal surface area in space-constrained environments. Urban quick-service restaurants in Manhattan and central London deploy wall-mounted units to maximize customer transaction space.
- Portable:Battery-powered mobile units with belt clips or shoulder straps extend printing to curbside and tableside workflows. Restaurant delivery aggregators across India and Brazil equip drivers with portable Bluetooth units for contactless receipt handoff.
- Integrated:Embedded print mechanisms within self-service kiosks and automated teller machines eliminate separate device management. Supermarket self-checkout manufacturers in Germany and the Netherlands source integrated thermal mechanisms for receipt-on-demand dispensing.
Tabletop maintains installed base dominance. Portable configurations are climbing the fastest as curbside and mobile commerce workflows proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian precision manufacturing clusters anchor thermal printhead supply chains, while quick-service restaurant automation drives deployment intensity across North American and European quick-service lanes. Regulatory divergence around energy efficiency and chemical safety is fragmenting certification requirements. Installation patterns concentrate in urban commercial corridors where modern trade formats displace traditional retail.
United States
Quick-service restaurant chains are deploying kitchen automation and drive-thru confirmation systems at scale. FCC certification governs electromagnetic emissions for retail network deployments. Deployment concentrates in Dallas-Fort Worth and Atlanta corridors where drive-thru lane expansion outpaces front-counter retrofit.
Germany
Airport ground services and supermarket self-checkout manufacturers source integrated thermal mechanisms for baggage tagging and receipt-on-demand systems. EU Green Deal ecodesign requirements force thermal heating element redesigns below one-watt standby thresholds. Industrial procurement clusters in the Rhine-Ruhr and Stuttgart manufacturing belts.
India
Tier-two cities generate concentrated demand as modern trade formats penetrate beyond Mumbai and Delhi metros. BIS certification requirements for electronic goods filter uncertified imports and protect domestic assembly operations. Quick-service deployment accelerates in Bangalore and Hyderabad tech corridors where delivery aggregator workflows proliferate.
Japan
Boutique retail segments specify inkjet mechanisms for brand-differentiated receipts with color logo reproduction. METI efficiency standards and JIS interoperability frameworks shape procurement specifications. Compact tabletop thermal units dominate convenience store chains across Tokyo-Osaka commercial corridors.
United Kingdom
Mid-market hospitality chains standardize on Ethernet-connected kitchen printers for remote diagnostic alerting. CE marking mandates compliance with EU safety standards despite post-Brexit regulatory divergence. Supermarket thermal deployments with automatic cutter mechanisms concentrate in Greater London and Manchester retail clusters.
Point of Sale (Pos) Printers Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers extend from receipt printing into cloud-native POS integration and mobile ruggedized solutions. The vendor base organizes around three tiers: precision mechanism specialists with captive thermal printhead technology, compact form-factor designers serving space-constrained hospitality, and ruggedized mobility providers targeting warehouse-adjacent retail. Strategic archetypes include component-integrated full-stack providers, software-hardware convergent platforms, and geographic niche defenders. M&A activity and API-first architecture licensing represent the dominant competitive vectors reshaping market boundaries.
Within the precision mechanism tier, Epson Corporation and Star Micronics Co., Ltd. exemplify divergent specialization paths—Epson leveraging micro-piezo technology dominance in high-speed thermal segments, Star Micronics anchoring compact footprint optimization for hospitality environments. Zebra Technologies Corporation occupies a distinct mobility-focused position, representing the ruggedized portable printing archetype extending into hybrid fulfillment workflows. These three Japanese and US-based entities illustrate how technology lineage and form-factor prioritization segment competitive territory.
| Leading Market Players |
|---|
| Epson Corporation |
| Star Micronics Co., Ltd. |
| Zebra Technologies Corporation |
| Bixolon Co., Ltd. |
| Honeywell International Inc. |
| Citizen Systems |
| HP Development Company |
| NCR Corporation |
| Toshiba Tec Corporation |
| Others |
Value Network & Pricing Analysis
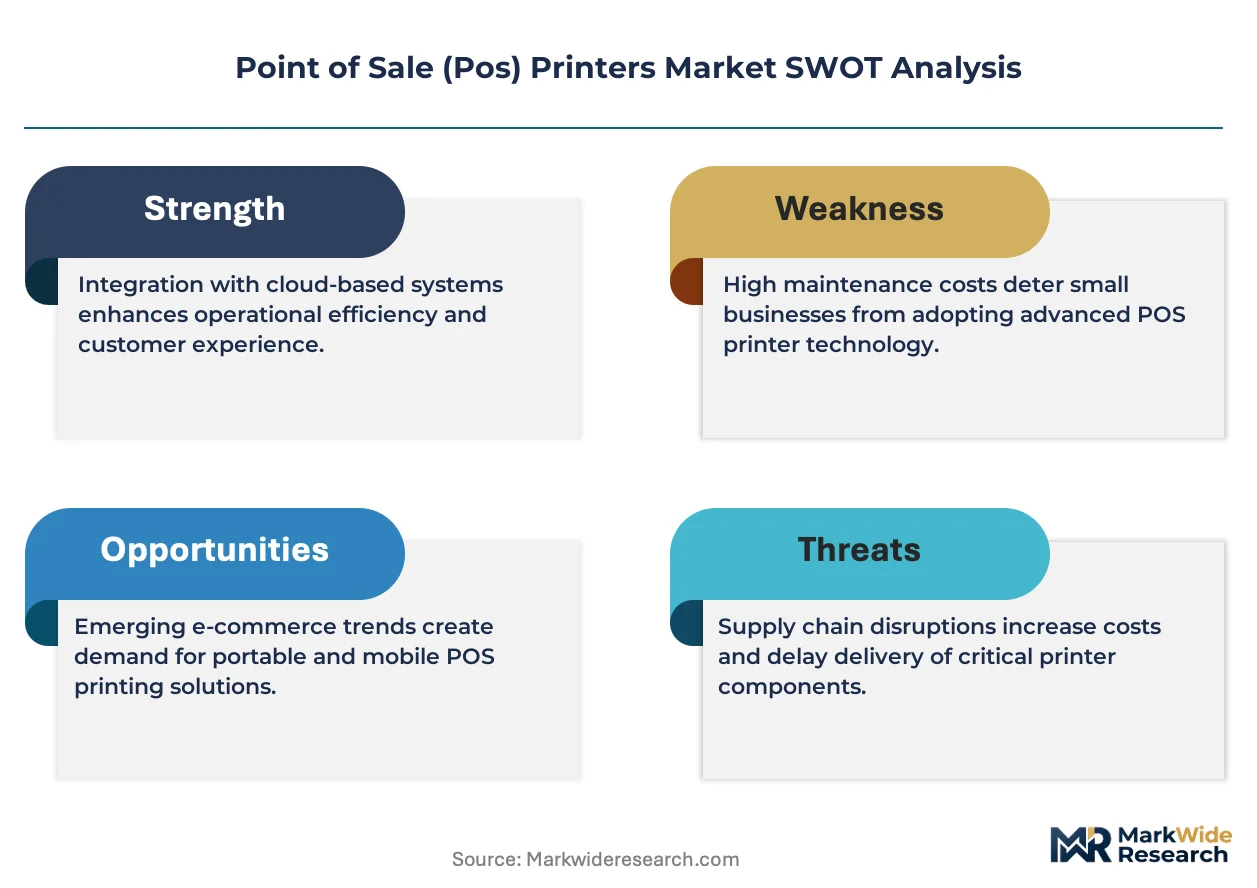
EU Green Deal ecodesign mandates for sub-one-watt standby power are forcing thermal mechanism redesigns that compress supplier margins and shift procurement toward certified-tier premiums. This specification pressure concentrates pricing power with precision printhead manufacturers capable of rapid recertification cycles.
Pricing Analysis
Input-cost pass-through from thermal paper coating chemistry and precision printhead silicon dominates pricing dynamics. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels separates buyers by regulatory exposure and volume scale. Cost compression in economy tiers is intensifying because Bisphenol-A coating restrictions and specialty chemical supply constraints squeeze consumables margins. Quick-service restaurant chains exhibit highest price sensitivity due to multi-unit procurement scale, while healthcare networks show lowest sensitivity given patient safety specification rigidity.
Supply Chain Analysis
Reverse-logistics flows for thermal printhead refurbishment and printer remanufacturing are emerging as supply chain value-recovery mechanisms, particularly in European markets with extended producer responsibility frameworks. Precision thermal printhead manufacturing concentrates in Japan, South Korea, and Taiwan, with final assembly distributed across China, Vietnam, and India. Raw material dependencies center on ceramic substrate materials, precision heating element alloys, and thermal-sensitive paper coatings. Single-source vulnerability in East Asian specialist foundries creates structural risk exposure. Distribution runs through authorized distributor networks serving regional VARs and direct OEM relationships with large hospitality and retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Point of Sale Printers Market functions as a stable compounder anchored by recurring consumables revenue streams and mandated replacement cycles driven by regulatory recertification requirements.
For Market Incumbents: Lock in thermal printhead supply through captive production or long-term offtake agreements with East Asian foundries to defend against component concentration risk. Prioritize API-first firmware architectures that embed printers into SaaS POS ecosystems, creating switching costs against pure-hardware competitors. Certification investment in India's BIS framework and EU ecodesign compliance creates protected market access that emerging entrants cannot rapidly replicate. For New Entrants and Emerging Players: E-commerce direct-to-channel routes offer the most penetrable path around established distributor networks controlling incumbent access. Target India's tier-two cities where modern trade format expansion outruns certified domestic supply capacity. Curbside and pop-up retail Bluetooth-enabled portable units represent the fastest-climbing installation type with lower certification barriers and compressed sales cycles compared to enterprise Ethernet deployments. For Investors and Strategic Acquirers: Asymmetric upside sits with software-hardware convergent platforms possessing cloud-native POS integration capabilities and recurring revenue attachment. Long-term viability over a five-to-ten year window favors vendors with thermal mechanism expertise and vertical control over printhead supply rather than pure assembly operations. Monitor BIS certification expansion timelines and EU ecodesign enforcement intensity as inflection indicators for competitive access shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native POS Integration | API-first architectures embed printers into SaaS ecosystems, compressing standalone hardware margins. |
| Thermal Mechanism Recertification | EU Green Deal compliance below one-watt standby thresholds forces product line redesigns and barriers uncertified competitors. |
| India BIS Certification Investment | Procedural filtering of uncertified imports creates protected runway for compliant domestic assembly operations. |
| Bluetooth Portable Unit Expansion | Curbside and pop-up retail formats compress installation timelines from weeks to hours, displacing cabled infrastructure. |
| Precision Printhead Backward Integration | Captive supply of ceramic substrate and heating element components mitigates single-source vulnerability in East Asian foundries. |
Research Methodology
Direct dialogue with POS hardware procurement managers, hospitality technology directors, quick-service restaurant operations executives, thermal printhead manufacturing engineers, and cloud POS platform product managers grounded qualitative insights. Secondary validation drew from FCC equipment authorization databases, EU Ecodesign preparatory study documentation, India BIS certification registries, SEC filings of listed printer manufacturers, and customs trade data for thermal paper and printhead component flows. Bottom-up unit shipment modeling and top-down value chain triangulation reconciled volume and value estimates.
Bottom-up analysis aggregated segment-level demand across thermal, impact, inkjet, and dot matrix product types, with cross-validation against end-user deployment patterns in retail, hospitality, transportation, and healthcare verticals. Connectivity architecture preferences, installation type distributions, and geographic regulatory clusters provided segmentation dimensions throughout the projection horizon. CAGRs derived from fitted growth curves incorporating replacement cycle timing, regulatory mandate effective dates, and modern trade format penetration rates in emerging markets.
The model assumes a particular technology adoption path; alternative pathways for cloud-native POS platform migration would alter the outlook if on-premise server dependencies persist longer than projected. Forecasts reflect assumptions regarding EU ecodesign enforcement consistency, India BIS certification processing timelines, and thermal paper coating chemistry regulatory stability. Practitioners should monitor BIS expansion to additional electronic product categories, EU standby power threshold revisions, and Bluetooth protocol security standard updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Large Format Printer Market
Printing Technology
ID Card Printers Market
Printing Technology
Global Barcode Printer Market
Printing Technology
Large Character Printers Market
Printing Technology
Roll to Roll Printing Market
Printing Technology
Print Equipment Market
Printing Technology
Commercial Printer Market
Printing Technology
Digital Fabric Printer Market
Printing Technology
Book Printing Service Market
Printing Technology
Automated Document Inserter (ADI) Market
Printing Technology
Print on Demand Software Market
Printing Technology
Global Computer to Plate Printing System Market
Printing Technology
Retail Printers Market
Printing Technology
Global Wireless Printers Market
Printing Technology
Barcode Printers and Consumables Market
Printing Technology
Inkjet Printhead Market