
 ID Card Printers Market | 2026-2036
ID Card Printers Market Size, Share, and Industry Trends Forecast 2026-2036
ID Card Printers Market Outlook
The gap between premium security-grade card printers and commodity desktop units is expanding, with enterprise buyers demanding embedded holographic lamination and contactless encoding while price-sensitive education sectors accept basic thermal transfer models. Evolis leverages its French manufacturing base to dominate European government tenders with modular upgrade paths. Entrust Corporation sustains North American banking relationships through FIPS-certified encryption modules. Zebra Technologies competes on channel density, occupying retail and logistics verticals with compact single-sided designs.
ID card printers are electromechanical devices that apply pigment to PVC or composite card stock through thermal transfer or dye sublimation processes, typically achieving 300 dpi resolution and encoding magnetic stripes, smart chips, or RFID inlays for physical and logical access control. Thermal transfer technology leads installed volume due to durability and lower per-card cost, while dye sublimation captures margin pools in portrait-quality corporate and diplomatic credentialing. Government agencies represent the fastest-growing end-user category as national ID programs and voter registration drives multiply procurement cycles across emerging economies.
The US NIST and FERC influence federal procurement standards for encrypted card personalization, while the EU GDPR and eIDAS framework mandate data protection during credential issuance and cross-border recognition. Indias BIS certification and UIDAI interoperability requirements shape product specifications for vendors serving Aadhaar-linked programs. Stakeholders must monitor whether biometric-integrated printer architectures or cloud-credential alternatives command the next wave of infrastructure investment.
Market Dynamics
Secure credential personalization is migrating from centralized government bureaus to distributed issuance points, forcing printer architectures to embed FIPS-certified encryption modules at the edge rather than relying on backend HSM infrastructure.
Growth Catalysts
- India's UIDAI-linked Aadhaar enrollment:Biometric-integrated card issuance terminals are proliferating through state-level enrollment centers, requiring ruggedized double-sided units with simultaneous encoding capability.
- Europes eIDAS 2.0 framework:Cross-border digital identity recognition is mandating interoperable encryption standards that favor modular printer platforms with field-upgradeable security modules.
- Saudi Arabia's giga-project construction:Worker credentialing programs at NEOM and Red Sea Global are driving bulk procurement of high-volume units with embedded lamination for ten-year durability.
Market Restraints
- PVC resin supply concentration:Feedstock for card substrate production clusters in East Asian petrochemical corridors, exposing converters to freight volatility and customs delays.
- Smart chip shortage persistence:Contact and contactless IC lead times extend 26-40 weeks, forcing printer OEMs to hold inflated component inventory or defer module integration.
- Cloud credential substitution:Mobile driver's licenses and digital wallet passes are compressing physical card issuance volumes in North American banking and transit verticals.
Strategic Opportunities
- Indonesia's civil registry modernization:The national e-KTP program expansion into remote archipelago regions creates demand for solar-powered portable issuance units with satellite uplink capability.
- Healthcare smart card convergence:EU member states are piloting unified health insurance and prescription tokens, requiring multi-application encoding that legacy single-purpose printers cannot execute.
- Subscription-based hardware provisioning:Managed print service contracts with per-card pricing are displacing capital expenditure models in U.S. university credentialing offices.
Industry Challenges
- FIPS 140-3 certification timelines:Federal validation queues extend 18-24 months, delaying product launches for vendors targeting U.S. government procurement windows.
- Legacy mainframe integration:State motor vehicle agencies require printer middleware that bridges 1970s COBOL-based registration systems to modern TCP/IP card personalization protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ID Card Printers Market |
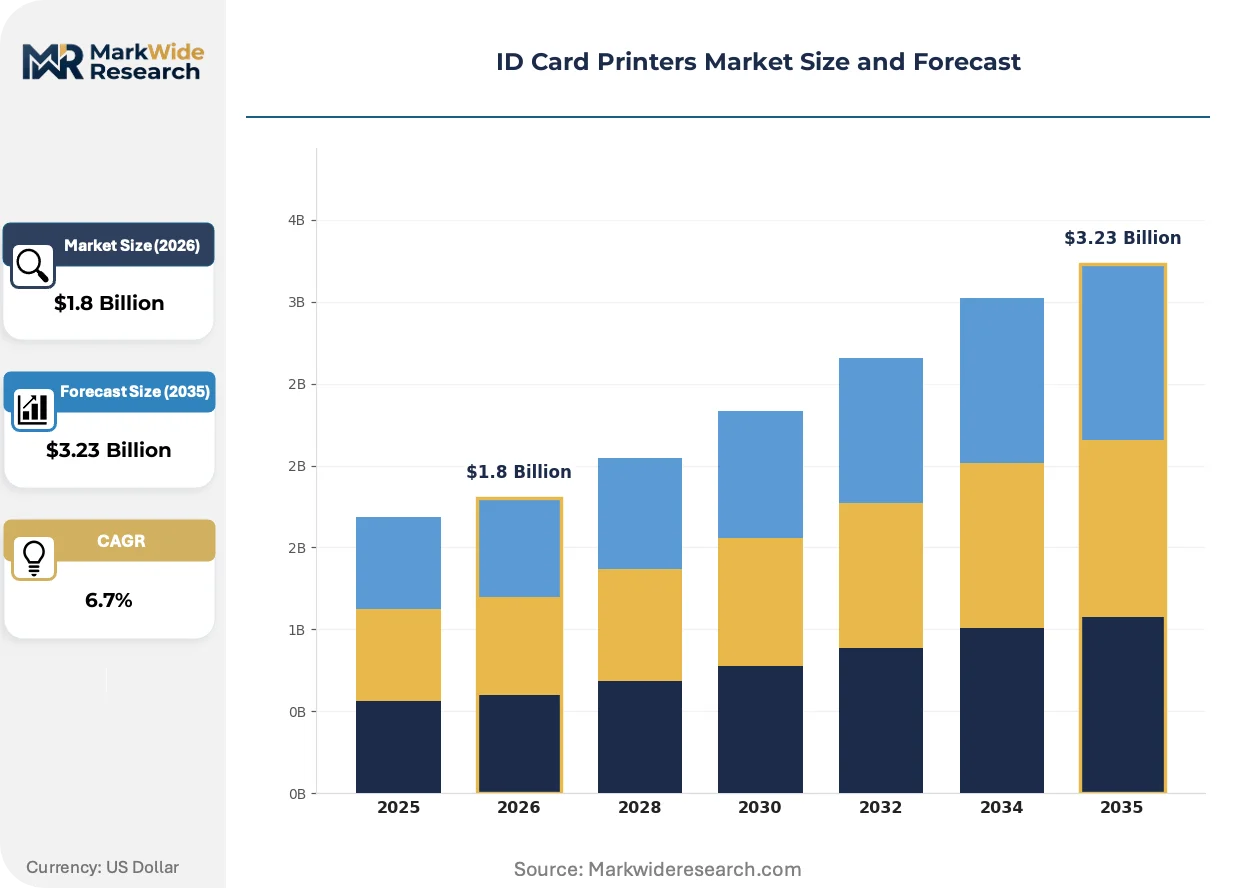
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided Printers, Double-Sided Printers, Multifunction Printers, Mobile Printers Technology: Thermal Transfer, Dye Sublimation, Inkjet, Electromagnetic End User: Corporate Offices, Educational Institutions, Government Agencies, Healthcare Facilities Distribution Channel: Online Retailers, Direct Sales, Distributors, Resellers |
| Companies Covered | Evolis, Magicard, Entrust Corporation, DASCOM, NBS Technologies, HID Global, Matica Technologies, IDP, Zebra Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ID Card Printers Market Strategic Shifts
Issuance infrastructure is fragmenting across physical, digital, and hybrid credential formats, forcing printer vendors to architect platforms that span centralized bureau production, distributed office deployment, and mobile field units without security downgrade.
Edge-based encryption processing is decentralizing sensitive personalization operations from hardened data centers to branch-level issuance points. Regional banks in Brazil and Mexico are deploying countertop units with embedded HSM modules that perform key injection and certificate generation locally. This architecture eliminates network latency for instant card activation while reducing attack surface by limiting plaintext data transmission.
The EU's Digital Identity Wallet framework is mandating re-engineering of personalization workflows to support pseudonymous attribute verification. Printer firmware must now interface with national eID nodes through standardized APIs, complicating software stacks for vendors serving multiple member states. German automotive suppliers and French healthcare networks are piloting credential formats that embed selective disclosure cryptography, requiring encoder hardware with post-quantum algorithm readiness.
Consolidated service contracts are displacing discrete hardware transactions across North American higher education. Procurement committees now evaluate total credential-lifecycle cost including consumables, remote diagnostics, and helpdesk support rather than capital expenditure alone. Campus card offices at Texas A&M and University of California system campuses have shifted to per-student-semester pricing that bundles printer fleet management with mobile credential provisioning.
ID Card Printers Market Segmentation
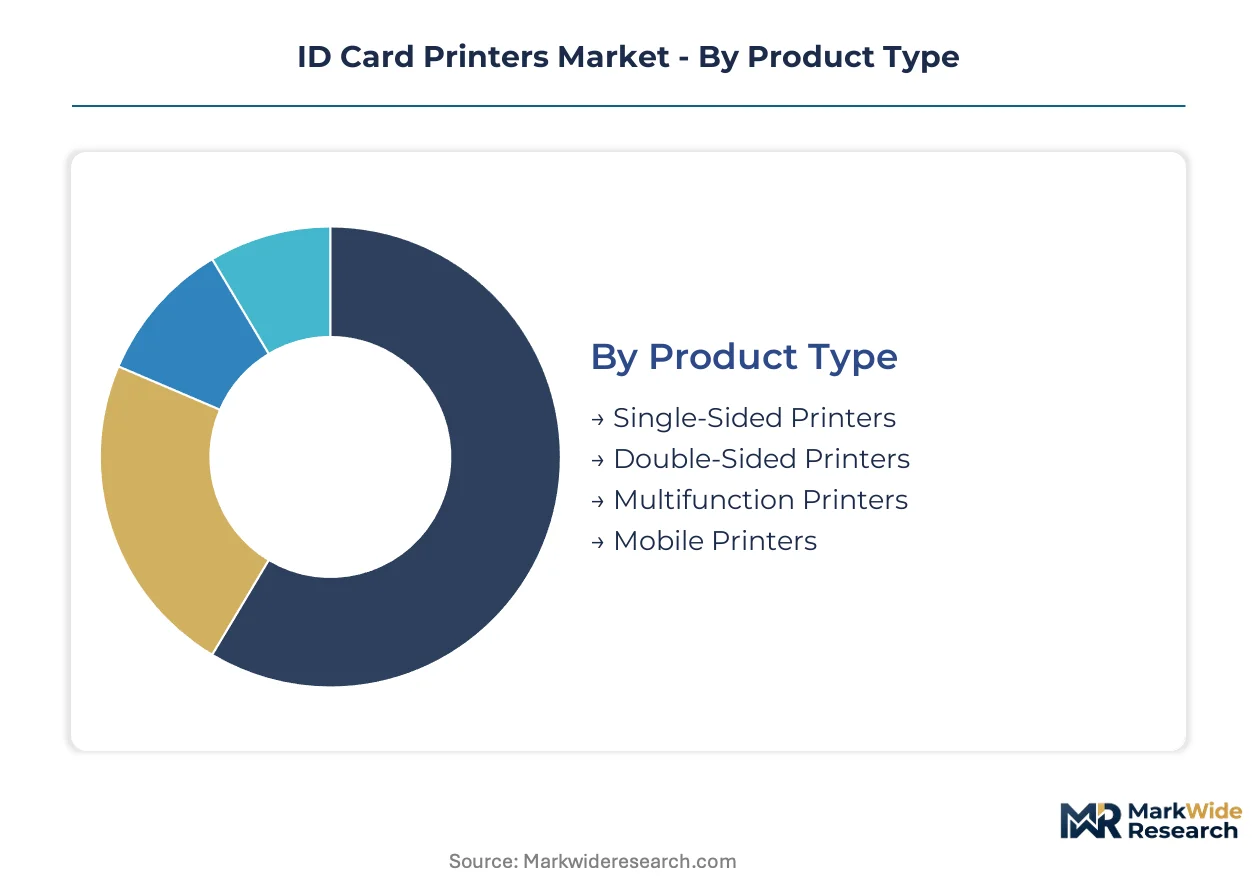
ID card printer procurement patterns diverge sharply across deployment contexts, with certification requirements, print volume thresholds, and integration complexity dictating which architectures win in each segment. Vendors must align product roadmaps to these structural boundaries rather than pursuing one-size-fits-all platforms.
Product Type:
FIPS 140-3 certification burdens fall heaviest on double-sided and multifunction units destined for government credentialing, while single-sided models face lighter validation requirements for basic corporate access control.
- Single-Sided Printers:Compact desktop units print one card face at 300 dpi through thermal transfer or dye sublimation, encoding magnetic stripes or basic RFID. Demand concentrates in North American retail and logistics for temporary worker badges, though cloud credential substitution is compressing volumes in banking.
- Double-Sided Printers:Simultaneous dual-face printing with inline lamination delivers ten-year durability for national ID and driver's license programs. Saudi Arabia's NEOM and Red Sea Global worker credentialing drives bulk procurement of high-volume units with embedded holographic security.
- Multifunction Printers:Modular architectures combine printing, lamination, encoding, and tactile impression in single chassis for passport and secure credential bureaus.
- Mobile Printers:Battery-powered portable units with satellite uplink serve remote enrollment in Indonesia's e-KTP archipelago expansion.
Single-Sided Printers sit at the top of the volume ranking, with Double-Sided Printers climbing the fastest.
Technology:
Cost tiers separate technologies by consumable economics and image quality requirements, with thermal transfer dominating high-volume issuance and dye sublimation capturing premium portrait applications.
- Thermal Transfer:Resin-based ribbon transfer onto PVC or composite stock yields abrasion-resistant cards at lower per-unit cost. Government agencies across India and the Middle East specify this technology for Aadhaar-linked and national ID programs where durability outweighs photographic fidelity.
- Dye Sublimation:Continuous-tone color diffusion produces portrait-quality credentials for diplomatic, corporate executive, and premium membership applications. EU government tenders increasingly mandate dye sublimation for eIDAS-compliant digital identity wallets requiring high-resolution facial image capture.
- Inkjet:Piezoelectric drop-on-demand systems edge into short-run personalized card markets with lower capital barriers.
- Electromagnetic:Legacy encoding technology for magnetic stripe personalization persists in transit and hospitality verticals with delayed smart card migration.
Thermal Transfer holds the largest installed base, while Dye Sublimation gains share fastest in European government modernization.
End User:
Application-specific workflows determine whether buyers prioritize throughput speed, security certification, or mobile credential integration.
- Corporate Offices:Badging for physical access and logical network authentication drives demand for compact single-sided units with Ethernet fleet management. North American enterprises are piloting subscription-based per-employee pricing that bundles hardware, consumables, and mobile credential provisioning.
- Government Agencies:National ID, voter registration, and driver's license programs require FIPS-certified double-sided printers with inline lamination and smart chip encoding. India's UIDAI enrollment centers and Saudi Arabia's giga-project credentialing represent the steepest expansion trajectory in this category.
- Educational Institutions:Campus card offices balance capital constraints against multi-application demands, shifting toward managed print services with semester-based pricing.
- Healthcare Facilities:EU member states pilot unified health insurance and prescription smart cards requiring multi-application encoding beyond legacy printer capabilities.
Government Agencies anchor premium revenue pools, with Healthcare Facilities expanding most quickly through European convergence pilots.
Distribution Channel:
Customer type and procurement scale determine whether transactions flow through direct enterprise relationships or layered channel intermediaries.
- Direct Sales:National government tenders and multinational corporate rollups negotiate directly with OEMs for customized firmware, field-upgradeable security modules, and multi-year service contracts. European vendors leverage French and German manufacturing bases to satisfy EU public procurement localization requirements.
- Distributors:Regional stocking distributors serve mid-market corporate and educational buyers requiring rapid consumable replenishment and local technical support.
- Resellers:Value-added resellers integrate printer middleware with legacy COBOL-based motor vehicle agency systems and campus ERP platforms.
- Online Retailers:E-commerce channels capture price-sensitive small office and retail segment demand for entry-level single-sided units.
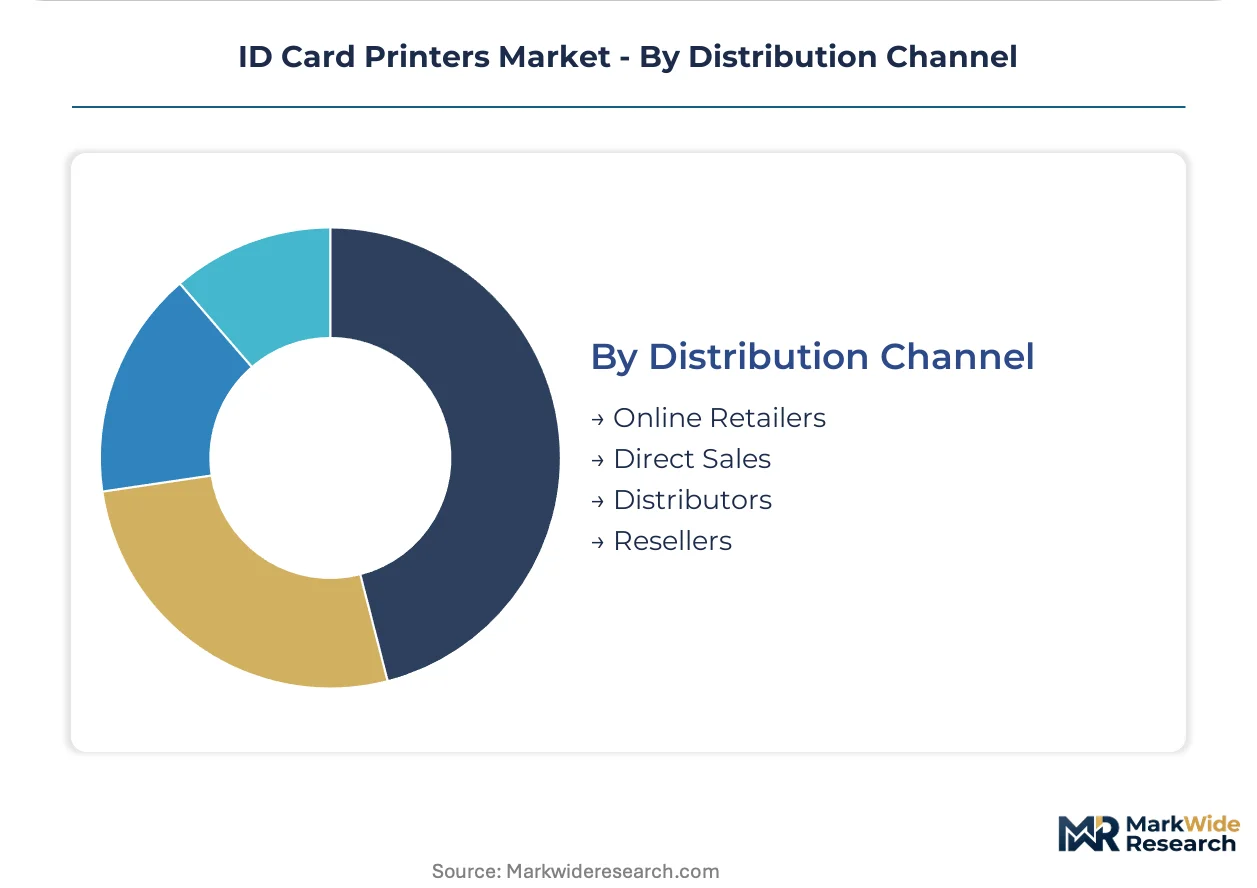
Direct Sales commands the highest transaction values, with Resellers gaining traction in legacy system integration complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
French and German engineering talent anchors European secure credential manufacturing, while Indian and Saudi technical workforces drive enrollment infrastructure deployment across emerging economies.
United States
Federal credential modernization and banking sector mobile wallet pilots sustain demand for FIPS-certified personalization equipment. NIST validation queues extend 18-24 months for encryption module certification. Government procurement concentrates in Washington DC corridor and Texas federal centers.
Germany
Automotive supplier credentialing and healthcare network digital identity pilots require post-quantum-ready encoder hardware. KBA and BSI regulations mandate field-upgradeable security modules for eIDAS interoperability. Manufacturing clusters in Bavaria and Baden-Württemberg supply modular bureau-scale systems.
India
UIDAI-linked Aadhaar enrollment centers proliferate biometric-integrated issuance terminals through state-level deployments. BIS certification and interoperability requirements shape vendor specifications. Hardware demand concentrates in Maharashtra and Karnataka enrollment corridors.
Saudi Arabia
NEOM and Red Sea Global worker credentialing programs drive bulk procurement of high-volume double-sided units with embedded lamination. SFDA and national ID modernization frameworks mandate ten-year durability standards. Giga-project construction sites in northwestern region absorb fleet deployments.
France
Diplomatic and corporate executive credentialing sustains dye sublimation demand for portrait-quality applications. CNIL data protection mandates complicate personalization workflow engineering. Manufacturing base in Rhône-Alpes region dominates EU government tender responses.
ID Card Printers Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the credential personalization equipment sector. The vendor base separates between integrated manufacturing operations and firmware-specialized assembly houses. Three archetypes dominate: European bureau-system specialists, Asian volume manufacturers, and North American security-integrated platforms. Capacity expansion and strategic technology licensing represent the dominant competitive moves as vendors position for government tender cycles.
Within the European specialist tier, Evolis exemplifies modular upgrade path architecture, while Entrust Corporation occupies a position in FIPS-certified encryption integration. Zebra Technologies anchors the compact single-sided segment serving distributed deployment contexts. These three represent distinct competitive vectors rather than overlapping market positions.
| Leading Market Players |
|---|
| Evolis |
| Magicard |
| Entrust Corporation |
| DASCOM |
| NBS Technologies |
| HID Global |
| Matica Technologies |
| IDP |
| Zebra Technologies |
| Others |
Value Chain & Pricing Dynamics
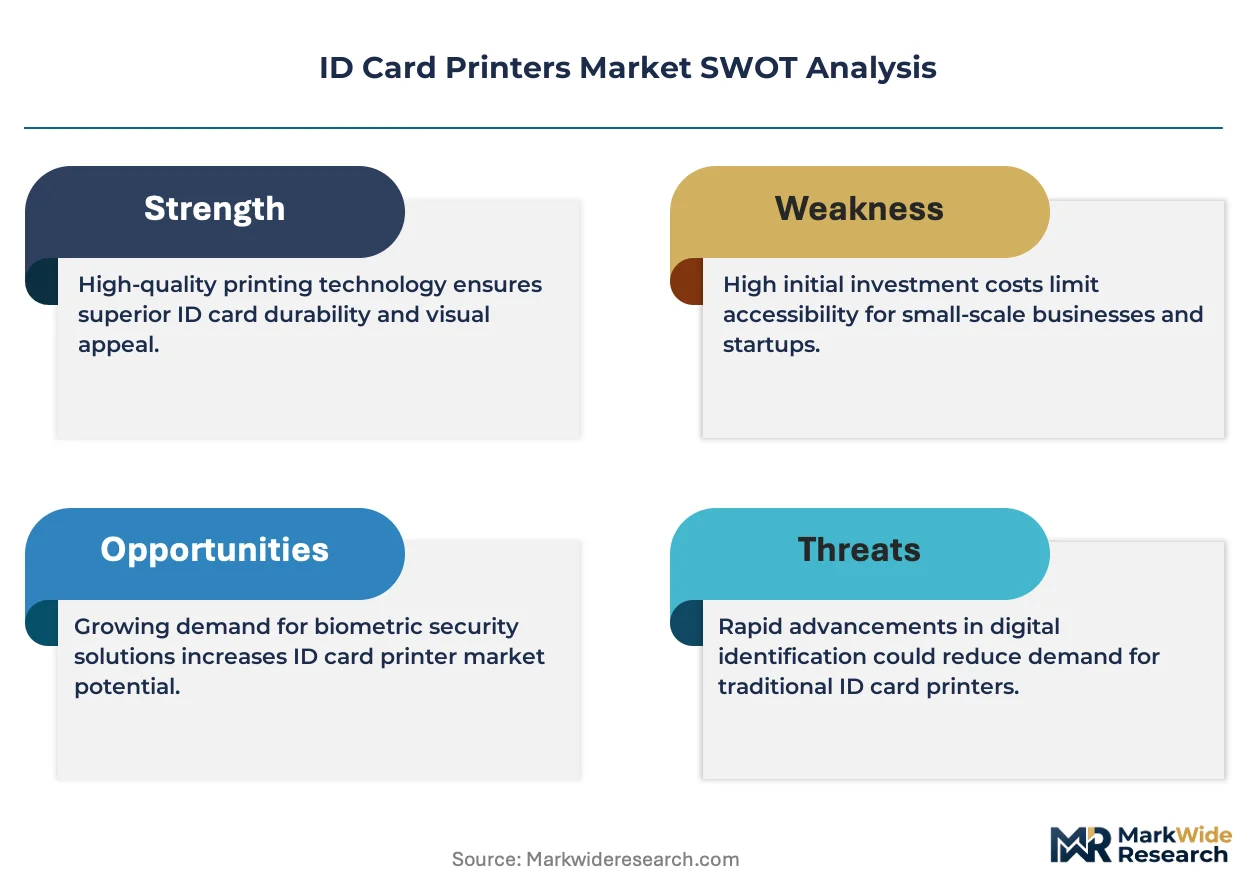
Backward integration into FIPS-certified encryption module production anchors pricing power for vendors serving government credentialing programs, while assembly houses sourcing security components from third parties compete on capital efficiency in corporate access control segments. This structural split concentrates margin pools with integrated manufacturers capable of field-upgradeable security architectures, particularly across European eIDAS-compliant tenders and Indian UIDAI-linked deployments.
Pricing Analysis
The bundled-vs-unbundled service split separates capital-intensive bureau systems from subscription-based distributed deployment models. Three-tier pricing structure across premium, standard, and economy levels aligns with FIPS 140-3 certification grades and inline lamination capabilities. Cost compression in entry-level single-sided units intensifies because cloud credential substitution erodes replacement demand across North American banking. Educational institutions exhibit highest price sensitivity through per-student-semester procurement, while government agencies accept premium positioning for ten-year durability specifications.
Supply Chain Analysis
Smart chip supply rests on Taiwanese and South Korean semiconductor fabrication capacity, with contactless IC lead times extending through congested packaging and testing facilities. PVC resin feedstock draws from East Asian petrochemical corridors, while holographic laminate substrates source from German and French specialty converters. Single-source vulnerability concentrates in encryption module foundries certified to FIPS 140-3 standards. Distribution runs through direct OEM relationships for national government tenders and regional stocking distributors serving mid-market corporate buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by sovereign identity program modernization cycles that refresh installed bases regardless of economic cyclicality.
For Market Incumbents: Hedge against cloud credential substitution by deepening firmware integration with national eID nodes and accelerating modular upgrade paths for field-deployed units. Prioritize certification investment in post-quantum-ready encoder architectures to capture EU healthcare convergence pilots before specialized competitors consolidate position. For New Entrants and Emerging Players: Remote archipelago enrollment offices in Indonesia's e-KTP expansion represent an underserved buyer archetype demanding solar-powered portable issuance with satellite uplink capability. Solar-powered field units with ruggedized chassis and minimal consumable dependency offer the most penetrable entry vector, with go-to-market execution through development finance institution procurement channels rather than conventional security distributors. For Investors and Strategic Acquirers: Consolidation pressure builds where FIPS certification queues extend validation timelines beyond product development cycles, favoring acquirers with existing federal approvals. The five-to-ten year viability window rewards platforms with embedded encryption manufacturing and established government tender relationships. Acquisition target archetypes include modular firmware specialists with eIDAS API compatibility. Watch cloud credential adoption rates in North American transit and banking verticals as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Encryption Module Development | German BSI and French ANSSI mandates accelerate encoder hardware refresh cycles across EU member states. |
| Managed Print Service Contract Expansion | Texas A&M and University of California system campuses validate per-student-semester pricing models. |
| Solar-Powered Portable Unit Launch | Indonesia's civil registry modernization into remote archipelago regions creates first-mover positioning. |
| FIPS 140-3 Certification Fast-Track | NIST validation queue compression enables timely entry into U.S. federal procurement windows. |
| Healthcare Smart Card Convergence Partnership | EU pilot programs for unified health insurance and prescription tokens require multi-application encoding capabilities. |
Study Parameters
Bottom-up government agency and corporate end-use modeling reconciled against top-down OEM shipment tracking forms the analytical core of this study. Primary interviews with credential program directors, campus card office managers, motor vehicle agency IT directors, and security hardware procurement leads combined with secondary validation against NIST certification databases, EU eIDAS implementation reports, UIDAI technical specifications, and Saudi SFDA regulatory filings. Triangulation across these sources ensures segmentation integrity across product type, technology, and deployment context dimensions.
The input-output matrix framing maps installed base replacement cycles, enrollment center expansion plans, and giga-project construction timelines against production capacity and component availability constraints. Segmentation dimensions modeled include printer architecture, encoding capability, lamination integration, regional regulatory cluster, and credential durability specification. CAGRs were derived through logistic diffusion curve fitting applied to sovereign identity program deployment schedules. Forecast inputs incorporate smart chip lead time volatility and PVC resin freight cost fluctuations.
Inputs from NIST certification queues and EU member state eIDAS implementation schedules were available through the study window; gaps in real-time OEM production data introduce uncertainty bands around quarterly shipment estimates. Forecasts reflect documented assumptions regarding credential format persistence and cloud substitution rates. A small set of named triggers warrants ongoing watch: mobile driver's license adoption thresholds, post-quantum algorithm standardization timelines, and sovereign digital wallet interoperability mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Global Computer to Plate Printing System Market
Printing Technology
Digital Production Printer Market
Printing Technology
Digital Presses Market
Printing Technology
Commercial Printer Market
Printing Technology
Variable Data Printing Market
Printing Technology
Print Equipment Market
Printing Technology
Computer-To-Plate and Computer-To-Press Systems Market
Printing Technology
Dye-Sublimation Printing Machines Market
Printing Technology
Book Printing Service Market
Printing Technology
Managed Print Services Market
Printing Technology
Digital Paper System Market
Printing Technology
Professional Printers Market
Printing Technology
North America Commercial Printing Market
Printing Technology
Inkjet Printhead Market
Printing Technology
Card Printers Market
Printing Technology
Automated Document Inserter (ADI) Market