
 AR and VR Display Market | 2026-2036
AR and VR Display Market Size, Share, and Industry Trends Forecast 2026-2036
AR and VR Display Market Analysis
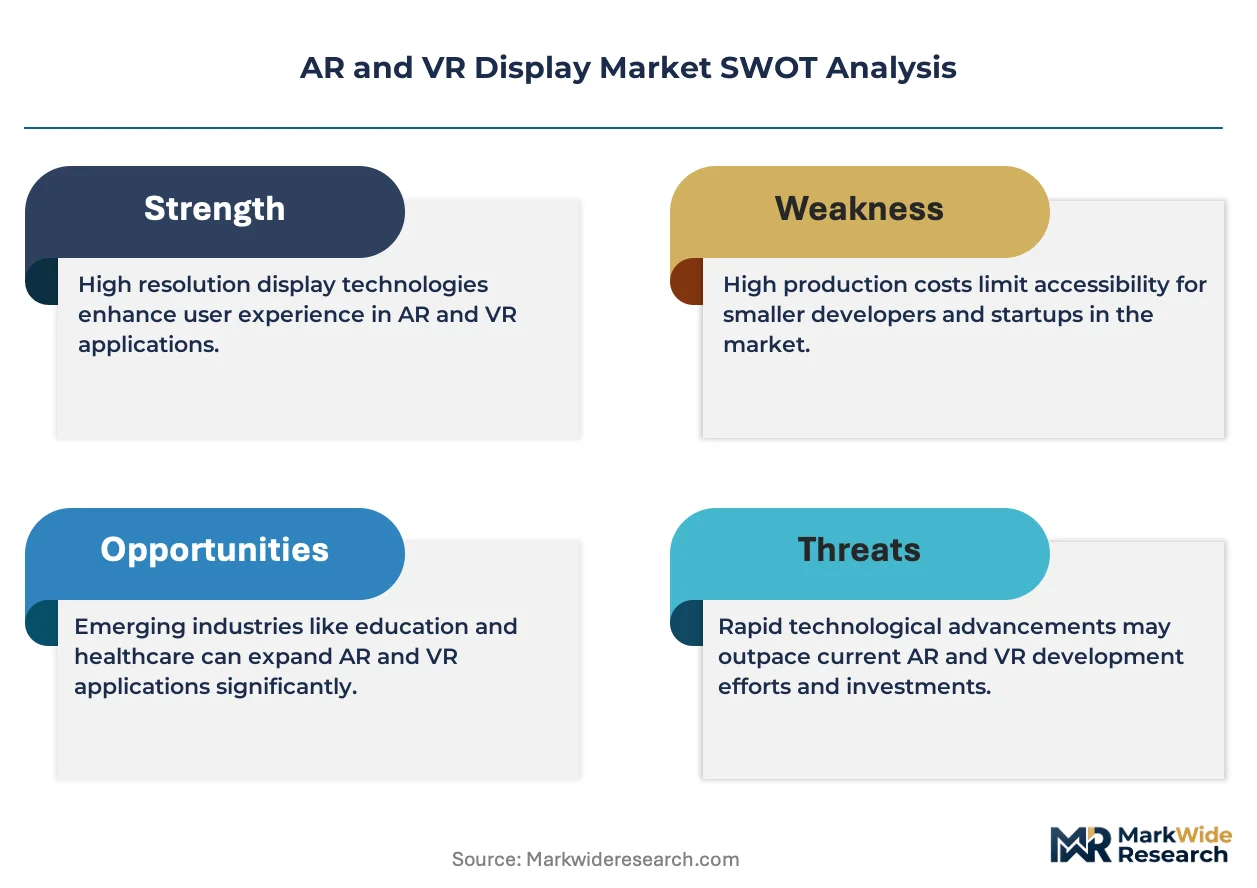
The EU AI Act is realigning compliance costs for biometric data capture in AR headsets, forcing display makers to certify privacy-by-design architectures. Samsung Electronics leverages its vertical OLED fabrication to control supply timelines for high-resolution panels. Sony anchors its position through proprietary micro-OLED technology for premium headsets. LG Display competes aggressively on LCoS wafer-scale production for enterprise smart glasses.
AR and VR displays are optoelectronic subsystems engineered to render stereoscopic imagery at sub-20 millisecond motion-to-photon latency, typically employing silicon backplanes with pixel densities exceeding 2,000 pixels per inch for foveated rendering. These displays serve primarily to eliminate vergence-accommodation conflict in immersive computing environments. Head Mounted Displays dominate volume shipments due to gaming industry procurement cycles, while MicroLED technology represents the fastest-expanding segment as manufacturers resolve mass transfer yield limitations. Training Simulation applications command premium pricing relative to Entertainment because military and aviation buyers require ruggedized optical stacks with extended mean-time-between-failures specifications.
The US FDA regulates surgical AR displays as Class II medical devices, requiring clinical validation of overlay accuracy for patient safety. China's MIIT enforces GB standards for near-eye display blue-light emissions and electromagnetic compatibility. Japan's METI promotes JIS-compliant domestic supply chains through targeted R&D consortia. Stakeholders must monitor divergence between regional certification regimes when allocating module production across fabs.
Market Dynamics
The EU AI Act's biometric data governance mandates are forcing display manufacturers to re-engineer privacy-by-design architectures, while mass transfer yield breakthroughs in MicroLED fabrication are unlocking volume economics previously blocked by technical barriers.
Growth Catalysts
- Surgical Visualization Demand:Healthcare providers in the US are expanding procurement of AR-enabled surgical systems as the FDA clears Class II devices for overlay accuracy validation. Operating room integration drives panel specifications for sub-20 millisecond latency.
- GB Standards Compliance:China's MIIT enforcement of near-eye display blue-light emission limits is accelerating domestic panel maker investment in low-power OLED architectures. Certification alignment opens military and aviation procurement channels.
- MicroLED Mass Transfer:Pick-and-place throughput improvements are resolving yield limitations that previously constrained high-density emitter arrays. Panel fabs are converting legacy LED lines to micro-emitter production.
Market Restraints
- Silicon Backplane Concentration:Advanced node CMOS wafer supply concentrates among foundries in Taiwan and South Korea, creating allocation risk for foveated rendering chipsets during semiconductor cycle tightness.
- Optical Stack Input Costs:Precision molded glass and diffractive waveguide substrates face price volatility tied to rare earth element processing capacity in China's Jiangxi province.
- Vergence-Accommodation Conflict:Current varifocal and light-field solutions remain physically bulky, limiting all-day wearable form factors for enterprise smart glasses deployments.
Strategic Opportunities
- Aviation Training Simulation:Military and civil aviation authorities are mandating immersive procedural training for pilot certification renewal, creating specification demand for ruggedized optical stacks with extended mean-time-between-failures.
- EU Green Deal Alignment:The CSRD's supply chain disclosure requirements are creating preference for display modules with verified lifecycle carbon footprints, favoring European assembly operations with renewable energy sourcing.
- Foveated Rendering Convergence:Integration of eye-tracking silicon with micro-OLED backplanes is enabling dynamic resolution allocation that reduces GPU load and extends battery endurance in untethered headsets.
Industry Challenges
- Optomechanical Talent Scarcity:The intersection of precision optics design and semiconductor packaging engineering lacks sufficient trained practitioners, extending product development timelines for waveguide-emitter integration.
- Multi-Regulatory Certification Burden:Simultaneous FDA Class II, EU MDR, and China NMPA validation requires redundant clinical studies, compressing margin structures for mid-tier headset manufacturers.
- Legacy Display Integration:Enterprise smart glasses must interface with existing warehouse management and maintenance software stacks, creating API compatibility engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AR and VR Display Market |
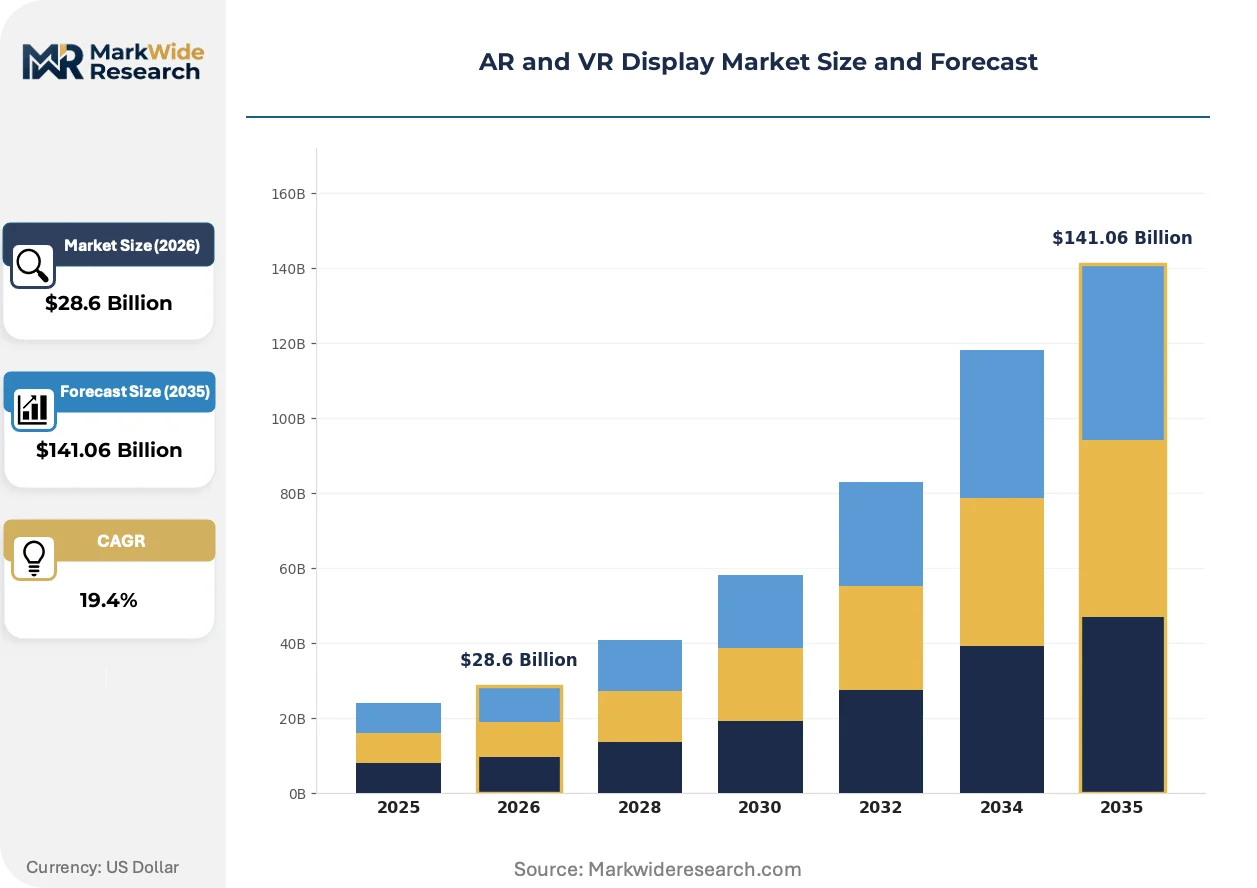
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $141.06 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Head Mounted Displays, Smart Glasses, Augmented Displays, Virtual Reality Headsets Technology: OLED, LCD, MicroLED, LCoS End User: Gaming Industry, Healthcare Providers, Education Institutions, Military Application: Training Simulation, Remote Assistance, Entertainment, Virtual Tours |
| Companies Covered | Samsung Electronics, LG Display, Sony, eMagin Corporation, Kopin Corporation, AU Optronics, Japan Display, Barco, BOE Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AR and VR Display Market Emerging Trajectories
Active reshaping in this market centers on three vectors: display technology consolidation around micro-emitter architectures, regulatory divergence forcing multi-jurisdictional compliance engineering, and procurement model evolution toward outcome-validated performance contracts.
MicroLED emitter technology is consolidating its position as the dominant next-generation display architecture for premium immersive headsets. Military and aviation training buyers are specifying micro-emitter panels for their luminance stability and operational lifespan advantages over incumbent OLED solutions. This technology shift is consolidating supplier power among fabs with demonstrated mass transfer yield above industry thresholds, compressing the viable vendor base for high-resolution near-eye displays.
Japan's METI is accelerating domestic JIS-compliant supply chain development through targeted R&D consortia for micro-OLED and LCoS backplane technologies. This industrial policy is redirecting procurement preferences within Japanese enterprise and defense sectors toward domestically certified module suppliers. Aerospace and medical device manufacturers in Japan are responding by qualifying local panel integrators ahead of foreign competitors.
Healthcare procurement departments are moving toward performance-validated contracting for surgical AR systems, where payment terms tie to overlay accuracy metrics verified in clinical use. This displaces traditional capital equipment purchase models in US hospital networks and European university medical centers. The shift is most visible in Germany and the United Kingdom, where national health technology assessment bodies now mandate real-world evidence submission for display system reimbursement eligibility.
AR and VR Display Market Segmentation
Display subsystem requirements diverge sharply across use cases. Surgical visualization demands sub-20 millisecond latency and pixel densities exceeding 2,000 ppi for foveated rendering, while enterprise smart glasses prioritize optical transparency and all-day battery endurance over raw resolution.
Product Type:
Capital intensity varies by optical stack complexity and silicon backplane integration requirements.
- Head Mounted Displays:Stereoscopic optoelectronic subsystems employing silicon backplanes with high-density pixel arrays for immersive computing. Gaming industry procurement cycles in the United States and China dominate volume demand, with seasonal refresh patterns tied to console release calendars.
- Smart Glasses:Lightweight see-through displays integrating waveguide optics with micro-emitter panels for enterprise augmented reality. Warehouse management and field maintenance deployments in Germany and Japan are specifying ruggedized form factors with extended operational lifespans.
- Augmented Displays:Overlay projection systems for heads-up applications in aviation and automotive sectors. Military pilot training programs require luminance stability exceeding commercial specifications.
- Virtual Reality Headsets:Fully occlusive displays with wide field-of-view optics for entertainment and simulation. Consumer demand concentrates in China's Guangdong province manufacturing corridor for cost-optimized panel sourcing.
Head Mounted Displays absorb the bulk of installed capacity; Smart Glasses are expanding most quickly.
Technology:
Process maturity and yield economics determine which architectures can scale beyond niche applications.
- OLED:Organic electroluminescent displays with self-emitting pixels and sub-millisecond response times. Samsung Electronics and LG Display control high-volume fabrication for premium headset tiers.
- LCD:Transmissive liquid crystal panels with LED backlighting for cost-sensitive VR applications. Chinese panel makers leverage legacy TFT-LCD capacity for entry-level headset supply.
- MicroLED:Inorganic micro-emitter arrays with superior luminance stability and operational lifespan. Mass transfer yield breakthroughs are unlocking volume economics previously blocked by technical barriers in pick-and-place throughput.
- LCoS:Liquid crystal on silicon reflective displays for compact near-eye projection systems. Enterprise smart glasses manufacturers specify LCoS for waveguide-integrated architectures requiring high optical efficiency.
LCD retains the largest installed base; MicroLED is climbing the fastest as fabs convert legacy LED lines.
End User:
Procurement authority and validation requirements shape display specification priorities across buyer categories.
- Gaming Industry:Consumer entertainment hardware with annual refresh cycles and price-sensitive volume demand. Console platform holders in the United States and Japan drive panel specifications for tethered and standalone headsets.
- Healthcare Providers:Surgical visualization and diagnostic imaging systems requiring FDA Class II or EU MDR certification. US hospital networks are expanding procurement of AR-enabled operating room integration with overlay accuracy validation.
- Education Institutions:Immersive learning laboratories and vocational training centers with extended procurement timelines. University medical centers in Germany and the United Kingdom mandate real-world evidence submission for display system reimbursement eligibility.
- Military:Ruggedized tactical displays with extended mean-time-between-failures specifications for combat and training applications. Aviation authorities are mandating immersive procedural training for pilot certification renewal.
Gaming Industry commands the highest shipment volumes; Military specifications are gaining share fastest in value terms.
Application:
Performance validation models and outcome measurement frameworks differentiate commercial terms across use cases.
- Training Simulation:High-fidelity immersive environments for procedural skill acquisition in aviation, healthcare, and defense. Military and civil aviation buyers specify ruggedized optical stacks with premium pricing relative to entertainment applications.
- Remote Assistance:Real-time expert guidance overlays for field maintenance and manufacturing operations. Industrial deployments in Japan and Germany require JIS-compliant and CE-marked module certification.
- Entertainment:Consumer gaming and media consumption with sensitivity to unit cost and content ecosystem breadth. Chinese domestic brands compete aggressively on price for volume headset sales.
- Virtual Tours:Location-based experiential displays for real estate, tourism, and cultural heritage. European museum networks are specifying CSRD-aligned supply chain disclosure for lifecycle carbon footprint verification.
Entertainment dominates unit shipments; Training Simulation shows the steepest expansion trajectory in average selling price.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Guangdong province hosts the densest concentration of AR and VR display manufacturing, with Shenzhen's special economic zone offering tax incentives that anchor panel production clusters for global headset supply chains.
United States
Healthcare providers in the US are expanding procurement of surgical AR systems as the FDA clears Class II devices for overlay accuracy validation. The FAA mandates immersive procedural training for pilot certification renewal, driving specification demand for ruggedized optical stacks. Boston's medical device corridor anchors surgical visualization R&D concentration.
China
BOE Technology and domestic panel makers cluster manufacturing capacity in Guangdong province for cost-optimized module sourcing. MIIT enforces GB standards for near-eye display blue-light emissions and electromagnetic compatibility. Shenzhen's electronics ecosystem integrates micro-emitter backplane fabrication with downstream headset assembly.
Germany
Industrial deployments of enterprise smart glasses concentrate in Bavaria and Baden-Württemberg for warehouse management and field maintenance applications. The EU AI Act realigns data governance requirements for biometric capture in AR headsets. Stuttgart's automotive engineering cluster drives heads-up display specification development.
Japan
METI promotes JIS-compliant domestic supply chains through targeted R&D consortia for micro-OLED and LCoS backplane technologies. Aerospace and medical device manufacturers qualify local panel integrators ahead of foreign competitors. Tokyo-Osaka corridor anchors precision optics design talent concentration.
South Korea
Samsung Electronics leverages vertical OLED fabrication to control supply timelines for high-resolution panels serving gaming industry procurement cycles. The national industrial policy prioritizes advanced node CMOS wafer allocation for foveated rendering chipsets. Suwon-Gyeonggi province hosts display fab concentration with captive semiconductor supply.
AR and VR Display Market Vendor Landscape
South Korean and Chinese producers anchor one tier; Japanese and Taiwanese specialists hold differentiated positions in reflective and micro-emitter architectures. The vendor base consolidates around fabs with demonstrated mass transfer yield above industry thresholds for MicroLED volume economics. Three strategic archetypes dominate: vertically integrated electronics conglomerates, pure-play display panel specialists, and precision optics subsystem vendors. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure silicon backplane allocation.
Among the vertically integrated tier, Samsung Electronics and LG Display exemplify scale-driven positioning through captive OLED fabrication and wafer-scale production capabilities. Sony occupies a specialist position in proprietary micro-OLED technology for premium headset tiers. BOE Technology anchors the China-based fabricator archetype with concentration in Guangdong province manufacturing clusters. These three firms represent the competitive core as mass transfer yield breakthroughs unlock volume economics for next-generation micro-emitter architectures.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Display |
| Sony |
| eMagin Corporation |
| Kopin Corporation |
| AU Optronics |
| Japan Display |
| Barco |
| BOE Technology |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between FDA Class II surgical displays and consumer entertainment headsets generates divergent margin structures that reshape procurement patterns across both upstream silicon backplane allocation and downstream optical stack sourcing. Premium healthcare panels command extended validation timelines that compress volume economics, while gaming industry buyers prioritize spot-market flexibility in panel procurement.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as military and aviation training programs accelerate ruggedized optical stack procurement ahead of certification deadlines. Pricing stratifies across premium, standard, and economy tiers with FDA Class II validation and JIS compliance as primary differentiation drivers. Cost compression in consumer VR headsets intensifies as Chinese panel makers convert legacy TFT-LCD capacity for entry-level supply. Gaming industry buyers exhibit highest price sensitivity; healthcare procurement committees prioritize overlay accuracy metrics over unit cost.
Supply Chain Analysis
Photoresist supply for advanced node CMOS backplanes rests on Japanese specialty chemical producers concentrated in the Tokyo-Osaka corridor. Silicon wafer fabrication concentrates in Taiwan and South Korea, with rare earth element processing for precision molded glass anchored in China's Jiangxi province. Single-source vulnerability in mass transfer equipment for MicroLED emitter arrays threatens volume scaling timelines. Distribution runs through Shenzhen's special economic zone for module integration and downstream headset assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive silicon backplane fabrication and precision optics design represents the decisive competitive lever as mass transfer yield thresholds consolidate supplier power among demonstrated high-volume MicroLED fabs.
For Market Incumbents: Deepen control over advanced node CMOS wafer allocation through foundry partnership structures that secure foveated rendering chipset supply during semiconductor cycle tightness. Expand in-house production of diffractive waveguide substrates to offset rare earth element price volatility from Jiangxi province concentration. Samsung Electronics and LG Display exemplify this defensive posture through captive OLED fabrication and wafer-scale LCoS production. For New Entrants and Emerging Players: The mid-tier pricing gap between Sony's proprietary micro-OLED premium positioning and Chinese LCD-based economy headsets offers white-space targeting for LCoS waveguide-integrated architectures in German and Japanese enterprise smart glasses deployments. Focus initial go-to-market efforts on warehouse management and field maintenance applications requiring CE marking and JIS compliance rather than FDA Class II validation timelines. For Investors and Strategic Acquirers: Re-rating potential sits with precision optics subsystem vendors demonstrating waveguide-emitter integration capabilities given aviation training simulation mandates for extended mean-time-between-failures specifications. Long-term viability favors acquisition targets with established mass transfer yield above industry thresholds and renewable energy-sourced European assembly operations aligned with CSRD supply chain disclosure requirements. Monitor pick-and-place throughput breakthroughs as the critical inflection signal for MicroLED volume economics unlocking.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Backplane Partnership | Secures advanced node CMOS allocation from Taiwan and South Korea foundries for foveated rendering chipsets. |
| Mass Transfer Yield Investment | Unlocks MicroLED volume economics previously blocked by pick-and-place throughput limitations in emitter array fabrication. |
| Regulatory Certification Pathway | Accelerates FDA Class II, EU MDR, and China NMPA validation for surgical AR display reimbursement eligibility. |
| Precision Optics Acquisition | Consolidates waveguide design and diffractive substrate capabilities threatened by optomechanical talent scarcity. |
| Renewable Energy Sourcing | Aligns European assembly operations with CSRD supply chain disclosure requirements for verified lifecycle carbon footprints. |
Methodological Framework
Multi-period observation of panel shipment volumes, certification timelines, and foundry capacity utilization anchored the trend analysis, supplemented by interviews with display subsystem engineering directors, healthcare procurement managers at US hospital networks, aviation training program officers, and semiconductor foundry account executives. Secondary validation drew from MIIT GB standards filings, FDA 510(k) clearance databases, METI R&D consortium disclosures, and customs records for rare earth element trade flows. Bottom-up triangulation across product type and technology segmentation converged with top-down macroeconomic scenario testing.
Input-output matrices modeled relationships between silicon backplane supply, mass transfer yield improvements, and downstream headset assembly capacity across the analysis window. Segmentation dimensions included product type, display technology, end user category, and application with geographic regulatory cluster overlays. CAGRs were derived from elasticity-weighted demand projections incorporating foveated rendering adoption curves and military procurement cycle patterns. Forecast inputs incorporated aviation authority training mandates and EU AI Act biometric data governance implementation timelines.
Inputs from foundry utilization reports and clinical validation study disclosures were available through the study window; gaps in real-time mass transfer yield data from proprietary fab operations introduce uncertainty bands around MicroLED volume scaling assumptions. Forecasts reflect documented assumptions regarding pick-and-place throughput improvement trajectories and regulatory divergence between FDA, EU MDR, and China NMPA validation requirements. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Virtual Fence Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR in Training Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Production Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Construction Market
Virtual Reality (VR) and Augmented Reality (AR)
Global AR and VR Smart Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
VR HMD Shipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Mobile Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Box Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Neuro-Gaming Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Mirror Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Retail Market
Virtual Reality (VR) and Augmented Reality (AR)
Enterprise AR Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented and Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
Commercial Augmented Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Holographic AR Display Market