
 Small Business Marketing Software Market | 2026-2036
Small Business Marketing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Small Business Marketing Software Market Analysis
Subscription-based pricing for software-defined marketing automation is hardening as the dominant commercial model in this space. HubSpot leverages its inbound methodology and freemium tier to anchor mid-market expansion. ActiveCampaign competes through advanced behavioral segmentation and CRM convergence. Klaviyo specializes in e-commerce retention workflows, dominating direct-to-consumer merchant adoption.
Small business marketing software encompasses cloud-deployable applications that orchestrate customer acquisition, engagement, and analytics through API-integrated modules spanning email delivery, social publishing, search optimization, and attribution measurement. Email marketing retains the largest installed base while social media management captures the fastest expansion as short-form video platforms reshape content distribution economics. Cloud-based deployment commands the majority of new bookings, though hybrid configurations persist among regulated retailers handling payment card data.
FCC guidelines on telemarketing and automated communications shape consent architecture requirements, while GDPR and state-level privacy statutes in California and Virginia force data residency and deletion protocols into product roadmaps. The FTC's scrutiny of deceptive advertising claims influences how analytics vendors present attribution accuracy to non-technical buyers. Stakeholders must weigh interoperability standards against platform lock-in as AI-generated content capabilities redraw competitive boundaries.
Market Dynamics
Cloud-first procurement mandates from enterprise buyers are compressing deployment timelines and forcing legacy on-premise vendors into SaaS migration or obsolescence. This structural pressure is redrawing competitive boundaries around API-native architectures and consumption-based pricing models.
Growth Catalysts
- GDPR and state-level privacy statutes:California's CCPA and Virginia's CDPA force data residency and deletion protocols into product roadmaps, creating compliance-driven replacement cycles among legacy systems.
- Short-form video platforms:TikTok and Instagram Reels are reshaping content distribution economics, accelerating demand for integrated social publishing and analytics modules among direct-to-consumer merchants.
- Behavioral segmentation engines:Machine learning-powered predictive models enable micro-targeting at previously enterprise-only scale, democratizing precision marketing for sub-50-employee businesses.
Market Restraints
- API interoperability friction:Platform lock-in risks intensify as AI-generated content capabilities create proprietary data moats that resist cross-platform migration.
- Cloud infrastructure concentration:AWS, Google Cloud, and Azure dominance in hosting creates single-point-of-failure exposure for multi-tenant SaaS providers serving regulated retailers.
- FCC telemarketing consent architecture:TCPA compliance costs and litigation exposure constrain automated SMS and voice campaign deployment for cost-sensitive micro-businesses.
Strategic Opportunities
- Underpenetrated professional services vertical:Law firms, accounting practices, and architecture studios remain below 15% automation penetration for client nurture workflows, representing greenfield expansion territory.
- AI-human hybrid content generation:Convergence of large language models with brand voice calibration tools enables production-scale personalization without creative team expansion.
- Embedded finance integration:Partnerships with payment processors and lending platforms create new distribution channels through contextual marketing automation at transaction points.
Industry Challenges
- MarTech stack integration complexity:SMBs average 15+ disconnected tools, creating data silos that degrade attribution accuracy and campaign orchestration effectiveness.
- First-party data engineering talent scarcity:Cookie deprecation and privacy walls require server-side tracking expertise that commands premium compensation beyond typical small business budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Business Marketing Software Market |
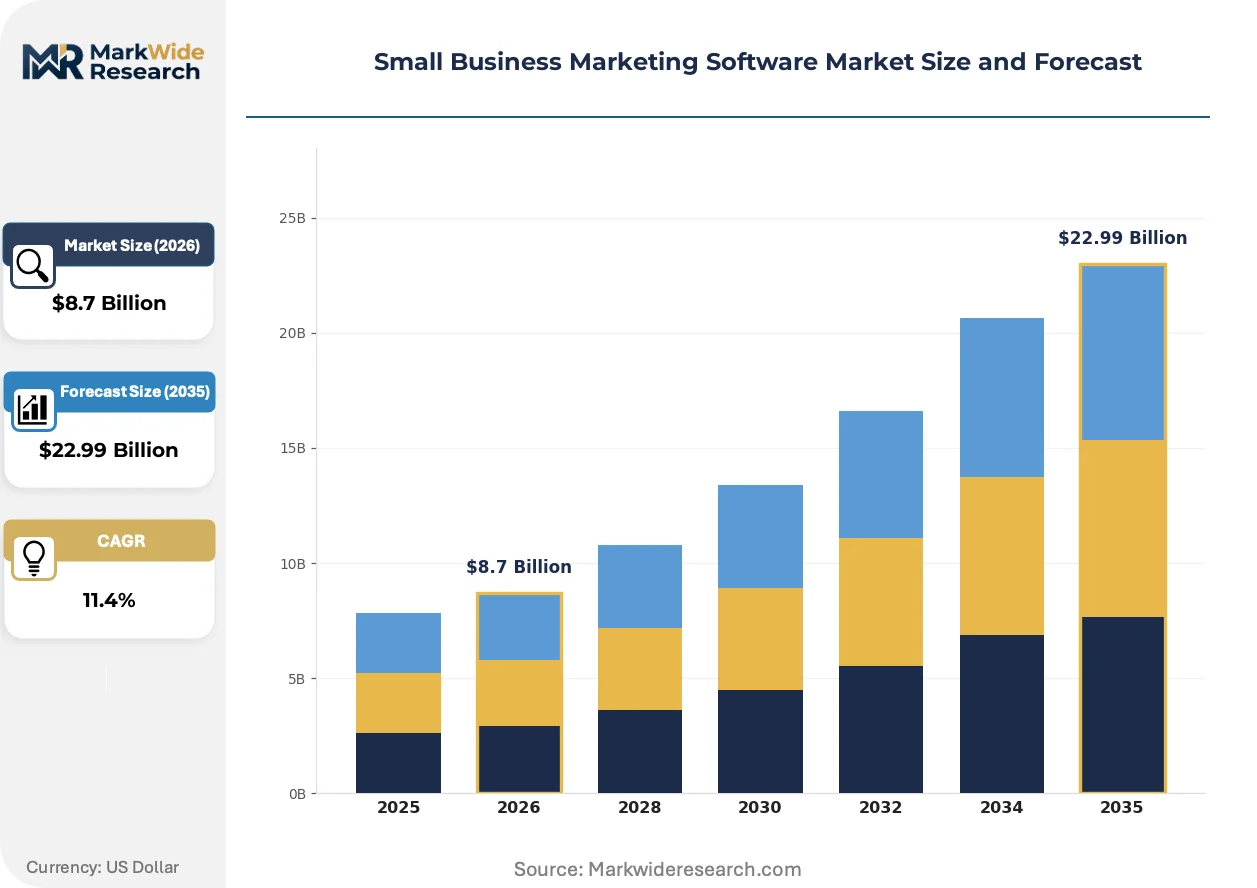
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Email Marketing, Social Media Management, SEO Tools, Analytics Deployment: Cloud-based, On-premises, Hybrid, Mobile End User: Retailers, Service Providers, Consultants, Startups Customer Type: Small Enterprises, Freelancers, Non-profits, Others |
| Companies Covered | HubSpot, Mailchimp, ActiveCampaign, Klaviyo, EngageBay, Omnisend, Zapier, AdRoll, Moosend, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Business Marketing Software Market Emerging Trajectories
Generative AI capabilities are compressing creative production timelines from weeks to hours, forcing vendors to reposition around strategy and orchestration rather than execution tools. This shift is electrifying competitive dynamics as differentiation migrates from feature depth to implementation velocity.
Natural language campaign builders are electrifying how non-technical founders deploy sophisticated multi-channel sequences without specialist hires. E-commerce merchants in Austin and Denver are adopting these tools fastest, collapsing the traditional agency-mediated setup process from months to days. The structural consequence is a compression of vendor sales cycles and a displacement of entry-level marketing service providers.
The EU AI Act's risk-based classification system for automated decision-making is forcing transparency and human oversight requirements into product architecture. Marketing automation platforms targeting European SMBs must now document training data provenance and enable contestability mechanisms for algorithmic recommendations. Germany's KBA and France's CNIL are already enforcing sector-specific interpretations that exceed baseline compliance burdens.
Subscription fatigue among digitally native startups is driving unbundling of all-in-one platforms into composable, API-first components. Buyers in Colorado and Texas increasingly prefer best-of-breed point solutions integrated through middleware rather than monolithic suites. This procurement pattern rewards vendors with robust developer ecosystems and punishes closed architectures, reversing a decade of consolidation momentum.
Small Business Marketing Software Market Segmentation
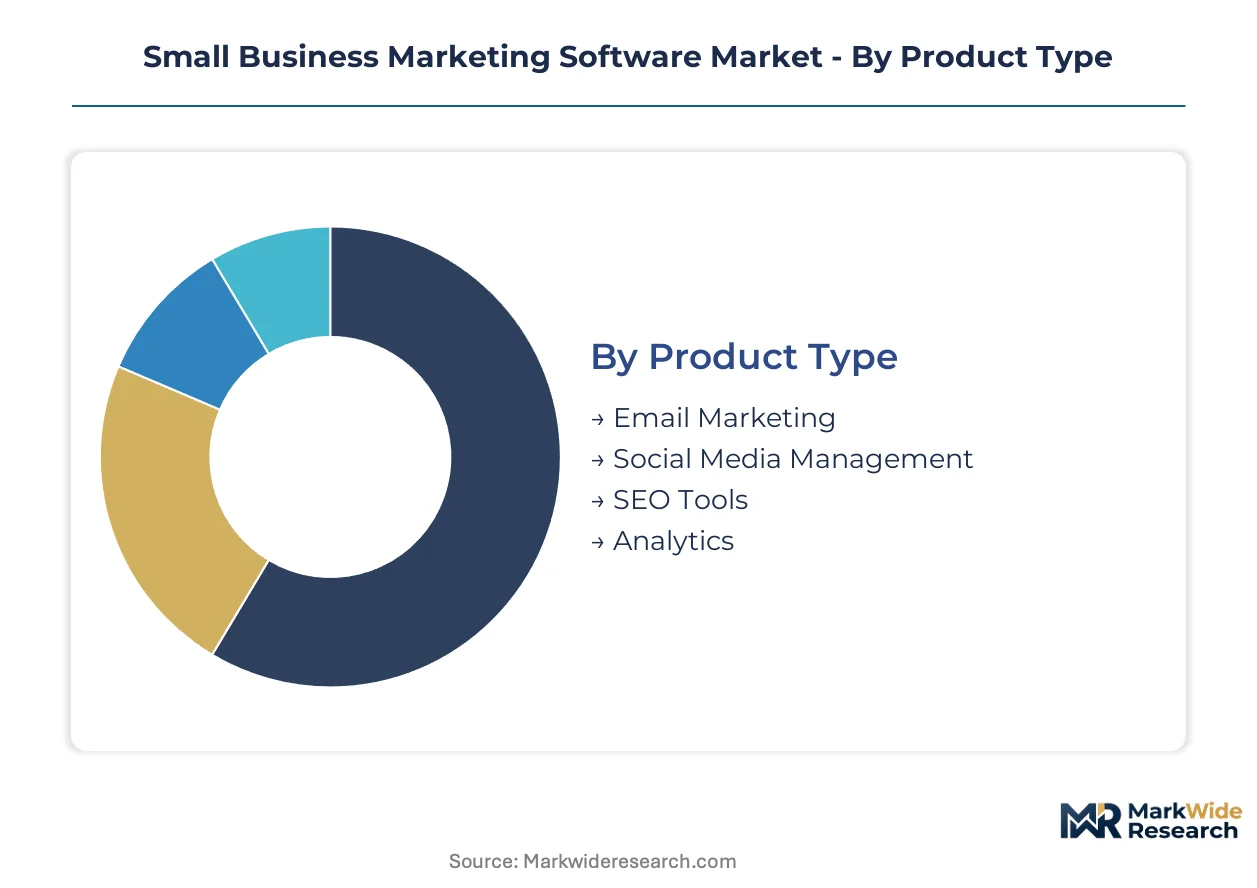
Segmentation in small business marketing software reveals how compliance burdens, deployment constraints, and buyer sophistication stratify purchasing patterns. Vendors must align certification requirements with customer operational maturity to capture expansion opportunities.
Product Type:
Email marketing and social media modules carry lighter regulatory overhead than analytics platforms processing biometric or financial data, though GDPR and state privacy statutes impose universal consent architecture obligations.
- Email Marketing:Core automation engines orchestrate list management, deliverability optimization, and behavioral trigger sequences through SMTP relay infrastructure. Demand concentrates among retailers in California and Texas managing abandoned cart recovery workflows, constrained by FCC TCPA consent requirements for SMS-triggered campaigns.
- Social Media Management:Unified publishing dashboards integrate TikTok, Instagram Reels, and LinkedIn APIs with engagement analytics and influencer collaboration tools. Direct-to-consumer merchants in Austin and Denver adopt these fastest, driven by short-form video platform economics reshaping content distribution.
- SEO Tools:Rank tracking, technical audit, and backlink analysis modules targeting organic search visibility.
- Analytics:Attribution measurement and predictive modeling platforms requiring GDPR Article 22 compliance for automated decision-making.
Email marketing sits at the top of the volume ranking, with social media management climbing the fastest.
Deployment:
Cost tier stratification separates enterprise-grade cloud subscriptions from budget-constrained on-premises installations, with hybrid configurations commanding premium pricing for regulated retailers.
- Cloud-based:Multi-tenant SaaS architectures with API-native module integration and consumption-based metering. Digitally native startups in Colorado and Texas prefer these for zero-infrastructure deployment velocity.
- On-premises:Single-tenant installations on customer-managed servers for air-gapped data control. Demand persists among law firms and accounting practices in Virginia subject to professional liability insurer mandates.
- Hybrid:Split configurations keeping sensitive customer data on-premises while leveraging cloud orchestration layers.
- Mobile:Native iOS and Android applications for field sales teams and founder-operated micro-businesses.
Cloud-based deployment holds the volume lead, with hybrid configurations gaining share fastest among PCI-DSS regulated merchants.
End User:
Application intensity varies sharply—retailers demand e-commerce retention workflows while professional services prioritize client nurture automation with lower message frequency.
- Retailers:Inventory-integrated campaign systems connecting POS data to personalized promotional triggers. This segment shows highest platform stickiness due to embedded finance integration opportunities at transaction points.
- Service Providers:Appointment-based businesses including salons, repair contractors, and wellness practitioners requiring scheduling-linked automation.
- Consultants:Solo practitioners and boutique firms below 15% automation penetration for proposal follow-up and thought leadership distribution.
- Startups:Venture-backed technology companies in Austin and Denver with subscription fatigue driving unbundled, API-first procurement preferences.
Retailers dominate current volume, with consultants representing the steepest expansion trajectory as vertical-specific templates penetrate professional services.
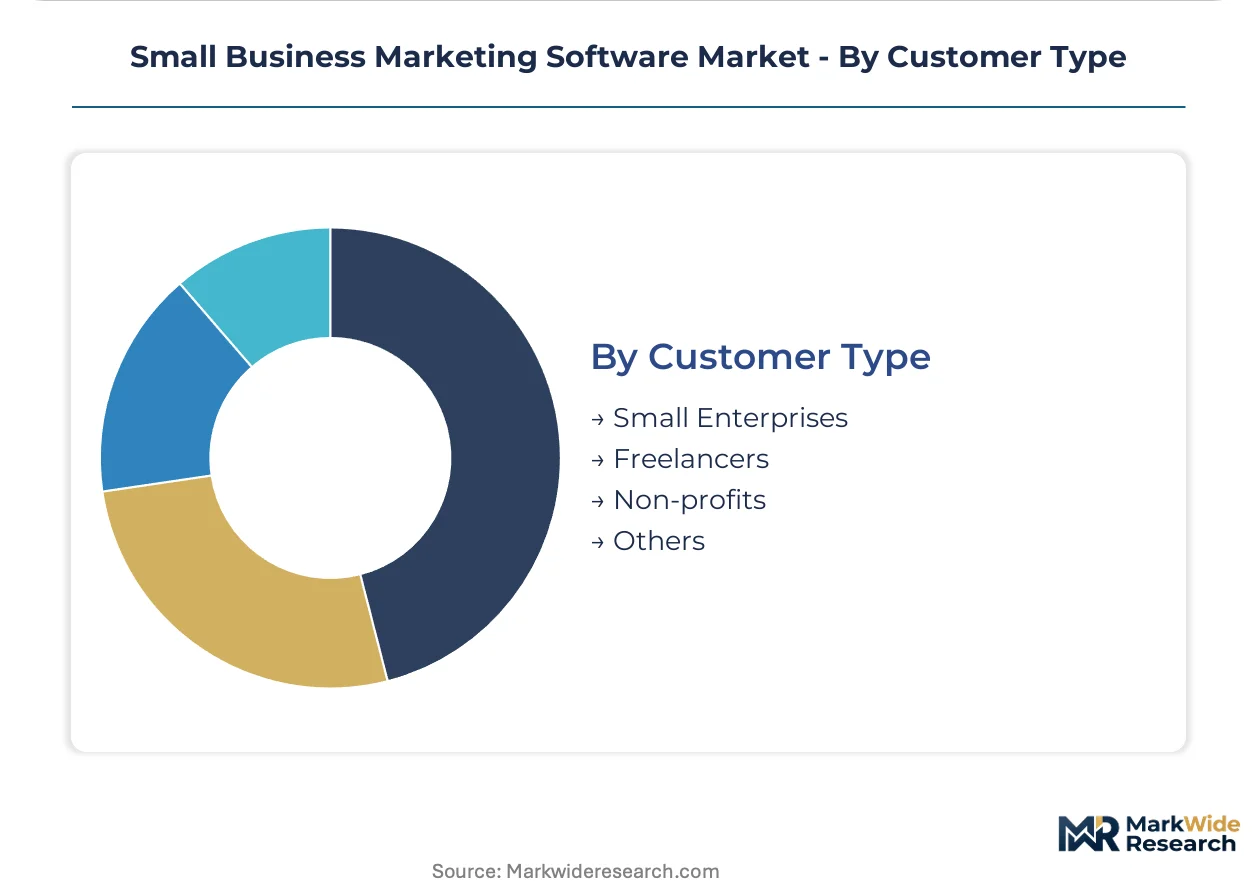
Customer Type:
Organizational scale determines feature complexity tolerance and support channel expectations, with freelancers prioritizing freemium tiers against enterprise-grade SLA requirements.
- Small Enterprises:10-100 employee businesses with dedicated marketing coordinators managing 15+ tool stacks. MarTech integration complexity creates highest churn risk in this bracket.
- Freelancers:Solo operators and side-hustle founders requiring natural language campaign builders without specialist hires.
- Non-profits:Donor stewardship and volunteer coordination workflows with constrained budgets and grant-reporting compliance needs.
- Others:Franchisees, cooperative associations, and membership organizations with distributed governance structures.
Small enterprises anchor current volume, with freelancers expanding most quickly as generative AI compresses setup timelines from months to days.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands the largest installed base of small business marketing software, while Germany's Mittelstand sector drives Europe's compliance-heavy procurement patterns. Regulatory divergence between GDPR jurisdictions and US state-level privacy statutes creates distinct product architecture requirements across Atlantic markets.
United States
Digitally native startups in Austin and Denver are collapsing campaign setup timelines through natural language automation builders. FCC TCPA consent requirements constrain SMS-triggered abandoned cart recovery for Texas retailers. California's CCPA and Virginia's CDPA force data residency protocols into vendor roadmaps, with Los Angeles and Miami emerging as cloud infrastructure hubs for PCI-DSS regulated merchants.
Germany
Mittelstand manufacturers and professional services firms below 50 employees are accelerating behavioral segmentation adoption. The KBA enforces sector-specific interpretations of EU AI Act transparency requirements for algorithmic campaign recommendations. Berlin and Munich anchor demand concentration, with Bavarian automotive suppliers deploying client nurture automation for B2B procurement cycles.
United Kingdom
London's fintech and professional services clusters are driving unbundled, API-first procurement preferences among venture-backed startups. The Information Commissioner's Office enforces GDPR Article 22 compliance for automated decision-making in attribution platforms. Manchester and Edinburgh show fastest expansion for hybrid deployment configurations among regulated legal and accounting practices.
India
Direct-to-consumer merchants in Bangalore and Delhi-NCR are adopting social media management modules for Instagram Reels and WhatsApp Business integration. TRAI regulations on commercial communications shape consent architecture for SMS marketing automation. Gujarat's textile exporters and Maharashtra's pharmaceutical distributors represent greenfield expansion for e-commerce retention workflows.
Japan
Small retailers in Osaka and Fukuoka are migrating from legacy on-premise installations to cloud-native campaign orchestration. METI's data free flow with trust initiative influences cross-border data handling protocols for multi-tenant SaaS providers. Tokyo's creative agencies are pioneering AI-human hybrid content generation for brand voice calibration at production scale.
Small Business Marketing Software Market Vendor Landscape
Top-tier vendors anchor the mid-market expansion segment, while specialized boutiques occupy vertical niches with lighter regulatory overhead. The competitive structure stratifies across three tiers: inbound methodology platforms, behavioral segmentation engines, and e-commerce retention specialists. Consolidation pressure intensifies as AI-generated content capabilities redraw differentiation boundaries around implementation velocity rather than feature depth. Dominant competitive moves include API-native architecture investments and embedded finance partnerships at transaction points.
Within the inbound methodology tier, HubSpot exemplifies freemium-to-premium conversion architecture, while ActiveCampaign occupies a position among behavioral segmentation specialists converging CRM and automation workflows. Klaviyo anchors the e-commerce retention archetype, representing direct-to-consumer merchant adoption patterns. These three entities collectively illustrate how vendor positioning stratifies around core workflow specialization rather than horizontal feature parity.
| Leading Market Players |
|---|
| HubSpot |
| Mailchimp |
| ActiveCampaign |
| Klaviyo |
| EngageBay |
| Omnisend |
| Zapier |
| AdRoll |
| Moosend |
| Others |
Supply Flow & Price Mechanics
Server-side tracking engineers concentrated in Austin and Denver command compensation premiums that widen pricing spreads between premium-tier automation suites and economy self-service tiers.
Pricing Analysis
Capacity additions in India and Eastern Europe are reshaping price floors for cloud infrastructure layers, compressing margins at the economy tier while premium vendors defend differentiation through GDPR Article 22 compliance certification and dedicated implementation support. Three-tier pricing structure across premium, standard, and economy levels stratifies by integration complexity and data residency guarantees. Cost compression in the economy tier intensifies as freemium conversion rates stagnate among digitally native startups. Freelancers and micro-businesses exhibit highest price sensitivity, while PCI-DSS regulated retailers demonstrate lowest elasticity due to compliance-driven procurement mandates.
Supply Chain Analysis
Regional distribution centers in Virginia, California, and Texas anchor hub-and-spoke patterns for SaaS delivery, with latency-sensitive analytics workloads clustering near cloud infrastructure hubs in Los Angeles and Miami. Core dependencies draw from AWS, Google Cloud, and Azure for compute; SendGrid and Twilio for message relay; and proprietary training data for behavioral segmentation models. Single-source vulnerability concentrates in hyperscaler hosting, where multi-tenant outages cascade across vendor ecosystems. Distribution runs through direct self-service portals for sub-50-employee businesses and value-added resellers for regulated verticals requiring compliance consulting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Small business marketing software has entered a late-cycle quality phase where buyer procurement favors API-native architectures with documented GDPR and CCPA compliance over feature breadth.
For Market Incumbents: Anchor market position through backward integration into proprietary large language model training pipelines, reducing dependency on third-party AI APIs. Defend against unbundling pressure by certifying ISO 27001 and SOC 2 Type II compliance for enterprise procurement eligibility. Prioritize embedded finance partnerships at transaction points to deepen platform stickiness among retailers. For New Entrants and Emerging Players: Launch via vertical-specific templates targeting law firms and accounting practices below 15% automation penetration, where lighter regulatory overhead enables faster sales cycles. Prioritize natural language campaign builders for non-technical founders in Austin and Denver, collapsing setup timelines to differentiate against incumbent complexity. White-space opportunity concentrates in professional services client nurture workflows. For Investors and Strategic Acquirers: Private equity firms with SaaS portfolio expertise are the most active acquirer in this space, targeting behavioral segmentation engines with CRM convergence capabilities. Long-term viability hinges on first-party data infrastructure ownership as cookie deprecation accelerates. Monitor FCC TCPA enforcement patterns as inflection indicator for SMS automation vendor valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-native module convergence reduces MarTech stack fragmentation for 10-100 employee businesses. |
| Acquisition of Specialist Firm | Behavioral segmentation boutiques add predictive modeling depth to horizontal automation suites. |
| Geographic Expansion | EU AI Act compliance investments unlock Mittelstand procurement in Germany and Austria. |
| Strategic Partnership | Embedded finance alliances with payment processors create distribution at transaction points. |
| Product Launch | Natural language campaign builders displace entry-level agency services for non-technical founders. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with SaaS procurement officers, marketing operations directors, platform engineers, and compliance consultants informed demand-side dynamics. Secondary sources include SEC filings from publicly traded vendors, hyperscaler capex disclosures, GDPR enforcement actions from supervisory authorities, and FCC TCPA litigation databases. Bottom-up sizing of vendor bookings triangulates against top-down estimates of small business technology spending.
Rate-of-change decomposition separates volume growth from pricing evolution across the projection horizon. Segmentation dimensions modeled include deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster. CAGRs derive from logistic diffusion curves fitted to adoption data, with inputs from cloud infrastructure pricing trends and privacy regulation implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated AI Act enforcement or hyperscaler concentration-driven outages. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Website Builder Software Market
Software & Services
Global Data Quality Software Market
Software & Services
Global Electronic Lab Notebook (ELN) Market
Software & Services
Global Online Form Builder Software Market
Software & Services
Global Smartphone Operating System (OS) Market
Software & Services
Electromagnetic Simulation Software Market
Software & Services
Systems Administration Management Tools Market
Software & Services
Interactive Digital Signage Software Market
Software & Services
Strategy Management Software Market
Software & Services
MES Software Market
Software & Services
North America Restaurant Management Software Market
Software & Services
Global Pre-Employment Testing Software Market
Software & Services
Procurement Software Market
Software & Services
Survey and Feedback Management Software Market
Software & Services
Europe Integration Platform As a Service Market
Software & Services
Asia-Pacific Accounting Software Market