
 North America Deck Design Software Market | 2026-2036
North America Deck Design Software Market Size, Share, and Industry Trends Forecast 2026-2036
North America Deck Design Software Market Intelligence
A shortage of skilled landscape architects and contractors in North America is rotating the market's focus toward user-friendly, intuitive software platforms. Autodesk, Inc. leverages its broad portfolio in AEC software to offer integrated design workflows for complex projects. Trimble Inc. competes by embedding its geospatial and construction technology into its design solutions, appealing to large-scale contractors. Chief Architect, Inc. specializes in software tailored specifically for residential design professionals, creating a strong niche.
Deck design software comprises specialized computer-aided design (CAD) tools that enable the creation of detailed 2D and 3D models of outdoor decks. These applications often feature parametric modeling capabilities, allowing for real-time adjustments to dimensions and components. Their primary function is to help users visualize designs, generate construction-ready blueprints, and produce accurate material lists. The feature set is expanding, with 3D modeling and cost estimation becoming standard, while residential remodeling applications command the largest share of use in North America.
Compliance with local building codes, including the International Residential Code (IRC) in the United States and the National Building Code of Canada, directly influences software features. These regulations dictate structural integrity and material specifications, which design tools must incorporate to ensure project approval. The key strategic decision for vendors centers on balancing deep integration with building information modeling (BIM) ecosystems against developing simplified, accessible tools for the growing DIY segment.
Market Dynamics
The primary structural force in the North America deck design software market is a skilled labor shortage among contractors. This deficit accelerates the demand for intuitive, automated platforms that reduce design complexity and enable less experienced staff to produce professional-grade output.
Growth Catalysts
- Augmented Reality Integration:The incorporation of AR technology allows contractors to superimpose 3D deck models onto a client's actual backyard using a smartphone or tablet, significantly improving client comprehension and speeding up design approvals.
- Residential Remodeling Boom:Sustained activity in home renovations, particularly for outdoor living spaces in sun-belt states like Florida and California, directly fuels demand for specialized design tools that streamline project planning and execution.
- Building Code Automation:Software that automates compliance with regulations like the International Residential Code (IRC) is a major catalyst, as it helps users avoid costly errors and ensures structural integrity from the initial design phase.
Market Restraints
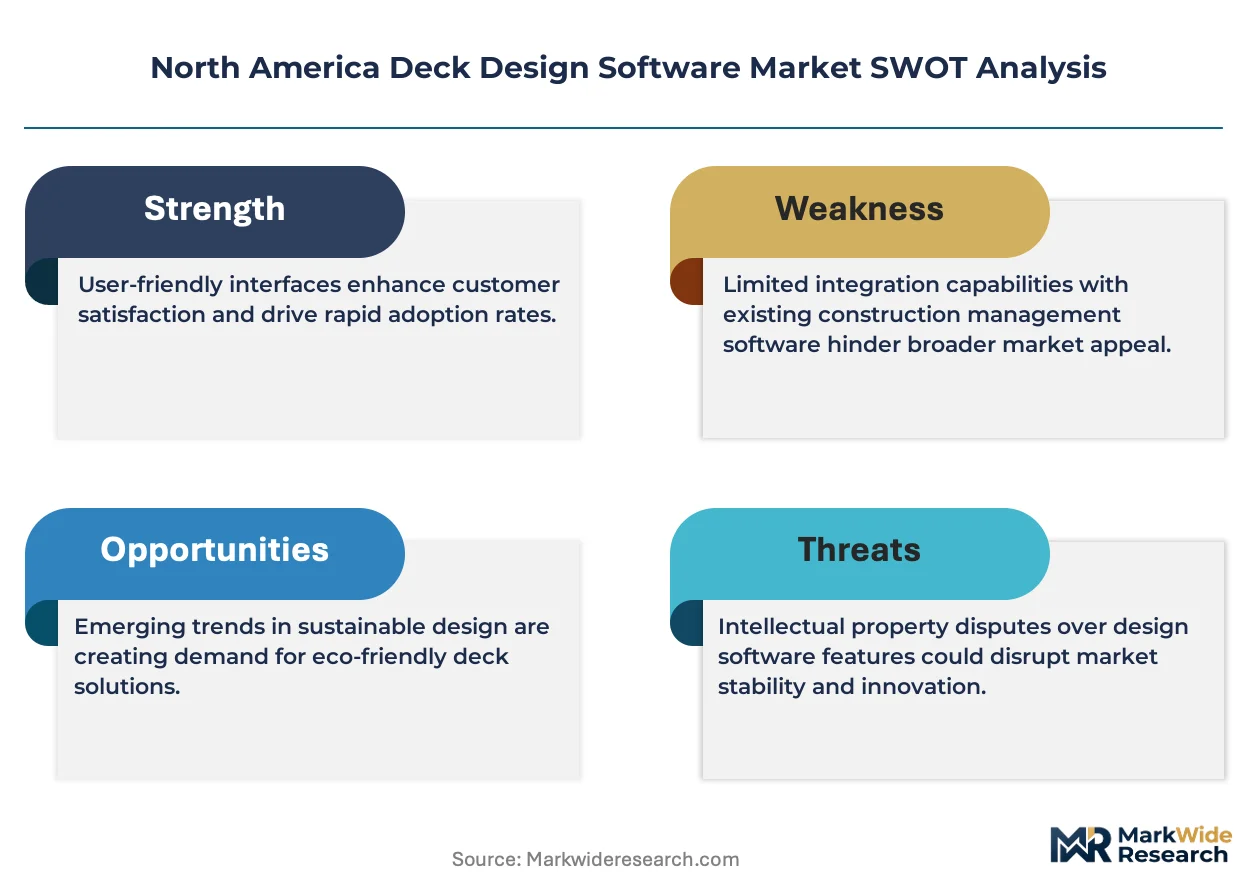
- High Software Costs:The subscription and licensing fees for professional-grade software with advanced features like building information modeling (BIM) integration can be prohibitive for small contracting firms and independent designers.
- Platform Interoperability:A lack of seamless data exchange between different brands of CAD, project management, and cost estimation software creates workflow inefficiencies and can deter adoption by firms with established, multi-vendor toolchains.
- Freemium Model Competition:The availability of free or very low-cost design applications, while feature-limited, can capture a portion of the DIY and small-project market, creating a barrier to converting these users to paid, professional platforms.
Strategic Opportunities
- DIY Segment Penetration:Developing simplified, mobile-first applications with intuitive user interfaces and template-based designs presents a significant opportunity to capture the expanding do-it-yourself (DIY) market segment.
- E-commerce Integration:Embedding direct purchasing capabilities for lumber, hardware, and other materials within the software offers a new revenue stream and enhances user value by creating a one-stop-shop for design and procurement.
- Outdoor Living Ecosystems:Expanding software modules to include the design of adjacent outdoor features such as pergolas, patios, and outdoor kitchens allows vendors to position their products as comprehensive outdoor living design solutions.
Industry Challenges
- Keeping Pace with Code Changes:The frequent and inconsistent updates to local building codes across thousands of municipalities in the United States and Canada pose a significant operational challenge for software vendors to maintain accurate compliance features.
- User Training and Onboarding:The complexity of advanced 3D modeling and parametric design features requires substantial investment in user training and support, increasing the total cost of ownership for customers.
- Hardware Demands:Rendering complex 3D models with realistic textures and lighting requires significant computing power, creating a challenge for users who may not have access to high-performance computer hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Deck Design Software Market |
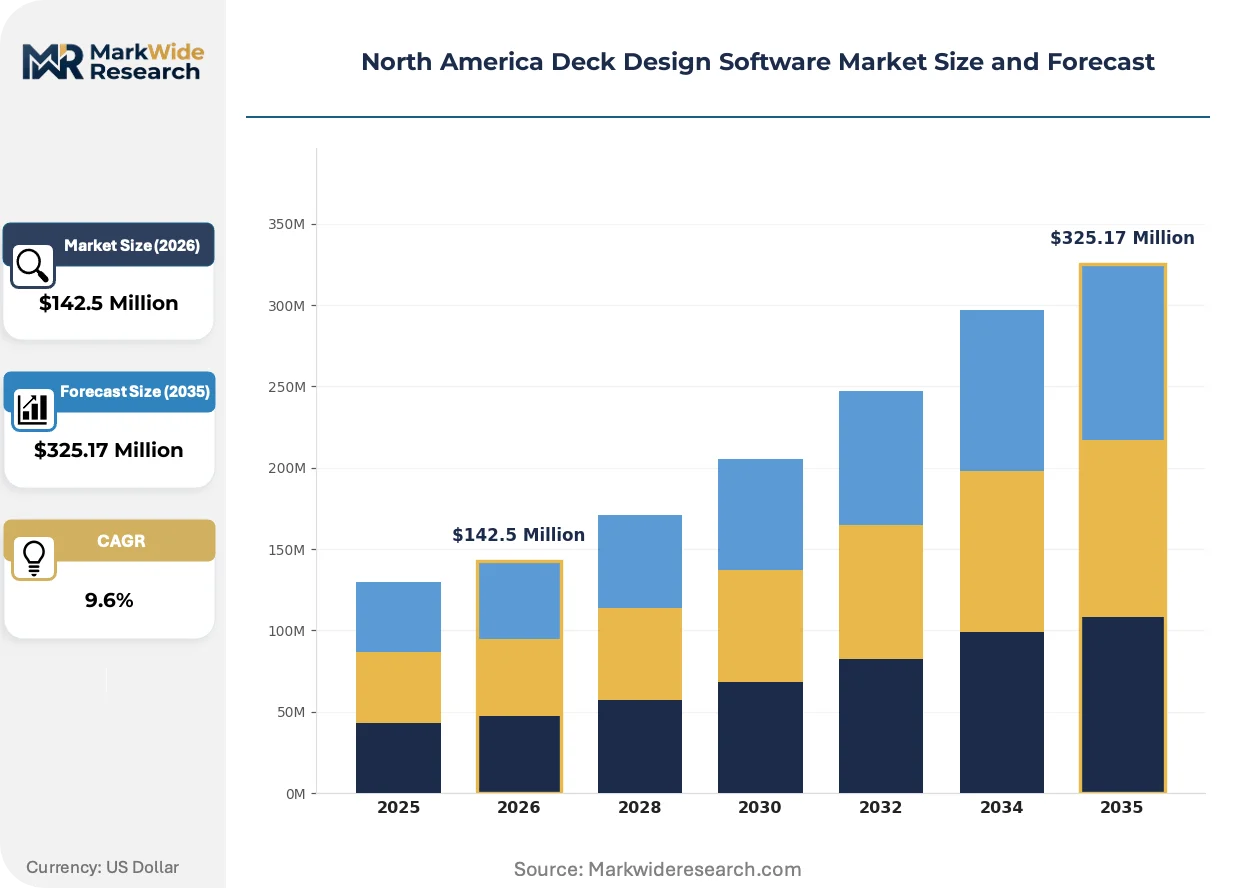
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $325.17 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform: Windows, macOS, Web-Based, Linux, Mobile Feature: 3D Modeling, Cost Estimation, Material Selection, Structural Analysis, Lighting Simulation Application: Residential Remodeling, Commercial Projects, Landscape Architecture, Outdoor Entertainment, Custom Installations User Type: Architects, Landscape Designers, Contractors, Homeowners, Interior Designers |
| Companies Covered | Autodesk, Inc., Trimble Inc., Chief Architect, Inc., Dassault Systèmes, The AZEK Company Inc., Trex Company, Inc., SmartDraw Software, LLC, Simpson Strong-Tie Company Inc., MiTek Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Deck Design Software Market Strategic Shifts & Innovations
The central evolution in deck design software is the shift from being a specialist tool for architects to an accessible platform for contractors and homeowners. This democratization is driven by embedded intelligence, automated code compliance, and direct links to the material supply chain, transforming design into a more integrated project management function.
Parametric 3D modeling provides the ability to make real-time, dynamic adjustments to deck designs where changing one dimension automatically updates all related components. Residential contractors are adopting this technology to shorten client feedback cycles and explore design variations instantly. This rapid visualization capability is displacing the slower, more labor-intensive process of manual 2D drafting and creating static renderings for approval.
Continuous updates to building codes, including the International Residential Code (IRC) in the United States, mandate strict adherence to structural safety standards. This regulatory pressure compels software developers to embed automated code-checking modules that verify elements like joist spans, footing depths, and guardrail heights. The residential remodeling segment, in particular, depends on this feature to ensure plans gain municipal approval without delays.
A shift toward an integrated "design-to-procure" workflow is altering how contractors operate. This model disrupts the traditional separation of design and material purchasing by enabling software to auto-generate an accurate bill of materials that links directly to supplier inventories for ordering. This procurement pattern is most prominent among mid-sized contracting firms in the United States seeking to minimize material waste and improve project profitability.
North America Deck Design Software Market Segmentation
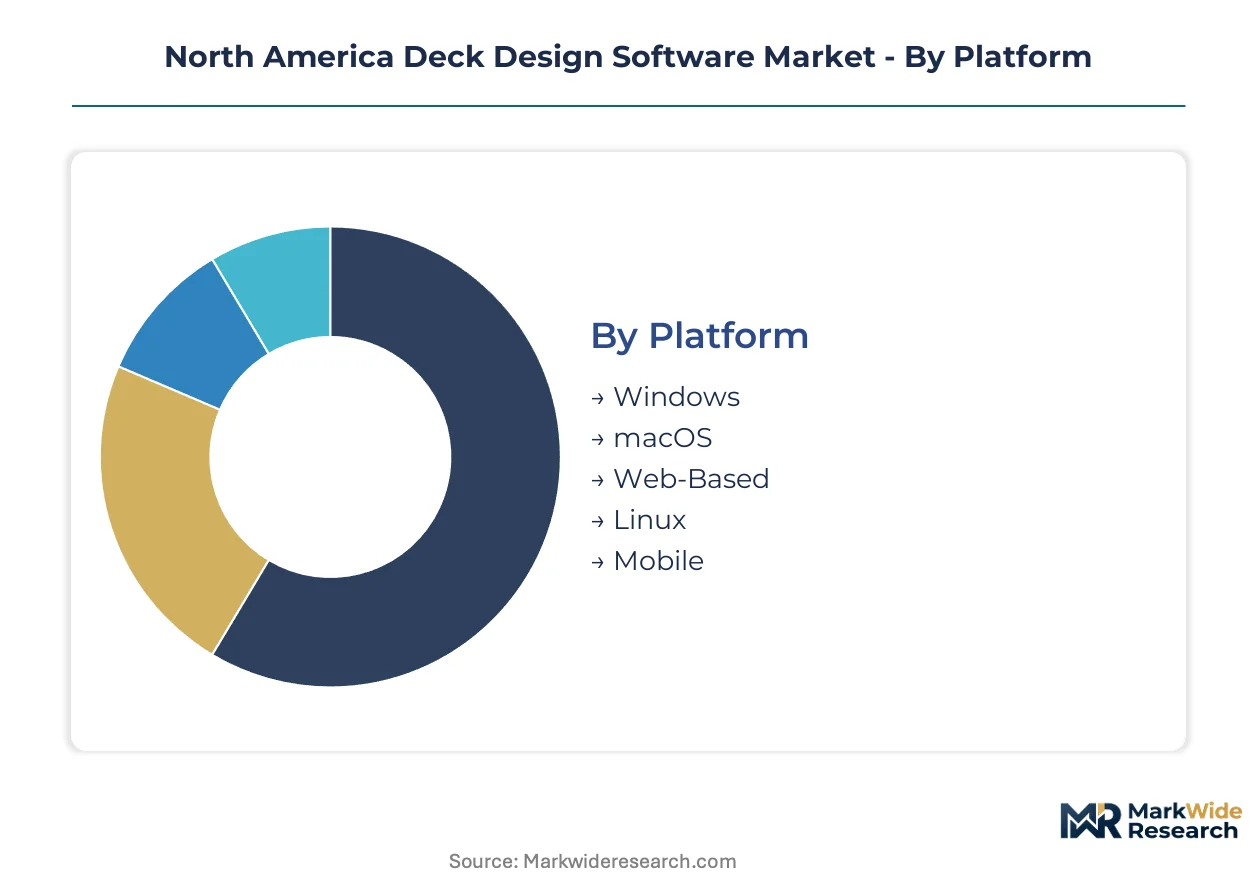
The North America deck design software market is segmented to reflect distinct user needs and technological preferences, providing vendors with targeted development pathways. Understanding these segments allows companies to tailor product offerings and marketing strategies for specific customer groups, optimizing market penetration and revenue growth.
Platform:
The North America deck design software market exhibits a diverse channel mix for platform delivery, catering to varying user preferences and technical requirements.
- Windows:These desktop applications offer comprehensive features and robust performance, often preferred by professional designers and contractors for complex projects requiring significant processing power. Demand remains strong among established firms with existing hardware infrastructure.
- Web-Based:Cloud-native solutions provide accessibility from any device with an internet connection, appealing to users seeking flexibility and collaborative tools. This segment is experiencing rapid adoption due to lower initial costs and ease of deployment for small businesses.
- macOS:Software designed for Apple's operating system caters to a niche segment of creative professionals who value the macOS ecosystem's design tools and user interface.
- Linux:Open-source or specialized applications running on Linux address a very small, technically proficient user base, primarily for custom integration or specific technical requirements.
- Mobile:These applications, often simplified versions for smartphones and tablets, support on-site consultations and basic design adjustments, enhancing client interaction.
Windows software dominates the installed base. Web-Based platforms are where expansion concentrates.
Feature:
Customer type significantly influences the selection of software features, as professional users demand more advanced capabilities than casual users.
- 3D Modeling:This core capability enables the creation of realistic, navigable three-dimensional representations of deck designs, crucial for client visualization and design iteration. Residential remodeling projects heavily rely on this feature for accurate spatial planning.
- Cost Estimation:Integrated tools automatically calculate material and labor costs based on the design, providing immediate project budgeting insights for contractors. Mid-sized contracting firms prioritize this feature to manage project profitability effectively.
- Material Selection:Databases of lumber, decking materials, and fasteners allow users to specify and visualize different options, streamlining the procurement process.
- Structural Analysis:Advanced modules provide engineering checks for load-bearing capacity and code compliance, ensuring the safety and integrity of the deck structure.
- Lighting Simulation:Features that simulate natural and artificial lighting conditions enhance the aesthetic presentation and functional planning of outdoor living spaces.
3D Modeling capabilities remain foundational for all design workflows. Cost Estimation features are expanding most quickly.
Application:
The volume of projects dictates the emphasis on specific application areas, with high-frequency segments driving software development priorities.
- Residential Remodeling:This segment includes projects focused on renovating or expanding existing residential decks, representing the largest share of software use. Sustained activity in sun-belt states drives demand for efficient design tools.
- Commercial Projects:Design of decks for commercial properties such as restaurants, hotels, or public spaces requires robust tools for larger scale and specific regulatory compliance.
- Landscape Architecture:Integration with broader landscape design elements, including patios, gardens, and hardscapes, positions deck software as part of a comprehensive outdoor planning suite.
- Outdoor Entertainment:Specialized designs for areas dedicated to entertainment, incorporating features like outdoor kitchens, fire pits, and seating, reflect a growing consumer trend. This application segment is particularly prominent in affluent residential markets.
- Custom Installations:Unique, bespoke deck designs that do not fit standard templates require highly flexible and parametric modeling capabilities, catering to high-end clients.
Residential Remodeling constitutes the largest share of application. Outdoor Entertainment projects are gaining share fastest.
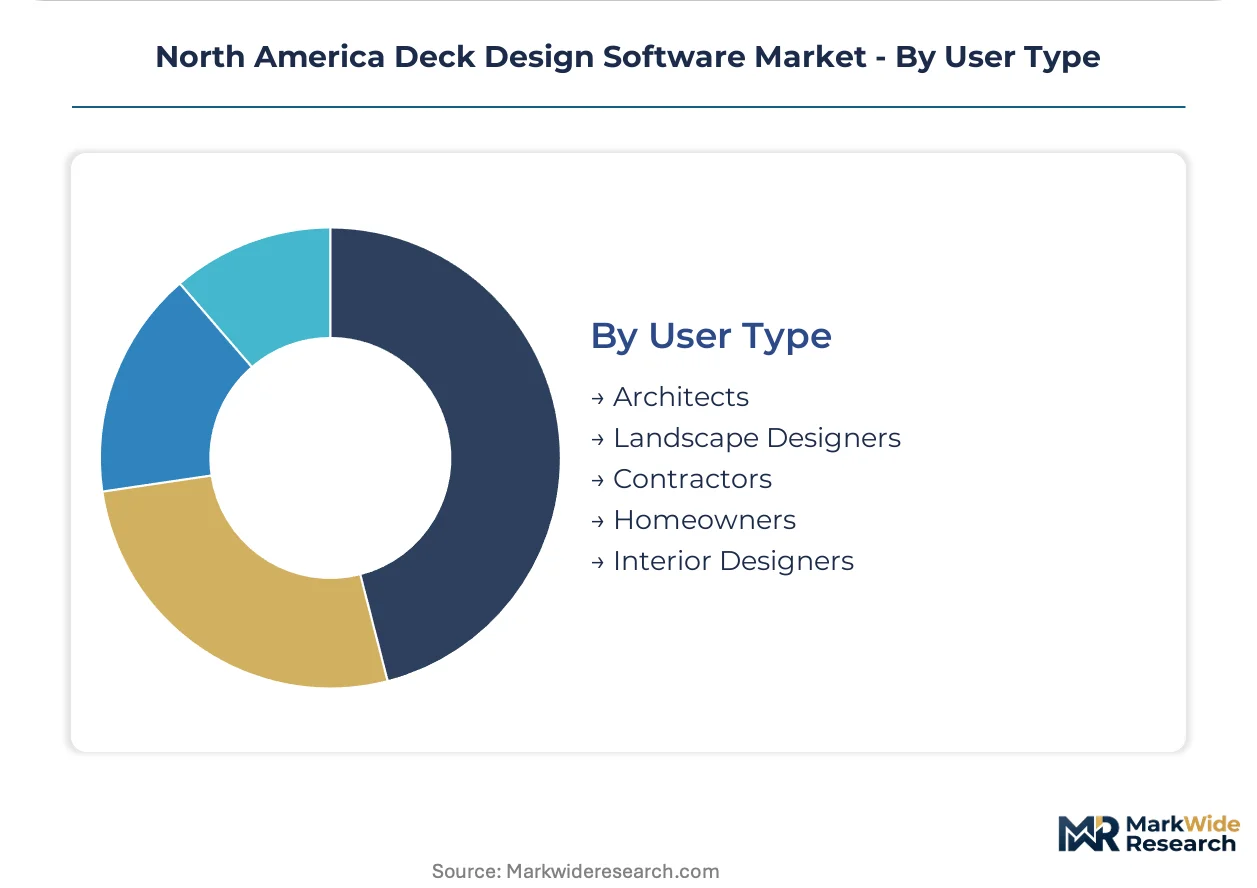
User Type:
Margin potential for software vendors varies across user types, with professional segments often justifying higher-priced, feature-rich solutions.
- Architects:These professionals utilize advanced software for detailed structural planning, aesthetic integration with overall building design, and compliance with complex architectural codes. Architects often require BIM integration capabilities.
- Landscape Designers:Specialists in outdoor spaces leverage software to integrate decks seamlessly into broader landscape plans, considering topography, planting, and drainage. Their focus is often on aesthetic and environmental harmony.
- Contractors:General and specialized deck contractors use software for efficient project planning, material ordering, and client communication, driven by the need to streamline operations amidst labor shortages. This user type commands the largest market share.
- Homeowners:The DIY segment uses simpler, more intuitive software to visualize personal projects and generate basic plans, often seeking cost-effective or freemium solutions. This segment presents a significant opportunity for accessible design tools.
- Interior Designers:While less direct, interior designers sometimes use deck software to ensure outdoor spaces complement indoor aesthetics and flow, especially for integrated indoor-outdoor living concepts.
Contractors represent the core user segment. Homeowners exhibit the steepest expansion trajectory for new user adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The International Residential Code (IRC) anchors the North America deck design software market, influencing structural integrity and material specifications. This market is propelled by a robust residential remodeling boom and the integration of augmented reality for client visualization. Strong demand is observed across key regions and states within the continent.
United States
Sustained residential remodeling and a preference for expansive outdoor living spaces drive significant demand for deck design software. The International Residential Code (IRC) mandates structural safety standards, compelling software developers to embed automated code-checking modules. Sun-belt states like Florida and California exhibit particularly strong demand for these efficient design tools.
Canada
A skilled labor shortage among Canadian contractors accelerates the adoption of intuitive, user-friendly software platforms for deck design. The National Building Code of Canada influences software features, requiring compliance with structural and material specifications. Major urban centers such as Toronto and Vancouver are seeing increased uptake for complex residential projects.
Florida
The prevalence of outdoor living spaces and a continuous home renovation market in Florida fuels demand for specialized deck design software. Local building codes, including specific hurricane-resistant design requirements, necessitate robust structural analysis features within design tools. Coastal communities across Florida prioritize advanced software for creating safe and aesthetically pleasing deck structures.
California
Affluent residential markets and a trend towards bespoke outdoor entertainment areas generate high demand for flexible and parametric deck design capabilities. The California Building Code, with its seismic design considerations, requires software to incorporate specific structural integrity checks. Southern California's luxury home sector actively utilizes advanced platforms for custom, high-end outdoor installations.
North America Deck Design Software Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive landscape for North America deck design software. The market structure features distinct archetypes, including broad AEC software providers, specialized residential design firms, and construction technology integrators. Strategic partnerships and the development of accessible tools for diverse user segments represent dominant competitive moves.
Within the broad AEC software provider archetype, Autodesk, Inc. exemplifies comprehensive design workflows that serve complex project needs. Trimble Inc. occupies a position as a construction technology integrator, embedding geospatial and construction technology into its design solutions, appealing to large-scale contractors. Chief Architect, Inc. anchors the specialized residential design segment, offering tailored software specifically for home professionals and creating a strong niche.
| Leading Market Players |
|---|
| Autodesk, Inc. |
| Trimble Inc. |
| Chief Architect, Inc. |
| Dassault Systèmes |
| The AZEK Company Inc. |
| Trex Company, Inc. |
| SmartDraw Software, LLC |
| Simpson Strong-Tie Company Inc. |
| MiTek Inc. |
| Others |
Cost & Logistics Intelligence
Composite decking substitution for traditional lumber reshapes both the geographic sourcing of materials and the pricing economics for design software, impacting integrated material databases. This dynamic influences how software vendors package material selection and cost estimation features within their platforms.
Pricing Analysis
Geographic price spreads for professional-grade deck design software demonstrate variance, with higher costs observed in urban centers like Toronto and Southern California due to specialized feature demand. The dominant pricing model is subscription-based, often tiered by feature set and user count. Price differentiation stems from advanced capabilities like BIM integration and comprehensive customer support. Pricing softness stems from the proliferation of freemium models and low-cost alternatives in the DIY segment. Homeowners and small contracting firms exhibit the highest price sensitivity, while architects and large-scale contractors prioritize feature richness over cost.
Supply Chain Analysis
Port congestion impacting physical hardware components for high-performance workstations creates inbound logistics costs for software vendors, particularly those bundling hardware with advanced design suites. Software development talent concentrates in technological hubs across the United States, Canada, and India. Raw material dependencies include skilled software developers, robust cloud infrastructure, and up-to-date regulatory data for code compliance. Talent scarcity presents a structural risk to development pipelines. Digital distribution through online marketplaces and direct downloads, complemented by reseller networks, forms the primary downstream model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deck design software represents a significant service-attach opportunity, with recurring subscriptions for cloud-based platforms and integrated data services expanding faster than one-time software licenses.
For Market Incumbents:
Secure intellectual property through continuous innovation in parametric modeling and AI-driven design assistance, especially for complex outdoor living ecosystems. Deepen integration with existing BIM platforms to solidify professional workflows, countering the threat from fragmented point solutions. Invest in advanced material science databases to maintain a competitive edge in material selection and structural analysis. Control the user experience by offering comprehensive training and certification programs.
For New Entrants and Emerging Players:
Lead with mobile-first, template-driven applications specifically targeting the expanding DIY segment and smaller contractors seeking intuitive tools. Target underpenetrated rural markets in North America with simplified design interfaces and automated material lists. Focus on e-commerce integration within the software, allowing direct purchasing of materials to create a one-stop-shop value proposition. Leverage social media platforms for community building and user-generated content.
For Investors and Strategic Acquirers:
Secondary-cycle assets sit with niche residential design software firms offering specialized compliance modules for local building codes. Long-term viability favors platforms capable of integrating diverse outdoor living features beyond just decks. Identify acquisition targets with strong user adoption in sun-belt states and robust mobile application ecosystems. The signal to watch is rapid user growth in mobile platforms coupled with high subscription renewal rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Seamless data exchange with project management and BIM software streamlines contractor workflows. |
| Strategic Partnership | Collaborations with material suppliers offer direct procurement links and enhanced user value. |
| Product Launch (Mobile-First) | Accessible mobile applications capture the expanding DIY and on-site contractor segments. |
| Geographic Expansion (Sun-Belt States) | Targeting regions with high outdoor living demand maximizes market penetration for specialized features. |
| Acquisition of Specialist Firm | Integrating niche players with strong code compliance features enhances overall product robustness. |
Research Approach
Cross-validation between primary interviews with general contractors and secondary analysis of building permit data anchors the qualitative findings. This approach combined insights from architects, landscape designers, contractors, and homeowners. Secondary data sources included industry association reports, government building codes like the IRC, and company financial filings, forming a robust foundation for bottom-up and top-down triangulation.
Sensitivity analysis informed the forecast framework, evaluating market responses to varying adoption rates of augmented reality and building information modeling. The analytical framework involved segmenting the market by platform, feature, application, user type, and regional adoption patterns across the modeling period. Compound annual growth rates were derived from historical trends, projected market drivers, and expert consensus. Forecast inputs included residential remodeling spend and AR technology adoption rates.
Underlying assumptions cover consistent technological advancements and stable regulatory environments, with deviation risk concentrated in unforeseen economic downturns or significant shifts in housing market activity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Real-Time Voice Changing Software Market
Software & Services
Europe Yacht Management Software Market
Software & Services
Automotive Operating Systems Market
Software & Services
Credit Management Software Market
Software & Services
Global Reference Check Software Market
Software & Services
Truck Dispatch Software Market
Software & Services
Global ITSM Software Market
Software & Services
Global Food Traceability Software Market
Software & Services
BIM Objects Software Market
Software & Services
Asia-Pacific Accounting Software Market
Software & Services
Ecommerce Inventory Management Software Market
Software & Services
Russian IT Software and Services Market
Software & Services
Global 360 Degree Feedback Software Market
Software & Services
Global Custom Software Development Services Market
Software & Services
Global Order Management Software Market
Software & Services
Programmable Automation Controller Software Market