
 Europe Indoor Air Purification Market | 2026-2036
Europe Indoor Air Purification Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Indoor Air Purification Market Foresight
Multi-sourced component procurement is expanding across the Europe indoor air purification supply base as manufacturers diversify filter media and sensor suppliers to mitigate raw material volatility. Blueair AB leverages its Scandinavian manufacturing footprint to sustain premium positioning in residential HEPA segments. Daikin Europe N.V. anchors commercial deployment through its HVAC integration capabilities, while IQAir AG specializes in medical-grade precision with hyper-localized Swiss engineering.
Europe indoor air purification encompasses mechanical and electronic systems engineered to remove particulate matter, volatile organic compounds, and biological contaminants from enclosed environments, typically achieving removal efficiencies of 99.97% at 0.3 microns for true HEPA configurations. These systems serve critical functions in protecting occupant respiratory health and ensuring compliance with workplace exposure limits across commercial and institutional buildings. HEPA Filters and Activated Carbon Filters occupy the core technology tier where replacement cycles generate recurring revenue streams, while UV Purifiers represent the fastest-growing product category as healthcare facilities prioritize pathogen inactivation without chemical residuals. Portable Units dominate residential deployment due to low installation barriers, whereas Centralized Solutions command premium margins in new commercial construction where duct infrastructure permits integrated air handling.
The EU Green Deal and Ecodesign for Sustainable Products Regulation mandate progressive energy efficiency thresholds and material transparency for air purification equipment sold across member states. ECHA maintains oversight of chemical substances in filter media under REACH, constraining certain activated carbon treatments and antimicrobial coatings. Stakeholders must monitor evolving MEP integration standards and building certification schemes such as BREEAM and WELL as these frameworks increasingly prescribe minimum filtration performance and real-time air quality monitoring in project specifications.
Market Dynamics
The EU Green Deal is compressing replacement cycles for legacy air handling equipment as building renovation mandates tighten energy efficiency thresholds across member states. ECHA's REACH enforcement on filter media chemistry is forcing rapid reformulation of activated carbon treatments, while healthcare procurement shifts toward pathogen inactivation capabilities.
Growth Catalysts
- Healthcare Procurement:German hospital networks are mandating HEPA filtration with real-time air quality monitoring in renovation specifications. This creates pull-through demand for integrated sensor-filtration systems.
- Ecodesign Regulation:The EU Green Deal's progressive efficiency thresholds are accelerating equipment replacement in commercial buildings across France and Italy.
- Building Certification Schemes:BREEAM and WELL standards in the Netherlands and Denmark are embedding minimum filtration performance into project financing conditions.
Market Restraints
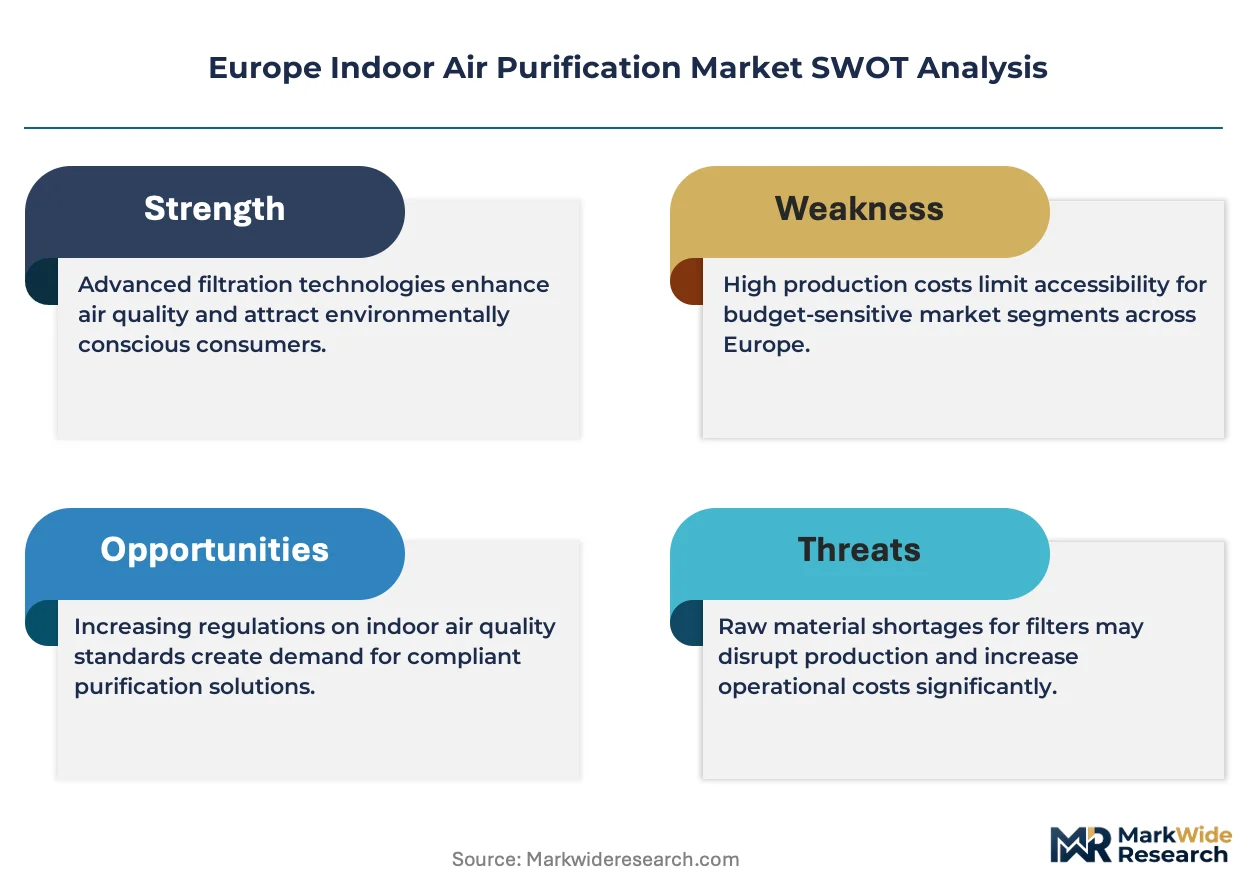
- Filter Media Supply Concentration:Glass microfiber production for true HEPA configurations concentrates in a narrow supplier base, exposing manufacturers to input volatility.
- REACH Compliance Friction:ECHA's evolving substance restrictions on certain activated carbon impregnations are extending product development timelines by 12-18 months.
- Energy Cost Structure:High-efficiency fan motors and variable air volume controls add 15-25% to unit manufacturing costs, compressing margins in price-sensitive residential segments.
Strategic Opportunities
- Underpenetrated Eastern Europe:Poland and Romania exhibit sub-15% penetration of centralized air handling in commercial stock, creating whitespace for duct-integrated purification.
- UV-C LED Convergence:Solid-state pathogen inactivation is unifying with mechanical filtration in single-unit designs, enabling retrofit deployment without duct modification.
- Service Contract Unbundling:Filter replacement and sensor calibration subscriptions are emerging as recurring revenue streams independent of equipment sales.
Industry Challenges
- Multi-Physics Simulation Talent:Computational fluid dynamics expertise for optimizing airflow patterns in compact units remains scarce across European engineering pools.
- MEP Integration Complexity:Legacy building automation protocols in Nordic commercial stock resist seamless integration with IoT-enabled purification monitoring.
- Certification Timeline Compression:CE marking under the Ecodesign for Sustainable Products Regulation demands simultaneous energy and material disclosure, lengthening time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Indoor Air Purification Market |
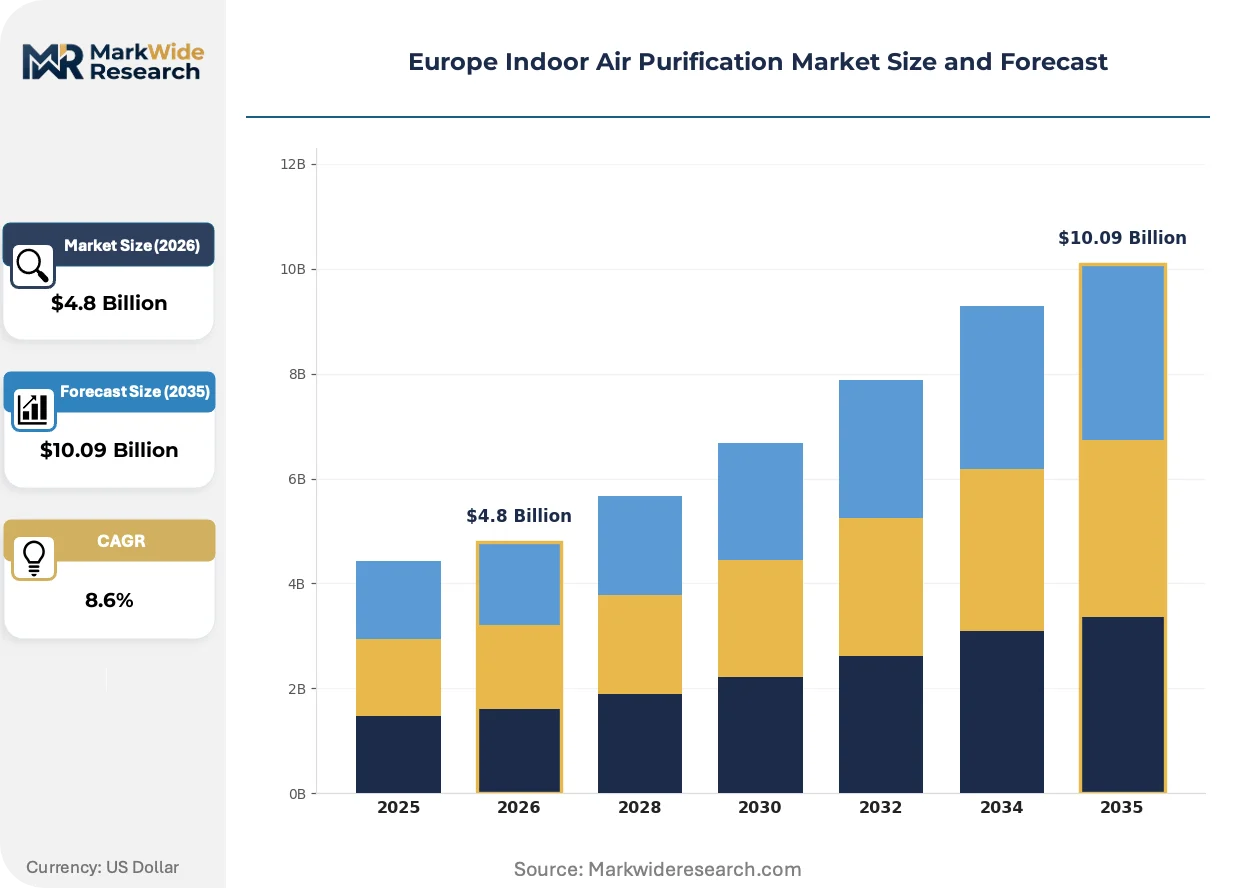
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA Filters, Activated Carbon Filters, UV Purifiers, Ionizers End User: Residential Sectors, Commercial Spaces, Healthcare Facilities, Educational Institutions Technology: Photocatalytic Oxidation, Electrostatic Precipitation, Ozone Generation, Air Exchange Systems Deployment: Portable Units, Wall-mounted Systems, Centralized Solutions, Ducted Systems |
| Companies Covered | Blueair AB, IQAir AG, Koninklijke Philips N.V., Daikin Europe N.V., Camfil AB, Honeywell International, Inc., Dyson, Winix Europe B.V., Boneco AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Indoor Air Purification Market Shifts & Advancements
Electrochemical sensing and solid-state disinfection are compressing the traditional separation between detection and remediation in European air quality management. Equipment vendors are repositioning around continuous monitoring rather than episodic filtration.
Photocatalytic oxidation paired with HEPA mechanical capture is unifying contaminant removal pathways in single-stage configurations. German healthcare facilities are piloting these hybrid systems in operating theater retrofits. The technology is compressing equipment footprint requirements by 30-40% versus stacked conventional units.
REACH authorization requirements for nanomaterial additives in antimicrobial coatings are constraining formulation choices for filter media suppliers. The regulation is forcing migration toward plasma-based surface treatments that avoid substance registration thresholds. Nordic manufacturers are responding fastest, leveraging existing clean chemistry capabilities from adjacent water purification segments.
Facility managers in Benelux commercial real estate are consolidating vendor relationships through multi-site service agreements spanning filtration, monitoring, and maintenance. Traditional equipment distributors are losing position to integrated building service operators. This concentration is most visible in Amsterdam and Rotterdam Class A office stock, where single-source contracts now cover 60% of annual filter spend.
Europe Indoor Air Purification Market Segmentation
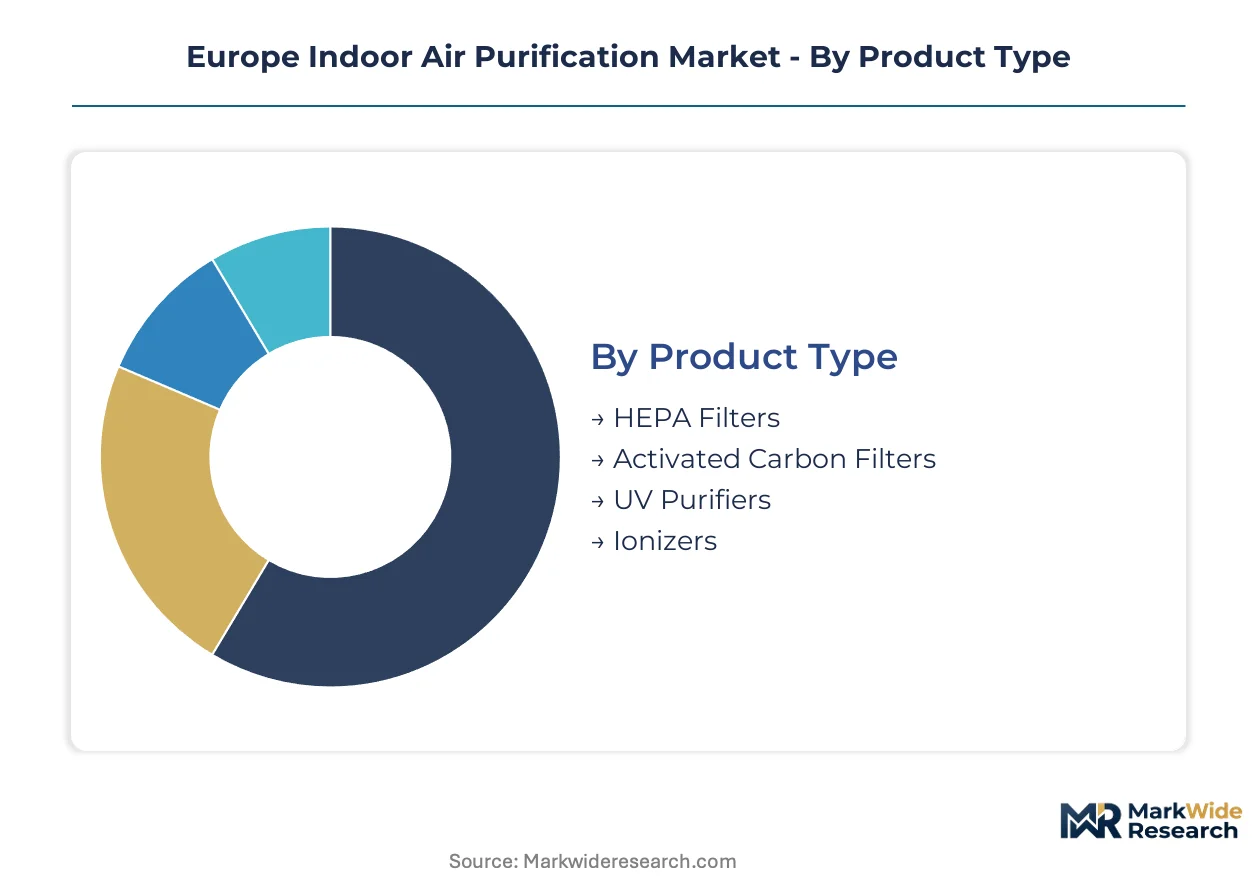
Technology choices in European air purification reflect divergent buyer priorities across cost sensitivity, installation constraints, and regulatory compliance. Segmentation reveals where procurement power concentrates and which specifications command premium positioning.
Product Type:
Buyers in this category separate by replacement cost tolerance and contaminant specificity rather than upfront equipment spend.
- HEPA Filters:Glass microfiber media achieving 99.97% efficiency at 0.3 microns defines the technical standard. German hospital networks and Dutch commercial real estate drive specification intensity as BREEAM and WELL certifications embed minimum filtration performance into financing conditions.
- Activated Carbon Filters:Porous carbon structures adsorb volatile organic compounds and gaseous pollutants. ECHA REACH enforcement on chemical impregnations extends product development timelines by 12-18 months, constraining supplier agility in France and Italy.
- UV Purifiers:Ultraviolet germicidal irradiation inactivates pathogens without chemical residuals. Healthcare procurement across Europe prioritizes this capability for operating theater retrofits.
- Ionizers:Electrostatic charge generation precipitates particulates onto collection surfaces. Residential segments in Eastern Europe favor these for low operating cost despite ozone emission concerns.
Volume sits with HEPA Filters; growth tilts toward UV Purifiers.
End User:
Application context determines performance thresholds, with regulatory pressure varying sharply across institutional versus private deployment.
- Residential Sectors:Individual household deployment favors portable units with minimal installation. Scandinavian markets sustain premium positioning through energy efficiency labeling alignment with EU Green Deal thresholds.
- Commercial Spaces:Office and retail environments require continuous operation at scale. Benelux facility managers consolidate vendor relationships through multi-site service agreements covering filtration, monitoring, and maintenance.
- Healthcare Facilities:Operating theaters and isolation rooms demand medical-grade precision with real-time air quality monitoring. German hospital networks mandate HEPA filtration in renovation specifications.
- Educational Institutions:Schools and universities balance capital constraints against occupancy density. Polish and Romanian public procurement shows rising specification intensity as EU renovation funding reaches these markets.
Revenue concentrates in Commercial Spaces; Healthcare Facilities expand most quickly.
Technology:
Underlying mechanism selection tracks energy efficiency mandates and chemical substance restrictions.
- Photocatalytic Oxidation:Titanium dioxide catalysts activated by UV light degrade organic contaminants. German healthcare pilots in operating theater retrofits compress equipment footprint by 30-40% versus stacked conventional units.
- Electrostatic Precipitation:Charged plates capture particulates without filter media replacement. Industrial applications in Nordic countries favor this for high-volume process air handling.
- Ozone Generation:Deliberate ozone production targets odor elimination and microbial control. ECHA oversight constrains deployment in occupied spaces across member states.
- Air Exchange Systems:Mechanical ventilation with heat recovery integrates purification into building infrastructure. New commercial construction in the Netherlands and Denmark embeds these as standard.
Deployment volume favors Air Exchange Systems; Photocatalytic Oxidation gains share fastest.
Deployment:
Physical integration method dictates margin structure and customer acquisition economics.
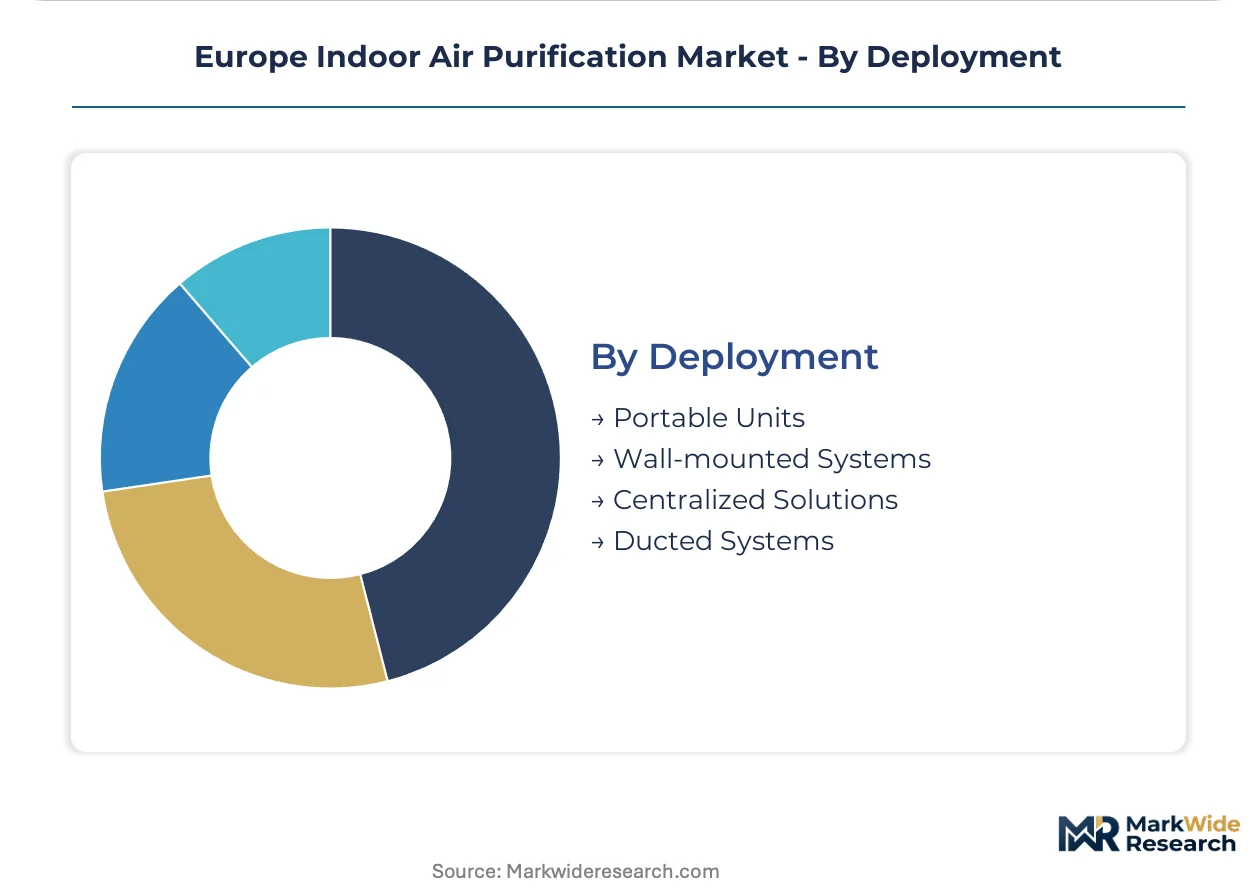
- Portable Units:Self-contained systems requiring no installation. Residential penetration in Germany outpaces neighboring markets due to building renovation rates and indoor environmental quality certifications.
- Wall-mounted Systems:Fixed installation with dedicated electrical supply. Commercial retrofits in France and Italy favor these where duct infrastructure is absent.
- Centralized Solutions:Building-integrated air handling with premium margins. New construction specifications in Amsterdam and Rotterdam Class A office stock now cover 60% of annual filter spend through single-source contracts.
- Ducted Systems:Integration with existing HVAC distribution. Poland and Romania exhibit sub-15% penetration of centralized air handling in commercial stock, creating whitespace for this category.
Unit volume runs through Portable Units; value capture concentrates in Centralized Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glass microfiber production for true HEPA configurations concentrates in Germany and the Netherlands, anchoring supply-side capacity for the broader European market. This feedstock locality shapes procurement patterns across member states.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia mandate HEPA filtration with real-time air quality monitoring in renovation specifications. The EU Green Deal accelerates equipment replacement in commercial buildings as efficiency thresholds tighten. Stuttgart and Munich anchor manufacturing clusters where filter media suppliers co-locate with precision engineering firms.
Netherlands
Facility managers in Amsterdam and Rotterdam Class A office stock consolidate vendor relationships through multi-site service agreements covering filtration, monitoring, and maintenance. BREEAM and WELL standards embed minimum filtration performance into project financing conditions. Eindhoven's clean chemistry capabilities from adjacent water purification segments enable rapid migration toward plasma-based surface treatments.
France
Commercial retrofits in Paris and Lyon favor wall-mounted systems where duct infrastructure is absent. ECHA REACH enforcement on chemical impregnations extends product development timelines by 12-18 months. The Île-de-France region exhibits specification intensity as EU renovation funding reaches public procurement channels.
Italy
Building renovation mandates under the EU Green Deal accelerate equipment replacement in Milan and Rome commercial stock. Ecodesign efficiency thresholds compress replacement cycles for legacy air handling equipment. Northern industrial clusters around Turin resist seamless integration with IoT-enabled purification monitoring due to legacy building automation protocols.
Poland
Sub-15% penetration of centralized air handling in Warsaw and Kraków commercial stock creates whitespace for duct-integrated purification deployment. EU renovation funding reaches educational institutions, balancing capital constraints against occupancy density. Public procurement shows rising specification intensity as building certification schemes gain traction.
Europe Indoor Air Purification Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers diversify filter media and sensor suppliers to mitigate raw material volatility. The vendor base fragments across Scandinavian engineering houses, Japanese HVAC conglomerates, and Swiss precision specialists. Three archetypes define competitive positioning: premium residential specialists leveraging regional manufacturing footprints, commercial integrators anchoring through HVAC system compatibility, and medical-grade precision engineers serving healthcare procurement channels. Portfolio diversification and geographic expansion constitute the dominant competitive moves as participants seek recurring revenue streams beyond equipment sales.
Within the premium residential tier, Blueair AB exemplifies Scandinavian manufacturing footprint leverage, while IQAir AG occupies a position among Swiss precision engineering specialists. Daikin Europe N.V. sits within the commercial integration archetype, anchoring deployment through HVAC system capabilities. These three represent distinct strategic postures: regional manufacturing proximity, medical-grade engineering heritage, and building infrastructure integration respectively.
| Leading Market Players |
|---|
| Blueair AB |
| IQAir AG |
| Koninklijke Philips N.V. |
| Daikin Europe N.V. |
| Camfil AB |
| Honeywell International, Inc. |
| Dyson |
| Winix Europe B.V. |
| Boneco AG |
| Others |
Supply & Pricing Matrix
Benelux facility managers consolidating multi-site service agreements anchor pricing power toward vendors bundling filter replacement, sensor calibration, and maintenance subscriptions. Equipment margins compress where standalone unit sales dominate, while integrated service contracts capture recurring value streams independent of hardware transactions.
Pricing Analysis
Warranty and service bundling separates premium positioning from transactional hardware sales across the European market. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and real-time monitoring capability, with medical-grade HEPA configurations commanding substantial premiums over residential portable units. Pricing pressure stems from high-efficiency fan motor costs adding manufacturing burden, compressing margins in price-sensitive Eastern European residential segments where ionizers compete on operating cost alone.
Supply Chain Analysis
Regional distribution centers in Germany and the Netherlands anchor hub-and-spoke patterns serving the broader European market. Glass microfiber feedstock for true HEPA configurations concentrates in German and Dutch manufacturing clusters, while activated carbon media draws from specialized chemical treatment facilities in France and Italy. Single-source vulnerability in glass microfiber production exposes manufacturers to input volatility. Distribution runs through HVAC integrators and building service operators consolidating vendor relationships in Benelux Class A commercial stock.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European indoor air purification market represents a consolidation play as REACH compliance friction and energy efficiency mandates force smaller participants toward exit or acquisition. ECHA's evolving substance restrictions extend product development timelines beyond the capital reserves of undifferentiated competitors.
For Market Incumbents: Deploy backward integration into filter media production to secure glass microfiber supply against raw material volatility. Blueair AB and Daikin Europe N.V. should deepen captive manufacturing capabilities in Scandinavian and German clusters respectively, while accelerating CE marking investment under Ecodesign for Sustainable Products Regulation to outpace compliance-timeline compression affecting weaker rivals.
For New Entrants and Emerging Players: Solid-state UV-C LED convergence with mechanical filtration offers a technology-first wedge into Polish and Romanian commercial stock where centralized air handling penetration sits below fifteen percent. Target educational institutions in Warsaw and Kraków accessing EU renovation funding, positioning duct-integrated retrofit solutions without infrastructure replacement. Channel through facility management service contracts rather than equipment distribution to bypass entrenched HVAC integrator relationships.
For Investors and Strategic Acquirers: The window for entry favors Swiss and German precision engineering specialists with medical-grade certification heritage and clean chemistry capabilities from adjacent water purification segments. Acquisition targets should demonstrate plasma-based surface treatment expertise avoiding REACH nanomaterial thresholds. Watch German hospital network procurement specifications as the inflection indicator, as Bavaria and North Rhine-Westphalia renovation mandates signal pull-through demand intensity for integrated sensor-filtration systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Filter Media Backward Integration | German manufacturers securing glass microfiber supply against input volatility from concentrated feedstock sources. |
| Service Contract Unbundling | Benelux facility managers shifting sixty percent of annual filter spend toward integrated building service operators. |
| UV-C LED Technology Convergence | Solid-state pathogen inactivation enabling retrofit deployment without duct modification in Eastern European commercial stock. |
| Plasma-Based Surface Treatment Migration | Nordic manufacturers leveraging clean chemistry capabilities to avoid REACH nanomaterial registration thresholds. |
| Multi-Site Vendor Consolidation | Amsterdam and Rotterdam Class A office procurement favoring single-source agreements spanning filtration and monitoring. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews conducted across equipment manufacturers, facility management executives, hospital procurement committees, and HVAC system integrators. ECHA REACH substance databases, EU Ecodesign implementing measures, and BREEAM certification scheme documentation provided regulatory boundary conditions. Bottom-up unit shipment estimates triangulated against top-down spending patterns derived from commercial construction permits and healthcare capital expenditure disclosures.
Granularity-level modeling tracked technology type, deployment configuration, end-use vertical, and national regulatory cluster across the projection horizon. CAGRs emerged from segment-level growth rate synthesis validated against replacement cycle assumptions for legacy equipment under EU Green Deal efficiency thresholds. Photocatalytic oxidation adoption curves, UV-C LED cost decline trajectories, and filter media supply concentration indices informed technology transition assumptions.
Several conditions sit outside the modeled scope, including potential revision of ECHA substance restrictions, unanticipated breakthroughs in solid-state disinfection efficiency, and macroeconomic disruption to EU renovation funding flows. Forecasts reflect assumptions regarding regulatory timeline adherence and healthcare procurement specification stability. Periodic stress-testing of base assumptions is recommended given REACH enforcement variability and energy cost volatility affecting high-efficiency fan motor economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Contactless Biometrics Technology Market
Others
Plastic Films and Sheets Market
Others
Global Pumpkin Candles Market
Others
Coalescing Filter Market
Others
Asia-Pacific Adtech Market
Others
Africa Smart Card Market
Others
Middle East and Africa Halal Food & Beverage Market
Others
Metal Ore Mining Market
Others
Fluorite Market
Others
Rotary Union Market
Others
China Packaging Primers Market
Others
Smart-Connected Power Plug Socket Market
Others
Folding Screen Mobile Phone Market
Others
Canada Laser Hair Removal Market
Others
South Korea Automotive LED Lighting Market
Others
United States Printed Signage Market