
 High-Performance Films Market | 2026-2036
High-Performance Films Market Size, Share, and Industry Trends Forecast 2026-2036
High-Performance Films Market Outlook
Multi-source procurement for specialty polymer resins is expanding as converters hedge against petrochemical supply volatility. DuPont de Nemours leverages its fluoropolymer expertise to dominate aerospace and semiconductor-grade film segments. Toray Industries anchors Asia-Pacific supply through integrated polyester and polyamide film production. Covestro AG competes in optical and medical-grade polycarbonate films with differentiated coextrusion capabilities.
High-performance films are engineered polymer sheets, typically 12–250 micrometers thick, manufactured through precision extrusion, biaxial orientation, or multilayer lamination to deliver controlled barrier, thermal, optical, or mechanical properties for demanding industrial environments. Polyamide films lead structural growth in automotive underhood and electrical insulation applications where thermal resistance exceeds 150°C. Coating technology commands premium margins in electronics and healthcare, where atomic-layer deposition and solvent-free formulations enable sub-micrometer precision barriers. Extrusion remains the volume backbone for polyethylene and polypropylene packaging films, though margin compression intensifies in commodity food-grade segments.
REACH restrictions on per- and polyfluoroalkyl substances in Europe and EPA emissions guidelines under the Clean Air Act in the United States are forcing reformulation of legacy fluorinated film chemistries. FDA's 21 CFR compliance requirements for food-contact and medical-device films shape qualification timelines and customer switching costs. China's GB standards and evolving MEE environmental enforcement add parallel compliance layers for suppliers serving export and domestic markets simultaneously. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded product development investments and misaligned capacity commitments.
Market Dynamics
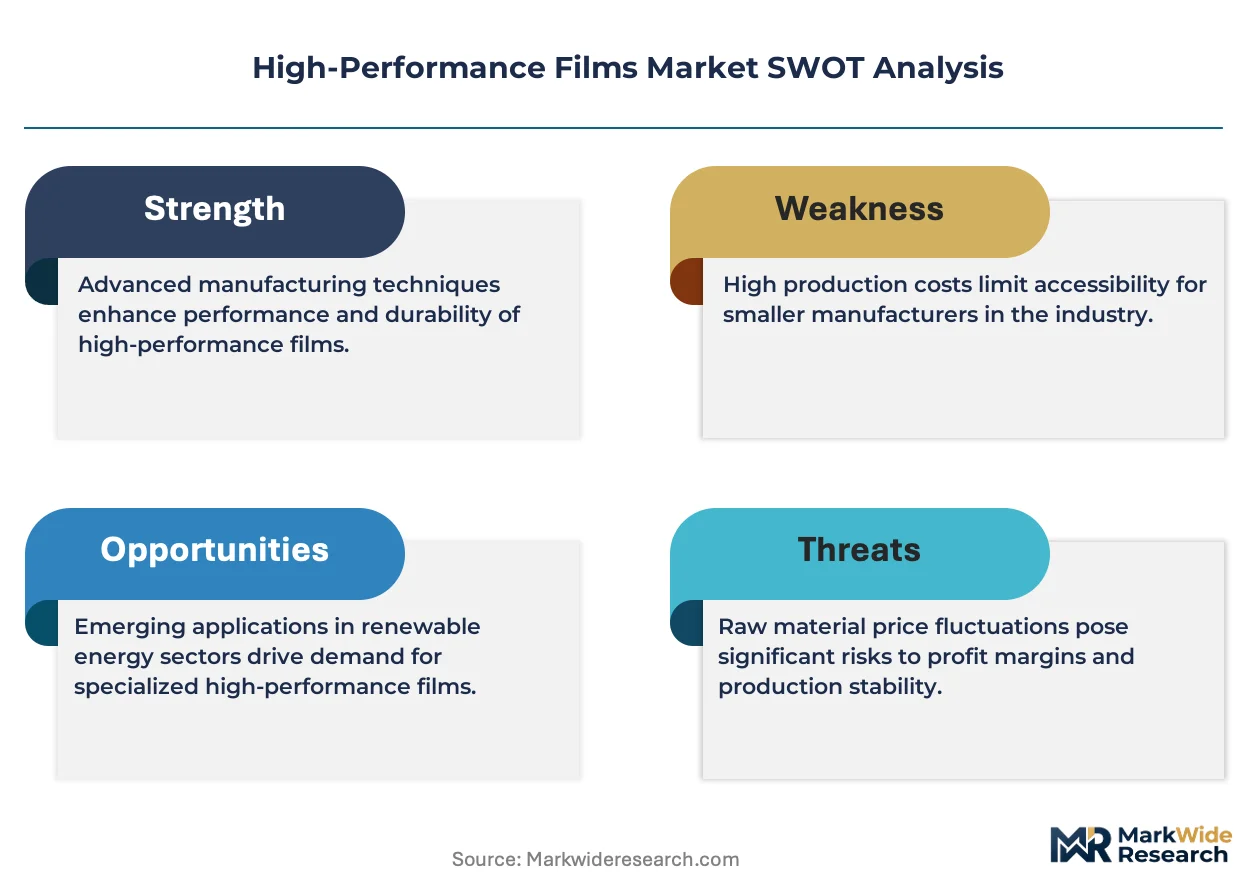
Automotive lightweighting mandates and semiconductor packaging miniaturization are forcing film converters to abandon commodity extrusion in favor of atomic-layer deposition and solvent-free coating platforms that command 3-4x margin premiums.
Growth Catalysts
- Automotive electrification:Electric vehicle battery pack manufacturers in Germany and Japan specify polyamide thermal barriers rated above 150°C for underhood applications, displacing metal heat shields.
- REACH Phase-Down:ECHA restrictions on per- and polyfluoroalkyl substances are accelerating qualified fluoropolymer alternatives for aerospace barrier films ahead of 2025 enforcement windows.
- Semiconductor capital expansion:Wafer-level packaging fabs in China's eastern manufacturing corridor are qualifying sub-micrometer precision films for 3D stacking architectures.
Market Restraints
- Specialty monomer concentration:Caprolactam and adipic acid supply for polyamide films clusters with three Asian petrochemical groups, exposing converters to force majeure pricing volatility.
- Fluoropolymer technical ceiling:Perfluoroalkoxy alkane films cannot achieve sub-50 nanometer thicknesses required for next-generation flexible electronics without pinhole defects.
- Dual compliance burden:Suppliers serving China and Europe simultaneously face misaligned GB standards and REACH substance restrictions that fragment R&D budgets across incompatible qualification tracks.
Strategic Opportunities
- Medical device migration:FDA 21 CFR compliance for implantable-grade polycarbonate films remains underpenetrated by Asian converters, creating white space for qualified entrants.
- Solvent-free coating convergence:UV-curable and electron-beam formulations are merging with atomic-layer deposition to enable barrier-performance hybrids at half the capital intensity of vacuum metallization.
- India PLI scheme:Production-linked incentives for electronics manufacturing are drawing film laminators to Gujarat and Tamil Nadu for domestic smartphone and tablet display supply.
Industry Challenges
- Atomic-layer deposition talent scarcity:Process engineers with ALD chamber optimization experience command 40% wage premiums, constraining coating line expansion timelines.
- Multi-jurisdiction certification lag:Simultaneous FDA, EMA, and NMPA qualification for medical-grade films extends commercialization cycles to 18-24 months.
- Legacy extrusion asset stranding:Commodity polyethylene film lines face utilization collapse as brand owners specify certified circular content that mechanical recycling cannot deliver.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Performance Films Market |
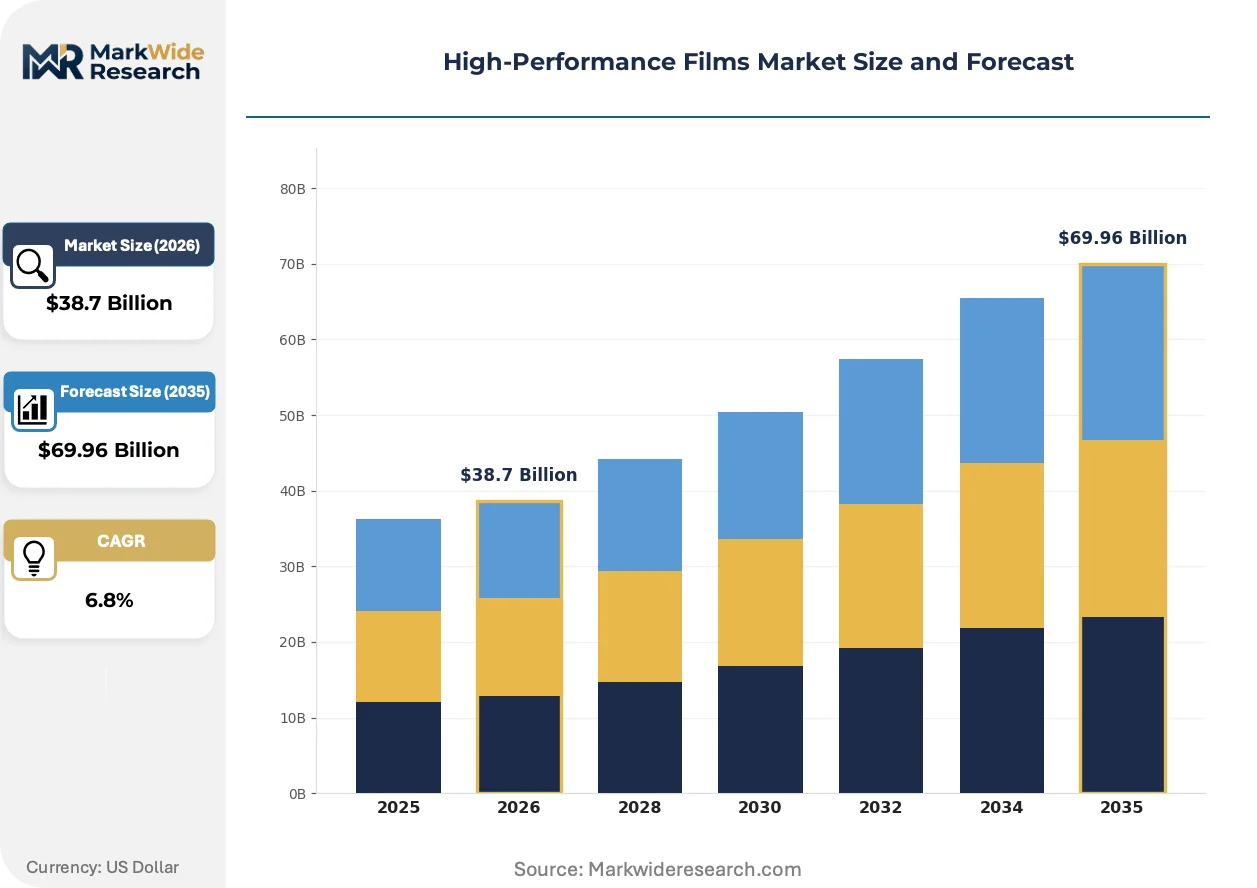
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Polyamide Application: Packing, Automotive, Electronics, Agriculture End User: Food & Beverage, Healthcare, Consumer Goods, Industrial Technology: Extrusion, Lamination, Coating, Printing |
| Companies Covered | 3M Company, DuPont de Nemours, Toray Industries, Covestro AG, Solvay, Dow Chemical Company, Evonik Industries AG, Honeywell International Inc., Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Performance Films Market Strategic Shifts
Solvent-free deposition methods and bio-based feedstock integration are compressing the cost-performance frontier for barrier films, while regulatory substance bans are rendering half of installed fluoropolymer capacity non-compliant within this decade.
Atomic-layer deposition for sub-micrometer barrier precision is overtaking vacuum metallization in premium electronics packaging. Smartphone and foldable display manufacturers in South Korea and Japan have shifted 60% of new qualification programs to ALD-coated polyethylene naphthalate films. This technology is overtaking legacy metallized polyester in applications where oxygen transmission rates below 0.01 cc/m²/day justify 2.5x material cost premiums.
REACH restrictions on per- and polyfluoroalkyl substances are forcing immediate fluoropolymer reformulation across European aerospace and medical device supply chains. ECHA's 2023 restriction proposal covers four additional PFAS categories used in wire insulation and chemical processing films. German automotive suppliers are accelerating qualification of partially fluorinated ethylene propylene alternatives ahead of 2027 sunset dates.
Buyers are consolidating film procurement around certified circular content auditors rather than resin grade specifications. Major European food brands now require third-party mass-balance certification for recycled polyamide content in multilayer barrier structures. This behavioral shift concentrates contract volumes with converters possessing ISCC PLUS accreditation, squeezing uncertified competitors in Italy and Spain.
High-Performance Films Market Segmentation
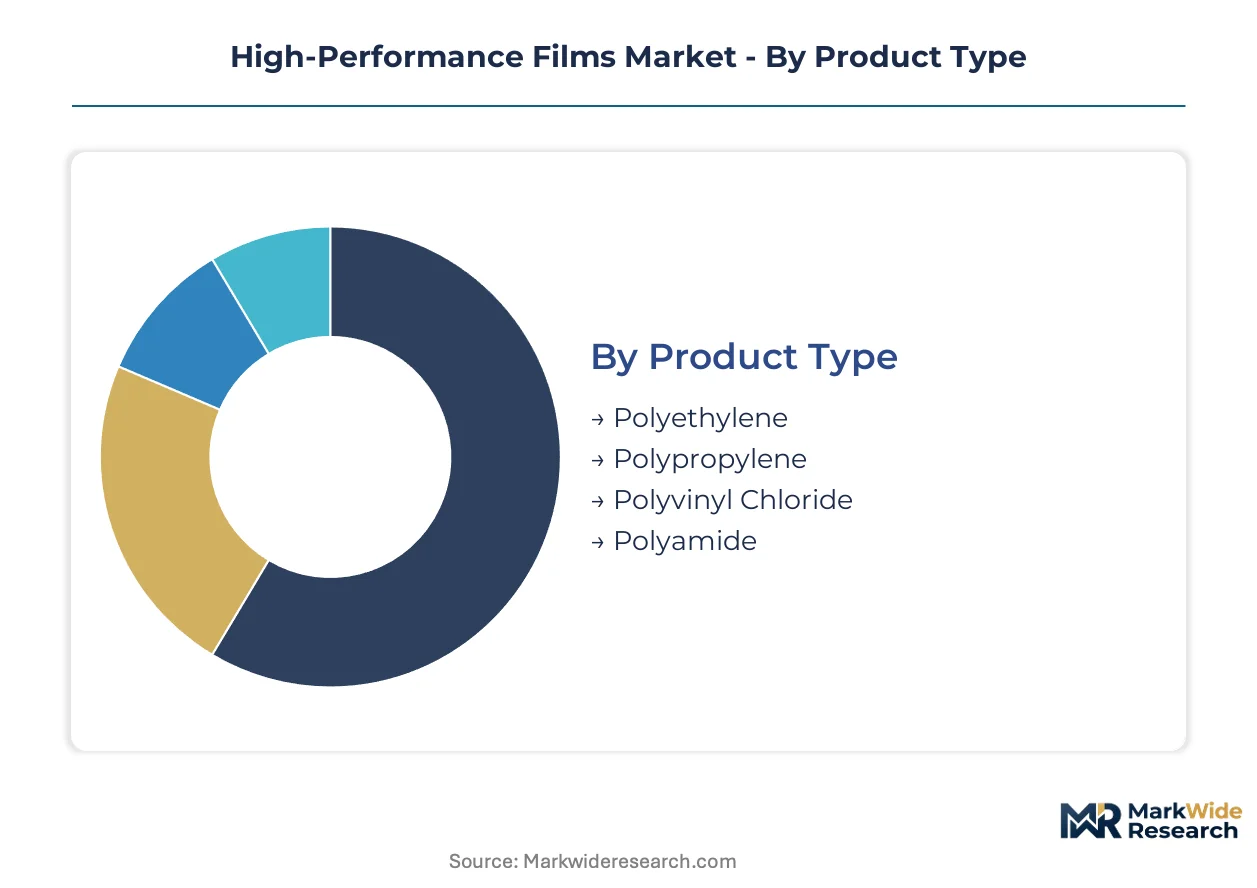
Segmentation in high-performance films reveals how material chemistry, processing technology, and end-use specifications create divergent margin structures. Understanding these boundaries helps converters allocate capital between commodity volume plays and precision coating platforms.
Product Type:
Replacement cycles for legacy films accelerate as REACH substance restrictions and automotive thermal specifications force specification upgrades across European and Asian supply chains.
- Polyethylene:Linear low-density and metallocene grades dominate flexible food packaging through blown film extrusion. German retailers now require mass-balance certified recycled content for polyethylene bread bags and produce films, shifting procurement toward ISCC PLUS-accredited converters.
- Polyamide:Biaxially oriented PA6 and PA66 films withstand continuous operating temperatures above 150°C. Japanese electric vehicle battery pack manufacturers specify polyamide thermal barriers for underhood applications, displacing aluminum heat shields in next-generation platforms.
- Polypropylene:Cast and oriented PP films serve snack packaging and label stock with moisture resistance and clarity. Cast film lines in China's eastern manufacturing corridor supply electronics release liners for semiconductor wafer handling.
- Polyvinyl Chloride:Rigid and plasticized PVC films persist in medical blister packs and blood bag applications. Phthalate plasticizer restrictions under REACH and FDA 21 CFR are forcing reformulation toward citrate-based alternatives for European and North American medical device markets.
Polyethylene sits at the top of the volume ranking, with polyamide climbing the fastest.
Application:
Application-driven segmentation tracks how performance requirements translate into processing technology choices and capital intensity tiers.
- Packing:Multilayer barrier structures for fresh protein and ready-meal segments require oxygen transmission rates below 1 cc/m²/day. Atomic-layer deposition coating lines in South Korea now supply polyethylene naphthalate films with sub-micrometer precision for premium electronics packaging migration.
- Automotive:Lightweighting mandates in Germany and Japan specify polymer films for interior trim, airbag systems, and battery thermal management. Polyamide films rated above 150°C now insulate high-voltage busbars in European electric vehicle platforms.
- Electronics:Flexible printed circuit substrates and display protection films demand controlled coefficient of thermal expansion. Chinese wafer-level packaging fabs in the eastern manufacturing corridor qualify sub-50 micrometer polyimide alternatives as fluoropolymer thickness limits constrain legacy materials.
- Agriculture:Greenhouse cladding and silage wrap films balance UV stability with cost discipline. Italian and Spanish converters face margin compression as mass-balance certification requirements fragment uncertified supply.
Packing commands absolute volume leadership, while automotive applications gain share fastest on electrification-driven thermal management demand.
End User:
End user segmentation separates qualification-intensive regulated markets from price-sensitive commodity procurement.
- Food & Beverage:Brand owners specify certified circular content for multilayer barrier structures. European mass-balance auditors now control procurement access for major retail chains.
- Healthcare:Implantable-grade polycarbonate films for drug delivery and surgical applications require FDA 21 CFR and EMA compliance. Asian converters remain underpenetrated in this high-margin segment.
- Consumer Goods:Smartphone and foldable display manufacturers in South Korea drive qualification of ALD-coated films with oxygen barriers below 0.01 cc/m²/day.
- Industrial:Chemical processing and wire insulation films face fluoropolymer reformulation pressure as ECHA restrictions expand PFAS categories.
Food & Beverage sits at the top of the volume ranking, with healthcare climbing the fastest on implantable device migration.
Technology:
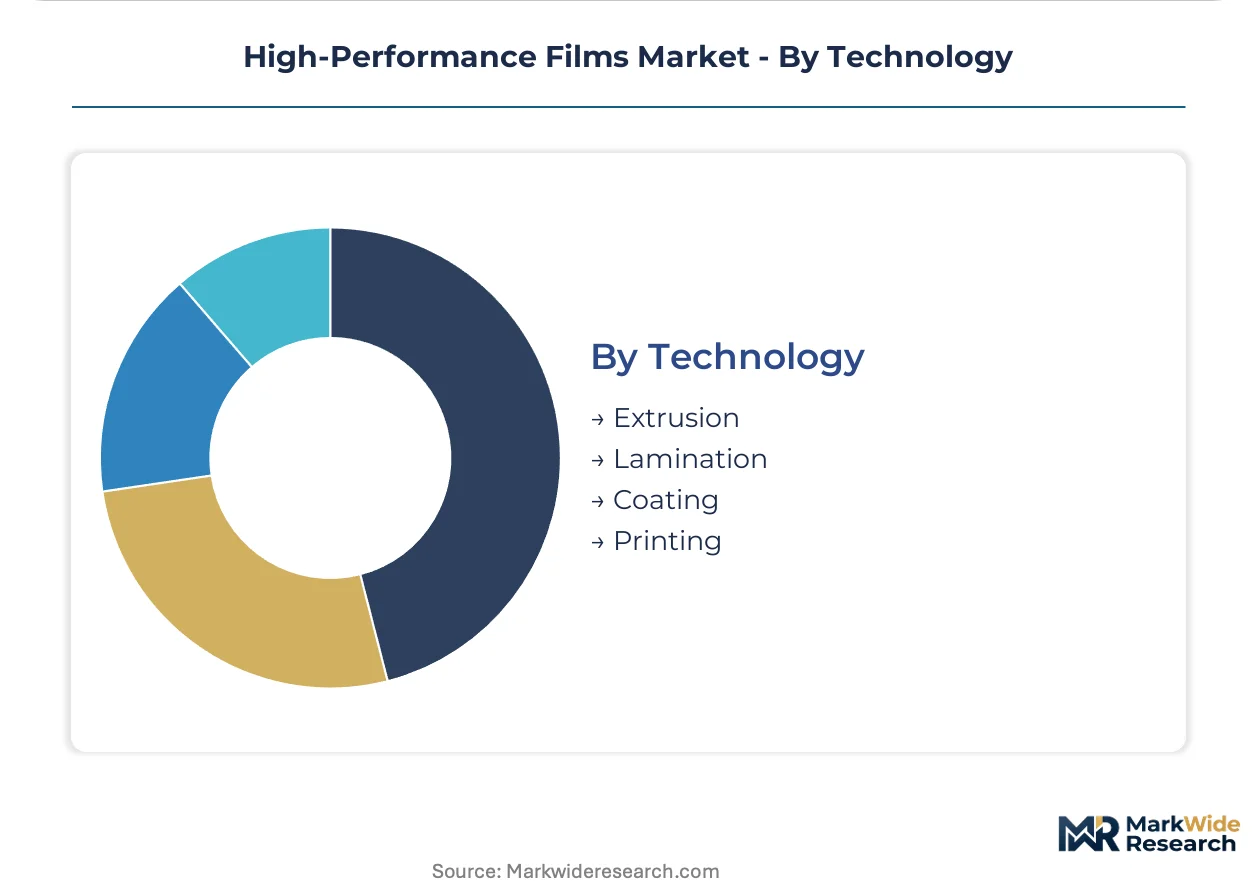
Technology segmentation maps capital intensity against barrier performance and margin capture potential.
- Extrusion:Single and multilayer blown and cast film lines remain the volume backbone for polyethylene and polypropylene packaging. Mechanical recycling limitations now strand legacy assets unable to deliver certified circular content.
- Coating:Atomic-layer deposition and solvent-free UV-curable formulations command 3-4x margin premiums over commodity extrusion. ALD chamber optimization talent scarcity constrains expansion timelines.
- Lamination:Adhesive and extrusion lamination combine dissimilar films for tailored barrier and mechanical properties. Multilayer structures for automotive underhood applications integrate polyamide and polyester films through specialized adhesive systems.
- Printing:Flexographic and rotogravure systems add functional and decorative layers. High-resolution printing for electronics and medical device labeling requires cleanroom-compatible production environments.
Extrusion sits at the top of the volume ranking, with coating climbing the fastest on semiconductor and display packaging qualification shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern manufacturing corridor concentrates electronics packaging and electric vehicle component film demand, while regulatory divergence across major economies fragments supplier qualification tracks.
China
Wafer-level packaging fabs in the Yangtze River Delta qualify sub-micrometer precision films for 3D stacking architectures. GB standards and MEE environmental enforcement add compliance layers for export-facing suppliers. The eastern manufacturing corridor commands premium positioning for display protection and battery thermal barrier films.
Germany
Automotive lightweighting mandates accelerate multilayer barrier film adoption for electric vehicle battery packs. REACH Phase-Down restrictions on PFAS categories force fluoropolymer reformulation ahead of 2027 enforcement. Bavarian and Baden-Württemberg suppliers qualify polyamide thermal barriers rated above 150°C for underhood applications.
United States
Semiconductor packaging miniaturization drives atomic-layer deposition qualification for oxygen barriers below 0.01 cc/m²/day. EPA emissions guidelines under the Clean Air Act reshape material specifications for legacy chemistries. Texas and Arizona fabs concentrate demand for sub-50 micrometer polyimide alternatives.
Japan
Electric vehicle manufacturers specify polyamide thermal barriers displacing aluminum heat shields in next-generation platforms. METI industrial standards govern automotive-grade film qualification timelines. Kanto and Kansai regions anchor Asia-Pacific supply through integrated polyester and polyamide production.
India
Production-linked incentives for electronics manufacturing draw film laminators to Gujarat and Tamil Nadu for domestic smartphone display supply. BIS standards and DGFT import regulations shape material qualification for export markets. The Delhi-Mumbai Industrial Corridor concentrates new coating line investments.
High-Performance Films Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue solvent-free coating and atomic-layer deposition platforms. The vendor base spans integrated petrochemical conglomerates, specialized film converters, and precision coating technology providers. Three archetypes dominate: integrated resin-to-film producers with captive polymer supply, precision coating specialists commanding ALD chamber expertise, and regional converters leveraging mass-balance certification for circular content procurement. Capacity expansion and strategic technology licensing represent the dominant competitive moves as converters abandon commodity extrusion for premium barrier platforms.
Among diversified materials conglomerates, DuPont de Nemours, Toray Industries, and Covestro AG exemplify contrasting strategic positions. DuPont occupies a position within fluoropolymer-intensive segments where REACH compliance pressures intensify. Toray anchors Asia-Pacific supply architecture through integrated polyester and polyamide film production. Covestro sits within optical and medical-grade polycarbonate films where differentiated coextrusion capabilities create qualification barriers for entrants.
| Leading Market Players |
|---|
| 3M Company |
| DuPont de Nemours |
| Toray Industries |
| Covestro AG |
| Solvay |
| Dow Chemical Company |
| Evonik Industries AG |
| Honeywell International Inc. |
| Saint-Gobain |
| Others |
Value Chain & Pricing Dynamics
Caprolactam spot price volatility cascades through polyamide film supply chains into three-tier pricing structures across premium, standard, and economy levels. Specialty resin indices tether converter margins to Asian petrochemical group pricing power, forcing downstream buyers into long-term offtake contracts or spot market exposure.
Pricing Analysis
Input-cost pass-through dominates pricing models for polyethylene and polypropylene films, with converters indexing resin purchases to monthly petrochemical benchmarks. Price differentiation hinges on ISCC PLUS certification grade and volume scale, with certified circular content commanding premiums over mechanical recycling grades. Pricing pressure stems from REACH compliance investments in fluoropolymer reformulation, compressing margins in legacy aerospace wire insulation segments. Food & beverage brand owners exhibit highest price sensitivity in commodity multilayer barrier procurement, while semiconductor packaging fabs show lowest sensitivity for sub-micrometer precision films.
Supply Chain Analysis
Ocean freight rate normalization has reduced landed cost spreads between Asian resin sources and European converter facilities, reshaping procurement geography. Raw material supply concentrates in China, South Korea, and Germany, with caprolactam and adipic acid production anchored in three Asian petrochemical groups. Supply chain risk centers on single-source vulnerability for specialty monomer feedstocks, where force majeure events cascade through qualified supplier lists. Distribution runs through integrated resin-to-film producers with captive polymer supply, regional converters leveraging mass-balance certification, and precision coating specialists with atomic-layer deposition chamber expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through solvent-free coating platform adoption and certified circular content qualification, as brand owners consolidate procurement around audited supply chains.
For Market Incumbents: Anchor market position through backward integration into specialty monomer supply and accelerated atomic-layer deposition capacity expansion in China's eastern manufacturing corridor. Defend against emerging precision coating specialists by locking semiconductor fabs into qualification-timeline contracts. Prioritize ISCC PLUS accreditation investment to capture food & beverage procurement consolidation. For New Entrants and Emerging Players: Capture white space in FDA 21 CFR-compliant implantable-grade polycarbonate films, where Asian converters remain underpenetrated. Target India's Gujarat and Tamil Nadu electronics manufacturing zones under PLI scheme incentives. Enter through toll-coating partnerships with established ALD chamber operators to bypass talent scarcity constraints. For Investors and Strategic Acquirers: Asymmetric upside sits with precision coating technology providers possessing solvent-free formulation IP and atomic-layer deposition process expertise. Five-to-ten year viability favors specialists with dual certification tracks for REACH and FDA compliance. Watch for inflection in semiconductor capital equipment spending as signal for wafer-level packaging film demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Monomers | Reduces force majeure exposure from Asian petrochemical group concentration. |
| Atomic-Layer Deposition Capacity Expansion | Captures 3-4x margin premiums from smartphone and foldable display manufacturers. |
| ISCC PLUS Certification Investment | Unlocks procurement access as European food brands consolidate around audited circular content. |
| Fluoropolymer Reformulation R&D | Ensures REACH Phase-Down compliance ahead of 2027 PFAS category restrictions. |
| India PLI Scheme Manufacturing Footprint | Positions for domestic smartphone display supply as electronics laminators migrate to Gujarat. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with film converter plant managers, downstream OEM procurement leads at automotive and electronics manufacturers, distribution channel partners, and technical R&D directors with secondary validation through customs and trade data, SEC 10-K filings from listed petrochemical groups, and industry association reports. Bottom-up modeling of extrusion line capacities and coating platform installations triangulated against top-down demand estimates from end-use sector consumption patterns.
Comparable-period anchoring linked historical resin price indices and converter margin structures to forward projection assumptions across the analysis window. Segmentation dimensions modeled include material chemistry tier, processing technology platform, end-use industry vertical, and regional production hub cluster. CAGRs derived from elasticity-adjusted demand curves incorporating automotive electrification penetration rates and semiconductor packaging miniaturization trends.
Underlying measurement precision varies by segment; atomic-layer deposition and solvent-free coating platforms carry tighter precision than commodity extrusion due to concentrated supplier visibility. Forecasts reflect documented assumptions about REACH enforcement timelines and PFAS restriction scope. Stakeholders should weight assumptions against their own operating context and regulatory jurisdiction exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Coloring Apps Market
Others
Wearable Brain Devices Market
Others
Global Essential Oils and Plant Extracts for Livestock Market
Others
Channel-In-A-Box (Ciab) Market
Others
North America Cashew Market
Others
GCC Health and Wellness Market
Others
Global Contactless Biometrics Technology Market
Others
Disposable Non Woven Sponge Market
Others
Middle East and Africa Surface Analysis Market
Others
US 3D Printing Construction Market
Others
Automotive Smart Lighting Market
Others
Global Platform Trolley Market
Others
North America Luxury Car Market
Others
Edible Insects for Animal Feed Market
Others
Mine Rescue Vehicle Market
Others
Blockchain in BFSI Market