
 Military Wearable Market | 2026-2036
Military Wearable Market Size, Share, and Industry Trends Forecast 2026-2036
Military Wearable Market Analysis
The US Department of Defense's updated MIL-STD-810H testing protocols is restructuring supplier qualification timelines for military wearable vendors. BAE Systems plc leverages its UK-US dual manufacturing footprint to sustain rapid certification cycles across Atlantic supply chains. Elbit Systems Ltd. specializes in helmet-mounted display architectures that anchor Israeli Defense Forces modernization programs. Rheinmetall AG competes through its Bundeswehr-focused exoskeleton development pipeline in Germany.
Military wearables encompass soldier-borne electronic and mechanical systems engineered to MIL-STD-810H environmental resilience thresholds, typically integrating ballistic protection substrates with power-distribution fabrics weighing under five kilograms for dismounted operations. Their primary purpose centers on enhancing individual combatant situational awareness, physiological endurance, and command connectivity without mobility degradation. Smart Helmets represent the most mature revenue pool given established night-vision and heads-up display retrofit cycles across Western militaries. Exoskeletons occupy the fastest-expansion trajectory as load-bearing reduction specifications harden in US Army infantry brigade requirements. Biometric Sensors concentrate margin capture through sole-source health-monitoring contracts tied to veteran affairs rehabilitation protocols.
The US Department of Defense, NATO Standardization Office, and EMA's dual-use medical device frameworks collectively shape procurement eligibility, export licensing, and data-handling compliance for cross-border wearable deployments. FDA clearance pathways for battlefield trauma monitors increasingly determine which biometric platforms qualify for joint-service adoption. Stakeholders must monitor how NATO's next STANAG revision treats encrypted physiological data streams as classified information assets rather than routine logistics signals.
Market Dynamics
Special operations procurement cycles are compressing vendor qualification windows while MIL-STD-810H protocol updates force simultaneous hardware redesigns across multiple program offices.
Growth Catalysts
- Biometric-integrated tactical gear:NATO member states are accelerating sole-source contracts for physiological monitoring systems that stream encrypted health data to command nodes.
- US Army Futures Command modernization:Infantry brigade requirements now mandate load-bearing reduction specifications that drive exoskeleton pilot programs.
- FDA clearance pathways:Battlefield trauma monitors with dual-use medical device status qualify for joint-service adoption under veteran affairs rehabilitation protocols.
Market Restraints
- Power-distribution fabric supply concentration:Specialized conductive textile manufacturing clusters in limited geographies create single-source vulnerabilities for systems under five kilograms.
- MIL-STD-810H testing backlog:Updated environmental resilience protocols extend supplier qualification timelines by 8-14 months for new entrants.
- Night-vision retrofit substitution:Established smart helmet upgrade cycles face pressure from uncooled thermal imaging alternatives in dismounted operations.
Strategic Opportunities
- EMA dual-use medical device frameworks:European regulatory harmonization creates expedited market entry for biometric sensor platforms with civilian trauma applications.
- Helmet-mounted display convergence:Augmented reality overlays for navigation and targeting are penetrating Israeli Defense Forces modernization programs ahead of Western adoption curves.
- Direct program office contracting:Special Operations Command equipment refresh cycles are bypassing traditional prime contractor layers for specialized subsystem vendors.
Industry Challenges
- Encrypted data stream classification:NATO STANAG revision debates treat physiological telemetry as classified information assets, complicating cross-border logistics signal handling.
- Ballistic protection substrate integration:Combining environmental resilience with power distribution requires rare composite engineering expertise concentrated in defense-adjacent materials labs.
- Legacy command connectivity protocols:New wearable architectures must backward-integrate with fielded radio networks without mobility degradation penalties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Wearable Market |
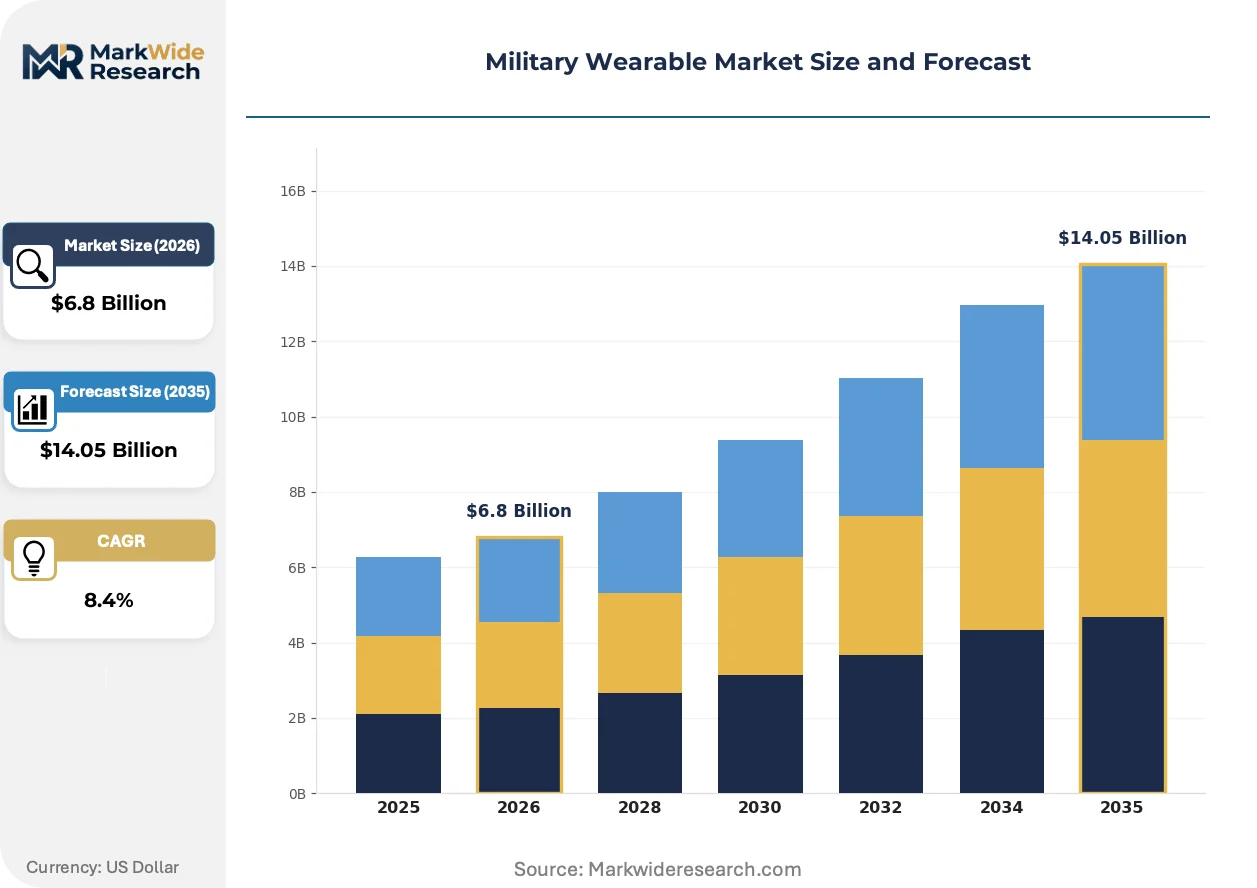
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Helmets, Tactical Vests, Body Cameras, Exoskeletons Technology: Augmented Reality, GPS Tracking, Biometric Sensors, Communication Systems Application: Surveillance, Combat Training, Health Monitoring, Mission Planning End User: Military Forces, Defense Contractors, Government Agencies, Research Institutions |
| Companies Covered | BAE Systems plc, Lockheed Martin Corporation, Thales Group, Elbit Systems Ltd., Rheinmetall AG, Saab AB, L3Harris Technologies Inc., General Dynamics Corporation, Aselsan A.S., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Wearable Market Emerging Trajectories
Active convergence between soldier-borne electronics and medical-grade monitoring is dissolving traditional boundaries between tactical gear and health infrastructure.
Power-distribution fabric technology is converging with ballistic protection substrates to create single-layer systems that eliminate redundant weight penalties. US Army infantry brigades are field-testing these integrated textiles in load-bearing vests under eight-week evaluation windows. The structural consequence is converging with procurement timelines as program offices abandon separate power and armor contracts for unified subsystem awards.
EMA's evolving stance on battlefield trauma monitors as dual-use medical devices is forcing hardware redesigns toward FDA-equivalent validation standards. Manufacturers must now document clinical-grade accuracy for heart-rate and blood-oxygen sensors intended for combat deployment. Israeli Defense Forces procurement channels are responding fastest, embedding civilian medical certification teams within their modernization offices.
Special operations forces are consolidating vendor relationships around firms capable of Atlantic-spanning manufacturing footprints. Buyers now demand simultaneous US and European certification cycles to hedge against single-qualification delays. This concentration is most visible in UK-US dual-source arrangements where BAE Systems plc and similar entities leverage transatlantic production nodes.
Military Wearable Market Segmentation
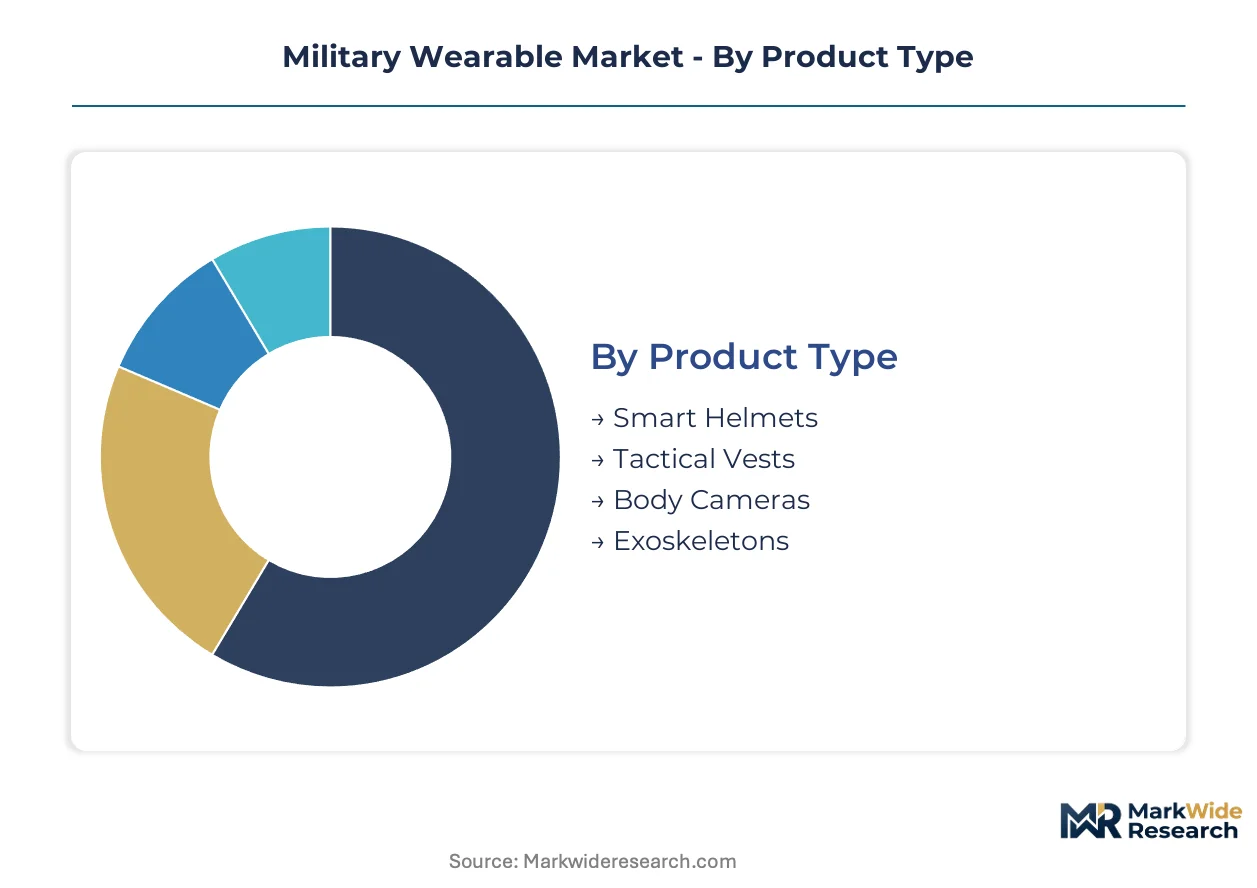
Military wearable procurement splits across mission-critical hardware, enabling technologies, operational use cases, and institutional buyers. Each dimension carries distinct certification requirements and budget cycles that reshape vendor positioning.
Product Type:
Standardization dominates helmet and vest platforms while exoskeletons remain customized to unit specifications.
- Smart Helmets:These integrate night-vision mounts, heads-up displays, and ballistic protection rated to NIJ Level IIIA. US Army infantry brigades drive replacement cycles through established retrofit programs, though uncooled thermal imaging alternatives now pressure upgrade timelines.
- Exoskeletons:Powered and passive load-bearing frames reduce musculoskeletal strain during dismounted operations. US Army Futures Command mandates load reduction specifications that accelerate pilot programs across NATO special operations forces.
- Tactical Vests:Modular platforms combining ballistic substrates with power-distribution fabrics under five kilograms.
- Body Cameras:Ruggedized recording devices with encrypted chain-of-custody protocols for evidence collection.
Most installed capacity flows through Smart Helmets. Expansion is steepest in Exoskeletons.
Technology:
Mature GPS and communication systems yield to biometric and AR platforms with steeper development curves.
- Biometric Sensors:Physiological monitors stream encrypted heart-rate, hydration, and stress indicators to command nodes. NATO member states are accelerating sole-source contracts for these systems, with FDA clearance pathways determining joint-service eligibility under veteran affairs rehabilitation protocols.
- Augmented Reality:Helmet-mounted overlays project navigation waypoints and targeting data within the operator's field of view. Israeli Defense Forces modernization programs are penetrating this technology ahead of Western adoption curves through embedded civilian medical certification teams.
- GPS Tracking:Precision positioning with anti-jamming countermeasures for dismounted situational awareness.
- Communication Systems:Software-defined radios and mesh networking protocols for squad-level connectivity.
Biometric Sensors capture the highest margins through sole-source health-monitoring contracts. Augmented Reality is gaining share fastest as display architectures mature.
Application:
Surveillance and training applications leverage commercial-off-the-shelf components while health monitoring requires medical-grade validation.
- Health Monitoring:Continuous physiological telemetry for casualty prevention and post-mission rehabilitation. EMA dual-use medical device frameworks are expediting European market entry for platforms with civilian trauma applications, forcing hardware redesigns toward FDA-equivalent standards.
- Surveillance:Sensor fusion for perimeter security and reconnaissance operations.
- Combat Training:After-action review systems with biometric feedback for performance optimization.
- Mission Planning:Wearable access to distributed command-and-control networks.
Surveillance deploys the widest installed base. Health Monitoring shows the steepest expansion trajectory as NATO STANAG revisions treat physiological data as classified assets.
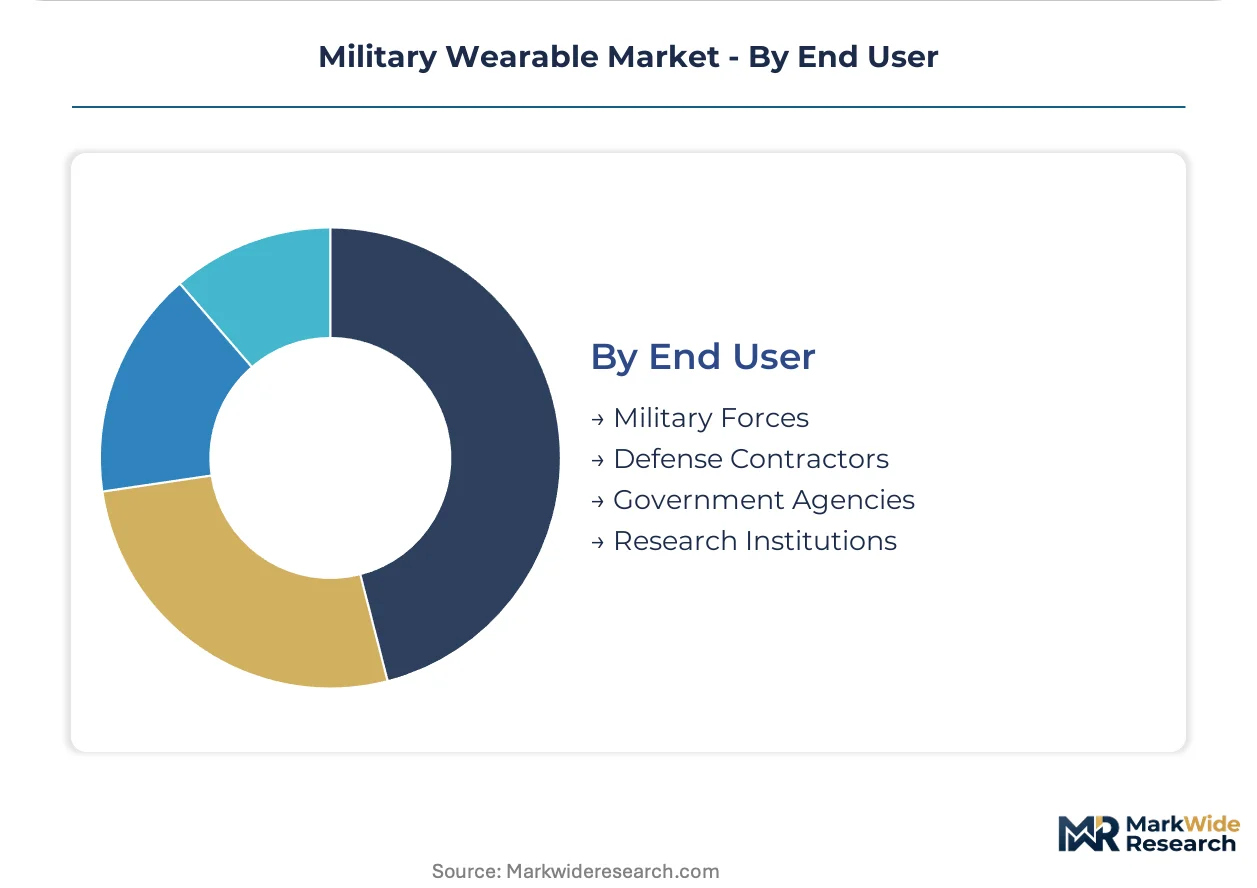
End User:
Defense contractors concentrate demand for subsystem integration while government agencies drive standardization.
- Military Forces:Operational units across NATO member states with compressed procurement cycles for special operations equipment. Special Operations Command refresh cycles are bypassing traditional prime contractor layers for specialized subsystem vendors.
- Defense Contractors:System integrators assembling wearable subsystems into platform-level solutions.
- Government Agencies:Non-military security services and border enforcement units with lighter certification requirements.
- Research Institutions:Testbed environments for emerging exoskeleton and biometric architectures.
Military Forces absorb the majority of procurement volume. Defense Contractors are expanding most quickly as program offices consolidate vendor relationships around Atlantic-spanning manufacturing footprints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense engineering talent clusters in the United States, Israel, and Germany anchor military wearable development. These concentrations sustain specialized manufacturing nodes that feed NATO procurement pipelines. Cross-border certification demands now favor vendors with dual-Atlantic production footprints.
United States
Army Futures Command modernization and Special Operations Command refresh cycles drive procurement volume. MIL-STD-810H testing protocols from the Department of Defense extend supplier qualification timelines. Huntsville, Alabama and Boston-Cambridge defense corridors concentrate subsystem integration facilities for biometric-integrated tactical gear.
Germany
Bundeswehr exoskeleton development and NATO standardization alignment shape demand patterns. EMA dual-use medical device frameworks expedite biometric sensor platforms with civilian trauma applications. Bavaria's defense-industrial cluster around Munich hosts Rheinmetall AG's load-bearing frame engineering operations.
Israel
Israeli Defense Forces modernization programs penetrate helmet-mounted display architectures ahead of Western curves. Embedded civilian medical certification teams accelerate FDA-equivalent validation standards. Tel Aviv and Haifa technology corridors concentrate augmented reality overlay development for navigation and targeting systems.
United Kingdom
UK-US dual manufacturing footprints sustain rapid certification cycles across Atlantic supply chains. Ministry of Defence procurement aligns with NATO STANAG revisions on encrypted physiological data classification. South England defense corridors around Portsmouth and Bristol anchor transatlantic production nodes.
South Korea
MFDS regulatory pathways and export-oriented defense industrialization expand manufacturing capacity. Biometric sensor integration for allied military health monitoring contracts attracts subsystem vendors. Seoul Capital Area and Busan-Ulsan corridors develop power-distribution fabric manufacturing for under-five-kilogram tactical vest specifications.
Military Wearable Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across subsystem tiers. Market structure shows moderate consolidation around prime contractors with Atlantic-spanning footprints, while specialized biometric and exoskeleton vendors occupy niche positions. Three archetypes dominate: systems integrators with dual-continental certification capabilities, pure-play wearable subsystem developers, and defense-electronics conglomerates with helmet-mounted display portfolios. Competitive moves concentrate on strategic partnerships for MIL-STD-810H testing access and geographic expansion into EMA-aligned regulatory jurisdictions.
Within the systems integrator tier, BAE Systems plc and Lockheed Martin Corporation represent dual-manufacturing-footprint archetypes that sustain rapid Atlantic certification cycles. Elbit Systems Ltd. exemplifies the specialist vector with concentrated helmet-mounted display architecture development. These three entities occupy positions that align with Israeli Defense Forces and US Army program office procurement patterns.
| Leading Market Players |
|---|
| BAE Systems plc |
| Lockheed Martin Corporation |
| Thales Group |
| Elbit Systems Ltd. |
| Rheinmetall AG |
| Saab AB |
| L3Harris Technologies Inc. |
| General Dynamics Corporation |
| Aselsan A.S. |
| Others |
Supply Flow & Price Mechanics
Power-distribution fabric integration with ballistic protection substrates is compressing unit economics while concentrating manufacturing among vendors with composite engineering capabilities. This convergence eliminates redundant material layers but raises qualification barriers that reshape pricing power across the supplier base.
Pricing Analysis
Bundled subsystem contracts now dominate unbundled component sales as program offices consolidate power and armor procurement. Pricing stratifies across MIL-STD-810H certification tiers, with FDA-cleared biometric platforms commanding substantial premiums over tactical-only alternatives. Cost compression in smart helmet retrofits is intensifying because uncooled thermal imaging substitutes erode upgrade cycle pricing. Defense contractors exhibit highest price sensitivity due to fixed-bid integration contracts, while special operations units prioritize performance over unit cost.
Supply Chain Analysis
Freight cost volatility for specialized conductive textiles is amplifying geographic sourcing constraints across Atlantic supply chains. Manufacturing concentrates in the United States, Germany, and South Korea, with Bavaria and Seoul Capital Area anchoring power-distribution fabric production. Raw material dependencies span aramid fibers, lithium-ion cells, and rare-earth magnets for exoskeleton actuators. Single-source vulnerability pervades conductive textile weaving capacity certified to military specifications. Distribution runs through prime contractor integration facilities rather than direct-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through biometric sensor premiumization and exoskeleton load-reduction specifications that justify higher unit economics. Power-distribution fabric consolidation is driving cost-down opportunities for integrated vest platforms.
For Market Incumbents: Anticipate compressed qualification windows by pre-certifying subsystems across multiple NATO STANAG revisions before formal mandate release. Backward integration into conductive textile weaving secures supply continuity against single-source vulnerabilities. Establish dual-Atlantic production nodes to hedge against MIL-STD-810H testing backlog delays that disadvantage single-qualification competitors. For New Entrants and Emerging Players: Defense contractors seeking subsystem integration partners represent the most penetrable channel for bypassing traditional prime contractor layers. Target Israeli Defense Forces modernization programs where embedded civilian medical certification teams accelerate FDA-equivalent validation timelines. Pursue direct Special Operations Command equipment refresh contracts rather than tiered prime-subcontractor structures. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play biometric sensor developers lacking Atlantic-spanning manufacturing footprints. Long-term viability hinges on EMA dual-use medical device framework alignment that opens European procurement channels. Watch for NATO STANAG revision finalization on encrypted physiological data classification as the inflection signal for health-monitoring contract eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| MIL-STD-810H Pre-Certification Investment | BAE Systems plc leverages dual UK-US manufacturing to sustain rapid Atlantic certification cycles. |
| Biometric Sensor FDA Clearance Pathway | Dual-use medical device status unlocks joint-service adoption under veteran affairs rehabilitation protocols. |
| Conductive Textile Backward Integration | In-house power-distribution fabric production eliminates single-source supply vulnerabilities for under-five-kilogram systems. |
| Helmet-Mounted Display Convergence | Elbit Systems Ltd. anchors Israeli Defense Forces modernization with augmented reality overlay architectures. |
| Direct Program Office Contracting | Special Operations Command refresh cycles bypass prime contractor layers for specialized subsystem vendors. |
Methodological Framework
Multiple input streams — procurement officer interviews, program office budget documentation, and subsystem vendor technical disclosures — were reconciled against secondary validation. Primary fieldwork engaged military equipment program managers, defense contractor integration leads, biomedical certification specialists, and GSA contracts officers. Secondary sources encompassed DoD budget justification materials, NATO standardization office publications, FDA 510(k) clearance databases, and EMA medical device guidance documents. Bottom-up unit economics and top-down defense expenditure allocations were cross-referenced for triangulation.
Historical program office award patterns were cross-referenced against expert panel input on modernization timeline acceleration. Segmentation modeling spanned product type, technology maturity, application criticality, and end-user procurement authority across the projection horizon. CAGRs were derived from fitted growth curves calibrated to disclosed program office spending profiles. Exoskeleton pilot program conversion rates and biometric sensor sole-source contract renewal patterns served as industry-specific forecast anchors.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NATO STANAG revision timing and EMA dual-use regulatory harmonization pace. Assumptions reflect disclosed program office priorities rather than speculative threat environment shifts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Bitcoin Mining Servers Market
Others
Canada 3D Printing Construction Market
Others
Belt Loader Market
Others
Process Spectroscopy Market
Others
Digital LUX Meter Market
Others
US Tablet Market
Others
Gem Faceting Machine Market
Others
Asia Pacific Contract Packaging Market
Others
Corn Fiber Market
Others
Global Lavender Extracts Market
Others
Linseed Oil Market
Others
Depth Gauge Market
Others
Global Personal Care Packaging Market
Others
Europe Astrology Market
Others
Biopharma Plastics Market
Others
Space Cables Market