
 Photo Booth Market | 2026-2036
Photo Booth Market Size, Share, and Industry Trends Forecast 2026-2036
Photo Booth Market Analysis
Chinese component suppliers is rebalancing global photo booth manufacturing capacity as domestic labor costs climb. Photo Booth International leverages vertically integrated mirrorless camera sourcing to sustain margin stability across North American distribution. Photobooth Supply Co. anchors its position through proprietary enclosure designs that differentiate hardware from commodity open-air alternatives. Faceplace dominates European event rental channels through direct venue partnerships that control placement density in major metropolitan markets.
A photo booth is a self-service photography station comprising a digital camera, touchscreen interface, instant dye-sublimation printer, and LED lighting array housed within a freestanding enclosure or open-air rig, designed to capture and output branded or personalized images at commercial and social venues. Open-air configurations lead volume sales due to lower shipping costs and flexible footprint deployment, while 360-degree booths command premium rental rates at festivals and brand activations where immersive content generation drives repeat bookings. Enclosed booths retain stable demand from wedding planners seeking private capture environments, whereas photo pods occupy a shrinking niche constrained by limited customization depth relative to full-featured alternatives.
FCC certification governs radio-frequency emissions from wireless photo transmission modules in the United States, while CE marking mandates electrical safety compliance for equipment sold across European Union member states. GDPR constraints shape social media integration features by requiring explicit consent workflows before facial data uploads to cloud platforms. Event planners and equipment lessors must monitor evolving battery transportation regulations from IATA and local fire codes as lithium-powered mobile booth deployments expand into outdoor festival environments.
Market Dynamics
Mirrorless camera migration and instant dye-sublimation print technology are compressing equipment replacement cycles while redefining performance benchmarks across wedding, corporate, and festival deployment channels.
Growth Catalysts
- FCC Part 15 Certification:Wireless photo transmission modules in the United States now operate under streamlined radio-frequency emission protocols, accelerating mobile booth deployments at outdoor venues without site-specific engineering reviews.
- Social-First Event Design:Wedding planners and brand activation teams now specify instant shareable content as a mandatory deliverable, pulling cloud-integrated hardware into standard procurement packages.
- LED Array Efficiency Gains:Solid-state lighting modules have reduced enclosure power draw by half, enabling battery-powered festival installations previously constrained by generator logistics.
Market Restraints
- Lithium Battery Transportation:IATA Dangerous Goods regulations and evolving local fire codes impose documentation burdens and shipping surcharges on mobile booth operators deploying to multi-day outdoor events.
- Chinese Component Concentration:Mirrorless camera sensors, dye-sublimation print heads, and touchscreen controllers concentrate sourcing in Shenzhen and Dongguan manufacturing clusters, exposing margins to tariff volatility and logistics congestion.
- GDPR Facial Data Constraints:Explicit consent workflows for cloud uploads add friction to social media integration features, compressing user adoption rates in European Union event deployments relative to North American benchmarks.
Strategic Opportunities
- Underpenetrated Indian Wedding Market:Tier-2 and Tier-3 cities in Maharashtra and Gujarat show rising demand for photo booth rentals at pre-wedding functions, with local event planners seeking hardware-as-a-service models over capital purchases.
- AI-Powered Background Replacement:Real-time chroma-key automation without physical green screens is converging with gesture-triggered capture, opening premium pricing tiers for brand activations requiring immersive environments.
- Australian Outdoor Festival Circuit:Dust-resistant IP65-rated enclosures and solar-battery hybrid power systems address placement gaps at remote regional events underserved by grid-dependent equipment.
Industry Challenges
- Dye-Sublimation Technician Scarcity:Maintenance of print head calibration and thermal transfer ribbon replacement requires specialized skills rarely found in general AV rental technician pools, extending equipment downtime at critical event windows.
- Multi-Certification Timelines:Simultaneous FCC, CE marking, and Australian RCM compliance for wireless transmission modules stretches product launch schedules by eight to fourteen months for hardware developers targeting cross-border distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photo Booth Market |
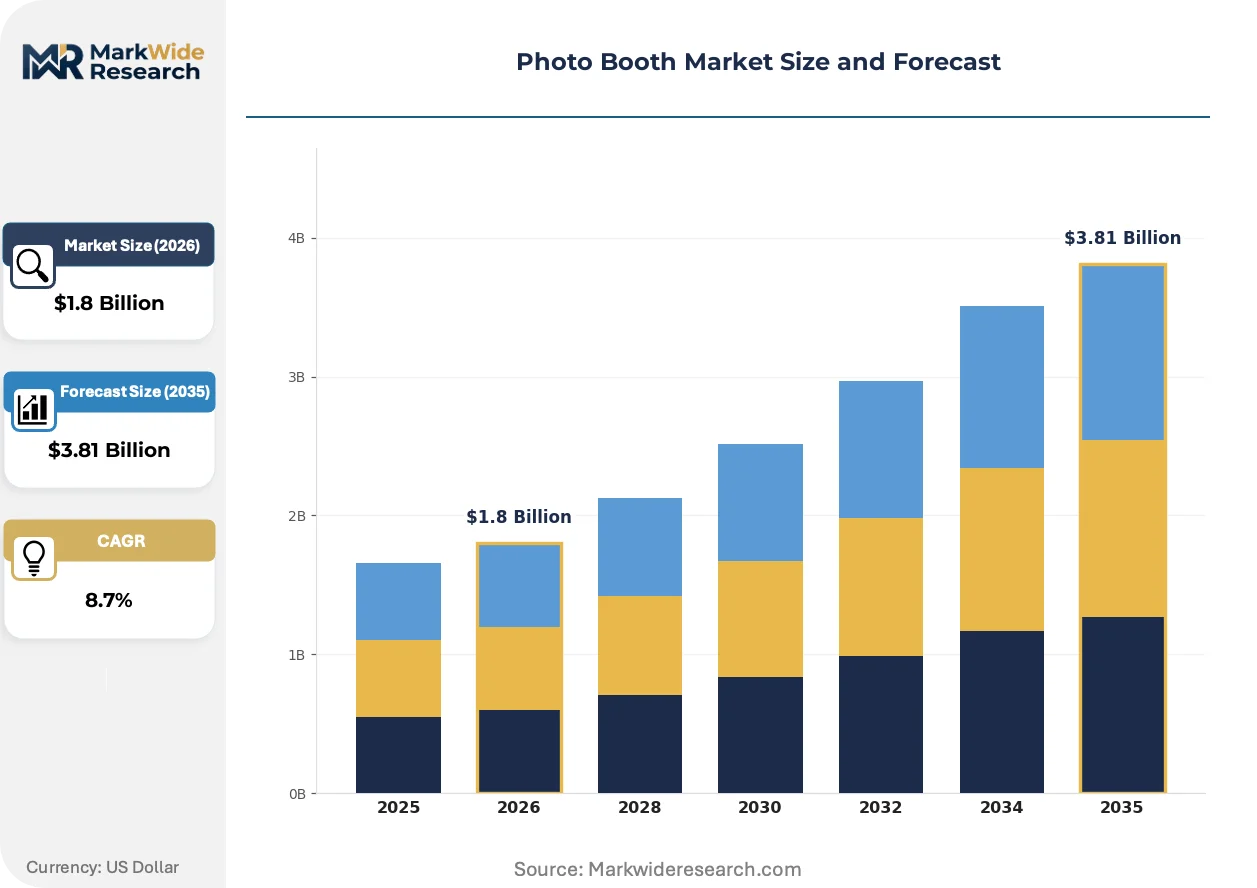
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Air, Enclosed Booth, 360-Degree Booth, Photo Pod Application: Weddings, Corporate Events, Birthday Parties, Festivals Technology: Digital Cameras, Instant Print, GIF Creation, Social Media Integration End User: Event Planners, Businesses, Schools, Nonprofits |
| Companies Covered | Faceplace, Photo Booth International, Photobooth Supply Co., Extreme Booths, Photo Me, Digital Centre, Kindom Photo Booth, Open Air Photobooth, Dream Booth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photo Booth Market Emerging Trajectories
Automation of capture workflows and regulatory pressure on data handling are forcing hardware redesigns, while procurement patterns favor rental over ownership across corporate and private event segments.
AI-driven pose detection and automatic retouching is automating the operator role at high-volume activations. Brand marketing teams at product launches and music festivals now deploy unattended booths that trigger capture through gesture recognition, eliminating attendant labor costs while maintaining throughput during peak traffic intervals. This compression of staffing requirements is automating margin structures that previously allocated thirty to forty percent of rental revenue to on-site personnel.
GDPR Article 9 restrictions on biometric data processing have forced European booth operators to implement local-storage-only architectures with delayed social upload options. Hardware manufacturers serving Germany, France, and the Netherlands now ship firmware with facial recognition features disabled by default and cloud sync requiring double-opt-in consent workflows. The regulatory friction is fragmenting product roadmaps, with EU-bound SKUs diverging from North American configurations on identical hardware platforms.
Festival procurement officers now bundle photo booth services into comprehensive site infrastructure contracts rather than contracting standalone vendors. This consolidation of buying authority is compressing the addressable vendor pool, with operators who lack IP65 weather ratings or solar power compatibility excluded from tender shortlists. The behavioral shift is most visible in Australia's regional event circuit, where multi-day outdoor deployments now represent the majority of annual rental revenue for established equipment lessors.
Photo Booth Market Segmentation
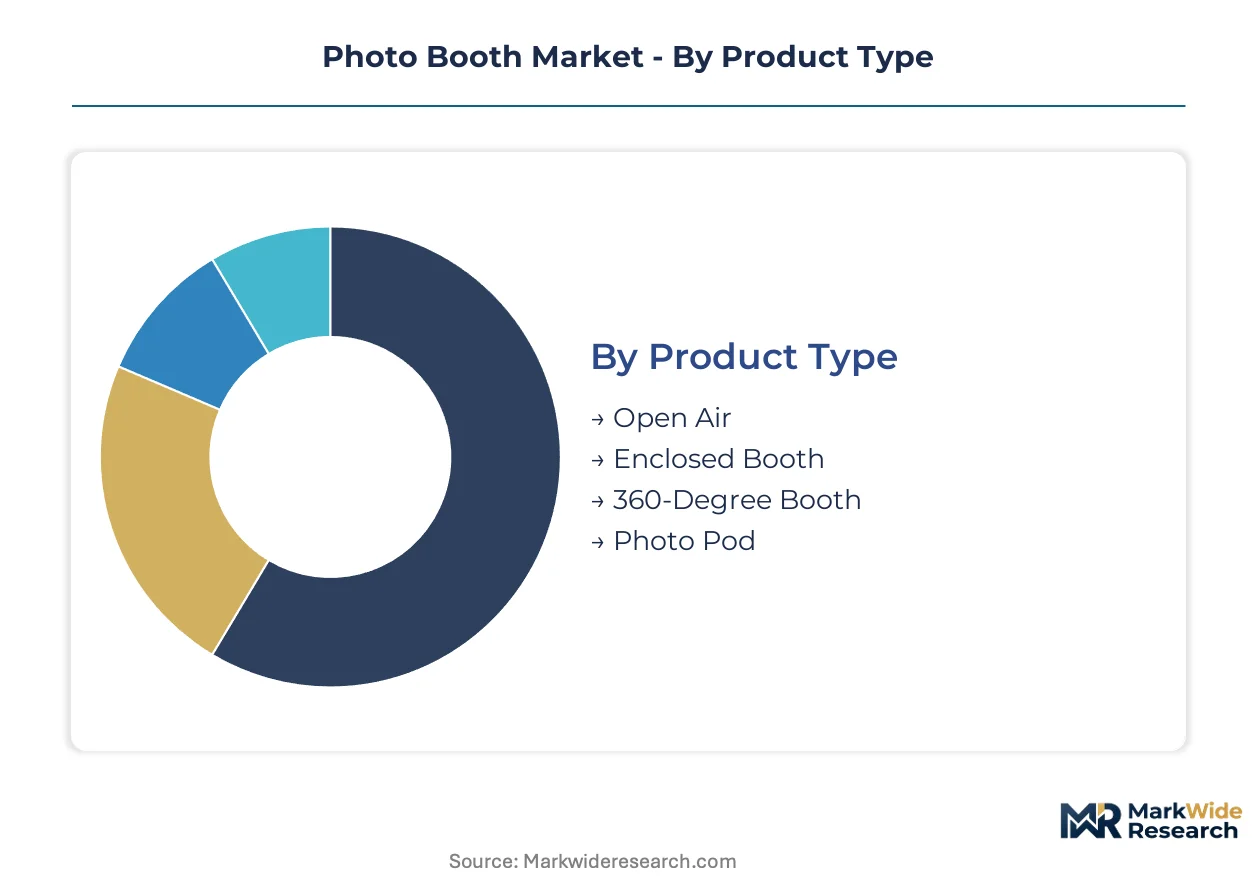
Photo booth procurement patterns diverge sharply between high-volume rental fleets seeking operational flexibility and premium event producers demanding immersive content capabilities. Equipment specifications, certification requirements, and service models reshape competitive positioning across each segment boundary.
Product Type:
Open-air configurations dominate unit shipments through lower logistics costs and venue adaptability, while enclosed booths and 360-degree systems capture divergent premium tiers.
- Open Air:Aluminum frame rigs with modular backdrops and collapsible LED arrays reduce shipping weight by sixty percent versus enclosed alternatives. Wedding rental operators in Texas and Florida favor these systems for beach and vineyard deployments where enclosure footprints face venue restrictions.
- Enclosed Booth:Freestanding cabins with privacy curtains and climate-controlled interiors sustain demand from corporate event planners seeking branded wrap environments. GDPR-compliant local-storage architectures in Germany and France have forced hardware redesigns eliminating cloud-dependent features from EU-bound SKUs.
- 360-Degree Booth:Motorized camera arm rigs capturing rotational video content command premium rental rates at music festivals and automotive launches where shareable immersive footage drives social engagement metrics.
- Photo Pod:Compact touchscreen kiosks with limited customization depth occupy shrinking market share as open-air alternatives expand feature parity at comparable price points.
Today's leader: Open Air. Tomorrow's challenger: 360-Degree Booth.
Application:
Corporate procurement consolidation and festival infrastructure bundling are reshaping vendor selection criteria across end-use channels.
- Weddings:Multi-function pre-wedding events in Indian Tier-2 cities generate hardware-as-a-service demand, with Maharashtra and Gujarat event planners eschewing capital purchases for rental subscriptions. Private capture environments and instant album creation sustain enclosed booth preference in this channel.
- Corporate Events:Brand activation teams now mandate cloud-integrated instant sharing as standard deliverables, pulling FCC-certified wireless transmission modules into procurement specifications. Product launch deployments in California and New York prioritize gesture-triggered unattended operation to eliminate on-site labor costs.
- Birthday Parties:Residential and small-venue deployments favor lightweight open-air systems with dye-sublimation print output, though price sensitivity constrains feature depth relative to commercial installations.
- Festivals:Australia's regional outdoor circuit demands IP65 dust-resistant enclosures and solar-battery hybrid power systems, with procurement officers bundling photo services into comprehensive site infrastructure contracts that exclude grid-dependent vendors.
Festivals and corporate activations are climbing the fastest; wedding volume sustains baseline fleet utilization.
Technology:
Mirrorless camera migration and regulatory pressure on biometric data handling are fragmenting product roadmaps across regional compliance regimes.
- Digital Cameras:Sony and Canon mirrorless sensor modules have displaced DSLR architectures, compressing equipment replacement cycles while demanding recalibration of enclosure mounting systems. Shenzhen-sourced components concentrate supply risk for North American distributors.
- Instant Print:Dye-sublimation thermal transfer systems from Mitsubishi and Citizen deliver waterproof output within fifteen seconds, though technician scarcity for print head maintenance extends downtime at critical event windows.
- GIF Creation:Burst-capture software processing three to five frames into looped animations serves social-first event design requirements without hardware modification.
- Social Media Integration:GDPR Article 9 constraints force European operators into delayed-upload architectures with double-opt-in consent workflows, fragmenting firmware configurations from North American cloud-sync defaults.
Instant Print anchors current revenue; Social Media Integration faces regulatory headwinds in Europe.
End User:
Procurement authority concentration and technical capability gaps determine hardware versus service purchasing patterns.
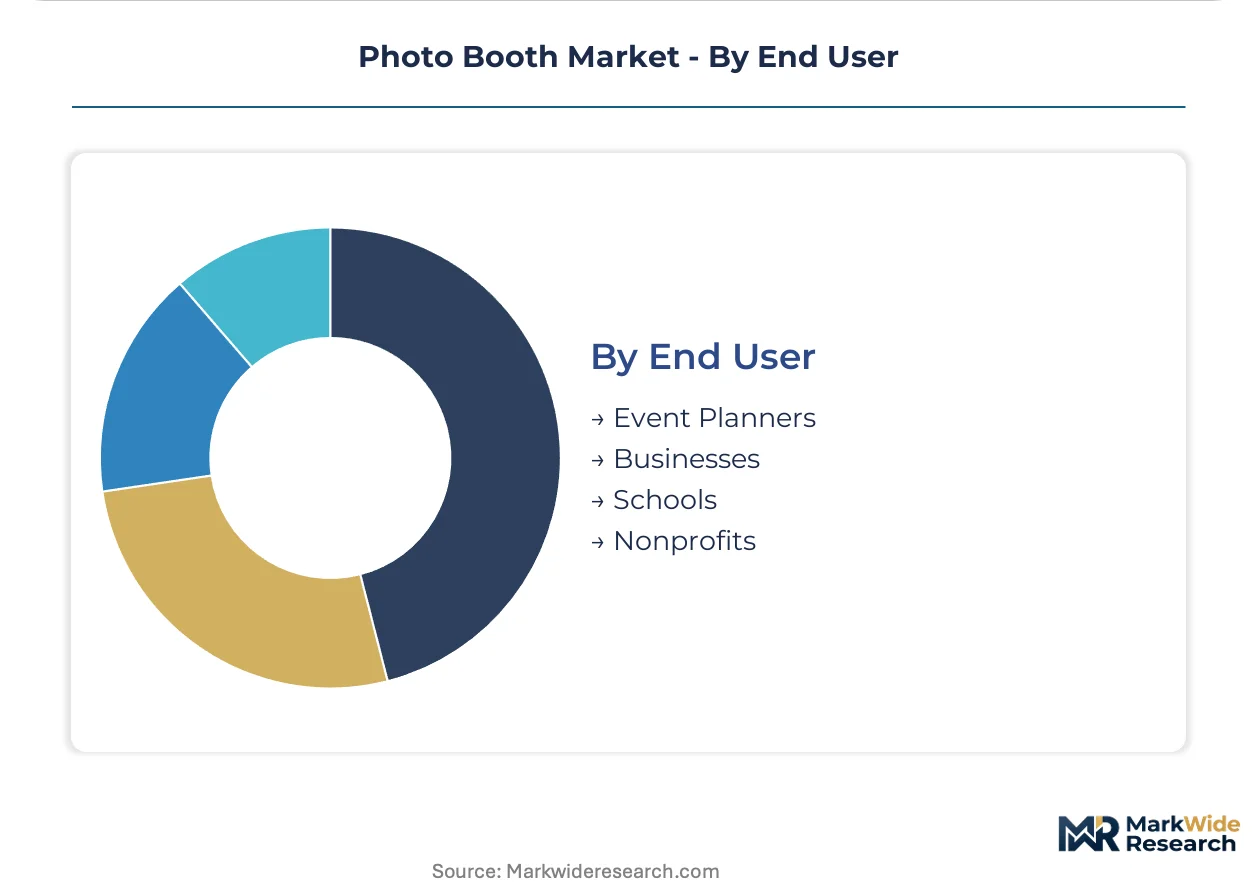
- Event Planners:Full-service coordinators in London and Sydney control placement density through direct venue partnerships, specifying equipment with unified FCC and CE marking to enable cross-border deployment flexibility.
- Businesses:Marketing departments at technology and automotive firms purchase outright for recurring activation calendars, prioritizing AI-powered background replacement and gesture-triggered capture for unattended operation.
- Schools:Budget-constrained educational institutions favor basic open-air rentals for proms and fundraisers, with procurement typically decentralized to parent-teacher organizations.
- Nonprofits:Charitable event coordinators seek donated or heavily discounted services, representing minimal addressable hardware demand but meaningful brand exposure value for rental operators.
Event Planners command placement economics; Businesses drive technology upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between manufacturing jurisdictions are reshaping production footprints. Shenzhen and Dongguan clusters absorb component assembly while final integration migrates toward destination markets to satisfy certification proximity requirements.
United States
Wedding rental operators in Texas and Florida drive open-air booth procurement for beach and vineyard venues. FCC Part 15 certification governs wireless transmission modules, streamlining outdoor deployments without site-specific engineering reviews. California and New York marketing departments anchor corporate activation demand for gesture-triggered unattended systems.
Germany
Corporate event planners in Berlin and Munich sustain enclosed booth preference for branded wrap environments. GDPR Article 9 constraints force local-storage-only architectures with double-opt-in consent workflows. Bavarian hardware distributors now stock EU-bound SKUs with cloud features disabled by default.
United Kingdom
London-based full-service coordinators control venue placement density through direct partnerships. CE marking mandates electrical safety compliance across equipment imports. Midlands manufacturing clusters assemble enclosures for European distribution, leveraging proximity to Netherlands and France event circuits.
China
Shenzhen and Dongguan manufacturing clusters concentrate mirrorless camera sensors, dye-sublimation print heads, and touchscreen controllers. MIIT standards govern wireless module certification for domestic sales. Yangtze River Delta assembly plants face margin pressure from climbing labor costs and tariff exposure on North American-bound shipments.
Australia
Regional outdoor festival procurement officers bundle photo services into comprehensive site infrastructure contracts. TGA-equivalent electrical safety standards apply to equipment deployment. Queensland and Western Australia events demand IP65 dust-resistant enclosures and solar-battery hybrid power systems for remote grid-independent installations.
Photo Booth Market Vendor Landscape
North American distributors anchor one tier; European venue partnership specialists hold placement density advantages in metropolitan markets. The vendor base spans vertically integrated hardware developers, rental fleet operators, and component-focused fabricators. Three archetypes dominate: Shenzhen-sourced assemblers with captive component supply, enclosure designers with proprietary industrial design portfolios, and regional lessors with direct venue relationships. Capacity expansion and certification diversification represent the dominant competitive moves as operators seek cross-border deployment flexibility.
Among North American hardware developers, Photo Booth International and Photobooth Supply Co. exemplify divergent sourcing strategies. Photo Booth International occupies a position emphasizing vertically integrated mirrorless camera procurement to sustain margin stability. Photobooth Supply Co. represents the proprietary design archetype through differentiated enclosure architectures. Faceplace anchors European competitive positioning through direct venue partnerships controlling placement density in major metropolitan markets.
| Leading Market Players |
|---|
| Faceplace |
| Photo Booth International |
| Photobooth Supply Co. |
| Extreme Booths |
| Photo Me |
| Digital Centre |
| Kindom Photo Booth |
| Open Air Photobooth |
| Dream Booth |
| Others |
Supply Flow & Price Mechanics
Dye-sublimation technician scarcity in North American AV rental pools widens the spread between premium full-service rental tiers and economy self-operated deployments, compressing mid-market positioning as labor-cost differentials exceed equipment depreciation schedules.
Pricing Analysis
Distributor margin layers of twenty-five to thirty-five percent separate Shenzhen-sourced hardware from end-rental pricing in Texas and Florida wedding markets. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FCC Part 15 and CE marking compliance commanding fifteen to twenty percent premiums over uncertified alternatives. Cost compression in economy open-air tiers is intensifying because Shenzhen component concentration exposes margins to tariff volatility. School and nonprofit buyers exhibit highest price sensitivity, while corporate marketing departments in California show lowest sensitivity when AI-powered background replacement features are bundled.
Supply Chain Analysis
Dual-sourcing requirements from North American distributors now mandate qualified secondary suppliers for mirrorless camera modules and dye-sublimation print heads beyond sole-source Shenzhen dependencies. Component assembly concentrates in China, South Korea, and Japan, with mirrorless sensors drawing from Sony and Canon fabrication networks. Raw material dependencies span lithium-ion cells for battery systems, aluminum extrusions for enclosure frames, and thermal transfer ribbons for instant print output. Tariff exposure on North American-bound shipments constitutes the primary structural risk. Distribution runs through regional equipment lessors with direct venue partnerships, bypassing traditional retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in photo booth hardware hinges on automation-driven labor cost reduction, with unattended gesture-triggered systems eliminating thirty to forty percent of on-site personnel allocation previously embedded in rental economics.
For Market Incumbents: Deploy captive supply of mirrorless camera modules to buffer margin stability against Shenzhen tariff volatility. Consolidate position through proprietary enclosure IP that differentiates from commodity open-air alternatives, while accelerating FCC and CE marking diversification to enable cross-border deployment flexibility against emerging regional certification barriers. For New Entrants and Emerging Players: The price-point gap between premium 360-degree immersive systems and economy open-air rigs offers entry latitude for mid-tier AI-powered background replacement offerings. Target hardware-as-a-service models in Indian Tier-2 wedding markets, where Maharashtra and Gujarat event planners eschew capital purchases. Pursue direct venue partnerships to secure placement density before established lessors lock metropolitan markets. For Investors and Strategic Acquirers: Valuations sit cheapest among regional rental fleet operators with underdeveloped technology upgrade roadmaps. Long-term viability favors equipment lessors integrating solar-battery hybrid power systems for Australian festival circuit exposure. Monitor IATA dangerous goods regulation evolution as inflection indicator for mobile booth operator margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Background Replacement Development | Real-time chroma-key automation enables premium pricing at brand activations without physical green screen infrastructure. |
| Multi-Certification Compliance Investment | Simultaneous FCC, CE marking, and Australian RCM qualification accelerates cross-border deployment flexibility for hardware developers. |
| Solar-Battery Hybrid Power Integration | Grid-independent operation opens placement gaps at remote Australian regional festivals previously excluded from tender shortlists. |
| Direct Venue Partnership Expansion | Placement density control in London and Sydney metropolitan markets secures recurring rental revenue streams against fragmented competition. |
| GDPR-Compliant Local-Storage Architecture | Cloud-disabled firmware defaults for EU-bound SKUs satisfy German and French regulatory constraints while maintaining hardware platform commonality. |
Methodological Framework
Direct dialogue with wedding rental operators, corporate event planners, festival procurement officers, and dye-sublimation maintenance technicians grounded qualitative findings, cross-referenced against secondary validation from FCC equipment authorization databases, CE marking registries, IATA dangerous goods bulletins, and Australian TGA electrical safety filings. Bottom-up and top-down triangulation reconciled unit shipment estimates with revenue aggregation across identified vendor archetypes.
Bottom-up modeling segmented volume and value across product type, application, technology, and end user dimensions, with additional granularity for regional regulatory cluster differentiation. CAGRs were derived from fitted growth curves anchored to disclosed equipment replacement cycles and procurement pattern shifts. Forecast inputs incorporated mirrorless camera migration timelines and lithium battery transportation regulation evolution.
The model assumes a particular technology adoption path; alternative pathways for AI-powered pose detection and gesture-triggered capture would alter the outlook for unattended booth deployment penetration. Deviation in GDPR enforcement intensity or IATA dangerous goods classification revisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Events and Festivals
Europe Event Pro-Av Services Market
Events and Festivals
Events Market
Events and Festivals
K-Pop Events Market
Events and Festivals
UK Arts Promoter Market
Events and Festivals
Global Escape Room Market
Events and Festivals
Sports Events Tickets Market
Events and Festivals
Event Services Market
Events and Festivals
India Event Services Market
Events and Festivals
Europe K-Pop Events Market
Events and Festivals
Stage and Scenery Equipment Market
Events and Festivals
India Event and Exhibition Market
Events and Festivals
Global Exhibition Market
Events and Festivals
Virtual Events Market
Events and Festivals
Asia-Pacific K-Pop Events Market
Events and Festivals
Music Fountain Market
Events and Festivals
Global Special Effects Fog and Smoke Machines Market