
 GCC Health and Wellness Market | 2026-2036
GCC Health and Wellness Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Health and Wellness Market Intelligence
Digital health platform integration is tilting how wellness services reach consumers across the GCC. Okadoc leverages telemedicine infrastructure to connect patients with specialists in real time, bypassing traditional clinic queues. Fitness First anchors its regional footprint through premium club networks in Dubai and Riyadh, while Holland & Barrett Retail Limited differentiates via specialized supplement formulations tailored to local dietary patterns.
GCC health and wellness encompasses preventive care products, fitness infrastructure, personal care formulations, and therapeutic services designed to maintain or improve physical and mental functioning. Supplement manufacturing follows GMP-certified processes with halal certification requirements governing ingredient sourcing and facility audits. Wellness Services capture expanding margin pools as employers in Saudi Arabia and the UAE mandate annual health screenings, while Online Retail accelerates fastest among distribution channels driven by pharmacy-app integrations and same-day delivery commitments from hypermarket chains.
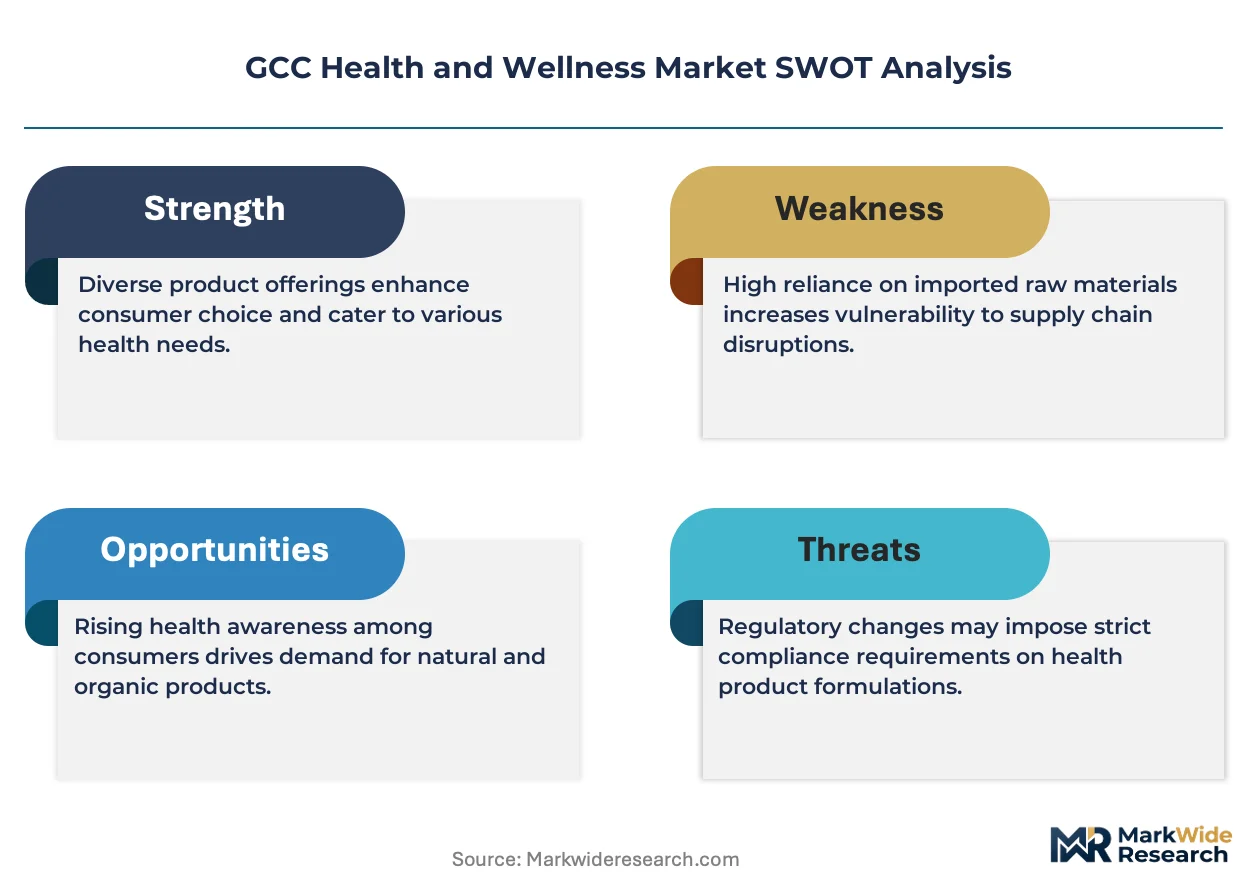
MOHAP in the UAE enforces strict product labeling and advertising standards for nutritional supplements, while Saudi FDA requires clinical evidence dossiers for novel ingredient registrations. These frameworks elevate barriers for unverified imports but create structured pathways for compliant manufacturers. Stakeholders must monitor evolving halal certification reciprocity agreements between Gulf states to anticipate which production facilities gain cross-border market access without redundant audits.
Market Dynamics
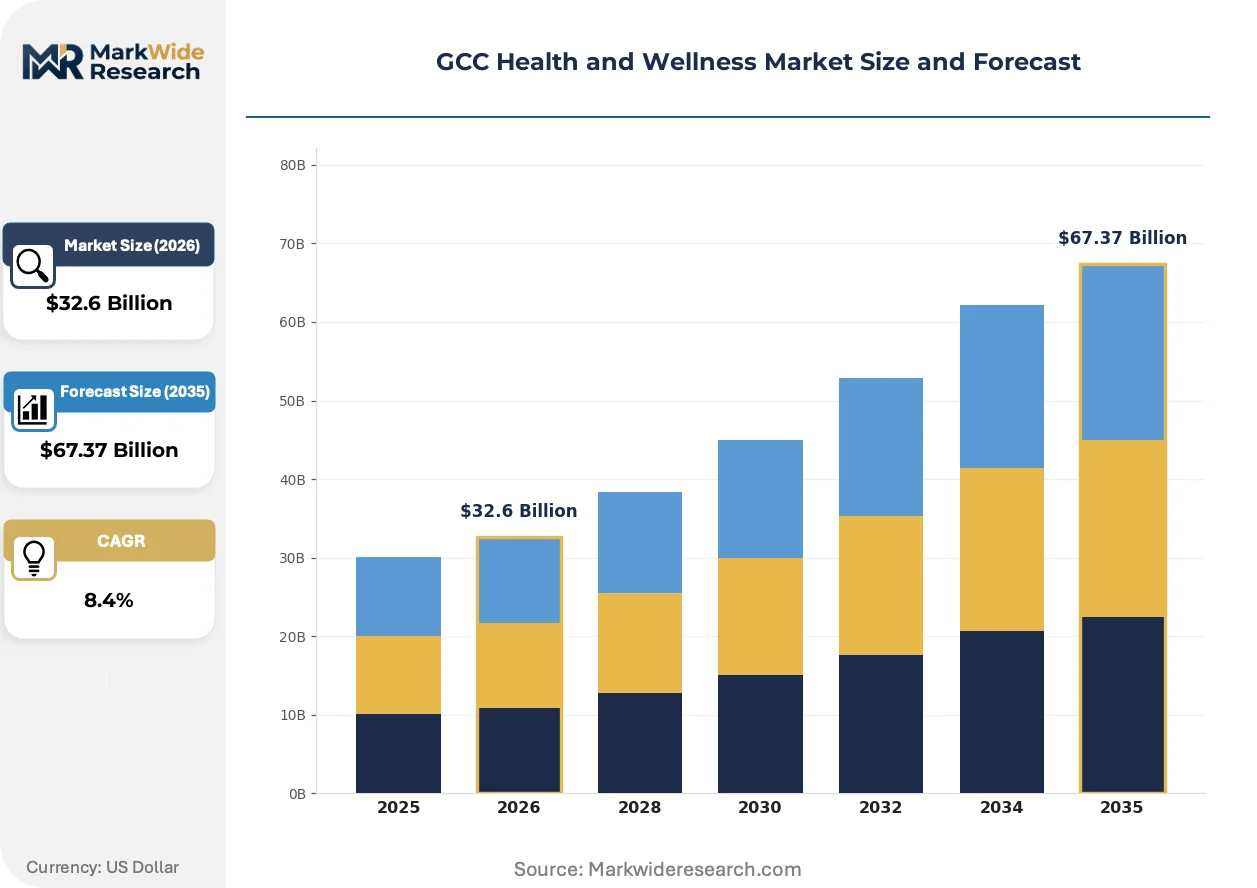
Corporate wellness mandates across Saudi Arabia and the UAE are restructuring procurement flows, pulling preventive services into employer-sponsored coverage pools and compressing traditional out-of-pocket spending channels.
Growth Catalysts
- SFDA Registration Mandates:Saudi Arabia's tightened supplement dossier requirements are filtering low-quality imports and elevating compliant domestic manufacturers into preferred supplier status.
- Telemedicine Infrastructure:Real-time specialist connectivity platforms are bypassing clinic congestion and extending specialist reach into secondary Gulf cities previously underserved.
- Employer Screening Mandates:Annual health assessments required by UAE insurers are creating captive demand pools for diagnostic chains and wellness service providers.
Market Restraints
- Halal Certification Fragmentation:Non-reciprocal facility audits between Gulf states force redundant compliance spending on multi-market suppliers.
- Specialist Labor Concentration:Clinical talent clusters in Dubai and Riyadh, leaving peripheral markets dependent on intermittent locum coverage.
- Import Dependency for Actives:API sourcing concentrates in South Asian and European suppliers, exposing formulators to currency and shipping volatility.
Strategic Opportunities
- Kuwait and Oman Penetration:These markets show lower wellness service density per capita, creating first-mover positioning for platform-based providers.
- Pharmacy-App Convergence:Hypermarket chains integrating same-day delivery with prescription management are opening new supplement distribution rails.
- Preventive Mental Health:Employer programs expanding beyond physical screening into stress management and counseling represent uncaptured service revenue.
Industry Challenges
- SFDA Dossier Timelines:Novel ingredient approvals stretch 18-24 months, freezing product pipelines and accelerating working capital cycles.
- Legacy Clinic Integration:Digital health platforms face friction connecting with established hospital EMR systems, fragmenting patient record continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Health and Wellness Market |
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $67.37 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Supplements, Fitness Equipment, Personal Care, Wellness Services End User: Individuals, Corporates, Gyms, Healthcare Providers Distribution Channel: Online Retail, Hypermarkets, Pharmacies, Specialty Stores Service Type: Nutrition Coaching, Physical Therapy, Wellness Retreats, Fitness Classes |
| Companies Covered | Amway Corporation, Fitness First, Cura Healthcare, Nestle S.A., Johnson & Johnson Services Inc., Okadoc, Holland & Barrett Retail Limited, Unilever plc, Herbalife Nutrition Ltd., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Health and Wellness Market Strategic Shifts & Innovations
Digital infrastructure is collapsing distance between patients and specialists across the GCC, while regulatory tightening and employer procurement centralization are rewiring how wellness services reach end users.
AI-powered diagnostic triage is collapsing traditional referral hierarchies in Gulf healthcare networks. Primary care clinics in Jeddah and Abu Dhabi deploy symptom-checking algorithms that route patients directly to appropriate specialties, bypassing generalist gatekeeping. This compression reduces appointment backlogs and reallocates specialist capacity toward complex cases.
MOHAP's advertising and labeling standards for nutritional supplements are tightening visual and claims compliance requirements. Manufacturers must now submit packaging designs for pre-approval, extending launch timelines but reducing post-market enforcement actions. Dubai-based formulators are responding by embedding regulatory review into early-stage product development.
Employer procurement centralization is consolidating wellness service purchasing into HR-benefit platforms. Large Saudi employers now contract screening and fitness programs through single-vendor arrangements, displacing fragmented departmental spending. This concentration favors providers with integrated service bundles and multi-site delivery capability.
GCC Health and Wellness Market Segmentation
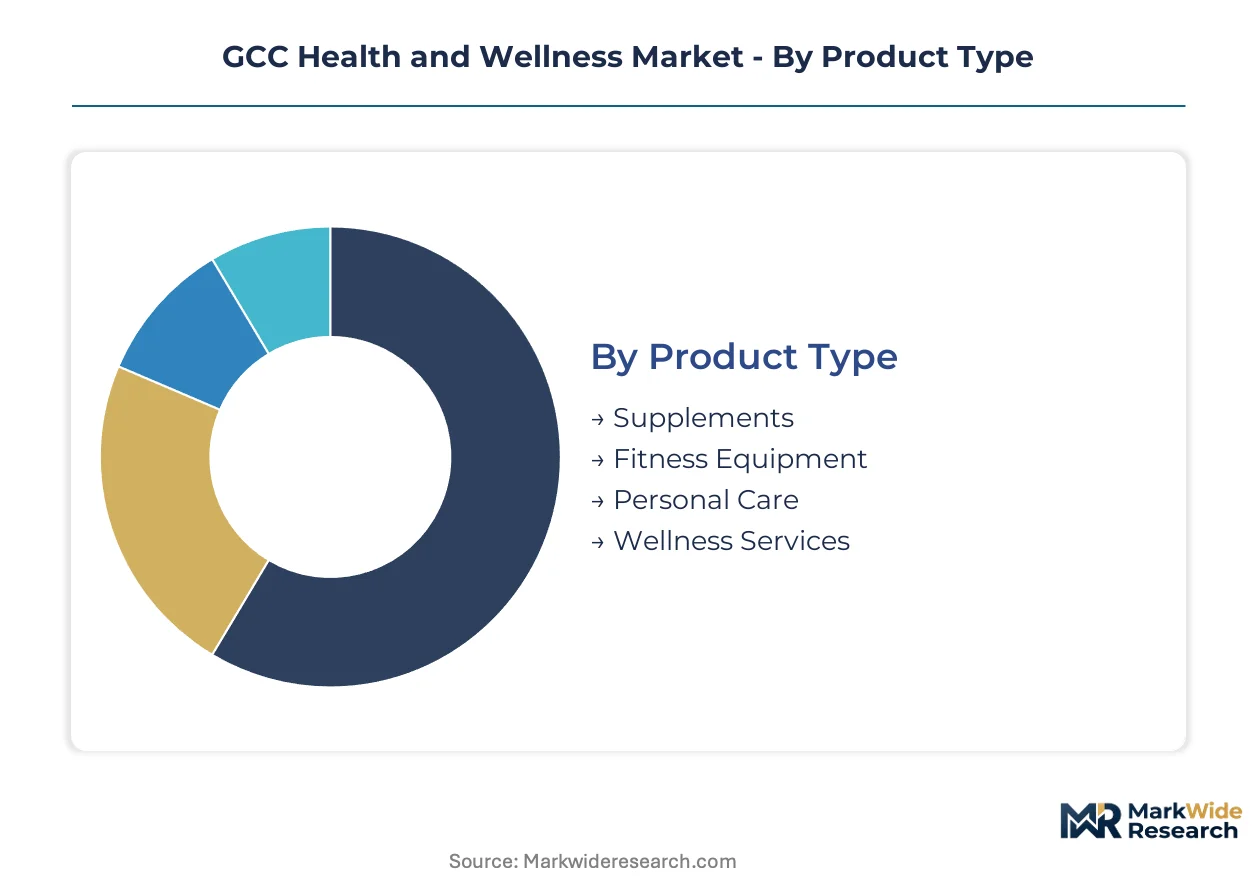
Segmentation in the GCC health and wellness market reveals how regulatory frameworks, employer procurement centralization, and digital infrastructure are reshaping demand patterns across product and service categories. Understanding these divides exposes where margin pools concentrate and which channels are capturing volume migration.
Product Type:
Cost tier differentiation separates premium formulations from mass-market alternatives, with compliance burden acting as the primary price escalator across the Gulf.
- Supplements:GMP-certified manufacturing with halal ingredient sourcing dominates formulation protocols. SFDA dossier requirements in Saudi Arabia and MOHAP labeling mandates in the UAE are compressing import volume while elevating domestic manufacturers with established compliance pathways.
- Wellness Services:Employer-mandated annual screenings and corporate fitness programs are pulling preventive care into sponsored coverage pools. Dubai's medical tourism cluster and Abu Dhabi's insurance-linked wellness requirements generate concentrated procurement demand for integrated service bundles.
- Fitness Equipment:Premium club networks in Riyadh and Dubai anchor commercial demand, with home equipment sales accelerating through pharmacy-app integrations.
- Personal Care:Halal-certified formulations tailored to regional climate conditions and dietary patterns command shelf space in hypermarket chains.
Supplements holds installed capacity. Wellness Services is rotating up the share rankings.
End User:
Customer type determines procurement channel and price sensitivity, with corporate buyers consolidating spend through single-vendor arrangements.
- Corporates:Large Saudi and UAE employers now contract screening and fitness programs through centralized HR-benefit platforms, displacing fragmented departmental purchasing. This concentration favors providers with multi-site delivery capability and integrated reporting systems.
- Individuals:Out-of-pocket spending channels traditional clinic visits and retail supplement purchases, though telemedicine platforms are capturing growing share of primary care interactions.
- Healthcare Providers:Hospitals and clinics in Jeddah and Abu Dhabi deploy AI-powered diagnostic triage to route patients directly to specialties, bypassing generalist gatekeeping.
- Gyms:Premium club networks in Dubai and Riyadh anchor regional fitness infrastructure, with membership models expanding into corporate wellness partnerships.
Corporates dominates procurement volume. Individuals is gaining share fastest through digital channel migration.
Distribution Channel:
Supply concentration varies by fulfillment speed and regulatory proximity, with pharmacy-linked platforms capturing prescription-adjacent supplement sales.
- Online Retail:Pharmacy-app integrations and same-day delivery commitments from hypermarket chains are accelerating fastest among channels. Real-time inventory visibility and prescription management functionality lock in recurring purchase behavior.
- Pharmacies:SFDA and MOHAP enforcement of strict labeling and advertising standards positions licensed pharmacies as trusted verification points for supplement authenticity.
- Hypermarkets:Same-day delivery infrastructure and in-store wellness consultations bridge convenience and professional guidance for mass-market personal care and fitness equipment.
- Specialty Stores:Curated supplement formulations and personalized nutrition coaching services target consumers seeking differentiated product assortments beyond standard retail offerings.
Pharmacies holds regulatory trust positioning. Online Retail is climbing the fastest on fulfillment speed investment.
Service Type:
Application focus separates acute intervention from preventive maintenance, with employer programs expanding beyond physical screening into behavioral health domains.
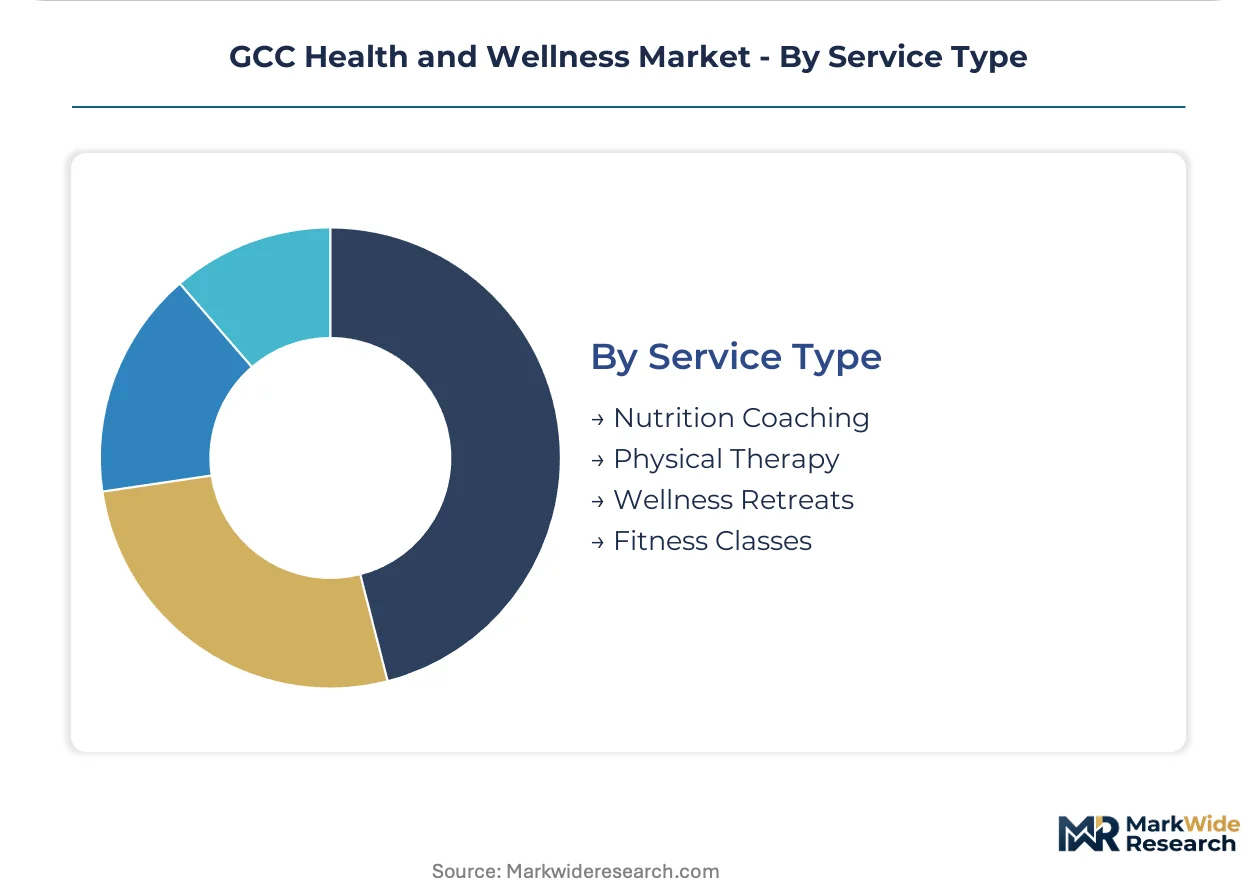
- Nutrition Coaching:Specialized supplement formulations tailored to local dietary patterns require paired professional guidance. Dubai-based formulators embed regulatory review into early-stage product development to satisfy MOHAP packaging pre-approval requirements.
- Physical Therapy:Post-surgical rehabilitation and sports injury recovery services cluster around medical tourism facilities in Dubai and tertiary hospitals in Riyadh.
- Fitness Classes:Corporate wellness mandates are pulling group exercise programs into employer-sponsored benefit structures, with premium club networks capturing contract volume.
- Wellness Retreats:Destination facilities leverage UAE and Saudi leisure infrastructure to package preventive health assessments with recovery-oriented programming.
Physical Therapy holds established clinical infrastructure. Nutrition Coaching is rotating up the share rankings on preventive care prioritization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia exports wellness services and medical tourism capacity to neighboring Gulf states, while the UAE channels diagnostic technology and telemedicine platforms across the Arabian Peninsula. This cross-border service flow concentrates procurement decisions in Riyadh and Dubai, with satellite markets absorbing technology transfer and compliance standards from these hubs.
Saudi Arabia
SFDA dossier requirements for novel supplement ingredients are filtering import volume and elevating domestic manufacturers with established compliance pathways. The Kingdom's national transformation program mandates employer-sponsored wellness screenings for large enterprises, pulling preventive services into corporate procurement pools. Riyadh's medical city cluster anchors specialist capacity, while Jeddah's Red Sea corridor attracts wellness retreat investment targeting religious tourism extensions.
United Arab Emirates
MOHAP enforces strict pre-approval for supplement packaging designs, extending launch timelines but reducing post-market enforcement exposure for compliant formulators. Dubai's medical tourism cluster generates concentrated demand for integrated diagnostic and recovery services, with Abu Dhabi's insurance-mandated annual health assessments creating captive procurement pools. The Dubai Healthcare City free zone concentrates telemedicine platform development and AI-powered diagnostic triage deployment.
Kuwait
Lower wellness service density per capita creates first-mover positioning for platform-based providers entering from Saudi and UAE hubs. The country's national health authority maintains supplement registration requirements aligned with Gulf Cooperation Council harmonization frameworks, though enforcement capacity trails Riyadh and Dubai standards. Kuwait City's private hospital corridor shows expanding diagnostic chain penetration as employer wellness mandates gradually extend coverage obligations.
Oman
Government wellness initiatives under the national health strategy are expanding preventive screening access beyond Muscat's metropolitan core. The Sultanate's pharmaceutical regulator applies GCC-common technical documentation standards for supplement imports, with halal certification reciprocity agreements reducing redundant facility audits for Saudi and UAE manufacturers. Salalah's emerging medical zone targets wellness tourism positioning leveraging monsoon climate differentiation.
Qatar
National health insurance mandates are consolidating wellness service procurement into centralized employer-benefit platforms, mirroring Saudi and UAE structural shifts. The Supreme Council of Health maintains stringent supplement labeling requirements with Arabic-language dominance provisions exceeding baseline GCC standards. Doha's Education City health cluster anchors specialized pediatric and sports medicine wellness services targeting expatriate professional populations.
GCC Health and Wellness Market Key Industry Players
Channel-controlling players compete with product-specialist players across divergent margin structures in the GCC health and wellness market. Hypermarket chains and pharmacy networks leverage same-day delivery infrastructure and prescription-adjacent positioning to capture supplement volume, while dedicated wellness platforms and fitness operators defend service-margin pools through employer contract concentration. Three archetypes dominate: integrated health-tech platforms spanning telemedicine and diagnostic booking, premium fitness club networks with corporate wellness extensions, and specialized supplement formulators with halal-certified manufacturing credentials. Competitive dynamics center on geographic expansion into Kuwait and Oman, plus pharmacy-app convergence strategies that merge fulfillment speed with regulatory trust positioning.
Among platform-based service providers, Okadoc exemplifies the telemedicine infrastructure archetype connecting real-time specialist access across Gulf cities. Fitness First occupies the premium club network position with corporate wellness partnership capabilities. Holland & Barrett Retail Limited represents the specialized supplement formulation segment with halal-certified product development protocols. These three anchors illustrate how compliance burden, fulfillment speed, and employer procurement centralization are restructuring competitive positioning across the GCC wellness economy.
| Leading Market Players |
|---|
| Amway Corporation |
| Fitness First |
| Cura Healthcare |
| Nestle S.A. |
| Johnson & Johnson Services Inc. |
| Okadoc |
| Holland & Barrett Retail Limited |
| Unilever plc |
| Herbalife Nutrition Ltd. |
| Others |
Cost & Logistics Intelligence
Riyadh's GMP-certified manufacturing cluster concentrates domestic supplement production capacity, translating halal compliance infrastructure into pricing power over import-dependent competitors. SFDA dossier timelines and facility audit reciprocity gaps between Gulf states create cost-plus contract structures where compliant domestic manufacturers capture premium positioning against unverified imports.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient indexation dominate supplement procurement between Gulf formulators and South Asian suppliers. Three-tier pricing structure across GMP-halal certified, standard GMP, and unverified import tiers separates compliant domestic manufacturers from cost-pressured traders. Pricing pressure stems from SFDA registration delays stretching working capital cycles for novel ingredients. Corporate wellness buyers show lowest price sensitivity due to insurance-mandated coverage pools, while individual retail purchasers drive volume through pharmacy-app discounting.
Supply Chain Analysis
Supplier-financing facilities extended by Dubai-based hypermarket chains compress payment terms for wellness product distributors, locking in shelf access against specialty store competitors. Active pharmaceutical ingredient sourcing concentrates in India, China, and selected European suppliers, exposing formulators to currency volatility and shipping disruption. Halal certification fragmentation between MOHAP and SFDA standards creates redundant facility audit burdens. Distribution runs through pharmacy-linked platforms with same-day delivery infrastructure, bypassing traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across employer procurement systems, regulatory compliance pathways, and digital channel development creates niche positioning opportunities for specialists. Employer wellness mandate expansion in Saudi Arabia and the UAE is splintering demand into segment-specific service bundles.
For Market Incumbents: Build regulatory compliance moats through redundant halal certification across Saudi, UAE, and Qatar standards to preempt entrant cost advantages. Deepen pharmacy-app integration with prescription management APIs to defend against hypermarket same-day delivery expansion. Anchor multi-site corporate wellness contracts before platform-based competitors consolidate HR-benefit purchasing. For New Entrants and Emerging Players: Build out Kuwait and Oman service density gaps before incumbent platform coverage extends from Riyadh and Dubai hubs. Target preventive mental health programming where employer mandates remain underdeveloped versus physical screening saturation. Launch through telemedicine infrastructure partnerships to bypass legacy clinic EMR integration friction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated wellness platforms combining screening, fitness, and nutrition coaching under single-vendor corporate contracts. Long-term viability favors acquirers of GMP-halal certified manufacturing assets with established SFDA registration track records. Watch for halal certification reciprocity agreement announcements between Gulf states as margin expansion signal.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Dossier Pre-Submission Investment | Compresses 18-24 month approval timelines for novel supplement ingredients entering Saudi Arabia. |
| Pharmacy-App Platform Integration | Locks recurring purchase behavior through prescription-adjacent supplement visibility in UAE hypermarket chains. |
| Corporate Wellness Bundle Expansion | Captures HR-benefit platform consolidation pulling preventive services into employer-sponsored coverage pools. |
| Halal Certification Reciprocity Alignment | Eliminates redundant facility audit costs for multi-market suppliers across MOHAP and SFDA jurisdictions. |
| AI Diagnostic Triage Deployment | Routes patients directly to specialties in Jeddah and Abu Dhabi clinics, bypassing generalist gatekeeping bottlenecks. |
Research Approach
Operator-level perspectives from supplement formulators, corporate HR benefit managers, pharmacy chain procurement leads, and telemedicine platform engineers anchored the qualitative base. Secondary validation drew from SFDA registration filings, MOHAP labeling pre-approvals, GCC customs trade data, and hospital procurement databases. Bottom-up volume estimates triangulated against top-down employer wellness spending aggregates across the analysis window.
Scenario-bracketing around SFDA dossier timeline variations and halal certification reciprocity developments shaped the projection framework. Segmentation modeling spanned product type, end user archetype, distribution channel, and service application dimensions. CAGRs derived from employer mandate expansion rates, telemedicine platform penetration curves, and pharmacy-app order volume trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive platform consolidation moves by integrated health-tech providers would shift outcomes beyond modeled ranges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
North America Healthcare Flexible Packaging Market
Others
Smart Badge Market
Others
Magnetic Stripe Readers Market
Others
Traditional PC Market
Others
North America IT Device Market
Others
Wearable AI Market
Others
Exosome Technologies Market
Others
Snus Market
Others
Hopper Dryers Market
Others
Allogeneic T Cell Therapies Market
Others
Global Process Equipment Market
Others
Idaas Market
Others
Boston Round Bottle Market
Others
Senior Cat Food Market
Others
Dandelion Market
Others
Calcined Petroleum Coke Market