
 Saudi Arabia Laser Hair Removal Market | 2026-2036
Saudi Arabia Laser Hair Removal Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Laser Hair Removal Market Insights
Medical aesthetics distribution is reshaping how laser devices reach end users in Saudi Arabia. Alma Lasers Ltd leverages direct clinic partnerships to sustain premium positioning in Riyadh and Jeddah. Cynosure competes through specialized training programs that anchor practitioner loyalty across private dermatology networks.
Laser hair removal employs concentrated light beams targeting melanin in hair follicles, with diode systems typically operating at 800-810 nm wavelengths for optimal absorption in darker skin types. The technology permanently reduces hair growth through selective photothermolysis, making it a staple in cosmetic dermatology and medspa practice. Diode laser product types dominate installed bases due to versatility across skin phototypes, while facial hair removal applications command premium pricing in women's segments where cultural grooming standards drive repeat sessions. Intense pulsed light technology trails in clinical settings but occupies growing home-use channels where convenience outweighs efficacy demands.
SFDA regulates all medical laser devices under medical device classification rules requiring local registration and quality system documentation. The Saudi central bank's consumer financing frameworks indirectly shape demand by governing installment plans for elective cosmetic procedures. Stakeholders must monitor how SFDA harmonizes with Gulf Cooperation Council medical device directives, as unified standards would streamline multi-country distribution but raise compliance costs for smaller manufacturers lacking regional regulatory infrastructure.
Market Dynamics
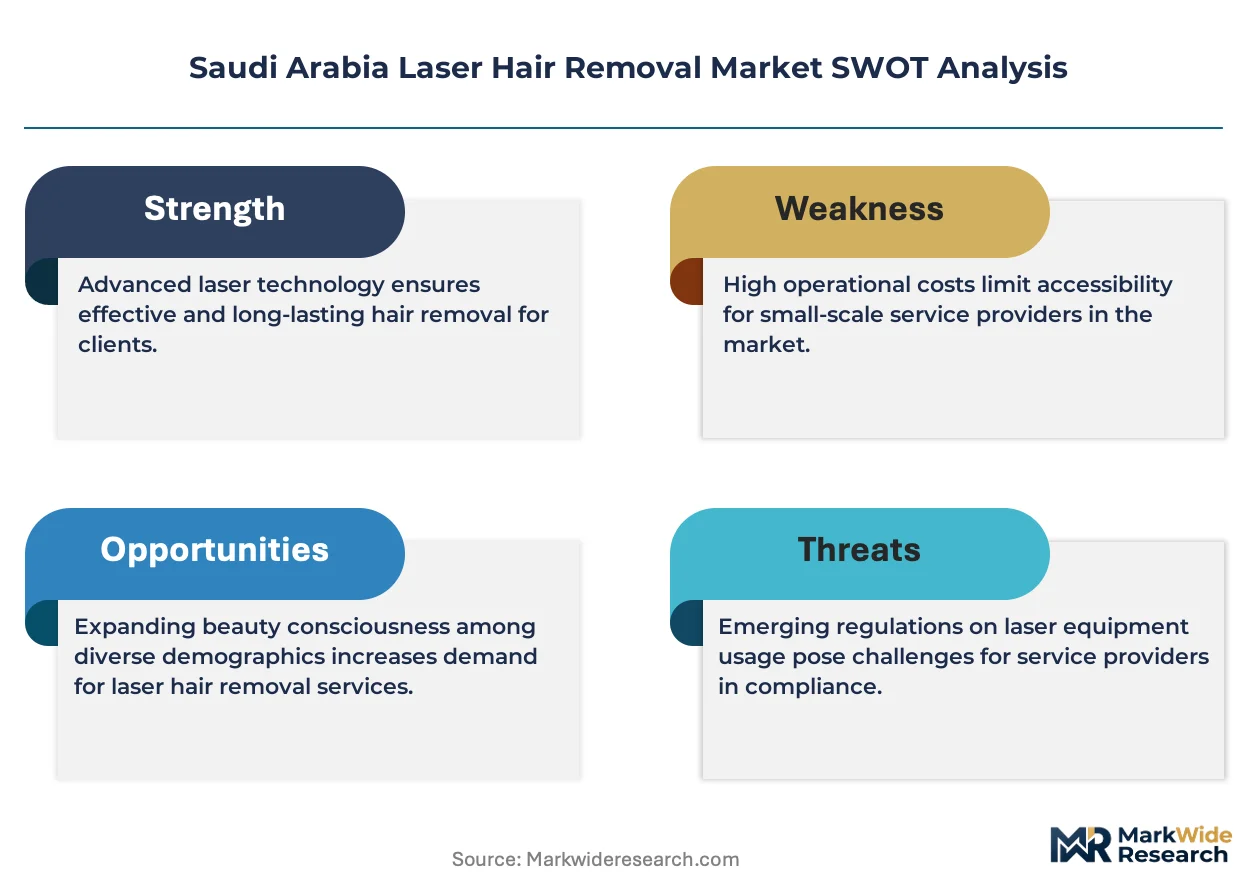
SFDA medical device registration requirements are tightening quality benchmarks for imported laser systems, forcing distributors to consolidate around fewer compliant suppliers and reshaping competitive positioning in Riyadh and Jeddah clinic networks.
Growth Catalysts
- Medical tourism flows:Inbound aesthetic patients from Gulf Cooperation Council states are accelerating clinic-grade device procurement in Jeddah and Riyadh dermatology chains.
- SFDA quality harmonization:Unified Gulf Cooperation Council medical device directives would streamline multi-country distribution for registered manufacturers.
- Diode laser versatility:800-810 nm wavelength systems accommodate darker skin phototypes prevalent in the Saudi population, expanding addressable patient bases.
Market Restraints
- Import cost volatility:Euro- and dollar-denominated laser systems expose clinics to currency fluctuation risk on capital equipment purchases.
- SFDA registration timelines:Local quality system documentation requirements create 12-18 month approval windows that delay product launches.
- Intense pulsed light substitution:Lower-cost home-use IPL devices capture price-sensitive consumers seeking convenience over clinical efficacy.
Strategic Opportunities
- Eastern Province penetration:Dammam and Khobar clinic networks remain underdeveloped relative to Riyadh and Jeddah, offering whitespace for device placement.
- Men's grooming expansion:Cultural normalization of male aesthetic procedures is opening back and chest hair removal applications previously concentrated in women's segments.
- Central bank financing frameworks:Saudi Arabian Monetary Authority consumer installment regulations indirectly govern elective cosmetic procedure payment plans, enabling higher-ticket treatment packages.
Industry Challenges
- Laser safety certification gaps:SFDA requires documented practitioner training on registered devices, but accredited program availability lags device import volumes.
- Service technician scarcity:Specialized diode and Nd:YAG laser maintenance expertise concentrates in Riyadh, leaving Jeddah and Eastern Province clinics dependent on extended response timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Laser Hair Removal Market |
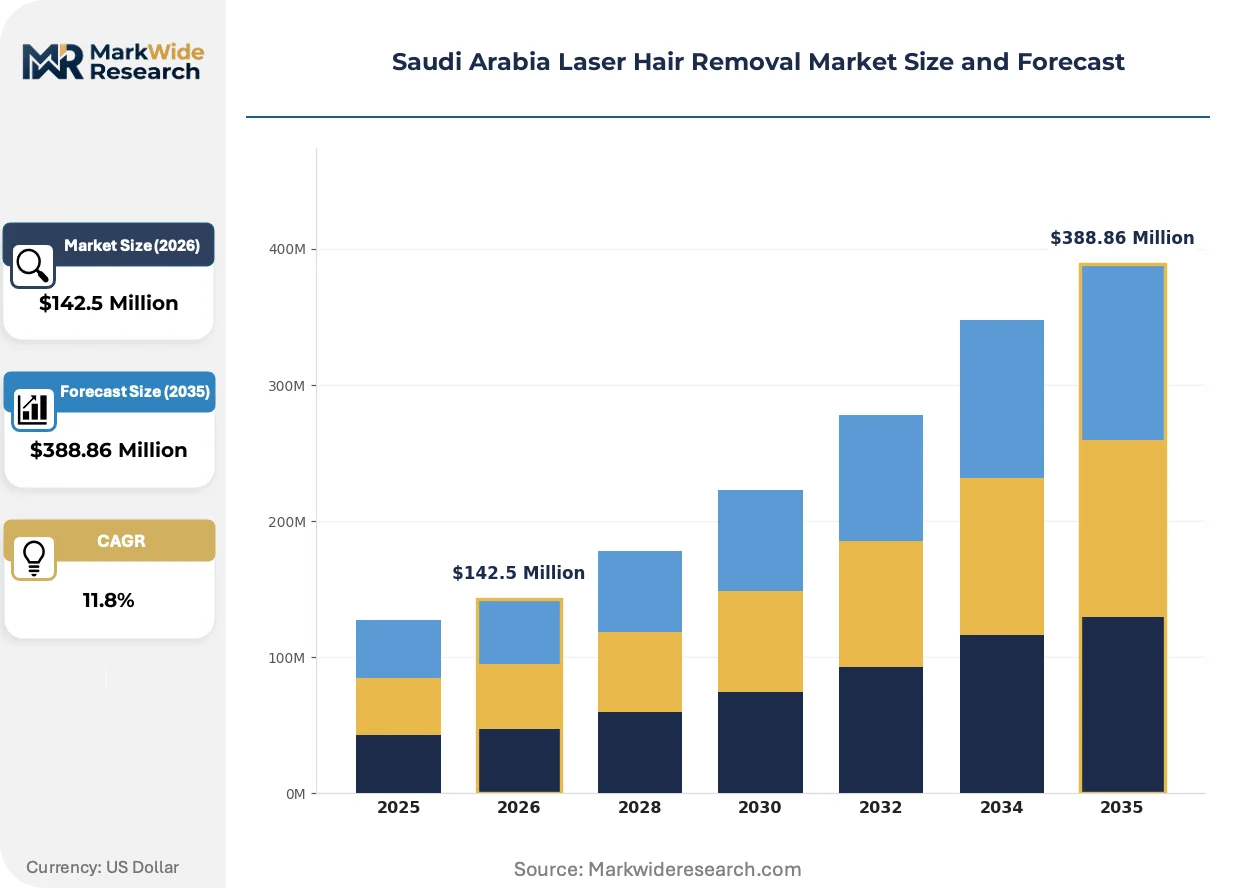
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $388.86 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diode Laser, Alexandrite Laser, Nd:YAG Laser, Ruby Laser End User: Men, Women, Clinics, Home Users Technology: Laser Technology, Intense Pulsed Light, Radiofrequency, Pulsed Laser Application: Facial Hair Removal, Body Hair Removal, Sensitive Area Treatment, Hair Restoration |
| Companies Covered | Lumenis, Sinclair Pharma plc, Cynosure, Bausch Health Companies Inc, Cutera Inc, Alma Lasers Ltd, Lutronic Co Ltd, Venus Group, Candela Medical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Laser Hair Removal Market Trends and Innovations
Device manufacturers are embedding predictive maintenance sensors and cooling system upgrades into next-generation platforms. These advances compress downtime costs for high-volume clinics while raising the technical bar for market entry.
Triple-wavelength diode systems combining 755 nm, 810 nm, and 1064 nm outputs are rendering obsolete single-wavelength platforms that required separate devices for varying skin types. Premium dermatology chains in Riyadh are adopting these systems to consolidate equipment footprints. The technology is compressing capital allocation per treatment room while expanding serviceable patient demographics.
SFDA medical device classification rules now mandate local adverse event reporting infrastructure for all registered laser systems. This policy is diverting smaller international manufacturers toward distributor partnerships rather than direct market entry. European and North American device firms are responding by acquiring Saudi-based regulatory consulting capabilities to accelerate registration timelines.
Clinic procurement committees are unbundling after-sales service contracts from equipment purchases, negotiating separate maintenance agreements based on utilization metrics rather than fixed annual fees. This behavioral shift is pressuring device margins in Jeddah's competitive private dermatology sector. The pattern is most visible among multi-location clinic groups standardizing fleet management across Riyadh, Jeddah, and Dammam networks.
Saudi Arabia Laser Hair Removal Market Segmentation
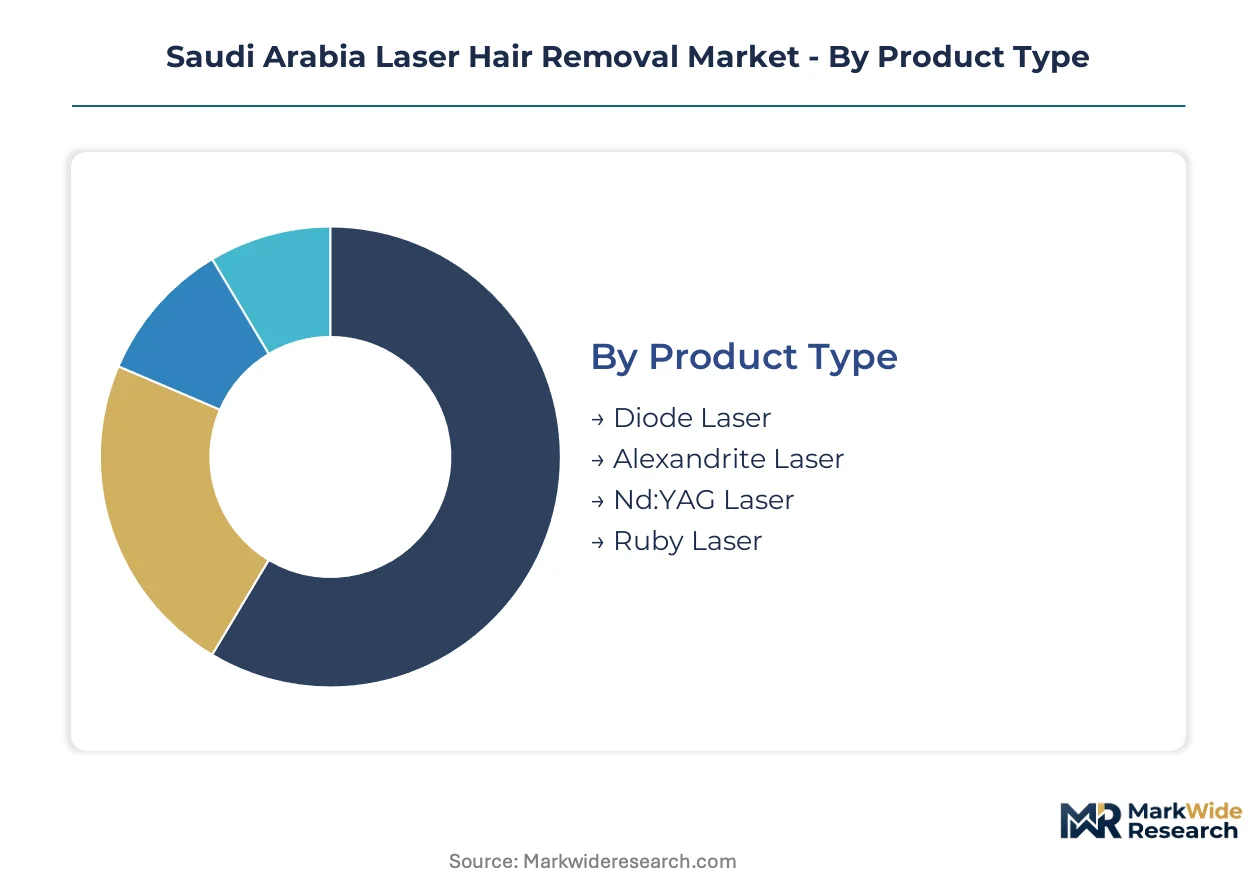
Saudi Arabia's laser hair removal market fragments across device technologies, patient demographics, and clinical settings. Each segmentation axis reveals distinct procurement patterns and margin structures that shape how manufacturers and distributors compete.
Product Type:
Device selection in Riyadh and Jeddah clinics tracks skin phototype prevalence and treatment volume economics.
- Diode Laser:Operating at 800-810 nm wavelengths, these systems accommodate darker skin types prevalent across the Saudi population. Premium dermatology chains in Riyadh favor diode platforms for their versatility across facial and body applications, consolidating equipment footprints while maximizing patient throughput per treatment room.
- Alexandrite Laser:The 755 nm wavelength delivers superior efficacy on lighter skin phototypes. Demand concentrates among high-end Jeddah clinics serving medical tourists from Gulf Cooperation Council states where lighter complexions predominate, with practitioners accepting higher capital costs for speed advantages on appropriate candidates.
- Nd:YAG Laser:The 1064 nm output penetrates deeply with minimal epidermal absorption, serving darker skin patients safely. Eastern Province clinics lacking multi-device budgets often select this wavelength as their sole platform.
- Ruby Laser:The oldest aesthetic laser technology with 694 nm output now occupies niche applications. Limited procurement occurs among budget-conscious independent practitioners in secondary cities.
The dominant share belongs to Diode Laser, while Nd:YAG Laser is closing the gap fastest.
End User:
Customer archetypes in the Saudi market diverge sharply on price sensitivity, session frequency, and channel preference.
- Women:Cultural grooming standards drive repeat facial hair removal sessions at premium pricing. Riyadh's upscale dermatology chains report women comprising the core revenue base, with many committing to 6-8 session packages for permanent reduction.
- Clinics:Multi-location dermatology groups in Jeddah and Riyadh dominate device procurement volumes. These buyers negotiate unbundled service contracts and demand predictive maintenance capabilities to minimize downtime across high-utilization fleets.
- Men:Normalization of male aesthetic procedures is expanding back and chest applications previously absent from the market. Khobar and Dammam clinics report faster growth in male consultations than established Riyadh locations.
- Home Users:Price-sensitive consumers seeking convenience over clinical efficacy gravitate toward lower-cost IPL devices. This segment captures volume outside regulated medical channels, though SFDA registration requirements do not currently govern home-use products as strictly as clinic-grade systems.
Women retain the largest absolute spend, though Men are expanding most quickly as cultural barriers erode.
Technology:
Technology selection reflects the tension between clinical efficacy and operational flexibility in Saudi practice settings.
- Laser Technology:Coherent monochromatic light enables precise targeting of melanin with minimal collateral damage. SFDA-registered diode, alexandrite, and Nd:YAG systems dominate clinic procurement, with registration timelines favoring established manufacturers possessing local regulatory infrastructure.
- Intense Pulsed Light:Broadband light sources offer lower capital costs but reduced specificity. IPL occupies growing home-use channels and budget clinic segments where convenience outweighs efficacy demands, particularly among first-time aesthetic consumers in secondary cities.
- Radiofrequency:Energy-based hair reduction without melanin dependence serves lighter hair colors poorly addressed by optical systems. Adoption remains limited among Saudi clinics prioritizing established laser modalities with clearer clinical evidence.
- Pulsed Laser:Q-switched and long-pulsed variants address specific indications including fine facial hair and resistant growth patterns. Niche deployment occurs in specialized Riyadh practices serving complex cases referred from general dermatology networks.
Laser Technology commands clinic procurement budgets, while Intense Pulsed Light is gaining share fastest in consumer-direct channels.
Application:
Procedure type determines pricing power, session economics, and competitive intensity across Saudi practice settings.
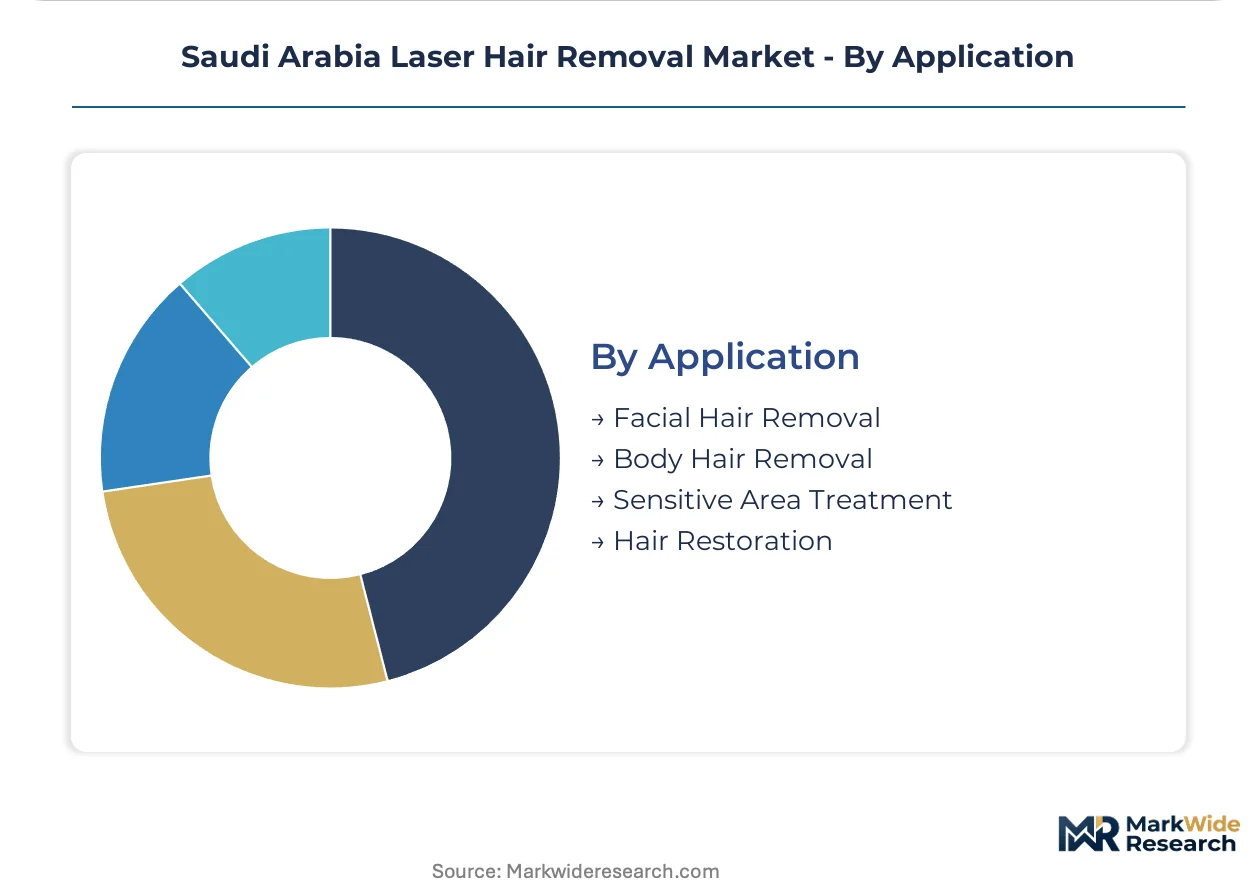
- Facial Hair Removal:Upper lip, chin, and sideburn treatments command premium per-session pricing due to precision requirements and cultural sensitivity. Women in Riyadh and Jeddah drive consistent demand, with many practitioners reporting facial procedures as their highest-margin service line.
- Body Hair Removal:Larger treatment areas generate lower per-cm² revenue but higher absolute session values. Leg and arm applications scale efficiently for high-volume clinics, with Dammam networks expanding body-focused marketing to differentiate from saturated Riyadh facial markets.
- Sensitive Area Treatment:Bikini and underarm applications require enhanced cooling systems and practitioner discretion. Premium positioning in Jeddah's private dermatology sector reflects patient preference for female practitioners and discrete clinic environments.
- Hair Restoration:Low-level laser therapy for androgenetic alopecia occupies a distinct clinical niche. Limited overlap with hair removal device procurement, though some multi-service clinics justify dual-purpose platform investments.
Facial Hair Removal generates the dominant revenue share, while Body Hair Removal is climbing the fastest as male participation expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA regulatory harmonization with Gulf Cooperation Council directives is redirecting procurement flows toward registered suppliers in Riyadh and Jeddah clinic networks. Device distributors are consolidating compliance capabilities to capture medical tourism expenditure from neighboring states.
Riyadh
Central Region dermatology chains drive premium diode laser procurement for facial hair removal services. SFDA registration requirements favor established manufacturers with local quality documentation infrastructure. King Fahd Medical City anchors high-volume aesthetic practice, with multi-location groups standardizing triple-wavelength platforms across satellite clinics.
Jeddah
Western Region clinics capture inbound medical tourism from Gulf Cooperation Council states with lighter skin phototypes. Demand concentrates in upscale private dermatology networks along the Corniche district. Alma Lasers Ltd and Cynosure compete through direct partnerships and practitioner training programs.
Eastern Province
Dammam and Khobar networks remain underdeveloped relative to Riyadh and Jeddah, creating whitespace for device placement. Nd:YAG systems predominate due to budget constraints limiting multi-device procurement. Service technician scarcity extends maintenance response timelines versus the Central Region.
Western Region
Makkah and Madinah clinic demand tracks religious tourism flows rather than medical aesthetics. Device procurement volumes lag Riyadh and Jeddah by significant margins. Local practitioners prioritize single-wavelength platforms with lower capital requirements.
NEOM Northwest
Planned healthcare infrastructure investment is pre-positioning regulatory consulting capabilities for future device registration. No operational clinic networks currently exist. SFDA is coordinating with project developers on medical device classification frameworks for the zone.
Saudi Arabia Laser Hair Removal Market Competitive Landscape
On the supply side, the industry is consolidating around distributors with proven SFDA registration track records and local service infrastructure. Tiered competitive dynamics separate premium device manufacturers with direct clinic partnerships from mid-market suppliers dependent on third-party distribution. Two strategic archetypes dominate: full-stack providers bundling equipment, training, and maintenance; and specialized technology licensors focusing on wavelength innovation. M&A activity targets regulatory consulting capabilities in Riyadh, while geographic expansion concentrates on Eastern Province whitespace.
Within the premium-tier vector, Lumenis and Cynosure exemplify full-stack positioning through established SFDA registrations and practitioner training ecosystems. Alma Lasers Ltd occupies a distinctive anchor position in direct clinic partnerships across Riyadh and Jeddah. Among mid-market specialists, Lutronic Co Ltd and Cutera Inc represent technology-focused archetypes competing on wavelength versatility rather than bundled service depth. Candela Medical and Venus Group sit within the consolidation perimeter as acquisition targets for distributors seeking to deepen vertical integration into after-sales service capabilities.
| Leading Market Players |
|---|
| Lumenis |
| Sinclair Pharma plc |
| Cynosure |
| Bausch Health Companies Inc |
| Cutera Inc |
| Alma Lasers Ltd |
| Lutronic Co Ltd |
| Venus Group |
| Candela Medical |
| Others |
Pricing and Supply Chain Analysis
Jeddah Islamic Port freight corridors channeling European and East Asian device imports impose landed cost differentials that concentrate procurement power among Riyadh-based distributors with bonded warehousing capacity. These logistics economics compress margins for Eastern Province clinics while enabling premium pricing stratification in Central Region dermatology chains.
Pricing Analysis
Certification grade creates the primary spread across Saudi procurement tiers. SFDA-registered diode systems with full quality documentation command premium positioning against CE-marked alternatives awaiting local registration. Price erosion runs through mid-market segments as distributor consolidation intensifies bidding for multi-clinic fleet contracts. Home-use IPL devices capture the most price-sensitive consumers, while premium dermatology chains exhibit inelastic demand for triple-wavelength platforms.
Supply Chain Analysis
Israeli and German original equipment manufacturers hold dominant production capacity for clinic-grade laser systems serving Saudi Arabia. GaN semiconductor substrates and precision optical components draw from specialized foundries in Japan and the USA. Single-source vulnerability concentrates in cooling system subassemblies where two European suppliers control global output. Distribution runs through Jeddah-based medical device distributors with SFDA regulatory consulting capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's laser hair removal market sits in early-cycle expansion as male aesthetic normalization penetrates previously female-concentrated segments. Cultural grooming standard evolution and medical tourism infrastructure investment provide durable adoption tailwinds.
For Market Incumbents: Pre-empt service technician scarcity by embedding predictive maintenance sensors that reduce field dependency. Acquire Saudi-based regulatory consulting capabilities to compress SFDA registration timelines before harmonized GCC directives raise compliance barriers. Defend against IPL substitution by unbundling after-sales contracts to match clinic utilization-based procurement preferences. For New Entrants and Emerging Players: Eastern Province clinic networks offer the most penetrable whitespace relative to saturated Riyadh and Jeddah markets. Khobar and Dammam dermatology groups seek Nd:YAG systems under constrained capital budgets. Anchor entry through specialized training program partnerships that compensate for absent brand heritage. For Investors and Strategic Acquirers: Carve-out targets emerge from European device manufacturers lacking Saudi regulatory infrastructure. Long-term viability hinges on wavelength innovation capabilities and installed base service revenue attachment. Monitor SFDA adverse event reporting mandate enforcement as an inflection signal for distributor partnership dependency.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Acceleration | Local quality documentation infrastructure compresses 12-18 month approval windows for Israeli and German manufacturers. |
| Predictive Maintenance Integration | Sensor-embedded diode platforms reduce technician dispatch dependency in Jeddah and Eastern Province clinics. |
| Triple-Wavelength Platform Launch | Consolidated 755/810/1064 nm systems displace single-wavelength fleets across Riyadh multi-location dermatology groups. |
| Practitioner Training Ecosystem | Accredited laser safety programs anchor loyalty in private dermatology networks competing for medical tourism flows. |
| Eastern Province Distribution Expansion | Dammam and Khobar clinic network penetration captures whitespace before competitor fleet standardization solidifies. |
Research Methodology
Cross-validation between distributor procurement data and clinic-level utilization metrics anchors the qualitative findings. Primary interviews with SFDA regulatory consultants, dermatology chain procurement directors, biomedical equipment service technicians, and medical tourism coordinators combined with secondary validation from SFDA medical device registration databases, Saudi Customs import records, and Gulf Cooperation Council harmonization directives. Bottom-up clinic fleet analysis and top-down device import value triangulation establish market sizing boundaries.
Calibration against historical SFDA approval velocity and medical tourism patient flow patterns shapes the projection framework. Segmentation models incorporate product type, end user demographics, application area, and regional regulatory cluster dimensions across the analysis window. CAGRs derive from equipment replacement cycles, session economics, and penetration rate trajectories. Forecast inputs include SFDA registration timeline distributions and male aesthetic procedure normalization velocity.
Practitioners should monitor SFDA-GCC harmonization implementation schedules and central bank consumer financing regulation adjustments for early signals of demand inflection. Forecasts reflect assumptions around medical tourism sustainability and technician training program expansion. Quarterly review of SFDA adverse event reporting compliance rates and Eastern Province clinic network development indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Latin America Smart Home Market
Others
Cathode Battery Material Market
Others
HPHT Diamond Cubic Press Market
Others
Nuclear Power Cables Market
Others
Over the Top Devices and Services Market
Others
Augmented Reality in BFSI Market
Others
Liquid Density Meters Market
Others
Finished Leather Market
Others
Metaverse Market
Others
Connected Wearable Patches Market
Others
Refractometer Market
Others
Astrology Market
Others
Super Computer Market
Others
Europe Aircraft Lighting Systems Market
Others
Massive Machine Type Communication in Healthcare Market
Others
Smart Home Solutions Market