
 Myristoyl Chloride Market | 2026-2036
Myristoyl Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Myristoyl Chloride Market Analytics
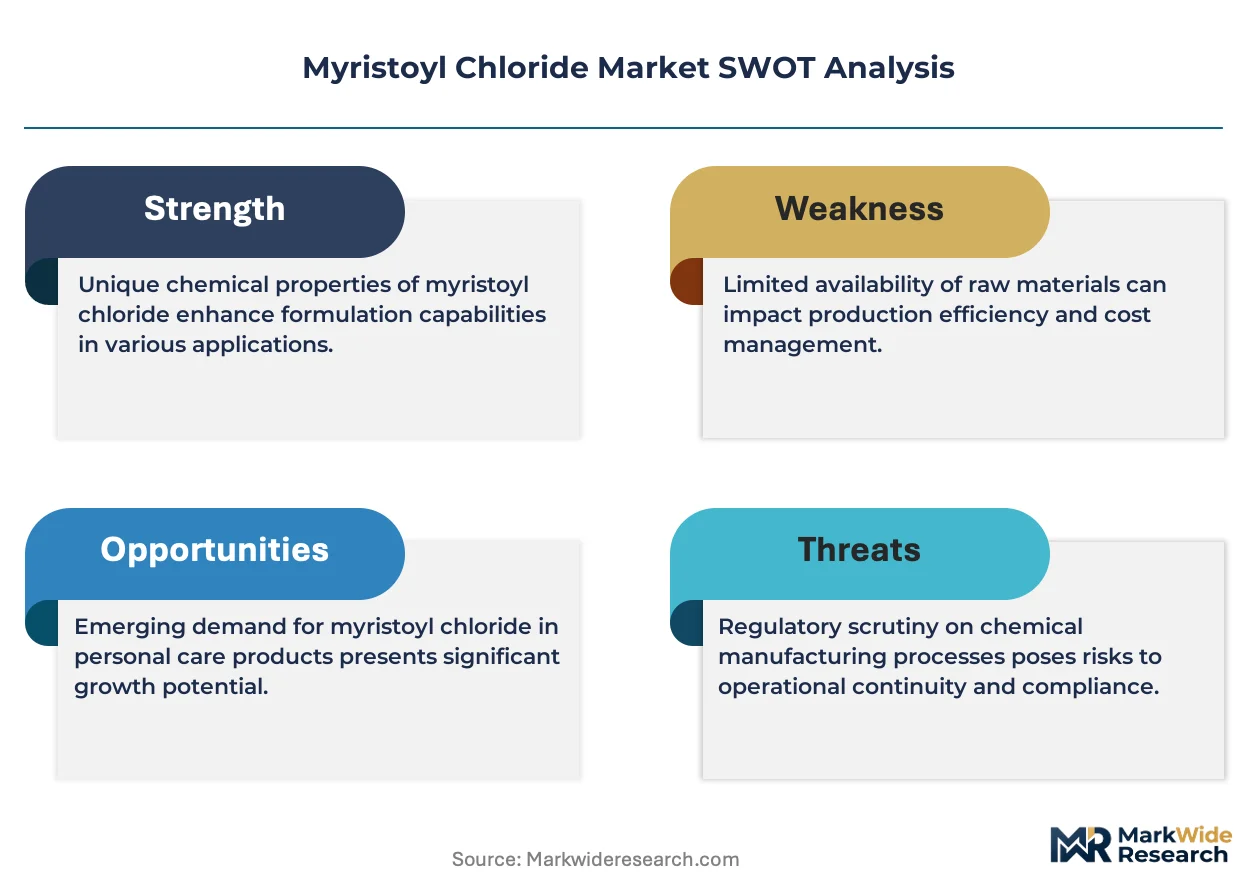
REACH is hardening the cost-of-entry calculus for myristoyl chloride suppliers seeking European cosmetic-grade certification. BASF SE leverages its integrated fatty acid chloride portfolio to sustain margin stability across specification tiers. Croda International Plc anchors its position through backward integration into palm-derived feedstock supply chains. Jiangshan Chemical Co competes on scale in the Asian reagent segment, while Innospec Inc. differentiates via pharmaceutical-grade cGMP compliance.
Myristoyl chloride (tetradecanoyl chloride, C14H27ClO) functions as an acylating agent produced through thionyl chloride-mediated chlorination of myristic acid, with purity grades spanning 95% to 99% for cosmetic and pharmaceutical applications. The liquid product type dominates volume flows due to handling efficiency in continuous esterification processes, while the reagent category commands premium positioning in peptide synthesis and analytical chemistry. Cosmetics as an end-use industry leads value capture, though pharmaceutical applications are expanding fastest as lipid nanoparticle drug delivery systems advance.
EMA and REACH in Europe, FDA in the United States, and China's SAMR collectively shape product standards, with each regulator imposing distinct residual solvent limits and documentation requirements that fragment compliance costs. ISO 9001 and ICH Q7 certifications increasingly function as baseline qualifiers rather than differentiators for pharmaceutical-grade supply contracts. Stakeholders must monitor divergence between EU Green Deal chemical sustainability criteria and Asia-Pacific cost-optimization priorities when allocating capacity investments.
Market Dynamics
REACH compliance in Europe is hardening purity specifications for cosmetic-grade myristoyl chloride imports, forcing suppliers to reconfigure chlorination protocols and fragmenting certification costs across specification tiers.
Growth Catalysts
- Lipid Nanoparticle Drug Delivery:Pharmaceutical formulators are expanding acylating agent procurement for mRNA vaccine excipient synthesis, creating sustained pull for high-purity grades.
- Southeast Asian Personal Care Expansion:Reagent-grade myristoyl chloride demand is concentrating in Indonesia and Vietnam as regional emulsifier producers scale esterification capacity.
- China's Shandong Chemical Corridor:Domestic chlorination capacity expansion is feeding integrated surfactant supply chains, reducing import dependency for C14 acyl chlorides.
Market Restraints
- Thionyl Chloride Feedstock Volatility:Sulfur dioxide and chlorine price swings directly compress margins for batch chlorination operators lacking long-term supply contracts.
- European Import Certification Friction:REACH documentation requirements and residual solvent testing protocols extend qualification timelines for non-EU suppliers by 6-12 months.
- Palm Oil Derivative Substitution:Lauric and caprylic acid chlorides compete for emulsifier applications where carbon chain length flexibility exists.
Strategic Opportunities
- Pharmaceutical-Grade cGMP Capacity:Contract manufacturers in India and China can capture premium positioning by securing ICH Q7 certification for peptide synthesis supply.
- EU Green Deal Chemical Sustainability:Bio-based myristic acid feedstock pathways qualify for carbon border adjustment exemptions, rewarding early renewable feedstock adopters.
- Continuous Flow Chlorination Technology:Microreactor systems are reducing solvent waste and enabling modular capacity deployment closer to downstream formulators.
Industry Challenges
- Analytical Chemistry Talent Scarcity:Residual solvent validation and impurity profiling require specialized chromatography expertise that commands premium compensation in competitive labor markets.
- Multi-Jurisdiction Certification Overlap:Simultaneous FDA, EMA, and SAMR qualification creates documentation redundancy and extends time-to-revenue for new capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myristoyl Chloride Market |
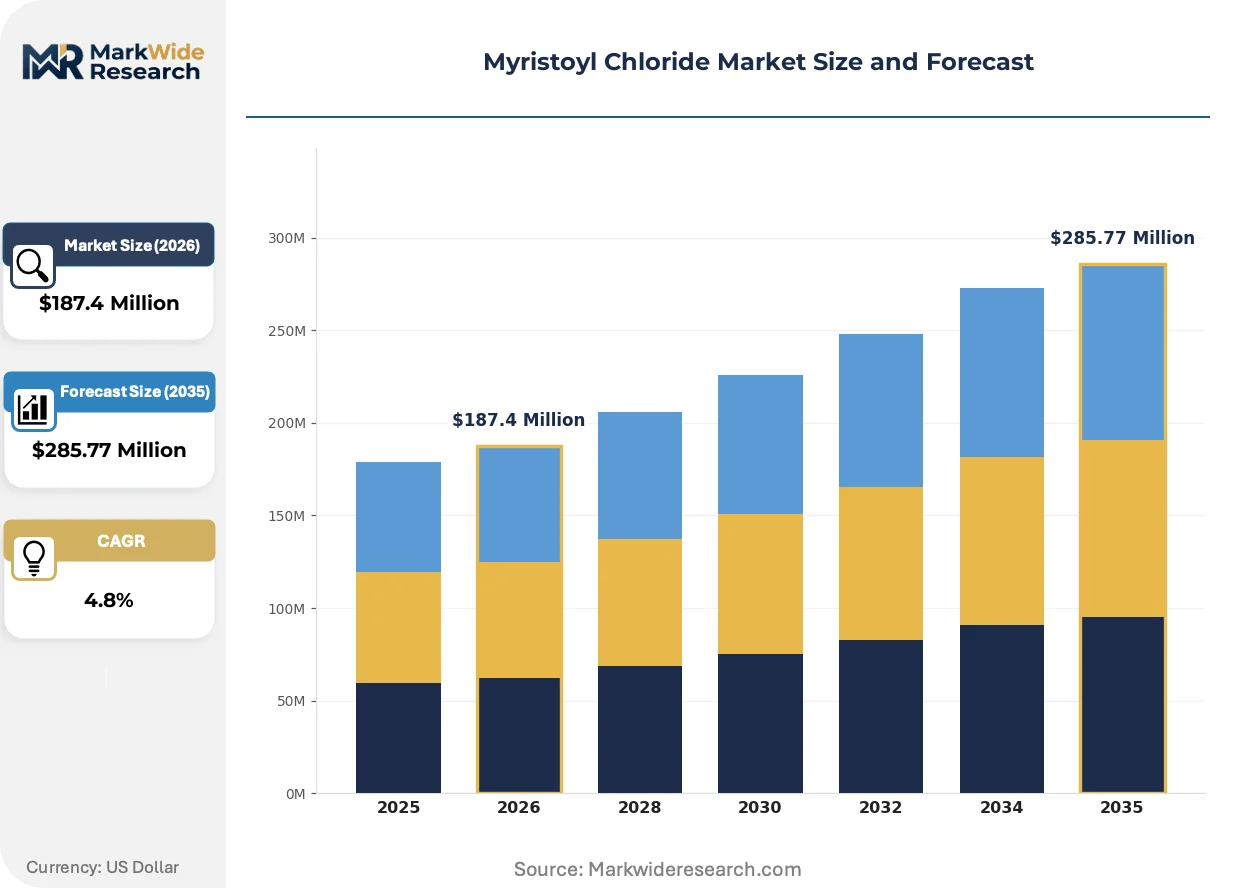
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Solid, Reagent, Compound End Use Industry: Cosmetics, Pharmaceuticals, Agrochemicals, Food Additives Formulation Type: Emulsion, Solution, Suspension, Paste Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | BASF SE, Merck Group, Croda International Plc, Jiangshan Chemical Co, Innospec Inc., Shandong Jinwei Chemical Co, Taiwan Prosperity Chemical Corporation, AcmeHardesty Company, New Japan Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myristoyl Chloride Market Evolving Landscape
Continuous processing technologies and sustainability mandates are restructuring how myristoyl chloride is manufactured, qualified, and procured across cosmetic and pharmaceutical value chains.
Microreactor-based continuous chlorination is decentralizing production economics for C14 acyl chlorides. Pharmaceutical contract manufacturers in Switzerland and Singapore are adopting skid-mounted flow chemistry units to reduce solvent inventory and batch-to-batch variability. This modular architecture is compressing minimum efficient scale thresholds and enabling distributed production closer to formulation sites.
REACH authorization list expansion is tightening residual thionyl chloride limits for cosmetic-grade imports into Germany and France. The European Chemicals Agency's 2024 updates to SVHC screening protocols now require additional genotoxicity documentation for acyl chlorides used in leave-on personal care products. Specialty chemical distributors are responding by segregating inventory streams and investing in third-party testing partnerships.
Direct procurement relationships between surfactant producers and chlorination specialists are displacing traditional merchant chemical distribution in Asia-Pacific. Large personal care formulators in South Korea and Japan are negotiating multi-year tolling arrangements that guarantee volume off-take in exchange for process transparency. This channel consolidation is most pronounced in the reagent-grade segment where specification consistency outweighs spot price flexibility.
Myristoyl Chloride Market Segmentation
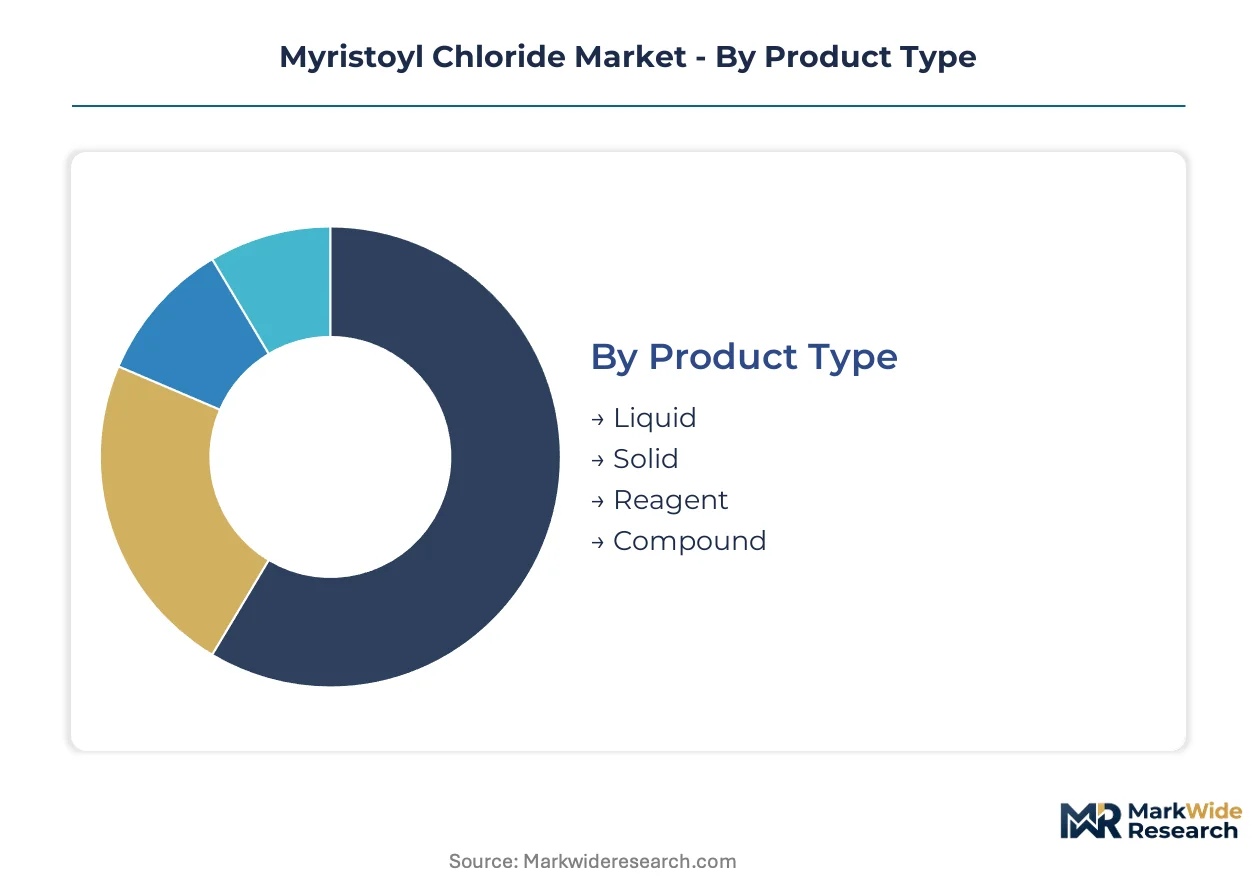
Myristoyl chloride procurement patterns diverge sharply between high-volume cosmetic emulsifier applications and precision-driven pharmaceutical synthesis. Specification tiers, formulation requirements, and channel economics create distinct competitive arenas within each segmentation dimension.
Product Type:
Liquid formats dominate tonnage flows while reagent grades command premium positioning through purity certification burdens.
- Liquid:Continuous esterification processes in Southeast Asian surfactant plants favor pumpable C14 acyl chlorides with 95-98% purity. Handling efficiency and reduced packaging costs sustain volume leadership in cosmetic emulsifier supply chains.
- Reagent:Peptide synthesis and analytical chemistry applications demand 99% purity with comprehensive impurity profiling. ICH Q7 documentation requirements and residual solvent validation extend qualification timelines, compressing supplier pools to cGMP-certified manufacturers.
- Solid:Crystalline myristoyl chloride serves niche pharmaceutical formulations requiring precise dosing and extended shelf stability.
- Compound:Pre-formulated blends with co-solvents or stabilizers address specialized agrochemical and research laboratory workflows.
Mature deployment sits with liquid grades in established surfactant corridors. Newer deployment is concentrated in reagent formats serving lipid nanoparticle drug delivery expansion.
End Use Industry:
Cosmetic applications anchor current revenue while pharmaceutical demand climbs the fastest on mRNA excipient proliferation.
- Cosmetics:Leave-on personal care products in Indonesia and Vietnam drive reagent-grade procurement for emulsifier synthesis. REACH SVHC screening updates for acyl chlorides now mandate additional genotoxicity documentation, fragmenting supplier qualification costs.
- Pharmaceuticals:Lipid nanoparticle formulations for nucleic acid therapeutics require pharmaceutical-grade myristoyl chloride with validated impurity profiles. SAMR in China and FDA in the United States impose divergent residual solvent limits, complicating multi-jurisdiction supply contracts.
- Agrochemicals:Pesticide intermediate synthesis in India's Gujarat chemical belt consumes standard-grade material through toll manufacturing arrangements.
- Food Additives:Flavor ester production operates under FSSAI oversight in India and FDA food additive regulations, with stricter purity thresholds than industrial grades.
Established volume concentration rests with cosmetic emulsifiers. Steepest expansion trajectory belongs to pharmaceutical-grade supply serving drug delivery innovation.
Formulation Type:
Emulsion systems capture the bulk of cosmetic applications while suspension technologies address pharmaceutical solubility challenges.
- Emulsion:Oil-in-water systems for skincare and haircare formulations constitute the dominant consumption pattern. South Korean and Japanese formulators negotiate direct tolling arrangements with chlorination specialists to guarantee specification consistency.
- Suspension:Insoluble active delivery in topical pharmaceuticals requires precise particle size control, favoring myristoyl chloride with narrow batch-to-batch variability.
- Solution:Clear-phase personal care products and injectable drug formulations demand ultra-low residual thionyl chloride specifications.
- Paste:High-viscosity applications in specialized industrial coatings and concentrated agrochemical formulations.
Volume leadership remains with emulsion formats. Suspension applications gain share fastest on pharmaceutical formulation complexity.
Distribution Channel:
Direct procurement relationships are displacing traditional merchant distribution where specification transparency outweighs price flexibility.
- Direct Sales:Multi-year tolling agreements between Shandong chlorination operators and integrated surfactant producers eliminate intermediary margins. Process transparency requirements favor this channel for reagent-grade procurement.
- Wholesale:Standard-grade liquid myristoyl chloride moves through regional chemical distributors serving fragmented cosmetic compounders.
- Online:Research-grade quantities for analytical chemistry and academic laboratories, with digital platforms streamlining documentation access.
- Retail:Minimal presence limited to small-volume specialty chemical outlets serving artisan formulators.
Established channel concentration sits with wholesale for commodity grades. Emerging deployment concentrates in direct sales for pharmaceutical and premium cosmetic supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the dominant share of myristoyl chloride consumption, with Shandong Province's integrated chlorination-to-surfactant corridors driving procurement volumes for domestic emulsifier producers.
China
Shandong chemical corridor operators expand captive chlorination capacity to feed surfactant supply chains serving Southeast Asian personal care formulators. SAMR enforces divergent residual solvent limits for pharmaceutical-grade imports compared with FDA benchmarks. Qingdao and Weifang host the densest concentration of C14 acyl chloride production, with tolling arrangements displacing spot market procurement.
Germany
EMA documentation requirements for lipid nanoparticle excipients sustain demand for validated pharmaceutical-grade material from peptide synthesis contract manufacturers. REACH authorization list expansion tightens residual thionyl chloride limits for cosmetic-grade imports, extending qualification timelines for non-EU suppliers. BASF SE leverages integrated fatty acid chloride production in Ludwigshafen to sustain margin stability across specification tiers.
United States
FDA cGMP compliance requirements for mRNA vaccine excipient synthesis concentrate procurement among ICH Q7-certified suppliers serving lipid nanoparticle formulators. EPA oversight of chlorination byproduct emissions shapes site selection for new acyl chloride capacity. New Jersey and Texas chemical manufacturing clusters anchor pharmaceutical-grade supply contracts with multi-year volume commitments.
India
Gujarat chemical belt agrochemical intermediate producers consume standard-grade myristoyl chloride through toll manufacturing arrangements with regional chlorination specialists. CDSCO pharmaceutical regulations create parallel compliance tracks for domestic formulation versus export-oriented supply. Ankleshwar and Vadodara industrial zones concentrate batch chlorination capacity serving both pesticide and surfactant derivative markets.
Japan
PMDA oversight of nucleic acid therapeutic excipients sustains premium positioning for high-purity reagent grades in lipid nanoparticle applications. METI industrial chemical standards fragment from EU REACH protocols, creating documentation redundancy for suppliers serving multiple jurisdictions. Osaka and Nagoya pharmaceutical manufacturing corridors anchor demand for validated impurity profiling and residual solvent certification.
Myristoyl Chloride Market Competitive Landscape
European producers anchor one tier; Asian specialists hold scale-driven positions in reagent-grade supply. The vendor base clusters around three strategic archetypes: integrated petrochemical majors with fatty acid chloride portfolios, backward-integrated palm derivative processors, and cGMP-certified pharmaceutical contract manufacturers. Capacity expansion and direct tolling arrangements constitute the dominant competitive moves, displacing traditional merchant chemical distribution in high-specification segments.
Within the integrated major tier, BASF SE and Croda International Plc exemplify divergent feedstock strategies—petrochemical integration versus palm oil derivative supply chain control. Jiangshan Chemical Co occupies a position among Asian scale operators competing on reagent-grade volume, while Innospec Inc. sits within the pharmaceutical-certified specialist archetype. These three named entities represent the competitive spectrum without exhausting the supplier pool.
| Leading Market Players |
|---|
| BASF SE |
| Merck Group |
| Croda International Plc |
| Jiangshan Chemical Co |
| Innospec Inc. |
| Shandong Jinwei Chemical Co |
| Taiwan Prosperity Chemical Corporation |
| AcmeHardesty Company |
| New Japan Chemical Company |
| Others |
Value Network & Pricing Analysis
Thionyl chloride spot price volatility cascades through myristoyl chloride supply chains, compressing margins for batch operators while rewarding integrated producers with captive sulfur dioxide supply. Contract-based long-term offtake agreements between Shandong chlorination specialists and Southeast Asian surfactant formulators insulate pricing tiers from feedstock swings.
Pricing Analysis
Volume leadership rests with liquid grades at 95-98% purity, while reagent formats at 99% purity capture margin premiums through ICH Q7 certification burdens. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and industrial-grade levels reflects purity thresholds and documentation intensity. Cost compression in standard-grade supply runs through thionyl chloride feedstock exposure and energy input inflation. Agrochemical intermediate buyers in India's Gujarat belt exhibit highest price sensitivity, whereas lipid nanoparticle formulators prioritize specification consistency over unit economics.
Supply Chain Analysis
Myristoyl chloride production rests on thionyl chloride, myristic acid, and chlorination catalyst inputs sourced from China, Germany, and Malaysia. Geographic supply concentration clusters in Shandong Province, Ludwigshafen, and Ankleshwar as dominant chlorination hubs. Single-source vulnerability in specialty-grade thionyl chloride supply creates qualification bottlenecks for non-integrated producers. Distribution runs through direct tolling arrangements for reagent grades and regional chemical distributors for standard liquid formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into palm-derived feedstock supply chains and forward integration into formulated surfactant output defines the vertical-integration race, with REACH compliance costs accelerating consolidation economics.
For Market Incumbents: Lock in multi-year tolling arrangements with Southeast Asian personal care formulators to secure volume off-take against emerging Chinese scale players. Deepen captive chlorination capacity in Shandong or Ludwigshafen to insulate margins from thionyl chloride spot volatility. Prioritize ICH Q7 certification maintenance as peptide synthesis demand concentrates among validated suppliers. For New Entrants and Emerging Players: Launch via contract manufacturing partnerships serving Indian pharmaceutical-grade demand, where CDSCO compliance creates parallel qualification tracks distinct from FDA-centric incumbents. Target white-space in bio-based myristic acid feedstock pathways qualifying for EU Green Deal carbon border exemptions. Penetrate through continuous flow chlorination technology offerings that reduce solvent waste and enable modular deployment. For Investors and Strategic Acquirers: Distressed-cycle entries favor cGMP-certified pharmaceutical contract manufacturers in India and China with validated impurity profiling capabilities. Five-to-ten year viability hinges on positioning for lipid nanoparticle drug delivery expansion as nucleic acid therapeutics proliferate. Monitor SAMR-FDA regulatory divergence as the signal indicating multi-jurisdiction supply contract complexity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palm Feedstock | Croda International Plc secures supply chain control against oleochemical price swings. |
| Continuous Flow Chlorination Deployment | Microreactor systems reduce solvent inventory and batch-to-batch variability for pharmaceutical grades. |
| ICH Q7 Certification Investment | Innospec Inc. anchors premium positioning in peptide synthesis supply chains. |
| Direct Tolling Arrangements | Shandong producers displace merchant distribution through process transparency guarantees. |
| Bio-Based Feedstock Transition | EU Green Deal compliance rewards renewable myristic acid pathway adopters with carbon border exemptions. |
Research Methodology
Trade databases, chemical industry association filings, and regulatory submission records formed the secondary backbone, cross-referenced against primary interviews with chlorination plant managers, surfactant procurement leads, and pharmaceutical formulation scientists. Bottom-up and top-down triangulation validated volume estimates across purity grades and end-use segments.
Bottom-up modeling built from individual production facility capacities and utilization rates, while top-down analysis anchored on surfactant derivative consumption patterns and lipid nanoparticle formulation expansion. Segmentation dimensions spanned product type, end-use industry, formulation technology, and regional production hub. CAGRs derived from regression analysis against feedstock cost trajectories and regulatory compliance cost indices.
Feedstock price shocks, REACH authorization list expansions, and pharmaceutical-grade certification timeline extensions are the dominant revision risks to projection assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Dimethyl Dicarbonate Market
Chemical Intermediates
Tertiary Butylhydroquinone Acids Market
Chemical Intermediates
Phosphate Chemical Reagents Market
Chemical Intermediates
Copper Chemicals Market
Chemical Intermediates
Japan Formic Acid Market
Chemical Intermediates
Methacrylic Ester Market
Chemical Intermediates
Butadiene Derivatives Market
Chemical Intermediates
Global Glycinates Market
Chemical Intermediates
Natural Chelating Agents Market
Chemical Intermediates
Penicillin Intermediate Market
Chemical Intermediates
Duloxetine Intermediate and Atorvastatin Intermediates Market
Chemical Intermediates
Ph Controlling Agents Market
Chemical Intermediates
Hydroxyisobutyric Acid Market
Chemical Intermediates
API Intermediate Market
Chemical Intermediates
Nutrition Chemicals Market
Chemical Intermediates
Triisobutyl Phosphate Market