
 Hydroxyisobutyric Acid Market | 2026-2036
Hydroxyisobutyric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Hydroxyisobutyric Acid Market Analysis
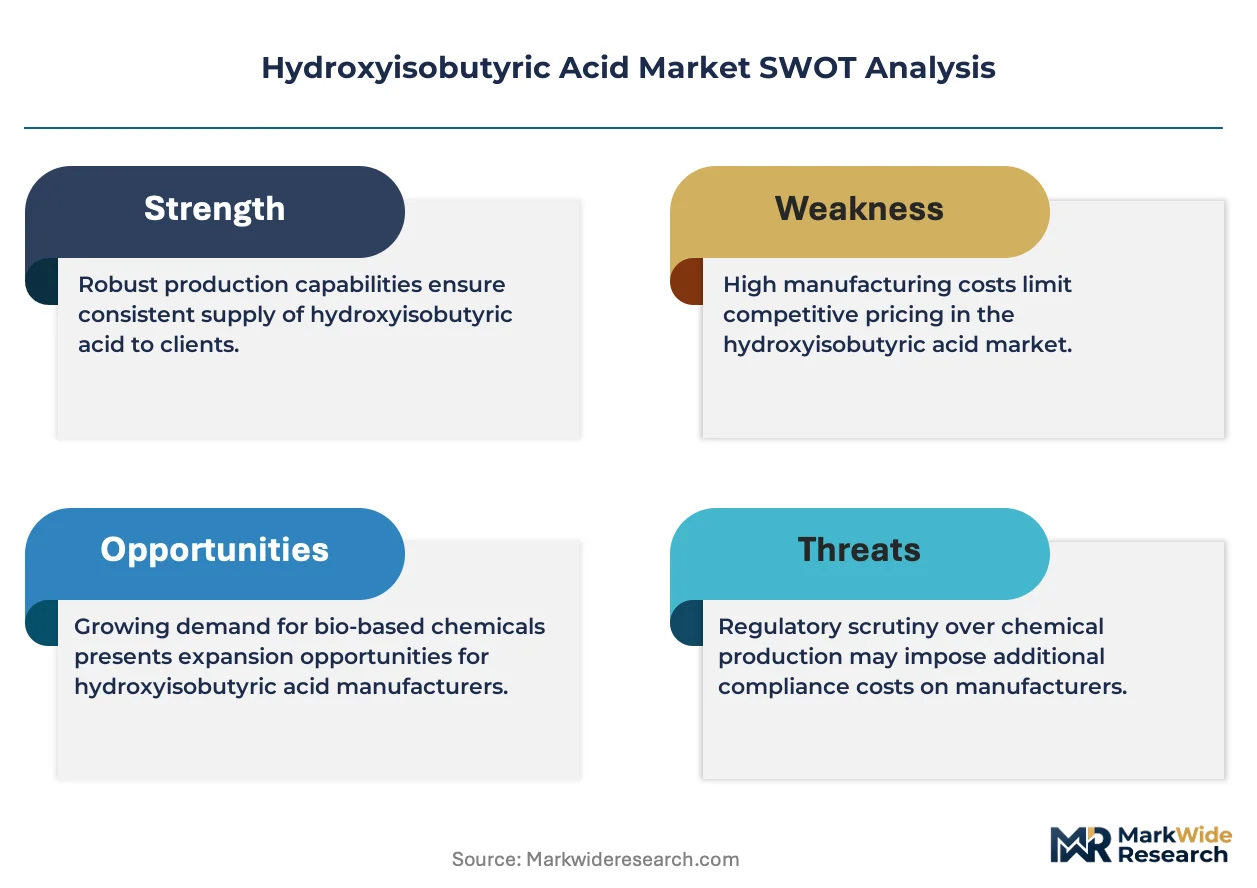
Biocatalytic synthesis routes are reshaping how hydroxyisobutyric acid manufacturers achieve stereoselective production at commercial scale. Evonik Industries AG leverages enzyme engineering platforms to sustain cost advantages in pharmaceutical-grade output. Mitsubishi Gas Chemical anchors Asian supply through integrated petrochemical feedstock access. BASF SE competes on global distribution density for industrial-grade formulations.
Hydroxyisobutyric acid (2-hydroxy-2-methylpropanoic acid, CAS 594-61-6) is a chiral alpha-hydroxy acid synthesized via cyanohydrin hydrolysis or microbial fermentation, typically supplied at 98-99% purity with specific rotation specifications critical for pharmaceutical applications. The compound serves as a key building block for methacrylic acid derivatives, nutritional supplements, and polymer crosslinking agents where enantiomeric excess determines functional performance. Purified Hydroxyisobutyric Acid commands premium positioning in pharmaceutical intermediates where chiral purity requirements exclude lower-grade alternatives. Ester Derivatives represent the fastest-expanding product category as cosmetic formulators adopt lipophilic variants for enhanced skin penetration. Pharmaceutical Grade material concentrates margin pools due to certification burdens that exclude commodity producers.
EPA industrial chemical reporting requirements and FDA Good Manufacturing Practice standards govern US market access for pharmaceutical and food-grade material. REACH registration obligations in Europe mandate toxicological dossiers that favor established suppliers with dedicated regulatory affairs capacity. EMA quality guidelines for active pharmaceutical ingredient starting materials directly influence purity specifications demanded by downstream drug manufacturers. Stakeholders must monitor evolving dual-use export controls on chiral synthesis technologies that could restrict technology transfer to emerging production centers.
Market Dynamics
Biocatalytic synthesis is compressing cost structures for stereoselective production, forcing incumbent cyanohydrin-based manufacturers to retool or cede pharmaceutical-grade margins to enzyme-engineered competitors.
Growth Catalysts
- Pharmaceutical chiral purity mandates:FDA Good Manufacturing Practice standards for active pharmaceutical ingredient starting materials exclude racemic alternatives, locking in demand for enantiomerically pure hydroxyisobutyric acid.
- China's high-purity capacity expansion:Domestic chemical manufacturers in Jiangsu and Zhejiang provinces are scaling pharmaceutical-grade output for export markets, capturing share from European incumbents.
- Ester derivative adoption in cosmetics:Lipophilic variants enable enhanced skin penetration for anti-aging formulations, opening volume channels beyond traditional industrial applications.
Market Restraints
- Acetone cyanohydrin feedstock volatility:Hydrogen cyanide supply disruptions and petrochemical price swings compress margins for conventional synthesis routes.
- REACH registration cost barriers:ECHA toxicological dossier requirements favor established suppliers with dedicated regulatory affairs capacity, excluding smaller commodity producers from European pharmaceutical supply chains.
- Microbial fermentation yield limitations:Biocatalytic routes face titer and productivity ceilings that constrain scale-up beyond pilot volumes for certain stereoisomer targets.
Strategic Opportunities
- India's contract manufacturing expansion:CDSCO pharmaceutical export incentives and PLI scheme benefits attract hydroxyisobutyric acid procurement for generic active ingredient synthesis.
- Nutraceutical grade certification:FSSAI and EFSA food additive approvals unlock sports nutrition and dietary supplement applications with premium pricing over industrial grades.
- Continuous flow reactor integration:Convergence of enzymatic biocatalysis with continuous processing technology enables real-time quality control and reduced batch failure rates.
Industry Challenges
- Enzyme engineering talent scarcity:Protein design and directed evolution expertise concentrates at specialized biotechnology firms, constraining in-house capability building at traditional chemical manufacturers.
- Pharmaceutical grade certification timelines:FDA and EMA starting material qualification processes extend 18-24 months, delaying revenue recognition for new production capacity.
- Chiral synthesis IP fragmentation:Patent thickets around specific biocatalysts and stereoselective processes complicate freedom-to-operate assessments for route selection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydroxyisobutyric Acid Market |
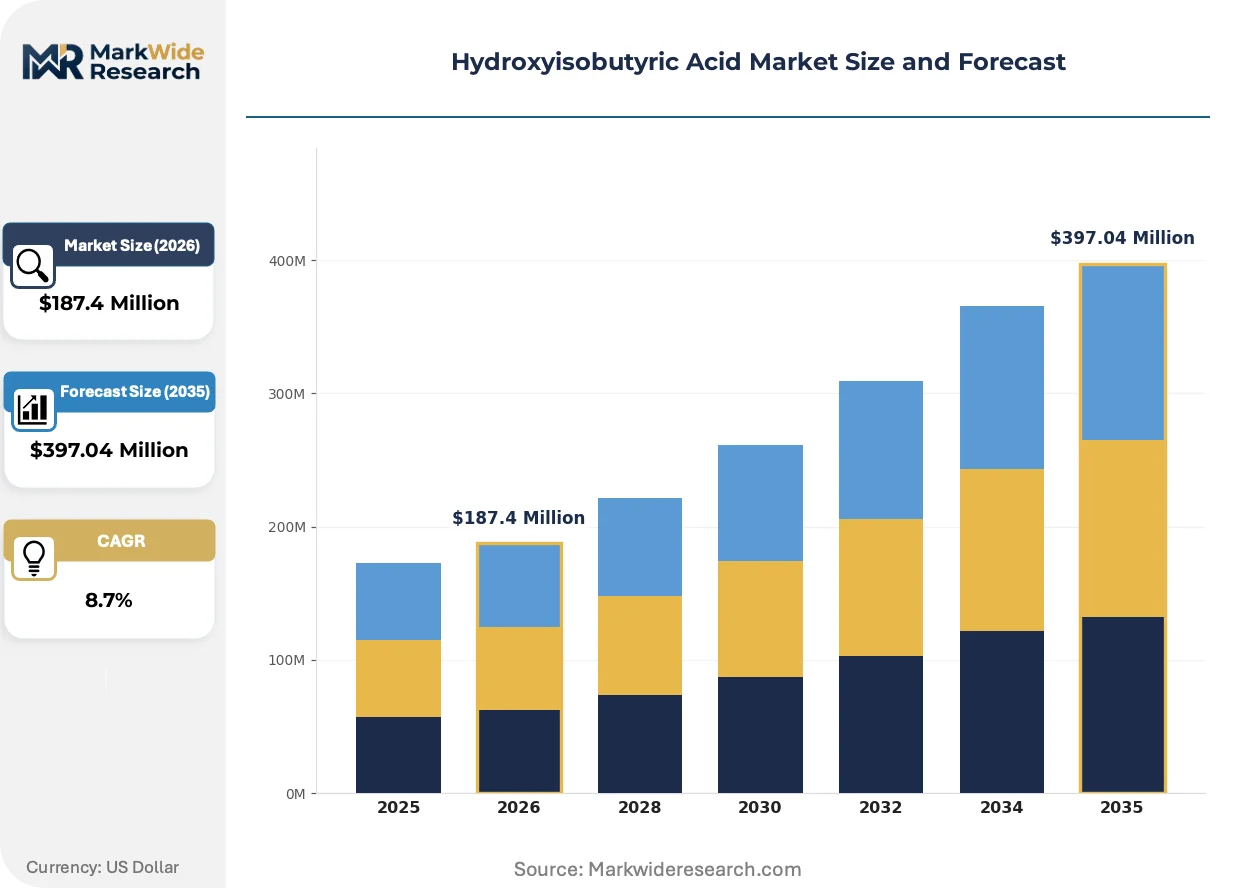
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Purified Hydroxyisobutyric Acid, Hydroxyisobutyric Acid Salts, Ester Derivatives, Mixed Isomers End User: Pharmaceutical Companies, Cosmetic Manufacturers, Food Additives, Research Institutions Application: Dietary Supplements, Pharmaceutical Intermediates, Cosmetic Formulations, Industrial Solvents Grade: Food Grade, Pharmaceutical Grade, Industrial Grade, Technical Grade |
| Companies Covered | Mitsubishi Gas Chemical, Nippoh Chemicals, Xinan Chem, Thermo Fisher Scientific Inc., Alfa Chemistry, Evonik Industries AG, BASF SE, Arkema S.A., Nippon Shokubai Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydroxyisobutyric Acid Market Emerging Trajectories
Process intensification and regulatory harmonization are reconfiguring how hydroxyisobutyric acid manufacturers compete on cost, purity, and speed-to-market across divergent end-use specifications.
Whole-cell biocatalysis is migrating from niche pharmaceutical applications to broader industrial-scale deployment. Specialty chemical producers in Germany and Switzerland are retrofitting existing fermentation assets with engineered yeast strains for (R)-hydroxyisobutyric acid production. This shift is compressing capital requirements for stereoselective capacity while raising the technical barrier for commodity entrants lacking microbial platform expertise.
EMA quality guidelines for active pharmaceutical ingredient starting materials are tightening impurity profiling requirements for hydroxyisobutyric acid supplied to drug manufacturers. The revised specifications mandate identification thresholds for unspecified impurities at 0.10 percent, forcing suppliers to implement advanced chromatographic analytical methods. European pharmaceutical intermediate buyers are consolidating qualified supplier lists in response, favoring partners with in-house quality control laboratories over trading intermediaries.
Direct procurement contracts between hydroxyisobutyric acid manufacturers and pharmaceutical formulators are displacing traditional distributor channels for high-purity grades. Large generic drug producers in India and China are establishing multi-year offtake agreements with certified producers to secure chiral building block supply continuity. This channel compression is most pronounced in oncology and cardiovascular therapeutic segments where starting material traceability requirements exclude spot-market sourcing.
Hydroxyisobutyric Acid Market Segmentation
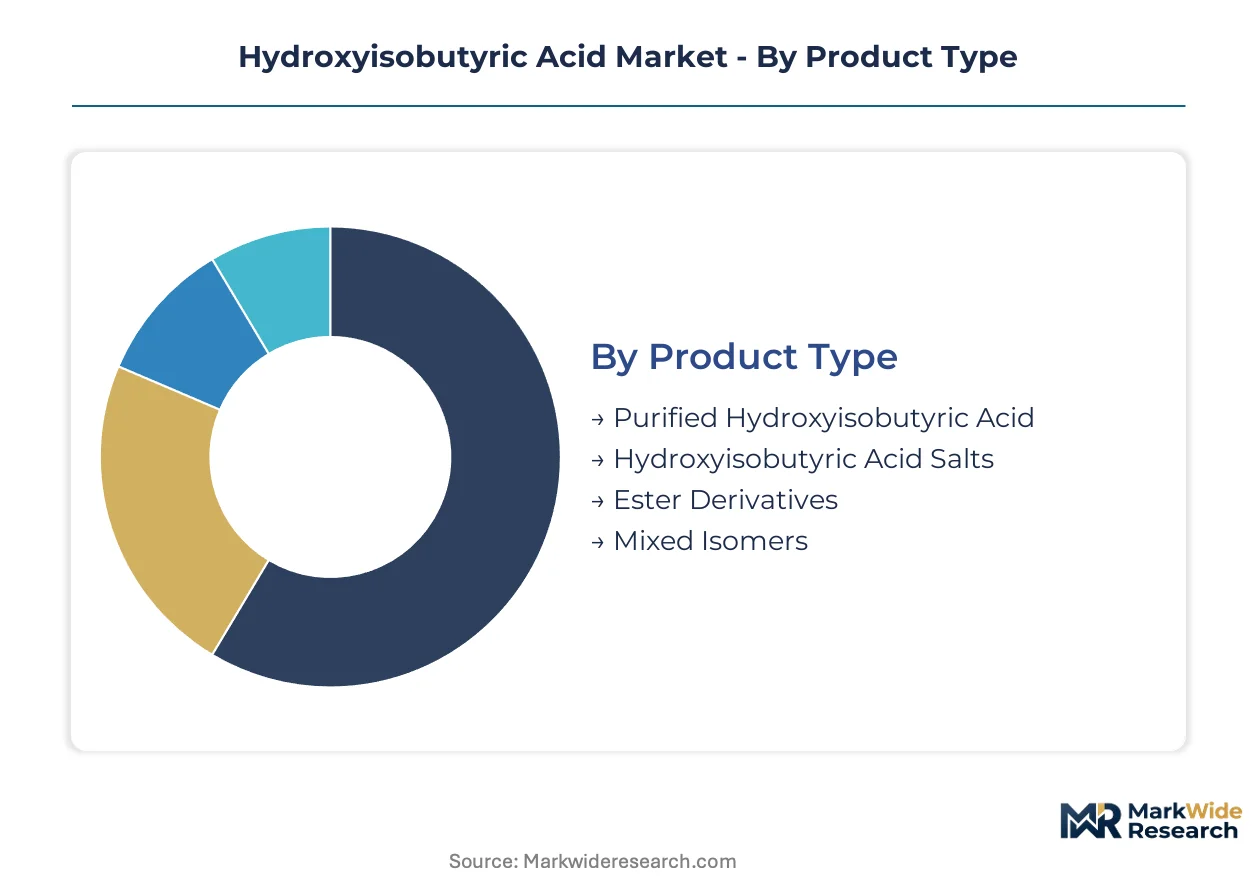
Segmentation in hydroxyisobutyric acid markets reflects divergent purity standards, regulatory burdens, and end-use performance requirements. Each tier commands distinct pricing architectures and supplier qualification barriers.
Product Type:
Application requirements across pharmaceutical synthesis, polymer modification, and nutritional formulations drive four distinct product configurations with varying chiral purity specifications.
- Ester Derivatives:Lipophilic variants synthesized through acid-catalyzed esterification enable enhanced skin penetration in cosmetic formulations. Demand concentrates among South Korean and French cosmetic manufacturers developing anti-aging serums where lipophilicity determines active ingredient bioavailability.
- Purified Hydroxyisobutyric Acid:Material meeting 98-99% purity with defined specific rotation serves as the critical chiral building block for methacrylic acid derivatives and complex pharmaceutical synthesis. FDA and EMA starting material qualification processes lock in multi-year supply agreements with certified producers.
- Hydroxyisobutyric Acid Salts:Alkali metal and ammonium salts provide improved aqueous solubility for parenteral pharmaceutical formulations and buffer systems.
- Mixed Isomers:Racemic or partially resolved material serves industrial polymer crosslinking and solvent applications where enantiomeric excess is not performance-critical.
Purified Hydroxyisobutyric Acid commands the established base. The steepest expansion runs through Ester Derivatives.
End User:
Customer sophistication and regulatory exposure create four procurement tiers with divergent technical service demands and contract structures.
- Pharmaceutical Companies:Generic drug manufacturers and innovator firms require enantiomerically pure material with complete impurity profiling and regulatory documentation packages. CDSCO export incentives in India and China's NMPA pharmaceutical reforms are consolidating procurement around qualified suppliers with dedicated regulatory affairs capacity.
- Cosmetic Manufacturers:Formulators in France, South Korea, and Switzerland source ester derivatives for premium skincare where lipophilic delivery systems command formulation premiums.
- Food Additives:Sports nutrition and dietary supplement producers seek FSSAI and EFSA food additive approvals for nutritional grade material.
- Research Institutions:Academic and contract research organizations procure small volumes of high-purity material for method development and reference standards.
Pharmaceutical Companies anchor volume commitments. Cosmetic Manufacturers are gaining share fastest.
Application:
Functional performance requirements across biological systems, chemical synthesis, and industrial processing define four application domains with distinct purity thresholds.
- Pharmaceutical Intermediates:Chiral building block applications for methacrylic acid derivatives and active pharmaceutical ingredient synthesis demand enantiomeric excess above 99% with full impurity identification per ICH Q3A guidelines. EMA revised specifications mandating 0.10% identification thresholds for unspecified impurities are disqualifying commodity suppliers.
- Cosmetic Formulations:Ester derivatives enable lipophilic active delivery in anti-aging and skin brightening products where percutaneous absorption determines efficacy.
- Dietary Supplements:Nutritional grade material serves sports nutrition formulations with FSSAI and EFSA food additive compliance requirements.
- Industrial Solvents:Lower-purity material functions in polymer crosslinking and specialty coating applications where racemic composition does not impair performance.
Pharmaceutical Intermediates dominate margin capture. Cosmetic Formulations show the steepest volume trajectory.
Grade:
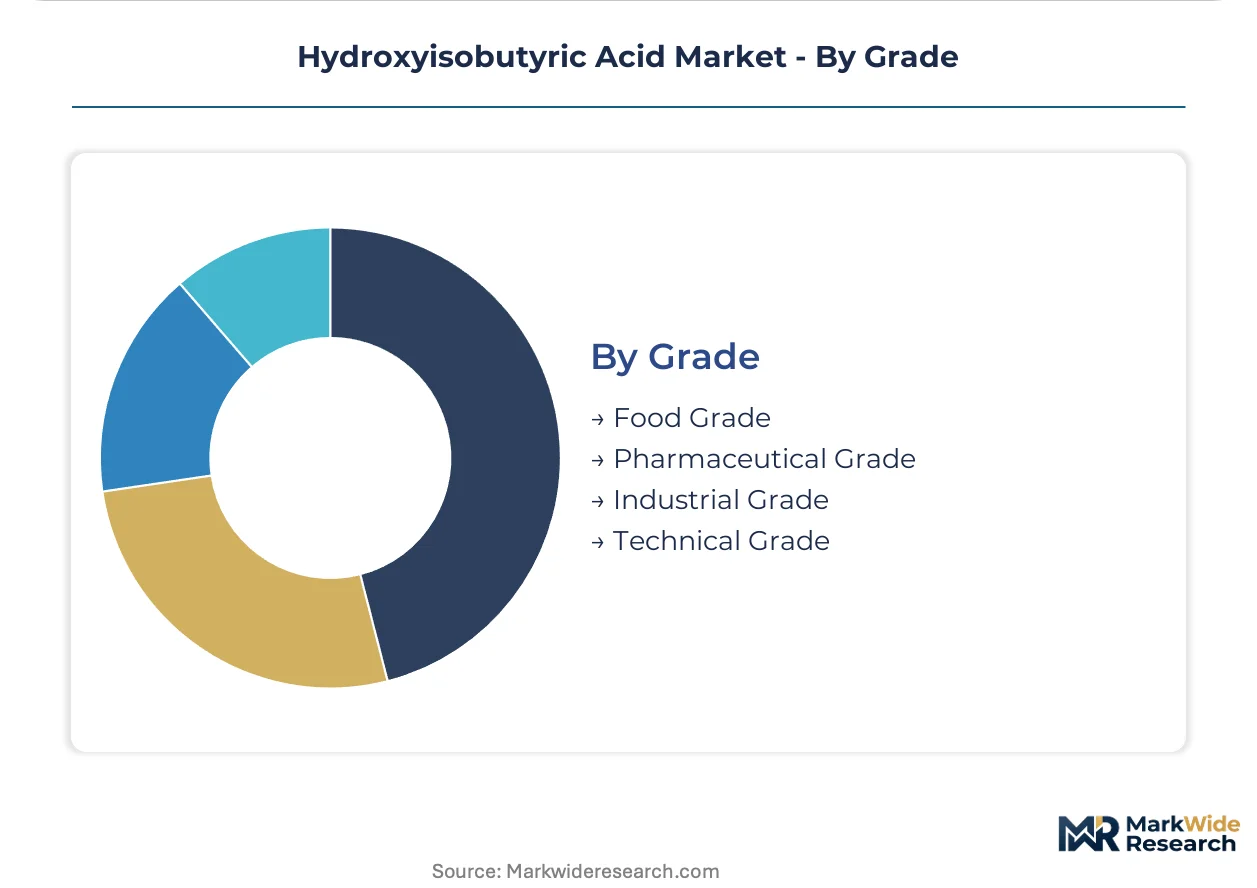
Certification intensity and analytical burden stratify supply into four quality tiers with order-of-magnitude pricing spreads.
- Pharmaceutical Grade:Material produced under FDA Good Manufacturing Practice and EMA starting material guidelines with complete impurity profiling, stability data, and regulatory documentation. Certification timelines of 18-24 months and dedicated quality control infrastructure exclude commodity producers.
- Food Grade:Nutritional and dietary supplement applications require FSSAI, EFSA, or FDA food additive compliance with microbial and heavy metal specifications distinct from pharmaceutical standards.
- Industrial Grade:Standard purity material serves polymer modification, solvent applications, and chemical synthesis where racemic composition is acceptable.
- Technical Grade:Basic purity material for research and development, pilot-scale synthesis, and non-critical industrial applications with minimal analytical documentation.
Pharmaceutical Grade concentrates premium positioning. Food Grade is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese hydroxyisobutyric acid producers export pharmaceutical-grade material to European and Indian generic drug manufacturers, establishing the dominant east-west trade corridor in chiral building blocks.
China
Jiangsu and Zhejiang province chemical manufacturers scale high-purity output for export markets as domestic CDMOs absorb growing volumes. NMPA pharmaceutical reforms tighten starting material traceability requirements. The Yangtze River Delta cluster around Shanghai anchors capacity expansion for enantiomerically pure production.
Germany
Specialty chemical producers retrofit fermentation assets with engineered biocatalysts for stereoselective manufacturing. REACH registration obligations mandate toxicological dossiers that favor established suppliers. The Rhine-Ruhr industrial corridor sustains pharmaceutical-grade output through integrated quality control infrastructure.
India
Generic drug manufacturers establish multi-year offtake agreements with certified hydroxyisobutyric acid suppliers to secure chiral building block continuity. CDSCO export incentives and PLI scheme benefits attract procurement for active ingredient synthesis. Maharashtra and Gujarat pharmaceutical clusters consolidate qualified supplier lists.
United States
FDA Good Manufacturing Practice standards for starting materials lock in demand for enantiomerically pure material with complete impurity profiling. EPA industrial chemical reporting requirements govern market access for pharmaceutical-grade supply. The New Jersey-Pennsylvania chemical corridor maintains formulation-grade distribution networks.
Switzerland
Swissmedic quality guidelines for active pharmaceutical ingredient starting materials influence purity specifications demanded by downstream drug manufacturers. Specialty chemical producers leverage enzyme engineering platforms for cost advantages in pharmaceutical-grade output. The Basel region concentrates biocatalytic expertise and regulatory affairs capacity.
Hydroxyisobutyric Acid Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic tiers differentiated by regulatory certification depth and biocatalytic capability. Established chemical conglomerates with dedicated quality control infrastructure occupy the pharmaceutical-grade segment. Mid-scale fermentation specialists compete on ester derivative volumes for cosmetic applications. Commodity producers with cyanohydrin-based routes retreat to industrial-grade racemic supply. Dominant competitive moves include capacity expansion in China's Yangtze Delta and strategic partnerships linking enzyme engineering platforms to pharmaceutical formulators.
Within the premium-tier segment, Evonik Industries AG and BASF SE exemplify European suppliers competing on global distribution density and regulatory dossier completeness. Mitsubishi Gas Chemical anchors Asian supply through integrated petrochemical feedstock positioning. These three entities represent distinct archetypes: the enzyme-engineered biocatalytic specialist, the diversified chemical conglomerate with pharmaceutical-grade certification, and the feedstock-integrated Asian producer.
| Leading Market Players |
|---|
| Mitsubishi Gas Chemical |
| Nippoh Chemicals |
| Xinan Chem |
| Thermo Fisher Scientific Inc. |
| Alfa Chemistry |
| Evonik Industries AG |
| BASF SE |
| Arkema S.A. |
| Nippon Shokubai Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Jiangsu province's Yangtze River Delta chemical cluster anchors global pharmaceutical-grade capacity expansion, translating concentrated high-purity output into asymmetric pricing leverage for certified producers serving FDA and EMA-qualified supply chains.
Pricing Analysis
Cyanohydrin-based legacy routes face widening price pressure from enzyme-engineered biocatalytic alternatives. Three-tier pricing structure across pharmaceutical, food, and industrial grades reflects certification burden and impurity profiling depth. Price differentiation centers on EMA starting material qualification status and chiral purity specifications. Pharmaceutical buyers show lowest price sensitivity due to 18-24 month supplier qualification timelines, while industrial racemic purchasers negotiate aggressively on acetone cyanohydrin feedstock pass-through.
Supply Chain Analysis
Dual-use export controls on chiral synthesis technologies constrain technology transfer to emerging biocatalytic production centers. Supply concentrates in China, Germany, and Switzerland, with hydrogen cyanide and engineered enzyme platforms as critical inputs. Single-source vulnerability runs through acetone cyanohydrin feedstock exposure to petrochemical volatility. Distribution runs through direct procurement contracts between certified manufacturers and pharmaceutical formulators, displacing traditional distributor channels for high-purity grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market cycles with pharmaceutical capital expenditure waves, as generic drug manufacturers accelerate chiral building block procurement during patent cliff periods and active ingredient synthesis expansion.
For Market Incumbents: Entrench biocatalytic capability through enzyme engineering platform investments and backward integration into engineered yeast strain supply. Cyanohydrin-based competitors threaten margin compression in pharmaceutical-grade segments. Prioritize multi-year offtake agreements with Indian CDMOs leveraging PLI scheme benefits.
For New Entrants and Emerging Players: Build out nutraceutical-grade certification capacity targeting FSSAI and EFSA food additive approvals, a white-space segment with premium pricing over industrial grades and lower regulatory barriers than pharmaceutical starting materials. Cosmetic ester derivatives in South Korea and France offer the most penetrable volume channel. Lead with lipophilic variant formulation partnerships rather than commodity acid supply.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat specialty chemical play because certification timelines and quality infrastructure requirements create durable barriers against commodity entrants. Target acquisition archetypes are mid-scale fermentation specialists with existing microbial platforms and incomplete regulatory dossiers. Watch for EMA impurity specification tightening as the signal for accelerated supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzyme Engineering Platform Investment | Evonik's directed evolution capabilities sustain cost advantages in stereoselective pharmaceutical-grade production. |
| Multi-Year Offtake Agreement | Indian generic drug manufacturers secure chiral building block continuity through CDSCO-export-linked procurement. |
| Continuous Flow Reactor Integration | Convergence with enzymatic biocatalysis enables real-time quality control and reduced batch failure rates. |
| Nutraceutical Grade Certification | FSSAI and EFSA approvals unlock sports nutrition applications with premium pricing over industrial grades. |
| Backward Integration into Feedstock | Mitsubishi Gas Chemical's petrochemical integration insulates margin from hydrogen cyanide supply disruptions. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, EMA quality guideline revisions, and SEC filings from listed chemical producers. Primary interviews engaged regulatory affairs directors at pharmaceutical intermediate suppliers, procurement leads at Indian generic drug manufacturers, and technical R&D heads at biocatalytic technology providers. Secondary validation drew from CDSCO export incentive disclosures, REACH registration databases, and NMPA pharmaceutical reform documentation. Bottom-up capacity assessments triangulated against top-down end-use demand modeling across pharmaceutical, cosmetic, and nutritional applications.
Forecast inputs include biocatalytic yield improvement trajectories, regulatory specification evolution, and regional production cost differentials across the projection horizon. Segmentation dimensions span grade tier, end-use industry, chiral purity specification, and regional production hub. CAGRs derive from weighted scenario analysis incorporating technology substitution rates and certification timeline compression. Industry-specific inputs capture enzyme engineering talent availability and dual-use export control enforcement intensity.
Stress conditions across hydrogen cyanide supply disruptions, EMA impurity threshold revisions, and biocatalytic scale-up bottlenecks were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions on regulatory harmonization pace and pharmaceutical outsourcing trends. Material shifts in FDA starting material qualification requirements or REACH registration cost structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Iodoacetonitrile Market
Chemical Intermediates
Polyamide Intermediate Chemicals Market
Chemical Intermediates
Epoxy Silanes Market
Chemical Intermediates
Nutrition Chemicals Market
Chemical Intermediates
Metal Alkyls Market
Chemical Intermediates
Glycidyl Methacrylate Market
Chemical Intermediates
Elemental Formula Market
Chemical Intermediates
Triisobutyl Phosphate Market
Chemical Intermediates
Fungal Staining Reagent Market
Chemical Intermediates
Global Textile Finishing Chemicals Market
Chemical Intermediates
United States Cellulose Acetate Market
Chemical Intermediates
Ph Controlling Agents Market
Chemical Intermediates
Dimethyl Dicarbonate Market
Chemical Intermediates
Octenylsuccinate Market
Chemical Intermediates
Palmitoyl Chloride Market
Chemical Intermediates
Preformulation Intermediates Market