
 Iodoacetonitrile Market | 2026-2036
Iodoacetonitrile Market Size, Share, and Industry Trends Forecast 2026-2036
Iodoacetonitrile Market Insights
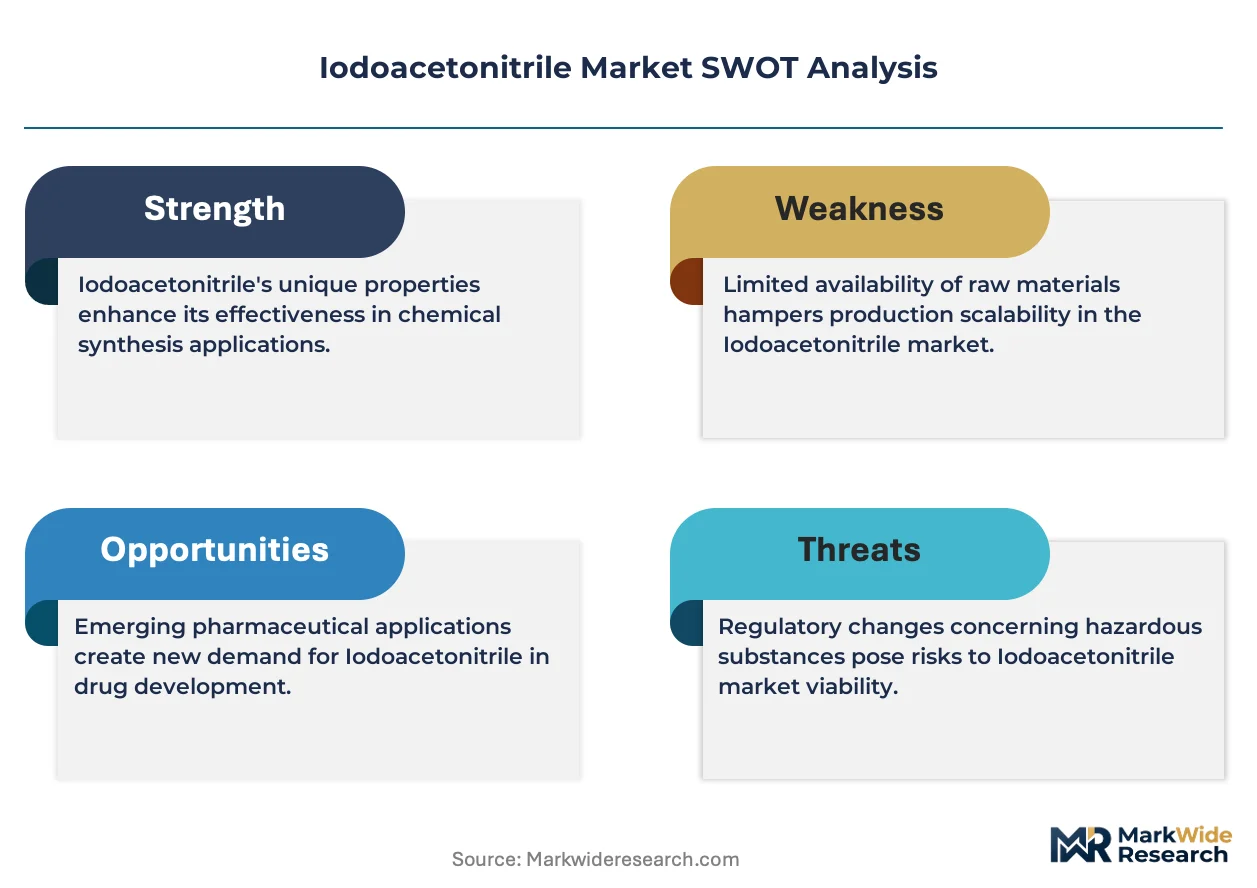
Pharmaceutical synthesis demand is broadening the addressable base for iodoacetonitrile suppliers. Merck leverages its global distribution network to supply research-grade reagents across multiple continents. Thermo Fisher Scientific sustains competitive positioning through deep integration with pharmaceutical quality control workflows. Finetech Industry specializes in custom synthesis volumes for early-stage drug discovery programs.
Iodoacetonitrile is a halogenated nitrile compound with the molecular formula C2H2IN, characterized by a high-reactivity iodine substituent that facilitates nucleophilic substitution in organic synthesis. The compound serves primarily as an alkylating reagent and synthetic intermediate in pharmaceutical and agrochemical manufacturing, requiring storage below 30 degrees Celsius and moisture-free conditions to prevent degradation. Reagents and intermediates command the strongest margin pools due to stringent purity certifications and batch-specific documentation requirements. Pharmaceutical applications lead volume consumption, while agrochemical synthesis represents the fastest-growing demand channel as crop science companies advance novel active ingredient pipelines.
EPA chemical management protocols and REACH registration requirements in Europe shape product specifications and market access conditions for iodoacetonitrile manufacturers. China's NMPA and GB standards impose additional impurity thresholds on imports used in pharmaceutical applications. Stakeholders must monitor regulatory divergence across these jurisdictions to align inventory and certification strategies with evolving compliance landscapes.
Market Dynamics
Contract research organizations in Germany, China, and the United States are consolidating procurement volumes for high-purity iodoacetonitrile, compressing supplier margins while elevating batch documentation requirements as the dominant market-shaping force.
Growth Catalysts
- REACH compliance mandates:European ECHA registration requirements for halogenated nitriles are forcing pharmaceutical manufacturers to source certified research-grade materials, expanding the addressable supplier base.
- Agrochemical pipeline advancement:Crop science companies advancing novel active ingredient programs are adopting iodoacetonitrile as a nucleophilic substitution intermediate in herbicide and fungicide synthesis.
- Custom synthesis scaling:Early-stage drug discovery programs in Boston and Shanghai are concentrating demand for small-batch, high-purity alkylating reagents with full chain-of-custody documentation.
Market Restraints
- Iodine feedstock volatility:Chilean and Japanese iodine supply concentration exposes producers to price swings in the primary raw material for iodoacetonitrile synthesis.
- Moisture sensitivity:The compound's degradation below 30 degrees Celsius and under humid conditions necessitates cold-chain logistics that inflate delivered costs versus alternative alkylating agents.
- EPA chemical management friction:Evolving United States EPA protocols for halogenated nitriles create registration uncertainty that delays new supplier market entry and extends compliance timelines.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO regulatory alignment with ICH standards is positioning Mumbai and Hyderabad as alternative sourcing hubs for research-grade intermediates serving Western contract research organizations.
- Continuous flow synthesis adoption:Microreactor technology integration with traditional batch processes promises yield improvements and reduced iodine waste in iodoacetonitrile production.
- Green chemistry incentives:EU Green Deal funding for sustainable pharmaceutical manufacturing creates preference for suppliers demonstrating solvent recovery and waste reduction in halogenated nitrile synthesis.
Industry Challenges
- Analytical chemist scarcity:Specialized expertise in residual iodide detection and chiral purity verification for research-grade certifications commands premium compensation and constrains quality control scaling.
- Multi-jurisdiction documentation:Simultaneous compliance with REACH dossiers, EPA TSCA filings, and China NMPA impurity thresholds fragments regulatory affairs resources and extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iodoacetonitrile Market |
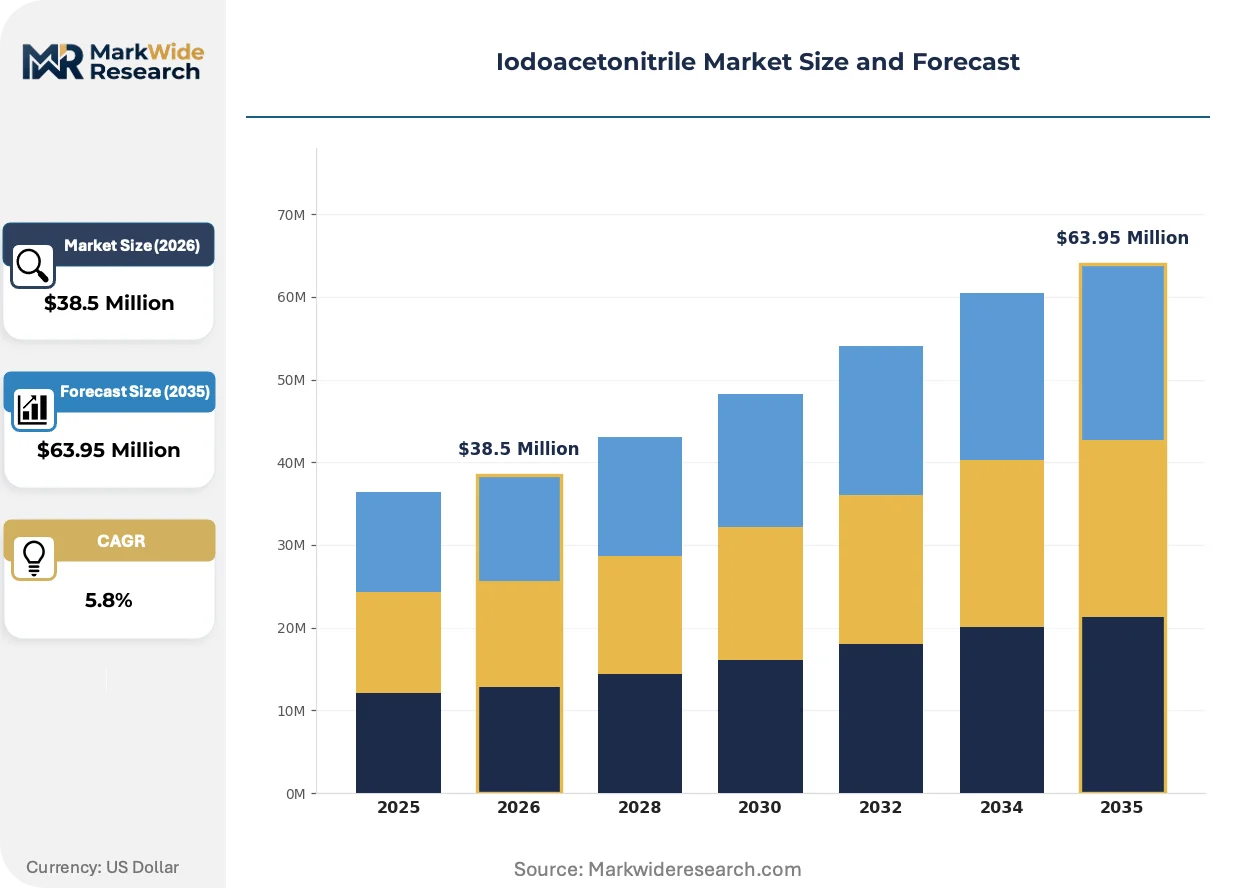
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $63.95 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Intermediates, Solvents, Catalysts Application: Synthesis, Pharmaceutical, Agrochemical, Chemical Manufacturing End User: Research Laboratories, Chemical Companies, Academia, Pharmaceutical Firms Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | Merck, Thermo Fisher Scientific, Finetech Industry, Alfa Chemistry, BOC Sciences, Sinfoobiotech, Yuhao Chemical, Hairui Chemical, Oakwood Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iodoacetonitrile Market Trends and Innovations
Pharmaceutical quality control workflows and agrochemical discovery pipelines are reshaping how iodoacetonitrile specifications are defined, with purity thresholds and documentation depth becoming primary competitive differentiators.
Microreactor-based continuous flow synthesis is modularizing iodoacetonitrile production architecture. Mid-scale suppliers in Basel and Basel-adjacent chemical clusters are adopting plug-and-play reactor modules to reduce batch-to-batch variability. This technology is modularizing capital deployment, enabling producers to scale capacity in 500-liter increments rather than committing to traditional 5,000-liter batch vessels upfront.
China's NMPA implementation of ICH Q3D elemental impurity guidelines is tightening acceptance thresholds for heavy metal contamination in pharmaceutical-grade halogenated nitriles. Domestic producers in Jiangsu province are retrofitting purification trains to meet these specifications. European importers sourcing from Chinese contract manufacturers now require third-party verification of NMPA compliance documentation prior to customs clearance.
Research-grade reagent buyers are consolidating vendor relationships around suppliers offering integrated digital batch records with LIMS compatibility. Contract research organizations in Cambridge, Massachusetts and Cambridge, United Kingdom are prioritizing vendors whose certificates of analysis integrate directly with electronic laboratory notebook systems. This preference shift is most pronounced in oncology discovery programs where audit trail completeness influences funding agency compliance reviews.
Iodoacetonitrile Market Segmentation
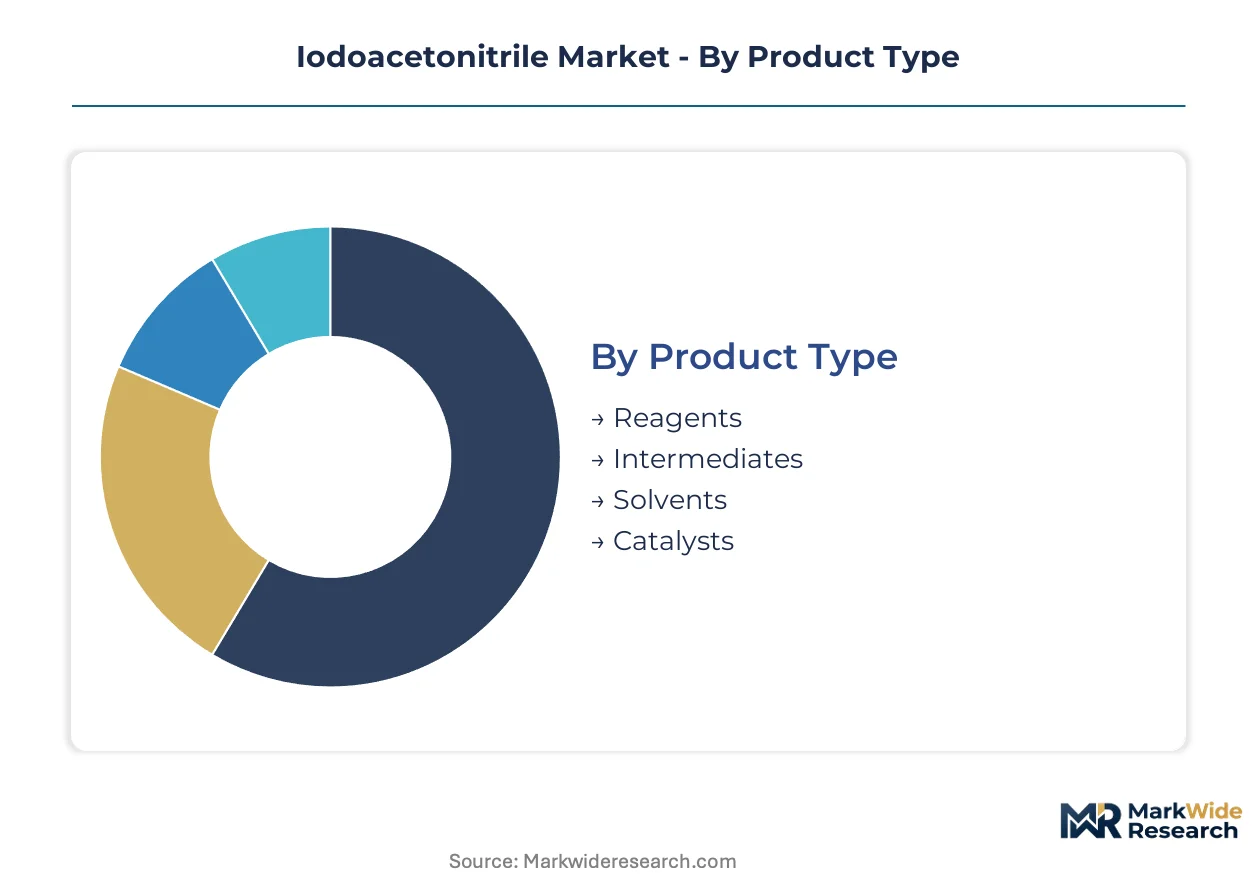
Iodoacetonitrile procurement patterns diverge sharply across user categories, with purity specifications and documentation requirements creating distinct commercial tiers. Suppliers must align certification depth and logistics infrastructure with each segment's technical and regulatory demands.
Product Type:
Supply concentration among certified producers favors segments with the steepest documentation barriers, locking in margin premiums for validated batches.
- Reagents:Research-grade formulations exceeding 98% purity with full chain-of-custody documentation command the widest supplier spreads. Pharmaceutical quality control workflows in Germany and Massachusetts concentrate demand here, with ECHA REACH dossiers and EPA TSCA filings required for each lot.
- Intermediates:Bulk quantities for downstream synthesis carry reduced certification overhead but face iodine feedstock volatility from Chilean and Japanese supply concentration. Agrochemical manufacturers in Jiangsu province and crop science clusters near Basel represent the primary demand nodes.
- Solvents:Formulation-grade material serves reaction media applications with moderate purity thresholds.
- Catalysts:Specialized activation chemistries for halogenation processes occupy niche volumes.
Today's leader: Reagents. Tomorrow's challenger: Intermediates.
Application:
Cost tier stratification separates premium-certified pharmaceutical use from volume-driven agrochemical adoption.
- Synthesis:General organic chemistry applications span academic and industrial laboratories with variable purity requirements.
- Pharmaceutical:GMP-aligned manufacturing demands NMPA, EMA, and FDA-compliant documentation batches. CDSCO alignment in India is redirecting some contract research organization procurement toward Mumbai and Hyderabad facilities.
- Agrochemical:Novel active ingredient pipelines for herbicides and fungicides are expanding most quickly. Crop science companies in Research Triangle Park and Shanghai chemical parks are scaling nucleophilic substitution protocols.
- Chemical Manufacturing:Commodity-scale consumption for industrial alkylating processes operates on leaner margins.
Pharmaceutical applications anchor current value capture. Agrochemical synthesis shows the steepest expansion trajectory.
End User:
Volume concentration among multi-site contract research organizations is compressing supplier margins while elevating service requirements.
- Research Laboratories:Small-batch procurement with stringent audit trail requirements dominates oncology and infectious disease discovery programs in Cambridge, Massachusetts and Cambridge, United Kingdom.
- Chemical Companies:Integrated manufacturers with captive synthesis capabilities source selectively for capacity gaps.
- Academia:University procurement operates on constrained budgets with reduced documentation depth.
- Pharmaceutical Firms:Large-scale manufacturers demand vertical integration into supplier quality systems with LIMS-compatible batch records.
Research laboratories drive specification innovation. Pharmaceutical firms consolidate procurement leverage.
Distribution Channel:
Customer type fragmentation between digital-native procurement teams and relationship-dependent technical buyers shapes channel viability.
- Online Retail:E-procurement platforms serve routine reagent replenishment for standardized catalog items. Electronic laboratory notebook integration is becoming a selection criterion for contract research organizations in Boston and Basel.
- Direct Sales:Technical field support for custom synthesis volumes and regulatory dossier preparation retains preference for complex pharmaceutical engagements.
- Wholesalers:Inventory pooling reduces lead times for predictable consumption patterns.
- Distributors:Regional logistics networks manage cold-chain requirements for moisture-sensitive shipments.
Direct sales commands pharmaceutical premium capture. Online retail is gaining share fastest among standardized reagent procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redistributing iodoacetonitrile production capacity toward jurisdictions with streamlined chemical registration frameworks. Producers in India and China capture contract manufacturing volumes that European facilities cede due to REACH compliance cost burdens.
United States
Contract research organizations in Cambridge, Massachusetts and Research Triangle Park drive demand for GMP-certified reagents with full chain-of-custody documentation. EPA chemical management protocols for halogenated nitriles impose evolving registration requirements that extend supplier qualification timelines. Boston-area pharmaceutical clusters concentrate procurement leverage among multi-site buyers.
Germany
Basel-adjacent chemical parks and Frankfurt-Rhine-Main pharmaceutical hubs sustain Europe's deepest demand pool for research-grade alkylating reagents. ECHA REACH registration mandates for halogenated nitriles force manufacturers to maintain comprehensive substance dossiers. Ludwigshafen and Leverkusen industrial corridors host integrated producers with captive synthesis capabilities.
China
Jiangsu province chemical manufacturers retrofit purification trains to meet NMPA ICH Q3D elemental impurity guidelines for pharmaceutical exports. GB standards and evolving MEE environmental protocols shape domestic production specifications. Shanghai chemical parks and Suzhou industrial zones anchor contract synthesis capacity serving Western drug discovery programs.
India
CDSCO regulatory alignment with ICH standards positions Mumbai and Hyderabad as alternative sourcing hubs for research-grade intermediates. The country's national pharmaceutical regulator is tightening impurity thresholds on imported starting materials. Gujarat and Telangana manufacturing corridors attract contract research organization procurement migrating from higher-cost European suppliers.
Iodoacetonitrile Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. Research-grade reagent supply concentrates among distributors with global logistics networks and regulatory dossier capabilities. Three archetypes dominate: integrated life science conglomerates with catalog breadth, pure-play custom synthesis houses, and regional chemical manufacturers with cost-optimized batch production. Competitive moves center on digital batch record integration and cold-chain logistics partnerships.
Among integrated life science suppliers, Merck and Thermo Fisher Scientific occupy positions defined by global distribution infrastructure and pharmaceutical quality control workflow integration. Finetech Industry exemplifies the custom synthesis archetype, anchoring early-stage drug discovery procurement with small-batch, high-purity capabilities. These three represent distinct competitive vectors: scale-driven catalog coverage, technical field support depth, and flexible batch production.
| Leading Market Players |
|---|
| Merck |
| Thermo Fisher Scientific |
| Finetech Industry |
| Alfa Chemistry |
| BOC Sciences |
| Sinfoobiotech |
| Yuhao Chemical |
| Hairui Chemical |
| Oakwood Products |
| Others |
Pricing and Supply Chain Analysis
Analytical chemist scarcity in Basel-adjacent chemical clusters widens labor-cost differentials between European and Asian production hubs, translating into three-tier pricing spreads across research-grade, pharmaceutical-intermediate, and commodity solvent grades.
Pricing Analysis
Distributor margins compress most severely in standardized reagent tiers where electronic procurement platforms disintermediate technical field support. Pricing stratifies across premium-certified, standard-grade, and economy-solvent tiers driven by purity certification depth and cold-chain logistics bundling. Cost compression in economy grades intensifies because iodine feedstock volatility from Chilean and Japanese suppliers squeezes producer margins. Contract research organizations in Boston and Basel exhibit lowest price sensitivity, while academic procurement teams in European university systems demonstrate highest elasticity.
Supply Chain Analysis
Cold-chain freight costs inflate delivered pricing by 15-25% for moisture-sensitive shipments requiring sub-30-degree Celsius transit conditions. Supply concentrates in China, Germany, and India, with Jiangsu province and Mumbai-Hyderabad corridors capturing contract manufacturing volumes. Synthesis draws from iodine feedstock, acetonitrile solvent, and catalytic halogenation reagents. Single-source vulnerability in Chilean iodine extraction creates concentration risk. Distribution runs through direct sales for pharmaceutical engagements and regional distributors for standardized reagent replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Iodoacetonitrile procurement represents a geographic-arbitrage play where REACH compliance burdens in Europe push contract research organization demand toward CDSCO-aligned Indian suppliers with equivalent ICH certification at lower cost structures.
For Market Incumbents: Anchor market position through backward integration into iodine feedstock sourcing and captive purification train investments in Basel-adjacent facilities. Custom synthesis houses from China are eroding margin pools in mid-tier pharmaceutical intermediates. Certification investment in NMPA-compliant documentation capabilities protects European supplier relevance for Western drug discovery programs.
For New Entrants and Emerging Players: Launch via online retail platforms targeting standardized reagent procurement in research laboratories with LIMS-compatible batch records. Agrochemical synthesis in Shanghai chemical parks and Research Triangle Park offers the most penetrable white space. Position through electronic laboratory notebook integration as the primary go-to-market wedge.
For Investors and Strategic Acquirers: Life science conglomerates with catalog breadth are the most active acquirers in this space, consolidating custom synthesis capabilities to fill pipeline gaps. Over a multi-year horizon, viability hinges on regulatory dossier depth rather than scale alone. Monitor EPA chemical management protocol evolution as the critical inflection signal for US market access conditions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Iodine Feedstock | Reduces exposure to Chilean supply concentration and stabilizes input costs for halogenated nitrile synthesis. |
| NMPA Certification Investment | Enables customs clearance for pharmaceutical-grade exports to European contract research organizations. |
| Continuous Flow Synthesis Adoption | Microreactor technology in Basel facilities cuts batch-to-batch variability and iodine waste. |
| LIMS-Compatible Batch Records | Electronic laboratory notebook integration captures procurement preference from Cambridge oncology programs. |
| Joint Venture in Mumbai Corridor | CDSCO-aligned production capacity serves Western contract research organizations migrating from European suppliers. |
Research Methodology
Coverage spans Germany, China, the United States, and India, with primary inputs from each jurisdiction combined with secondary validation. Interviews with custom synthesis directors, pharmaceutical procurement leads, regulatory affairs specialists, and cold-chain logistics coordinators informed demand-side dynamics. Secondary sources included ECHA REACH dossiers, EPA TSCA filings, NMPA ICH Q3D implementation guidance, and customs trade data for halogenated nitrile flows. Bottom-up volume estimates triangulated against top-down market sizing across the analysis window.
Rate-of-change decomposition separated volume growth from price-mix effects across product type, application, end user, and distribution channel dimensions. CAGRs derived from segmented growth trajectories incorporating iodine feedstock cost indices, regulatory compliance timeline assumptions, and contract research organization procurement scaling patterns. Forecast inputs weighted agrochemical pipeline advancement and continuous flow synthesis adoption as technology-driven demand shapers.
Several conditions sit outside the modeled scope, including abrupt iodine supply disruptions from Chilean geopolitical events, rapid EPA protocol revisions halting new supplier registrations, and breakthrough displacement by non-halogenated alkylating reagents. Forecasts reflect documented assumptions about regulatory stability and feedstock cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Global Glycinates Market
Chemical Intermediates
Tertiary Butylhydroquinone Acids Market
Chemical Intermediates
Thiochemicals Market
Chemical Intermediates
Pharmaceutical Intermediates Market
Chemical Intermediates
Duloxetine Intermediate and Atorvastatin Intermediates Market
Chemical Intermediates
Lauoryl Chloride Market
Chemical Intermediates
Potential Hydrogen (Ph) Adjusters Market
Chemical Intermediates
Refinery Process Chemicals Market
Chemical Intermediates
Montelukast Intermediate Market
Chemical Intermediates
Phosphate Chemical Reagents Market
Chemical Intermediates
Carboxylic Acid Chlorides Market
Chemical Intermediates
Copper Chemicals Market
Chemical Intermediates
Metal Alkyls Market
Chemical Intermediates
Glycidyl Methacrylate Market
Chemical Intermediates
Organometallic Compounds Market
Chemical Intermediates
Dye Intermediates Market