
 Global Aniline Derivative Market | 2026-2036
Global Aniline Derivative Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aniline Derivative Market Foresight
Buyer concentration across agrochemical manufacturers is consolidating as multinational crop science firms reduce supplier counts and demand batch-to-batch consistency. Aarti Industries Ltd leverages integrated nitration infrastructure to secure long-term offtake agreements with these consolidated buyers. Deepak Novochem Technologies Limited anchors its position through specialized acetoacetanilide production for dye intermediate applications. Karoon Petrochemical Company competes on feedstock proximity, operating adjacent to benzene supply corridors in the Middle East.
Aniline derivatives comprise functionalized aromatic amines produced through electrophilic substitution, nitration-reduction sequences, or condensation reactions with formaldehyde and sulfur trioxide, serving primarily as molecular building blocks for rubber vulcanization, colorant synthesis, and crop protection chemistry. Acetoacetanilides dominate current volume flows due to their entrenched role in azo pigment manufacturing for textile processing and paints coatings. Aniline sulfonates represent the fastest-expanding product category as pharmaceutical production scales crystallization-grade material for sulfonamide antibiotic precursors. Rubber accelerators constitute a mature application segment where pricing power has eroded amid commoditization of thiazole and guanidine derivatives.
EPA toxicity thresholds under the Toxic Substances Control Act and REACH registration requirements under ECHA constrain market access for non-compliant producers, elevating compliance costs but protecting incumbent positions for certified manufacturers. China's MEE enforcement of dual carbon goals is pressuring coal-based aniline routes toward natural gas feedstock switching, altering regional cost structures. Stakeholders must monitor regulatory divergence between EU Green Deal chemical restrictions and India's PLI scheme incentives for domestic intermediate manufacturing, as these policy trajectories will reshape sourcing geography and capital allocation priorities.
Market Dynamics
REACH registration deadlines and EPA toxicity thresholds are compressing supplier viability, forcing batch-traceability investments that favor integrated nitration operators over merchant traders. This regulatory squeeze is consolidating offtake relationships around certified manufacturers with captive reduction capacity.
Growth Catalysts
- Sulfonamide antibiotic demand:Pharmaceutical manufacturers are scaling crystallization-grade aniline sulfonate procurement for active ingredient synthesis, tightening purity specifications across supplier base.
- India PLI scheme:Domestic intermediate manufacturing incentives are attracting capital toward acetoacetanilide and dye intermediate capacity expansion in Gujarat and Maharashtra clusters.
- Natural gas feedstock switching:China's MEE enforcement of dual carbon goals is pressuring coal-based aniline routes toward methane-derived benzene supply, altering regional cost structures.
Market Restraints
- Benzene price volatility:Crude oil linkage and refinery operating rate fluctuations transmit directly into aniline derivative cost structures, compressing margin predictability for non-integrated processors.
- ECHA registration friction:REACH data requirements and substance evaluation timelines create multi-year market access barriers for new entrants lacking existing dossier portfolios.
- Azo pigment substitution:High-performance organic pigments and inorganic colorants are displacing traditional acetoacetanilide-based azo dyes in premium coatings applications.
Strategic Opportunities
- Brazil agrochemical formulation:ANVISA registration harmonization with OECD standards is opening import pathways for sulfonated intermediates in crop protection chemistry.
- Continuous flow nitration:Microreactor technology convergence with automated process control is enabling modular capacity deployment with reduced safety inventory requirements.
- EU Green Deal chemical restrictions:Hazardous substance phase-out mandates are creating first-mover advantage for bio-based aniline derivative alternatives meeting CSRD disclosure thresholds.
Industry Challenges
- Process safety engineering scarcity:Experienced nitration hazard assessment specialists command premium compensation, constraining expansion timelines for brownfield projects.
- Legacy DCS integration complexity:Batch record digitization for ECHA audit trails requires retrofitting analog control systems with ISA-95 compliant data historians.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aniline Derivative Market |
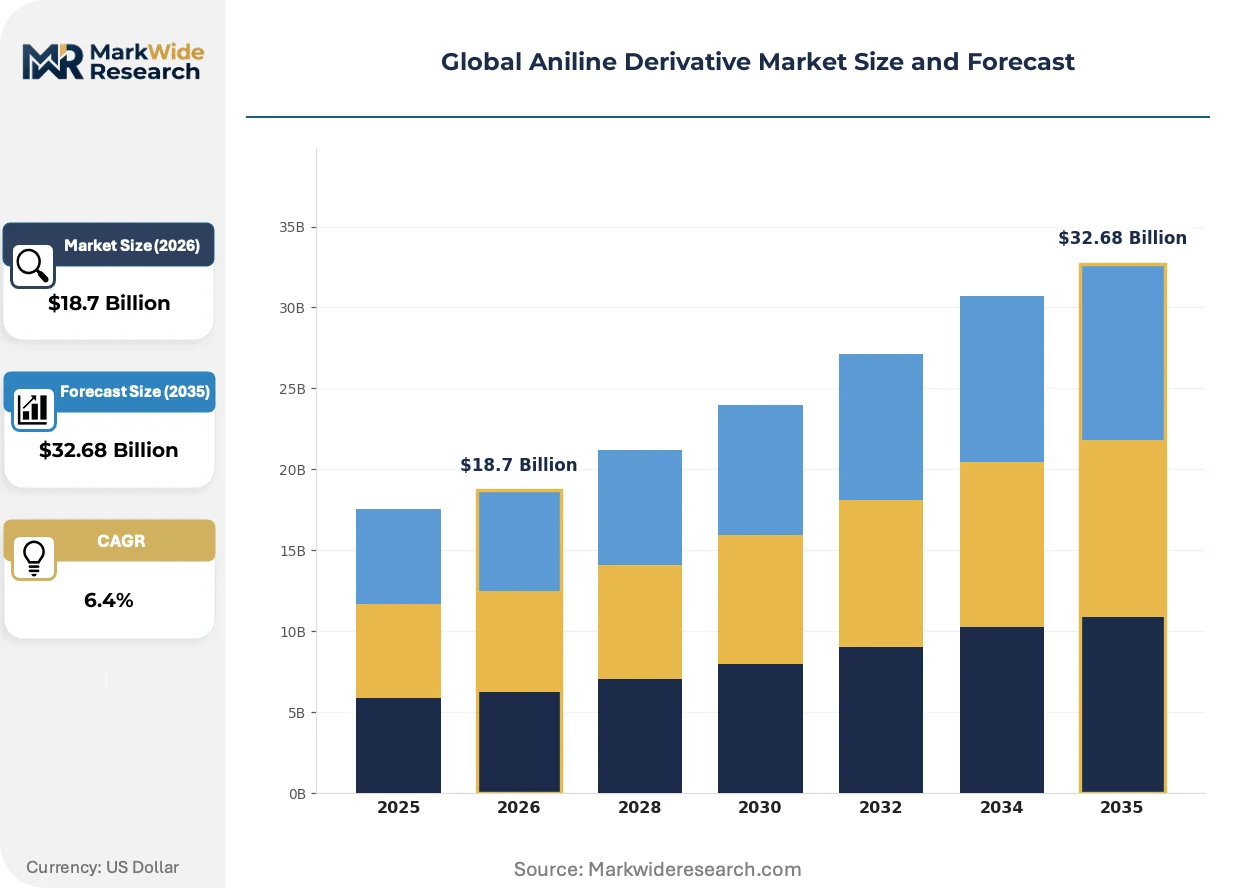
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aniline Sulfonates, Acetoacetanilides, Aniline Formaldehyde, Aniline Phosphates, Aniline Oxides Application: Rubber Accelerators, Dyes & Pigments, Herbicides, Pharmaceuticals, Dye Intermediates End User Industry: Agrochemical Manufacturers, Textile Processing, Pharmaceutical Production, Rubber Goods Manufacturing, Paints & Coatings Packaging Type: Drums, Bulk Bags, Intermediate Bulk Containers, Flexible Containers, Fiberboard Boxes |
| Companies Covered | Panoli Intermediates India Private Limited, Karoon Petrochemical Company, Azelis, Deepak Novochem Technologies Limited, Honshu Chemical Industry Co., Ltd, Aarti Industries Ltd, Mitsuboshi Chemical Co.,Ltd, Valiant Organics Limited, Industrial Solvents & Chemicals Pvt. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aniline Derivative Market Shifts & Advancements
Electrophilic substitution chemistry and downstream purification protocols are undergoing platform-level revision as sustainability metrics penetrate procurement scorecards. Three convergent developments are compressing incumbent process economics.
Continuous flow microreactor technology is rewriting nitration safety economics by enabling sub-stoichiometric reagent dosing with real-time thermal monitoring. Specialty chemical manufacturers in Germany and Japan are retrofitting pilot plants with Corning Advanced-Flow reactors, achieving residence time compression from hours to seconds. This shift is collapsing minimum efficient scale thresholds and enabling distributed production closer to benzene terminals.
EU Green Deal chemical restrictions under the CSRD framework are mandating substance-level carbon footprint disclosure for imported intermediates. ECHA is aligning REACH authorization lists with PFAS and persistent organic pollutant criteria, elevating compliance documentation burdens for non-EU suppliers. Affected traders are commissioning third-party lifecycle assessments to defend market access positions.
Multinational agrochemical formulators are consolidating approved supplier lists and demanding batch-level impurity profiling with certificate-of-analysis standardization. Direct procurement contracts are displacing distributor intermediation for volume sulfonate and accelerator grades, compressing trading margins in Rotterdam and Singapore hubs. Bayer Crop Science and Syngenta procurement teams are driving this consolidation most visibly in European and North American tender processes.
Global Aniline Derivative Market Segmentation
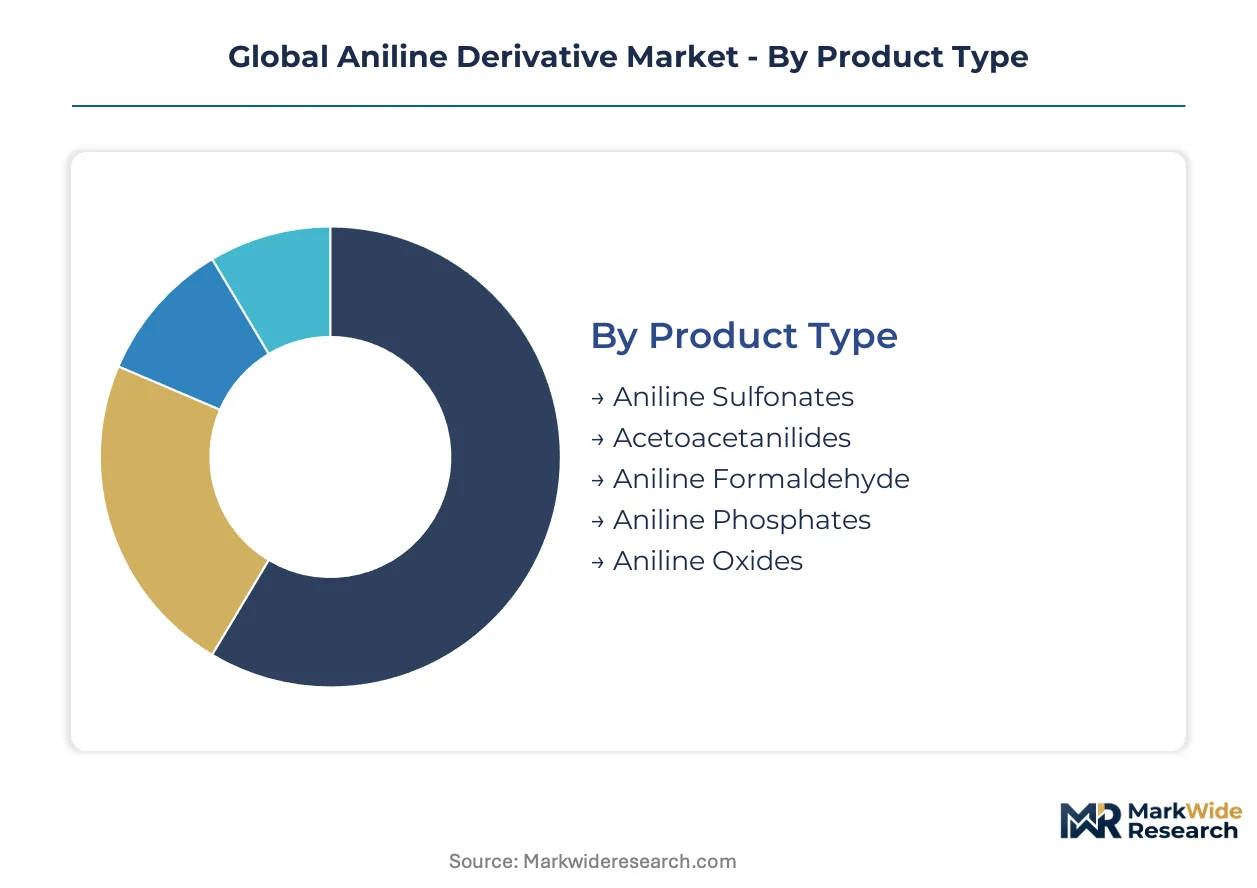
Product differentiation in aniline derivatives hinges on functional group substitution patterns that determine downstream reactivity. Manufacturers configure production trains around specific electrophilic substitution pathways, locking in dedicated capacity for sulfonation, acetoacetylation, or condensation chemistries.
Product Type:
Customization intensity varies sharply across this category, from standardized commodity sulfonates to specification-driven phosphates requiring pharmaceutical-grade certification.
- Acetoacetanilides:Beta-keto amide structures formed through diketene condensation with aniline feedstock. Textile processing operations in India and China concentrate procurement for azo pigment coupling reactions, though ECHA authorization pressures are compressing volumes in EU-bound coatings applications.
- Aniline Sulfonates:Aromatic sulfonic acid salts produced via oleum or SO3 sulfonation with controlled para-substitution ratios. Crystallization-grade material demand from sulfonamide antibiotic manufacturers in Germany and Switzerland is tightening purity specifications to sub-50ppm heavy metal thresholds.
- Aniline Formaldehyde:Condensation polymers with controlled methylol substitution used as rubber adhesion promoters. Agrochemical formulation facilities in Brazil represent the primary consumption anchor.
- Aniline Phosphates:Organophosphate derivatives serving flame-retardant applications in engineered polymers. Specialty compounders in Japan and South Korea drive specification development.
- Aniline Oxides:N-oxidized derivatives with niche surfactant and corrosion inhibitor applications. Limited commercial scale restricts supplier participation to integrated nitration operators.
Most installed capacity flows through acetoacetanilide trains. Expansion is steepest in aniline sulfonates.
Application:
Margin profiles diverge across this category based on regulatory burden intensity, with pharmaceutical and agrochemical applications commanding certification premiums over commodity rubber and dye segments.
- Dyes & Pigments:Azo coupling chemistry utilizing acetoacetanilide and sulfonated intermediates for textile and coatings coloration. Gujarat and Maharashtra industrial clusters in India concentrate derivative demand, though water discharge regulations under MEE enforcement are elevating treatment costs for lake pigment manufacturers.
- Pharmaceuticals:Sulfonamide antibiotic precursors and crystallization-grade intermediates for active ingredient synthesis. CDSCO filing requirements and US FDA DMF expectations are consolidating supplier relationships around audit-ready manufacturers with dedicated GMP suites.
- Rubber Accelerators:Thiazole and guanidine derivatives for vulcanization kinetics control. Pricing power erosion amid Chinese oversupply is compressing margins for non-integrated European producers.
- Herbicides:Sulfonylurea and imidazolinone intermediate synthesis for crop protection chemistry. ANVISA registration harmonization with OECD standards is opening Brazilian formulation market access.
- Dye Intermediates:Purified aniline derivatives for downstream azo and anthraquinone synthesis. Batch-to-batch consistency requirements from consolidated multinational buyers are displacing spot market trading.
Volume concentration sits in dyes and pigments. Value expansion is climbing the fastest in pharmaceutical-grade applications.
End User Industry:
Procurement sophistication tiers separate this category, with pharmaceutical and agrochemical buyers imposing certificate-of-analysis standardization that rubber goods manufacturers rarely demand.
- Agrochemical Manufacturers:Multinational crop science firms including Bayer Crop Science and Syngenta drive consolidated supplier list rationalization. Tender processes in Germany and North America now mandate batch-level impurity profiling with 18-month stability data.
- Pharmaceutical Production:Active ingredient synthesis operations require crystallization-grade sulfonates with documented genotoxic impurity controls. EMA and FDA audit readiness is filtering supplier viability to integrated manufacturers with captive quality laboratories.
- Textile Processing:Dye house operations in Surat and Tiruppur clusters consume acetoacetanilide derivatives for azo pigment coupling. BIS certification requirements are elevating documentation burdens for imported intermediates.
- Rubber Goods Manufacturing:Tire and industrial rubber producers procure accelerator packages through distributor channels. Commoditization of thiazole derivatives is compressing direct contract penetration.
- Paints & Coatings:High-performance pigment dispersion applications in automotive and industrial coatings. EU Green Deal chemical restrictions are accelerating substitution toward non-azo colorants.
Contract concentration is heaviest with agrochemical formulators. Procurement transformation is proceeding most rapidly in pharmaceutical production.
Packaging Type:
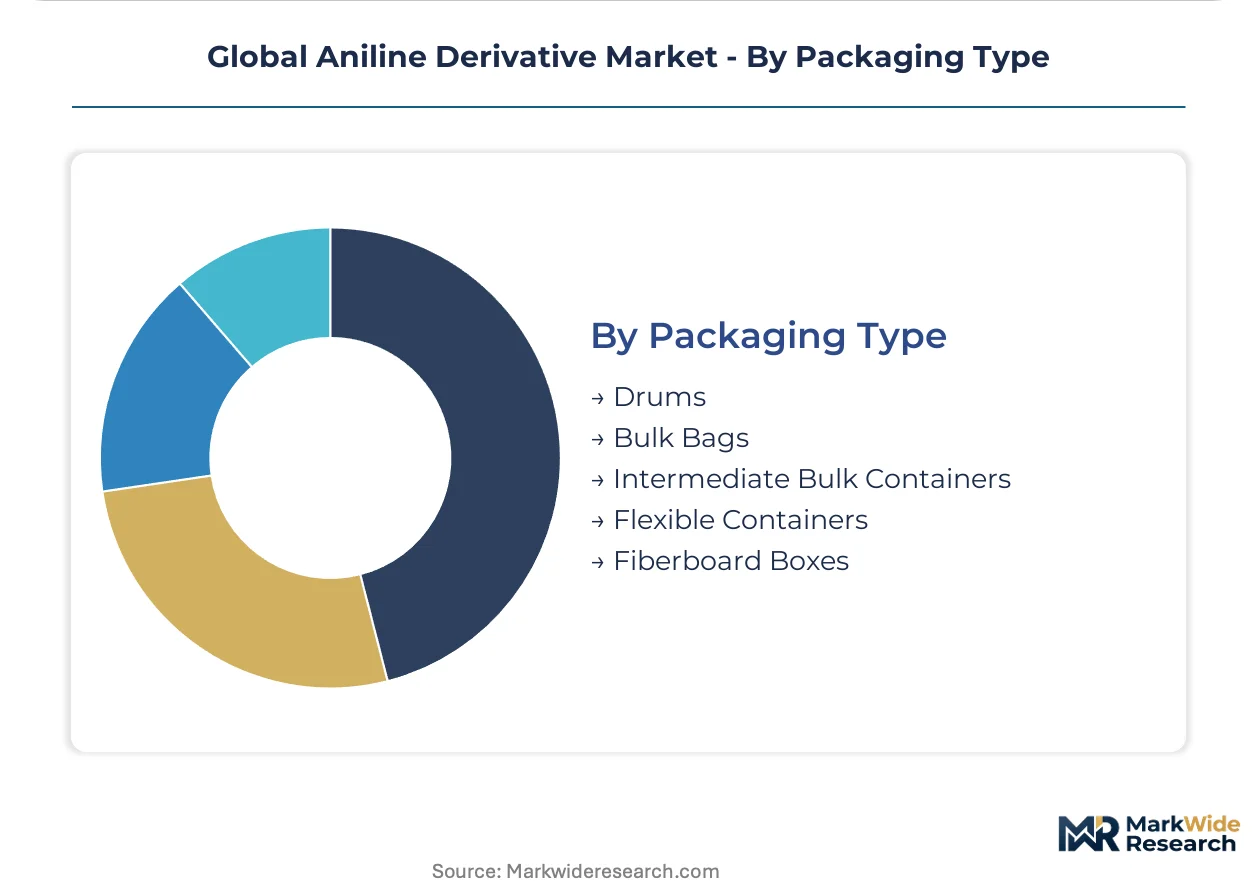
Logistics configuration across this category tracks hazard classification and customer scale, with bulk formats dominating integrated supply chains and small containers serving distributed formulation operations.
- Intermediate Bulk Containers:1000-liter composite totes with UN-certified stacking frames. Pharmaceutical manufacturers in Switzerland and Germany specify single-use liners to prevent cross-contamination.
- Bulk Bags:Flexible intermediate bulk containers with conductive fabric for static control. Agrochemical formulation facilities in Brazil and India drive procurement for powder-grade sulfonates.
- Drums:Steel and polymer drums with epoxy phenolic linings for liquid derivatives. Standard packaging for dye intermediate distributors in Rotterdam and Singapore trading hubs.
- Flexible Containers:Multi-ply laminated bags for moisture-sensitive acetoacetanilide powders. Textile processing clusters in Gujarat specify silica gel desiccant integration.
- Fiberboard Boxes:Corrugated packaging with polyethylene inner barriers for laboratory and sample quantities. Limited scale restricts use to R&D procurement channels.
Shipment volume concentrates through intermediate bulk containers. Format innovation is advancing fastest in bulk bag conductive fabric specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's coal-to-gas feedstock transition contrasts with India's PLI-driven intermediate manufacturing push, creating divergent cost structures across Asian supply bases. Germany anchors European pharmaceutical-grade demand while Brazil's agrochemical formulation sector opens import pathways for sulfonated derivatives.
China
Shandong and Jiangsu provinces concentrate acetoacetanilide capacity serving textile dye houses. MEE enforcement of dual carbon goals pressures coal-based aniline producers toward natural gas feedstock switching. The Yangtze River Delta chemical clusters are retrofitting nitration trains to meet crystallization-grade sulfonate specifications for export markets.
India
Gujarat and Maharashtra industrial corridors attract PLI scheme capital toward acetoacetanilide and dye intermediate expansion. CDSCO filing requirements and US FDA DMF expectations filter supplier viability to audit-ready manufacturers. Surat dye house clusters consume beta-keto amide structures for azo pigment coupling despite water discharge treatment cost pressures.
Germany
REACH registration deadlines and ECHA substance evaluation timelines protect incumbent positions for certified manufacturers. BASF and Bayer Crop Science procurement teams mandate batch-level impurity profiling with certificate-of-analysis standardization. Ludwigshafen and Leverkusen chemical parks anchor sulfonamide antibiotic precursor demand from Swiss and domestic pharmaceutical producers.
Brazil
ANVISA registration harmonization with OECD standards opens import pathways for sulfonated intermediates in crop protection chemistry. São Paulo and Rio Grande do Sul agrochemical formulation facilities drive procurement for powder-grade sulfonates. Multinational crop science firms consolidate approved supplier lists for volume sulfonate tenders.
United States
EPA toxicity thresholds under the Toxic Substances Control Act constrain market access for non-compliant producers. Gulf Coast benzene supply corridors feed derivative production for domestic rubber processing and pharmaceutical applications. Houston and Baton Rouge chemical complexes face margin compression from crude oil-linked benzene price volatility.
Global Aniline Derivative Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across nitration infrastructure and downstream purification capabilities. The supplier base stratifies into integrated manufacturers with captive reduction capacity, merchant traders dependent on toll processing, and regional distributors serving fragmented dye house demand. Three archetypes dominate: benzene-backward integrated operators, pharmaceutical-grade certification holders, and feedstock-proximate Middle Eastern producers. Consolidation pressures favor M&A among non-integrated processors while technology licensing agreements spread continuous flow microreactor capabilities.
Among India-based integrated specialists, Aarti Industries Ltd and Deepak Novochem Technologies Limited exemplify divergent positioning archetypes. Aarti Industries Ltd leverages nitration infrastructure to anchor long-term offtake relationships with consolidated agrochemical buyers. Deepak Novochem Technologies Limited occupies a specification-driven position through specialized acetoacetanilide production. Karoon Petrochemical Company represents feedstock-proximate competition, operating adjacent to benzene supply corridors in the Middle East.
| Leading Market Players |
|---|
| Panoli Intermediates India Private Limited |
| Karoon Petrochemical Company |
| Azelis |
| Deepak Novochem Technologies Limited |
| Honshu Chemical Industry Co., Ltd |
| Aarti Industries Ltd |
| Mitsuboshi Chemical Co.,Ltd |
| Valiant Organics Limited |
| Industrial Solvents & Chemicals Pvt. Ltd |
| Others |
Supply & Pricing Matrix
Captive nitration infrastructure anchors competitive positioning for integrated manufacturers serving pharmaceutical and agrochemical buyers, insulating certified producers from benzene price volatility that erodes merchant processor margins. This backward integration into reduction capacity concentrates pricing power among REACH-registered operators while forcing toll-dependent traders toward specification-driven niches with thinner returns.
Pricing Analysis
Capacity additions in Gujarat and Maharashtra are reshaping price floors for acetoacetanilide grades, compressing spot market premiums as PLI-subsidized supply enters dye intermediate channels. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and commodity-grade tiers separates crystallization-certified sulfonates from standard textile applications. Cost compression in rubber accelerator segments is intensifying because Chinese oversupply of thiazole derivatives has collapsed contract negotiation leverage. Agrochemical formulators exhibit lowest price sensitivity due to batch-traceability mandates, while Surat dye houses face acute margin pressure from water treatment cost pass-throughs.
Supply Chain Analysis
Freight cost differentials between Middle Eastern benzene corridors and Asian manufacturing clusters are widening procurement arbitrage windows for integrated operators with dedicated tanker arrangements. Production gravity centers on China, India, and Germany, with Shandong and Jiangsu provinces anchoring acetoacetanilide output while Ludwigshafen concentrates pharmaceutical-grade sulfonate purification. Feedstock draws from crude-linked benzene supply, natural gas-derived aromatics, and coal-based aniline routes depending on regional carbon policy enforcement. Single-source vulnerability concentrates around oleum supply for sulfonation trains, particularly for European manufacturers dependent on Nordic sulfuric acid imports. Distribution runs through Rotterdam and Singapore trading hubs for spot market participants, with direct procurement contracts displacing distributor intermediation for volume buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical-grade certification requirements are filtering supplier viability toward audit-ready manufacturers with captive quality infrastructure, elevating late-cycle returns for specification-compliant producers over commodity-grade competitors.
For Market Incumbents: Deepen backward integration into benzene supply corridors to defend margin position against feedstock volatility transmitted through crude oil linkage. Prioritize continuous flow microreactor retrofitting to collapse safety inventory requirements and accelerate ECHA audit readiness, as REACH registration deadlines compress viability for non-compliant processors. Lock in multi-year offtake agreements with consolidated agrochemical buyers before PLI-subsidized Indian capacity reaches commercial scale. For New Entrants and Emerging Players: Launch via toll processing partnerships with certified nitration operators to bypass multi-year ECHA dossier development timelines. Target Brazilian agrochemical formulation facilities as the most penetrable geography, where ANVISA registration harmonization with OECD standards has opened import pathways without incumbent supply lock-in. Pursue specification-driven positioning in crystallization-grade sulfonates rather than competing on volume in commoditized azo pigment intermediates. For Investors and Strategic Acquirers: Roll-up economics work for non-integrated merchant traders because REACH compliance costs have fragmented the supplier base below efficient scale thresholds. Focus acquisition screening on European toll processors with existing ECHA registrations but lacking captive reduction capacity, as regulatory squeeze forces consolidation around certified manufacturing assets. Watch for inflection signals in China's MEE enforcement intensity, as dual carbon policy acceleration would strand coal-based aniline assets and revalue natural gas-adjacent production.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive benzene supply insulates margins from crude-linked volatility affecting Gulf Coast processors. |
| Continuous Flow Retrofit | Microreactor deployment collapses safety inventory and satisfies ECHA batch-traceability mandates. |
| Pharmaceutical Certification | CDSCO and FDA DMF readiness filters supplier viability to audit-capable integrated manufacturers. |
| Long-term Supply Agreement | Direct contracts with Bayer Crop Science and Syngenta displace Rotterdam distributor intermediation. |
| Feedstock Switching | Natural gas-derived benzene routes align with China's MEE dual carbon enforcement trajectory. |
Research Methodology
Coverage spans China, India, Germany, Brazil, and the United States, with primary inputs from each market informing demand calibration and regulatory trajectory assessment. Plant managers at nitration facilities, procurement leads at agrochemical formulators, distribution channel partners in Rotterdam and Singapore, and technical R&D directors at dye intermediate manufacturers provided operational data. Secondary validation drew from customs and trade flow databases, ACC and Cefic industry reports, SEC 10-K filings from disclosed chemical producers, and ECHA REACH registration dossiers. Bottom-up capacity modeling triangulated against top-down end-use consumption estimates to anchor volume projections.
Granularity-level modeling distinguished pharmaceutical-grade, technical-grade, and commodity-grade specifications across each product category, with application-level splits for dyes and pigments, pharmaceuticals, rubber accelerators, and agrochemical intermediates. Regional production hub configurations shaped cost structure assumptions throughout the projection horizon. CAGRs were derived from segmented demand elasticity analysis and capacity expansion timelines. Key forecast inputs included benzene feedstock cost trajectories, REACH registration deadline compliance rates, and PLI scheme disbursement pacing for Indian intermediate manufacturers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt MEE enforcement acceleration or ECHA authorization list expansion beyond current PFAS criteria. Forecasts reflect documented assumptions regarding regulatory timeline adherence and feedstock switching economics. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Methacrylic Ester Market
Chemical Intermediates
Metal Alkyls Market
Chemical Intermediates
Nickel Acetate Market
Chemical Intermediates
Global Etoricoxib Intermediate Market
Chemical Intermediates
Pharmaceutical Intermediates Market
Chemical Intermediates
Acetamide MEA Market
Chemical Intermediates
Fungal Staining Reagent Market
Chemical Intermediates
API Intermediate Market
Chemical Intermediates
Ph Controlling Agents Market
Chemical Intermediates
Enzyme Substrates Market
Chemical Intermediates
Elemental Formula Market
Chemical Intermediates
Isosafrole Market
Chemical Intermediates
Iodoacetonitrile Market
Chemical Intermediates
Glycidyl Methacrylate Market
Chemical Intermediates
1, 3, 5-Triazine Market
Chemical Intermediates
Thioesters Market