
 Isosafrole Market | 2026-2036
Isosafrole Market Size, Share, and Industry Trends Forecast 2026-2036
Isosafrole Market Analytics
Project finance tied to dedicated aroma chemical facilities is tilting competitive dynamics toward firms with captive feedstock access. BASF leverages backward integration into phenol derivatives to secure cost-advantaged positions. Berjé anchors European distribution through specialized cold-chain logistics for high-purity grades. Wuhan Yuancheng Technology dominates Chinese export volumes via integrated isosafrole-to-piperonal conversion capabilities.
Isosafrole is a phenylpropenoid compound with the molecular formula C10H10O2, synthesized primarily through base-catalyzed isomerization of safrole or produced via catalytic dehydrogenation routes, serving as a critical precursor for heliotropin (piperonal) and specialty fragrance molecules. Synthetic isosafrole leads volume output due to consistent purity profiles and scalable batch production, while natural isosafrole extraction from sassafras oil occupies premium fragrance segments where botanical provenance commands price premiums. The fragrance industry application pool generates the dominant revenue share, though pharmaceutical-grade derivatives are expanding fastest as GMP-compliant specifications tighten across regulated markets.
EMA guidelines on genotoxic impurity thresholds and REACH Annex XIV authorization requirements shape product specifications and market access conditions for European suppliers. FDA oversight of food-contact flavoring substances and EPA toxic substance control provisions govern US import and formulation standards. Stakeholders must monitor evolving ECHA substance evaluation timelines and FDA FEMA GRAS reassessment protocols to anticipate specification shifts that could disqualify existing supply sources.
Market Dynamics
REACH Annex XIV authorization timelines and tightening ECHA substance evaluation protocols are compressing supplier qualification windows, forcing fragrance houses to consolidate procurement around pre-registered bulk manufacturers with validated purity documentation.
Growth Catalysts
- Heliotropin demand surge:Fragrance formulators in France and Germany are expanding synthetic piperonal output, pulling isosafrole volumes through captive precursor relationships.
- EMA genotoxic impurity thresholds:Tightened pharmaceutical-grade specifications are disqualifying marginal suppliers and concentrating volume among GMP-certified producers.
- Base-catalyzed isomerization advances:Continuous-flow reactor designs are reducing batch-to-batch purity variance, enabling scale-up for fine fragrance applications.
Market Restraints
- Safrole feedstock volatility:Sassafras oil harvest irregularities in Southeast Asia create raw material cost instability for natural extraction routes.
- Zhejiang supply concentration:Wuhan Yuancheng Technology and clustered chemical parks control dominant export capacity, creating single-geography disruption risk.
- Substitution by synthetic heliotropin:Direct catalytic routes to piperonal from catechol derivatives are bypassing isosafrole entirely in cost-sensitive applications.
Strategic Opportunities
- Indian pharmaceutical excipient demand:CDSCO's tightening impurity specifications for drug master files create entry windows for EU-registered suppliers.
- Cold-chain logistics specialization:High-purity grade distribution through temperature-controlled networks commands premium positioning in Swiss and German markets.
- Biocatalytic conversion pathways:Enzyme-mediated isomerization is converging with green chemistry mandates to unlock bio-based fragrance certification.
Industry Challenges
- REACH registration data gaps:ECHA's evolving guidance on phenylpropenoid derivatives requires costly toxicity study updates for existing dossiers.
- Analytical chemist scarcity:Specialized chromatography expertise for sub-ppm impurity quantification is concentrated among aging workforces in Basel and Ludwigshafen clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isosafrole Market |
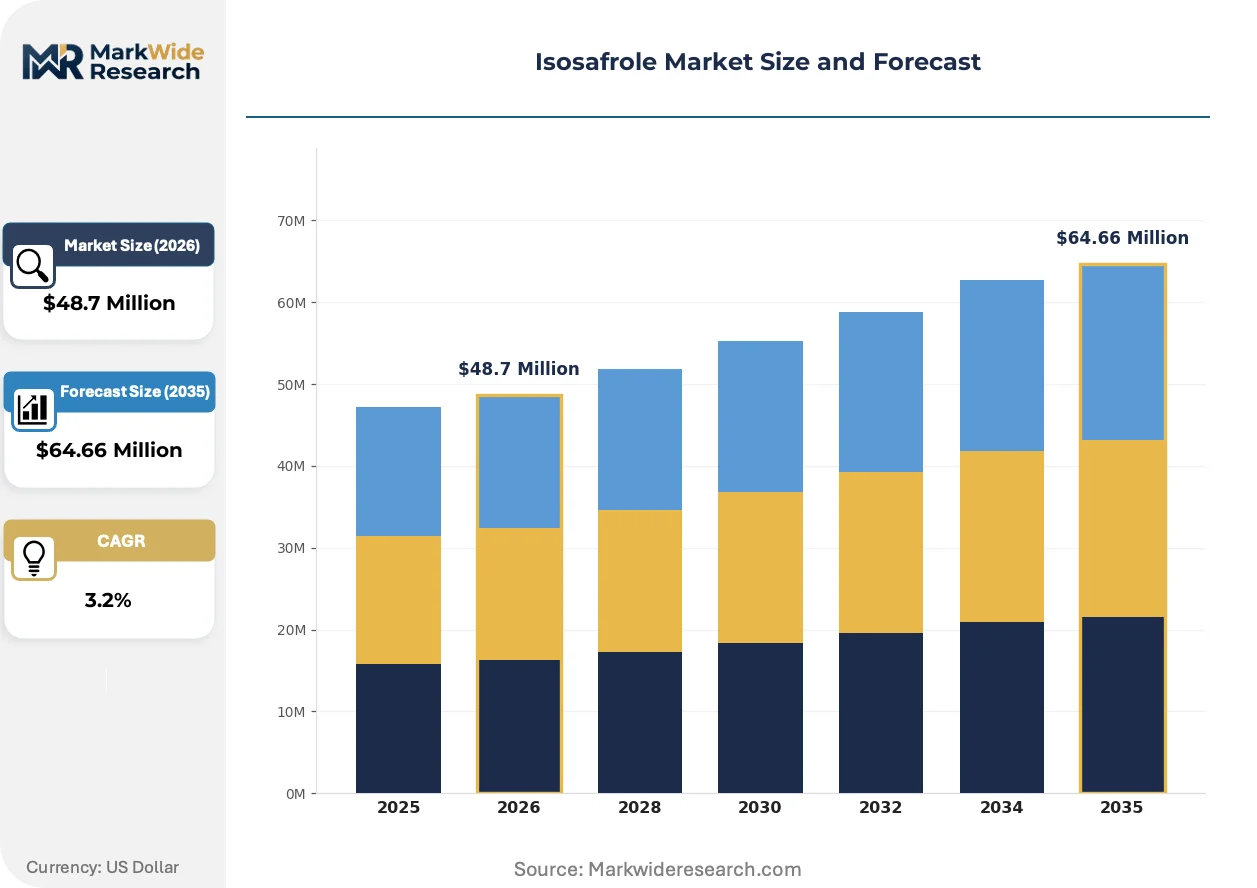
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $64.66 Million |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Isosafrole, Synthetic Isosafrole, Isosafrole Derivatives, Blends Application: Fragrance Industry, Cosmetic Products, Flavoring Agents, Pharmaceuticals End User: Food Manufacturing, Personal Care, Chemical Industry, Healthcare Packaging Type: Bulk Containers, Bottles, Drums, Pails |
| Companies Covered | Taj Pharmaceuticals Ltd., Berjé, BOC Sciences, Penta Manufacturing Company, BASF, Eastman Chemical Company, Wuhan Yuancheng Technology, Spectrum Chemical Manufacturing Corp., Tokyo Chemical Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isosafrole Market Evolving Landscape
Process intensification and regulatory data requirements are compressing the viable supplier base while opening premium tiers for compliant producers. Three developments are restructuring competitive positioning.
Continuous-flow microreactor technology for base-catalyzed isomerization is delivering consistent 99.5%+ purity profiles with reduced thermal degradation. Fine fragrance houses in Grasse and Geneva are adopting these systems for captive production. Batch reactor infrastructure is rendering obsolete for new capacity investments.
REACH authorization timelines for phenylpropenoid derivatives are extending beyond 36 months, freezing market access for unregistered imports. ECHA's 2024 substance evaluation roadmap prioritizes genotoxicity endpoints. EU-based fragrance compounders are qualifying alternative synthetic routes to reduce authorization dependency.
Direct procurement from integrated manufacturers is displacing distributor intermediaries for volume accounts. Fragrance houses in Germany are negotiating multi-year offtake agreements with Zhejiang producers. This consolidation is most visible in heliotropin-forward formulations where supply security outweighs price elasticity.
Isosafrole Market Segmentation
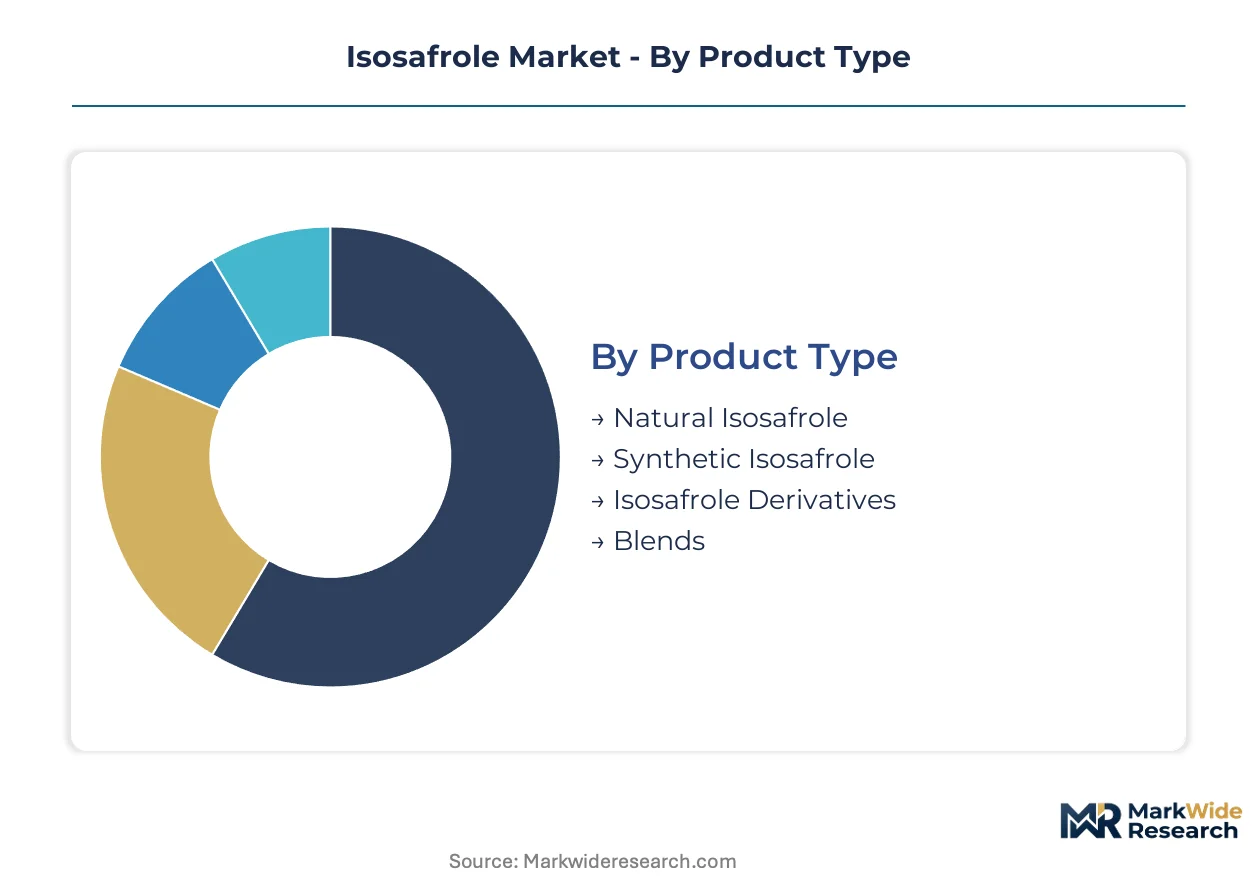
Isosafrole procurement patterns diverge sharply across purity grades and end-use specifications, with fragrance houses demanding certified botanical provenance while pharmaceutical formulators prioritize batch consistency. Understanding these segment boundaries reveals where margin pools concentrate and which qualification barriers protect incumbent positions.
Product Type:
Mature extraction technologies dominate volume output while synthetic routes capture specification-critical applications.
- Synthetic Isosafrole:Manufactured through base-catalyzed isomerization of safrole or catalytic dehydrogenation, delivering 99.5%+ purity with minimal batch variance. Grasse-based fragrance compounders and Ludwigshafen chemical parks specify synthetic grades for heliotropin production where impurity profiles must meet REACH Annex XIV thresholds.
- Natural Isosafrole:Extracted from sassafras oil via fractional distillation, carrying geographic origin certification for premium fragrance segments. French and Swiss perfume houses pay premiums for Madagascar or Brazilian provenance to support marketing narratives around botanical authenticity.
- Isosafrole Derivatives:Functionalized intermediates including methylenedioxy derivatives for specialized pharmaceutical applications.
- Blends:Pre-formulated mixtures with carriers or stabilizers for small-batch cosmetic manufacturing.
Synthetic Isosafrole handles the majority of throughput; Natural Isosafrole is the fastest mover on share as provenance marketing intensifies.
Application:
Cost tier stratification separates commodity flavoring from precision fragrance chemistry.
- Fragrance Industry:Fine perfume and functional fragrance formulations requiring sub-ppm impurity control. Geneva-based compounders specify GMP-adjacent documentation even for non-pharmaceutical grades, pulling volume toward EMA-registered suppliers.
- Pharmaceuticals:Precursor applications for heliotropin derivatives in drug synthesis, subject to ICH Q3D elemental impurity limits and FDA drug master file requirements.
- Flavoring Agents:Food-contact applications governed by FEMA GRAS listings and EPA toxic substance control provisions.
- Cosmetic Products:Skin-care and personal care formulations with moderate purity requirements.
Fragrance Industry commands the dominant revenue position; Pharmaceuticals is expanding most quickly as CDSCO and EMA tighten impurity specifications.
End User:
Customer type determines whether procurement emphasizes supply security or price elasticity.
- Personal Care:Multinational cosmetic houses in Germany and France negotiating multi-year offtake agreements for high-purity grades.
- Chemical Industry:Intermediate processors in Zhejiang province converting isosafrole to piperonal for downstream fragrance synthesis.
- Food Manufacturing:Flavor houses requiring FEMA-compliant documentation for North American market access.
- Healthcare:Pharmaceutical manufacturers subject to GMP audits and regulatory inspection protocols.
Personal Care anchors volume demand; Healthcare is gaining share fastest as specification premiums widen.
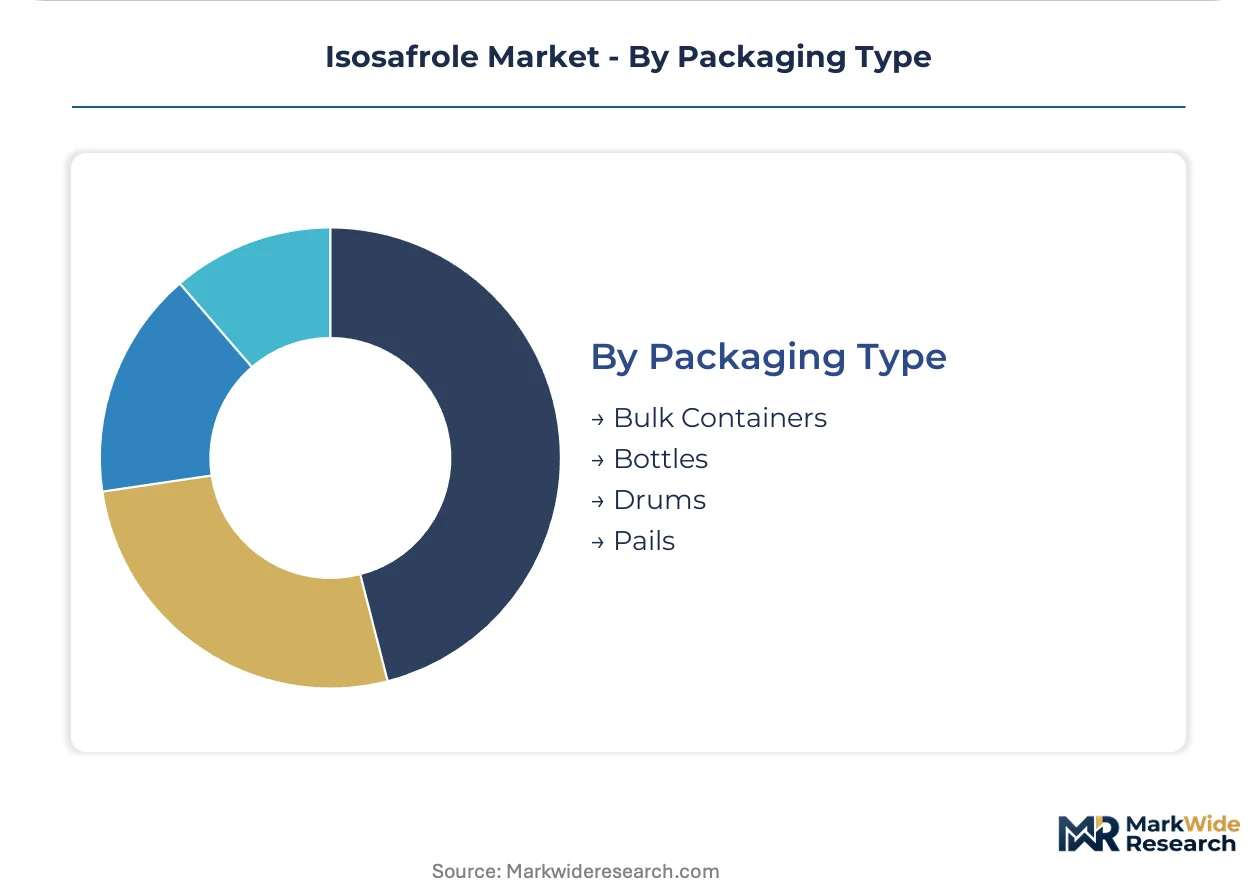
Packaging Type:
Volume scale dictates container economics, with cold-chain requirements fragmenting the premium tier.
- Bulk Containers:ISO tank deliveries for integrated fragrance manufacturers with captive conversion capacity.
- Drums:Standard 200-liter steel drums for mid-scale compounders with quarterly procurement cycles.
- Bottles:Amber glass with nitrogen headspace for high-purity samples and R&D quantities.
- Pails:Polyethylene containers for small-batch cosmetic formulators.
Bulk Containers move the greatest tonnage; Bottles are climbing fastest as sample-to-production qualification cycles accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH registration deadlines and EMA purity mandates are compressing supplier qualification windows across fragrance-consuming economies. Procurement offices in Grasse and Geneva are consolidating volume around pre-registered bulk manufacturers with validated documentation.
China
Zhejiang province hosts integrated manufacturing clusters converting isosafrole to piperonal at industrial scale. NMPA's tightening impurity specifications for pharmaceutical-grade imports are disqualifying marginal exporters. Wuhan Yuancheng Technology anchors export capacity through captive feedstock integration in the Yangtze River Delta chemical corridor.
Germany
Ludwigshafen and Leverkusen chemical parks specify synthetic grades for heliotropin production where REACH Annex XIV thresholds apply. ECHA's 2024 substance evaluation roadmap prioritizes genotoxicity endpoints for phenylpropenoid derivatives. BASF leverages backward integration into phenol derivatives to secure cost-advantaged positions in fine fragrance precursor supply.
France
Grasse-based fragrance compounders demand certified botanical provenance for premium perfume segments. ANSM guidelines on fragrance ingredient safety are tightening documentation requirements for natural extraction routes. Parisian procurement offices negotiate multi-year offtake agreements with Zhejiang producers to secure supply continuity.
Switzerland
Geneva-based specialty chemical distributors command premium positioning through cold-chain logistics for high-purity grades. Swissmedic's pharmaceutical excipient standards create entry barriers for unregistered suppliers. Basel clusters concentrate analytical chemistry expertise for sub-ppm impurity quantification in regulatory submissions.
India
Maharashtra and Gujarat pharmaceutical manufacturers are expanding heliotropin derivative output for domestic drug synthesis. CDSCO's tightening impurity specifications for drug master files create qualification windows for EU-registered suppliers. Mumbai procurement offices are consolidating volume around GMP-certified producers with validated purity documentation.
Isosafrole Market Competitive Landscape
On the supply side, the industry is consolidating around integrated manufacturers with captive feedstock access and validated regulatory dossiers. Three archetypes dominate: multinational chemical conglomerates with backward integration into phenol derivatives, specialized aroma chemical distributors with cold-chain logistics capabilities, and Chinese integrated producers with isosafrole-to-piperonal conversion capacity. Competitive moves center on multi-year offtake agreements and REACH registration data package acquisitions.
Within the integrated manufacturing tier, Wuhan Yuancheng Technology exemplifies the Chinese archetype of captive precursor conversion. Among European distributors, Berjé occupies a position representing specialized logistics for high-purity grades. BASF anchors the multinational chemical conglomerate archetype with upstream control over phenol derivative feedstocks.
| Leading Market Players |
|---|
| Taj Pharmaceuticals Ltd. |
| Berjé |
| BOC Sciences |
| Penta Manufacturing Company |
| BASF |
| Eastman Chemical Company |
| Wuhan Yuancheng Technology |
| Spectrum Chemical Manufacturing Corp. |
| Tokyo Chemical Industry Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Zhejiang supply concentration creates dual vulnerability that widens pricing spreads between REACH-registered and unregistered grades while forcing fragrance houses toward multi-year offtake structures. This geographic lock-in simultaneously inflates premium tiers for validated documentation and compresses margins on spot-market volumes.
Pricing Analysis
Certification level creates the primary spread, with EMA-registered and REACH-compliant grades commanding substantial premiums over standard technical grades. Pricing stratifies across pharmaceutical-grade, fine fragrance-grade, and industrial-grade tiers, with impurity thresholds and documentation depth as the key differentiators. Cost compression in industrial-grade segments is intensifying because direct catalytic routes to piperonal bypass isosafrole entirely. Personal care multinationals show lowest price sensitivity due to supply security priorities, while small-batch cosmetic formulators face acute margin pressure.
Supply Chain Analysis
Wuhan Yuancheng Technology and clustered Zhejiang chemical parks hold dominant contract-manufacturing capacity for isosafrole-to-piperonal conversion. Supply draws from China, Germany, and India as primary production nodes, with feedstock dependencies on safrole derivatives, phenol-based precursors, and sassafras oil extraction. Single-source vulnerability concentrates in the Yangtze River Delta corridor where NMPA inspections and environmental compliance disruptions can freeze export flows. Distribution runs through specialized cold-chain networks for high-purity pharmaceutical grades and standard bulk logistics for industrial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern tied to fragrance industry inventory restocking following REACH registration deadline compressions. Procurement normalization is creating window for positioning moves.
For Market Incumbents: Build regulatory data moats through REACH Annex XIV dossier acquisitions and ECHA toxicity study updates before evaluation timelines extend. Consolidate procurement relationships with Zhejiang producers through captive offtake agreements to lock feedstock access. BASF and Berjé archetypes should deepen backward integration into phenol derivatives while expanding cold-chain distribution footprints in Swiss and German markets. For New Entrants and Emerging Players: Establish a beachhead in Indian pharmaceutical excipient demand where CDSCO tightening creates qualification windows for EU-registered suppliers. Target Maharashtra and Gujarat drug manufacturers with GMP-compliant documentation and validated impurity profiles. Leverage biocatalytic conversion pathways as green chemistry differentiation to unlock bio-based fragrance certification premiums. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated manufacturers with captive feedstock and validated regulatory dossiers. Long-term viability centers on REACH registration asset values and multi-year offtake contract backlogs. Watch ECHA substance evaluation timelines as inflection indicator for authorization-dependent volume shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenol Derivatives | BASF secures cost-advantaged feedstock positions for synthetic isosafrole production. |
| REACH Registration Data Package Acquisition | EU fragrance compounders reduce authorization dependency through dossier consolidation. |
| Long-term Supply Agreement with Zhejiang Producers | Grasse-based houses secure supply continuity for heliotropin-forward formulations. |
| Cold-Chain Logistics Network Expansion | Swiss distributors command premium positioning for high-purity pharmaceutical grades. |
| Biocatalytic Conversion Pathway Development | Specialty producers align with green chemistry mandates for bio-based fragrance certification. |
Research Methodology
The analysis maps synthetic routes, natural extraction methods, and derivative functionalization pathways, each validated through fragrance compounder procurement leads, pharmaceutical regulatory affairs directors, chemical plant managers, and specialty distributor sales heads. Primary fieldwork combined with secondary validation from customs trade data, ECHA registration databases, SEC chemical sector filings, and fragrance industry association reports. Bottom-up volume builds triangulated against top-down market sizing across purity grades and end-use applications.
Assumptions held fixed include REACH authorization timeline progression and EMA genotoxic impurity threshold enforcement, while feedstock cost volatility and substitution technology adoption were modeled as scenario variables. Segmentation dimensions span product type, application, end user, and packaging format alongside regional production hub clustering. CAGRs derived from historical trajectory analysis adjusted for regulatory compression effects and inventory cycle positioning. Industry-specific inputs include heliotropin demand elasticity and sassafras oil harvest variability across Southeast Asia.
Sensitivities concentrate around ECHA substance evaluation delays, NMPA inspection intensity in Zhejiang, and catalytic dehydrogenation technology cost curves. Forecasts reflect these documented assumptions with acknowledged revision potential from regulatory guidance shifts or feedstock supply disruptions. Quarterly review of REACH registration status updates, CDSCO drug master file approvals, and fragrance house inventory positions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Tertiary Butylhydroquinone Acids Market
Chemical Intermediates
Global Electrophoresis Reagents Market
Chemical Intermediates
Preformulation Intermediates Market
Chemical Intermediates
Diketene Derivatives Market
Chemical Intermediates
Diethyl Phthalate Market
Chemical Intermediates
Leather Chemicals Market
Chemical Intermediates
Hydroxyisobutyric Acid Market
Chemical Intermediates
Japan Formic Acid Market
Chemical Intermediates
Pharmaceutical Intermediates Market
Chemical Intermediates
Nutrition Chemicals Market
Chemical Intermediates
Molybdenum Disulfide (MoS2) Market
Chemical Intermediates
Natural Chelating Agents Market
Chemical Intermediates
9-Decanoic Acid Methyl Ester Market
Chemical Intermediates
Metaphenoxy Benzaldehyde (MPBD) Market
Chemical Intermediates
Ethylene Urea Market
Chemical Intermediates
Phosphate Chemical Reagents Market