
 Refinery Process Chemicals Market | 2026-2036
Refinery Process Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Refinery Process Chemicals Market Outlook
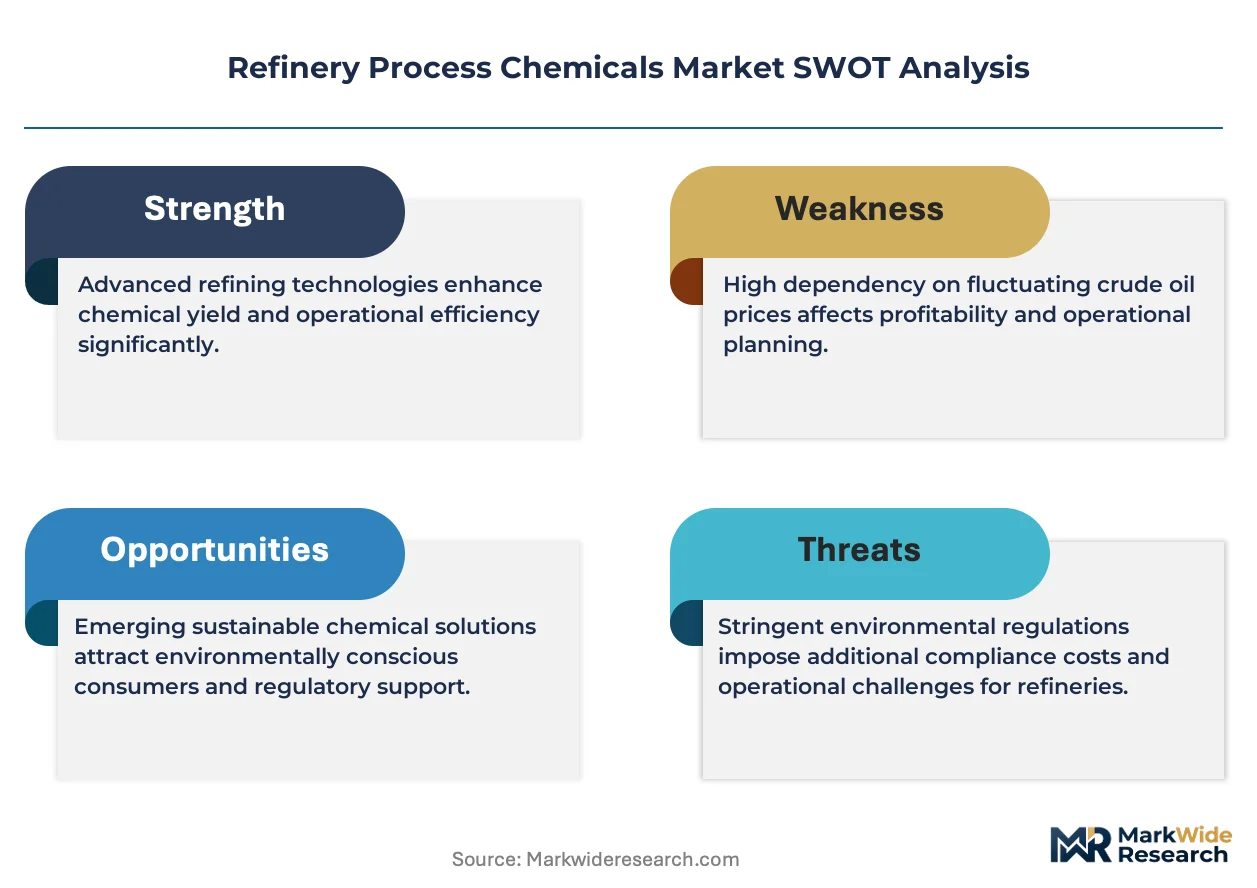
The EU Green Deal's carbon border adjustment mechanism is expanding compliance requirements for European refiners importing high-sulfur crude feeds. BASF SE leverages its integrated catalyst manufacturing network to supply hydroprocessing units across Rotterdam and Antwerp hubs. Baker Hughes anchors its position through specialized digital chemical monitoring systems tied to refinery automation platforms. Clariant AG competes via its customized zeolite catalyst portfolio optimized for FCC unit yield improvements.
Refinery process chemicals comprise specialty formulations including alkylation acids, hydroprocessing catalysts, corrosion inhibitors, and antifoulants designed to optimize hydrocarbon conversion efficiency, protect metallurgy, and meet product quality specifications at operating temperatures exceeding 400°C. Catalysts dominate value capture due to replacement cycles tied to unit run-length economics and regenerability constraints. Hydrotreating applications are outpacing alkylation in growth velocity as refiners reconfigure for ultra-low-sulfur diesel and marine fuel compliance.
The EPA's Tier 3 gasoline sulfur standards and the EU F-Gas Regulation constrain formulation choices for North American and European operators, pushing demand toward low-emission chemical delivery systems. India's BIS certification requirements for refinery chemicals and China's GB standards on wastewater discharge from petrochemical complexes add compliance layers for suppliers entering Asian markets. Stakeholders must weigh regulatory divergence against scale economies when configuring regional product portfolios and technical service capabilities.
Market Dynamics
The International Maritime Organization's sulfur cap mandates are forcing integrated oil companies to reconfigure hydrotreating capacity, triggering replacement cycles for hydroprocessing catalysts and corrosion inhibitors across marine fuel supply chains.
Growth Catalysts
- IMO 2020 Sulfur Regulations:Marine fuel sulfur limits are accelerating hydrotreating unit upgrades at coastal refineries processing high-sulfur residual streams.
- Middle East Refinery Expansions:Saudi Arabia and the UAE are concentrating procurement for desalination chemicals and corrosion inhibitors at new mega-complexes.
- FCC Yield Optimization:Zeolite catalyst formulations for fluid catalytic cracking units are capturing value from heavier crude processing economics.
Market Restraints
- Specialty Chemical Feedstock Volatility:Molybdenum and cobalt prices for hydroprocessing catalyst precursors swing with mining supply disruptions from the Democratic Republic of Congo.
- Regulatory Friction from Divergent Standards:India's BIS certification requirements and China's GB wastewater discharge standards create compliance fragmentation for multinational suppliers.
- Technical Limitation in Catalyst Regenerability:Fixed-bed hydrotreating catalysts face permanent deactivation from metals deposition, constraining unit run-length economics.
Strategic Opportunities
- EU Carbon Border Adjustment Mechanism:European refiners importing high-sulfur crudes need low-emission chemical delivery systems to offset embedded carbon penalties.
- Digital Chemical Monitoring Convergence:Integration of IoT sensors with refinery automation platforms enables predictive catalyst replacement and antifoulant dosing.
- India's BIS-Certified Import Substitution:Domestic formulation capabilities for alkylation acids and corrosion inhibitors remain underdeveloped versus import volumes.
Industry Challenges
- Catalyst Synthesis Skill Scarcity:Zeolite manufacturing expertise concentrates at legacy research centers, constraining capacity expansion for FCC and hydrocracking formulations.
- Legacy DCS Integration Complexity:Digital chemical monitoring systems require retrofitting into distributed control systems designed decades before data analytics platforms.
- EPA Tier 3 Compliance Timelines:Gasoline sulfur standards compress certification windows for new additive formulations entering North American supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refinery Process Chemicals Market |
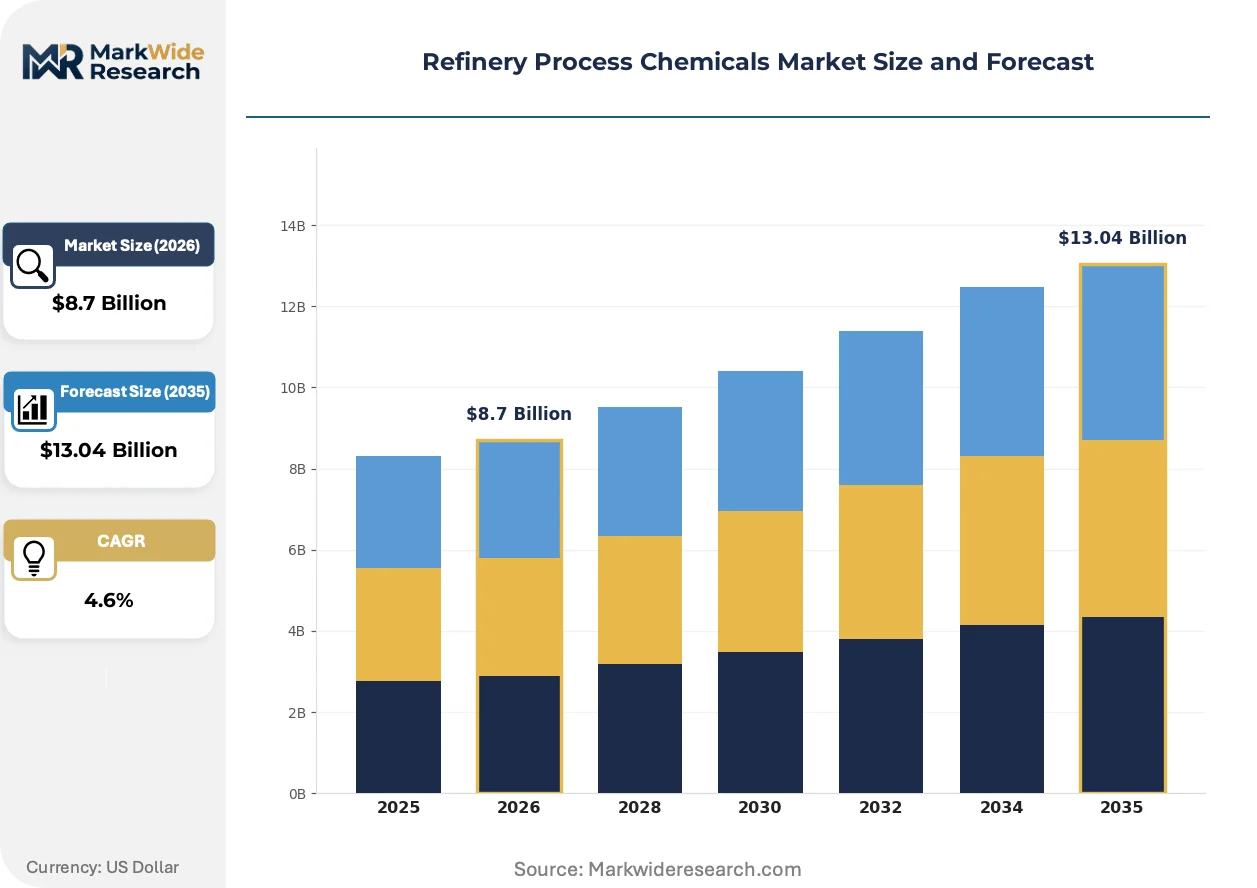
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkylation Chemicals, Catalysts, Solvents, Additives Application: Crude Oil Refining, Petrochemical Production, Gas Treatment, Lubricant Oils End User: Oil & Gas Companies, Petrochemical Firms, Chemical Manufacturers, Environmental Regulators Technology: Hydrogenation, Distillation, Hydrotreating, Alkylation |
| Companies Covered | BASF SE, Baker Hughes, Clariant AG, ExxonMobil Corporation, Dow Inc., Honeywell UOP, Nalco Champion, Lubrizol Corporation, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refinery Process Chemicals Market Strategic Shifts
Refinery process chemicals are pivoting toward predictive application models and regulatory-aligned formulations, with digital integration and sulfur compliance reshaping technical service architectures.
Membrane-based catalyst recovery systems are decentralizing spent hydroprocessing catalyst regeneration away from centralized reclamation facilities. Mid-size refiners in the US Gulf Coast and Rotterdam-Antwerp corridor are adopting skid-mounted units for on-site metals recovery and reactivation. This distributed model is decentralizing the historical supplier-captive regeneration business and compressing logistics costs for catalyst-intensive operations.
The EU F-Gas Regulation is constraining fluorinated compound formulations used in alkylation acid catalyst regeneration and cooling systems. European refiners face phasedown quotas forcing substitution toward ionic liquid or solid acid alternatives for isobutane-olefin alkylation. Hydrotreating units processing bio-feedstocks are most affected, requiring reformulation of antifoulants and corrosion inhibitors compatible with oxygenated streams.
Refinery operators are consolidating chemical procurement under performance-based supply agreements rather than transactional purchase orders. Integrated oil companies in the Middle East and US Midwest are bundling catalyst supply with technical service contracts tied to unit availability guarantees. This restructuring is visible most acutely at Saudi Aramco's Jazan and Satorp complexes, where suppliers assume inventory risk and on-site technical staffing obligations.
Refinery Process Chemicals Market Segmentation
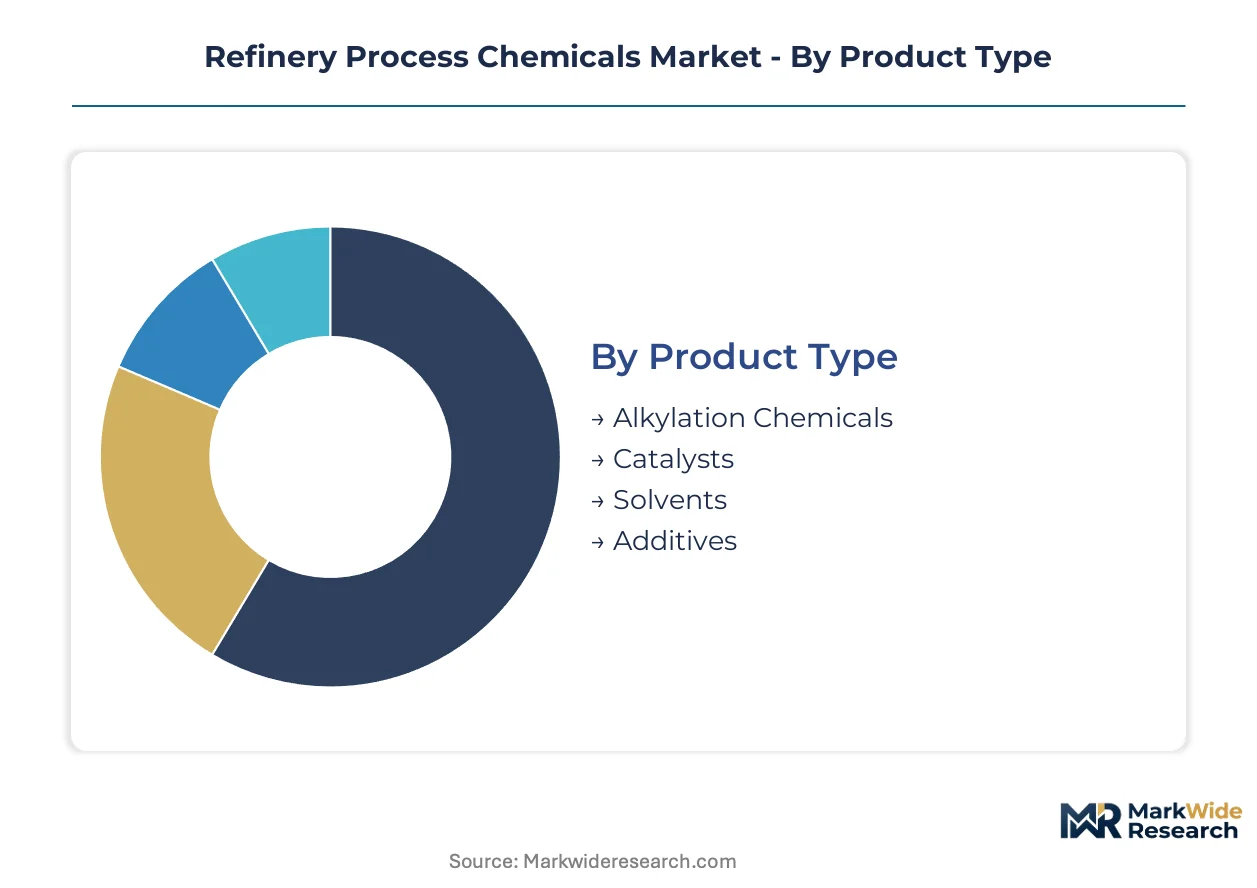
Refinery process chemicals segment along four distinct axes that determine procurement patterns, technical service intensity, and margin capture. Product type governs replacement economics and catalyst regenerability. Application and technology alignment dictate formulation specifications and regulatory compliance burdens.
Product Type:
Buyers differentiate by unit economics—catalysts dominate capital deployment while alkylation chemicals and solvents drive recurring operating expenditure.
- Catalysts:Zeolite and metal-sulfide formulations for FCC and hydroprocessing units require precise pore structure engineering to match crude slate characteristics. Demand concentrates at integrated complexes in Saudi Arabia and the UAE where mega-refinery expansions trigger bulk procurement cycles tied to unit commissioning schedules.
- Alkylation Chemicals:Sulfuric and hydrofluoric acid catalysts enable isobutane-olefin alkylation for high-octane gasoline blending. European refiners face substitution pressure under the EU F-Gas Regulation, pivoting procurement toward ionic liquid alternatives at Rotterdam and Antwerp hubs.
- Solvents:Extraction and washing agents for lube oil dewaxing and aromatics recovery operate at high circulation rates with continuous makeup requirements.
- Additives:Antifoulants, corrosion inhibitors, and metal passivators protect fixed-bed reactors and fractionation columns from fouling and metallurgical degradation.
Catalysts lead volumes today; alkylation chemicals are gaining share fastest as marine fuel sulfur regulations force gasoline yield reconfiguration.
Application:
Volume concentration tracks crude throughput scale and complexity tier, with coastal marine fuel hubs commanding premium formulation specifications.
- Crude Oil Refining:Hydrotreating and FCC unit operations consume the majority of process chemicals by value, with hydrotreating catalyst replacement cycles accelerating at US Gulf Coast refineries responding to EPA Tier 3 gasoline standards.
- Petrochemical Production:Steam cracker feed pretreatment and pygas hydrotreating require specialized catalysts tolerant of diene and styrene contamination.
- Gas Treatment:Amine-based acid gas removal and molecular sieve dehydration systems rely on continuous chemical replenishment at high-pressure sour gas facilities.
- Lubricant Oils:Hydrocracking and catalytic dewaxing units for Group II/III base oil production use noble-metal catalysts with stringent sulfur and nitrogen guard bed requirements.
Crude oil refining anchors current demand; petrochemical production is climbing the fastest as integrated complexes expand aromatics and olefins output.
End User:
Procurement sophistication varies by vertical integration depth and technical staffing density, separating integrated majors from merchant chemical buyers.
- Oil & Gas Companies:Integrated majors like Saudi Aramco and ExxonMobil negotiate performance-based supply agreements bundling catalyst delivery with unit availability guarantees and on-site technical staffing.
- Petrochemical Firms:Merchant olefins and aromatics producers prioritize catalyst selectivity for ethylene and benzene yield optimization over feed flexibility.
- Chemical Manufacturers:Specialty chemical producers purchasing refinery-derived intermediates impose strict contaminant specifications that cascade back to upstream hydrotreating chemical requirements.
- Environmental Regulators:Compliance monitoring agencies drive demand for analytical standards and reference materials used in emissions testing and wastewater discharge verification.
Oil and gas companies dominate procurement volumes today; petrochemical firms are expanding their chemical intensity fastest through cracker feed pretreatment investments.
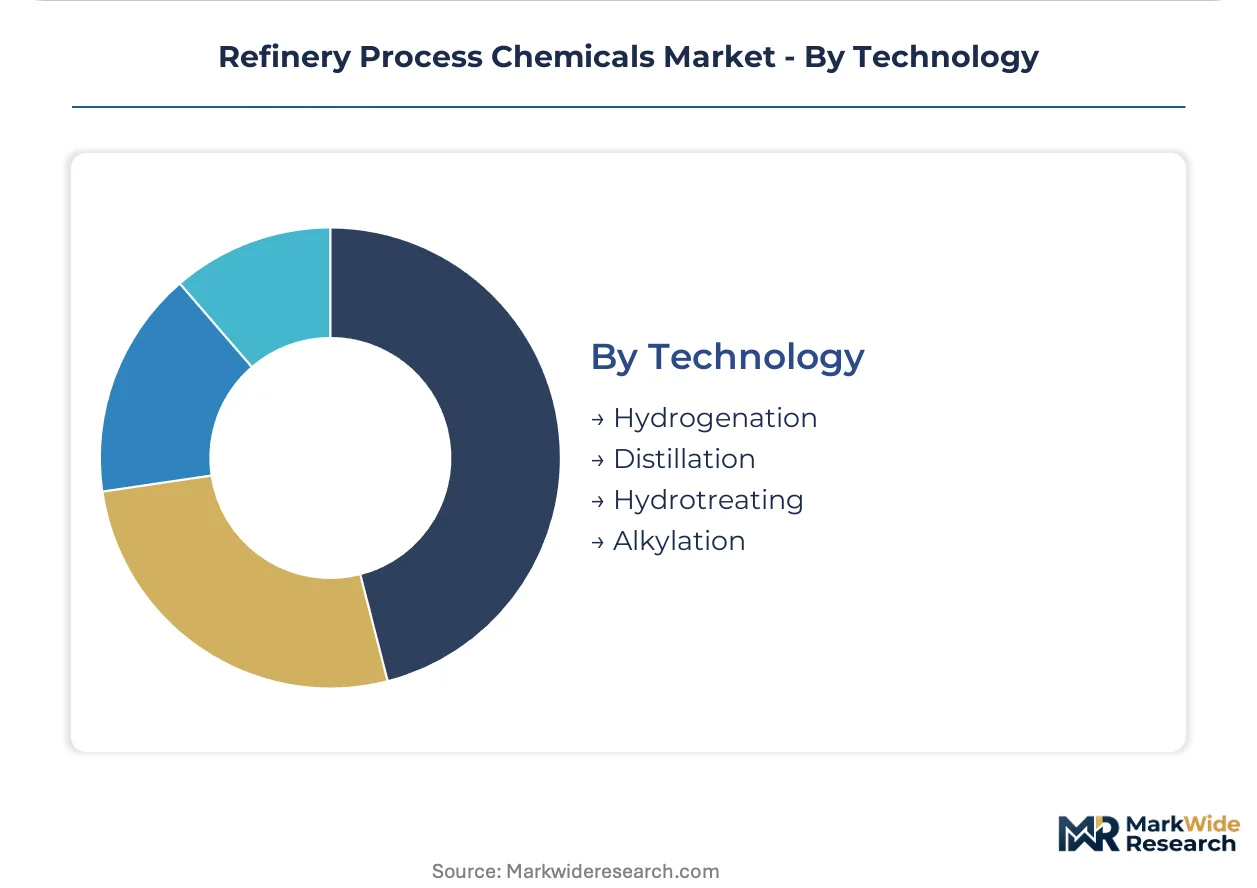
Technology:
Process chemistry selection determines catalyst deactivation mechanisms and regeneration potential, separating fixed-bed from ebullated-bed economic models.
- Hydrotreating:Fixed-bed and ebullated-bed configurations for sulfur, nitrogen, and aromatics saturation face permanent metals deposition constraints that limit run-length economics and drive replacement demand.
- Hydrogenation:Selective and non-selective hydrogenation for pygas and pyrolysis gasoline upgrading requires sulfur-tolerant noble-metal catalysts with precise activity control.
- Alkylation:Liquid-acid and solid-acid processes for isobutane-olefin reaction face regulatory phase-down of fluorinated compounds under EU F-Gas constraints.
- Distillation:Extractive and azeotropic distillation for aromatics recovery relies on solvent circulation chemistry and corrosion inhibitor packages.
Hydrotreating commands the largest installed base today; hydrogenation is expanding most quickly as steam cracker feed pretreatment requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Catalyst synthesis expertise concentrates in Germany's Ruhr industrial corridor and the US Gulf Coast petrochemical belt. These workforce clusters anchor procurement decisions for hydrotreating formulations and FCC zeolites. Regional regulatory divergence is reshaping supplier technical service requirements.
United States
EPA Tier 3 gasoline sulfur standards are compressing certification windows for new additive formulations entering North American supply chains. The US Gulf Coast refining corridor from Houston to Baton Rouge is accelerating hydrotreating catalyst replacement cycles at coastal facilities processing high-sulfur residual streams for marine fuel compliance.
Germany
The EU F-Gas Regulation constrains fluorinated compound formulations used in alkylation acid catalyst regeneration and cooling systems. BASF SE leverages its integrated catalyst manufacturing network to supply hydroprocessing units across Rotterdam and Antwerp hubs. The Ruhr industrial corridor retains concentrated zeolite manufacturing expertise for FCC and hydrocracking formulations.
Saudi Arabia
Saudi Aramco's Jazan and Satorp complexes are consolidating chemical procurement under performance-based supply agreements bundling catalyst delivery with unit availability guarantees. The country's national petroleum regulator imposes strict product quality specifications that cascade to upstream chemical requirements. The Eastern Province industrial zone around Jubail is concentrating procurement for desalination chemicals and corrosion inhibitors at new mega-complexes.
China
GB standards on wastewater discharge from petrochemical complexes add compliance layers for suppliers entering Asian markets. The Yangtze River Delta refining cluster is expanding hydrotreating capacity to process heavier domestic crude slates. State-owned integrated oil companies are negotiating technical service contracts with on-site staffing obligations.
India
BIS certification requirements for refinery chemicals create import substitution opportunities for domestic formulation capabilities. Reliance Industries' Jamnagar complex is driving demand for hydroprocessing catalysts and corrosion inhibitors. The Gujarat petrochemical corridor remains dependent on imported alkylation acids and specialty catalysts.
Refinery Process Chemicals Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the catalyst and specialty chemical value chain. The market structure consolidates around integrated chemical conglomerates with captive raw material positions and specialized catalyst engineering houses with proprietary zeolite synthesis IP. Three archetypes dominate: diversified chemical majors with refinery-adjacent portfolios, pure-play catalyst technology licensors, and oilfield service providers extending into process chemicals. Competitive moves concentrate on backward integration into molybdenum and cobalt precursor supply, plus digital chemical monitoring system deployment.
Among diversified chemical conglomerates, BASF SE and Dow Inc. occupy positions anchored by integrated manufacturing networks spanning precursor chemicals through finished catalyst formulations. Baker Hughes exemplifies the oilfield services archetype extending into refinery process chemicals through specialized digital monitoring systems. Clariant AG represents the pure-play catalyst technology vector with customized zeolite portfolios. These three companies illustrate the strategic tension between scale-driven raw material security and technology-driven yield optimization.
| Leading Market Players |
|---|
| BASF SE |
| Baker Hughes |
| Clariant AG |
| ExxonMobil Corporation |
| Dow Inc. |
| Honeywell UOP |
| Nalco Champion |
| Lubrizol Corporation |
| Evonik Industries |
| Others |
Value Chain & Pricing Dynamics
Performance-based supply agreements bundling catalyst delivery with unit availability guarantees are compressing margins for unbundled transactional suppliers. Refiners in Saudi Arabia and the US Gulf Coast now demand on-site technical staffing and inventory risk transfer, forcing chemical suppliers to absorb working capital costs that previously sat with buyers.
Pricing Analysis
The bundled-versus-unbundled service split defines pricing architecture across the market. Three-tier pricing structure across premium, standard, and economy levels tracks catalyst regenerability, technical service intensity, and crude slate complexity. Cost compression in standard-tier hydroprocessing formulations is intensifying because Middle Eastern mega-refinery procurement concentrates volume leverage with integrated majors. Merchant refiners without captive technical staffing exhibit highest price sensitivity; integrated oil companies with performance-guarantee contracts show lowest elasticity.
Supply Chain Analysis
Freight costs for spent catalyst reclamation and fresh catalyst delivery dominate landed cost structures for inland refiners distant from Rotterdam-Antwerp and US Gulf Coast hubs. Supply concentrates in Germany's Ruhr corridor, the US Gulf Coast petrochemical belt, and China's Yangtze River Delta for zeolite synthesis and metal-sulfide precursor production. Molybdenum and cobalt feedstocks draw from mining operations in the Democratic Republic of Congo and Chile, creating single-source vulnerability for hydroprocessing catalyst manufacturers. Distribution runs through regional blending terminals with just-in-time delivery to refinery tank farms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where the International Maritime Organization's sulfur cap mandates trigger cascading replacement cycles for hydrotreating catalysts and corrosion inhibitors.
For Market Incumbents: Deepen backward integration into molybdenum and cobalt precursor supply to offset commodity volatility from DRC mining disruptions. Lock in long-term offtake agreements with Rotterdam-Antwerp hub refiners facing EU F-Gas Regulation compliance deadlines. Deploy digital chemical monitoring systems to capture performance-based contract renewals from integrated majors consolidating procurement. For New Entrants and Emerging Players: Launch via BIS-certified domestic formulation capabilities targeting India's import-dependent alkylation acid and specialty catalyst markets. Focus initial penetration on mid-size US Gulf Coast refiners adopting skid-mounted catalyst regeneration units outside supplier-captive networks. Pursue technical service partnerships with state-owned Chinese refiners expanding hydrotreating capacity for heavier domestic crude processing. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play catalyst technology licensors possessing proprietary zeolite synthesis IP and established FCC yield optimization track records. Five-to-ten-year viability hinges on regulatory divergence between EU carbon border mechanisms and Asian certification requirements. Monitor membrane-based catalyst recovery system adoption rates as inflection indicator for distributed regeneration model displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Molybdenum and cobalt security insulates BASF and Dow from DRC supply disruptions. |
| Digital Chemical Monitoring Deployment | Baker Hughes leverages IoT convergence to anchor performance-based contracts at Saudi Aramco complexes. |
| Membrane-Based Catalyst Recovery Scale-Up | Skid-mounted regeneration units decentralize spent catalyst logistics for US Gulf Coast independents. |
| Ionic Liquid Alkylation Formulation | EU F-Gas phasedown quotas force substitution away from fluorinated compounds at Rotterdam hubs. |
| BIS Certification Investment | Domestic Indian capabilities capture import substitution demand at Reliance Industries' Jamnagar complex. |
Study Parameters
Bottom-up refinery unit modeling reconciled against top-down catalyst production tracking forms the analytical core of this study. Primary interviews with plant managers, downstream procurement leads, technical R&D directors, and distribution channel partners combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC filings, and EPA regulatory databases. Triangulation between demand-side unit economics and supply-side manufacturing capacity ensures cross-verified volume and value estimates.
Historical trendline analysis of hydrotreating catalyst replacement cycles, FCC unit run-length economics, and alkylation acid consumption patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include catalyst type, crude slate complexity tier, refinery configuration, and regional regulatory cluster. CAGRs derive from unit-by-unit capacity buildout schedules, regulatory compliance timelines, and feedstock quality degradation trajectories. Industry-specific inputs incorporate marine fuel sulfur specification changes and bio-feedstock penetration rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under molybdenum price volatility and EU carbon border adjustment enforcement intensity. Forecasts reflect assumptions about refinery utilization rates, catalyst regenerability limits, and regulatory implementation timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Preformulation Intermediates Market
Chemical Intermediates
Carboxylic Acid Chlorides Market
Chemical Intermediates
Acid Chlorides Market
Chemical Intermediates
Polyamide Intermediate Chemicals Market
Chemical Intermediates
Natural Chelating Agents Market
Chemical Intermediates
Isosafrole Market
Chemical Intermediates
Tertiary Amines Market
Chemical Intermediates
Ethylene Diamine Tetra Acetic Acid (EDTA) Market
Chemical Intermediates
Global Textile Finishing Chemicals Market
Chemical Intermediates
Iodoacetonitrile Market
Chemical Intermediates
Potential Hydrogen (Ph) Adjusters Market
Chemical Intermediates
Lauoryl Chloride Market
Chemical Intermediates
Myristoyl Chloride Market
Chemical Intermediates
Dental Etching Agents Market
Chemical Intermediates
Global Glycinates Market
Chemical Intermediates
Glycidyl Methacrylate Market