
 Glycidyl Methacrylate Market | 2026-2036
Glycidyl Methacrylate Market Size, Share, and Industry Trends Forecast 2026-2036
Glycidyl Methacrylate Market Analysis
Technical service agreements for customized viscosity grades and on-site formulation support is realigning procurement relationships in specialty monomers. Mitsubishi Gas Chemical Company leverages backward integration into epichlorohydrin feedstock to secure supply continuity. Evonik Industries AG anchors its position through R&D intensity in reactive diluents for dental applications. Dow Chemical dominates North American volume through manufacturing scale and channel control.
Glycidyl methacrylate is an acrylate monomer bearing both a methacrylate ester and an epoxide functional group, typically produced via esterification of methacrylic acid with epichlorohydrin under alkaline catalysis, yielding a bifunctional building block for crosslinkable polymer systems. The copolymer segment leads value generation due to formulation flexibility in UV-curable coatings, while glycidyl methacrylate homopolymer sustains premium pricing in photoresist and microelectronic applications where purity thresholds exceed standard industrial grades. Adhesives and coatings together occupy the largest application footprint, with sealants gaining traction in electric vehicle battery module assembly.
EPA oversight of epichlorohydrin emissions shapes domestic manufacturing economics, while REACH registration requirements in Europe constrain import pathways for non-compliant Asian suppliers. FDA biocompatibility standards for medical device polymers further differentiate qualified suppliers from commodity traders. Stakeholders must monitor evolving dual-use export controls and carbon border adjustment mechanisms that could reroute trade flows.
Market Dynamics
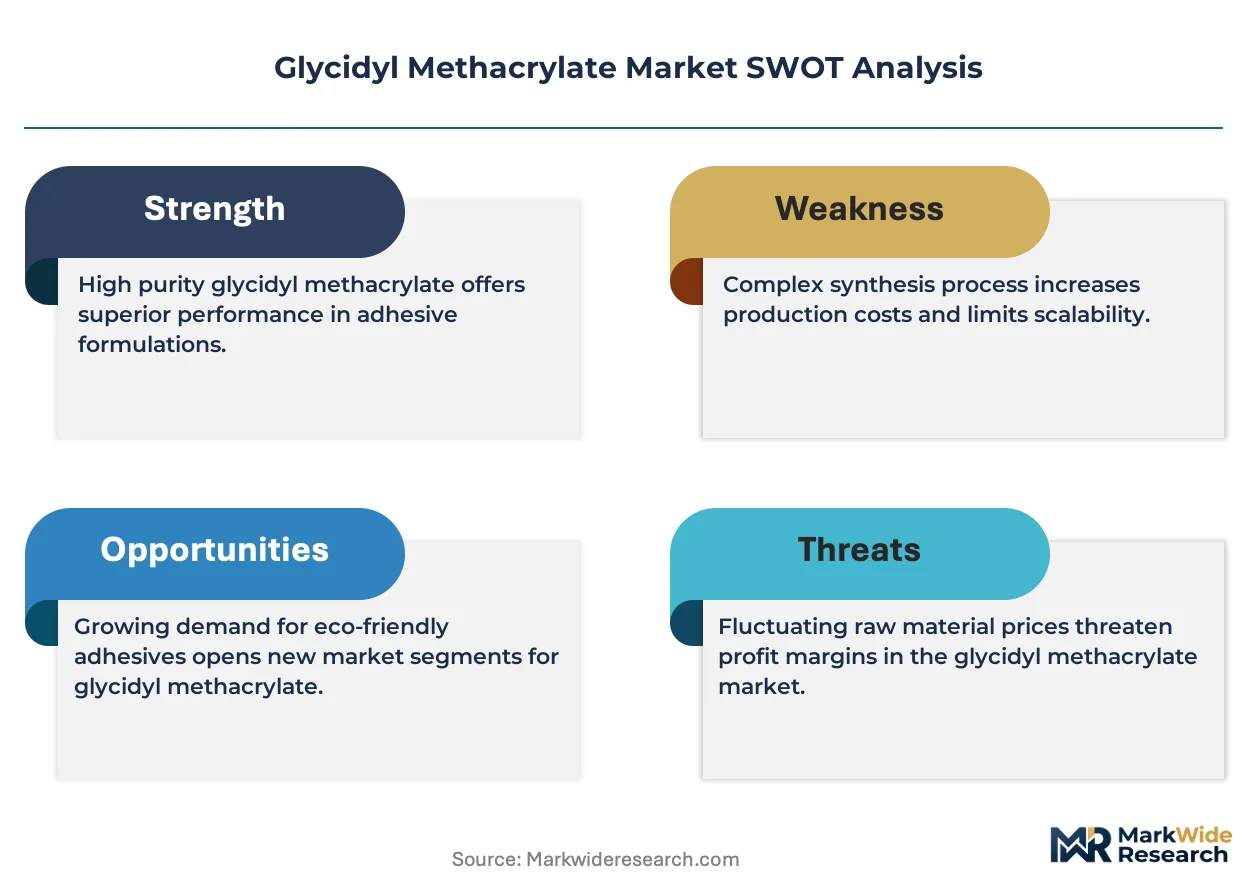
Epichlorohydrin feedstock volatility and tightening biocompatibility certification timelines are compressing supplier margins while rewarding backward-integrated producers with captive epichlorohydrin supply.
Growth Catalysts
- Medical device polymer mandates:FDA biocompatibility standards for implantable devices are accelerating qualification of high-purity glycidyl methacrylate grades in cardiovascular and orthopedic applications.
- REACH registration compliance:European chemical registration requirements are filtering out non-compliant Asian suppliers, creating volume capture opportunities for registered producers serving coatings and adhesives segments.
- Electric vehicle battery assembly:Thermal management sealants incorporating glycidyl methacrylate copolymers are penetrating battery module production lines as OEMs prioritize flame-retardant encapsulation.
Market Restraints
- Epichlorohydrin cost volatility:Propylene-chlorine integrated producers command input cost advantages that independent glycidyl methacrylate manufacturers cannot replicate.
- China supply concentration:Bulk industrial-grade capacity clusters in Shandong and Jiangsu provinces, creating single-source dependency risks for non-integrated European and North American formulators.
- Acrylate substitution pressure:Alternative reactive diluents including trimethylolpropane triacrylate and pentaerythritol triacrylate compete on cost in UV-curable coating formulations where epoxy functionality is not strictly required.
Strategic Opportunities
- India specialty chemicals expansion:PLI scheme incentives for domestic chemical manufacturing are attracting joint venture investments to serve underserved South Asian coatings and dental materials markets.
- Photoresist purity grades:Semiconductor lithography applications demand sub-ppm metal ion specifications that command pricing multiples over standard industrial grades.
- Technical service integration:On-site viscosity customization and formulation support are displacing spot-market transactions in specialty monomer procurement.
Industry Challenges
- Specialized polymer chemist scarcity:Formulation expertise spanning epoxide ring-opening kinetics and methacrylate free-radical polymerization resides in a limited talent pool concentrated at major chemical companies.
- Multi-jurisdiction certification timelines:Simultaneous FDA, REACH, and ISO 10993 biocompatibility testing extends product qualification cycles to 18-24 months for medical-grade entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glycidyl Methacrylate Market |
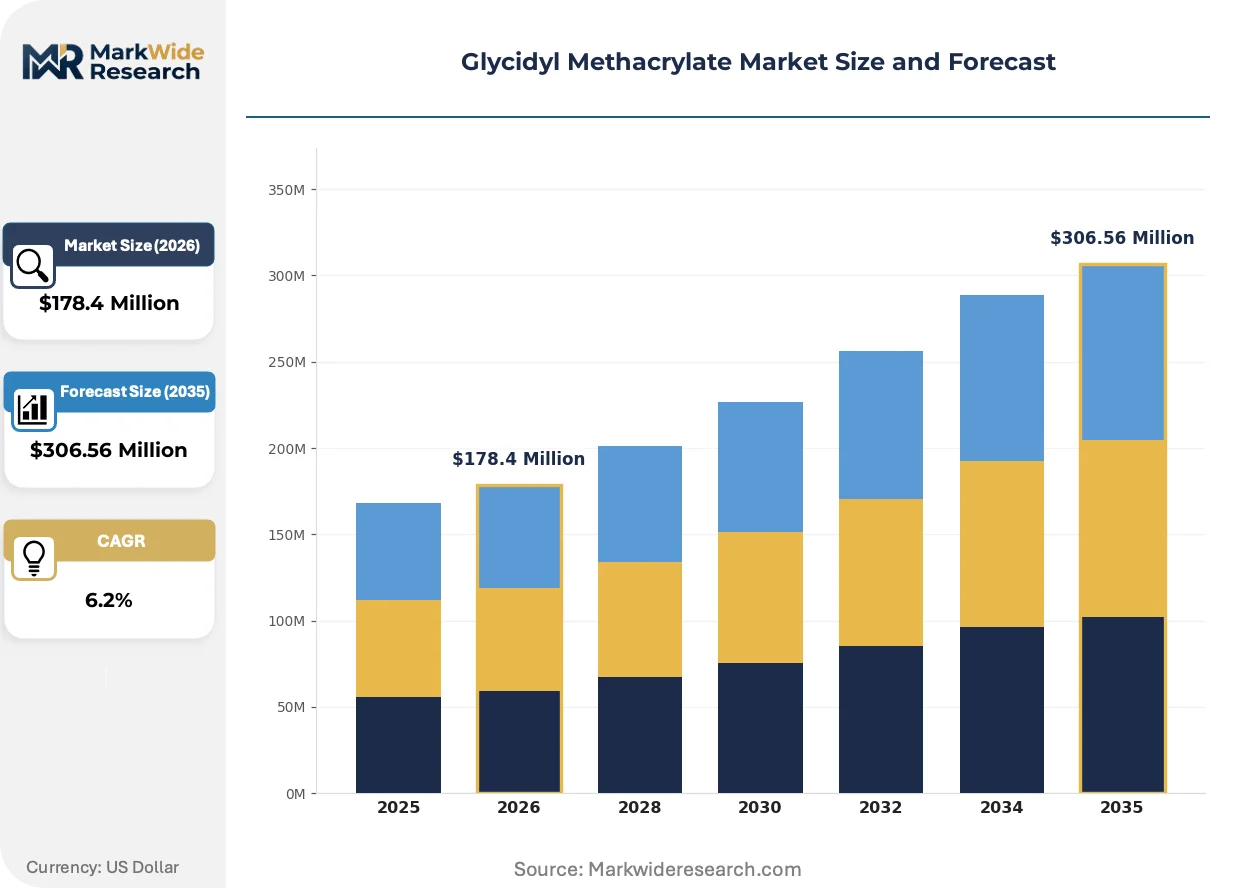
| Market Size in 2026 | $178.4 Million |
| Market Size in 2035 | $306.56 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glycidyl Methacrylate Homopolymer, Copolymer, Block Copolymer, Oligomer Application: Adhesives, Coatings, Sealants, Textiles End User: Aerospace, Automotive Components, Construction, Medical Devices Distribution Channel: Online Sales, Direct Sales, Distributors, Retail |
| Companies Covered | Mitsubishi Gas Chemical Company, Inc., Evonik Industries AG, Estron Chemical, Inc., Lianyungang Ningkang Chemical Co., Ltd., Sumitomo Chemical Co., Ltd., The Dow Chemical Company, KOWA AMERICAN CORPORATION, Oswal Udhyog, Hubei Xiansheng Biotechnology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glycidyl Methacrylate Market Emerging Trajectories
Reactive diluent chemistry and regulatory chemistry are converging to redefine value capture in specialty monomer markets, with purity segmentation and service bundling displacing commodity trading models.
Low-viscosity glycidyl methacrylate oligomers are absorbing demand from conventional monomer grades in UV-curable inkjet formulations. Packaging printers and industrial decoration coaters are adopting these oligomers to reduce volatile organic compound emissions without sacrificing cure speed. The technology is absorbing volume from solvent-borne alternatives while compressing pricing power for standard-grade monomer suppliers.
REACH authorization requirements for epichlorohydrin derivatives are tightening substance volume tracking and downstream user communication obligations. European formulators must now document safe-use conditions across complete supply chains, increasing compliance administration costs. Dental adhesive manufacturers in Germany and Switzerland are responding by consolidating supplier relationships to reduce audit burden.
Specification-driven procurement is consolidating buyer power among large coating formulators and medical device OEMs. Technical service agreements with embedded formulation support are displacing spot-market purchasing for specialty viscosity grades. This behavioral shift is most visible in North American automotive coatings and German dental materials, where qualified supplier lists have narrowed to three or four backward-integrated producers.
Glycidyl Methacrylate Market Segmentation
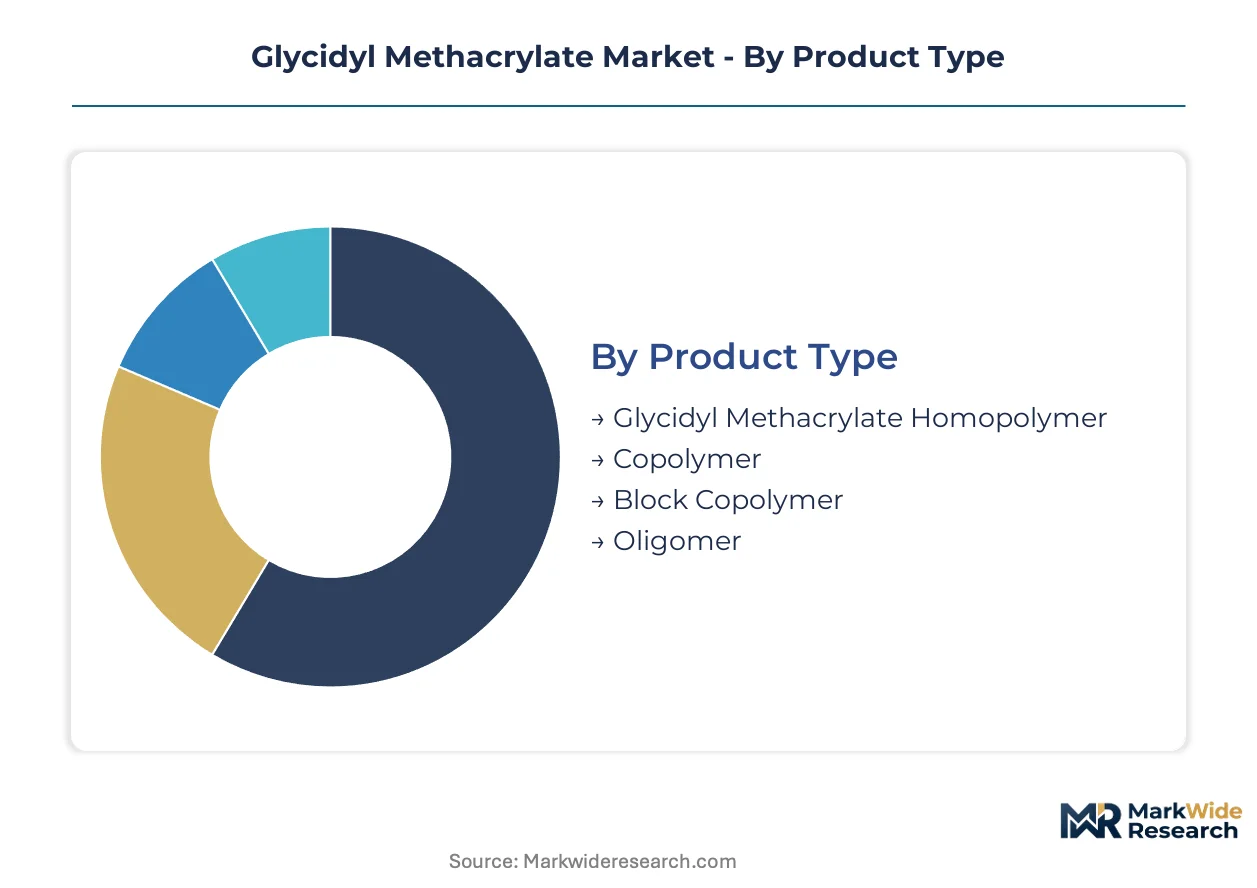
Glycidyl methacrylate procurement splits sharply between specification-driven medical grades and commodity industrial volumes. Formulators select product architectures based on crosslinking density requirements, regulatory certification burdens, and viscosity constraints in automated dispensing systems.
Product Type:
Customization intensity spans from standardized homopolymer bulk to engineered oligomers with tailored molecular weight distributions.
- Glycidyl Methacrylate Homopolymer:Linear polymer chains with pendant epoxide functionality serve photoresist applications in semiconductor lithography. Sub-ppm metal ion specifications command qualification premiums from Japanese and German wafer fabrication facilities.
- Copolymer:Statistical incorporation with acrylates or styrenic monomers balances epoxide reactivity with free-radical cure kinetics. UV-curable coatings for automotive refinishing and wood furniture dominate volume offtake in Italy and the United States.
- Block Copolymer:Segmented architectures enable phase-separated morphologies for toughened thermoset systems.
- Oligomer:Low-viscosity oligomeric grades reduce VOC emissions in inkjet printing formulations.
Leading the category by volume: Copolymer. Growing fastest: Oligomer.
Application:
Performance requirements escalate from structural bonding to barrier protection across this spectrum.
- Adhesives:Structural acrylics leverage epoxide-methacrylate dual cure mechanisms for aerospace composite bonding. Boeing and Airbus tier-1 suppliers in Kansas and Toulouse specify qualified lots with full batch traceability.
- Coatings:Radiation-curable industrial finishes absorb the largest monomer volumes. German automotive OEMs drive formulation standardization through pooled procurement consortia.
- Sealants:Thermal interface materials for electric vehicle battery modules demand flame-retardant encapsulation.
- Textiles:Graft copolymerization imparts wrinkle resistance and dye affinity to cotton and polyester fibers.
Adhesives lead on margin contribution. Sealants expand most quickly on unit growth.
End User:
Certification burden and technical service intensity define customer segmentation in this category.
- Aerospace:AS9100 quality systems and NADCAP chemical processing accreditation filter supplier pools to three backward-integrated producers. Epoxy-acrylate hybrids bond primary structural composites in wing and fuselage assemblies.
- Automotive Components:Lightweighting mandates accelerate adhesive substitution for mechanical fastening. Battery pack manufacturers specify thermal management sealants with dielectric stability.
- Construction:Concrete repair mortars and structural strengthening systems utilize glycidyl methacrylate-modified vinyl esters.
- Medical Devices:ISO 10993 biocompatibility testing and FDA master file submissions extend qualification timelines. Cardiovascular stent coatings and orthopedic cement formulations sustain premium pricing tiers.
Medical Devices concentrate pricing power. Automotive Components scale fastest on electrification investment.
Distribution Channel:
Channel selection reflects order size predictability and formulation support requirements.
- Direct Sales:Annual contracts with embedded technical service dominate medical and aerospace procurement. Mitsubishi Gas Chemical and Evonik maintain dedicated account teams for qualified buyers.
- Distributors:Regional chemical distributors serve mid-tier coatings formulators with stocked viscosity grades.
- Online Sales:E-procurement platforms capture spot demand for R&D quantities and urgent replenishment.
- Retail:Limited to consumer-grade adhesive formulations in hardware channels.
Direct Sales commands margin. Distributors handle largest transaction count.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in East Asia while consumption concentrates in Western Europe and North America, creating trade flows of high-purity grades across regulatory boundaries. China dominates epichlorohydrin-integrated output, yet German and Japanese buyers command premium specifications for medical and electronic applications.
China
Shandong and Jiangsu provinces host concentrated industrial-grade capacity serving coatings and adhesives formulators. MEE emission standards for epichlorohydrin derivatives are tightening wastewater discharge requirements at Taixing and Zibo manufacturing clusters. Lianyungang Ningkang Chemical Co., Ltd. anchors supply continuity through captive feedstock integration.
Germany
Dental materials manufacturers in Ludwigshafen and Leverkusen drive demand for REACH-registered high-purity grades. ECHA authorization protocols for epichlorohydrin derivatives extend compliance documentation burdens to downstream medical device producers. Evonik Industries AG maintains formulation laboratories supporting qualified buyer technical service requirements.
United States
EPA oversight of epichlorohydrin emissions shapes manufacturing economics at Gulf Coast petrochemical complexes. FDA biocompatibility standards for implantable devices filter supplier pools to three backward-integrated producers serving cardiovascular and orthopedic OEMs in Minnesota and Massachusetts. Dow Chemical leverages channel control across automotive coatings procurement.
Japan
Semiconductor lithography applications in Hiroshima and Kyoto prefectures sustain sub-ppm metal ion specification premiums. METI chemical substance management frameworks align with international semiconductor equipment and materials standards. Mitsubishi Gas Chemical Company secures wafer fabrication facility qualifications through dedicated high-purity production lines.
India
PLI scheme incentives attract joint venture investments targeting underserved South Asian coatings and dental materials markets. CDSCO medical device regulations are converging with ISO 13485 quality system requirements for imported polymer raw materials. Maharashtra and Gujarat chemical parks host emerging formulation capabilities serving domestic automotive component manufacturers.
Glycidyl Methacrylate Market Vendor Landscape
Capital-heavy producers compete with asset-light formulators across distinct value capture tiers. Three backward-integrated petrochemical groups dominate volume supply through captive epichlorohydrin production, while specialty monomer houses capture margin through medical-grade certification and technical service bundling. Strategic differentiation concentrates on purity segmentation, regulatory qualification speed, and on-site formulation support rather than commodity scale alone. Competitive moves center on REACH registration portfolio expansion and technical service team deployment to qualified buyer accounts.
Among East Asian integrated producers, Mitsubishi Gas Chemical Company, Inc. and Sumitomo Chemical Co., Ltd. occupy positions defined by semiconductor-grade purity capabilities and regional feedstock control. Evonik Industries AG and The Dow Chemical Company exemplify Western archetypes combining regulatory compliance depth with formulation partnership models. Lianyungang Ningkang Chemical Co., Ltd. represents cost-optimized industrial-grade supply serving price-sensitive coatings markets.
| Leading Market Players |
|---|
| Mitsubishi Gas Chemical Company, Inc. |
| Evonik Industries AG |
| Estron Chemical, Inc. |
| Lianyungang Ningkang Chemical Co., Ltd. |
| Sumitomo Chemical Co., Ltd. |
| The Dow Chemical Company |
| KOWA AMERICAN CORPORATION |
| Oswal Udhyog |
| Hubei Xiansheng Biotechnology Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed petrochemical conglomerates in China and family-owned specialty chemical mid-caps in Germany anchor divergent pricing behaviors, with state-financed capacity expansions in Shandong province compressing spot-market premiums while privately held European producers defend margin through certification bundling and technical service lock-in.
Pricing Analysis
Margin tightening in industrial-grade tiers reflects propylene-chlorine integration advantages that captive epichlorohydrin producers exploit against independent manufacturers. Three-tier pricing structure across medical-grade, industrial-grade, and economy-grade levels stratifies by ISO 10993 certification status and metal ion purity specifications. Pricing pressure intensifies in coatings applications as low-viscosity oligomer substitutes absorb volume from conventional monomer grades. Spot-market buyers in Asian industrial coatings exhibit highest price sensitivity, while FDA-registered medical device OEMs accept premiums for qualified supplier security.
Supply Chain Analysis
Specialized polymer chemist scarcity in Ludwigshafen and Leverkusen constrains formulation support expansion at European suppliers. Manufacturing concentrates in China, Germany, and Japan, with Shandong province hosting bulk industrial capacity and Japanese producers commanding semiconductor-grade purity output. Epichlorohydrin, methacrylic acid, and alkaline catalysts constitute critical input dependencies. Single-source vulnerability pervades non-integrated European and North American formulators dependent on Shandong and Jiangsu supply clusters. Distribution runs through direct sales contracts with embedded technical service for medical and aerospace segments, regional chemical distributors for mid-tier coatings formulators, and e-procurement platforms for R&D quantities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into epichlorohydrin feedstock represents the decisive upstream lever in this vertical-integration race, rewarding producers who secure captive supply against propylene-chlorine volatility while compressing margins for non-integrated competitors.
For Market Incumbents: Extend REACH registration portfolios to filter Asian competitors from European coatings procurement. Deepen formulation laboratory presence in German dental materials clusters to embed technical service relationships. Defend against acrylate substitution pressure in UV-curable applications by co-developing custom viscosity grades with automotive OEM procurement consortia. Prioritize ISO 10993 certification maintenance to sustain medical-grade pricing premiums. For New Entrants and Emerging Players: The premium-economy price-point gap in Indian coatings markets offers white-space entry through PLI scheme joint ventures. Target Maharashtra and Gujarat chemical parks for domestic formulation capabilities serving underserved South Asian demand. Penetrate photoresist purity grades where sub-ppm metal ion specifications command multiples over standard industrial tiers. Lead with on-site viscosity customization to displace spot-market transactions. For Investors and Strategic Acquirers: Distressed-cycle entries favor backward-integrated mid-cap specialists in East Asian epichlorohydrin corridors. Five-to-ten-year viability hinges on regulatory qualification speed rather than commodity scale alone. Watch for FDA master file submission acceleration as inflection signal for medical-grade margin expansion. Prioritize targets with captive feedstock and existing semiconductor or dental OEM qualifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive epichlorohydrin production secures supply continuity against propylene-chlorine volatility at Shandong and Zibo manufacturing clusters. |
| REACH Registration Expansion | ECHA compliance documentation filters non-compliant Asian suppliers from European coatings and adhesives procurement channels. |
| Technical Service Deployment | On-site formulation support in Ludwigshafen and Leverkusen embeds supplier relationships with German dental materials manufacturers. |
| Photoresist Purity Investment | Sub-ppm metal ion production lines capture semiconductor lithography premiums from Hiroshima and Kyoto wafer fabrication facilities. |
| Joint Venture Formation | PLI scheme partnerships in Maharashtra and Gujarat chemical parks access underserved South Asian coatings and dental markets. |
Methodological Framework
Independent corroboration across plant managers at epichlorohydrin-integrated facilities, procurement leads at coatings OEMs, distribution channel partners in specialty monomers, and technical R&D directors in dental materials underwrites the qualitative findings. Primary interviews with these stakeholders combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA registration databases. Bottom-up capacity and consumption estimates triangulated against top-down market sizing across producer disclosures.
Comparable-period anchoring to historical epichlorohydrin price cycles and medical device polymer qualification timelines structured the forecast window. Segmentation modeling spanned grade tier, end-use industry, regional production hub, and certification status dimensions. CAGRs derived from elasticity-adjusted demand projections and capacity expansion announcements. Forecast inputs incorporated REACH authorization timelines, FDA biocompatibility testing durations, and electric vehicle battery assembly adoption curves.
Inputs from ECHA registration databases and FDA master file repositories were available through the study window; gaps in real-time spot-market transaction data introduce uncertainty bands around industrial-grade pricing assumptions. Forecasts reflect documented assumptions regarding epichlorohydrin feedstock integration rates and medical-grade qualification success ratios. Epichlorohydrin cost volatility, dual-use export control expansion, or carbon border adjustment mechanism implementation warrant pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Bromate Substitute Market
Chemical Intermediates
Tetrahydrocurcumin Reagent Market
Chemical Intermediates
Polyamide Intermediate Chemicals Market
Chemical Intermediates
Global Electrophoresis Reagents Market
Chemical Intermediates
Global Iron Chelates Market
Chemical Intermediates
Leather Chemicals Market
Chemical Intermediates
1, 3, 5-Triazine Market
Chemical Intermediates
Ethylene Diamine Tetra Acetic Acid (EDTA) Market
Chemical Intermediates
Pigment Intermediates Market
Chemical Intermediates
Ethylene Urea Market
Chemical Intermediates
Ph Controlling Agents Market
Chemical Intermediates
Grignard Reagents Market
Chemical Intermediates
Hydroxyisobutyric Acid Market
Chemical Intermediates
Duloxetine Intermediate and Atorvastatin Intermediates Market
Chemical Intermediates
Acetoacetanilide Market
Chemical Intermediates
Sequencing Reagents Market