
 Ethylene Diamine Tetra Acetic Acid (EDTA) Market | 2026-2036
Ethylene Diamine Tetra Acetic Acid (EDTA) Market Size, Share, and Industry Trends Forecast 2026-2036
Ethylene Diamine Tetra Acetic Acid (EDTA) Market Foresight
Multi-source procurement of ethylene diamine tetra acetic acid is shifting toward captive and backward-integrated supply arrangements among large-scale consumers. BASF SE leverages its integrated amine production network to secure ethylenediamine feedstock internally. Dow Inc. competes through geographic manufacturing scale across North American and European production sites. Nouryon anchors its position with specialized chelating agent portfolios tailored to industrial water treatment.
Ethylene diamine tetra acetic acid is a hexadentate aminopolycarboxylic acid with the molecular formula C₁₀H₁₆N₂O₈, synthesized through the reaction of ethylenediamine with formaldehyde and sodium cyanide or via the Strecker synthesis pathway, functioning primarily as a metal ion sequestrant across industrial and consumer applications. Industrial grade formulations dominate volume consumption in heavy-duty water treatment and textile processing, while pharmaceutical grade commands concentrated margin pools due to stringent purity certifications and batch validation requirements. Food grade EDTA maintains steady demand within preservative and color retention applications, though growth rates trail the pharmaceutical segment.
EPA effluent limitation guidelines and REACH authorization protocols shape product specifications and market access conditions for manufacturers serving North American and European buyers. China's MEE discharge standards and India's BIS quality mandates further constrain formulation flexibility while creating compliance-driven replacement cycles. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and certification timelines.
Market Dynamics
REACH authorization protocols and China's MEE discharge standards are forcing simultaneous reformulation across European and Chinese manufacturing bases, compressing certification timelines and elevating compliance costs for cross-border suppliers.
Growth Catalysts
- Water treatment infrastructure expansion:Municipal and industrial facilities in India are scaling sequestration chemical procurement for heavy-metal effluent control. State pollution control boards are mandating tertiary treatment upgrades.
- REACH compliance cycles:European manufacturers face authorization deadlines for legacy chelating agents. EDTA substitution demand concentrates in surface coating and textile dyeing applications.
- Pharmaceutical manufacturing scale-up:Active pharmaceutical ingredient producers in India require pharmaceutical-grade EDTA for parenteral formulation stability. CDSCO batch validation requirements are tightening purity thresholds.
Market Restraints
- Feedstock concentration risk:Ethylenediamine supply concentrates among integrated petrochemical producers in Germany and the United States. Spot market exposure elevates margin volatility for non-integrated formulators.
- Biodegradability limitations:EDTA's persistence in aquatic environments triggers substitution pressure from biodegradable chelating agents in EU member states with stringent receiving-water standards.
- Regulatory friction from divergent standards:India's BIS quality mandates, China's GB standards, and REACH authorization create incompatible formulation specifications. Multi-plant operators face redundant certification burdens.
Strategic Opportunities
- Agricultural micronutrient underpenetration:Foliar fertilizer formulators in Brazil and Argentina are adopting EDTA-chelated trace elements for soybean and corn productivity. ANVISA registration pathways are streamlining for imported chelates.
- Green synthesis technology convergence:Bio-based ethylenediamine feedstock development intersects with electrochemical cyanide-free production routes. Joint ventures between biotechnology firms and chemical manufacturers are piloting commercial-scale units.
- Direct-to-formulator digital channels:Specialty chemical distributors are deploying platform-based procurement for mid-scale water treatment operators. Real-time inventory visibility and certificate-of-analysis access are compressing order cycles.
Industry Challenges
- Analytical chemist scarcity:Pharmaceutical-grade batch validation requires skilled personnel for complexometric titration and heavy-metal speciation. Indian and Chinese manufacturing clusters face recruitment competition from biopharma sectors.
- Multi-jurisdiction certification timelines:REACH authorization dossiers, CDSCO drug master file approvals, and EPA pesticide inert ingredient listings require parallel regulatory affairs capacity. Synchronization failures delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethylene Diamine Tetra Acetic Acid (EDTA) Market |
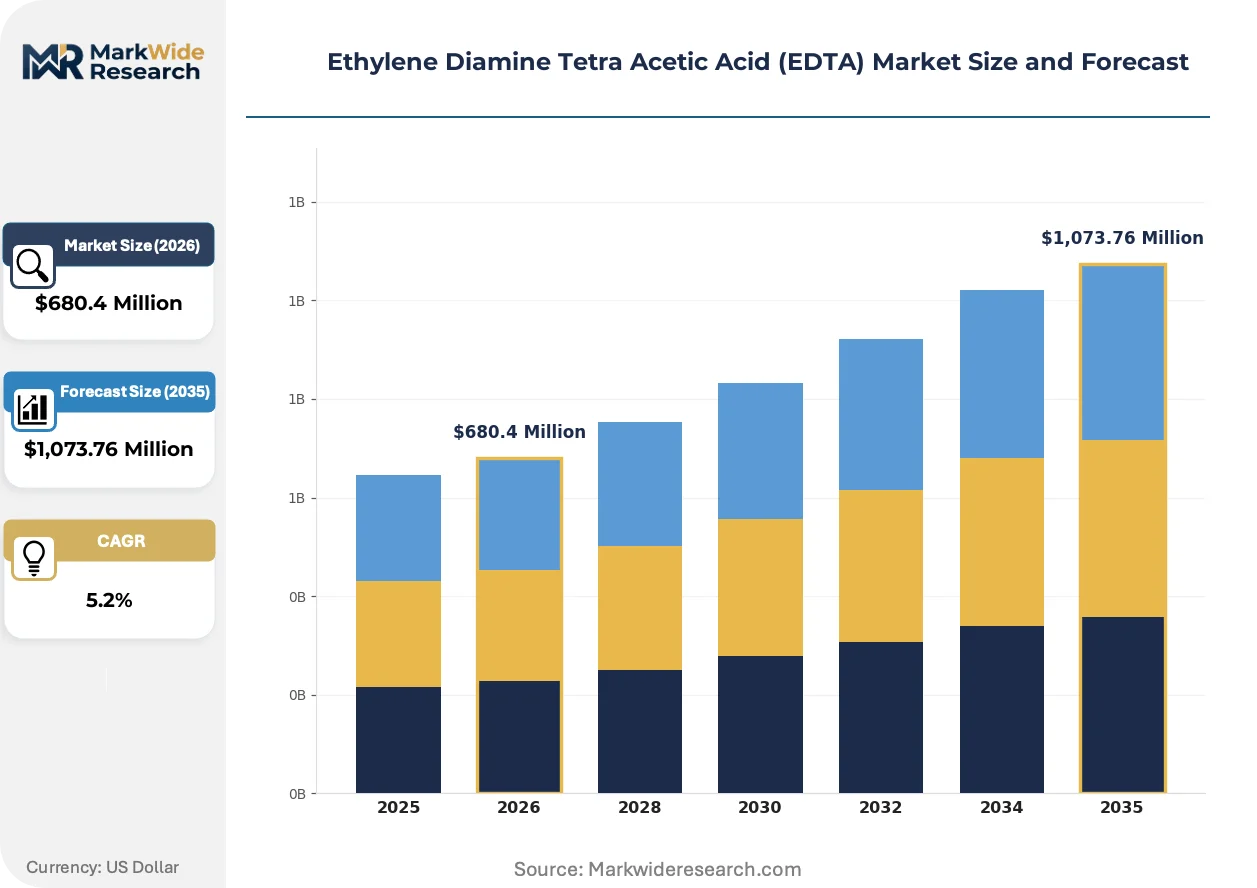
| Market Size in 2026 | $680.4 Million |
| Market Size in 2035 | $1,073.76 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Food Grade, Pharmaceutical Grade, Cheating Agent Application: Water Treatment, Agriculture, Pharmaceuticals, Textile End User: Chemical Industry, Agriculture Sector, Healthcare, Manufacturing Packaging Type: Drum, Bag, Bulk, Pail |
| Companies Covered | BASF SE, Dow Inc., AkzoNobel N.V., LG Chem Ltd., Shandong Maoming Chemical Group, FMC Corporation, Tosoh Corporation, Nouryon, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethylene Diamine Tetra Acetic Acid (EDTA) Market Shifts & Advancements
Formulation chemistry and regulatory compliance are converging to reshape competitive advantage, with sustainability credentials and supply chain traceability emerging as distinct purchasing criteria.
Membrane-based electrochemical synthesis is decentralizing EDTA production economics. Mid-scale water treatment chemical formulators in the United States and Germany are piloting modular units for on-site chelate generation. Distributed manufacturing is compressing logistics costs and enabling just-in-time inventory models for regional industrial clusters.
China's MEE discharge standards are tightening effluent metal concentration limits for electroplating and textile sectors. Provincial environmental protection bureaus are enforcing real-time monitoring and automated reporting. Surface treatment facilities are upgrading to pharmaceutical-grade EDTA formulations to guarantee compliance margin.
Certificate-of-analysis transparency is displacing traditional specification-sheet procurement. Large-scale municipal water authorities in India and Brazil are mandating batch-level heavy-metal and purity documentation. Digital platform integration is most advanced among metropolitan utilities with consolidated chemical purchasing authority.
Ethylene Diamine Tetra Acetic Acid (EDTA) Market Segmentation
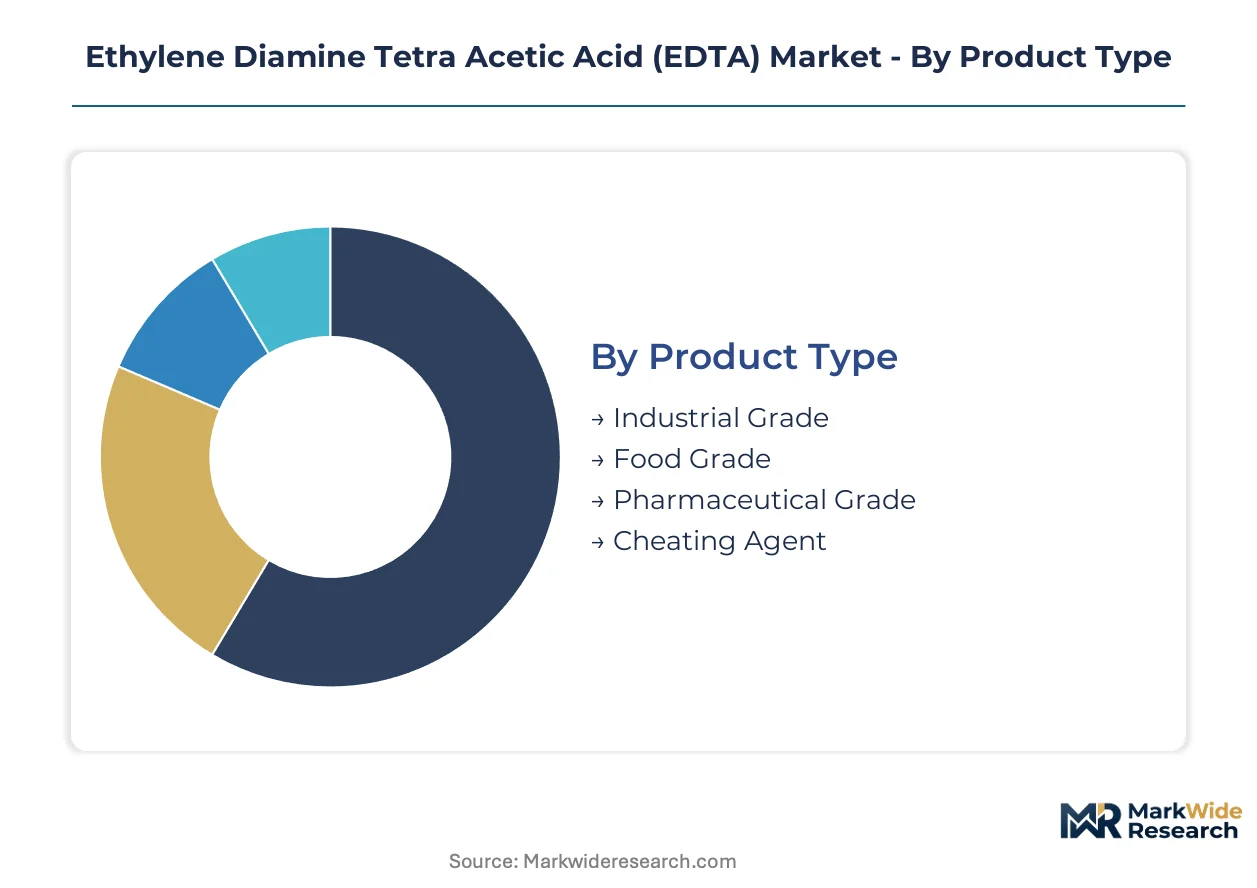
EDTA segmentation reflects divergent purity requirements and regulatory burdens across industrial, food, and pharmaceutical applications. Grade-specific certification costs and end-use performance thresholds create distinct margin architectures that reshape supplier positioning.
Product Type:
Industrial grade dominates tonnage consumption while pharmaceutical grade extracts disproportionate value through batch validation requirements.
- Industrial Grade:Standard purity formulations serve heavy-metal sequestration in textile dyeing and electroplating effluent streams. Demand concentrates in Chinese surface treatment facilities facing MEE discharge standard enforcement. Spot procurement patterns dominate due to price-sensitive volume buyers.
- Pharmaceutical Grade:USP-grade material meets parenteral formulation stability requirements with heavy-metal specifications below 10 ppm. Indian API manufacturers scaling under CDSCO oversight drive procurement concentration. Batch-level certificate-of-analysis documentation adds 15-20% cost premium over industrial equivalents.
- Food Grade:FSSAI-compliant formulations preserve color stability in canned vegetables and mayonnaise. Preservation applications in Indian processed food manufacturing show steady offtake.
- Chelating Agent:Pre-formulated blends combine EDTA with synergistic sequestrants for specialized industrial applications. Custom blends target textile scouring and boiler water treatment.
Mature deployment sits with industrial grade in legacy manufacturing. Newer deployment is concentrated in pharmaceutical grade as Indian and Southeast Asian API capacity expands.
Application:
Water treatment commands volume leadership while agricultural micronutrient delivery shows steepest expansion trajectory.
- Water Treatment:Municipal and industrial facilities deploy EDTA for calcium scale inhibition and heavy-metal effluent control. Indian state pollution control boards mandate tertiary treatment upgrades across electroplating clusters. Real-time monitoring requirements under China's MEE standards force formulation upgrades.
- Pharmaceuticals:Parenteral and ophthalmic formulations require EDTA for antioxidant stabilization and metal ion masking. CDSCO batch validation protocols tighten purity thresholds for imported excipients.
- Agriculture:Foliar fertilizers incorporate EDTA-chelated zinc, iron, and manganese for soybean and corn productivity gains. Brazilian ANVISA registration streamlining accelerates imported chelate adoption.
- Textile:Peroxide bleaching stabilization and dye bath sequestration consume industrial grade material. REACH authorization pressures drive substitution inquiries in EU member states.
Established penetration characterizes water treatment in mature industrial economies. Agricultural micronutrient applications are gaining share fastest across Latin American and South Asian markets.
End User:
Chemical industry procurement scales through distributor networks while healthcare direct-buying concentrates among validated API manufacturers.
- Chemical Industry:Water treatment chemical formulators and textile auxiliaries producers constitute bulk consumption. German and US distributors maintain regional inventory positions for just-in-time delivery.
- Healthcare:Parenteral drug manufacturers require pharmaceutical grade material with complete batch traceability. Indian API clusters in Hyderabad and Ahmedabad consolidate procurement through approved vendor lists.
- Agriculture Sector:Foliar fertilizer blenders and micronutrient premix formulators drive chelated trace element demand. Brazilian cooperatives and Argentine grain exporters specify EDTA-chelated formulations.
- Manufacturing:Surface treatment facilities and electronics plating operations consume industrial grade for effluent compliance. Chinese electroplating clusters face real-time discharge monitoring under provincial MEE enforcement.
Long-term contracting prevails in chemical industry procurement. Healthcare sector purchasing is consolidating through single-source validated supplier arrangements.
Packaging Type:
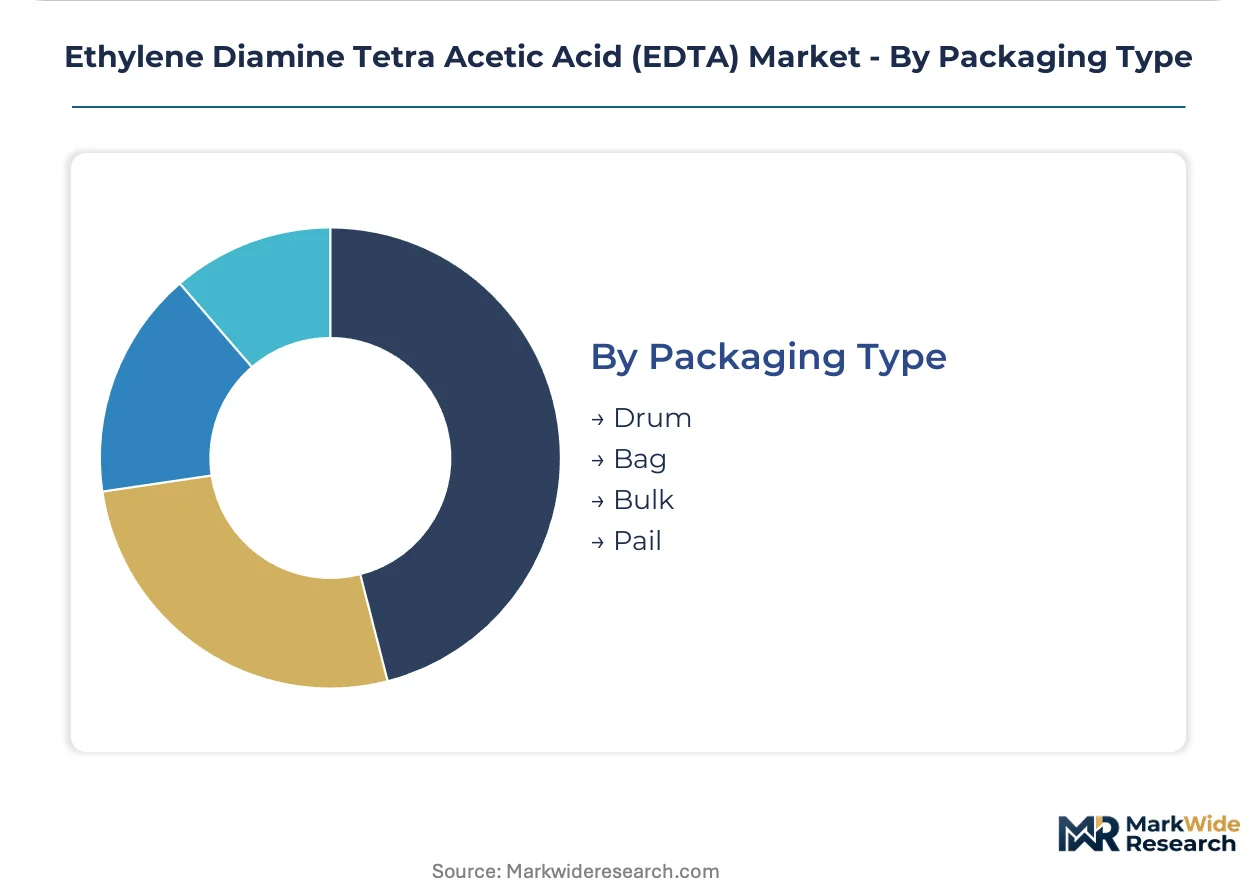
Drum and bag formats serve fragmented mid-scale demand while bulk delivery anchors integrated water treatment chemical production.
- Drum:200-liter steel and HDPE drums serve textile auxiliaries producers and small-scale electroplating operations. Indian and Southeast Asian distributors maintain drum stock for spot market coverage.
- Bag:25-50 kg multi-wall paper bags target agricultural micronutrient blenders and food processing facilities. Brazilian and Argentine fertilizer formulators specify bagged material for seasonal procurement flexibility.
- Bulk:Tanker and silo delivery supports integrated water treatment chemical manufacturing in Germany and the United States. Captive consumption by backward-integrated producers reduces external bulk market liquidity.
- Pail:20-25 liter containers serve laboratory and pilot-scale pharmaceutical formulation development. CDSCO-registered excipient suppliers package pharmaceutical grade in pail format for sampling and validation batches.
Conventional drum and bag formats retain dominance in fragmented end-use segments. Bulk infrastructure investment is concentrating among North American and European integrated producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylenediamine feedstock production concentrates in the Rhine-Ruhr industrial corridor and the US Gulf Coast, anchoring EDTA manufacturing capacity across Germany and the United States. These localities supply derivative chelating agent production serving municipal water treatment, pharmaceutical formulation, and agricultural micronutrient markets worldwide.
China
Electroplating clusters in Guangdong and Zhejiang provinces drive industrial-grade EDTA consumption for heavy-metal effluent sequestration. Provincial environmental protection bureaus enforce real-time discharge monitoring under MEE standards. Surface treatment facilities in the Pearl River Delta upgrade to pharmaceutical-grade formulations to guarantee compliance margins.
India
API manufacturers in Hyderabad and Ahmedabad scale pharmaceutical-grade EDTA procurement for parenteral formulation stability. CDSCO batch validation protocols tighten purity thresholds for imported excipients. State pollution control boards mandate tertiary treatment upgrades across electroplating clusters in Tamil Nadu and Maharashtra.
Germany
Integrated petrochemical producers in the Rhine-Ruhr region leverage captive ethylenediamine supply for chelating agent manufacturing. REACH authorization deadlines force substitution demand in textile dyeing and surface coating applications. Water treatment chemical formulators in North Rhine-Westphalia maintain regional inventory positions for just-in-time delivery.
United States
Municipal water authorities in Texas and California deploy EDTA for calcium scale inhibition in desalination and distribution infrastructure. EPA effluent limitation guidelines shape product specifications for industrial buyers. Mid-scale water treatment operators in the Midwest pilot membrane-based electrochemical synthesis for on-site chelate generation.
Brazil
Foliar fertilizer formulators in São Paulo and Paraná adopt EDTA-chelated trace elements for soybean and corn productivity gains. ANVISA registration pathways streamline for imported chelates. Agricultural cooperatives specify bagged material for seasonal procurement flexibility during planting windows.
Ethylene Diamine Tetra Acetic Acid (EDTA) Market Competitive Landscape
Backward integration into ethylenediamine feedstock dominates the current landscape, compressing margin structures for non-integrated formulators. The vendor base concentrates among petrochemical conglomerates with captive amine production, specialty chemical houses with chelating agent portfolios, and regional distributors serving fragmented end-use segments. Three archetypes prevail: integrated producers controlling upstream raw material supply, specialty manufacturers focusing on pharmaceutical-grade certification, and distributor-led networks covering spot procurement in emerging markets. Capacity expansion and strategic partnerships represent the dominant competitive moves, with joint ventures piloting bio-based feedstock development.
Within the integrated producer tier, BASF SE and Dow Inc. exemplify upstream control over critical feedstock supply. Nouryon occupies a position among specialty chelating agent manufacturers with tailored industrial water treatment portfolios. These three anchors represent distinct strategic postures: petrochemical-backed scale, geographic manufacturing distribution, and application-specific formulation expertise.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| AkzoNobel N.V. |
| LG Chem Ltd. |
| Shandong Maoming Chemical Group |
| FMC Corporation |
| Tosoh Corporation |
| Nouryon |
| Merck KGaA |
| Others |
Supply & Pricing Matrix
CDSCO batch validation requirements for pharmaceutical-grade material are compressing procurement timelines and forcing suppliers to absorb certification cost premiums or lose validated supplier status. This specification tightening concentrates buying power among backward-integrated producers with in-house analytical capabilities, while spot-market industrial-grade suppliers face margin compression from price-sensitive volume buyers.
Pricing Analysis
Certificate-of-analysis bundling separates pharmaceutical-grade suppliers from unbundled industrial-grade competitors. Pricing stratifies across pharmaceutical, food, and industrial tiers based on purity certification and batch documentation burden. Cost compression in industrial grade is intensifying because Chinese electroplating facilities face MEE-mandated formulation upgrades without corresponding price tolerance. Municipal water authorities show least price sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Ethylenediamine feedstock supply rests on integrated petrochemical producers in Germany and the United States. Manufacturing draws from formaldehyde and sodium cyanide inputs, with electrochemical cyanide-free routes emerging as alternative pathways. Single-source vulnerability concentrates around Rhine-Ruhr and US Gulf Coast ethylenediamine capacity. Distribution runs through specialty chemical distributors for drum and bag formats, with bulk tanker delivery serving integrated water treatment chemical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH authorization protocols and CDSCO validation requirements erect regulatory moats that favor incumbents with established dossier capacity and analytical infrastructure.
For Market Incumbents: Anticipate substitution pressure from biodegradable chelating agents in EU member states with stringent receiving-water standards. Defensive moves center on captive ethylenediamine supply security and pharmaceutical-grade certification investment in Indian API clusters. Priority levers include electrochemical synthesis piloting and digital platform integration for certificate-of-analysis transparency. For New Entrants and Emerging Players: ANVISA registration streamlining in Brazil opens a window for agricultural micronutrient chelate penetration. White-space targets include foliar fertilizer formulators in São Paulo and Paraná cooperatives, plus mid-scale Indian electroplating facilities facing state pollution control board tertiary treatment mandates. Go-to-market positioning emphasizes bagged material for seasonal procurement flexibility. For Investors and Strategic Acquirers: The window for entry favors specialty manufacturers with pharmaceutical-grade certification infrastructure and validated supplier relationships with Indian API producers. Long-term viability hinges on regulatory divergence management capacity and bio-based feedstock development partnerships. The signal to watch is membrane-based electrochemical synthesis commercialization at pilot scale.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive ethylenediamine supply secures margin control against feedstock volatility. |
| Green Manufacturing Transition | Bio-based feedstock development intersects with electrochemical cyanide-free production routes. |
| Long-term Supply Agreement | Validated supplier arrangements with CDSCO-registered API manufacturers lock in pharmaceutical-grade offtake. |
| Joint Venture | Biotechnology partnerships pilot commercial-scale bio-ethylenediamine units for sustainability positioning. |
| Capacity Expansion | Modular electrochemical synthesis deployment enables distributed manufacturing for regional industrial clusters. |
Research Methodology
Independent corroboration across regulatory filing databases, customs trade records, and industry association publications underwrites the qualitative findings. Primary interviews with plant managers at integrated chelating agent producers, procurement leads at Indian API manufacturers, distribution channel partners in Brazil and Germany, and technical R&D directors at specialty chemical houses combined with secondary validation from ECHA authorization dossiers, CDSCO drug master files, EPA effluent guidelines, and SEC 10-K disclosures. Bottom-up segmentation modeling and top-down macroeconomic anchoring triangulate volume and value estimates.
Comparable historical periods anchored demand trajectories and pricing dynamics across the projection horizon. The analytical framework models grade tier, end-use industry, packaging format, and regional production hub segmentation dimensions. CAGRs derive from regression-based trending of historical consumption patterns adjusted for regulatory compliance cycle timing. Forecast inputs include ethylenediamine feedstock capacity utilization rates and pharmaceutical-grade batch validation queue lengths at CDSCO.
The model assumes a particular technology adoption path; alternative pathways for membrane-based electrochemical synthesis would alter the outlook if commercial scale-up accelerates. Forecasts reflect assumptions about regulatory enforcement consistency and feedstock supply concentration. Feedstock price volatility, regulatory timeline slippage, and substitute chelating agent breakthroughs warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Myristoyl Chloride Market
Chemical Intermediates
Japan Formic Acid Market
Chemical Intermediates
Dimethyl Dicarbonate Market
Chemical Intermediates
Sequencing Reagents Market
Chemical Intermediates
Diethyl Phthalate Market
Chemical Intermediates
Pharmaceutical Intermediates Market
Chemical Intermediates
Montelukast Intermediate Market
Chemical Intermediates
Penicillin Intermediate Market
Chemical Intermediates
Natural Chelating Agents Market
Chemical Intermediates
Epoxy Silanes Market
Chemical Intermediates
Polyamide Intermediate Chemicals Market
Chemical Intermediates
Pigment Intermediates Market
Chemical Intermediates
Glycidyl Methacrylate Market
Chemical Intermediates
Thioesters Market
Chemical Intermediates
Reagent Bottle Market
Chemical Intermediates
Isosafrole Market