
 Tetrahydrocurcumin Reagent Market | 2026-2036
Tetrahydrocurcumin Reagent Market Size, Share, and Industry Trends Forecast 2026-2036
Tetrahydrocurcumin Reagent Market Insights
Curcumin is hardening into tetrahydrocurcumin across cosmetic and pharmaceutical labs seeking superior oxidative stability and colorless formulation compatibility. Merck KgaA (Sigma-Aldrich) leverages its global distribution network to sustain premium positioning in research-grade supply. Santa Cruz Biotechnology (SCBT) anchors North American life science channels with specialized biochemical reagents. Hangzhou J&H Chemical competes on cost-efficient synthesis from China's Zhejiang province.
Tetrahydrocurcumin reagent constitutes the hydrogenated derivative of curcumin, typically exhibiting enhanced bioavailability and reduced photosensitivity compared to its parent polyphenol, manufactured through catalytic hydrogenation or enzymatic reduction processes primarily for antioxidant, anti-inflammatory, and skin-whitening applications. The pharmaceutical grade segment commands the deepest margin pools due to stringent purity certifications and batch documentation requirements. Synthetic origin products dominate volume flows, though natural-labeled variants occupy expanding positions in clean-beauty cosmetics and premium nutraceutical channels. Powder form leads industrial procurement for formulation flexibility, while liquid preparations gain traction in automated laboratory workflows.
REACH registration requirements in the European Union and FDA oversight of cosmetic ingredient safety through the Voluntary Cosmetic Registration Program shape product standards and market access trajectories for tetrahydrocurcumin suppliers. China's NMPA and GB standards for cosmetic raw materials impose additional testing protocols that filter out subscale manufacturers. Stakeholders must monitor evolving purity thresholds across multiple regulatory jurisdictions and assess backward integration into curcumin feedstock cultivation or fermentation-derived alternatives to secure supply continuity.
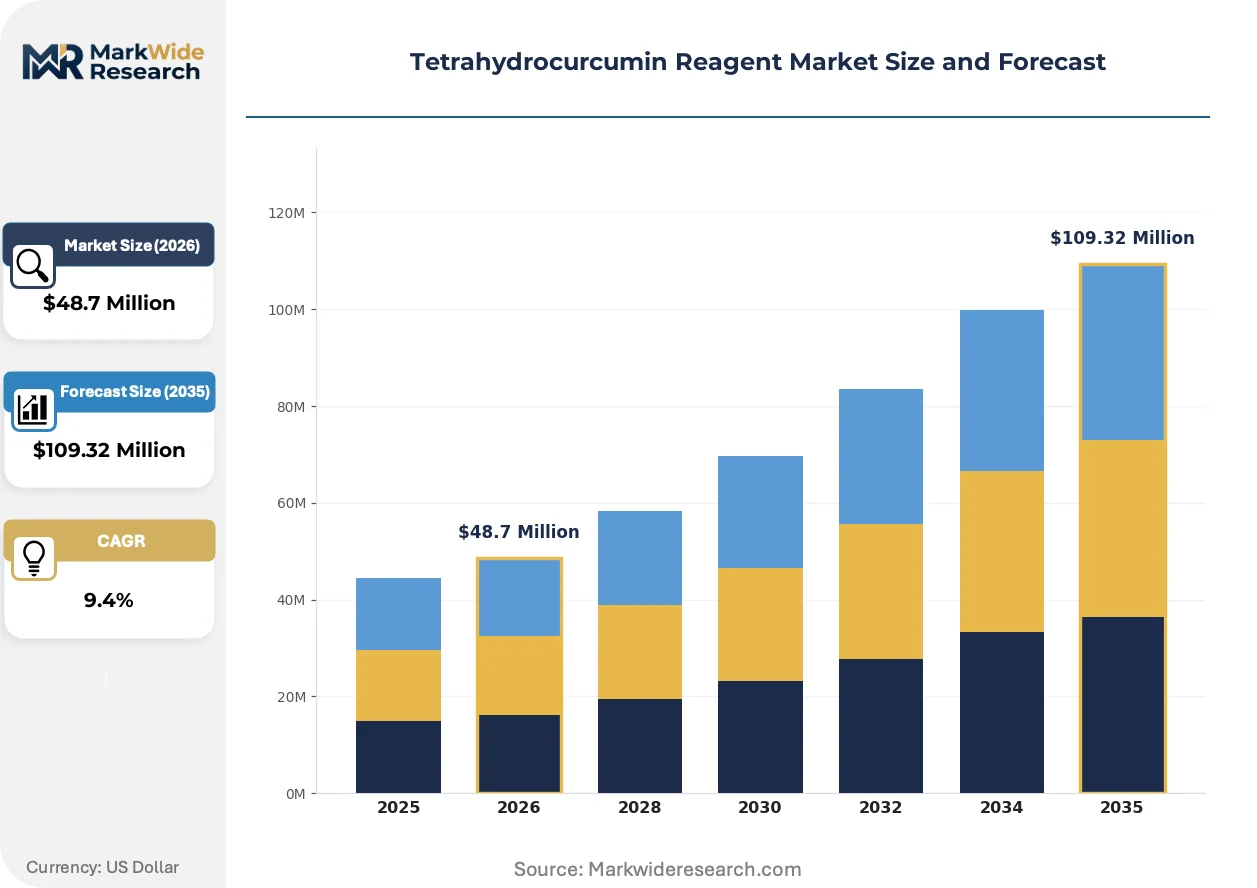
Market Dynamics
Catalytic hydrogenation process refinements and REACH registration burdens are bifurcating the supplier base into certified pharmaceutical-grade producers and excluded commodity-grade operators.
Growth Catalysts
- Cosmetic formulation demand:South Korean cosmetics formulators are expanding procurement of tetrahydrocurcumin for skin-brightening products, pulling volume through Hangzhou and Shanghai chemical clusters.
- REACH compliance elevation:Stricter purity thresholds from ECHA registration requirements are filtering out subscale European suppliers and consolidating demand among certified producers.
- Enzymatic reduction advances:Biocatalytic manufacturing routes are lowering residual solvent profiles and opening natural-labeled positioning for clean-beauty channels.
Market Restraints
- Curcumin feedstock volatility:Turmeric root price swings and Indian monsoon dependency transmit directly into tetrahydrocurcumin cost structures.
- Zhejiang production concentration:Overreliance on Hangzhou-area chemical parks creates single-point vulnerability for global supply continuity.
- Natural-synthetic labeling friction:Clean-beauty certification bodies impose ambiguous criteria that complicate positioning for catalytically hydrogenated material.
Strategic Opportunities
- Fermentation-derived alternatives:Microbial biosynthesis of tetrahydrocurcumin precursors offers path to natural-origin claims without agricultural feedstock exposure.
- Automated laboratory workflows:Liquid reagent formats are penetrating high-throughput screening segments previously served by powder handling.
- MFDS cosmetic ingredient pathways:South Korea's streamlined raw material approval processes enable faster market entry for documented pharmaceutical-grade suppliers.
Industry Challenges
- Batch documentation complexity:Pharmaceutical-grade certification requires full chain-of-custody records that strain legacy quality management systems.
- Cross-jurisdictional purity harmonization:Divergent thresholds between FDA cosmetic guidance, REACH annexes, and NMPA GB standards force redundant testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tetrahydrocurcumin Reagent Market |
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $109.32 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Authentic, Synthetic, Natural, Organic Application: Cosmetics, Pharmaceuticals, Nutraceuticals, Functional Foods Grade: Food Grade, Pharmaceutical Grade, Industrial Grade, Research Grade Form: Powder, Liquid, Capsule, Tablet |
| Companies Covered | Merck KgaA (Sigma-Aldrich), Santa Cruz Biotechnology (SCBT), Fluorochem, Hangzhou J&H Chemical, TIANFU CHEMICAL, Chemenu, COMBI-BLOCKS, Abcr GmbH, Parchem Fine and Specialty Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tetrahydrocurcumin Reagent Market Trends and Innovations
Process intensification and regulatory data requirements are compressing the viable supplier set while opening formulation opportunities in colorless cosmetic applications.
Continuous-flow hydrogenation reactors are consolidating batch manufacturing positions in pharmaceutical-grade tetrahydrocurcumin production. European and North American contract manufacturers are retrofitting fixed-bed catalytic systems to meet ECHA documentation standards. This equipment transition is consolidating production among capitalized operators capable of validated process analytical technology.
REACH annex revisions are tightening impurity disclosure thresholds for hydrogenated natural products used in cosmetic applications. ECHA's expanded substance evaluation workload is extending registration timelines for new market entrants. Pharmaceutical-grade suppliers with existing dossiers are capturing displaced demand from commodity operators facing compliance gaps.
Specification-driven sourcing contracts are displacing spot-market purchasing among multinational cosmetics formulators. Buyers are consolidating vendor panels to three qualified suppliers per region and demanding locked purity certificates. South Korean and Japanese cosmetics houses are leading this contractual shift, prioritizing supply security over unit cost minimization.
Tetrahydrocurcumin Reagent Market Segmentation
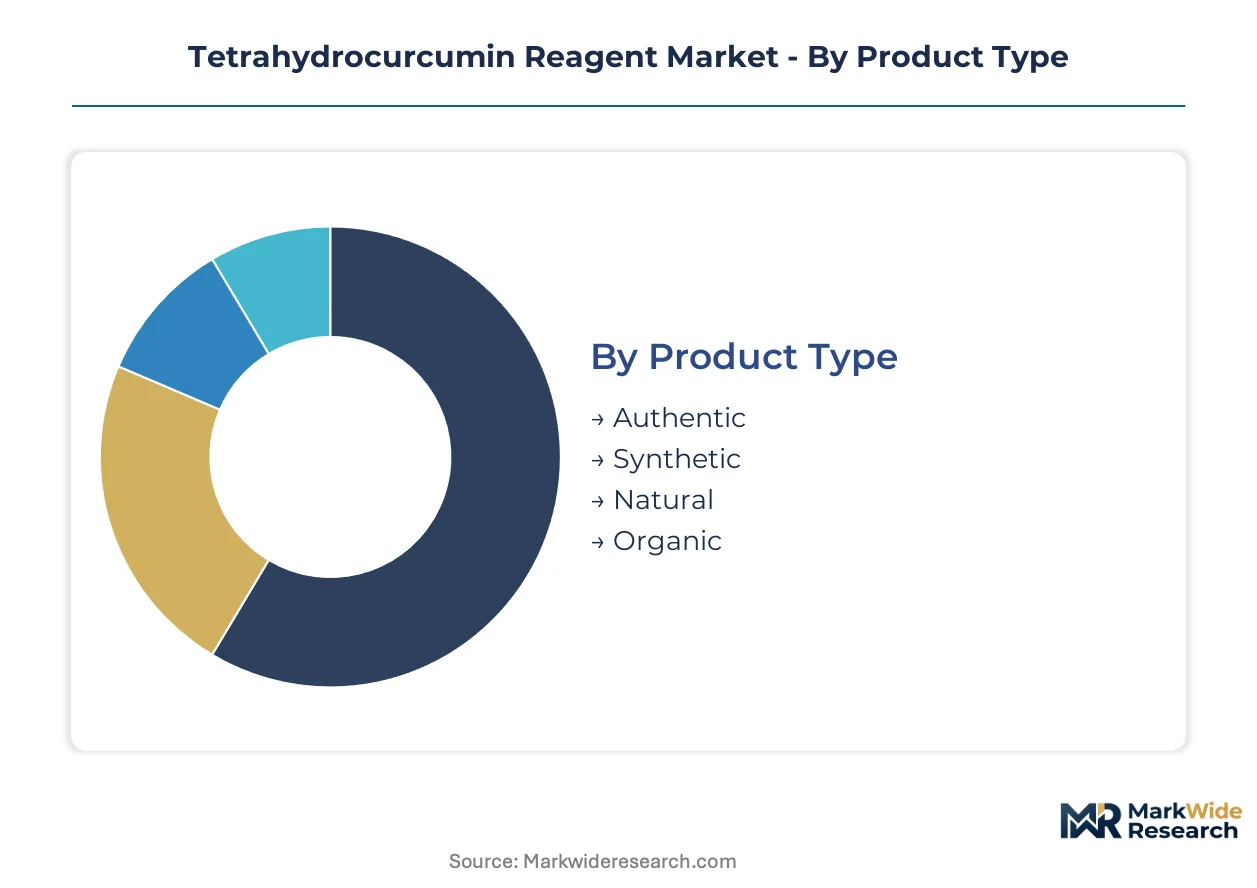
Tetrahydrocurcumin reagent procurement splits across four distinct classification axes, each governing access to different margin pools and regulatory clearance pathways. Specification choices at each tier determine compatibility with pharmaceutical dossiers, cosmetic safety assessments, or food additive approvals.
Product Type:
Origin certification defines pricing architecture and permissible label claims across consumer-facing channels.
- Authentic:Material derived from verified turmeric curcuminoid sources with documented hydrogenation provenance. South Korean cosmetics houses prioritize this segment for MFDS-compliant skin-brightening formulations requiring chain-of-custody verification.
- Synthetic:Petrochemical-derived precursors subjected to identical hydrogenation protocols yield cost advantages but forfeit natural-origin positioning. Chinese manufacturers in Hangzhou chemical parks dominate volume production for industrial and research applications where label claims are immaterial.
- Natural:Fermentation-derived or enzymatically reduced material satisfies clean-beauty certification criteria without agricultural feedstock dependency. ECHA's evolving natural-synthetic boundary definitions create compliance uncertainty for this positioning.
- Organic:Certified organic feedstock plus hydrogenation process audited under organic handling standards commands premium positioning in premium nutraceutical channels with the narrowest addressable demand base.
Authentic leads on scale; Natural leads on momentum.
Application:
End-use specifications diverge sharply on purity thresholds, documentation depth, and batch testing protocols.
- Cosmetics:Skin-brightening and antioxidant formulations drive procurement from South Korean and Japanese formulators seeking colorless, photostable actives. REACH cosmetic ingredient disclosure requirements and MFDS streamlined approval pathways shape supplier qualification.
- Pharmaceuticals:Investigational drug applications and API development demand pharmaceutical-grade material with full impurity profiling and stability data. FDA oversight through IND-enabling studies and EMA quality documentation standards elevate entry barriers.
- Nutraceuticals:Dietary supplement formulations prioritize bioavailability claims and natural-origin positioning over synthetic alternatives. FSSAI in India and China's SAMR impose distinct purity benchmarks for ingestible products.
- Functional Foods:Food-grade hydrogenated curcuminoids face stringent GRAS or novel food approvals with limited commercial penetration to date.
Cosmetics anchors current procurement volumes; Pharmaceuticals offers the steepest expansion trajectory.
Grade:
Certification tier directly determines accessible customer segments and margin realization.
- Pharmaceutical Grade:Batch-released material meeting USP/EP monographs with full COA documentation and stability data. Contract manufacturers serving FDA-regulated drug development programs consolidate procurement among three qualified suppliers per region.
- Research Grade:High-purity material for analytical standards and preclinical studies without pharmaceutical batch release overhead. Sigma-Aldrich and Santa Cruz Biotechnology anchor distribution through life science channels.
- Food Grade:FSSAI, FDA food additive, or EFSA-compliant material for nutraceutical and functional food incorporation with intermediate documentation requirements.
- Industrial Grade:Technical specification material for non-ingestible applications and process development with minimal certification burden and corresponding price compression.
Pharmaceutical Grade commands margin concentration; Research Grade shows the fastest volume climb in automated laboratory workflows.
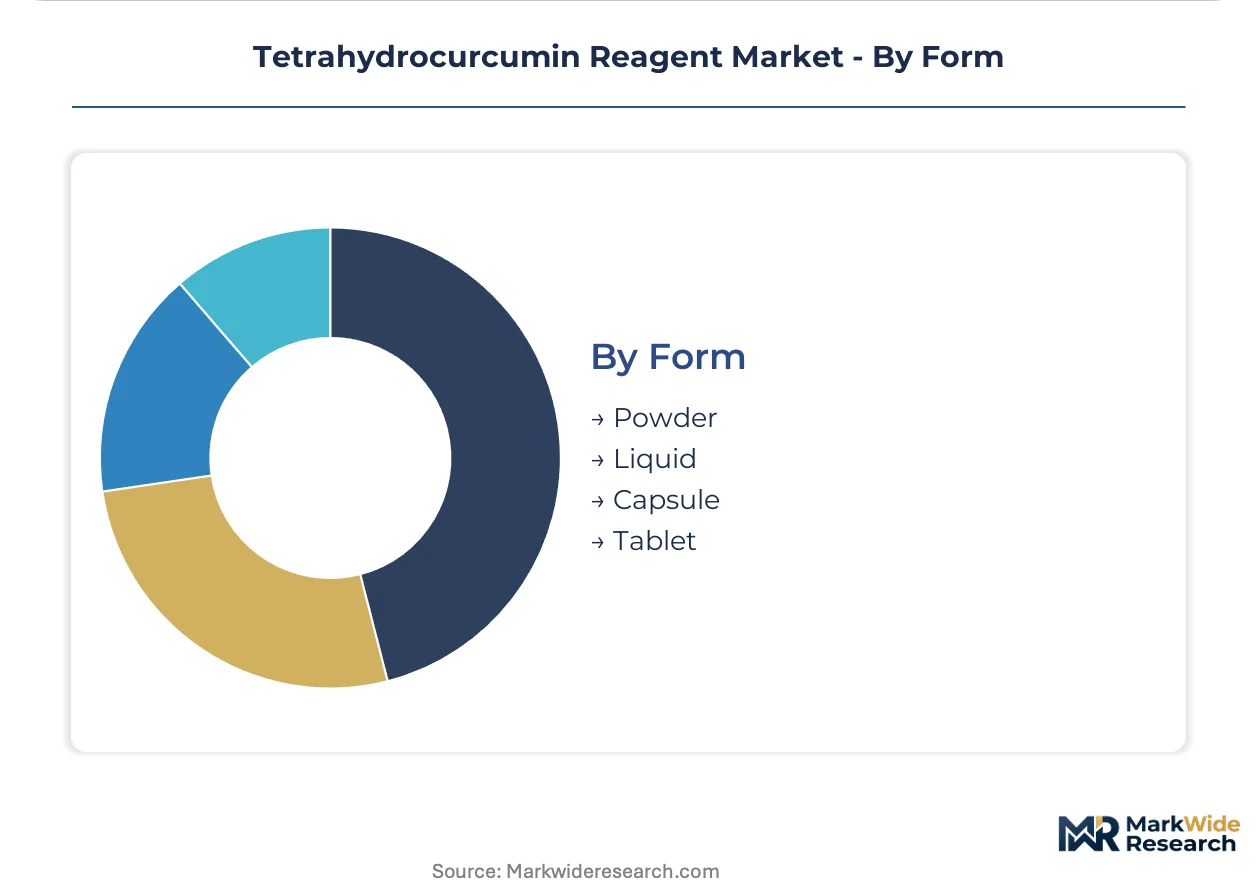
Form:
Physical presentation governs handling efficiency across manual formulation and automated processing environments.
- Powder:Crystalline or micronized solid dominates industrial procurement for formulation flexibility in cosmetics and nutraceutical compounding. Bulk handling efficiency favors high-volume manufacturers.
- Liquid:Dissolved or suspension formats penetrate high-throughput screening and automated liquid handling workflows in pharmaceutical discovery. Solvent selection and concentration standardization create specification fragmentation.
- Capsule:Pre-encapsulated material targets direct-to-consumer nutraceutical brands seeking manufacturing simplification.
- Tablet:Compressed dosage forms remain marginal for tetrahydrocurcumin given stability and dissolution profile challenges relative to powder-in-capsule alternatives.
Powder maintains volume leadership; Liquid gains share fastest in pharmaceutical discovery automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hangzhou chemical parks anchor production capacity for tetrahydrocurcumin reagents, with procurement demand radiating from South Korean cosmetics laboratories and European pharmaceutical contract manufacturers. Regulatory divergence across ECHA, FDA, and NMPA jurisdictions filters supplier access and shapes regional sourcing strategies.
China
Hangzhou and Shanghai chemical clusters dominate both catalytic hydrogenation capacity and export logistics for curcumin-derived reagents. NMPA cosmetic raw material GB standards impose testing protocols that filter subscale manufacturers from the supply base. Zhejiang province producers are consolidating batch documentation systems to meet pharmaceutical-grade export requirements.
South Korea
Seoul-based cosmetics formulators are expanding tetrahydrocurcumin procurement for MFDS-compliant skin-brightening formulations. MFDS streamlined raw material approval processes enable faster market entry for documented pharmaceutical-grade suppliers. Busan-Ulsan chemical processing zones are attracting hydrogenation technology partnerships to localize precursor supply.
United States
FDA oversight of cosmetic ingredient safety through the Voluntary Cosmetic Registration Program shapes supplier qualification protocols for domestic formulators. Greater Boston and New Jersey pharmaceutical corridors drive research-grade demand for IND-enabling studies. Contract manufacturers are consolidating vendor panels to three qualified suppliers per region to secure batch documentation.
Germany
REACH registration requirements and ECHA substance evaluation workloads are extending timelines for new market entrants and consolidating demand among certified producers. Bavaria and North Rhine-Westphalia host retrofitting of fixed-bed catalytic systems to meet ECHA documentation standards. Merck KgaA leverages its global distribution network from Darmstadt headquarters to sustain premium positioning.
India
Turmeric root cultivation in Maharashtra and Karnataka creates feedstock proximity for hydrogenation operations, though monsoon dependency transmits price volatility into cost structures. FSSAI purity benchmarks for ingestible products diverge from cosmetic-grade specifications, forcing redundant testing. CDSCO pharmaceutical-grade certification requirements are elevating documentation burdens for exporters.
Tetrahydrocurcumin Reagent Market Competitive Landscape
Global majors compete with regional champions across certification tiers, with pharmaceutical-grade documentation capabilities separating consolidated premium suppliers from fragmented commodity operators. The vendor base stratifies into three archetypes: diversified chemical conglomerates with full regulatory dossiers, specialized biochemical suppliers serving life science channels, and cost-focused regional fabricators concentrated in Chinese chemical parks. Dominant competitive moves include backward integration into curcumin feedstock cultivation and technology licensing for enzymatic reduction routes.
Among German diversified chemical conglomerates, Merck KgaA exemplifies the premium-tier archetype through research-grade distribution scale. Santa Cruz Biotechnology anchors North American biochemical specialization with life science channel focus. Hangzhou J&H Chemical occupies the cost-efficient synthesis position within China's Zhejiang production cluster. These three represent the structural poles—regulatory depth, regional specialization, and manufacturing scale—around which competitive positioning organizes.
| Leading Market Players |
|---|
| Merck KgaA (Sigma-Aldrich) |
| Santa Cruz Biotechnology (SCBT) |
| Fluorochem |
| Hangzhou J&H Chemical |
| TIANFU CHEMICAL |
| Chemenu |
| COMBI-BLOCKS |
| Abcr GmbH |
| Parchem Fine and Specialty Chemicals |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists in Zhejiang province anchor catalytic hydrogenation capacity, transmitting cost discipline through long-term offtake contracts while buffering pharmaceutical-grade premiums against turmeric feedstock volatility. Their concentrated ownership structures enable rapid capacity reallocation between research-grade spot sales and cosmetics contract manufacturing, tightening pricing power at the certified-tier apex while compressing margins for undocumented commodity operators.
Pricing Analysis
Turmeric root cost pass-through from Maharashtra and Karnataka cultivation belts directly governs tetrahydrocurcumin base pricing, with monsoon-driven harvest variability transmitting into quarterly contract renegotiations. Three-tier pricing structure across pharmaceutical, research, and industrial grade levels separates batch-certified material commanding documentation premiums from technical-grade powder sold on spot markets. Pricing pressure stems from enzymatic reduction process maturation lowering synthetic route cost floors. Cosmetics formulators in Seoul exhibit highest price sensitivity, while Boston-area pharmaceutical contract manufacturers prioritize supply security over unit cost minimization.
Supply Chain Analysis
REACH registration and MFDS cosmetic raw material qualification gating filter supplier access, concentrating viable production among Hangzhou, Shanghai, and Busan-Ulsan chemical clusters with validated quality management systems. Catalytic hydrogenation operations draw from turmeric curcuminoid isolates, palladium catalyst feedstocks, and solvent recovery infrastructure. Single-source vulnerability concentrates in Zhejiang province chemical parks where 60% of global hydrogenation capacity resides. Distribution runs through Sigma-Aldrich life science channels for research-grade material and direct procurement contracts for pharmaceutical-grade batches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tetrahydrocurcumin reagent market reads as a late-cycle quality story, with South Korean cosmetics houses shifting procurement toward pharmaceutical-grade specifications requiring full chain-of-custody documentation. This specification elevation rewards certified incumbents while accelerating exclusion of commodity operators.
For Market Incumbents: Deepen backward integration into curcumin feedstock cultivation or fermentation-derived precursor supply to insulate margin structures from Indian monsoon volatility. Expand fixed-bed catalytic system capacity in Busan-Ulsan zones to capture MFDS-qualification demand from Seoul-based formulators consolidating vendor panels. Prioritize ECHA dossier maintenance against REACH annex revision timelines that threaten commodity-tier competitors. For New Entrants and Emerging Players: Begin with liquid reagent format specialization targeting automated high-throughput screening workflows in Greater Boston pharmaceutical corridors, where incumbent powder-dominant supply chains show format friction. Penetrate natural-labeled positioning through enzymatic reduction technology licensing, exploiting clean-beauty certification ambiguity around catalytic hydrogenation provenance. Pursue direct technical sales to mid-tier contract manufacturers excluded from multinational vendor panels. For Investors and Strategic Acquirers: Valuations sit cheapest among Zhejiang-based manufacturers with pharmaceutical-grade certification gaps but intact hydrogenation assets, offering retrofit optionality. Long-term viability favors operators with dual-route capability across catalytic and biocatalytic process platforms. Watch ECHA substance evaluation workload clearance rates as inflection signal for registration timeline compression and demand consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Curcumin Feedstock | Cultivation partnerships in Maharashtra reduce monsoon exposure and secure pharmaceutical-grade origin claims. |
| Enzymatic Reduction Technology Licensing | Biocatalytic routes from Danish enzyme suppliers unlock natural-label positioning in clean-beauty channels. |
| Fixed-Bed Catalytic System Retrofit | Continuous-flow reactor installation satisfies ECHA process analytical technology documentation requirements. |
| Long-term Supply Agreement with Seoul Formulators | Locked purity certificates from Busan-Ulsan production insulate against vendor panel consolidation pressure. |
| Joint Venture in Fermentation-Derived Precursors | Microbial biosynthesis partnerships eliminate agricultural feedstock dependency for premium nutraceutical positioning. |
Research Methodology
Multiple input streams — procurement director interviews at South Korean cosmetics houses, regulatory affairs consultations with ECHA registration specialists, and trade flow analysis from Zhejiang customs districts — were reconciled against secondary validation. Primary discussions engaged plant managers at Hangzhou chemical parks, pharmaceutical analytical development leads in New Jersey, and distribution channel partners serving life science research accounts. Secondary sources encompassed FDA Voluntary Cosmetic Registration Program filings, NMPA cosmetic raw material GB standard updates, and SEC 10-K disclosures from diversified chemical conglomerates. Bottom-up volume estimates from hydrogenation capacity utilization rates were cross-checked against top-down demand aggregation from cosmetics formulation procurement data.
Historical capacity expansion patterns were cross-referenced against panel input from contract manufacturing procurement heads to anchor projection assumptions across the analysis window. Segmentation modeling incorporated grade tier, end-use industry, form factor, and regional regulatory cluster dimensions. CAGRs were derived from slope analysis of specification-driven sourcing contract growth rates and automation penetration in pharmaceutical discovery workflows. Forecast inputs included enzymatic reduction technology maturation curves and MFDS raw material approval pathway velocity.
Caveats apply where REACH annex revision scope, Indian monsoon severity, or fermentation-derived precursor cost parity could materially shift the outlook. Forecasts reflect assumptions about certification retention rates and cosmetics formulator vendor panel consolidation trajectories. A model refresh is warranted upon material change in ECHA substance evaluation clearance timelines or Zhejiang environmental enforcement intensity affecting hydrogenation capacity availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Acetoacetanilide Market
Chemical Intermediates
Enzyme Substrates Market
Chemical Intermediates
Thioesters Market
Chemical Intermediates
Myristoyl Chloride Market
Chemical Intermediates
2-Acetylthiophene Market
Chemical Intermediates
US Acids Market
Chemical Intermediates
Potassium Benzoate Market
Chemical Intermediates
Palmitoyl Chloride Market
Chemical Intermediates
Grignard Reagents Market
Chemical Intermediates
Nickel Acetate Market
Chemical Intermediates
Polyamide Intermediate Chemicals Market
Chemical Intermediates
Ethylene Urea Market
Chemical Intermediates
Penicillin Intermediate Market
Chemical Intermediates
Chemical Synthesizer Market
Chemical Intermediates
Metaphenoxy Benzaldehyde (MPBD) Market
Chemical Intermediates
Nutrition Chemicals Market