
 9-Decanoic Acid Methyl Ester Market | 2026-2036
9-Decanoic Acid Methyl Ester Market Size, Share, and Industry Trends Forecast 2026-2036
9-Decanoic Acid Methyl Ester Market Analysis
ISO 9001 certification is rotating as the baseline qualification for 9-decanoic acid methyl ester suppliers serving pharmaceutical and food-grade buyers. BASF SE leverages its integrated oleochemical platform to sustain feedstock security across European production sites. Cayman Chemical specializes in high-purity reference standards for analytical laboratories. Emery Oleochemicals anchors its position through backward integration into palm kernel oil supply chains.
9-Decanoic acid methyl ester is a fatty acid methyl ester derived from capric acid, characterized by a C10 carbon chain and methyl ester functional group, produced via transesterification of decanoic acid with methanol or direct esterification using acid catalysts. The compound serves as a precursor in surfactant synthesis, a fragrance carrier in cosmetic formulations, and a calibration standard in chromatographic analysis. Pharmaceutical Grade product type commands premium positioning due to stringent purity thresholds and batch documentation requirements. Surfactant application segments lead volume consumption in industrial channels. Biofuel application represents an emerging demand vector as renewable diesel specifications incorporate medium-chain esters.
REACH registration obligations under ECHA govern chemical substance market access across Europe, while FDA food additive regulations shape qualification pathways for U.S. food-grade supply. BIS certification requirements in India create additional compliance layers for exporters targeting specialty chemical manufacturing customers. Stakeholders must monitor evolving purity standards from pharmacopeial authorities and renewable fuel certification bodies to align product specifications with downstream qualification protocols.
Market Dynamics
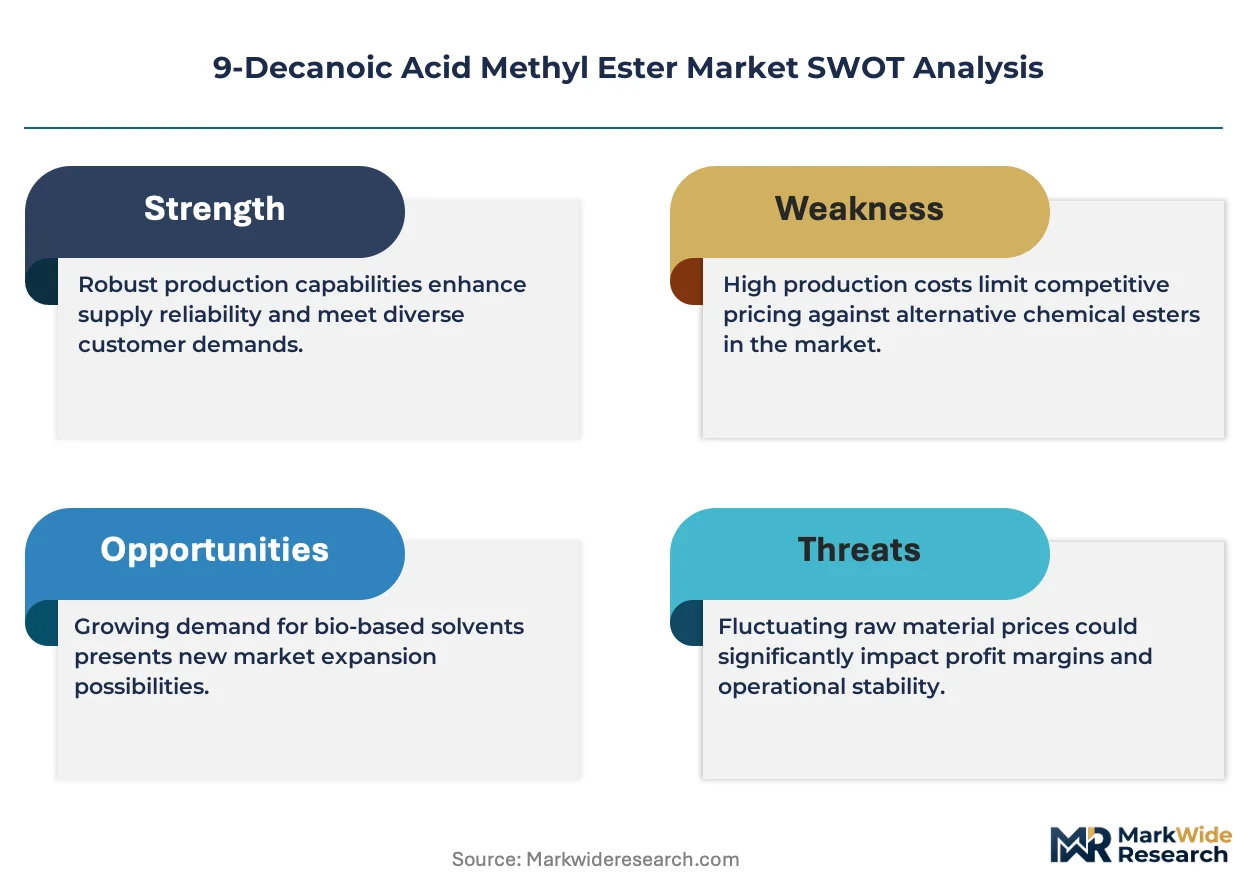
Pharmaceutical formulation standards are tightening purity thresholds for 9-decanoic acid methyl ester, forcing suppliers to invest in dedicated production lines and batch documentation systems that exceed general industrial chemical requirements.
Growth Catalysts
- REACH Registration Mandates:ECHA compliance requirements are filtering out non-registered suppliers across Europe, consolidating qualified vendor pools for pharmaceutical-grade buyers seeking reliable documentation trails.
- Renewable Diesel Blending Specifications:Medium-chain fatty acid methyl esters are gaining inclusion in biofuel certification protocols, opening industrial offtake channels beyond traditional surfactant applications.
- Germany's Specialty Chemical Corridor:Concentrated demand from Rhineland-Palatinate and North Rhine-Westphalia pharmaceutical clusters is sustaining premium pricing for GMP-certified production.
Market Restraints
- Palm Kernel Oil Price Volatility:Feedstock costs for integrated producers fluctuate with Malaysian and Indonesian export duties, compressing margin predictability for backward-integrated suppliers.
- Transesterification Energy Intensity:Methanol recovery and acid catalyst neutralization steps impose fixed thermal costs that disadvantage smaller batch producers against continuous-flow operations.
- Pharmaceutical Grade Documentation Burden:Pharmacopeial compliance with USP-NF and EP monographs requires dedicated quality systems that general chemical manufacturers cannot easily replicate.
Strategic Opportunities
- Indian BIS Certification Gap:Domestic specialty chemical manufacturers face import dependency for high-purity reference standards, creating qualification pathways for exporters meeting CDSCO-aligned purity protocols.
- Chromatographic Standard Expansion:Analytical laboratory demand for C10 chain-length internal standards is extending beyond pharmaceutical QC into environmental testing and food safety screening.
- EU Green Deal Bio-Based Mandates:Renewable content thresholds in surfactant formulations are favoring plant-derived methyl esters over petrochemical alternatives in institutional cleaning product specifications.
Industry Challenges
- GMP Auditor Shortage:Qualified inspectors for pharmaceutical-grade fatty acid ester facilities are concentrated in Germany and Switzerland, creating certification bottlenecks for new market entrants.
- Batch-to-Batch Consistency:Minor variations in C10 chain length distribution affect chromatographic calibration validity, requiring tighter process control than general industrial ester production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 9-Decanoic Acid Methyl Ester Market |
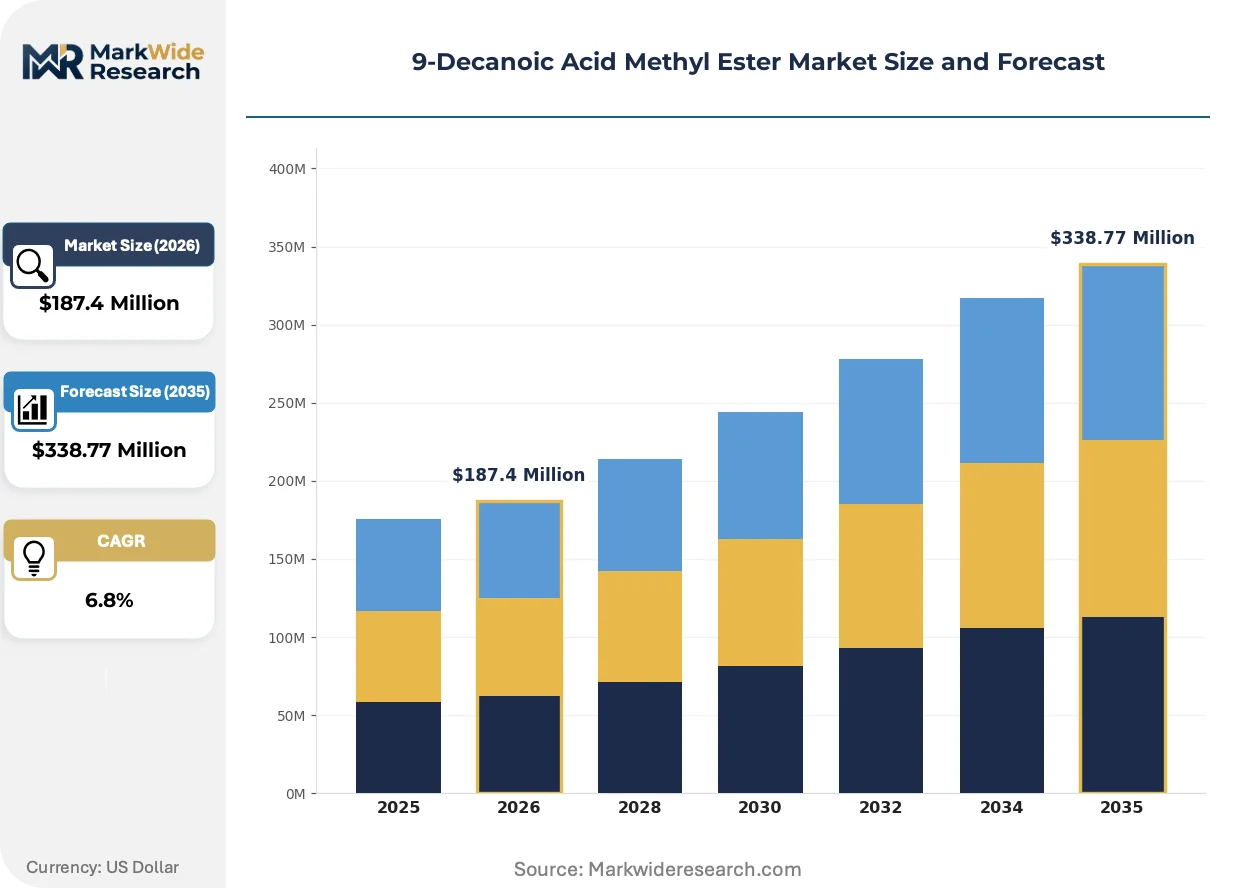
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Pharmaceutical Grade, Cosmetic Grade Application: Food Additive, Biofuel, Surfactant, Lubricant End User: Food Industry, Chemical Manufacturing, Cosmetics, Pharmaceuticals Distribution Channel: Online Sales, Retail Outlets, Wholesale, Direct Sales |
| Companies Covered | BASF SE, Thermo Fisher Scientific, Cayman Chemical, Merck & Co., Inc., Tokyo Chemical Industry Co., Ltd., LGC Limited, Sigma-Aldrich, Procter & Gamble, Emery Oleochemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
9-Decanoic Acid Methyl Ester Market Emerging Trajectories
Continuous processing technologies and regulatory data integrity requirements are splitting the supplier base into pharmaceutical-dedicated specialists and flexible industrial chemical producers serving multiple end-uses.
Membrane-assisted reactive distillation is bifurcating the production landscape between legacy batch transesterification units and continuous-flow systems. Pharmaceutical contract manufacturers in Basel and Frankfurt are specifying continuous-process material to reduce batch variability risks. This technology compression is marginalizing smaller batch operators unable to justify capital conversion costs.
EMA's revised excipient guideline on elemental impurities is forcing methyl ester suppliers to implement ICP-MS screening for catalyst residues. Industrial surfactant producers face documentation requests previously limited to active pharmaceutical ingredient contexts. German and Swiss pharmaceutical formulators are now auditing ester suppliers for complete supply chain impurity mapping.
Consolidated procurement by multinational fragrance houses is displacing spot-market purchasing for cosmetic-grade methyl esters. Givaudan and Firmenich are negotiating multi-year supply agreements with defined purity corridors and volume flexibility clauses. This contracting pattern is most visible in Paris and Geneva, where cosmetic formulation R&D clusters concentrate purchasing influence.
9-Decanoic Acid Methyl Ester Market Segmentation
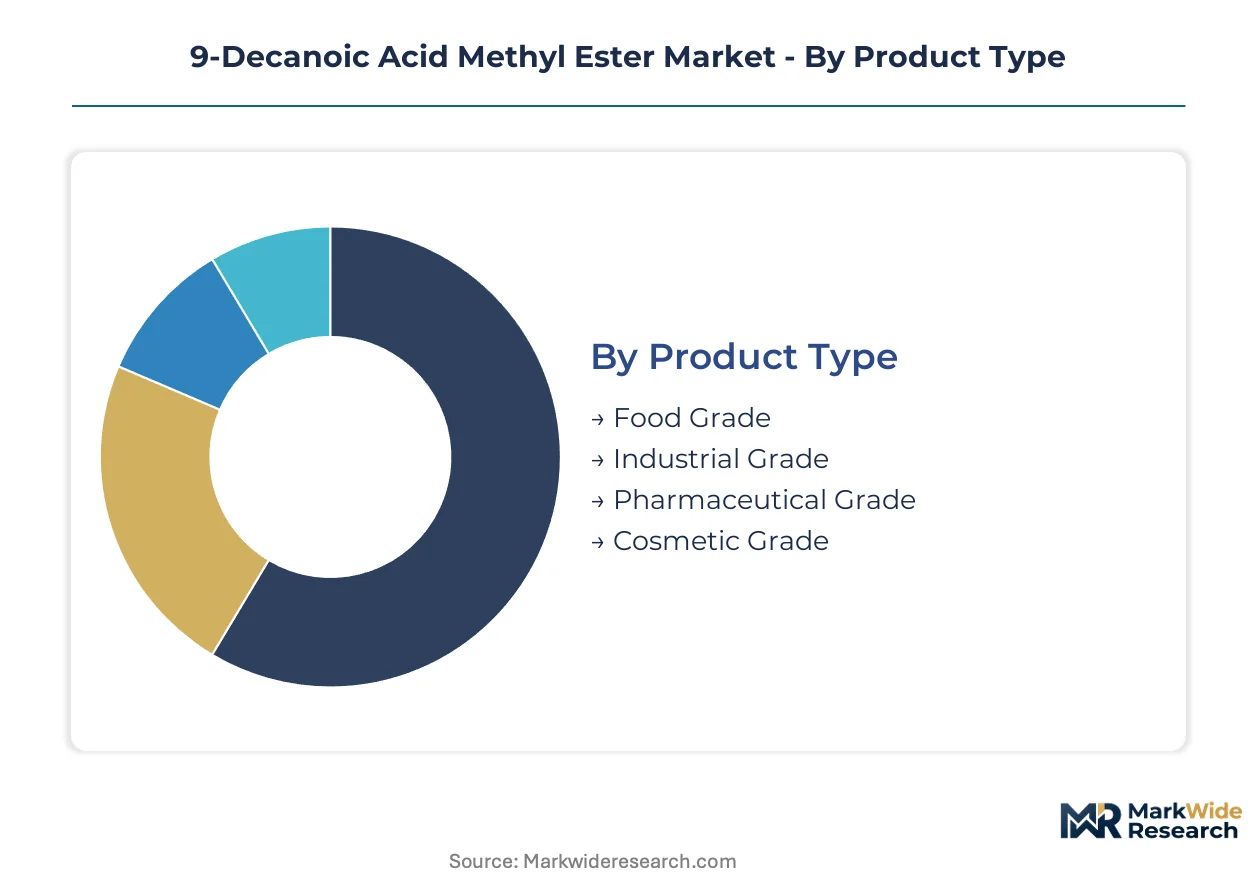
9-Decanoic acid methyl ester suppliers face divergent purity requirements across end-use channels. Pharmaceutical and food-grade buyers enforce certification barriers that industrial surfactant customers rarely demand. Segmentation discipline separates margin-rich specialty grades from commoditized industrial volumes.
Product Type:
Petrochemical-derived C10 esters exert substitution pressure on plant-based grades in industrial surfactant formulations, compressing pricing power for non-certified producers.
- Pharmaceutical Grade:Purity thresholds align with USP-NF and EP monographs for excipient use. Batch documentation systems and ICP-MS screening for elemental impurities are mandatory for supply into Basel and Frankfurt pharmaceutical clusters.
- Food Grade:FDA food additive regulations and FSSAI compliance in India govern qualification pathways. Demand concentrates in flavor carrier applications where residual methanol limits determine supplier selection.
- Cosmetic Grade:Fragrance houses specify odor profiles and color stability for personal care formulations.
- Industrial Grade:Surfactant manufacturers prioritize cost position over traceability in institutional cleaning product supply chains.
Industrial Grade retains volume leadership; Pharmaceutical Grade holds the steepest expansion curve.
Application:
Cost tier stratification splits the market between premium-priced reference standards and bulk surfactant intermediates.
- Surfactant:Medium-chain methyl esters function as hydrophobic tails in anionic and non-ionic surfactant synthesis. EU Green Deal bio-based mandates favor plant-derived C10 esters over petrochemical alternatives in institutional cleaning specifications.
- Biofuel:Renewable diesel blending protocols incorporate medium-chain fatty acid methyl esters for cold-flow property modification. Certification under EN 14214 and ASTM D6751 determines market access.
- Food Additive:Flavor and fragrance carriers require FEMA GRAS status or equivalent safety assessments.
- Lubricant:Estolide base stocks and metalworking fluid applications demand oxidative stability testing.
Surfactant applications dominate current offtake; biofuel represents the most rapidly climbing demand vector.
End User:
Customer-type concentration in Germany's specialty chemical corridor shapes regional supply priorities.
- Pharmaceuticals:Contract manufacturers in Rhineland-Palatinate specify GMP-certified production with complete supply chain impurity mapping. EMA excipient guidelines on elemental residues drive ICP-MS screening requirements.
- Chemical Manufacturing:Surfactant producers in North Rhine-Westphalia negotiate multi-year supply agreements with volume flexibility clauses.
- Cosmetics:Paris and Geneva formulation clusters consolidate procurement through Givaudan and Firmenich.
- Food Industry:Flavor houses in Switzerland and the Netherlands specify odor-neutral grades for beverage applications.
Chemical Manufacturing absorbs the largest volume share; Pharmaceuticals generates the highest margin contribution.
Distribution Channel:
Supply chain maturity separates established wholesale networks from emerging direct-to-manufacturer platforms.
- Direct Sales:Pharmaceutical and fragrance houses negotiate frame contracts with defined purity corridors. Technical service integration and audit access justify premium positioning over intermediated channels.
- Wholesale:Industrial surfactant producers rely on regional chemical distributors for inventory management and just-in-time delivery.
- Online Sales:Reference standard suppliers list catalog items through Cayman Chemical and similar specialty chemical portals.
- Retail Outlets:Limited to small-volume cosmetic ingredient sales through specialty chemical retailers.
Direct Sales commands the highest value concentration; Online Sales is gaining share fastest in analytical standard segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH registration mandates under ECHA are filtering supplier pools across Europe, while renewable diesel blending specifications in North America and BIS certification requirements in India create divergent qualification pathways for 9-decanoic acid methyl ester producers.
Germany
Pharmaceutical contract manufacturers in Rhineland-Palatinate and North Rhine-Westphalia sustain premium demand for GMP-certified production. EMA's revised excipient guidelines on elemental impurities force ICP-MS screening adoption. Frankfurt and Basel-area formulators now audit suppliers for complete supply chain impurity mapping.
United States
FDA food additive regulations shape qualification pathways for flavor carrier applications, with FEMA GRAS status determining supplier selection. Renewable diesel blending protocols under ASTM D6751 incorporate medium-chain esters for cold-flow modification. Gulf Coast biofuel producers are negotiating industrial offtake agreements with defined purity corridors.
India
BIS certification requirements create compliance layers for exporters targeting specialty chemical manufacturing customers. CDSCO-aligned purity protocols govern reference standard imports for analytical laboratories. Maharashtra and Gujarat-based domestic manufacturers face import dependency for high-purity grades, opening qualification pathways for certified exporters.
Switzerland
Swissmedic oversight of pharmaceutical excipients sustains demand for batch-documented production. Fragrance houses in Geneva consolidate procurement through multi-year supply agreements with volume flexibility clauses. Basel pharmaceutical clusters specify continuous-process material to reduce batch variability risks in chromatographic calibration applications.
China
GB standards and SAMR oversight govern food-grade methyl ester specifications for flavor and fragrance applications. NMPA registration requirements for pharmaceutical excipients are tightening documentation expectations. Yangtze River Delta surfactant manufacturers prioritize cost position in institutional cleaning product supply chains.
9-Decanoic Acid Methyl Ester Market Vendor Landscape
Player mix skews toward integrated oleochemical majors and high-purity reference standard specialists. The supplier base concentrates around three strategic archetypes: backward-integrated palm kernel oil processors, pharmaceutical-grade contract manufacturers, and catalog-based analytical chemical distributors. Competitive moves center on capacity rationalization for continuous-flow transesterification systems and strategic partnerships with fragrance houses for multi-year supply agreements.
Within the integrated oleochemical tier, BASF SE and Emery Oleochemicals exemplify upstream control over feedstock security. Cayman Chemical occupies a position among high-purity reference standard specialists serving analytical laboratories. These three anchors represent divergent capability sets: integrated production platforms, captive palm kernel oil supply chains, and chromatographic-grade purification expertise.
| Leading Market Players |
|---|
| BASF SE |
| Thermo Fisher Scientific |
| Cayman Chemical |
| Merck & Co., Inc. |
| Tokyo Chemical Industry Co., Ltd. |
| LGC Limited |
| Sigma-Aldrich |
| Procter & Gamble |
| Emery Oleochemicals |
| Others |
Supply Flow & Price Mechanics
Petrochemical-derived C10 ester substitution for plant-based grades in industrial surfactant formulations simultaneously shifts supply geography toward Gulf Coast petrochemical corridors and compresses pricing power for non-certified oleochemical producers serving commodity buyers.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and industrial-grade tiers. Three-tier pricing structure across pharmaceutical, food-grade, and industrial levels reflects documentation burden and purity thresholds. Cost compression in industrial grades is intensifying because petrochemical alternatives undercut plant-based feedstock economics. Surfactant manufacturers exhibit highest price sensitivity, while Basel pharmaceutical formulators accept premiums for GMP-certified batch documentation.
Supply Chain Analysis
Malaysia and Indonesia anchor palm kernel oil feedstock production for integrated methyl ester manufacturers. Downstream processing draws from German Rhineland-Palatinate pharmaceutical clusters and North Rhine-Westphalia surfactant corridors. Single-source vulnerability in Southeast Asian palm kernel supply creates exposure to export duty volatility. Distribution runs through direct frame contracts for pharmaceutical and fragrance houses, with regional chemical distributors serving industrial spot buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical formulation demand cycles favor suppliers with invested GMP infrastructure, positioning this market for recovery as EMA excipient guidelines tighten documentation requirements across European supply chains.
For Market Incumbents: Secure backward integration into palm kernel oil supply chains to defend against Malaysian export duty volatility. Invest in continuous-flow transesterification systems to reduce batch variability risks that Basel pharmaceutical auditors now flag. Capacity rationalization toward GMP-certified production lines captures premium pricing from Frankfurt contract manufacturers. For New Entrants and Emerging Players: BIS certification fast-track for Indian reference standard imports offers the most penetrable entry point, as Maharashtra and Gujarat laboratories face import dependency for high-purity C10 grades. Target CDSCO-aligned purity protocols as the go-to-market angle, leveraging domestic specialty chemical manufacturer demand for analytical laboratory supplies. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed oleochemical processors lacking pharmaceutical-grade certification infrastructure. Long-term viability hinges on conversion capability to EMA-compliant excipient production. Watch ICP-MS screening adoption rates as the inflection indicator for margin compression among general chemical manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Captive palm kernel oil supply insulates margin from Malaysian export duty volatility. |
| Continuous-Flow Technology Conversion | Membrane-assisted reactive distillation reduces batch variability for Basel pharmaceutical auditors. |
| GMP Certification Investment | EMA excipient guidelines on elemental impurities require ICP-MS screening infrastructure. |
| Multi-Year Supply Agreements | Frame contracts with Givaudan and Firmenich lock in volume flexibility for Geneva fragrance clusters. |
| BIS Certification Pathway Development | CDSCO-aligned protocols open qualification for Indian analytical laboratory reference standards. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across pharmaceutical formulation, surfactant manufacturing, and analytical laboratory segments. Primary interviews captured plant managers at integrated oleochemical facilities, procurement leads at fragrance houses, technical R&D directors at surfactant producers, and quality assurance officers at contract manufacturers. Secondary validation drew from ECHA REACH registration databases, FDA food additive filings, SEC 10-K disclosures from listed chemical producers, and customs/trade flow records. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down production capacity assessments.
Across the analysis window, forecasts segmented by product grade tier, end-use industry channel, and regional production hub. CAGRs were derived from elasticity-adjusted demand projections incorporating pharmaceutical formulation growth, renewable diesel blending specification evolution, and surfactant bio-based mandate adoption. Industry-specific inputs included EMA excipient guideline implementation timelines, palm kernel oil price volatility indices, and chromatographic standard expansion rates in environmental testing laboratories.
Decision-makers should treat outputs as directional under base assumptions of sustained REACH compliance costs and stable Malaysian-Indonesian palm kernel export policies; material deviation in either driver would warrant model refresh. Recalibration cycles align with material shifts in pharmacopeial purity standards and renewable fuel certification protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Ph Controlling Agents Market
Chemical Intermediates
Octenylsuccinate Market
Chemical Intermediates
Epoxy Silanes Market
Chemical Intermediates
Organometallic Compounds Market
Chemical Intermediates
Isosafrole Market
Chemical Intermediates
Dental Etching Agents Market
Chemical Intermediates
Duloxetine Intermediate and Atorvastatin Intermediates Market
Chemical Intermediates
Thiochemicals Market
Chemical Intermediates
Molybdenum Disulfide (MoS2) Market
Chemical Intermediates
Ethylene Urea Market
Chemical Intermediates
Dye Intermediates Market
Chemical Intermediates
Phosphate Chemical Reagents Market
Chemical Intermediates
Metal Alkyls Market
Chemical Intermediates
Potential Hydrogen (Ph) Adjusters Market
Chemical Intermediates
Tetrahydrocurcumin Reagent Market
Chemical Intermediates
Natural Chelating Agents Market