
 Global Elderly Care Market | 2026-2036
Global Elderly Care Market Size, Share, and Industry Trends Forecast 2026-2036
Global Elderly Care Market Analysis
CMS Five-Star Quality Rating certification is collapsing as a market gatekeeper, determining which operators qualify for Medicare referrals and preferred placement networks. Brookdale Senior Living dominates the assisted living segment through geographic density across metropolitan clusters. Genesis HealthCare anchors skilled nursing capacity with concentrated post-acute assets in key states. Amedisys leverages home health infrastructure to compete outside institutional settings.
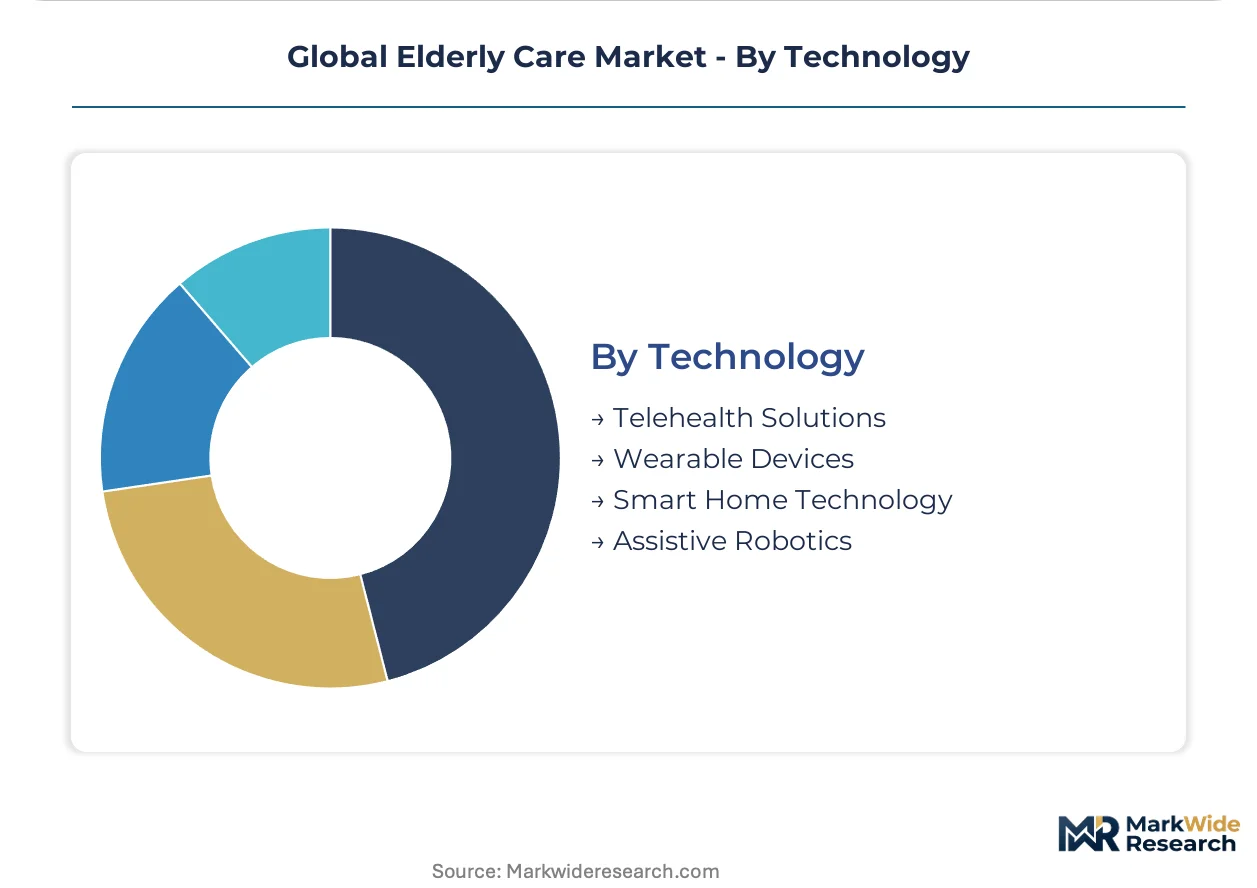
Elderly care encompasses medical, social, and residential services designed to support individuals aged sixty-five and older with activities of daily living, chronic disease management, and mobility assistance, typically delivered through licensed facilities or certified home health agencies operating under clinical supervision protocols. The service type dimension shows nursing care occupying the largest revenue pool while home healthcare represents the fastest structural expansion as reimbursement shifts toward community-based alternatives. Technology segmentation reveals smart home solutions capturing margin concentration through recurring monitoring subscriptions, whereas assistive robotics remains nascent with hardware costs limiting penetration.
FDA oversight shapes medical device standards for therapeutic equipment deployed in residential and clinical settings, while HIPAA compliance mandates data architecture across telehealth and wearable platforms handling protected health information. Japan's METI promotes assistive robotics adoption through targeted standardization, and the EU AI Act imposes risk classification on algorithmic care coordination tools. Stakeholders must monitor how reimbursement parity between institutional and home-based settings evolves across national health systems.
Market Dynamics
The elderly care market is being fundamentally restructured by reimbursement migration toward home-based models, as Medicare Advantage plans and national health systems compress institutional stays and expand remote monitoring coverage.
Growth Catalysts
- Japan METI Robotics Standards:Targeted certification pathways for assistive exoskeletons and mobility aids are accelerating hardware deployment in residential settings.
- EU Green Deal Facility Mandates:Energy retrofit requirements for nursing homes are triggering capital flows into building automation and climate-controlled care environments.
- Home Health Infrastructure:CMS reimbursement parity expansion between skilled nursing facilities and home health agencies is redirecting patient volume toward community-based care.
Market Restraints
- Workforce Supply Concentration:Certified nursing assistant training pipelines in the United States, Germany, and Japan cannot match demographic demand curves.
- Assistive Robotics Hardware Costs:Sensor arrays and actuation systems remain prohibitively expensive for mass residential deployment outside institutional procurement.
- HIPAA Data Architecture Compliance:Telehealth platform interoperability requirements impose multi-year development timelines on wearable and remote monitoring vendors.
Strategic Opportunities
- Rural China Penetration:County-level hospital networks seek turnkey elderly care partnerships to address aging populations in interior provinces.
- AI-IoT Convergence:Predictive fall detection algorithms integrated with ambient sensor networks enable proactive intervention before acute events.
- India PLI Medical Devices:Production-linked incentive schemes for domestic manufacturing of rehabilitation equipment reduce import dependency.
Industry Challenges
- Specialized Geriatric Nursing Shortage:Dementia care certification programs produce insufficient qualified staff relative to Alzheimer's prevalence curves.
- Legacy EHR Integration:Home health agencies struggle to synchronize patient data across fragmented hospital, pharmacy, and insurance databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Elderly Care Market |
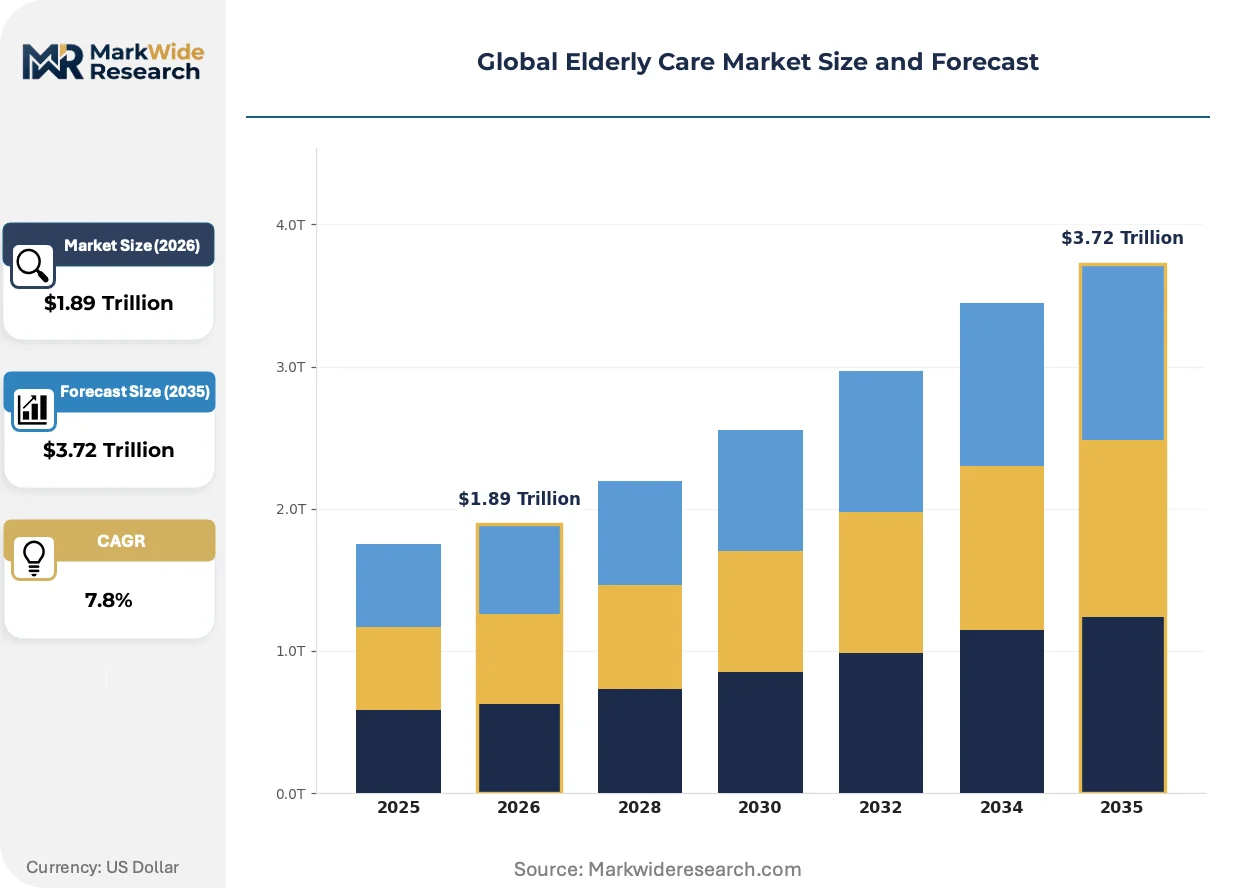
| Market Size in 2026 | $1.89 Trillion |
| Market Size in 2035 | $3.72 Trillion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Home Healthcare, Assisted Living, Nursing Care, Adult Daycare Product Type: Medical Devices, Mobility Aids, Home Modifications, Therapeutic Equipment End User: Individuals, Caregivers, Hospitals, Rehabilitation Centers Technology: Telehealth Solutions, Wearable Devices, Smart Home Technology, Assistive Robotics |
| Companies Covered | Genesis HealthCare, ProMedica Senior Care, Brookdale Senior Living, Extendicare, Five Star Senior Living, Atria Senior Living, Life Care Centers of America, Amedisys, Sunrise Senior Living, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Elderly Care Market Emerging Trajectories
Sensor-embedded wearables and ambient monitoring systems are displacing periodic clinical assessments with continuous data streams, fundamentally altering how chronic conditions are managed outside institutional walls.
Wearable biosensors capable of tracking hydration, gait velocity, and sleep architecture are miniaturizing to patch-scale form factors. Home health agencies in Germany and the Netherlands are deploying these devices across post-acute discharge cohorts. This compression of monitoring hardware is enabling room-scale sensor networks that eliminate patient adherence dependencies.
The EU AI Act risk classification framework is imposing algorithmic transparency requirements on care coordination software. Developers must now document training data provenance and decision logic for predictive triage tools. Skilled nursing operators in France and Italy are delaying procurement cycles until vendor compliance certifications are finalized.
Family caregivers are increasingly demanding unbundled service modules rather than bundled facility contracts. Adult children in the United States and Australia are purchasing standalone medication management, transportation, and companionship services through digital marketplaces. This fragmentation of care procurement is compressing traditional assisted living admission pipelines.
Global Elderly Care Market Segmentation
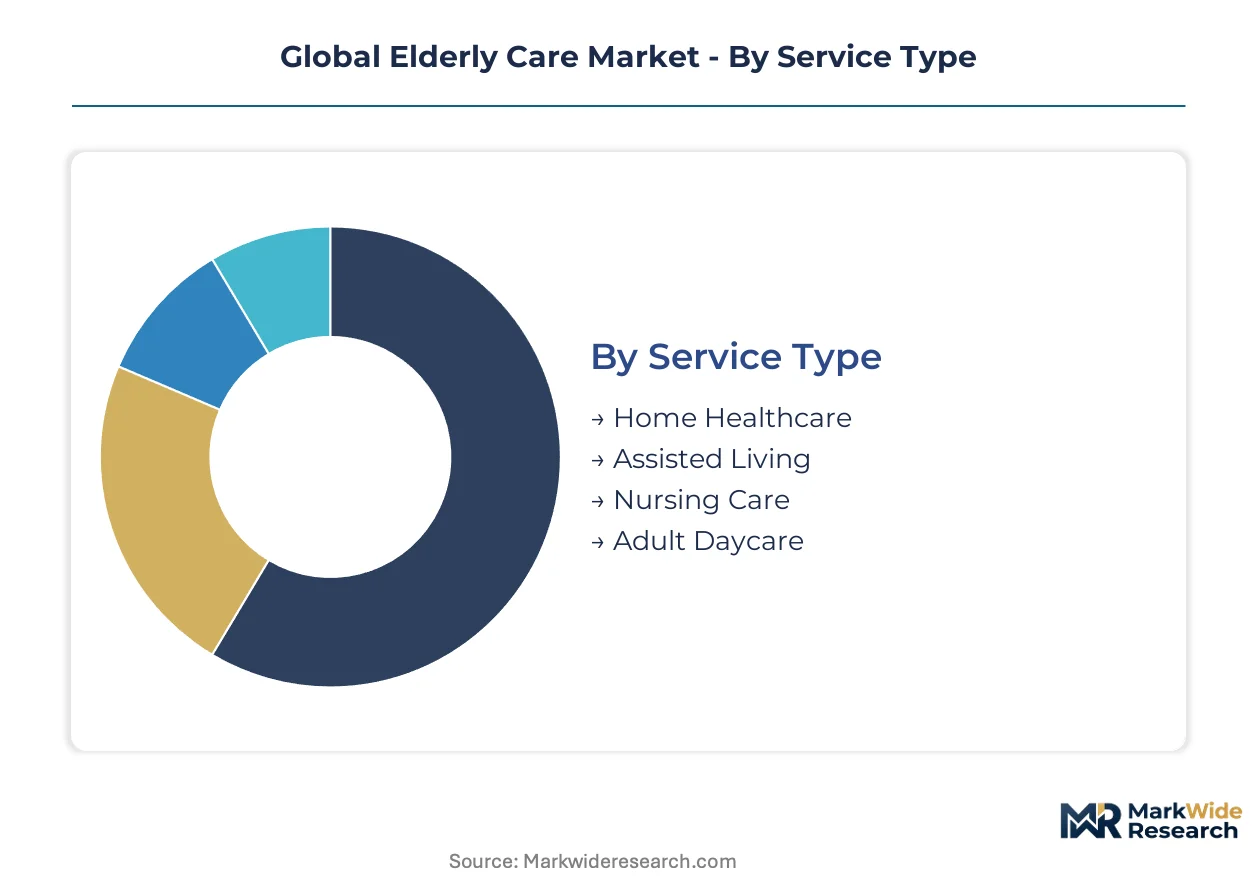
Elderly care market segmentation reveals how regulatory frameworks, reimbursement policies, and technology maturity create divergent growth trajectories across service delivery models. Understanding these divisions exposes where capital deployment and operational investment generate differentiated returns.
Service Type:
FDA facility licensing and CMS reimbursement tiers create distinct operational economics across institutional and community-based care models.
- Nursing Care:Skilled nursing facilities deliver 24-hour medical supervision, wound care, and post-acute rehabilitation under state licensure and federal Medicare certification. Demand concentrates in Florida, Texas, and Ohio where aging demographics intersect with hospital discharge pressure. CMS Five-Star Quality Ratings determine referral volume and preferred network status.
- Home Healthcare:Medicare-certified home health agencies provide skilled nursing, physical therapy, and medical social services in residential settings. Germany and the Netherlands lead adoption as national health systems expand remote monitoring reimbursement. This segment climbs fastest as institutional alternatives face cost containment.
- Assisted Living:Residential facilities offer housing, meals, and personal care assistance without skilled nursing oversight. State-level regulations govern staffing ratios and service scope.
- Adult Daycare:Community-based centers provide daytime supervision, meals, and therapeutic activities for seniors living with family caregivers. Medicaid waiver programs drive access in the United States.
Established volume favors nursing care; emerging adoption favors home healthcare.
Product Type:
Cost stratification separates premium therapeutic equipment from commoditized mobility aids, with reimbursement codes determining procurement concentration.
- Medical Devices:FDA-cleared diagnostic and monitoring equipment includes pulse oximeters, blood pressure monitors, and glucose meters for chronic disease management. Hospital discharge planners and home health agencies in the United States and Japan concentrate procurement through group purchasing organizations.
- Mobility Aids:Wheelchairs, walkers, canes, and transfer devices support independent movement and fall prevention. Medicare Part B durable medical equipment coverage shapes demand volume.
- Home Modifications:Structural adaptations including grab bars, ramps, stairlifts, and bathroom safety equipment enable aging-in-place. Germany's long-term care insurance funds partial retrofit costs.
- Therapeutic Equipment:Physical and occupational therapy devices for strength training, balance improvement, and pain management deploy in rehabilitation centers and residential settings.
Reimbursement density favors medical devices; out-of-pocket growth favors home modifications.
End User:
Decision-making authority fragments across clinical professionals, family caregivers, and institutional procurement committees with divergent evaluation criteria.
- Individuals:Seniors and their families purchase direct-to-consumer products and private-pay services outside insurance networks. Adult children in Australia and the United States drive standalone service procurement through digital marketplaces.
- Caregivers:Family members and paid home health aides utilize assistive technologies and monitoring systems to manage daily care tasks. Japan's METI robotics standards target this user group for exoskeleton deployment.
- Hospitals:Acute care facilities discharge patients to post-acute settings with equipment prescriptions and care coordination mandates.
- Rehabilitation Centers:Skilled nursing and outpatient therapy facilities procure therapeutic equipment and mobility aids for patient functional recovery programs.
Institutional volume favors hospitals; self-directed expansion favors individuals.
Technology:
Regulatory risk classification under the EU AI Act and HIPAA data architecture requirements impose multi-year compliance timelines on algorithmic care tools.
- Smart Home Technology:Ambient sensor networks, automated lighting, and climate control systems monitor activity patterns and environmental safety without wearable adherence. Dutch home health agencies deploy room-scale installations across post-acute cohorts.
- Wearable Devices:Biosensors tracking hydration, gait velocity, sleep architecture, and vital signs miniaturize to patch-scale form factors. FDA 510(k) clearance pathways govern clinical-grade deployment.
- Telehealth Solutions:Video consultation platforms, remote patient monitoring systems, and digital therapeutics connect seniors with clinicians. HIPAA interoperability requirements constrain vendor development cycles.
- Assistive Robotics:Exoskeletons, companion robots, and automated medication dispensers remain hardware-cost constrained outside institutional procurement. Japan METI certification accelerates residential adoption.
Near-term deployment favors smart home technology; long-term transformation favors assistive robotics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach anchors North American supply chains for medical device imports serving California's assisted living corridor. Germany's Rhine-Alpine freight corridor distributes therapeutic equipment across Benelux and into Central Europe. Japan's Shinkansen network enables rapid deployment of assistive robotics from manufacturing clusters in Aichi Prefecture to metropolitan care markets.
United States
Florida, Texas, and Ohio concentrate skilled nursing demand where hospital discharge pressure intersects with retiree migration patterns. CMS Five-Star Quality Ratings determine Medicare referral volume and preferred network placement for facility operators. The Dallas-Fort Worth metroplex anchors post-acute bed expansion as health systems consolidate rehabilitation assets.
Germany
Long-term care insurance funds drive home modification adoption and remote monitoring reimbursement across aging industrial regions. The EU Green Deal mandates energy retrofits for nursing homes, triggering capital deployment into climate-controlled care environments. The Ruhr Valley corridor concentrates facility automation vendors serving Dutch and Belgian cross-border demand.
Japan
Metropolitan Tokyo and Osaka face acute geriatric nursing shortages as Alzheimer's prevalence curves outpace dementia care certification output. METI robotics standards accelerate residential deployment of assistive exoskeletons and mobility aids through targeted certification pathways. Aichi Prefecture manufacturing clusters supply hardware to prefectural care networks under national long-term care insurance.
China
County-level hospital networks in interior provinces seek turnkey elderly care partnerships to address aging demographics outside coastal megacities. The national health commission promotes home-based care models to reduce institutional bed pressure. The Yangtze River Delta concentrates smart home technology vendors serving municipal eldercare procurement in Shanghai and Jiangsu.
Australia
Adult children in Sydney and Melbourne drive standalone service procurement through digital marketplaces, fragmenting traditional assisted living admission pipelines. The national aged care quality and safety commission imposes new transparency requirements on residential providers. Queensland's Gold Coast anchors retirement living development as interstate migration concentrates senior demand.
Global Elderly Care Market Vendor Landscape
Listed leaders compete with private specialists across facility ownership structures, creating tiered competitive dynamics. The market structure concentrates around publicly traded real estate investment trusts and privately held regional operators with divergent capital access. Three archetypes dominate: geographic density players, post-acute specialists, and home health platform operators. Consolidation through portfolio acquisition and vertical integration into care coordination technology represent the primary competitive moves.
Within the facility ownership tier, Genesis HealthCare and Brookdale Senior Living exemplify divergent strategic positioning. Genesis anchors skilled nursing capacity with concentrated post-acute assets in key states, while Brookdale dominates assisted living through metropolitan cluster density. Amedisys occupies a distinct position leveraging home health infrastructure to compete outside institutional settings entirely. These three represent how reimbursement migration toward community-based models fragments competitive terrain across delivery modalities.
| Leading Market Players |
|---|
| Genesis HealthCare |
| ProMedica Senior Care |
| Brookdale Senior Living |
| Extendicare |
| Five Star Senior Living |
| Atria Senior Living |
| Life Care Centers of America |
| Amedisys |
| Sunrise Senior Living |
| Others |
Supply Flow & Price Mechanics
CMS Five-Star Quality Rating certification gates both supply qualification and price differentiation across skilled nursing and home health segments, compressing margins for uncertified operators while enabling premium placement for top-tier facilities. Medicare Advantage plans and national health systems simultaneously drive reimbursement parity toward community-based models, reshaping how procurement committees evaluate total cost of care against institutional alternatives.
Pricing Analysis
Volume-discount tiering structures dominate group purchasing organization contracts for medical devices and therapeutic equipment, with hospital systems and nursing facility chains capturing standard-tier pricing while independent home health agencies absorb premium markups. Price differentiation rests on FDA clearance grade and CMS certification status, with 510(k)-cleared biosensors commanding substantial premiums over wellness-grade alternatives. Cost compression in assistive robotics stems from sensor array and actuation system expenses that limit residential penetration. Family caregivers purchasing standalone services through digital marketplaces exhibit highest price sensitivity; institutional procurement committees anchored to reimbursement codes demonstrate lowest.
Supply Chain Analysis
Inventory lead times for FDA-cleared medical devices extend through multi-quarter certification cycles, forcing home health agencies to buffer stock against discharge planning surges. Manufacturing concentrates in China for consumer-grade wearables, Germany for therapeutic equipment, and Japan for assistive robotics hardware. Component dependencies span semiconductor chips for sensor arrays, lithium-ion cells for portable devices, and precision actuators for mobility aids. Single-source vulnerability concentrates in Aichi Prefecture exoskeleton suppliers serving Japanese care networks under METI standards. Distribution runs through hospital discharge planners, GPO contracts, and direct-to-consumer digital marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Elderly care markets are approaching a platform-economics inflection as HIPAA-compliant data architectures and AI-IoT sensor networks demand interoperability standards that reshape competitive moats around ecosystem control rather than facility assets alone.
For Market Incumbents: Secure CMS Five-Star Quality Rating density across metropolitan clusters to defend referral volume against Medicare Advantage network exclusions. Acquire home health agencies with established remote monitoring infrastructure to capture reimbursement migration toward community-based models, countering pure-play telehealth entrants.
For New Entrants and Emerging Players: Lead with AI-IoT convergence platforms targeting rural China county-level hospital partnerships where turnkey elderly care solutions face minimal incumbent saturation. Penetrate Germany's long-term care insurance-funded home modification segment through certified smart home installations. Deploy direct-to-consumer digital marketplaces for unbundled caregiver services in Australia and the United States.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across home health technology platforms as software margins displace facility-heavy skilled nursing economics. Prioritize acquisition targets with HIPAA-compliant data architectures and established Medicare certification. Monitor EU AI Act algorithmic transparency compliance timelines as inflection indicator for care coordination software vendor viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | CMS certification pathways determine Medicare Advantage network placement and referral volume concentration. |
| Platform Integration | HIPAA-compliant data architectures enable ecosystem control across fragmented EHR and pharmacy databases. |
| CE Marking Pathway | EU AI Act risk classification gates algorithmic care coordination tools across French and Italian procurement. |
| Hospital System Partnership | Discharge planner relationships anchor post-acute patient volume for skilled nursing and home health operators. |
| Software Companion Development | FDA 510(k) clearance for predictive fall detection algorithms differentiates ambient sensor network offerings. |
Methodological Framework
Operator-level perspectives from skilled nursing facility administrators, home health agency directors, hospital discharge planners, and Medicare Advantage network managers anchored the qualitative base. These primary insights combined with secondary validation from CMS Medicare data, FDA 510(k) clearance databases, EU MDR submission records, and national health commission procurement disclosures. Bottom-up facility capacity and utilization modeling triangulated against top-down reimbursement flow analysis across the analysis window.
Sensitivity analysis tested forecast robustness against CMS reimbursement parity expansion velocity, EU Green Deal facility retrofit compliance timelines, and Japan METI robotics certification adoption curves. Segmentation dimensions modeled include service type, product category, end-user decision authority, and technology maturity tier alongside geographic regulatory cluster. CAGRs derived from logistic diffusion curves for technology adoption and demographic demand projections. Industry-specific inputs encompassed Alzheimer's prevalence trajectories and certified nursing assistant training pipeline outputs.
The analysis sits within stated boundaries; outcomes outside maintained CMS reimbursement structures, EU regulatory enforcement intensity, or Japan long-term care insurance funding levels would require recalibration. Forecasts reflect documented assumptions regarding technology cost reduction curves and workforce supply elasticity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
US Home Infusion Therapy Market
Home Healthcare
Senior in-Home Care Services Market
Home Healthcare
Global Home Healthcare Software Market
Home Healthcare
Germany Home Healthcare Market
Home Healthcare
Elderly Care Apps Market
Home Healthcare
UK Home Healthcare Market
Home Healthcare
Virtual Companion Care Market
Home Healthcare
Elder Care Subscription Market
Home Healthcare
Adult Day Care Market
Home Healthcare
Europe Home Care Market
Home Healthcare
Global Home Infusion Therapy Market
Home Healthcare
Smart Pillow Market
Home Healthcare
Global Ambient Assisted Living (AAL) Market
Home Healthcare
Outpatient Home Therapy Market
Home Healthcare
US Home Healthcare Market
Home Healthcare
Global Nursing Care Market