
 Taiwan Motor Insurance Market | 2026-2036
Taiwan Motor Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Motor Insurance Market Analytics
ISO 9001 quality management certification is bifurcating the competitive landscape between established underwriters and newer digital entrants. Cathay Life Insurance leverages its extensive agency network to sustain dominance in personal auto lines. Fubon Insurance anchors its position through bancassurance integration with its banking parent. Shin Kong Insurance competes aggressively on motorcycle coverage, a high-volume segment in Taiwan's dense urban mobility market.
Motor insurance constitutes a contractual risk-transfer mechanism indemnifying vehicle owners against collision, theft, liability, and property damage losses, with premiums calibrated through actuarial modeling of claims frequency and severity against insured vehicle value and driver risk profiles. The policy type dimension shows comprehensive coverage commanding the largest premium pool while third-party liability remains mandatory under Taiwan's Compulsory Automobile Liability Insurance Act. Within premium structures, usage-based and pay-as-you-drive models are gaining traction fastest among younger drivers in Taipei and Taichung, though fixed premium products still occupy the bulk of in-force policies.
The Financial Supervisory Commission enforces risk-based capital standards that constrain smaller insurers' capacity to underwrite commercial fleets, while the Compulsory Automobile Liability Insurance Act mandates minimum third-party coverage for all registered vehicles. Taiwan's Insurance Bureau periodically adjusts reserve requirements following catastrophe loss experience, directly compressing or expanding underwriting capacity available for comprehensive coverage expansion. Stakeholders must monitor telematics data portability rules and the central bank's interest rate trajectory, as investment income volatility increasingly determines whether insurers can absorb rising EV repair cost inflation without accelerating premium rate filings.
Market Dynamics
The Financial Supervisory Commission's risk-based capital requirements are compressing underwriting capacity for smaller insurers while telematics adoption accelerates pricing granularity across personal and commercial lines.
Growth Catalysts
- Fleet Digitization Mandates:Logistics operators across Taoyuan and Taichung are expanding coverage mandates for commercial vehicles, pulling comprehensive policies into long-term fleet contracts.
- Compulsory Automobile Liability Insurance Act:Taiwan's mandatory third-party coverage ensures a baseline premium pool that stabilizes revenue for underwriters across all vehicle classes.
- Telematics Integration:Usage-based insurance platforms are capturing granular driving behavior data, enabling dynamic pricing models that attract younger drivers in metropolitan corridors.
Market Restraints
- EV Repair Cost Inflation:Battery pack replacement costs and specialized labor requirements are compressing loss ratios for comprehensive coverage underwriters.
- Agency Concentration:Distribution remains anchored by established agency networks in Greater Taipei, limiting direct-to-consumer channel penetration for digital entrants.
- Interest Rate Volatility:The central bank's monetary policy trajectory creates investment income uncertainty that constrains pricing flexibility for long-tail liability reserves.
Strategic Opportunities
- Central Taiwan Corridor:Taichung's expanding automotive manufacturing cluster presents underpenetrated commercial fleet coverage demand from parts suppliers and logistics subcontractors.
- Telematics-AI Convergence:Real-time collision prediction algorithms integrated with pay-as-you-drive platforms can reduce claims frequency while deepening customer data assets.
- Bancassurance Expansion:Banking parent relationships offer captive distribution channels for bundled auto-loan insurance products targeting first-time vehicle buyers.
Industry Challenges
- Actuarial Talent Scarcity:Shortages of professionals skilled in telematics data modeling and EV risk assessment are delaying product development cycles.
- Legacy System Integration:Core policy administration platforms require costly reconfiguration to support real-time data ingestion from connected vehicle APIs.
- ISO 9001 Certification Burden:Quality management compliance timelines stretch 18-24 months, creating competitive lag for newer market entrants against established underwriters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Motor Insurance Market |
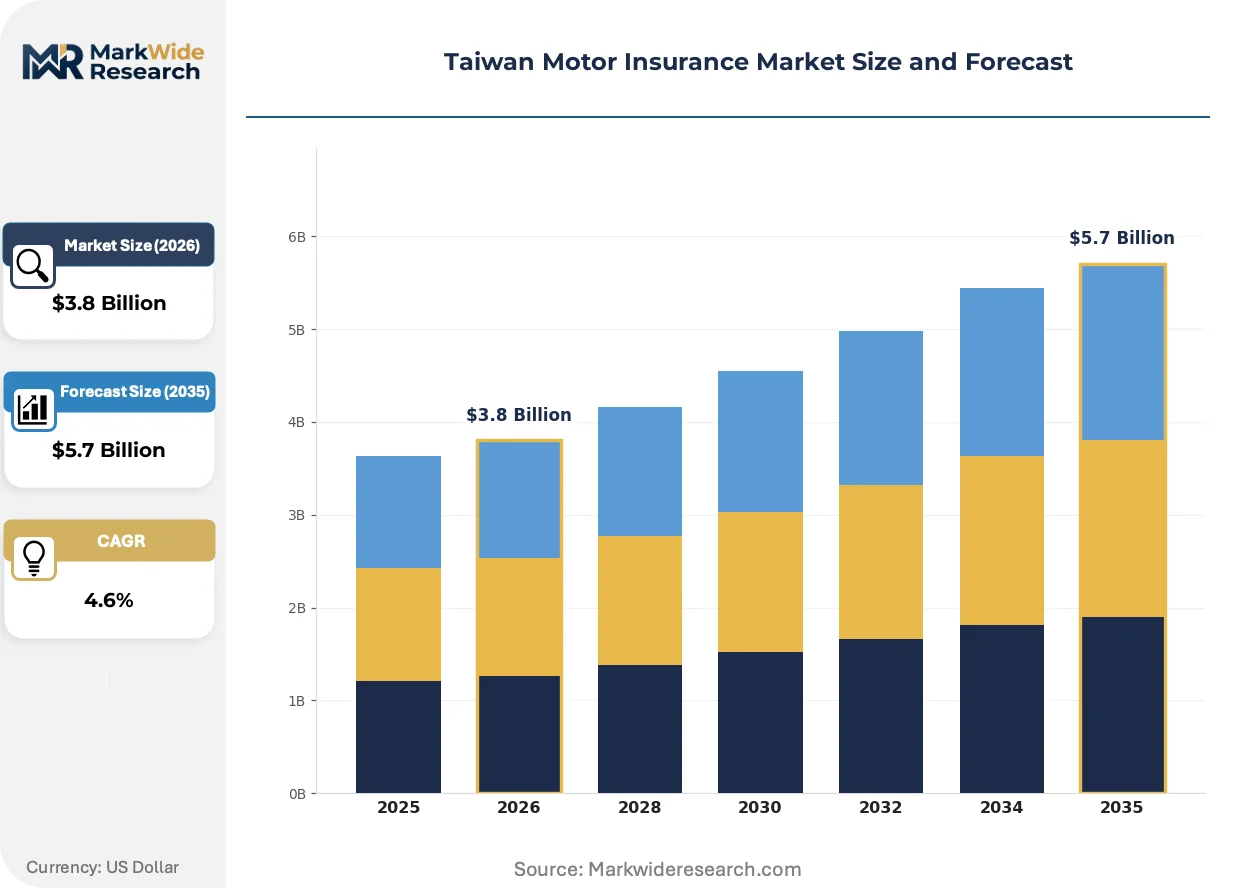
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Comprehensive, Third Party, Third Party Fire and Theft, Liability Premium Structure: Fixed Premium, Variable Premium, Pay-As-You-Drive, Usage-Based Insured Vehicle Type: Passenger Cars, Motorcycles, Commercial Vehicles, Electric Vehicles Customer Segment: Individuals, Corporations, Fleet Owners, Online Buyers |
| Companies Covered | Cathay Life Insurance, Nan Shan Life Insurance, Taipei Insurance, Taiwan Fire & Marine Insurance, Shin Kong Insurance, Fubon Insurance, China Trust Life Insurance, Hotai Insurance, Chung Kuo Insurance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Motor Insurance Market Evolving Landscape
Telematics-enabled pricing models and embedded insurance architectures are restructuring how coverage is distributed, priced, and consumed across Taiwan's vehicle ownership base.
Onboard diagnostic dongles and smartphone-based telematics applications are capturing granular driving behavior data including hard braking frequency, cornering aggression, and time-of-day exposure. Younger drivers in Taipei and Kaohsiung are adopting these platforms fastest, accepting privacy trade-offs for premium discounts. This sensor infrastructure is miniaturizing the traditional annual policy renewal cycle into continuous, adjustable coverage periods.
The Financial Supervisory Commission's risk-based capital framework tightens solvency standards quarterly, forcing smaller insurers to shed commercial fleet exposure or raise additional equity. Mid-tier underwriters are responding by ceding more risk to reinsurance partners or exiting high-severity comprehensive lines entirely. Northern Taiwan's Greater Taipei corridor, with its concentration of high-value vehicles, faces the sharpest premium rate adjustments.
Fleet procurement managers are consolidating insurance purchasing across vehicle classes, demanding multi-year contracts with embedded maintenance and telematics services. Traditional agency intermediaries in Tainan and Hsinchu are losing share to direct insurer relationships and banking channel integration. This concentration is most visible among electronics manufacturers operating just-in-time logistics networks across western Taiwan's industrial zones.
Taiwan Motor Insurance Market Segmentation
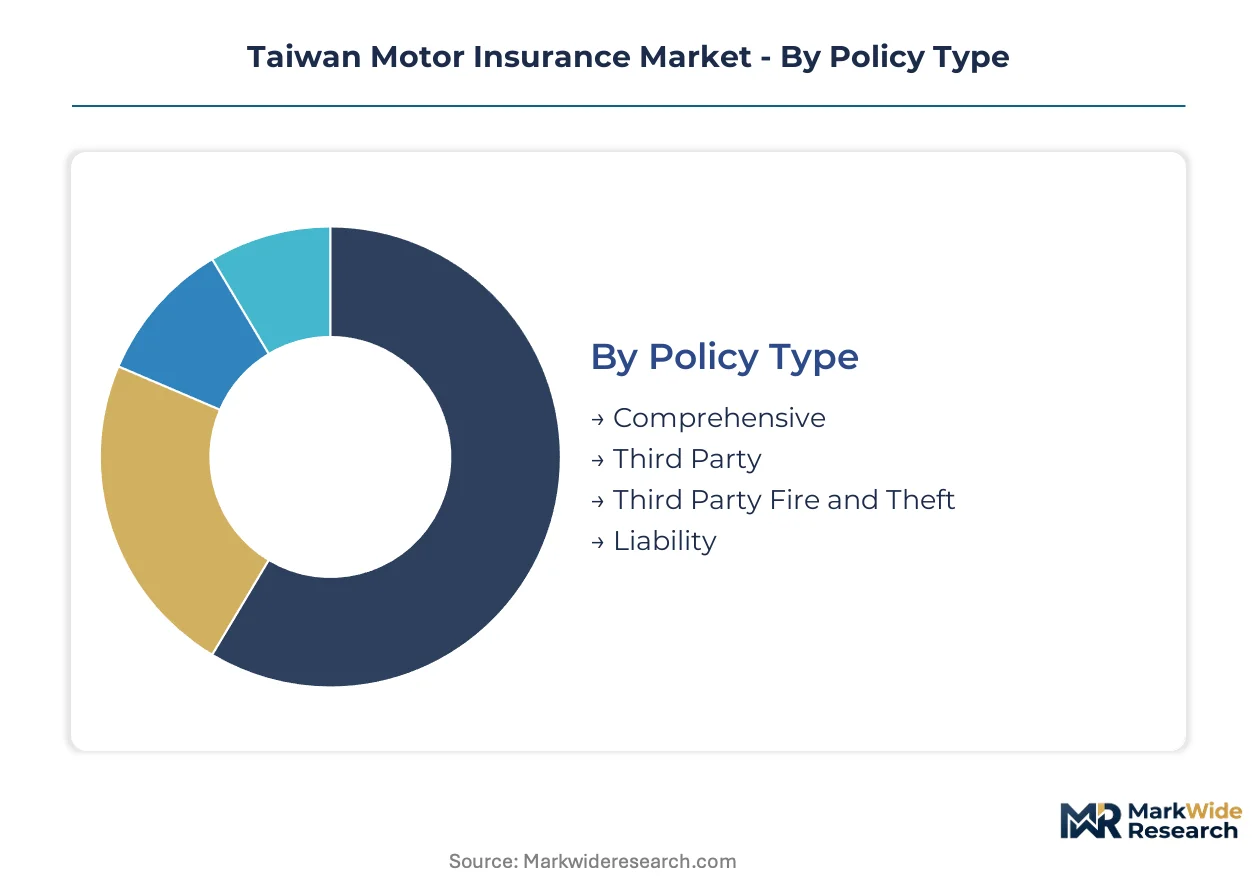
Taiwan's motor insurance market fragments across four critical dimensions that determine pricing mechanics, distribution channels, and risk pooling. Policy architecture and premium structures interact with vehicle electrification trends and fleet digitization mandates to reshape competitive positioning.
Policy Type:
Geographic concentration varies sharply across policy categories, with mandatory coverage penetrating rural counties while comprehensive products cluster in Greater Taipei's high-value vehicle corridors.
- Comprehensive:Full-spectrum coverage indemnifying collision, theft, natural disaster, and third-party liability losses through single-policy architecture. Demand concentrates heavily in northern Taiwan's Greater Taipei metropolitan corridor where high-value vehicles dominate registration data. The Financial Supervisory Commission's risk-based capital requirements compress underwriting capacity for this capital-intensive line.
- Third Party:Mandatory baseline coverage per Taiwan's Compulsory Automobile Liability Insurance Act, creating universal penetration across all 22 counties and cities. This segment stabilizes revenue pools for underwriters but offers minimal margin expansion potential.
- Third Party Fire and Theft:Intermediate coverage tier protecting against named perils beyond baseline liability. Penetration runs highest in Taichung's automotive manufacturing zones where commercial fleet operators seek cost-optimized protection.
- Liability:Legal obligation coverage for bodily injury and property damage to third parties. Kaohsiung's port logistics corridor generates concentrated demand from heavy commercial vehicle operators facing elevated exposure.
Comprehensive commands the established base. The steepest expansion runs through Third Party Fire and Theft as fleet operators optimize coverage tiers.
Premium Structure:
Cost tier differentiation separates legacy fixed-rate products from emerging dynamic pricing models, with technology infrastructure investments determining competitive access.
- Fixed Premium:Traditional annual rate structures calibrated through historical actuarial tables without behavioral adjustment. Established agency networks in Tainan and Hsinchu retain dominant distribution share for this mature category.
- Variable Premium:Rate adjustments tied to named risk factors including driver age, vehicle class, and territorial rating zones. Taoyuan's logistics hub generates concentrated commercial fleet demand for this flexible structure.
- Pay-As-You-Drive:Mileage-calibrated pricing capturing actual vehicle utilization through odometer verification or GPS telemetry. Younger drivers in Taipei and Kaohsiung are adopting this platform fastest, accepting privacy trade-offs for premium discounts.
- Usage-Based:Real-time behavioral pricing integrating hard braking frequency, cornering aggression, and time-of-day exposure data. The Financial Supervisory Commission's data portability rules are accelerating insurer investment in telematics infrastructure.
Fixed Premium retains volume dominance. Usage-Based is gaining share fastest among metropolitan millennials and Gen Z policyholders.
Insured Vehicle Type:
Application-specific risk profiles drive divergent pricing and claims experience across Taiwan's heterogeneous vehicle stock.
- Passenger Cars:Private automobile coverage dominating premium pools through higher insured values and comprehensive attachment rates. Northern Taiwan's urban corridors concentrate demand for this segment.
- Motorcycles:High-frequency, low-severity coverage line with mandatory third-party requirements. Shin Kong Insurance competes aggressively here, reflecting Taiwan's dense urban mobility patterns.
- Commercial Vehicles:Fleet-oriented coverage facing elevated severity exposure from heavy-duty logistics operations. Taoyuan and Taichung logistics operators are expanding coverage mandates, pulling comprehensive policies into long-term contracts.
- Electric Vehicles:Emerging category confronting battery pack replacement cost inflation and specialized labor scarcity. The Financial Supervisory Commission's reserve requirement adjustments following catastrophe loss experience directly compress underwriting capacity for this high-severity line.
Passenger Cars anchor premium volume. Electric Vehicles are expanding most quickly as Taiwan's vehicle fleet electrifies.
Customer Segment:
Customer type determines distribution channel economics and policy lifecycle value, with procurement consolidation reshaping competitive dynamics.
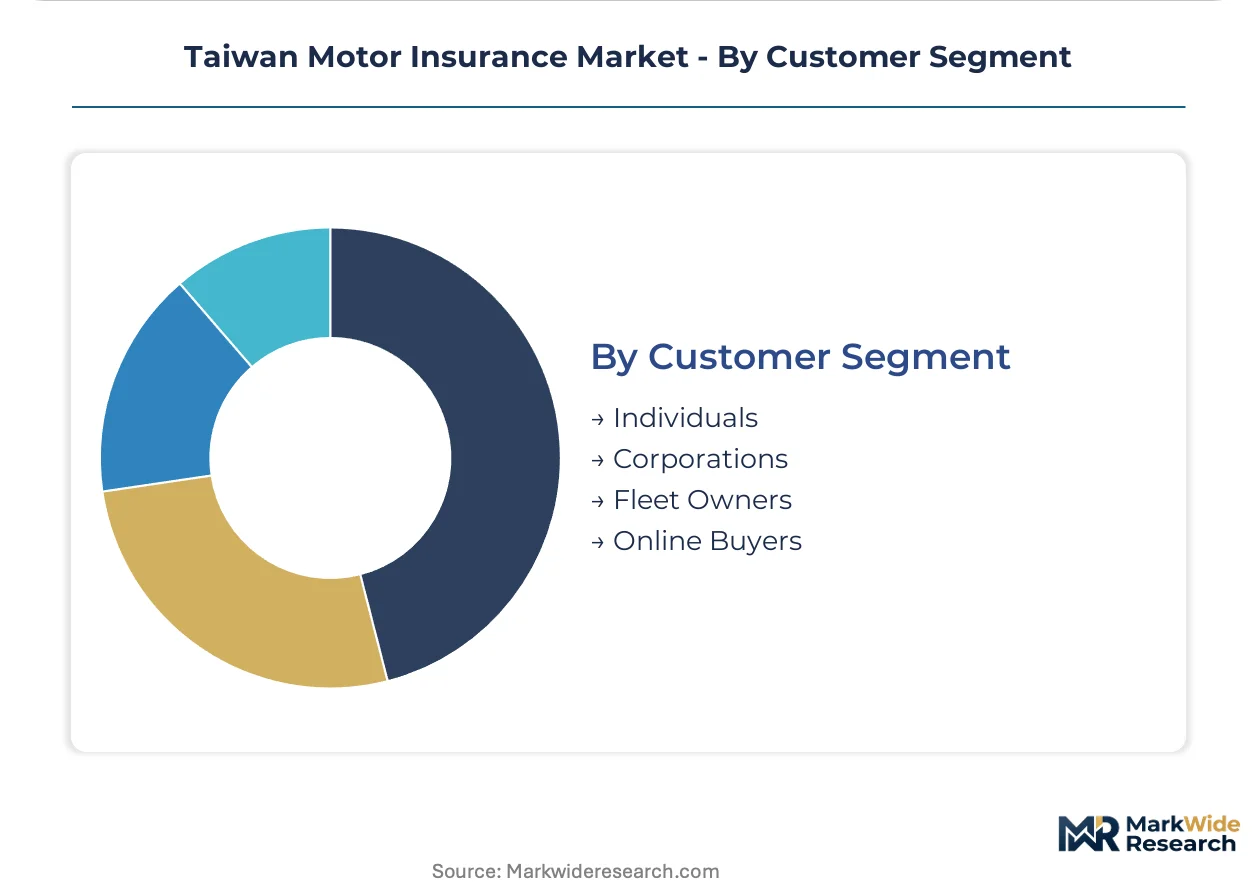
- Individuals:Retail policyholders purchasing through agency networks, bancassurance channels, or direct digital platforms. Cathay Life Insurance leverages its extensive agency network to sustain dominance in this personal auto line.
- Corporations:Enterprise vehicle coverage for executive fleets and commercial operations. Fubon Insurance anchors its position through bancassurance integration with its banking parent.
- Fleet Owners:Consolidated procurement managers demanding multi-year contracts with embedded maintenance and telematics services. Electronics manufacturers operating just-in-time logistics networks across western Taiwan's industrial zones are driving this segment's expansion.
- Online Buyers:Digital-native purchasers bypassing traditional intermediaries for direct insurer relationships. ISO 9001 quality management certification is bifurcating the competitive landscape between established underwriters and newer digital entrants.
Individuals retain the largest policy count. Fleet Owners are climbing the fastest as logistics digitization mandates expand coverage requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Financial Supervisory Commission's risk-based capital framework is compressing underwriting capacity unevenly across Taiwan's sub-regions, with northern metropolitan corridors facing sharper premium adjustments than southern industrial zones.
Greater Taipei Metropolitan Corridor
High-value vehicle concentration drives comprehensive coverage demand in Taipei City and New Taipei. The Compulsory Automobile Liability Insurance Act mandates baseline third-party coverage nationwide. Taoyuan's logistics hub generates concentrated commercial fleet demand as electronics manufacturers expand just-in-time coverage mandates.
Taichung Central Taiwan Corridor
Automotive manufacturing clusters pull cost-optimized third-party fire and theft policies from parts suppliers. The Financial Supervisory Commission's quarterly solvency reviews constrain smaller underwriters' capacity to serve this expanding commercial base. Fleet digitization mandates across Taichung's industrial zones are accelerating long-term contract consolidation.
Kaohsiung Southern Port Logistics Zone
Heavy commercial vehicle operators face elevated liability exposure from port freight movements. Usage-based insurance platforms capture younger drivers fastest in this metropolitan center. The Insurance Bureau's reserve requirement adjustments following catastrophe loss experience directly compress underwriting capacity available for high-severity comprehensive lines here.
Tainan-Hsinchu Western Industrial Belt
Traditional agency intermediaries retain dominant distribution share for fixed-premium personal auto products. ISO 9001 quality management certification timelines stretch 18-24 months, creating competitive lag for digital entrants against established underwriters. Electronics subcontractors across this corridor are consolidating insurance purchasing across vehicle classes.
Eastern Taiwan Corridor
Rural counties show universal mandatory coverage penetration with minimal comprehensive attachment. Pay-as-you-drive models gain limited traction outside metropolitan cores due to lower vehicle utilization rates. The region's sparse population density constrains telematics infrastructure investment relative to western corridors.
Taiwan Motor Insurance Market Competitive Landscape
Listed leaders compete with private specialists across distribution channel access, with agency network scale determining personal line dominance while bancassurance integration captures corporate fleet procurement. The market structure concentrates around three tiers: established life insurers with captive agency forces, banking-group affiliated underwriters leveraging cross-sell infrastructure, and specialist motorcycle coverage providers competing on price. Strategic moves center on telematics platform investment and multi-year fleet contract consolidation.
Within the life-insurer tier, Cathay Life Insurance and Nan Shan Life Insurance anchor positions through extensive agency networks that sustain dominance in personal auto lines. Fubon Insurance exemplifies the bancassurance archetype, occupying a position through banking parent integration that targets bundled auto-loan products. Shin Kong Insurance represents the specialist vector, sitting within motorcycle coverage where high-volume density matches Taiwan's urban mobility patterns.
| Leading Market Players |
|---|
| Cathay Life Insurance |
| Nan Shan Life Insurance |
| Taipei Insurance |
| Taiwan Fire & Marine Insurance |
| Shin Kong Insurance |
| Fubon Insurance |
| China Trust Life Insurance |
| Hotai Insurance |
| Chung Kuo Insurance |
| Others |
Value Network & Pricing Analysis
Long-term fleet contracts with embedded telematics services lock in premium visibility for underwriters while securing dedicated underwriting capacity for logistics operators across Taoyuan and Taichung. The Financial Supervisory Commission's risk-based capital requirements compress pricing flexibility for smaller insurers unable to match these contract structures.
Pricing Analysis
Certification level creates the primary spread between established underwriters and digital entrants, with ISO 9001 quality management compliance stretching 18-24 months for newer market participants. Fixed premium products retain volume dominance across personal auto lines, while usage-based models command rate premiums for behavioral data access. Pricing pressure stems from EV repair cost inflation compressing comprehensive coverage margins. Fleet owners show lowest price sensitivity due to embedded maintenance bundling, whereas individual retail policyholders in Greater Taipei demonstrate highest sensitivity to telematics discount availability.
Supply Chain Analysis
Taiwan anchors actuarial talent development and core policy administration platform engineering for domestic motor insurance operations. Reinsurance capacity draws from Singapore and London markets for catastrophic loss protection. Supply chain risk centers on single-source vulnerability for telematics hardware modules sourced from concentrated electronics manufacturing clusters. Distribution runs through established agency networks in northern Taiwan, with bancassurance channels gaining share for corporate fleet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Taiwan's motor insurance market operates as a defensive-moat sector where regulatory entrenchment through the Financial Supervisory Commission's risk-based capital requirements creates durable barriers against unqualified entrants.
For Market Incumbents: Secure telematics-AI convergence capabilities through partnership or in-house development to defend against digital-native competitors capturing younger metropolitan drivers. Deepen bancassurance integration with banking parents to lock in auto-loan insurance bundling for first-time vehicle buyers. Prioritize ISO 9001 certification maintenance to sustain quality differentiation against newer entrants facing 18-24 month compliance timelines. For New Entrants and Emerging Players: ISO 9001 fast-track certification programs offer the most viable path to competitive parity with established underwriters in personal auto lines. Target the Taichung Central Taiwan Corridor for commercial fleet coverage where automotive manufacturing clusters generate underpenetrated demand from parts suppliers. Lead with pay-as-you-drive platforms to capture metropolitan millennials and Gen Z policyholders bypassing traditional agency networks. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier underwriters with existing agency infrastructure but lacking telematics capabilities, where technology integration unlocks margin expansion. Long-term viability hinges on regulatory compliance scalability rather than pure pricing competition. Watch the Financial Supervisory Commission's quarterly solvency review announcements as the critical signal for underwriting capacity compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Real-time behavioral data from Taipei and Kaohsiung drivers enables dynamic premium calibration and claims frequency reduction. |
| ISO 9001 Certification Investment | Quality management compliance creates 18-24 month competitive lag for digital entrants against established underwriters. |
| Bancassurance Channel Expansion | Banking parent relationships capture bundled auto-loan insurance products targeting first-time vehicle buyers through Fubon Insurance's model. |
| Fleet Contract Consolidation | Multi-year agreements with embedded maintenance services lock in Taoyuan and Taichung electronics manufacturers operating just-in-time logistics. |
| EV Risk Assessment Capability Buildout | Battery pack replacement cost modeling addresses specialized labor scarcity compressing comprehensive coverage loss ratios. |
Research Methodology
A spread of perspectives from underwriting executives, actuarial directors, fleet procurement managers, and agency network heads converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through Financial Supervisory Commission regulatory filings, Insurance Bureau reserve requirement adjustments, and vehicle registration databases from Taiwan's Ministry of Transportation and Communications. Bottom-up policy volume estimates triangulated against top-down premium pool calculations across the analysis window.
Segmentation dimensions modeled include policy architecture, premium structure mechanics, insured vehicle classification, and customer procurement behavior throughout the forecast period. CAGRs were derived from historical loss ratio trends and forward-looking capacity constraints under risk-based capital standards. Forecast inputs incorporated telematics adoption curves and EV fleet penetration assumptions specific to Taiwan's automotive electrification pathway.
Underlying assumptions cover regulatory stability in solvency standards, with deviation risk concentrated in central bank interest rate trajectory shifts affecting investment income volatility. Forecasts reflect these conditions with acknowledgment that Financial Supervisory Commission policy adjustments or catastrophe loss experience could materially revise trajectory. Recalibration cycles align with material shifts in risk-based capital requirements and telematics data portability rule implementations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
United Kingdom Motor Insurance Market
Motor Insurance
Motorcycle Insurance Market
Motor Insurance
Philippines Motor Insurance Market
Motor Insurance
Brazil Car Insurance Market
Motor Insurance
Automotive Insurance Market
Motor Insurance
Thailand Motor Insurance Market
Motor Insurance
Two Wheeler Insurance Market
Motor Insurance
New Energy Car Insurance Market
Motor Insurance
Canada Motor Insurance Market
Motor Insurance
Indonesia Motor Insurance Market
Motor Insurance
Motor Insurance Market
Motor Insurance
Vietnam Motor Insurance Market
Motor Insurance
New Energy Vehicle Accident Insurance Market
Motor Insurance
Saudi Arabia Motor Insurance Market
Motor Insurance
Personal Auto Insurance Market
Motor Insurance
South Korea Motor Insurance Market