
 China Motor Insurance Market | 2026-2036
China Motor Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
China Motor Insurance Market Outlook
Multi-source data partnerships between insurers and telematics providers is realigning how risk gets priced and distributed across the China motor insurance value chain. PICC leverages its state-backed branch network to sustain dominance in rural and commercial vehicle segments. Ping An competes through proprietary AI-driven claims platforms that reduce loss adjustment expenses. China Pacific anchors its position in electric vehicle coverage through exclusive partnerships with domestic EV manufacturers.
China motor insurance constitutes a contractual risk-transfer mechanism where insurers indemnify policyholders against financial loss arising from vehicle damage, third-party bodily injury, or property damage in exchange for premium payments, with pricing increasingly indexed to real-time driving behavior data transmitted via onboard diagnostic ports or smartphone applications. The coverage type dimension shows liability coverage maturing as a mandatory baseline while comprehensive policies capture expanding margin pools from affluent individual policyholders and corporate fleet operators seeking bundled protection. Electric vehicle coverage within the vehicle type dimension represents the fastest-growing risk pool as NEV penetration drives actuarial model innovation and specialized component valuation methodologies.
SAMR enforces market conduct rules that constrain predatory pricing and mandate solvency transparency, while MIIT telematics standards dictate the data architecture available for usage-based insurance products. The country's national banking and insurance regulator supervises premium rate filing procedures that balance consumer protection with insurer profitability. Stakeholders must monitor how GB standards evolve for autonomous vehicle liability attribution and whether captive supply of driving data from domestic OEMs reshapes competitive access to risk-predictive inputs.
Market Dynamics
Connected vehicle telematics data streams are compressing risk assessment cycles from annual renewals to real-time pricing adjustments, forcing insurers to rebuild core actuarial systems around continuous data ingestion rather than static demographic proxies.
Growth Catalysts
- MIIT telematics standards:Mandated onboard diagnostic data architecture creates uniform inputs for usage-based insurance products, reducing data acquisition costs for underwriters.
- Logistics fleet digitization:Commercial operators managing thousands of vehicles demand granular risk visibility, pulling insurers toward enterprise-grade telematics partnerships.
- Yangtze River Delta concentration:Premium vehicle density in Shanghai-Jiangsu-Zhejiang corridors generates concentrated demand for comprehensive coverage tiers.
Market Restraints
- Domestic OEM data captivity:BYD, NIO and XPeng restrict telematics feed access to affiliated insurers, fragmenting risk-predictive input availability.
- SAMR rate-filing friction:Mandatory premium approval timelines compress pricing agility, delaying competitive responses to loss ratio shifts.
- Specialized EV component valuation:Battery pack depreciation curves and solid-state transition uncertainty inflate claim reserve volatility.
Strategic Opportunities
- Autonomous liability frameworks:Draft GB standards for driver-assist system fault attribution will open coverage white space before product-market fit crystallizes.
- Lower-tier city penetration:Henan, Sichuan and Hunan provinces show rising vehicle ownership with underdeveloped agency distribution, rewarding direct-to-consumer digital platforms.
- Carbon-accounting convergence:Dual carbon goals create regulatory pressure to link premium discounts to verified emission reductions, enabling new product differentiation.
Industry Challenges
- Actuarial talent scarcity:Shortage of professionals capable of integrating real-time telematics streams with traditional reserving models delays product launches.
- Legacy core system integration:Policy administration platforms built for annual cycles struggle to ingest and price continuous data feeds without expensive middleware.
- Cross-provincial claims adjudication:Varying local court interpretations of telematics evidence admissibility complicates loss adjustment standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Motor Insurance Market |
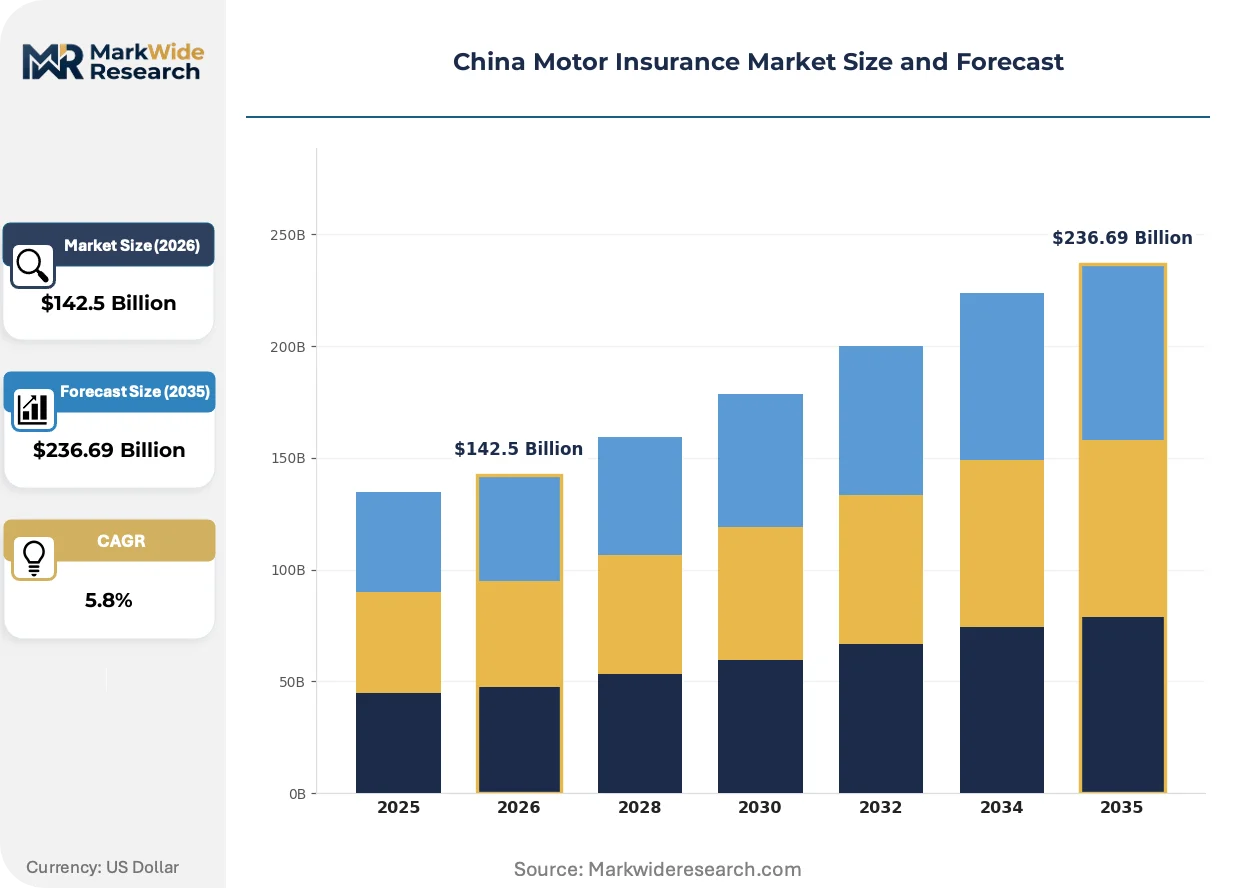
| Market Size in 2026 | $142.5 Billion |
| Market Size in 2035 | $236.69 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Liability, Comprehensive, Collision, Personal Injury Protection Policyholder Type: Individual, Corporate Fleet, Government Agency, Ride-sharing Service Vehicle Type: Passenger Car, Commercial Truck, Motorcycle, Electric Vehicle Distribution Channel: Broker, Direct Sales, Online Platforms, Agents |
| Companies Covered | China Continent Insurance, Axa Tianping, PICC, Samsung Property Insurance, China United Property Insurance, Ping An, China Taiping, Huatai Property Insurance, China Pacific, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Motor Insurance Market Strategic Shifts
Artificial intelligence and connected vehicle infrastructure are collapsing the latency between risk event occurrence and financial consequence settlement, redefining insurer policyholder relationships from annual transactions to continuous service engagements.
AI-driven computer vision for damage assessment is expanding into the claims workflow, enabling smartphone-based first notice of loss with automated repair cost estimation. PICC and Ping An have deployed these tools for minor collision claims, compressing settlement cycles from weeks to hours. The technology is expanding into total loss valuation and salvage auction pricing, displacing traditional adjuster dispatch for standardized damage categories.
SAMR solvency transparency rules now mandate quarterly public disclosure of combined operating ratios and reserve adequacy, exposing undercapitalized regional players to reputation-driven policyholder flight. The regulation forces mid-tier insurers toward reinsurance partnerships or consolidation, concentrating market share among state-backed and technology-forward competitors. Commercial fleet underwriters face the steepest compliance costs given their complex multi-provincial exposure aggregation.
Corporate procurement of motor coverage is consolidating around enterprise risk management platforms that unbundle traditional bundled policies into modular components. Logistics operators now source third-party liability, cargo damage and vehicle physical damage through separate negotiations, often with different carriers. This unbundling is most visible in Guangdong and Zhejiang provinces where large fleet operators have established captive insurance management subsidiaries to optimize coverage stacking.
China Motor Insurance Market Segmentation
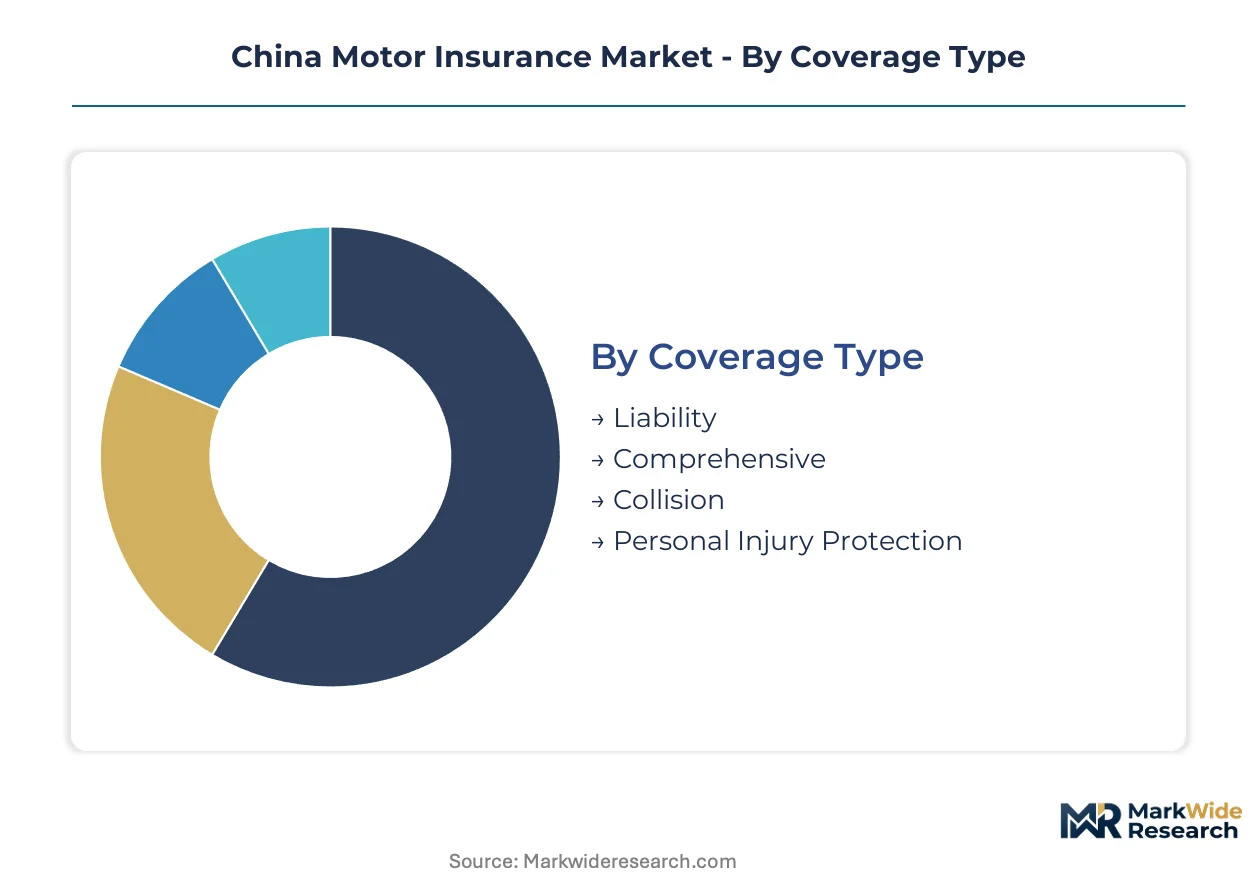
Segmentation in China's motor insurance market determines regulatory filing requirements, capital reserve calculations, and pricing autonomy under SAMR oversight. Each dimension carries distinct compliance burdens and margin profiles that shape competitive strategy.
Coverage Type:
Third-party liability coverage operates under mandatory rate filings with SAMR, while comprehensive and collision products face lighter regulatory touch but higher capital charges for reserve adequacy.
- Liability:Mandatory third-party bodily injury and property damage coverage forms the regulatory baseline. Shanghai and Jiangsu regulators enforce strict loss ratio monitoring, compressing margin flexibility for this high-volume segment.
- Comprehensive:Bundled protection against theft, natural disaster, and own-vehicle damage commands premium pricing in Zhejiang's affluent urban corridors. Fleet operators in the Yangtze River Delta drive demand for customizable deductible structures.
- Collision:Physical damage coverage limited to at-fault accidents carries lower regulatory scrutiny but requires precise telematics integration for usage-based pricing.
- Personal Injury Protection:Medical expense and disability coverage for occupants faces evolving GB standards on autonomous vehicle occupant liability attribution.
Leading the category by volume: Liability. Growing fastest: Comprehensive.
Policyholder Type:
Risk assessment protocols diverge sharply between individual retail purchasers and enterprise-scale buyers with continuous data streams.
- Individual:Personal vehicle owners represent the foundational risk pool. Henan and Sichuan provinces show rising penetration with underdeveloped agency infrastructure, rewarding direct digital acquisition models.
- Corporate Fleet:Logistics operators managing hundreds of vehicles demand granular telematics visibility. MIIT-mandated onboard diagnostic feeds enable real-time pricing adjustments unavailable to retail segments.
- Government Agency:State vehicle pools operate under centralized procurement with standardized coverage terms and limited pricing negotiation.
- Ride-sharing Service:Platform-mediated drivers present blurred personal-commercial use cases requiring specialized GB liability frameworks still under draft consultation.
Highest premium density: Corporate Fleet. Steepest expansion trajectory: Ride-sharing Service.
Vehicle Type:
Component valuation methodologies and data access protocols fragment underwriting approaches across propulsion technologies.
- Passenger Car:Conventional internal combustion vehicles dominate current premium volume. Established repair networks and depreciation curves support standardized reserving models.
- Commercial Truck:Heavy freight vehicles face stringent MEE emission compliance linkage to premium discounts under dual carbon goals.
- Motorcycle:Two-wheeler coverage operates in regulatory gray zones with limited telematics penetration and higher loss frequency.
- Electric Vehicle:Battery pack valuation uncertainty and solid-state transition risk inflate claim reserve volatility. BYD, NIO and XPeng restrict data feed access to affiliated insurers, fragmenting risk-predictive inputs.
Dominant by premium volume: Passenger Car. Gaining share fastest: Electric Vehicle.
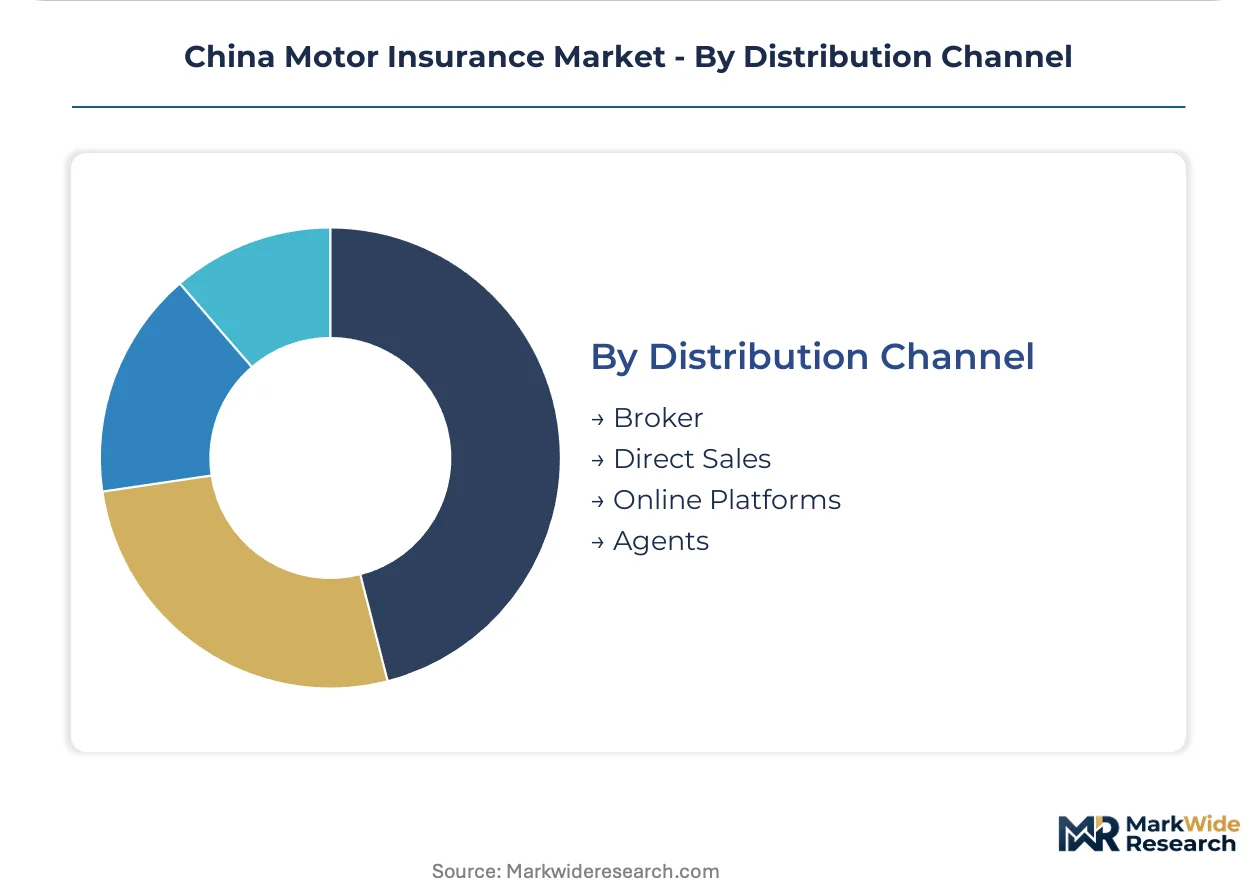
Distribution Channel:
Channel economics reflect regulatory capital requirements and customer acquisition cost structures under SAMR market conduct rules.
- Broker:Independent intermediaries aggregate multi-carrier comparisons. Lower-tier cities rely heavily on broker networks where direct digital penetration remains thin.
- Direct Sales:Insurer-owned channels capture margin otherwise paid to intermediaries. PICC leverages its state-backed branch network to sustain rural dominance through this channel.
- Online Platforms:Digital aggregators and insurer apps enable smartphone-based policy issuance. Ping An's proprietary AI claims platforms reduce friction in digital conversion funnels.
- Agents:Captive and independent agents persist in relationship-driven segments. Guangdong fleet operators increasingly bypass agents through captive insurance management subsidiaries.
Largest volume channel: Agents. Expanding most quickly: Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta vehicle density anchors premium concentration across the Chinese motor insurance landscape. Provincial regulatory divergence shapes underwriting autonomy and claims adjudication standards.
Shanghai
Luxury vehicle fleets and ride-sharing platforms drive comprehensive coverage demand. SAMR enforces strict loss ratio monitoring on mandatory liability products. Pudong and Hongqiao logistics corridors concentrate commercial fleet underwriting activity.
Jiangsu
Manufacturing supply chains generate heavy commercial truck exposure across Nanjing and Suzhou industrial zones. MIIT telematics standards mandate uniform onboard diagnostic data architecture. Wuxi and Changzhou host dense networks of EV component suppliers seeking specialized battery coverage.
Zhejiang
Affluent individual policyholders in Hangzhou and Ningbo pull comprehensive policy growth. Provincial regulators coordinate with SAMR on premium filing timelines. Wenzhou's private manufacturing clusters sustain demand for customizable fleet deductible structures.
Guangdong
Pearl River Delta logistics operators unbundle traditional bundled policies into modular components. MEE emission compliance linkage creates premium discount pressure on commercial truck coverage. Shenzhen and Guangzhou fleet operators establish captive insurance management subsidiaries.
Sichuan
Rising vehicle ownership in Chengdu and surrounding cities outpaces agency distribution infrastructure. Lower-tier city penetration rewards direct-to-consumer digital platforms. Chongqing's automotive manufacturing base generates captive OEM-affiliated insurer relationships.
China Motor Insurance Market Competitive Environment
Global majors compete with regional champions across distribution channel access and telematics data partnerships. The market exhibits tiered concentration with state-backed incumbents commanding rural networks while technology-forward challengers capture digital-native segments. Three archetypes dominate: branch-network heavyweights, AI-driven claims platforms, and EV-specialized underwriters. Competitive intensity manifests through exclusive OEM data partnerships and direct-to-consumer platform expansion.
Among state-backed incumbents, PICC leverages its branch infrastructure to anchor rural and commercial vehicle segments. Ping An occupies a position exemplifying the technology-forward archetype through proprietary AI claims platforms. China Pacific represents EV-specialized underwriting through exclusive partnerships with domestic manufacturers. These three players collectively illustrate how data access and distribution scale separate tier-one competitors from mid-tier regional challengers.
| Leading Market Players |
|---|
| China Continent Insurance |
| Axa Tianping |
| PICC |
| Samsung Property Insurance |
| China United Property Insurance |
| Ping An |
| China Taiping |
| Huatai Property Insurance |
| China Pacific |
| Others |
Value Chain & Pricing Dynamics
Logistics fleet digitization across the Yangtze River Delta is compressing underwriting cycles and forcing insurers to rebuild pricing engines around continuous telematics ingestion rather than static renewal schedules. This procurement shift toward real-time risk visibility fragments actuarial cost structures and rewards carriers with proprietary data partnerships.
Pricing Analysis
Warranty and service bundling separates comprehensive policies from stripped liability coverage, with premium-mid-economy pricing differentiation anchored to telematics integration depth and claims automation capability. Price differentiation hinges on MIIT-mandated diagnostic data access and AI-driven loss adjustment efficiency. Pricing pressure stems from SAMR rate-filing timelines that delay competitive responses to loss ratio shifts. Corporate fleet operators show lowest price sensitivity due to enterprise risk management platform consolidation, while individual retail segments in lower-tier provinces exhibit highest elasticity.
Supply Chain Analysis
GB standards certification and MIIT telematics architecture qualification gate access to usage-based insurance product development, filtering insurer technology partnerships. Risk-predictive inputs draw from domestic OEM captive data feeds, third-party telematics providers, and SAMR-mandated disclosure repositories. Supply chain risk centers on single-source vulnerability as BYD, NIO and XPeng restrict telematics access to affiliated underwriters. Distribution runs through state-backed branch networks, digital direct-to-consumer platforms, and broker intermediaries with varying data integration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
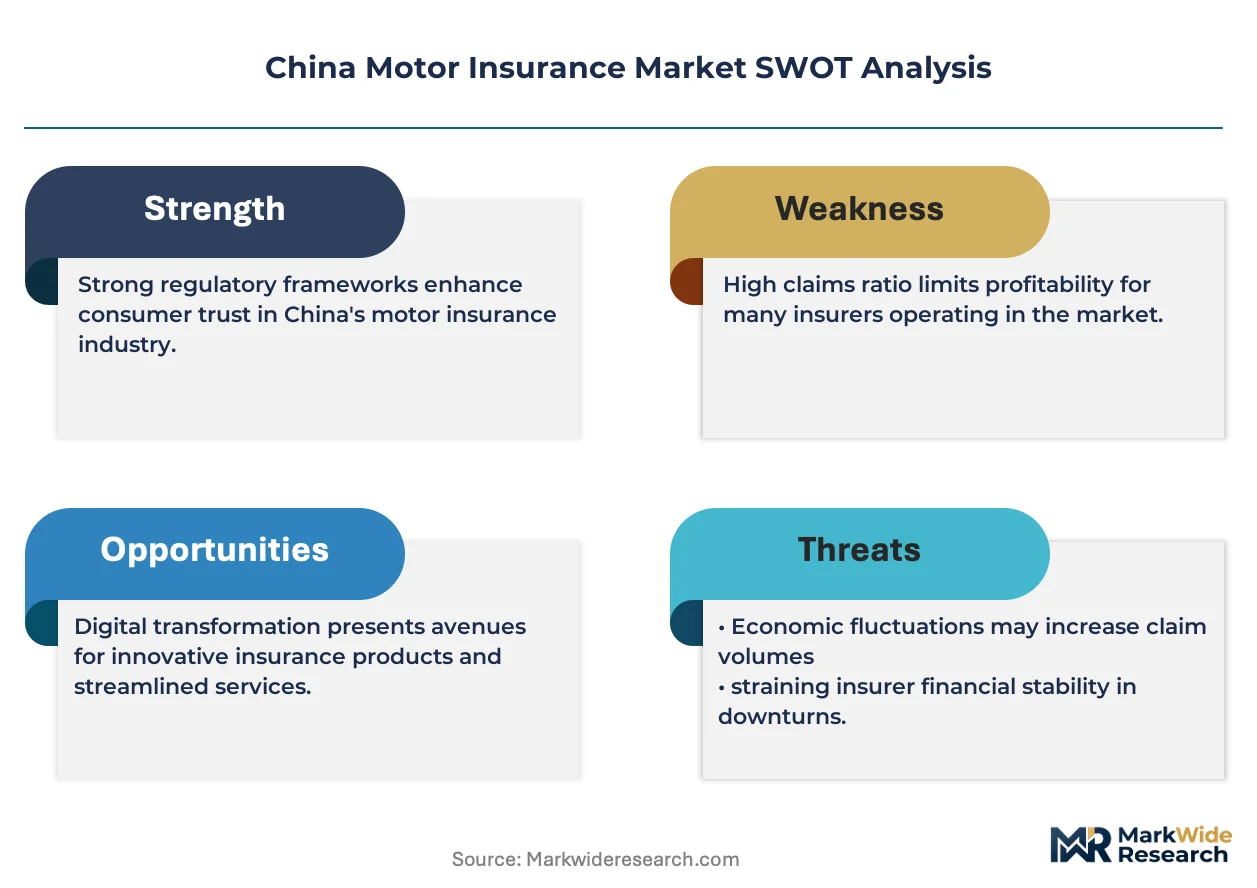
SAMR solvency transparency rules function as a cost-of-compliance moat, concentrating market share among carriers with capital reserves sufficient to absorb quarterly disclosure burdens and reputation-driven policyholder flight.
For Market Incumbents: Deploy proprietary AI claims platforms to compress settlement cycles and defend margin position against Ping An's technology-forward archetype. Consolidate reinsurance partnerships to absorb SAMR capital adequacy pressures, and deepen exclusive OEM data partnerships before domestic manufacturers finalize captive insurer affiliations. For New Entrants and Emerging Players: Direct-to-consumer digital platforms in Henan, Sichuan and Hunan provinces offer the most penetrable white space given underdeveloped agency infrastructure. Target ride-sharing service coverage under draft GB liability frameworks before product-market fit crystallizes, and anchor go-to-market strategy on smartphone-based policy issuance with automated first notice of loss. For Investors and Strategic Acquirers: The window for entry favors technology-forward challengers with integrated telematics capabilities over legacy branch-network heavyweights burdened by core system modernization debt. Long-term viability hinges on autonomous liability framework positioning ahead of GB standard finalization. Watch for MIIT telematics architecture revisions as inflection indicators for data access competitive dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive OEM Data Partnership | Secures risk-predictive feed access from BYD, NIO or XPeng before captive restrictions harden. |
| AI Claims Platform Deployment | Compresses Ping An-style settlement cycles from weeks to hours for minor collision categories. |
| Reinsurance Partnership Consolidation | Absorbs SAMR solvency transparency compliance costs for mid-tier carriers facing capital pressure. |
| Direct-to-Consumer Platform Expansion | Captures Henan and Sichuan individual policyholders where agency distribution remains thin. |
| Autonomous Liability Framework Positioning | Establishes coverage white space before GB standards crystallize fault attribution protocols. |
Study Parameters
Multi-period observation of SAMR rate filings, MIIT telematics standard revisions, and insurer combined operating ratio disclosures anchored the trend analysis, supplemented by interviews with actuarial directors, connected vehicle platform engineers, fleet procurement managers, and SAMR compliance officers. Secondary validation drew from NMPA regulatory filings, GB standards consultation drafts, MIIT policy circulars, and provincial insurance bureau statistical yearbooks. Bottom-up premium volume estimates triangulated against top-down macroeconomic vehicle ownership projections.
Input-output matrix modeling structured the analytical framework across the projection horizon, with segmentation dimensions spanning coverage type, policyholder archetype, vehicle propulsion technology, and distribution channel. CAGRs were derived from regression analysis of historical premium growth against vehicle registration trends and telematics penetration curves. Forecast inputs incorporated dual carbon goal compliance linkages to commercial truck premium discounts and solid-state battery transition timelines affecting EV component valuation.
Inputs from SAMR quarterly solvency disclosures and MIIT telematics architecture specifications were available through the study window; gaps in autonomous vehicle liability attribution draft standards introduce uncertainty bands around emerging coverage product timelines. Forecasts reflect documented assumptions regarding NEV penetration trajectories and regulatory filing timeline stability. A model refresh is warranted upon material change in GB standards for driver-assist system fault attribution or domestic OEM data captivity enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Global Commercial Auto Insurance Market
Motor Insurance
Marine Insurance Market
Motor Insurance
Automotive Insurance Market
Motor Insurance
Motorcycle Insurance Market
Motor Insurance
Japan Car Insurance Market
Motor Insurance
Russia Car Insurance Market
Motor Insurance
Vietnam Motor Insurance Market
Motor Insurance
New Energy Vehicle Accident Insurance Market
Motor Insurance
India Motor Insurance Market
Motor Insurance
Private Passenger Auto Insurance Market
Motor Insurance
United Arab Emirates Motor Insurance Market
Motor Insurance
New Energy Car Insurance Market
Motor Insurance
Singapore Motor Insurance Market
Motor Insurance
Thailand Motor Insurance Market
Motor Insurance
Germany Motor Insurance Market
Motor Insurance
Philippines Motor Insurance Market