
 Middle East and West Africa Pharmaceutical Plastic Packaging Market | 2026-2036
Middle East and West Africa Pharmaceutical Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and West Africa Pharmaceutical Plastic Packaging Market Foresight
REACH-equivalent chemical safety standards across Gulf Cooperation Council member states is expanding the cost-of-entry calculus for imported pharmaceutical plastic packaging. Amcor Limited leverages its regional manufacturing footprint to sustain compliance advantages across Saudi Arabia and the UAE. Berry Plastics Group anchors supply security through backward integration into resin compounding operations. Aptar Pharma differentiates via specialized dosing and dispensing closure systems for chronic disease therapies.
Pharmaceutical plastic packaging encompasses polymer-based primary and secondary containers engineered to meet barrier specifications for moisture, oxygen, and light transmission, typically manufactured through injection molding, blow molding, or thermoforming processes with wall thickness tolerances measured in millimeters. Its primary commercial purpose centers on preserving drug stability, ensuring patient safety through child-resistant and tamper-evident features, and enabling compliant distribution across temperature-variable climates. Bottles and blisters occupy the dominant volume positions, with bottles capturing the majority share in liquid and semi-solid formulations while blisters accelerate fastest due to unit-dose compliance packaging demand from chronic disease programs. Polypropylene and polyethylene lead material selection for chemical inertness and heat sealability, though PET gains share in visibility-driven over-the-counter segments where clarity supports brand differentiation.
Saudi Food and Drug Authority registration requirements and Nigeria's National Agency for Food and Drug Administration and Control cGMP guidelines jointly shape product standards, mandating extractables and leachables documentation that favors suppliers with established analytical laboratories. The UAE's Ministry of Health and Prevention import licensing protocols further filter market access, creating preference for packaging converters with prior Gulf regulatory dossiers. Stakeholders must monitor divergence between Gulf harmonization initiatives and country-specific pharmacopeial updates, as regulatory misalignment threatens to fragment procurement strategies across the Middle East and West Africa corridor.
Market Dynamics
The GCC's unified pharmaceutical traceability mandate is compressing supplier qualification timelines while redirecting procurement toward domestic converters with serialization-ready capabilities.
Growth Catalysts
- Localization mandates:Saudi Arabia's domestic content requirements and the UAE's industrial localization policies are redirecting procurement toward regional packaging converters with established Gulf regulatory dossiers.
- Chronic disease expansion:Nigeria's National Health Insurance Authority enrollment drives are scaling unit-dose compliance packaging for hypertension and diabetes therapies across West African distribution networks.
- Barrier polymer innovation:Cyclic olefin copolymer adoption for parenteral packaging is expanding moisture and oxygen protection for temperature-variable climates across the Middle East corridor.
Market Restraints
- Resin supply concentration:Polypropylene feedstock dependence on Gulf petrochemical complexes creates input cost volatility when regional crackers undergo maintenance cycles.
- Regulatory fragmentation:Divergence between Saudi Food and Drug Authority pharmacopeial updates and Nigeria's NAFDAC cGMP guidelines forces dual dossier preparation for cross-regional suppliers.
- Glass substitution threat:Borosilicate vials retain preference for high-value biologics, limiting polymer penetration in oncology and vaccine packaging segments.
Strategic Opportunities
- West African manufacturing gap:Nigeria's packaging import dependence creates white space for regional converters establishing Lagos-anchored production with ECOWAS trade corridor access.
- Smart packaging convergence:Near-field communication tags integrated with tamper-evident closures are enabling cold-chain verification for insulin distribution across Sahel temperature extremes.
- MOHAP fast-track licensing:The UAE's streamlined import protocols for pre-qualified packaging materials accelerate market entry for converters with existing European Medicines Agency dossiers.
Industry Challenges
- Extractables validation timelines:Saudi Food and Drug Authority requirements for comprehensive leachables documentation extend product qualification cycles for new polymer formulations.
- Serialization integration complexity:Legacy blow-molding lines require substantial retrofit capital to accommodate aggregation and track-and-trace data matrix printing at line speeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and West Africa Pharmaceutical Plastic Packaging Market |
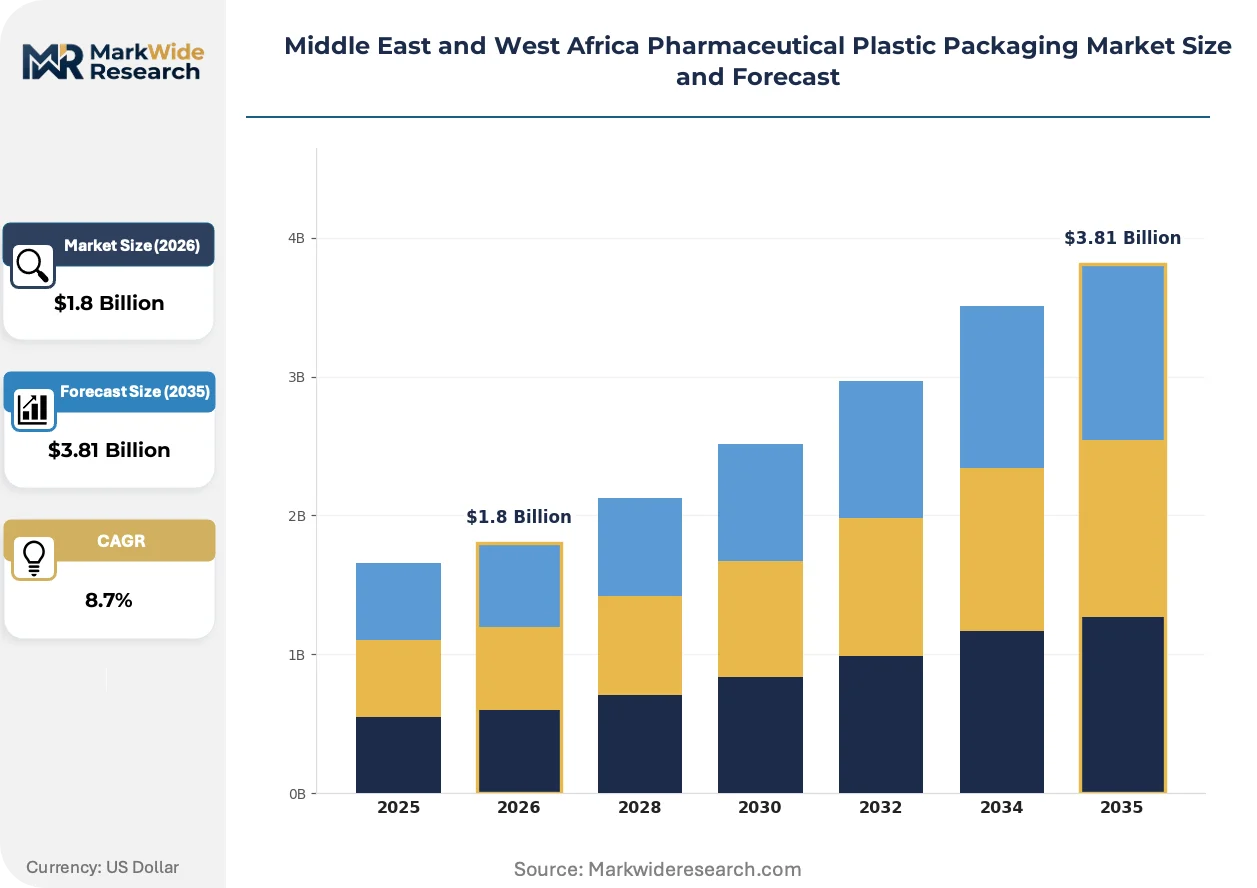
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Blisters, Caps, Jars Material: Polypropylene, Polyethylene, PVC, PET End User: Pharmaceutical Companies, Contract Manufacturers, Distributors, Retailers Distribution Channel: Online, Pharmacies, Hospitals, Wholesale |
| Companies Covered | Amcor Limited, Berry Plastics Group, Inc., Aptar Pharma, Berk Company, LLC, Alpha Packaging, Graham Packaging Company, COMAR, LLC, Alpack Plastic Packaging, Gulf Packaging Industries Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and West Africa Pharmaceutical Plastic Packaging Market Shifts & Advancements
Active pharmaceutical ingredient stability requirements are reshaping material selection priorities while regulatory serialization mandates accelerate equipment replacement cycles across regional converter bases.
Multilayer co-injection barrier technology is decentralizing supply chain risk for moisture-sensitive solid dosages. Regional pharmaceutical manufacturers in Saudi Arabia and the UAE are adopting five-layer polyamide-ethylene vinyl alcohol structures at accelerated procurement pace. This technology is decentralizing dependence on single-source desiccant canister suppliers by integrating active barrier function directly into container walls.
SFDA traceability regulations are mandating aggregation hierarchy standards from primary package to pallet. The industrial consequence compresses batch release timelines for exporters lacking pre-validated serialization workflows. Parenteral packaging categories face the steepest compliance burden, with Gulf-based converters investing in vision verification systems to maintain supply access.
Hospital procurement consolidation is compressing supplier rosters across the UAE's Ministry of Health and Prevention network. Group purchasing organizations are displacing direct manufacturer relationships, concentrating volume among converters with multi-site service capabilities. This pattern is most visible in Dubai and Abu Dhabi health system clusters, where three-year framework agreements now dominate tender participation requirements.
Middle East and West Africa Pharmaceutical Plastic Packaging Market Segmentation
Equipment replacement cycles and regulatory serialization mandates are forcing pharmaceutical manufacturers to requalify packaging formats across the Middle East and West Africa corridor. Segmentation clarity enables procurement teams to match barrier specifications against specific drug stability requirements while navigating divergent Gulf and West African compliance protocols.
Product Type:
Upgrade investments in serialization-ready lines are reshaping volume distribution across primary container categories, with track-and-trace compliance driving differential equipment spend.
- Bottles:Polymer containers for oral liquids and semi-solid formulations dominate procurement volumes in Saudi Arabia and the UAE, where government localization policies favor regional converters with SFDA-validated dossiers. The category captures the majority share of government tender volumes for chronic disease therapies distributed through hospital networks.
- Blisters:Unit-dose thermoformed packaging accelerates fastest across Nigeria's National Health Insurance Authority programs, with cold-form foil and push-through structures scaling for hypertension and diabetes medication compliance. Demand concentrates in Lagos-anchored distribution corridors serving ECOWAS trade networks.
- Caps:Child-resistant and tamper-evident closures integrate serialization data matrices for Gulf traceability mandates, with demand clustering around Riyadh and Dubai pharmaceutical clusters.
- Jars:Wide-mouth containers serve topical and semi-solid formulations across West African retail pharmacy networks, with procurement patterns tracking regional dermatology and OTC expansion.
Bottles sits at the top of the volume ranking, with Blisters climbing the fastest.
Material:
Cost tier differentiation separates commodity resins from barrier-grade polymers, with extractables documentation requirements filtering supplier access across regulatory jurisdictions.
- Polypropylene:Injection-molded and blow-molded containers offer chemical inertness and heat sealability for oral solid dosages, with Saudi petrochemical feedstock integration supporting regional converter cost positions. SFDA leachables documentation favors established suppliers with analytical laboratory capabilities.
- Polyethylene:HDPE and LDPE grades serve liquid formulations and flexible packaging across Nigerian import-dependent supply chains, with moisture barrier specifications varying by drug stability requirements.
- PVC:Blister base films and rigid containers retain position in cost-sensitive West African markets despite REACH-equivalent pressure from Gulf harmonization initiatives.
- PET:High-clarity bottles gain share in UAE and Saudi over-the-counter segments where brand visibility drives shelf differentiation, with amorphous and crystalline grades segmented by barrier requirements.
Polypropylene captures the largest volume position, while PET gains share fastest in premium OTC applications.
End User:
Customer type determines serialization complexity and qualification timelines, with direct manufacturer relationships commanding stricter documentation than intermediary channels.
- Pharmaceutical Companies:Multinational and regional drug manufacturers in Riyadh, Dubai, and Lagos drive specification-setting for primary packaging, with SFDA and NAFDAC cGMP compliance requirements cascading down supply chains.
- Contract Manufacturers:Toll manufacturing operations across Jebel Ali and Lagos Free Trade Zones concentrate demand for standardized blister and bottle formats with rapid changeover capabilities.
- Distributors:Regional logistics providers in the Gulf and ECOWAS corridors prioritize secondary packaging with aggregation hierarchy for track-and-trace compliance.
- Retailers:Pharmacy chains and hospital procurement consolidators in Abu Dhabi and Lagos influence unit-dose and compliance packaging formats through tender specifications.
Pharmaceutical Companies anchor the highest value tier, with Contract Manufacturers expanding most quickly on localization outsourcing trends.
Distribution Channel:
Channel concentration shapes packaging format fragmentation, with hospital consolidation favoring bulk formats and retail expansion driving unit-dose structures.
- Online:E-pharmacy platforms across the UAE and Nigeria require tamper-evident and temperature-monitoring packaging for last-mile integrity in variable climates.
- Pharmacies:Community and retail pharmacy networks across Saudi Arabia and West Africa drive blister and small-format bottle demand for prescription and OTC volumes.
- Hospitals:Ministry of Health and Prevention framework agreements in Dubai and Abu Dhabi concentrate procurement for multi-dose bottles and compliance packaging across chronic disease programs.
- Wholesale:Regional distributors serving ECOWAS and Gulf corridors prioritize pallet-level aggregation and serialization-ready secondary packaging for cross-border traceability.
Hospitals command the largest volume concentration, with Online channels posting the steepest expansion trajectory on e-pharmacy penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging engineers and polymer chemists cluster around Riyadh, Dubai, and Lagos, anchoring technical capability for pharmaceutical-grade conversion across the Middle East and West Africa corridor.
Saudi Arabia
Domestic content mandates redirect procurement toward local converters with SFDA-validated dossiers. The Saudi Food and Drug Authority's pharmacopeial updates mandate comprehensive leachables documentation that extends qualification cycles. Riyadh-based pharmaceutical clusters concentrate blow-molding capacity for oral liquid containers serving government chronic disease tenders.
United Arab Emirates
MOHAP fast-track licensing accelerates market entry for converters with existing European regulatory dossiers. The Ministry of Health and Prevention's framework agreements consolidate hospital procurement around multi-site service providers. Dubai and Abu Dhabi health system clusters drive demand for serialization-ready secondary packaging with aggregation hierarchy.
Nigeria
National Health Insurance Authority enrollment scales unit-dose compliance packaging for hypertension and diabetes therapies. NAFDAC cGMP guidelines shape product standards with extractables requirements that favor suppliers with established analytical laboratories. Lagos-anchored distribution corridors serving ECOWAS trade networks concentrate blister procurement for regional pharmaceutical manufacturers.
Qatar
Hospital procurement consolidation within the Hamad Medical Corporation network compresses supplier rosters toward converters with Gulf-wide service capabilities. The national pharmaceutical traceability mandate aligns with GCC serialization standards. Doha-based logistics hubs prioritize temperature-monitoring packaging for biologic distribution across Gulf Cooperation Council corridors.
Kuwait
Government pharmaceutical localization policies redirect tender participation toward regional converters with established SFDA or MOHAP regulatory histories. The Ministry of Health's import licensing protocols filter market access for primary packaging materials. Kuwait City pharmaceutical distribution clusters concentrate demand for child-resistant closures integrated with tamper-evident features.
Middle East and West Africa Pharmaceutical Plastic Packaging Market Competitive Landscape
The competitive structure tilts toward multinational converters with established Gulf regulatory dossiers and regional specialists with petrochemical feedstock integration. Three archetypes dominate: global packaging conglomerates with multi-site Middle East manufacturing, Gulf-based converters leveraging proximity to polymer supply, and European specialists exporting serialization-ready formats. Capacity expansion and backward integration into resin compounding represent the dominant competitive vectors.
Among global packaging conglomerates, Amcor Limited and Berry Plastics Group exemplify scale-driven archetypes with regional manufacturing footprints sustaining compliance advantages across Saudi Arabia and the UAE. Aptar Pharma occupies a position within the specialized dosing systems tier, representing differentiation through closure innovation for chronic disease therapies. These three anchors illustrate how regulatory dossier depth and feedstock integration separate sustainable participants from import-dependent challengers.
| Leading Market Players |
|---|
| Amcor Limited |
| Berry Plastics Group, Inc. |
| Aptar Pharma |
| Berk Company, LLC |
| Alpha Packaging |
| Graham Packaging Company |
| COMAR, LLC |
| Alpack Plastic Packaging |
| Gulf Packaging Industries Limited |
| Others |
Supply & Pricing Matrix
Polypropylene resin price indices on the Saudi Arabian petrochemical exchange cascade through converter margins into three distinct procurement tiers across the Middle East and West Africa corridor. Gulf-based converters with backward integration into resin compounding command pricing power over import-dependent Nigerian distributors, while European exporters with EMA dossiers capture premium positioning through MOHAP fast-track licensing.
Pricing Analysis
The bundled-versus-unbundled service split separates converters offering serialization-ready formats with regulatory dossier support from commodity resin suppliers. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth: SFDA-validated suppliers with analytical laboratories command top positioning, regional converters with Gulf petrochemical feedstock integration occupy the mid-tier, and import-dependent West African traders face margin compression from currency volatility and logistics costs. Pharmaceutical companies with government tender volumes exhibit lowest price sensitivity, while retail pharmacy chains in Lagos and Abu Dhabi drive aggressive procurement negotiation.
Supply Chain Analysis
Polymer feedstock supply rests on Saudi Arabian and UAE petrochemical complexes, with polypropylene and polyethylene resin production concentrated in Jubail Industrial City and Ruwais. Nigerian packaging demand draws from Asian and European converter imports due to absent domestic pharmaceutical-grade blow-molding capacity. Single-source vulnerability concentrates around desiccant canister suppliers for moisture-sensitive solid dosages. Distribution runs through Dubai's Jebel Ali Free Zone for Gulf hospital networks and Lagos-anchored ECOWAS corridors for West African pharmaceutical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and West Africa pharmaceutical plastic packaging market functions as a geographic-arbitrage play where Saudi domestic content requirements and Nigerian import dependence create divergent cost structures. Converters establishing Lagos production with ECOWAS access capture margin spreads unavailable to pure exporters.
For Market Incumbents: Hedge resin cost volatility through captive compounding operations or long-term offtake agreements with Saudi Basic Industries Corporation. SFDA pharmacopeial divergence from NAFDAC cGMP guidelines threatens dual dossier cost inflation; prioritize Gulf regulatory harmonization advocacy through industry associations. Serialization equipment retrofit requirements favor incumbents with capital reserves over fragmented regional competitors. For New Entrants and Emerging Players: Contract manufacturers in Jebel Ali Free Trade Zone represent the most penetrable channel partner type for packaging converters lacking established Gulf dossiers. Target unit-dose blister formats for Nigeria's National Health Insurance Authority chronic disease programs where import dependence creates supply security premiums. European converters with existing EMA documentation should pursue MOHAP fast-track licensing as the lowest-friction market entry pathway. For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory serialization mandates force capital-intensive equipment upgrades beyond fragmented converter capacity. Five-to-ten year viability favors converters with multi-site Gulf manufacturing and backward integration into resin supply. Acquisition target archetype: mid-tier regional players with SFDA dossiers and underutilized blow-molding lines. Watch SFDA-Nigeria NAFDAC regulatory alignment negotiations as the critical inflection signal for cross-regional supplier economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polypropylene supply insulates margins from Saudi petrochemical maintenance cycle volatility. |
| Serialization-Ready Equipment Retrofit | Vision verification systems preserve SFDA supply access as aggregation hierarchy mandates compress batch release timelines. |
| MOHAP Fast-Track Licensing Pursuit | European EMA dossiers accelerate UAE market entry for converters seeking Gulf hospital procurement consolidation. |
| Lagos-Anchored Production Establishment | ECOWAS trade corridor access captures Nigerian import-dependence premiums for regional pharmaceutical manufacturers. |
| Multilayer Co-Injection Barrier Technology Adoption | Five-layer polyamide-ethylene vinyl alcohol structures displace single-source desiccant dependence for moisture-sensitive dosages. |
Research Methodology
Bottom-up pharmaceutical manufacturer procurement modeling reconciled against top-down converter capacity tracking forms the analytical core of this study. Primary interviews with packaging procurement managers at multinational drug manufacturers, regulatory affairs directors at Gulf-based converters, hospital pharmacy directors in Riyadh and Dubai, and NAFDAC compliance officers in Lagos combined with secondary validation. Secondary sources include SFDA pharmacopeial update notices, MOHAP import licensing protocols, NAFDAC cGMP guideline publications, Saudi Industrial Development Fund localization reports, and customs trade data for polymer resin flows into Nigeria.
Historical trendline analysis of pharmaceutical packaging procurement volumes across the Middle East and West Africa corridor established baseline growth patterns. The projection framework segments by product type, material grade, end-user category, and distribution channel, with dosage form stability requirements and regional regulatory cluster divergence as cross-cutting dimensions. CAGRs derive from equipment replacement cycle timing, serialization mandate implementation schedules, and chronic disease program enrollment trajectories. Forecast inputs incorporate polymer resin price elasticity and Gulf petrochemical capacity utilization assumptions.
Revisions become necessary when Saudi-Nigeria regulatory harmonization initiatives materialize or when ECOWAS trade corridor logistics infrastructure investments accelerate. Forecasts reflect documented assumptions about SFDA traceability regulation enforcement timing and National Health Insurance Authority enrollment scaling. A small set of named triggers warrants ongoing watch: SFDA-NAFDAC pharmacopeial alignment negotiations, Gulf petrochemical complex maintenance scheduling, and e-pharmacy platform penetration rates in Lagos and Dubai.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Plastic Pharma Tray Market
Pharmaceutical Packaging
Pharmaceutical Tubes Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Oral Dose Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical 3PL Market
Pharmaceutical Packaging
Prescription Pharmacy Bags Market
Pharmaceutical Packaging
Global Parenteral Packaging Market
Pharmaceutical Packaging
Global Vaccine Storage and Packaging Market
Pharmaceutical Packaging
China Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Europe Dietary Supplement Packaging Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Smart Pharmaceutical Packaging Market
Pharmaceutical Packaging
Parenteral Drugs Packaging Market
Pharmaceutical Packaging
Pharmacy Repackaging Systems Market